
 China Subscription-Based Gaming Market | 2026-2036
China Subscription-Based Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
China Subscription-Based Gaming Market Insights
Premium-tier subscription bundles is collapsing the gap between console-quality experiences and mobile accessibility in China. Tencent Holdings Limited leverages its WeChat ecosystem to sustain subscriber retention across multiple titles. NetEase, Inc. anchors its competitive position through proprietary IP development and self-operated publishing channels. miHoYo differentiates via technical excellence in cross-platform engine optimization, commanding loyalty among high-ARPU players.
China subscription-based gaming denotes a recurring-revenue model where users pay periodic fees for library access, cloud saves, and multiplayer infrastructure rather than perpetual licenses. The architecture relies on low-latency streaming protocols, DRM authentication layers, and dynamic content delivery networks to maintain session continuity across fragmented device environments. Mobile platforms currently dominate subscriber volume, while cloud platforms represent the fastest-growing segment as 5G edge nodes expand. Monthly payment models capture the largest addressable base, though tiered structures concentrate margin pools by gating exclusive content and early access privileges.
China's MIIT, NMPA, and SAMR collectively shape market access through real-name verification mandates, content approval queues, and anti-addiction playtime restrictions for minors. NMPA licensing freezes and quota systems directly constrain title supply, elevating the strategic value of established back catalogs and approved foreign IPs. Stakeholders must monitor regulatory signal velocity around youth protection enforcement and cross-border data localization rules to calibrate content investment and server deployment timelines.
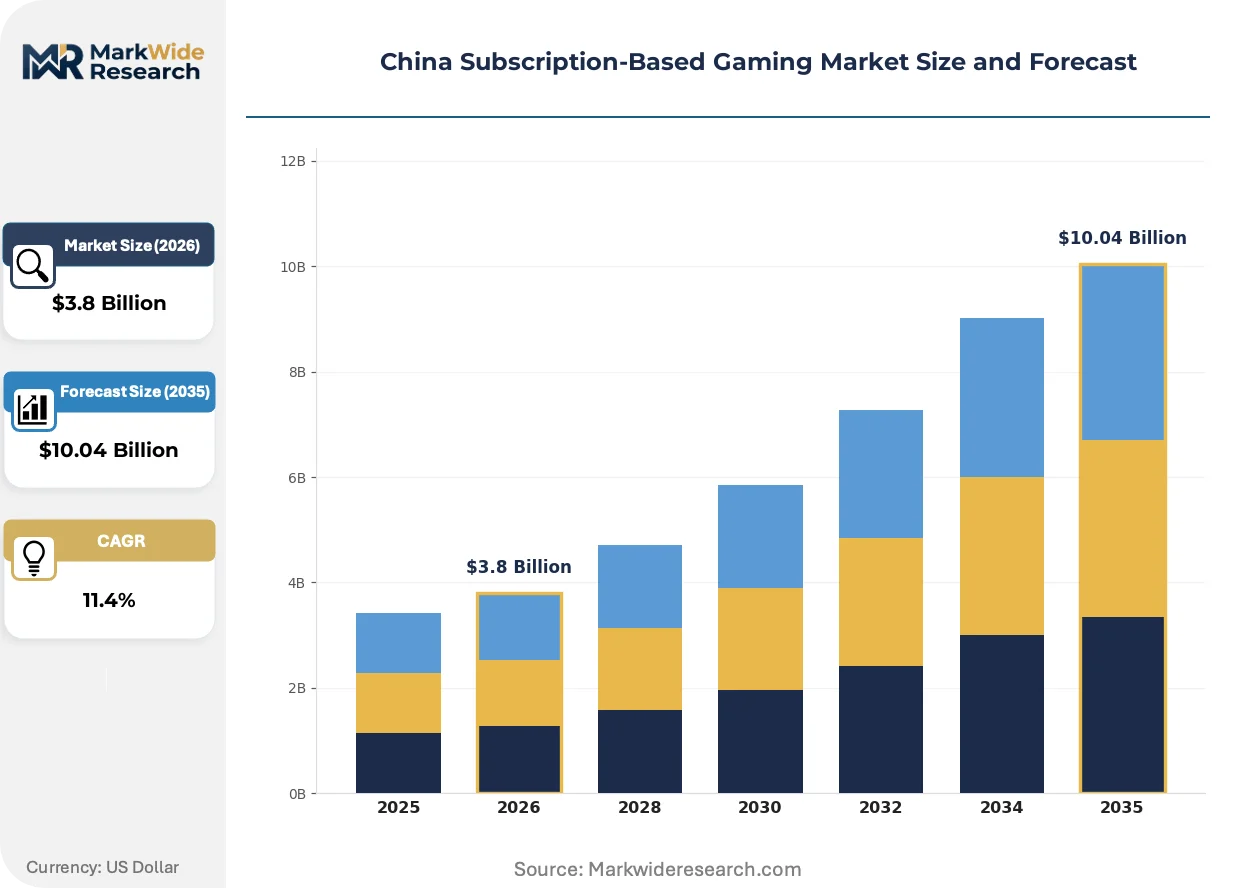
Market Dynamics
China's MIIT licensing framework is compressing title supply pipelines while 5G edge infrastructure expands cloud gaming capacity, creating a structural tension between regulatory-constrained content availability and technically-enabled distribution scale.
Growth Catalysts
- 5G Edge Deployment:Municipal governments in Shanghai and Shenzhen are accelerating base station densification, reducing streaming latency below 20 milliseconds for mobile subscribers.
- Dual Carbon Goals:China's national decarbonization targets are channeling state subsidies toward energy-efficient data center construction for cloud gaming workloads.
- Young Adult Demographics:University-educated cohorts in tier-one cities demonstrate higher willingness-to-pay for bundled content libraries versus à la carte purchases.
Market Restraints
- NMPA Licensing Quotas:Annual approval caps on new game titles limit catalog refresh rates, forcing operators to maximize monetization per approved asset.
- Input Cost Concentration:Graphics processing unit supply chains concentrate with Taiwan Semiconductor Manufacturing and NVIDIA, exposing margins to foundry pricing volatility.
- Real-Name Verification Mandates:SAMR identity authentication requirements increase customer acquisition friction and operational compliance overhead.
Strategic Opportunities
- Cross-Platform Engine Convergence:Unreal Engine 5 and Unity runtime optimization is bifurcating development pipelines between premium console-quality assets and lightweight mobile deployments.
- Guangdong-Hong Kong-Macao Greater Bay Area:Integrated data center zones and relaxed cross-border data flow pilot programs enable server deployment arbitrage.
- Subscription Bundling Innovation:Super-app ecosystems are integrating gaming subscriptions with fintech and social commerce verticals, capturing higher lifetime value per user.
Industry Challenges
- Anti-Addiction Compliance Engineering:Technical teams must architect real-time playtime monitoring systems that interface with national unified authentication platforms.
- Content Localization Velocity:Approved foreign IP adaptation requires script rewriting, cultural sensitivity review, and voice asset replacement within compressed windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Subscription-Based Gaming Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Action, Adventure, Sports, Puzzle Payment Model: Monthly, Yearly, Freemium, Tiered Platform: PC, Mobile, Console, Cloud User Demographic: Teenagers, Young Adults, Adults, Casual Gamers |
| Companies Covered | 37 Interactive Entertainment, Beijing Kunlun Technology Co. Ltd., Tencent Holdings Limited, Elex Technology, NetDragon Websoft Holdings, NetEase, Inc., Perfect World Games, The9 Limited, miHoYo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Subscription-Based Gaming Market Trends and Innovations
Cloud-native architecture adoption is redistributing computational loads from end-user devices to distributed edge nodes, fundamentally altering how gaming experiences are rendered and monetized across China's urban centers.
Proprietary game engines optimized for multi-tenant cloud environments are bifurcating the technical stack between high-fidelity streaming tiers and adaptive bitrate mobile delivery. Tier-one operators deploying these engines report session continuity improvements across fragmented device ecosystems. The technology is compressing the historical gap between console-quality visual fidelity and smartphone accessibility.
MIIT content approval timelines and SAMR anti-addiction enforcement protocols are tightening operational parameters for new market entrants. Established publishers with pre-approved back catalogs gain defensive positioning against supply-constrained competitors. Foreign IP holders are responding by accelerating joint venture structures with domestic operators to navigate licensing queues.
Consumption patterns among high-ARPU segments are rotating toward annual prepaid commitments over monthly recurring billing, reducing churn exposure for platform operators. This shift is most visible among professional demographics in Beijing and Shanghai who prioritize uninterrupted access during peak evening hours. Channel partners are reconfiguring commission structures to reward longer-duration subscription conversions.
China Subscription-Based Gaming Market Segmentation
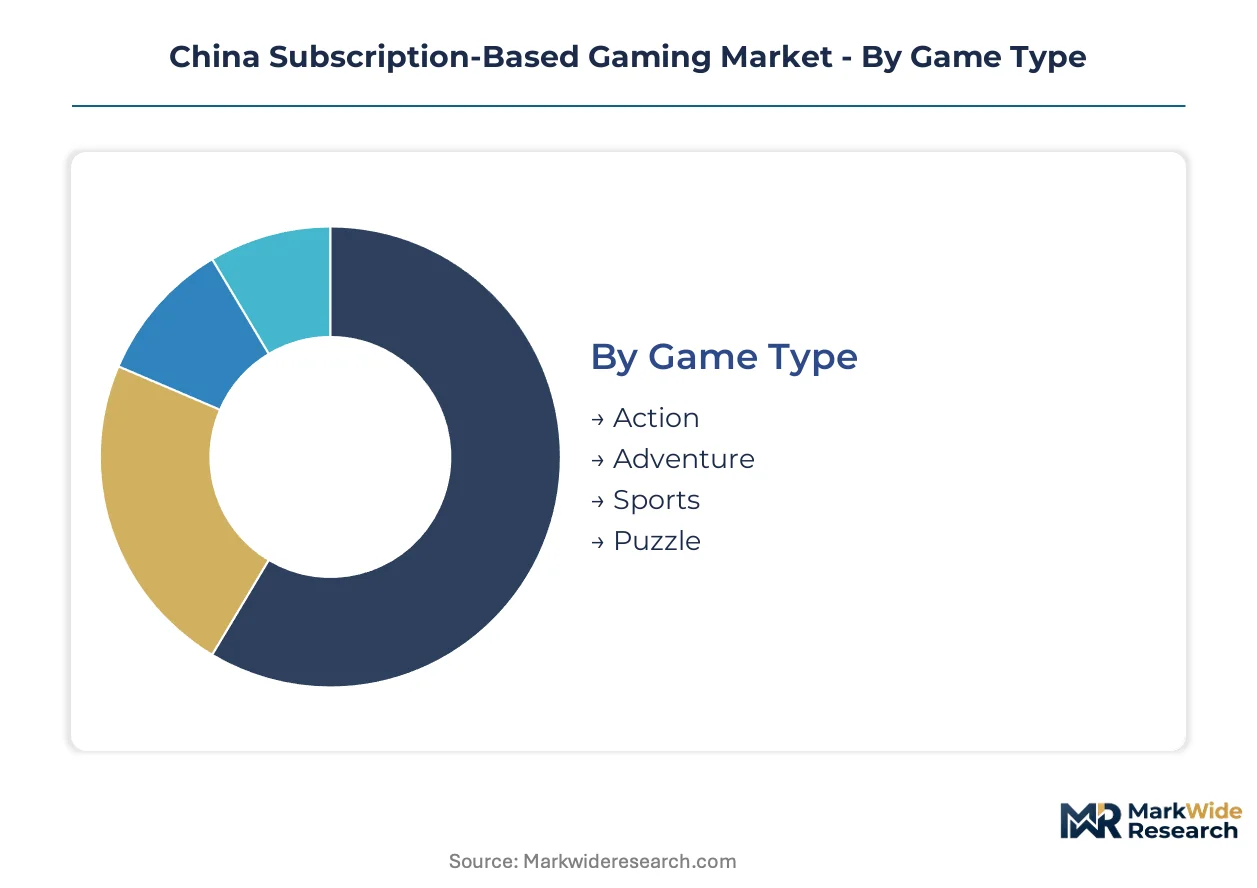
Segmentation in China's subscription-based gaming market reveals how regulatory constraints and infrastructure disparities create uneven substitution pressures across content categories and access methods. Platform operators calibrate catalog composition and pricing architecture to match distinct willingness-to-pay profiles across tier-one cities versus lower-tier markets.
Game Type:
Action titles face the strongest substitution threat from free-to-play alternatives with comparable mechanics but divergent monetization models, while Puzzle segments enjoy defensive positioning through lower development costs and broader demographic appeal.
- Action:High-fidelity combat systems and multiplayer infrastructure demand substantial server investment. Demand concentrates among young adults in Shenzhen and Shanghai where 5G edge nodes minimize input lag during competitive sessions. NMPA content review timelines extend longest for violent combat mechanics, compressing catalog refresh rates.
- Adventure:Narrative-driven progression systems with episodic content delivery sustain subscriber retention through cliffhanger structures. University-educated cohorts in Beijing demonstrate elevated willingness-to-pay for story-complete bundles versus fragmented chapter releases.
- Sports:Licensed IP from FIFA and NBA drives seasonal subscription spikes around real-world tournament calendars.
- Puzzle:Lightweight cognitive mechanics optimize for fragmented mobile sessions across commuting demographics.
Action retains volume leadership; Adventure holds the steepest expansion curve.
Payment Model:
Cost tier stratification separates mass-market acquisition funnels from high-ARPU retention pools, with annual commitments capturing professional demographics seeking uninterrupted evening access.
- Monthly:Low-friction entry points maximize subscriber acquisition velocity among price-sensitive casual gamers. Tier-one city operators report highest conversion efficiency when bundled with super-app fintech verticals.
- Yearly:Prepaid commitments reduce churn exposure and improve cash flow predictability for platform operators. Beijing and Shanghai professional demographics prioritize this tier for guaranteed peak-hour server priority.
- Freemium:Base-tier access with gated premium content creates upgrade pathways without initial payment friction.
- Tiered:Three-level pricing structures separate standard library access from exclusive early-release privileges and cloud save expansion.
Monthly captures the widest addressable base; Yearly concentrates margin pools most effectively.
Platform:
Volume distribution across access methods reflects infrastructure maturity gradients, with mobile dominance in subscriber count contrasting against cloud platforms' technical expansion trajectory.
- Mobile:Smartphone-native interfaces dominate absolute subscriber volume through WeChat ecosystem integration. MIIT real-name verification mandates create acquisition friction that Tencent mitigates through pre-authenticated social graph leverage.
- Cloud:Edge-computing architectures redistribute rendering loads from end-user devices to municipal base stations. Shanghai and Shenzhen municipal governments accelerate 5G densification programs that reduce streaming latency below 20 milliseconds.
- PC:Keyboard-mouse precision requirements sustain niche demand among competitive multiplayer segments.
- Console:Hardware scarcity and import restrictions limit addressable market despite premium ARPU profiles.
Mobile sustains volume supremacy; Cloud gains share fastest as edge infrastructure proliferates.
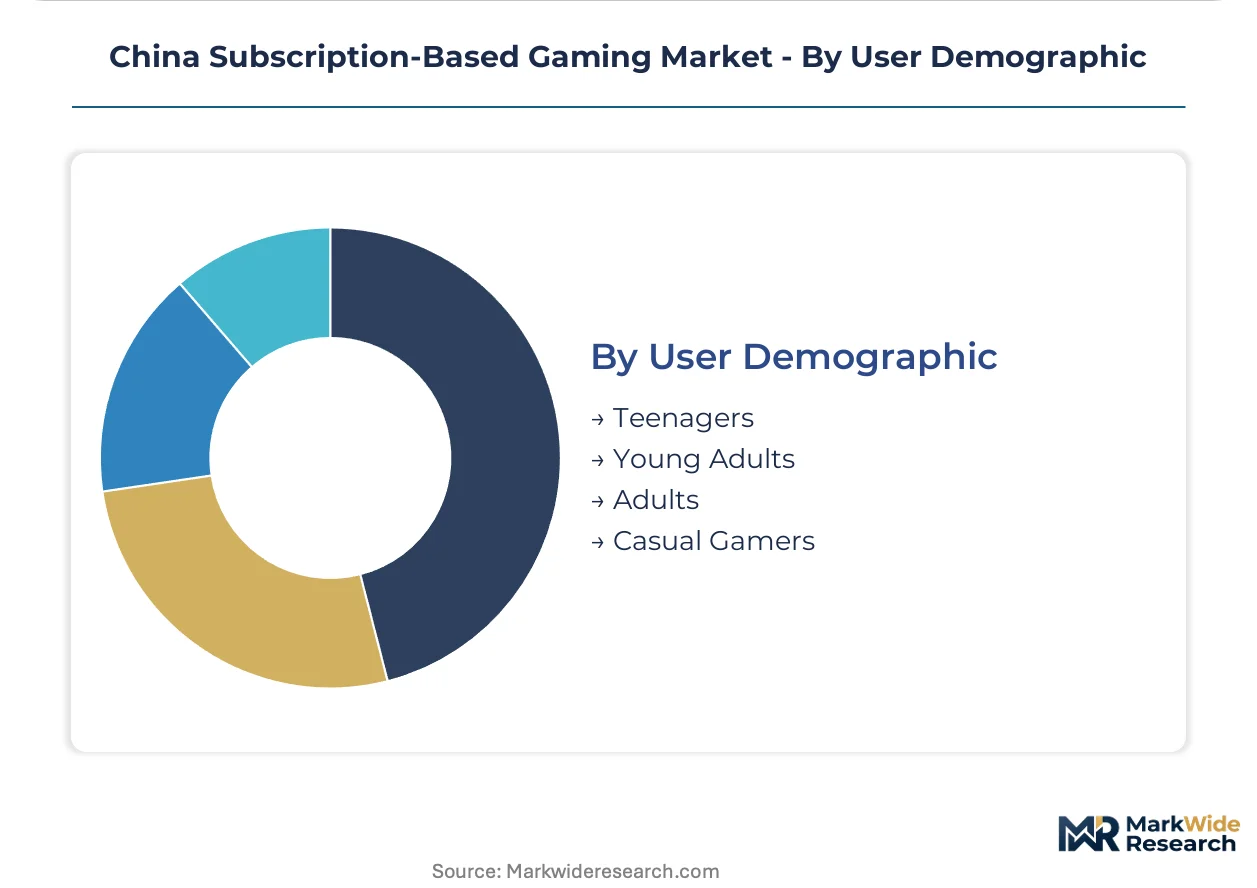
User Demographic:
Customer type segmentation aligns content curation and anti-addiction compliance engineering with distinct regulatory exposure profiles and session behavior patterns.
- Young Adults:University-educated cohorts in tier-one cities demonstrate highest willingness-to-pay for bundled libraries versus à la carte purchases. SAMR playtime restrictions do not apply, removing compliance engineering burdens for this segment.
- Casual Gamers:Fragmented session patterns and low competitive intensity reduce infrastructure cost per user. Demand concentrates among female demographics in Guangzhou and Chengdu seeking narrative and puzzle content.
- Teenagers:National unified authentication platform integration mandates real-time playtime monitoring systems.
- Adults:Professional demographics prioritize uninterrupted access and cross-platform save synchronization.
Young Adults anchor revenue concentration; Casual Gamers expand the addressable frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's subscription gaming sector operates as a net import market for foreign IP while exporting cloud infrastructure expertise to Southeast Asian markets. The domestic trade balance tilts toward licensing expenditure on approved foreign titles versus technology platform exports.
Shanghai
Shanghai anchors the highest subscriber density through municipal 5G edge densification programs reducing streaming latency below 20 milliseconds. MIIT real-name verification mandates create acquisition friction that local operators mitigate through pre-authenticated social graph leverage. The Yangtze River Delta cluster concentrates cloud data center investment from state-backed dual carbon subsidy programs.
Beijing
Beijing professional demographics drive annual prepaid subscription commitments prioritizing uninterrupted peak-hour access. NMPA content approval queues extend longest for narrative-driven adventure titles, compressing catalog refresh rates for local publishers. The Beijing-Tianjin-Hebei corridor hosts regulatory compliance engineering firms specializing in anti-addiction platform integration.
Shenzhen
Shenzhen's hardware manufacturing ecosystem supplies graphics processing components while municipal governments accelerate base station construction for mobile cloud gaming. SAMR identity authentication requirements increase customer acquisition costs that operators offset through super-app fintech bundling. The Pearl River Delta cluster integrates cross-border data flow pilot programs with Hong Kong server deployment.
Sichuan-Chongqing
Sichuan-Chongqing emerging markets demonstrate expanding casual gamer demand for puzzle and narrative content on lower-specification mobile devices. Provincial regulators enforce uniform anti-addiction playtime restrictions through national unified authentication platform integration. Chengdu anchors western China content localization studios serving approved foreign IP adaptation requirements.
China Subscription-Based Gaming Market Competitive Landscape
Listed leaders compete with private specialists across platform scale and proprietary engine development. The vendor base stratifies between ecosystem-integrated conglomerates and IP-focused independents. Three archetypes dominate: super-app ecosystem operators leveraging social graph retention, proprietary engine developers optimizing cross-platform rendering, and licensed IP aggregators maximizing approved content throughput. Consolidation pressure concentrates through M&A targeting pre-approved back catalogs and strategic partnerships securing foreign licensing queues.
Within the ecosystem-integrated tier, Tencent Holdings Limited and NetEase, Inc. occupy positions defined by platform scale advantages. Tencent exemplifies super-app ecosystem leverage through WeChat integration sustaining subscriber retention across multiple titles. NetEase represents proprietary IP development combined with self-operated publishing channel control. miHoYo sits within the technical excellence archetype, commanding loyalty among high-ARPU players through cross-platform engine optimization. These three entities anchor competitive positioning across the subscription value chain without exhaustive market coverage claims.
| Leading Market Players |
|---|
| 37 Interactive Entertainment |
| Beijing Kunlun Technology Co. Ltd. |
| Tencent Holdings Limited |
| Elex Technology |
| NetDragon Websoft Holdings |
| NetEase, Inc. |
| Perfect World Games |
| The9 Limited |
| miHoYo |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Taiwan Semiconductor Manufacturing and NVIDIA lock in graphics processing unit supply access while freezing price visibility for cloud gaming operators against foundry pricing volatility. These arrangements tether subscription margin stability to semiconductor procurement discipline across tier-one city deployments.
Pricing Analysis
Young adult subscribers in Beijing and Shanghai anchor annual prepaid commitments that concentrate margin pools through guaranteed peak-hour server priority. Three-tier pricing structure across premium, standard, and economy levels separates exclusive early-release privileges from basic library access. Cost compression in the monthly tier intensifies because super-app bundling subsidizes acquisition friction. Casual gamers in Guangzhou and Chengdu exhibit highest price sensitivity, while professional demographics demonstrate lowest elasticity.
Supply Chain Analysis
Just-in-time GPU procurement dominates operator inventory strategy, though NMPA licensing freezes force strategic stockpiling of approved titles to sustain catalog velocity. Supply concentrates in Taiwan, South Korea, and the United States for advanced semiconductor fabrication. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and 5G base station components. Single-source vulnerability at TSMC foundries poses structural risk. Distribution runs through municipal edge data centers integrated with state-backed dual carbon subsidy programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Free-to-play alternatives with comparable combat mechanics threaten subscription retention, forcing incumbents to differentiate through exclusive IP and uninterrupted peak-hour access guarantees.
For Market Incumbents: Shield pre-approved back catalogs against NMPA licensing quota constraints by accelerating joint venture structures with foreign IP holders. Deepen upstream control over proprietary game engine development to reduce reliance on Unreal Engine 5 licensing fees. Channel control through WeChat ecosystem integration sustains subscriber retention against emerging cloud-native competitors. For New Entrants and Emerging Players: Fast-track MIIT content approval through Chengdu localization studios serving western China adaptation requirements. Target Sichuan-Chongqing emerging markets where casual gamer demand for puzzle content outstrips supply from tier-one operators. Go-to-market leverage rests on super-app fintech bundling partnerships that offset SAMR identity authentication friction. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors established publishers with pre-approved title pipelines. Long-term viability hinges on regulatory navigation capability rather than pure technical scale. Acquisition archetypes center on proprietary engine developers with cross-platform optimization IP. Signal to monitor: NMPA approval velocity for foreign IP joint ventures.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Engine Development | Cross-platform optimization reduces latency below 20 milliseconds for Shanghai 5G edge deployments. |
| Foreign IP Joint Venture | Accelerates NMPA licensing queue navigation for narrative-driven adventure titles. |
| Super-App Fintech Bundling | WeChat ecosystem integration mitigates SAMR real-name verification acquisition friction. |
| Annual Prepaid Conversion | Beijing professional demographics prioritize guaranteed peak-hour server priority access. |
| Guangdong-Hong Kong-Macao Server Deployment | Cross-border data flow pilot programs enable infrastructure arbitrage for Pearl River Delta operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NMPA licensing disclosures, MIIT 5G infrastructure reports, and hyperscaler capex filings. Interviews with cloud platform engineers, content localization directors, super-app partnership leads, and municipal data center planners anchor demand-side validation. SEC filings from ecosystem-integrated conglomerates and trade data from Taiwan Semiconductor Manufacturing supply channels complete supply-side triangulation. Bottom-up subscriber modeling and top-down addressable market sizing converge through iterative reconciliation.
Segmentation dimensions modeled span payment model commitment duration, platform access method, game type development intensity, and user demographic regulatory exposure. Growth trajectories derive from elasticity estimates against 5G edge node deployment curves and NMPA approval velocity assumptions. Forecast inputs incorporate municipal dual carbon subsidy allocation patterns and real-name verification penetration rates across tier-one cities.
Decision-makers should treat outputs as directional under base assumptions of sustained MIIT content approval tightening and 5G infrastructure rollout continuity; material deviation would warrant model refresh. Specific risk factors span NMPA licensing freeze extensions, GPU supply chain disruption, and SAMR anti-addiction enforcement escalation. Revision becomes warranted when cross-border data flow pilot program scope crosses thresholds that alter server deployment economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Singapore Gaming Gadgets Market
Gaming
LAMEA Gaming Posters Market
Gaming
SLG Game Market
Gaming
VR Racing Gaming Market
Gaming
South Korea Virtual Reality Gaming Market
Gaming
Puzzle Video Game Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
South Asia Mobile Gaming Market
Gaming
Slot Machine Market
Gaming
MMORPG Gaming Market
Gaming
Australia Gaming Accessories Market
Gaming
Game Applications Market
Gaming
Traditional Casual Games Market
Gaming
Gaming Controller Market
Gaming
Australia Casino Tourism Market
Gaming
South Korea Subscription-Based Gaming Market