
 North America Casino Gambling Market | 2026-2036
North America Casino Gambling Market Size, Share, and Industry Trends Forecast 2026-2036
North America Casino Gambling Market Insights
Recreational bettors and digital-native players is bifurcating the North America casino gambling customer base away from legacy destination gamblers. MGM Resorts International anchors its position through integrated resort ecosystems spanning Las Vegas and regional markets. Caesars Entertainment Inc. leverages its omnichannel platform to bridge physical casinos with mobile sports betting. DraftKings Inc. competes aggressively in online sports wagering, capturing younger demographics through app-first engagement.
Casino gambling encompasses regulated wagering activities conducted through electronic gaming machines, table-based games of chance, and digital platforms operating under jurisdictional licensing frameworks, with random number generators and house-edge mathematics governing outcome distribution. The primary commercial purpose centers on generating gaming revenue for operators while delivering entertainment value to patrons within supervised regulatory environments. Slots dominate floor space allocation and revenue yield across brick-and-mortar operations, while sports betting represents the fastest-expanding service type following post-PASPA liberalization. Tribal license structures govern substantial capacity across Oklahoma and California jurisdictions, creating distinct competitive dynamics from commercial licensing regimes in Nevada and New Jersey.
The National Indian Gaming Commission oversees tribal gaming compacts, while state gaming commissions in Nevada and New Jersey enforce commercial operator standards; the Department of Justice interprets federal wire act applicability to interstate digital wagering. These overlapping frameworks create compliance complexity that favors operators with established regulatory affairs infrastructure and existing license portfolios. Stakeholders must monitor pending state legislative sessions and tribal compact renegotiations to anticipate market access shifts.
Market Dynamics
The migration of casino gambling onto mobile platforms is fragmenting revenue concentration away from destination resort corridors toward distributed digital access points. State compacts and tribal licensing frameworks are scrambling to capture tax flows from this channel shift.
Growth Catalysts
- Post-PASPA sports betting liberalization:State-level frameworks in New Jersey, Pennsylvania, and Michigan have unlocked mobile wagering tax bases previously captured by offshore operators.
- Tribal compact renegotiations:Oklahoma and California jurisdictions are expanding Class III gaming authorizations to include digital table games and peer-to-peer poker platforms.
- Cloud-native wagering infrastructure:Kubernetes-based backend systems are slashing time-to-market for new state launches from 18 months to under 90 days.
Market Restraints
- Wire Act uncertainty:Department of Justice reinterpretations of interstate digital wagering create compliance freezes that stall multi-state pool development.
- Payment processor concentration:ACH and card network dependencies expose operators to sudden fund-flow disruptions when financial institutions recalibrate risk tolerance.
- Real estate carry costs:Legacy Strip and regional casino properties face fixed-cost burdens that digital-native competitors avoid entirely.
Strategic Opportunities
- Untapped Canadian provincial markets:Ontario's iGaming framework expansion creates a regulated entry path for US-licensed platform providers.
- In-game wagering integration:Micro-betting on individual plays during live sporting events is compressing bet frequency and holding percentages simultaneously.
- Social casino convergence:Free-to-play mobile slots with sweepstakes redemption mechanics are acquiring players at sub-$15 CACs in pre-legalization states.
Industry Challenges
- Responsible gaming algorithm deployment:Real-time behavioral monitoring systems require machine learning engineering talent scarce outside Silicon Valley and Boston corridors.
- Legacy slot system integration:Server-based gaming floors from IGT and Aristocrat must interface with new mobile wallet architectures without disrupting floor operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Casino Gambling Market |
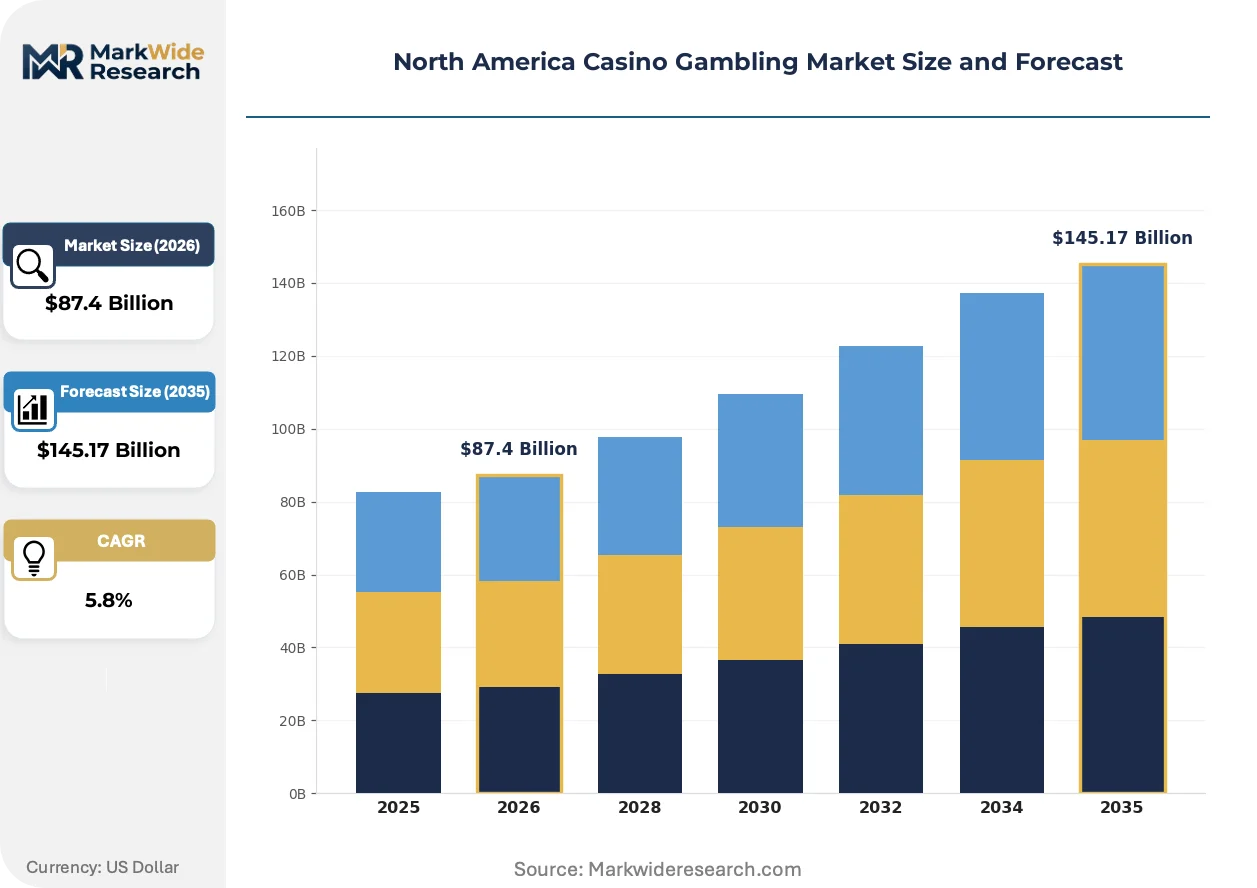
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Slots, Table Games, Poker, Bingo Service Type: Online Gambling, Brick-and-Mortar, Mobile Gaming, Sports Betting Customer Segmentation: Casual Gamblers, High Rollers, Tourists, Locals Licensing Model: Government License, Tribal License, Private License, Commercial License |
| Companies Covered | MGM Resorts International, Caesars Entertainment Inc., Las Vegas Sands Corp., Wynn Resorts Ltd., Penn Entertainment Inc., Boyd Gaming Corp., Hard Rock International, Mohegan Gaming & Entertainment, DraftKings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Casino Gambling Market Trends and Innovations
Platform architecture decisions are splitting operator capital allocation between cloud-native agility and on-premise control. This tension is visible in vendor selection patterns and compliance system design.
Containerized microservices architecture is decomposing monolithic player-account-management systems into modular components. Regional casino operators are adopting these stacks to launch white-label sportsbooks without building proprietary technology. The decomposition is compressing vendor switching costs and eroding incumbents' platform lock-in.
The Department of Justice's fluctuating Wire Act positions are forcing operators to architect payment and data routing as if interstate commerce remains restricted. This defensive posture is raising infrastructure costs for multi-state brands. New Jersey and Nevada gaming commissions are responding with memoranda of understanding that preserve liquidity pooling within compact regions.
Younger demographics are treating sportsbook apps as entertainment utilities rather than gambling destinations. This behavioral shift is displacing traditional casino loyalty programs with social features, streaming integrations, and free-to-play retention mechanics. The pattern is most visible in Michigan and Pennsylvania, where handle growth concentrates in demographics under 35.
North America Casino Gambling Market Segmentation
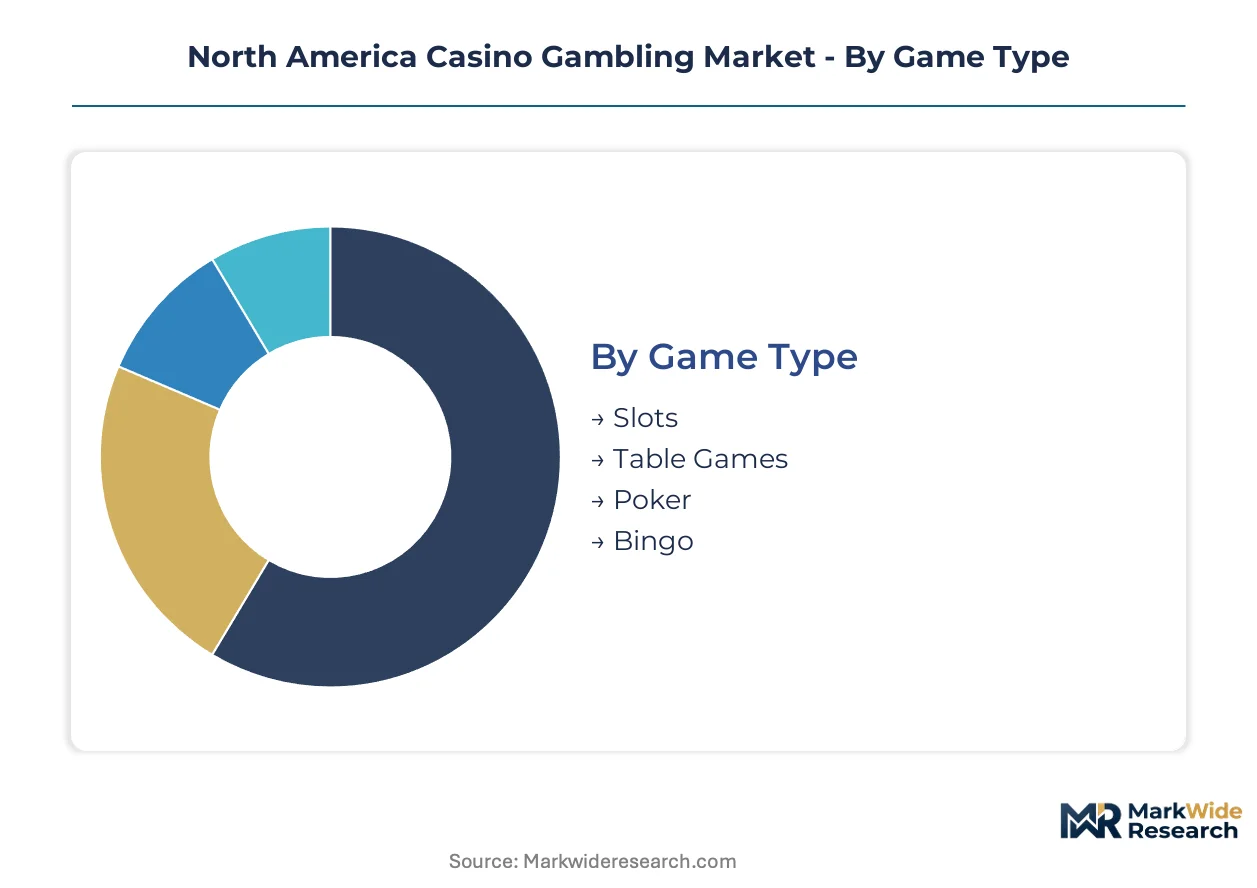
Casino gambling revenue pools fragment distinctly across game mechanics, access channels, and regulatory containers. Understanding where margin concentrates within each slice reveals which operator bets carry the highest return on capital deployed.
Game Type:
Margin pools concentrate in electronic gaming machines due to labor-light operations and continuous play velocity.
- Slots:Electronic gaming machines with random number generator outcomes and configurable payback percentages. Floor space allocation in Nevada and New Jersey commercial corridors tilts heavily toward these units, driven by 24-hour operational capacity without dealer labor.
- Table Games:Dealer-mediated games including blackjack, roulette, and baccarat with house-edge mathematics governing payouts. Tribal jurisdictions in Oklahoma and California emphasize table expansion to attract destination players seeking social gaming experiences.
- Poker:Player-versus-player card games where operators collect rake rather than assume house position.
- Bingo:Number-matching games with lower per-capita spend but high session frequency among older demographics.
The dominant share belongs to Slots, while Table Games is closing the gap fastest.
Service Type:
Channel economics diverge sharply between fixed-cost physical infrastructure and variable-cost digital delivery.
- Online Gambling:Browser and app-based casino gaming operating under state-specific licensing frameworks. Pennsylvania and Michigan regulatory openings have compressed customer acquisition costs through legal channel substitution from offshore competitors.
- Sports Betting:Wagering on athletic contest outcomes through retail sportsbooks and mobile platforms. In-game micro-betting integration is compressing bet frequency and holding percentages simultaneously in jurisdictions with live data partnerships.
- Mobile Gaming:Native application gambling optimized for smartphone form factors.
- Brick-and-Mortar:Physical casino floor operations with slot machines, table games, and hospitality amenities.
Online Gambling commands the largest revenue pool, though Sports Betting is expanding most quickly.
Customer Segmentation:
Spend concentration skews toward a narrow cohort of high-frequency, high-stake players despite their smaller headcount.
- High Rollers:Players wagering substantial sums per session, typically receiving comped hospitality and dedicated hosts. Las Vegas Strip operators structure entire resort ecosystems around capturing this segment's multi-day stays and cross-property play.
- Casual Gamblers:Recreational players with modest per-session budgets and irregular visit patterns. Digital-native millennials and Gen Z consumers in Michigan and Pennsylvania fit this profile, shifting operator investment toward app-first engagement mechanics.
- Tourists:Out-of-market visitors treating gambling as vacation entertainment.
- Locals:Repeat players within driving distance of regional casino properties.
High Rollers retain the dominant value share, while Casual Gamblers is gaining share fastest.
Licensing Model:
Regulatory container determines tax burden, operational flexibility, and market access boundaries.
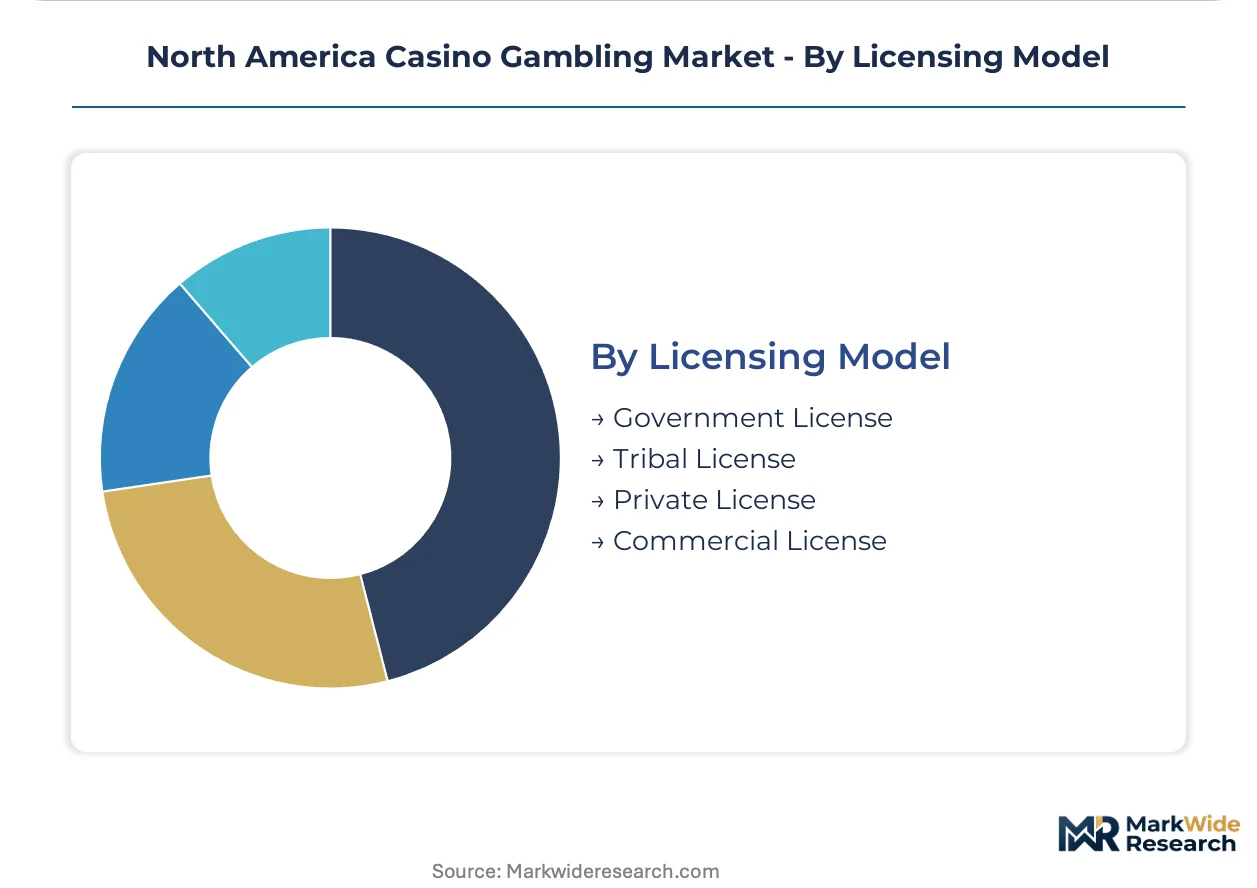
- Tribal License:Gaming compacts negotiated between sovereign nations and state governments under the Indian Gaming Regulatory Act. Oklahoma and California tribal operators leverage Class III expansions to include digital table games and peer-to-peer poker platforms.
- Commercial License:State-issued permits for non-tribal operators in jurisdictions like Nevada and New Jersey. These frameworks subject operators to gaming commission oversight with established responsible gaming mandates and liquidity pooling agreements.
- Government License:Direct state operation or tightly constrained private management contracts.
- Private License:Limited permits for specific charitable or social gaming contexts.
Tribal License holds the dominant position, while Commercial License is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-roller destination travelers and mobile-native recreational bettors concentrate demand across distinct North American corridors, with tribal jurisdictions and commercial licensing regimes creating divergent regulatory containers for operator investment.
United States
Pennsylvania and Michigan mobile wagering frameworks attract digital-native millennials through app-first onboarding flows. State gaming commissions in Nevada and New Jersey enforce liquidity pooling agreements that preserve multi-state player liquidity. The Las Vegas Strip cluster anchors integrated resort ecosystems designed around multi-day high-roller stays and cross-property play migration.
Canada
Ontario's iGaming framework expansion creates regulated entry paths for platform providers seeking pre-US-legalization player bases. Provincial lottery corporations in Quebec and British Columbia maintain hybrid models blending government-operated digital platforms with private operator partnerships. The Toronto-Waterloo corridor concentrates payment processor and compliance technology talent pools serving North American operators.
Mexico
Permit holders in Mexico City and Monterrey target cross-border tourist flows from Texas and California. The federal gaming authority SEGOB oversees limited casino licensing with strict geographic dispersion requirements. Baja California border zones cluster slot parlors capturing weekend leisure traffic from Southern California metropolitan areas.
Oklahoma
Tribal gaming compacts govern substantial Class III capacity expansion into digital table games and peer-to-peer poker platforms. The National Indian Gaming Commission oversight framework enables compact renegotiations that broaden authorized game portfolios. Oklahoma City and Tulsa corridors concentrate tribal casino properties competing for regional drive-in traffic from Texas and Kansas.
California
Tribal operators in Southern California and Central Valley jurisdictions leverage ballot measure campaigns to expand sports betting authorization beyond current card room limitations. State legislative gridlock on commercial online gambling preserves tribal exclusivity over digital channel development. The Los Angeles-San Diego corridor anchors destination casino resorts targeting Asian high-roller segments through dedicated VIP host programs.
North America Casino Gambling Market Competitive Landscape
Player mix skews toward integrated resort operators with physical-digital bridge capabilities and pure-play mobile platforms capturing younger demographics. Market structure concentrates around three strategic archetypes: legacy Strip operators with hospitality-anchored ecosystems, regional casino chains with tribal partnership networks, and cloud-native sportsbook platforms. Dominant competitive moves include tribal compact renegotiations for digital expansion rights and white-label technology licensing to accelerate state-by-state market entry.
Within the integrated resort tier, MGM Resorts International and Caesars Entertainment Inc. occupy positions bridging physical casino floors with mobile sports betting infrastructure. Among pure-play digital competitors, DraftKings Inc. exemplifies the app-first engagement model capturing millennial and Gen Z handle concentration in Michigan and Pennsylvania. These three companies represent the structural fault line between destination gambling and distributed digital access.
| Leading Market Players |
|---|
| MGM Resorts International |
| Caesars Entertainment Inc. |
| Las Vegas Sands Corp. |
| Wynn Resorts Ltd. |
| Penn Entertainment Inc. |
| Boyd Gaming Corp. |
| Hard Rock International |
| Mohegan Gaming & Entertainment |
| DraftKings Inc. |
| Others |
Pricing and Supply Chain Analysis
State gaming commission licensing frameworks in Nevada and New Jersey gate both supplier qualification and price differentiation simultaneously, as compliance infrastructure requirements separate Tier 1 platform providers from white-label resellers while tribal compact structures in Oklahoma and California create parallel pricing containers.
Pricing Analysis
Cost-plus contracts with CPI indexation dominate vendor agreements for gaming management systems and payment processing infrastructure. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth and regulatory coverage breadth. Pricing pressure stems from cloud-native competitors slashing deployment timelines from 18 months to 90 days. Casual gamblers exhibit highest price sensitivity through promotional acquisition offers, while high rollers show minimal elasticity given bundled hospitality value.
Supply Chain Analysis
Port congestion on the Los Angeles-Long Beach corridor elevates inbound logistics costs for slot machine hardware imports from Taiwan and Japan. Electronic gaming equipment draws from Taiwan, Japan, and USA manufacturing clusters. Critical dependencies include random number generator chipsets, server-grade GPUs, and payment terminal hardware. Single-source vulnerability concentrates in ACH network processors for fund flows. Distribution runs through regional casino operator procurement teams with direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward tribal operators and state lottery corporations as procurement consolidation accelerates across Oklahoma and California jurisdictions.
For Market Incumbents: Compound defensive positioning through tribal compact renegotiations for digital expansion rights and exclusive platform licensing deals. Cloud-native sportsbook entrants threaten legacy integrated resort margins. Vertical integration into payment processing infrastructure reduces fund-flow disruption exposure. For New Entrants and Emerging Players: Anchor in Ontario's iGaming framework as a pre-US-legalization beachhead with lower compliance barriers than Nevada or New Jersey. Social casino convergence mechanics in pre-legalization states offer the most penetrable acquisition channel. White-label technology licensing accelerates state-by-state market entry without proprietary platform buildout. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native wagering infrastructure as Kubernetes-based deployments slash fixed-cost requirements. Long-term viability favors operators with tribal partnership networks and multi-state license portfolios. Monitor Department of Justice Wire Act reinterpretations as the critical inflection signal for interstate liquidity pooling economics.| Strategic Initiative | Industry Significance |
|---|---|
| Tribal Compact Renegotiation | Class III expansions in Oklahoma and California unlock digital table games and peer-to-peer poker authorization. |
| Cloud-Native Platform Migration | Kubernetes-based backend systems compress new state launch timelines from 18 months to under 90 days. |
| White-Label Technology Licensing | Regional casino operators launch sportsbooks without proprietary engineering investment. |
| In-Game Wagering Integration | Micro-betting on individual plays compresses bet frequency and holding percentages in live data partnerships. |
| Social Casino Convergence | Free-to-play mobile slots with sweepstakes redemption acquire players at sub-$15 CACs in pre-legalization states. |
Research Methodology
A standing panel of casino operations executives, tribal gaming commission directors, state lottery corporation procurement leads, and payment processor risk officers provided ongoing calibration. Primary interviews combined with secondary validation from National Indian Gaming Commission filings, state gaming commission regulatory dockets, SEC 10-K disclosures, and tribal compact documentation. Bottom-up operator revenue modeling triangulated against top-down state tax revenue aggregates.
Consistency checks validated volume and value outputs against state-reported wagering handle and gross gaming revenue benchmarks. The analytical framework segmented across game type, service type, customer archetype, and licensing model dimensions throughout the forecast period. CAGRs derived from logistic adoption curves for mobile wagering penetration and linear projections for brick-and-mortar capacity utilization. Industry-specific inputs included tribal compact renewal schedules and state legislative session calendars.
Material uncertainties — Department of Justice Wire Act reinterpretations, tribal compact renegotiation outcomes, payment processor risk tolerance shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and technology adoption velocity. Practitioners should keep alternative scenarios live as federal enforcement priorities and state legislative compositions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
GCC Gaming Headsets Market
Gaming
3D Gaming Technology Market
Gaming
Videogames Market
Gaming
VR Gaming Accessories Market
Gaming
Slot Machine Market
Gaming
SLG Game Market
Gaming
Shooter Game Market
Gaming
VR Melee Games Market
Gaming
Online Strategy Games Market
Gaming
North America Gaming Market
Gaming
Latin America Mobile Gaming Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
China in-Game Advertising Market
Gaming
Global Game Testing Service Market
Gaming
Europe Casino Gambling Market
Gaming
Game Engine Management Market