
 United States Virtual Reality Gaming Market | 2026-2036
United States Virtual Reality Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
United States Virtual Reality Gaming Market Intelligence
Platform licensing revenue is fragmenting across hardware-agnostic storefronts and first-party ecosystems. Meta leverages its vertical stack of headsets, operating systems, and exclusive titles to capture value at multiple layers. Valve sustains its position through SteamVR's open distribution architecture and PC-tethered performance benchmarks. Schell Games differentiates by occupying the educational and enterprise-adjacent content niche with sustained IP development.
United States Virtual Reality Gaming denotes immersive interactive entertainment delivered through head-mounted displays with sub-20ms motion-to-photon latency, six-degrees-of-freedom tracking, and stereoscopic rendering at 90Hz or higher refresh rates, designed to simulate spatial presence for consumer and commercial engagement. Standalone headsets now dominate unit shipments by eliminating PC dependency and reducing setup friction, while PC-Based systems retain the highest per-user revenue through premium hardware and software bundles. Educational content within the Content Type dimension lags in revenue but attracts institutional procurement from schools seeking STEM engagement tools.
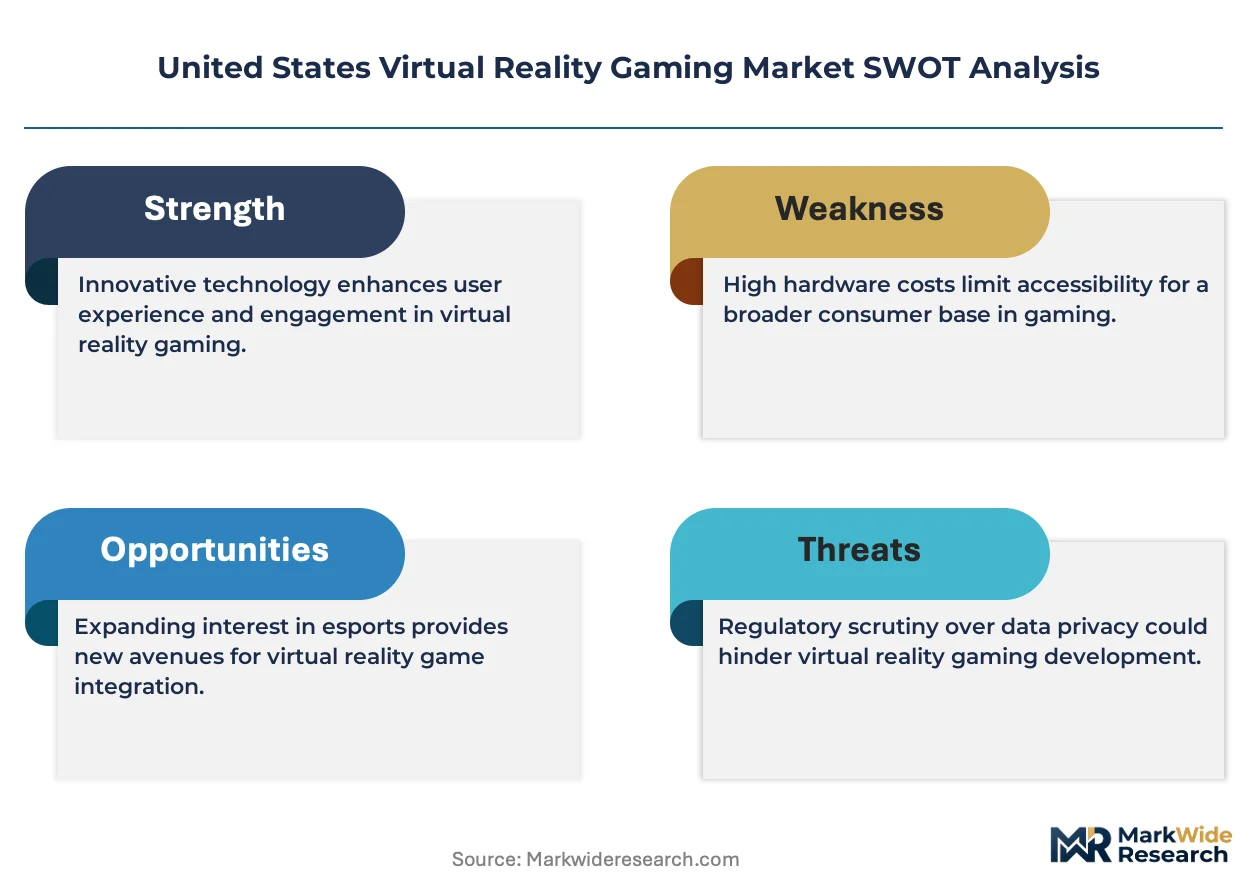
The FCC governs wireless transmission standards for untethered headsets, while the FDA maintains oversight on VR therapeutic applications that blur medical and entertainment boundaries. State-level consumer protection statutes in California and New York shape refund policies and subscription billing transparency for digital storefronts. Stakeholders must monitor how antitrust scrutiny of app store commission structures alters developer economics and hardware bundling strategies.
Market Dynamics
Standalone headsets with on-chip AI rendering are compressing PC-tethered distribution channels while the FCC's millimeter-wave spectrum allocations reshape wireless performance baselines for location-based entertainment venues.
Growth Catalysts
- Untethered 6DoF Tracking:Inside-out camera arrays eliminate external base stations, reducing venue setup costs for multiplayer arena operators in California's Bay Area cluster.
- STEM Procurement Mandates:Federal education grants channel institutional spending toward immersive learning modules, creating recurring revenue streams for educational content developers.
- Millimeter-Wave Spectrum:FCC decisions on unlicensed 60GHz bands enable sub-20ms wireless latency, unlocking free-roam multiplayer formats without backpack PCs.
Market Restraints
- Display Panel Concentration:Micro-OLED supply concentrates among Asian component foundries, creating input cost volatility for headset manufacturers.
- Motion Sickness Physiology:Vestibular-visual conflict limits session duration for a material share of users, capping per-user engagement metrics.
- Content Development Economics:High-fidelity asset production requires specialized engine expertise that concentrates in San Francisco and Seattle metro talent pools.
Strategic Opportunities
- Enterprise Training Adjacencies:OSHA-compliant safety simulations for construction and energy sectors open B2B procurement channels beyond consumer entertainment.
- Medicaid Reimbursement Pathways:FDA breakthrough device designations for therapeutic VR applications create prescription-based distribution models.
- Midwest Venue Expansion:Location-based entertainment remains underpenetrated in Texas and Florida metro corridors relative to coastal density.
Industry Challenges
- Real-Time Engine Talent Scarcity:Unreal Engine and Unity optimization for mobile chipsets requires scarce systems programming expertise.
- Cross-Platform Certification Friction:Content submissions face divergent technical requirements across Meta Horizon Store, SteamVR, and PlayStation VR2 pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Virtual Reality Gaming Market |
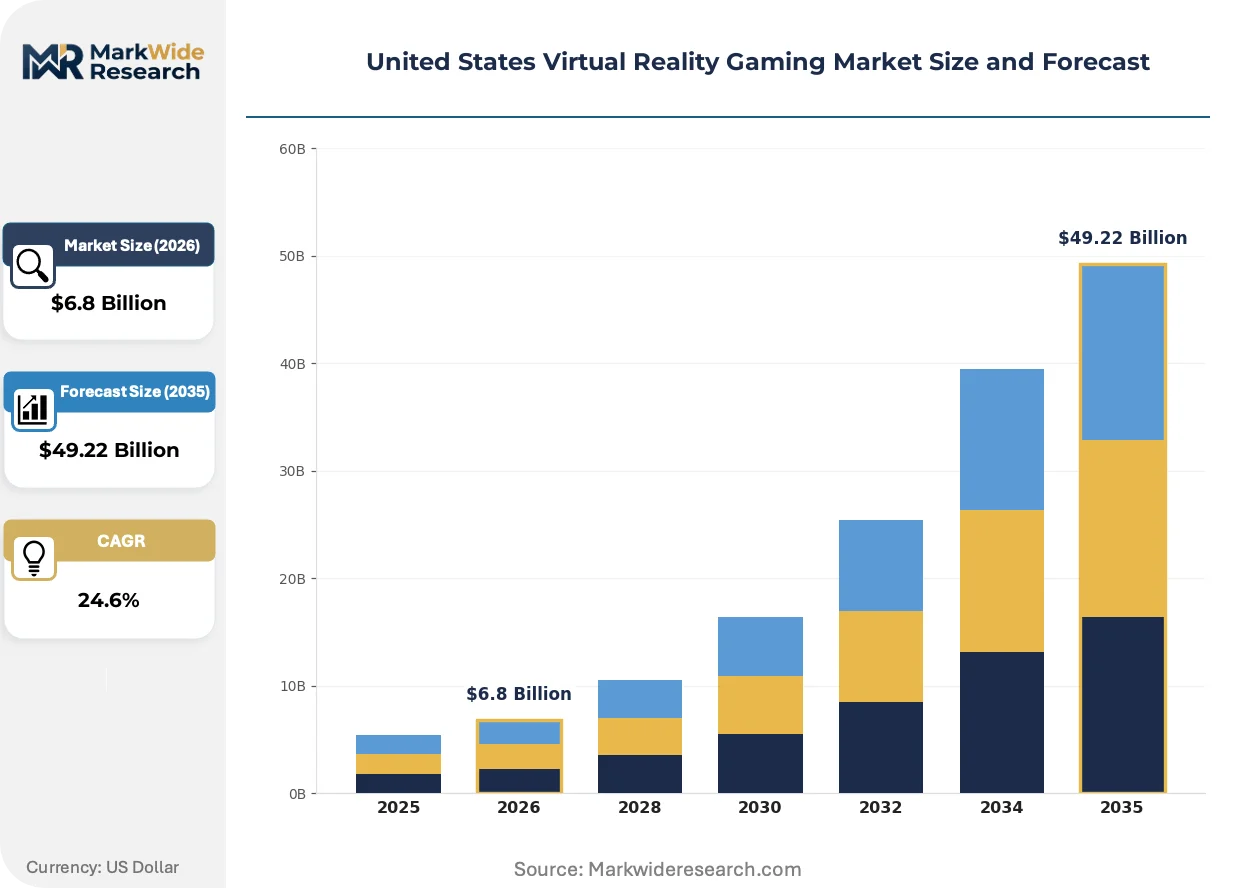
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $49.22 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: PC-Based, Console-Based, Standalone, Mobile Content Type: Action, Adventure, Simulation, Educational End User: Casual Gamers, Professional Gamers, Schools, Organizations Distribution Channel: Online, Retail, Subscription-Based, Event-Specific |
| Companies Covered | Schell Games, Rec Room, Meta, Polyarc, ForeVR Games, Valve, Survios, Bigscreen, Beat Games, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Virtual Reality Gaming Market Strategic Shifts & Innovations
Foveated rendering with eye-tracking sensors is redrawing hardware performance requirements while state-level consumer protection statutes force billing transparency reforms on subscription storefronts.
Pancake optics with folded light paths is rendering obsolete bulky Fresnel lens assemblies that dominated prior headset generations. Location-based entertainment venues in Las Vegas and Orlando are retrofitting existing pods with pancake-equipped hardware to compress equipment footprints. The shift is rendering obsolete the 500-gram weight class that constrained session duration for mainstream users.
The FTC's revived scrutiny of app store commission structures is forcing storefront operators to disclose revenue-sharing terms in standardized formats. Developers now negotiate alternative payment rails that bypass platform-native billing systems. California's SB-478 transparency mandates are accelerating this disclosure regime for subscription-based VR services.
After-sales content unbundling is fragmenting the traditional hardware-software bundle model. Arcade operators now procure hardware from Shenzhen suppliers while licensing content through direct studio relationships. Texas and Florida venue chains pioneered this disaggregation, separating CapEx cycles from recurring content refresh obligations.
United States Virtual Reality Gaming Market Segmentation
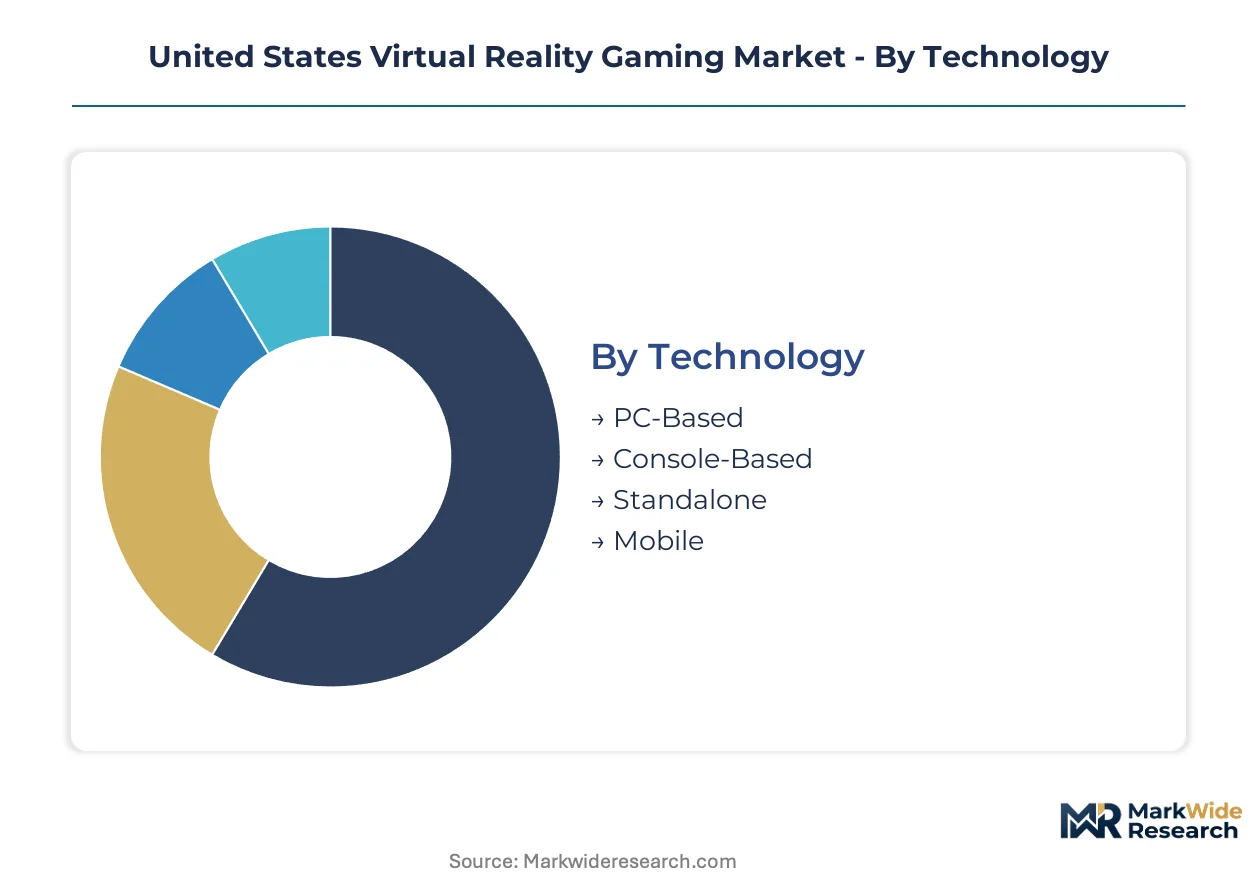
Segmentation reveals how hardware form factors, content genres, and procurement channels create distinct margin profiles across the United States Virtual Reality Gaming ecosystem. Each dimension carries specific service intensity requirements that shape vendor economics and buyer loyalty patterns.
Technology:
After-sales service intensity varies dramatically across hardware categories, with tethered systems demanding ongoing technical support while standalone devices minimize recurring touchpoints through simplified deployment.
- PC-Based:These systems tether to high-performance workstations via DisplayPort or USB-C, delivering uncompressed visuals at 90Hz or higher. Demand concentrates among professional gamers in Seattle and Austin metro areas where PC-building culture sustains enthusiast communities. The FCC's unlicensed spectrum rulings have limited impact here since wired connections eliminate wireless latency concerns.
- Standalone:On-chip AI rendering and inside-out tracking eliminate external sensors, reducing venue setup complexity for California Bay Area arcade operators. The segment's service model shifts burden to firmware updates and cloud-based content management rather than hardware maintenance.
- Console-Based:PlayStation VR2 and similar systems leverage existing console install bases, creating predictable upgrade cycles tied to platform generation releases.
- Mobile:Smartphone-dependent viewers like Samsung Gear VR successors target price-sensitive entry segments with limited processing capability.
Standalone holds the largest share; momentum sits with PC-Based among revenue-per-user metrics.
Content Type:
Development cost tiers separate premium narrative experiences from lightweight educational modules, with production budgets ranging from indie-scale to AAA-studio levels.
- Action:High-intensity combat and movement mechanics push hardware tracking precision to limits, requiring sub-20ms motion-to-photon latency to minimize vestibular discomfort. Texas location-based entertainment venues prioritize these titles for their throughput efficiency and repeat-play appeal.
- Adventure:Narrative exploration titles emphasize environmental storytelling over reflex demands, attracting longer session durations from casual demographics. Schell Games and similar studios concentrate development talent in Pittsburgh and San Francisco corridors for this genre.
- Simulation:Flight, racing, and social sandbox experiences demand specialized peripheral integration and precise physics modeling.
- Educational:STEM-aligned modules attract institutional procurement from Florida school districts seeking engagement tools for K-12 science curricula.
Action generates the highest per-title revenue; educational content is expanding most quickly through federal grant channels.
End User:
Procurement authority and budget cycles create four distinct customer archetypes with divergent price sensitivity and support expectations.
- Casual Gamers:Price-conscious consumers purchasing through retail channels or bundled hardware promotions, with low tolerance for setup complexity.
- Professional Gamers:Esports competitors and content creators demanding broadcast-grade streaming compatibility and tournament-ready tracking fidelity. California and Washington state host the densest concentration of this segment.
- Schools:Institutional buyers navigating federal Title I and ESSER funding timelines, requiring COPPA-compliant content libraries and bulk licensing structures.
- Organizations:Corporate training departments and healthcare systems procuring FDA-oversight therapeutic applications with prescription-based distribution models.
Professional Gamers command premium pricing; Schools represent the steepest expansion trajectory through mandated STEM procurement.
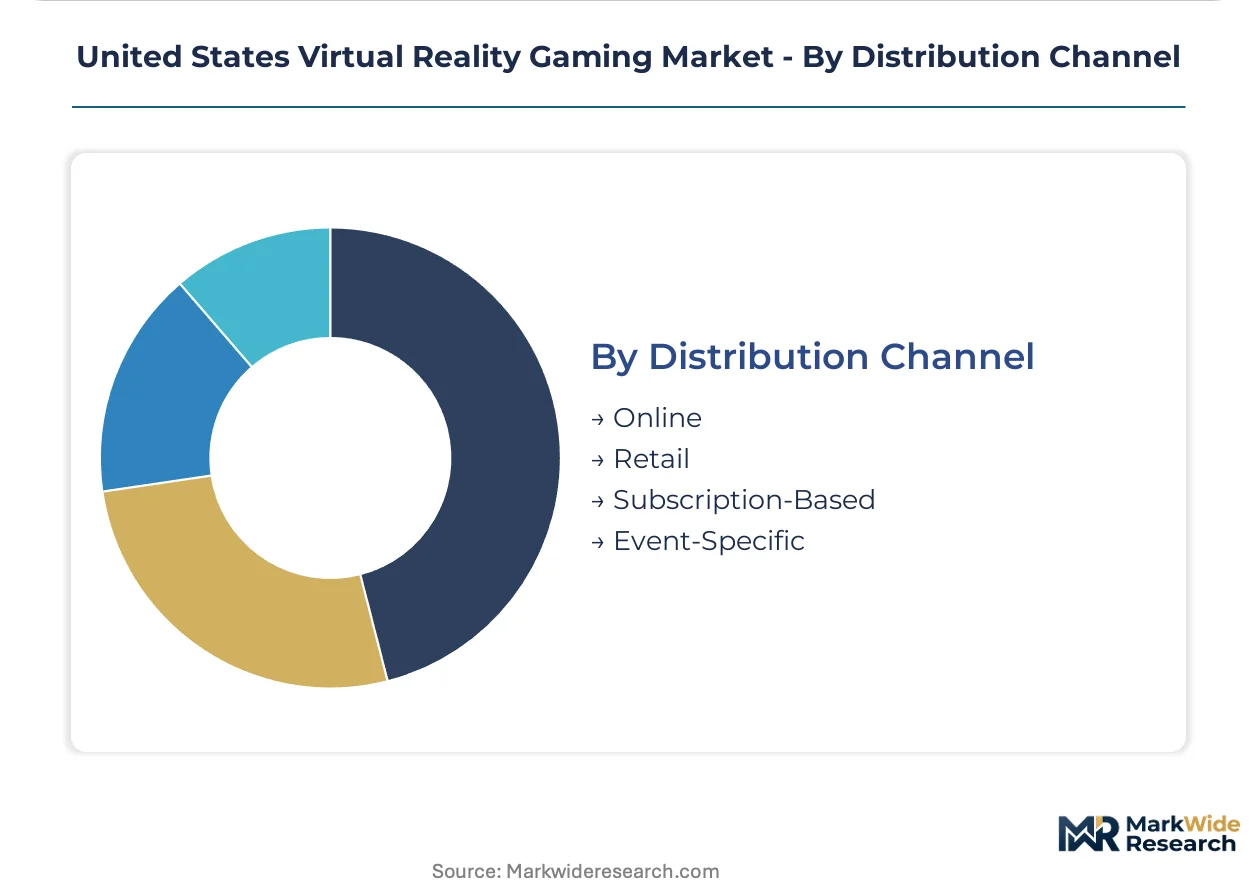
Distribution Channel:
Channel selection determines customer acquisition costs and lifetime value profiles, with digital storefronts capturing margin from physical retail while subscription models create recurring revenue predictability.
- Online:Meta Horizon Store and SteamVR dominate digital distribution, with the FTC's commission scrutiny forcing alternative payment rail experiments. California's SB-478 transparency mandates accelerate disclosure requirements for subscription billing practices.
- Retail:Best Buy and specialized gaming chains provide hands-on demonstration critical for first-time VR adopters, though shelf space competition intensifies.
- Subscription-Based:All-you-can-play libraries reduce per-title purchase friction, particularly attractive to Casual Gamers with uncertain genre preferences.
- Event-Specific:Convention and tournament licensing creates burst revenue patterns tied to E3, PAX, and esports calendar cycles.
Online captures the dominant transaction volume; Subscription-Based is gaining share fastest through hardware bundle partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between coastal technology clusters and interior expansion corridors. California's developer density sustains premium hardware adoption curves, while Texas and Florida metros concentrate location-based entertainment venue buildouts. Federal spectrum allocations and state-level procurement mandates reshape regional deployment timelines.
California
Venture capital concentration in San Francisco and Los Angeles sustains early-stage studio formation and hardware beta testing. The state's SB-478 transparency mandates force subscription billing disclosure reforms on digital storefronts. San Jose and San Diego anchor the densest headset manufacturing and software engineering talent pools nationwide.
Texas
Location-based entertainment chains in Dallas-Fort Worth and Houston pioneered hardware-content unbundling procurement models. State education agencies channel federal ESSER funds toward STEM-aligned immersive learning pilots in Austin and San Antonio school districts. Dallas anchors the largest multiplayer VR arena operator concentration outside California.
Florida
Orlando's tourism infrastructure supports high-throughput location-based entertainment venues retrofitting pancake-optic hardware. State procurement offices navigate COPPA-compliant content libraries for K-12 institutional buyers. Miami and Tampa Bay clusters concentrate medical-therapeutic VR applications seeking FDA breakthrough device pathways.
New York
Consumer protection statutes in New York City and Albany shape refund policy standards that propagate to national digital storefronts. The state's entertainment industry unions influence labor standards for VR content production studios. Brooklyn and Manhattan host specialized indie developers focused on narrative adventure genres.
Washington
Seattle's PC-building culture sustains enthusiast-tier tethered system demand among professional gamers and content creators. State-level privacy regulations intersect with headset biometric data collection practices. Bellevue and Redmond clusters concentrate engine optimization talent for mobile chipset performance tuning.
United States Virtual Reality Gaming Market Key Industry Players
Capability concentration sits with specialized content studios; scale advantage sits with vertically integrated platform operators. The market structure stratifies across three tiers: first-party hardware-software ecosystems, open distribution architectures, and niche content specialists. Dominant competitive moves include exclusive title acquisition and direct-to-venue content licensing that bypasses platform commission structures.
Within the specialized content tier, Schell Games exemplifies educational and enterprise-adjacent development with sustained IP investment, while Survios anchors location-based entertainment content pipelines. Meta occupies the integrated platform position, capturing value across hardware, operating systems, and storefront layers. Valve represents the open-architecture counterweight through SteamVR's distribution infrastructure.
| Leading Market Players |
|---|
| Schell Games |
| Rec Room |
| Meta |
| Polyarc |
| ForeVR Games |
| Valve |
| Survios |
| Bigscreen |
| Beat Games |
| Others |
Cost & Logistics Intelligence
The Port of Long Beach freight corridor channels micro-OLED display panels from Asian foundries through California distribution hubs, compressing logistics windows for standalone headset manufacturers while amplifying cost differentiation between premium PC-tethered bundles and mass-market standalone SKUs.
Pricing Analysis
Long-term offtake contracts dominate hardware procurement between California arcade operators and Shenzhen manufacturing partners, locking in component costs across 18-24 month cycles. Spot market exposure concentrates in memory and sensor modules where Korean suppliers exercise pricing power. Three-tier pricing structure across premium, standard, and economy levels separates enthusiast PC-tethered systems from console-integrated bundles and entry-level mobile viewers. Cost compression in the standalone tier is intensifying because Qualcomm Snapdragon XR chip allocation constraints favor volume commitments from Meta and ByteDance. Casual gamers exhibit highest price sensitivity, while professional gamers and institutional buyers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for headset manufacturers sourcing pancake optic assemblies and lithium-polymer battery packs. Taiwan anchors advanced semiconductor fabrication for AI rendering chipsets, while Japan and South Korea supply high-refresh display controllers and precision IMU sensors. Raw material dependencies center on rare earth magnets for haptic motors, optical-grade polymers for lens substrates, and copper-gold alloy bonding wire for chip packaging. Distribution runs through direct-to-venue relationships for location-based entertainment chains, bypassing traditional retail markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Virtual Reality Gaming Market rewards defensive moats built through exclusive content libraries and FCC spectrum coordination, with regulatory entrenchment in unlicensed millimeter-wave allocations creating durable barriers against hardware commoditization.
For Market Incumbents: Build exclusive content moats through direct studio acquisitions and first-party IP development that locks competitors out of high-engagement genres. Secure FCC pre-certification for 60GHz wireless implementations before spectrum allocation decisions finalize, denying latecomers technical parity. Channel control through owned storefronts defends against subscription billing transparency mandates eroding platform economics. Capacity addition in Texas and Florida venue markets consolidates location-based entertainment distribution before regional competitors achieve scale. For New Entrants and Emerging Players: Midwest commercial real estate corridors in Chicago and Detroit represent the most penetrable entry point for location-based entertainment venue buildouts, with lower rent burdens and underserved demand relative to coastal saturation. Educational content modules for ESSER-funded school districts offer institutional procurement pathways insulated from consumer hardware margin compression. Direct-to-venue licensing models bypass Meta Horizon Store commission structures and establish recurring revenue without platform dependency. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy entertainment conglomerates divesting underperforming immersive technology divisions amid portfolio rationalization. Long-term viability hinges on regulatory capture in therapeutic VR pathways and enterprise training adjacencies rather than consumer entertainment cyclicality. Watch FDA breakthrough device designation velocity as the inflection indicator separating prescription-based distribution models from discretionary hardware purchases.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Content Acquisition | Meta's first-party studio purchases deny SteamVR catalog parity in social multiplayer genres. |
| FCC Spectrum Pre-Certification | Early 60GHz compliance locks in wireless latency benchmarks for free-roam venue formats. |
| Direct-to-Venue Licensing | Texas arcade chains bypass platform commissions through studio-direct content procurement. |
| Educational Content Certification | COPPA-compliant modules unlock ESSER funding streams for K-12 institutional buyers. |
| Pancake Optic Retrofit Programs | Las Vegas venues compress equipment footprints while extending hardware depreciation schedules. |
Research Approach
Two parallel data streams informed the analysis: structured interviews with hardware engineering leads at headset manufacturers, content studio creative directors, arcade venue operators, and FCC regulatory affairs specialists, combined with secondary validation against SEC filings, EIA spectrum allocation dockets, and ESSER fund disbursement records. Bottom-up triangulation across component bill-of-materials estimates and top-down reconciliation with platform revenue disclosures anchored market sizing integrity.
Forecast inputs span hardware form factor migration curves, content development pipeline velocity, and institutional procurement cycle timing across the projection horizon. Segmentation dimensions modeled include technology tier, content genre, end-user archetype, and distribution channel structure. CAGRs derive from installed base growth rates multiplied by per-user revenue trajectories, with cross-validation against venture capital deployment patterns in San Francisco and Seattle metro clusters.
Practitioners should monitor FCC spectrum reallocation proceedings, micro-OLED foundry capacity announcements, and ESSER fund expiration timelines for early signals demanding forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
LAMEA Gaming Posters Market
Gaming
LAMEA in-Game Advertising Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
Mobile and Handheld Gaming Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Traditional Casual Games Market
Gaming
Australia Gaming Gadgets Market
Gaming
Mobile Gaming Market
Gaming
China in-Game Advertising Market
Gaming
Videogames Market
Gaming
FPS Game Market
Gaming
Advanced Digital Gaming Market
Gaming
Slot Machine Market
Gaming
3D Gaming Technology Market
Gaming
North America Gaming Hardware and Accessories Market
Gaming
Global Online Gambling and Betting Market