
 Arcade Cabinet Market | 2026-2036
Arcade Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Arcade Cabinet Market Analysis
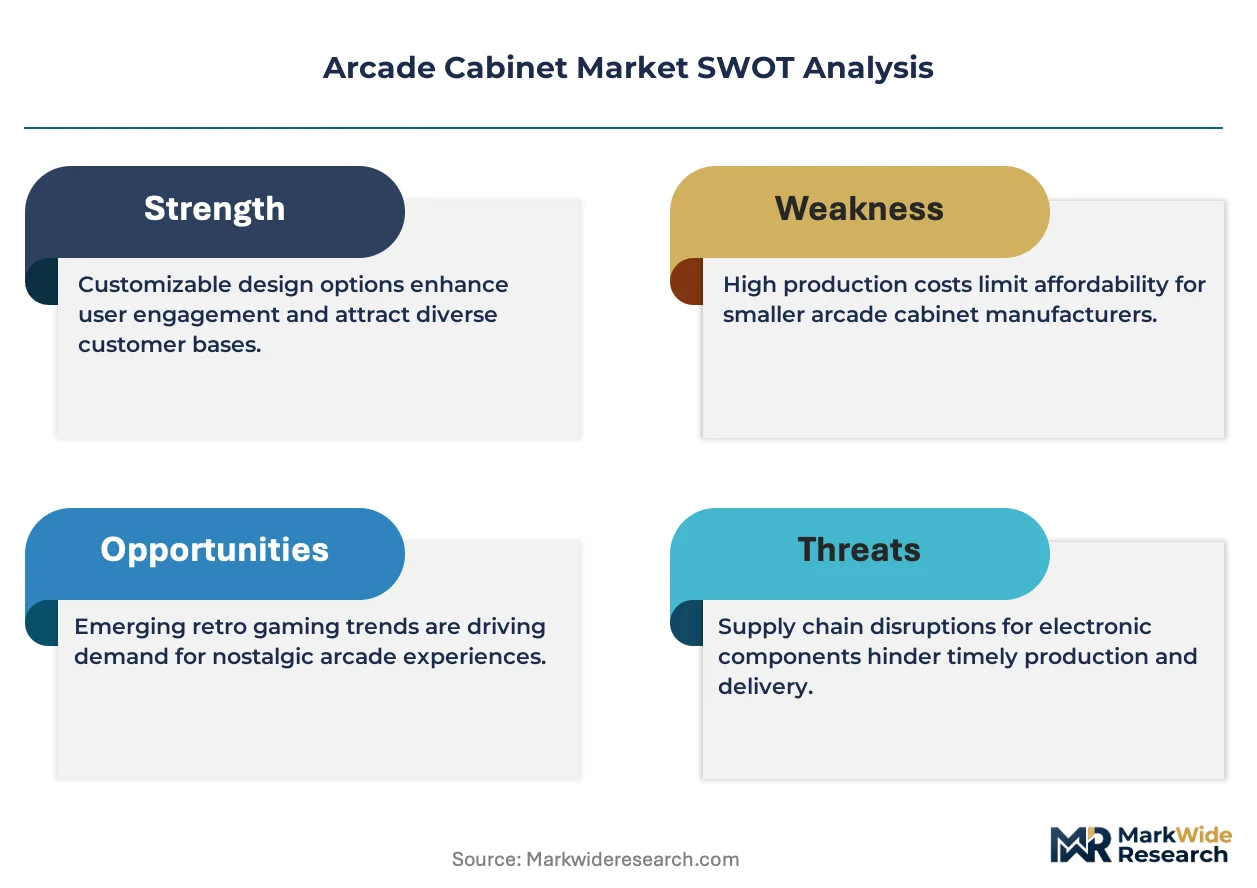
Modular cabinet configurations with swappable control decks and interchangeable game boards is repositioning buyer procurement patterns across the installed base. Raw Thrills leverages its proprietary hardware platforms to sustain high-margin refresh cycles in North American entertainment venues. Sega Amusements USA anchors its competitive stance through licensed intellectual property tied to enduring arcade franchises. LAI Games differentiates via prize-integrated and redemption-oriented cabinet designs that command premium floor placement.
An arcade cabinet is a self-contained gaming enclosure housing a display panel, control interface, power distribution system, and game processing hardware, typically constructed from engineered wood substrates, steel framing, and tempered glass viewing surfaces designed for high-cycle commercial use. Commercial Cabinets dominate unit volume as operators prioritize standardized form factors that simplify maintenance and maximize floor space efficiency, while Home Arcade Machines represent the fastest-expanding margin pool as collectors and residential buyers seek authentic reproductions with modern connectivity. Emulation Software is displacing legacy ROM-based architectures across refurbishment channels, though Digital Displays remain the critical upgrade vector as 4K panel costs decline.
The US Consumer Product Safety Commission enforces electrical safety and tip-over stability standards that directly shape cabinet chassis engineering and anchoring requirements for commercial installations. The EU F-Gas Regulation and REACH compliance obligations constrain foam insulation and refrigerant choices in prize-vending hybrid cabinets sold across European member states. Japan's Ministry of Economy, Trade and Industry (METI) oversees game content ratings and amusement machine certifications that gate market access for imported hardware. Stakeholders must monitor evolving e-waste directives and right-to-repair legislation that could mandate component standardization and extend hardware lifecycles.
Market Dynamics
Modular cabinet architectures with swappable control decks and interchangeable game boards are restructuring operator procurement patterns across the installed base. This hardware flexibility allows venues to refresh content without full cabinet replacement, compressing capital deployment cycles and reshaping manufacturer revenue models toward recurring software licensing.
Growth Catalysts
- Family entertainment center expansion:Venue operators in the United States are scaling machine fleets to capture rising foot traffic at experiential retail destinations. These deployments favor durable, high-cycle commercial hardware over consumer-grade alternatives.
- REACH compliance differentiation:European Union regulatory adherence on foam insulation and refrigerant choices in prize-vending hybrids creates procurement preference for certified manufacturers. METI certification requirements in Japan similarly gate market access for imported hardware.
- 4K panel cost decline:Digital display upgrade vectors are accelerating as LCD and OLED panel prices compress, enabling widespread refresh of legacy CRT and early LCD cabinets across refurbishment channels.
Market Restraints
- Engineered wood substrate volatility:Cabinet chassis construction depends on MDF and plywood inputs subject to construction-sector demand competition and freight cost fluctuations.
- Japan IP licensing concentration:Premium cabinet design and enduring arcade franchise intellectual property remain concentrated among Tokyo and Osaka-based licensors, creating dependency risk for non-Japanese manufacturers.
- Emulation software substitution:Software-based ROM emulation is displacing proprietary hardware architectures in refurbishment markets, compressing margins on legacy game board sales.
Strategic Opportunities
- Home arcade machine underpenetration:Residential collectors and enthusiasts in Germany and the United Kingdom represent expanding demand for authentic reproduction cabinets with modern connectivity features.
- Right-to-repair legislative tailwinds:Proposed component standardization mandates in multiple jurisdictions could extend hardware lifecycles and create aftermarket service revenue pools for technical support providers.
- Prize-integrated redemption convergence:Hybrid cabinets combining skill-based gameplay with ticket dispensing are commanding premium floor placement at family entertainment centers seeking diversified revenue streams.
Industry Challenges
- Electrical safety certification timelines:US Consumer Product Safety Commission tip-over stability and electrical safety testing creates multi-month approval delays for new cabinet chassis designs.
- Legacy system integration friction:Emulation software deployment requires backward compatibility with proprietary control interfaces and power distribution architectures from 1990s-era hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arcade Cabinet Market |
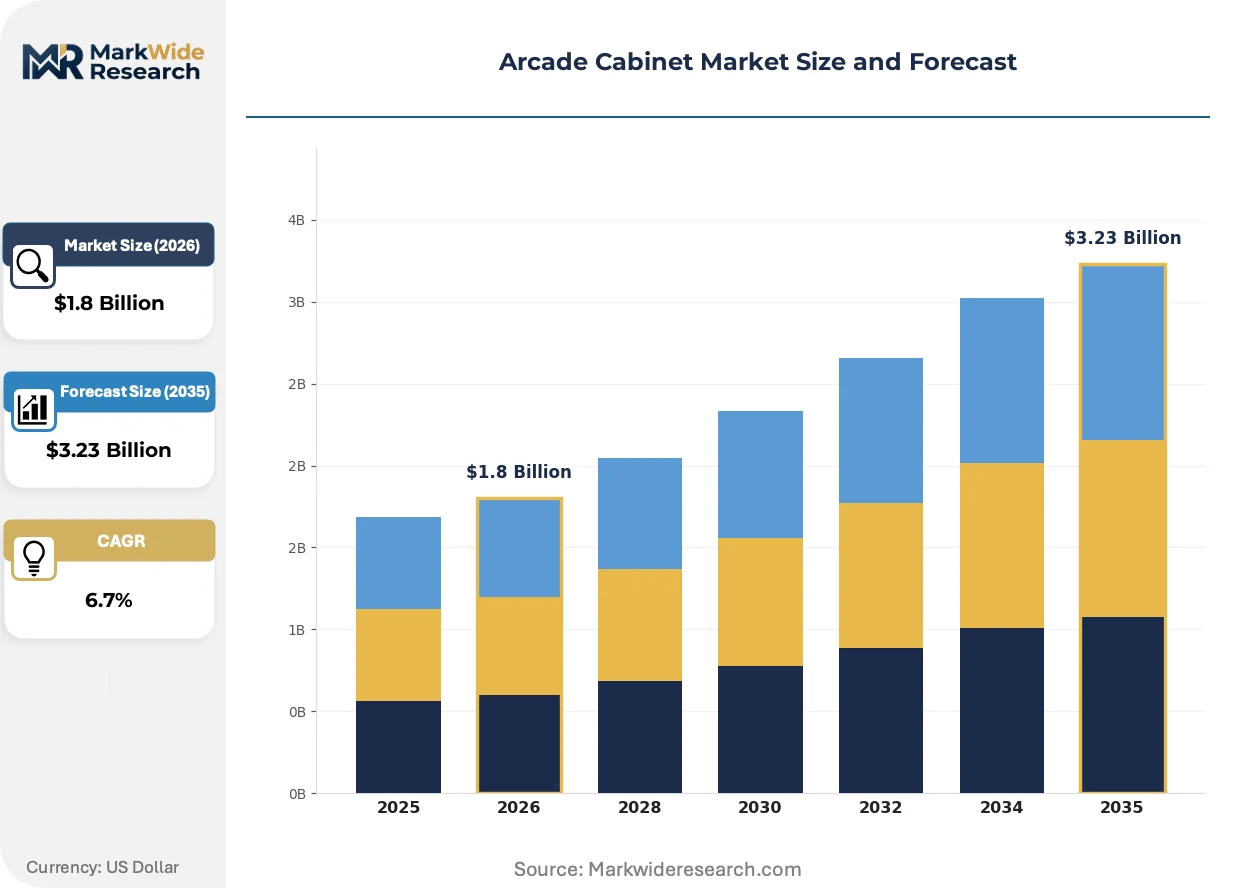
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Cabinets, Home Arcade Machines, Cocktail Cabinets, Tabletop Units Technology: Digital Displays, LED Lighting, Emulation Software, Cloud Gaming Application: Entertainment Venues, Home Use, Arcade Halls, Trade Shows End User: Gamers, Collectors, Operators, Businesses |
| Companies Covered | Andamiro USA, Coastal Amusements, Raw Thrills, Smart Industries, Valley-Dynamo, Innovative Concepts in Entertainment, Sega Amusements USA, LAI Games, Bay Tek Entertainment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arcade Cabinet Market Emerging Trajectories
Swappable hardware modules and digital content distribution are displacing fixed-configuration cabinet sales across commercial and residential channels. This shift rewards manufacturers with software platform capabilities while pressuring pure hardware assemblers.
LED-based display technology is expanding into premium cabinet segments previously served by LCD panels. Japanese and South Korean manufacturers are adopting micro-LED and advanced OLED configurations for location-based entertainment venues seeking visual differentiation. This technology is expanding into mid-tier product lines as panel yields improve and unit costs compress toward LCD parity.
The EU F-Gas Regulation is constraining refrigerant and foam insulation choices in prize-vending hybrid cabinets sold across European member states. Manufacturers serving this segment are reformulating thermal management systems and respecifying cabinet insulation materials to maintain CE marking eligibility. Prize-integrated designs with cooling-dependent mechanics face the steepest compliance engineering requirements.
Collector-driven procurement through direct-to-consumer channels is fragmenting traditional distributor relationships in the home arcade segment. Enthusiast buyers in the United States and Australia are sourcing cabinets via manufacturer websites and specialized forums, bypassing regional equipment wholesalers. This channel shift concentrates margin capture with vertically integrated producers while reducing independent distributor relevance.
Arcade Cabinet Market Segmentation
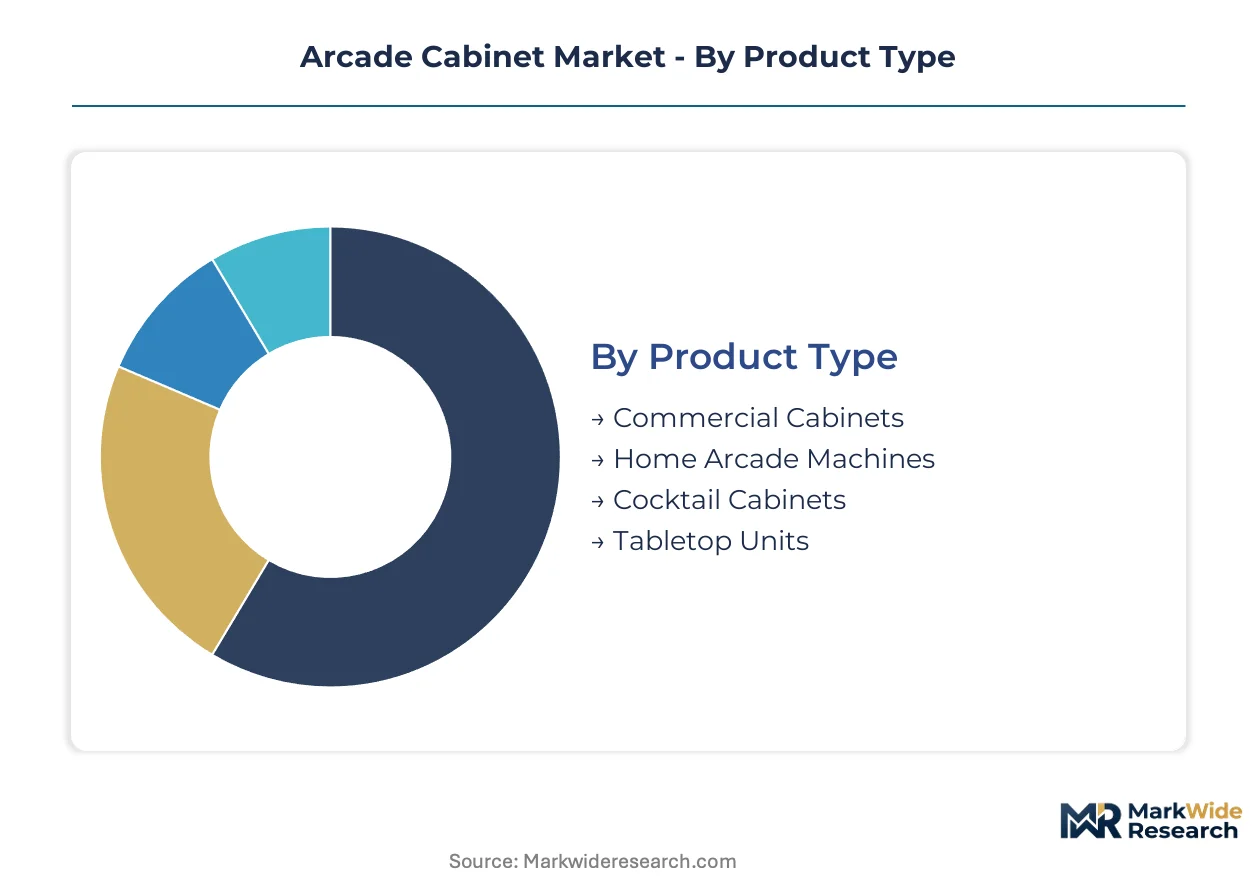
Segmentation in the arcade cabinet market determines procurement patterns across venues with vastly different capital deployment cycles. Commercial operators prioritize durability and serviceability, while residential buyers emphasize authenticity and connectivity features. Understanding these divergent requirements shapes manufacturer product roadmaps and distribution channel strategies.
Product Type:
Capital intensity varies sharply across product categories, with full-size commercial cabinets demanding the highest upfront investment in structural engineering and safety certification.
- Commercial Cabinets:Engineered wood substrates, steel framing, and tempered glass surfaces built for high-cycle commercial use. Demand concentrates at family entertainment centers in the United States as operators scale machine fleets to capture experiential retail foot traffic. US Consumer Product Safety Commission tip-over stability requirements extend certification timelines and chassis engineering costs.
- Home Arcade Machines:Authentic reproduction cabinets with modern connectivity features targeting residential collectors. Demand is expanding most quickly in Germany and the United Kingdom as enthusiast buyers bypass traditional distributors through direct-to-consumer channels.
- Cocktail Cabinets:Table-height horizontal displays designed for social multiplayer configurations.
- Tabletop Units:Compact footprint cabinets suited for limited-space venues and residential game rooms.
Most installed capacity flows through Commercial Cabinets. Expansion is steepest in Home Arcade Machines.
Technology:
Technology selection determines upgrade cycles and margin profiles, with display hardware commanding the largest share of bill-of-materials costs.
- Digital Displays:LCD and OLED panels replacing legacy CRT and early LCD configurations across refurbishment channels. 4K panel cost decline is accelerating refresh cycles as price compression enables widespread deployment. Japan and South Korean manufacturers are adopting micro-LED for location-based entertainment venues seeking visual differentiation.
- Emulation Software:ROM-based architecture displacement across refurbishment markets, requiring backward compatibility with proprietary 1990s-era control interfaces. Software licensing models are compressing margins on legacy game board sales while extending hardware lifecycles.
- LED Lighting:Ambient and accent illumination systems for cabinet aesthetics and player attraction.
- Cloud Gaming:Network-delivered content reducing local processing hardware requirements.
Volume concentration sits with Digital Displays. Technology transition is most rapid in Emulation Software.
Application:
Application context dictates durability specifications and revenue model design, with commercial venues requiring multi-year depreciation schedules.
- Entertainment Venues:Family entertainment centers and experiential retail destinations prioritizing durable, high-cycle hardware. Operators in the United States are scaling machine fleets to diversify revenue streams beyond traditional amusement offerings.
- Arcade Halls:Dedicated amusement facilities emphasizing premium cabinet placement and prize-integrated redemption convergence. Japan remains the epicenter of premium cabinet design and intellectual property licensing for this channel.
- Home Use:Residential installations where collectors prioritize authentic reproduction aesthetics.
- Trade Shows:Temporary deployment configurations emphasizing rapid setup and transportability.
Revenue generation concentrates in Entertainment Venues. Prize-integrated redemption convergence is expanding fastest in Arcade Halls.
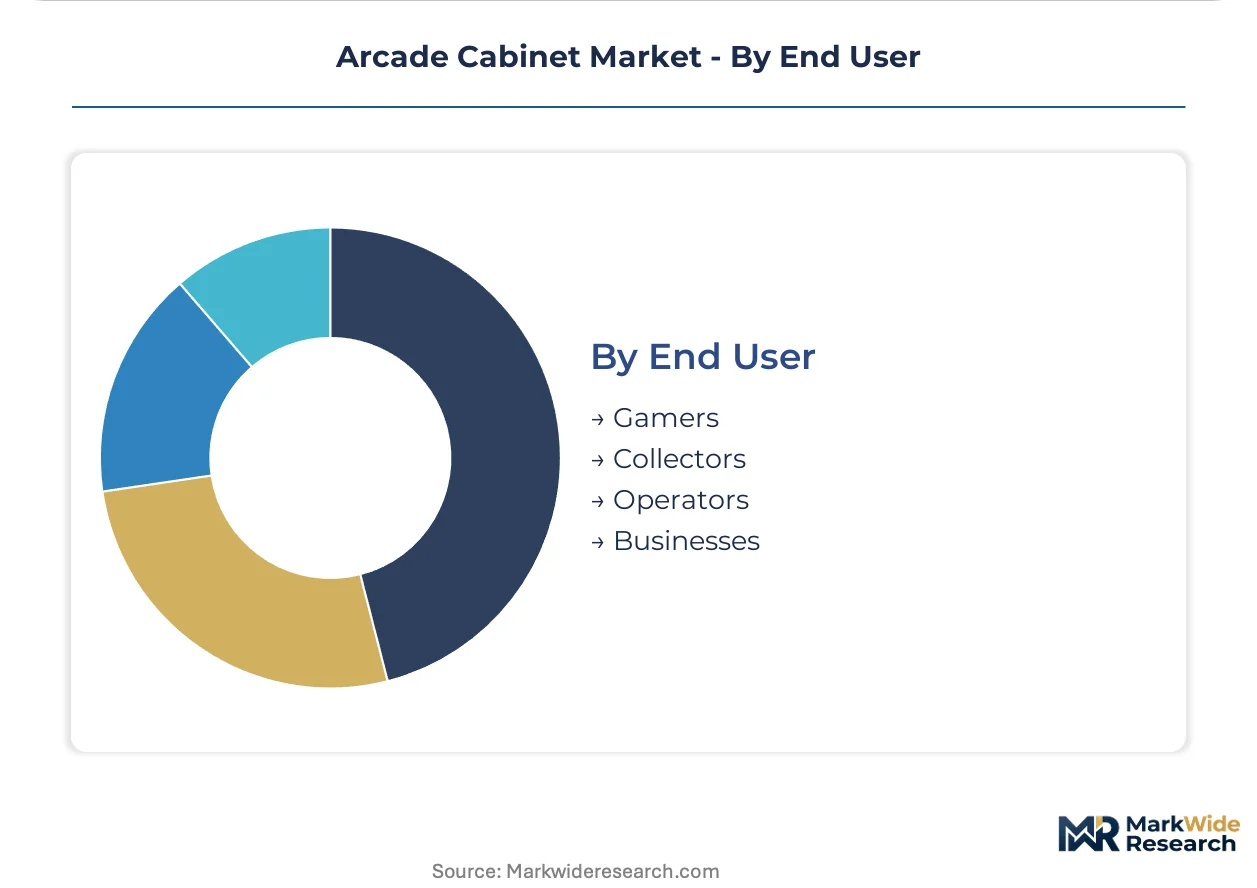
End User:
End user identity shapes purchasing authority and decision criteria, with institutional buyers following formal procurement processes absent in consumer transactions.
- Operators:Venue owners and fleet managers prioritizing total cost of ownership and maintenance standardization. Procurement patterns favor modular cabinet architectures with swappable control decks that compress capital deployment cycles.
- Collectors:Enthusiast buyers in the United States and Australia sourcing cabinets via manufacturer websites and specialized forums, fragmenting traditional distributor relationships and concentrating margin capture with vertically integrated producers.
- Gamers:End consumers whose preferences influence operator content selection.
- Businesses:Corporate buyers deploying cabinets for employee amenities or customer waiting areas.
Procurement volume flows through Operators. Direct channel expansion is most pronounced among Collectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered modern arcade cabinet manufacturing during the 1970s and 1980s, establishing design conventions and intellectual property licensing frameworks that persist across the industry. The sector now spans manufacturing clusters in East Asia, North American entertainment venue deployment, and European regulatory compliance zones.
United States
Family entertainment centers in Texas, Florida, and California are scaling machine fleets to capture experiential retail foot traffic. The US Consumer Product Safety Commission enforces tip-over stability and electrical safety standards that extend certification timelines for new chassis designs. Chicago and Los Angeles serve as distribution hubs where operators source modular cabinets with swappable control decks.
Japan
Tokyo and Osaka house the epicenter of premium cabinet design and enduring arcade franchise intellectual property licensing. METI oversees game content ratings and amusement machine certifications that gate market access for imported hardware. Chubu region manufacturers supply micro-LED display configurations for location-based entertainment venues seeking visual differentiation.
Germany
Residential collectors in Bavaria and North Rhine-Westphalia are expanding procurement of authentic reproduction cabinets with modern connectivity features. REACH compliance obligations on foam insulation and refrigerant choices constrain prize-vending hybrid cabinet specifications. Berlin-based distributors face fragmentation as enthusiast buyers bypass traditional channels through direct-to-consumer sourcing.
United Kingdom
Home arcade machine demand concentrates in Greater London and the Southeast among enthusiast buyers seeking direct manufacturer relationships. CE marking requirements align with EU F-Gas Regulation constraints on thermal management systems in prize-integrated designs. Midlands refurbishment channels are deploying emulation software to displace legacy ROM-based architectures.
South Korea
Seoul Capital Area manufacturers are adopting advanced OLED configurations for location-based entertainment venues at price points approaching LCD parity. Domestic content licensing supplements Japan-sourced intellectual property for regional arcade hall deployment. Busan-Ulsan industrial clusters supply steel framing and tempered glass components for export markets.
Arcade Cabinet Market Vendor Landscape
Premium-margin players sit above commodity-margin players across intellectual property control and hardware platform differentiation. The vendor base spans vertically integrated producers with captive software ecosystems, specialized fabricators focused on redemption-integrated mechanics, and regional assemblers serving refurbishment channels. Three archetypes dominate: IP-licensed platform holders, modular hardware specialists, and prize-mechanics integrators. Competitive moves concentrate on technology licensing partnerships and backward integration into display panel sourcing.
Within the IP-licensed tier, Sega Amusements USA and Raw Thrills anchor premium positioning through proprietary hardware platforms and franchise content control. LAI Games exemplifies the prize-mechanics integrator archetype, commanding premium floor placement via redemption-oriented cabinet designs. These three entities collectively represent the competitive spectrum from software-centric platform holders to hybrid gameplay-mechanics specialists.
| Leading Market Players |
|---|
| Andamiro USA |
| Coastal Amusements |
| Raw Thrills |
| Smart Industries |
| Valley-Dynamo |
| Innovative Concepts in Entertainment |
| Sega Amusements USA |
| LAI Games |
| Bay Tek Entertainment |
| Others |
Supply Flow & Price Mechanics
Family entertainment center operators in the United States anchor procurement volume and compress pricing power toward standardized commercial cabinets with modular architectures. This buyer concentration rewards manufacturers who bundle recurring software licensing with hardware refresh cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IP-licensed platform holders from modular hardware specialists and regional assemblers. Price differentiation hinges on METI certification tier and after-sales service bundling. Cost compression in economy-tier commercial cabinets is intensifying because emulation software substitution erodes proprietary game board margins. Home arcade collectors exhibit the lowest price sensitivity, while refurbishment channel buyers drive the hardest volume negotiations.
Supply Chain Analysis
Domestic-content mandates in Japan and South Korea are reshaping sourcing patterns for display panels and precision steel framing. Manufacturing gravity centers on Japan, South Korea, and China, with Chubu region micro-LED foundries and Busan-Ulsan steel clusters feeding export markets. The supply chain draws from engineered wood substrates in Southeast Asia, tempered glass from South Korean float lines, and proprietary control interface ASICs from Japanese fabs. Single-source vulnerability in 4K OLED panel supply creates bottleneck risk. Distribution runs through Chicago and Los Angeles hub warehouses serving North American venue operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where US Consumer Product Safety Commission tip-over stability mandates and EU F-Gas refrigerant constraints continuously reshape engineering specifications and procurement preferences.
For Market Incumbents: Deploy backward integration into display panel sourcing to defend margin position against 4K cost compression. Secure long-term IP licensing agreements with Tokyo and Osaka-based franchise holders to lock out emulation software competitors. METI certification investment creates switching costs for venue operators scaling machine fleets. For New Entrants and Emerging Players: Capture underpenetrated home arcade demand in Germany and the United Kingdom through direct-to-consumer channels bypassing Berlin-based distributors. Prize-integrated redemption convergence at family entertainment centers offers the most penetrable white space. Lead with modular cabinet architectures enabling rapid content refresh without full hardware replacement. For Investors and Strategic Acquirers: Entertainment venue operators are the most active acquirer in this space, seeking captive hardware supply to secure floor placement priority. Long-term viability rests on software platform capabilities extending hardware lifecycles. Watch right-to-repair legislative progression across multiple jurisdictions as the inflection signal for aftermarket service revenue pools.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Hardware Platform Development | Swappable control decks compress capital deployment cycles for US family entertainment center operators. |
| IP Licensing Partnership Expansion | Tokyo-based franchise agreements secure premium floor placement at Japanese arcade halls. |
| Direct-to-Consumer Channel Buildout | Manufacturer websites capture margin concentration from German and UK collector procurement. |
| Micro-LED Display Integration | Chubu region panel sourcing enables visual differentiation at location-based entertainment venues. |
| REACH Compliance Engineering Investment | Reformulated thermal management maintains CE marking eligibility for EU prize-vending hybrids. |
Methodological Framework
Bottom-up venue operator modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with family entertainment center fleet managers, arcade hall operators, cabinet procurement directors, and redemption mechanics engineers combined with secondary validation from US Consumer Product Safety Commission filings, METI amusement machine certification databases, EU F-Gas Regulation compliance registries, and SEC 10-K disclosures from publicly traded entertainment equipment manufacturers. Triangulation across these sources yields volume and pricing estimates.
Historical trendline analysis of commercial cabinet deployment cycles and home arcade machine direct-channel sales established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, display technology tier, application context, and end-user procurement authority. CAGRs derive from fitted trend extrapolation adjusted for regulatory milestone impacts and technology substitution elasticities. Forecast inputs incorporate 4K panel cost decline curves and emulation software penetration rates.
Regulatory timeline acceleration, raw material freight cost volatility, and intellectual property licensing concentration are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about modular architecture adoption rates and right-to-repair legislative progression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Serious Games Market
Gaming
Europe Video Game Software Market
Gaming
PC Games Market
Gaming
VR Gaming Controller Market
Gaming
Asia-Pacific Video Game Software Market
Gaming
Online Casual Games Market
Gaming
Galgames Market
Gaming
Video Game Software Market
Gaming
RPG Games Market
Gaming
Shooter Game Market
Gaming
Australia Gaming Accessories Market
Gaming
North America Gaming Hardware and Accessories Market
Gaming
Global Subscription-Based Gaming Market
Gaming
Cloud Gaming Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
South Korea Virtual Reality Gaming Market