
 AAA Games Market | 2026-2036
AAA Games Market Size, Share, and Industry Trends Forecast 2026-2036
AAA Games Market Insights
The EU Green Deal's digital sustainability reporting requirements is repositioning how AAA studios measure server energy consumption and hardware lifecycle impacts. Electronic Arts leverages its Frostbite engine optimization to reduce datacenter load across European markets. Sony Interactive Entertainment anchors premium console production through captive semiconductor partnerships in Japan and Taiwan. Nintendo sustains hardware-software integration margins by controlling proprietary chipset design for the Switch platform.
AAA games represent interactive entertainment software developed with production budgets exceeding typical industry thresholds, requiring specialized game engines, motion capture pipelines, and real-time rendering architectures capable of 4K resolution at 60 frames per second. Their primary commercial purpose centers on delivering narrative-driven, technologically intensive experiences that justify premium pricing across dedicated hardware ecosystems. Console platforms dominate revenue contribution due to locked ecosystems and software licensing structures, while cloud gaming represents the fastest-growing distribution vector as infrastructure latency decreases. The shooter genre maintains the largest concurrent player base, though RPG segments capture superior per-user monetization through expansion content and live-service models.
The Federal Trade Commission scrutinizes subscription bundling practices, while China's National Press and Publication Administration controls title approval timelines and youth playtime limits. Japan's METI promotes esports professionalization through visa classifications and venue standards. Stakeholders must monitor how fragmented regulatory approaches to loot box disclosures, cross-platform interoperability mandates, and AI-generated content labeling reshape development priorities and regional go-to-market sequencing.
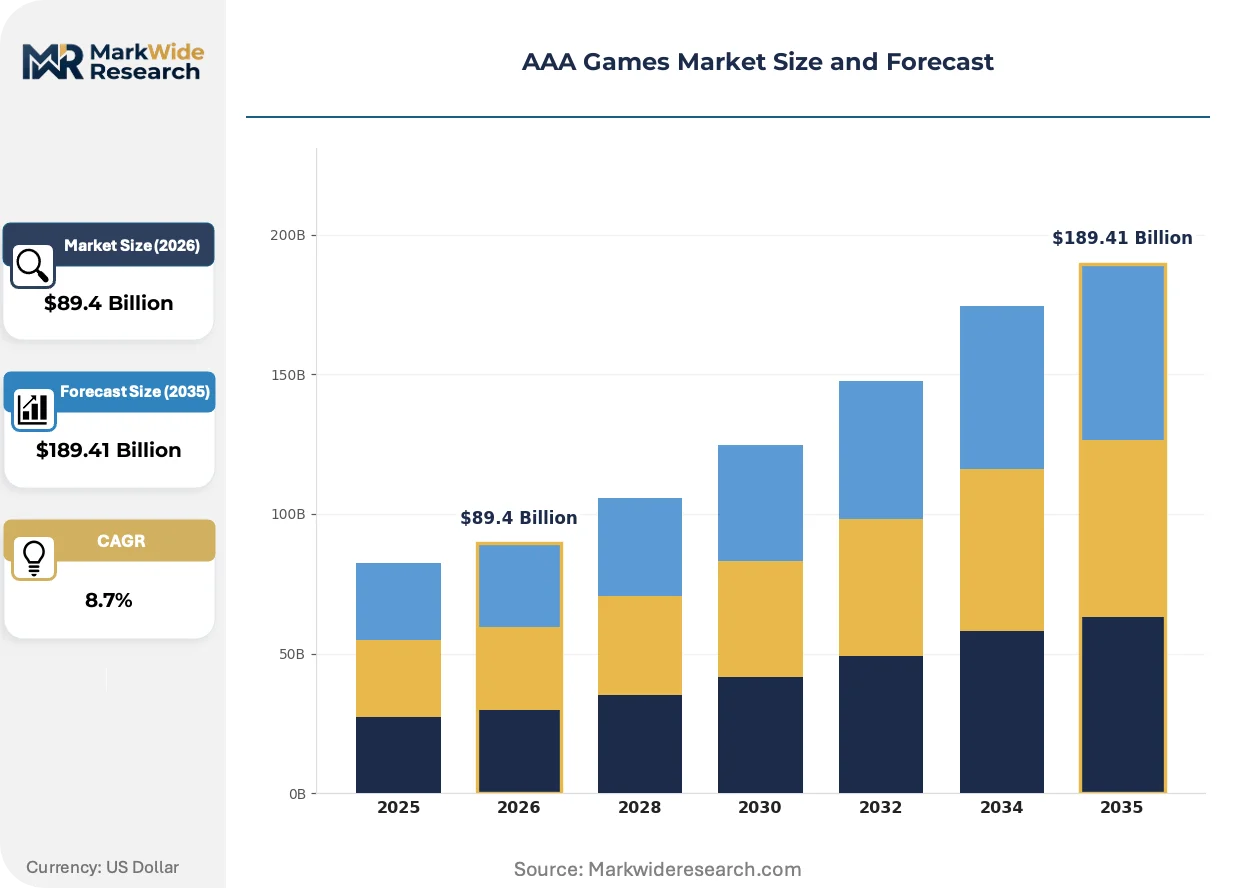
Market Dynamics
The live-service transition is fragmenting AAA revenue recognition across multi-year content roadmaps, forcing studios to restructure development pipelines around continuous player engagement metrics rather than discrete launch windows.
Growth Catalysts
- Cloud gaming infrastructure maturation:Latency reduction below 20 milliseconds in 5G networks is expanding addressable audiences beyond console-owners. Edge computing deployments by telecom operators are compressing streaming costs for publishers.
- EU Digital Services Act:Platform transparency mandates are reducing storefront commission disputes and clarifying content moderation liabilities for cross-border distribution. Studios gain predictable operating frameworks across member states.
- South Korea's PC bang ecosystem:Venue-based tournament licensing and professional visa pathways under METI-equivalent structures are cultivating concentrated esports talent pools that feed into AAA competitive titles.
Market Restraints
- Semiconductor supply concentration:Advanced node GPU fabrication depends on Taiwan and South Korea foundry capacity, creating vulnerability to geopolitical disruption or export control expansion.
- China's approval timeline volatility:The National Press and Publication Administration's discretionary title licensing creates revenue recognition uncertainty for publishers with significant exposure to mainland distribution.
- Live-service talent scarcity:Economies with established games-as-a-service expertise—Finland, Sweden, South Korea—command premium compensation for systems designers and economy balancing specialists.
Strategic Opportunities
- India's underpenetrated console base:Localized pricing and regional server infrastructure by platform holders is unlocking first-time hardware adoption in tier-two cities.
- Generative AI content pipelines:Convergence of procedural generation and large language models is compressing localization costs and concept art production timelines for narrative-heavy titles.
- Japan's esports professionalization:METI visa classifications and venue certification standards are creating regulatory tailwinds for tournament organizers and team franchise investments.
Industry Challenges
- Cross-platform certification complexity:Sony, Microsoft, and Nintendo maintain divergent technical compliance standards, forcing redundant QA cycles and release date synchronization friction.
- AI-generated asset IP ambiguity:Unclear training data licensing precedents across US, EU, and Japanese jurisdictions is delaying adoption of generative tools in commercial pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AAA Games Market |
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $189.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: PC, Console, Mobile, Cloud Gaming Genre: Action, RPG, Adventure, Shooter Distribution Channel: Digital Download, Retail, Subscription Service, Streaming Player Type: Casual, Competitive, Professional, Social |
| Companies Covered | Electronic Arts, Nintendo, Sony Interactive Entertainment, Ubisoft, Take-Two Interactive, Tencent Games, Epic Games, Activision Blizzard, Microsoft Gaming, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AAA Games Market Trends and Innovations
Player ownership expectations are shifting from perpetual licenses to persistent identity across titles, reshaping how studios architect account systems and monetization touchpoints.
Blockchain-based item verification is decentralizing digital asset provenance for cosmetic inventories. Early adopters in the collectible-driven shooter segment are piloting cross-title item portability. This architecture is decentralizing platform lock-in by enabling wallet-based identity independent of console ecosystems.
The EU AI Act's transparency requirements for algorithmic systems are mandating disclosure of matchmaking and recommendation engines. Publishers must document training data provenance and decision logic for player-facing automation. Competitive multiplayer titles face the steepest compliance costs given the complexity of skill-rating algorithms.
Subscription fatigue is compressing individual title discovery on Xbox Game Pass and PlayStation Plus. Indie publishers report reduced day-one visibility as catalog depth dilutes editorial curation. France and Germany exhibit the highest churn sensitivity, with players cycling subscriptions around specific release calendars rather than maintaining continuous membership.
AAA Games Market Segmentation

Platform choice dictates development budget allocation, rendering pipeline complexity, and monetization architecture for AAA releases. Genre classification shapes live-service roadmaps and community engagement cadences. Distribution channel selection determines revenue recognition timing and platform holder relationship structures.
Platform:
Hardware ownership patterns drive initial addressable market sizing and technical specification baselines.
- Console:Locked ecosystem licensing structures generate predictable software revenue per unit. Sony's PlayStation and Microsoft's Xbox platforms concentrate premium pricing power in Japan and the United States through exclusive content pipelines and semiconductor supply partnerships.
- PC:Open hardware configurations demand scalable rendering architectures across GPU tiers. Steam and Epic Games Store distribution dominates in South Korea's PC bang venues and Germany's enthusiast builder communities, where upgrade cycles outpace console generations.
- Mobile:Touch-native interfaces require stripped-back control schemes and session-length optimization for commuter contexts.
- Cloud Gaming:Infrastructure latency thresholds below 20 milliseconds unlock browser-based access without hardware ownership.
Volume sits with Console; growth tilts toward Cloud Gaming.
Genre:
Engagement mechanics determine content production ratios and post-launch staffing models.
- Shooter:Competitive matchmaking infrastructure and seasonal battle pass systems sustain multi-year player retention. Call of Duty and Counter-Strike ecosystems command the largest concurrent user bases in the United States and Sweden through esports tournament integration.
- RPG:Narrative branching and character progression systems justify expansion content pricing. Final Fantasy and The Witcher franchises capture superior per-user monetization in Japan and Poland via cosmetic item economies and downloadable story modules.
- Action:Cinematic set-piece density drives marketing spend intensity and preview event budgets.
- Adventure:Exploration-focused design reduces competitive balance overhead but extends environmental art production timelines.
Shooter maintains installed base leadership; RPG climbs fastest on expansion attach rates.
Distribution Channel:
Go-to-market sequencing affects cash flow timing and platform commission structures.
- Digital Download:Direct storefront relationships eliminate physical manufacturing margin leakage. Steam's 30% commission standard and Epic Games Store's reduced revenue share alternative shape publisher platform negotiations in the United States and France.
- Subscription Service:Xbox Game Pass and PlayStation Plus bundle libraries compress individual title discovery but guarantee upfront revenue minimums. Microsoft and Sony compete for catalog exclusivity in the United Kingdom and Canada through minimum revenue guarantees.
- Retail:Boxed copy distribution sustains collector edition premiums and hardware bundle positioning.
- Streaming:Browser-based access removes installation friction for trial conversion.
Digital Download holds transaction volume; Subscription Service gains share fastest on catalog depth competition.
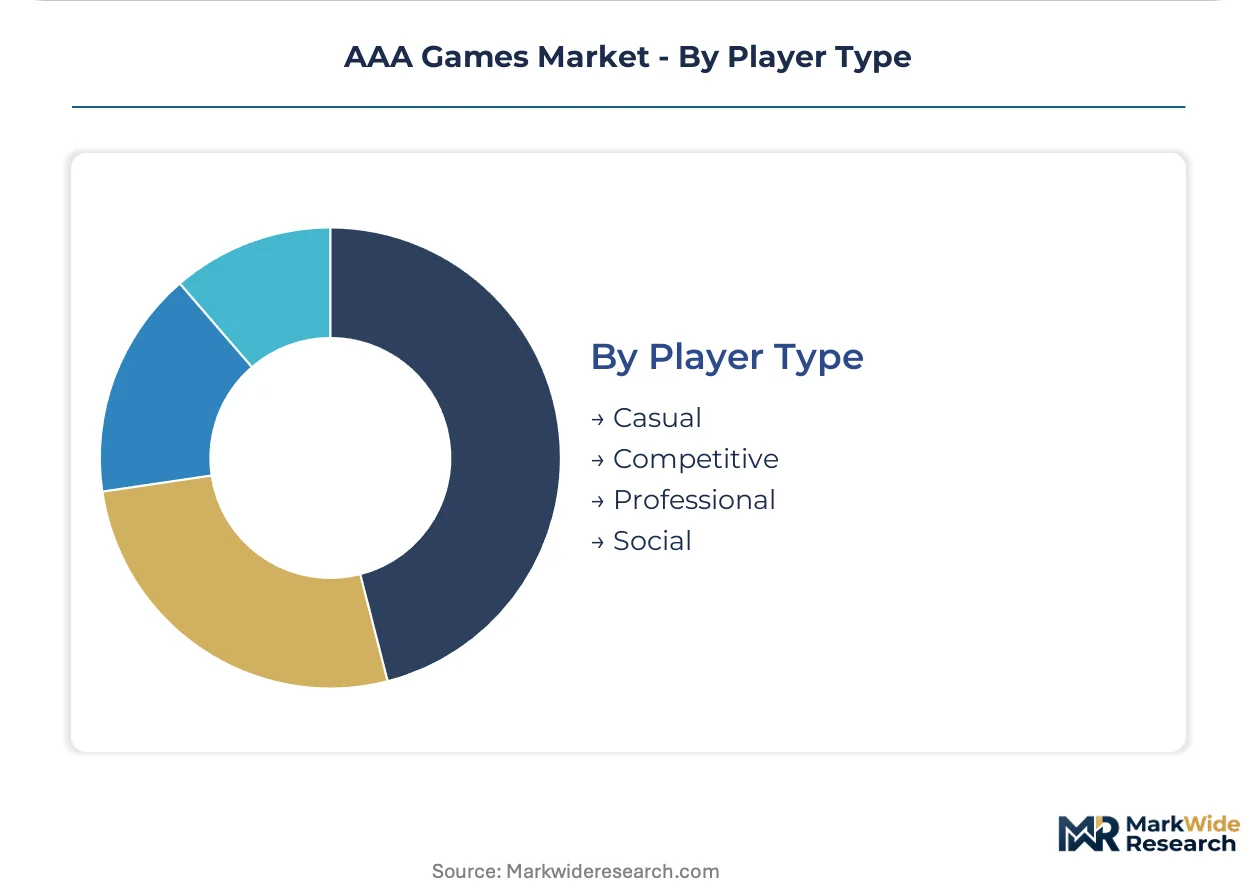
Player Type:
Engagement depth segmentation determines matchmaking algorithm design and community moderation staffing.
- Competitive:Skill-rating systems and ranked ladder structures demand anti-cheat infrastructure and server tick rate optimization. League of Legends and Valorant player bases in South Korea and Denmark sustain professional team franchise valuations through tournament viewership monetization.
- Professional:Visa classification pathways under Japan's METI and South Korea's esports governance structures enable full-time player careers with team housing and coaching staff.
- Casual:Drop-in matchmaking and AI-backfill systems accommodate irregular session patterns.
- Social:Party systems and voice communication tools prioritize friend-group retention over individual performance metrics.
Competitive players generate the highest per-user hours; Professional segment expands on regulatory recognition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates AAA development capacity while Japan and South Korea dominate hardware fabrication and competitive gaming infrastructure. Consumption clusters diverge between console-dominant Western markets and PC-centric Asian venues.
United States
Shooter genre dominance and subscription service adoption drive content consumption in California and Washington State. The Federal Trade Commission scrutinizes merger activity between major publishers. Austin and Los Angeles anchor development clusters where live-service operations and motion capture stages concentrate talent pools.
Japan
Hardware-software integration and character-driven RPG franchises sustain premium pricing power. METI promotes esports professionalization through visa classifications and venue certification standards. Tokyo and Osaka host development headquarters where proprietary engine teams and semiconductor partnerships coordinate supply security.
South Korea
PC bang venue culture and professional gaming infrastructure cultivate concentrated esports talent. The country's esports governance structures enable team franchise investments and tournament licensing. Seoul anchors competitive gaming operations where anti-cheat developers and broadcast production facilities cluster.
China
Mobile-first player bases and cloud gaming infrastructure expansion reshape distribution economics. The National Press and Publication Administration controls title approval timelines and youth playtime limits. Shenzhen and Shanghai concentrate platform operators where regulatory compliance teams and localization studios scale content pipelines.
Germany
PC hardware enthusiast communities and subscription churn sensitivity create price-conscious demand patterns. The EU Digital Services Act clarifies platform obligations for cross-border distribution. Hamburg and Munich host publisher offices where localization pipelines and age-rating compliance operations serve continental markets.
AAA Games Market Competitive Landscape
The competitive structure tilts toward platform-integrated publishers with captive hardware or engine ecosystems. Consolidation pressure concentrates among live-service specialists and mobile-adjacent studios seeking console credibility. Three archetypes dominate: vertically integrated platform holders, engine-technology licensors, and genre-specialized live-service operators. Strategic moves center on semiconductor supply partnerships and subscription catalog exclusivity negotiations.
Within the platform-holder tier, Sony Interactive Entertainment, Nintendo, and Microsoft Gaming exemplify hardware-software integration strategies. These entities occupy positions where captive chipset design and locked ecosystem licensing generate predictable revenue per unit. Tencent Games represents the mobile-to-console expansion archetype, leveraging domestic distribution scale to secure Western studio partnerships.
| Leading Market Players |
|---|
| Electronic Arts |
| Nintendo |
| Sony Interactive Entertainment |
| Ubisoft |
| Take-Two Interactive |
| Tencent Games |
| Epic Games |
| Activision Blizzard |
| Microsoft Gaming |
| Others |
Pricing and Supply Chain Analysis
Platform holders and subscription aggregators concentrate purchasing power, anchoring the industry's shift toward recurring-revenue models over discrete unit sales. This buyer consolidation reshapes how publishers negotiate revenue shares and structure content roadmaps.
Pricing Analysis
Pricing pressure intensifies in the mid-tier segment as cloud gaming subscriptions compress individual title willingness-to-pay. Three-tier pricing structure across premium, standard, and economy levels stratifies by content depth and platform exclusivity. Sony's PlayStation and Microsoft's Xbox command brand premiums through first-party exclusives, while Steam's regional pricing tools heighten price sensitivity in emerging markets. Subscription bundling by platform holders squeezes standalone launch pricing most acutely in France and Germany.
Supply Chain Analysis
Advanced node GPU fabrication rests on Taiwan Semiconductor Manufacturing and Samsung Foundry capacity in Taiwan and South Korea. Memory modules from SK Hynix and display panels from LG Display feed final assembly in China and Mexico. Single-source vulnerability concentrates in leading-edge lithography equipment. Distribution runs through platform-holder digital storefronts and retail hardware bundles, with physical manufacturing margin leakage eliminated in direct-download channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AAA games sector is transitioning from packaged-goods economics to live-service infrastructure, with cloud streaming technology displacing hardware-ownership requirements for audience expansion.
For Market Incumbents: Lock in semiconductor supply partnerships through captive capacity reservations at Taiwan and South Korea foundries. Secure exclusive content pipelines by acquiring live-service specialists in Finland and Sweden before talent scarcity escalates. The FTC's merger scrutiny and Sony's exclusive licensing practices threaten organic growth pathways. For New Entrants and Emerging Players: The EU Digital Services Act in Europe opens a window for independent storefronts by clarifying platform commission caps and content moderation liabilities. India's underpenetrated console base in tier-two cities offers first-mover hardware adoption curves. Target PC bang venue licensing in South Korea through localized tournament infrastructure partnerships. For Investors and Strategic Acquirers: The window for entry favors live-service operators with proven economy-balancing expertise and established player communities. Mid-cap studios with proprietary engine technology and multi-year content roadmaps represent acquisition targets with defensible IP. Watch for regulatory approval timeline shifts by China's National Press and Publication Administration as inflection indicators for revenue recognition volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Partnership | Microsoft and Sony deploy edge computing nodes to compress latency below 20 milliseconds in 5G networks. |
| Live-Service Talent Acquisition | Publishers acquire Finnish and Swedish studios to secure scarce systems design and economy balancing expertise. |
| Semiconductor Supply Agreement | Platform holders reserve advanced node capacity at TSMC and Samsung to insulate against geopolitical disruption. |
| Esports Venue Certification | Tournament organizers leverage Japan's METI visa classifications to professionalize player career pathways. |
| Generative AI Pipeline Integration | Studios deploy procedural generation and large language models to compress localization and concept art timelines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with live-service operations directors, platform partnership leads, semiconductor procurement specialists, and esports tournament organizers. Bottom-up triangulation against top-down publisher revenue disclosures and platform holder financial statements validated segment-level estimates. EMA submissions, FTC merger filings, and Japan's METI policy documents provided regulatory trajectory inputs.
Platform, genre, and distribution channel dimensions were modeled at country-level granularity across the projection horizon. CAGRs derived from historical revenue recognition patterns and forward content pipeline disclosures. Cloud gaming adoption curves, live-service player retention benchmarks, and semiconductor capacity expansion announcements informed scenario-weighted outputs.
The model assumes a particular technology adoption path; alternative pathways for cloud streaming infrastructure would alter the outlook. Regulatory approval volatility in China, GPU supply disruption in Taiwan, and subscription fatigue in Western Europe represent specific risk factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Video Game Software Market
Gaming
Latin America Mobile Gaming Market
Gaming
Mobile Shooter Market
Gaming
PC Games Market
Gaming
Mobile Game Software Market
Gaming
VR Gaming Accessories Market
Gaming
Gaming Chair Market
Gaming
North America Casino Gambling Market
Gaming
Metaverse in Gaming Market
Gaming
India Gaming Market
Gaming
Videogames Market
Gaming
China Casino Tourism Market
Gaming
Saudi Arabia Entertainment and Amusement Market
Gaming
LAMEA Gaming Posters Market
Gaming
Europe Casino Gambling Market
Gaming
United States Gaming Accessories Market