
 Virtual Reality (VR) in Gaming Market | 2026-2036
Virtual Reality (VR) in Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality (VR) in Gaming Market Intelligence
The unbundling of VR headsets from proprietary software ecosystems is consolidating consumer preference towards open-platform hardware. Meta leverages its extensive content library and social platform integration to maintain market presence. Valve positions its SteamVR platform as a hardware-agnostic standard for PC-based gaming. In contrast, Sony specializes in a console-tethered ecosystem, linking its VR hardware exclusively to the PlayStation platform.
Virtual reality in gaming utilizes head-mounted displays and motion tracking systems to immerse a user in a computer-generated, interactive environment. Key technical parameters include high refresh rates, typically 90Hz or above, and a wide field-of-view to minimize motion sickness. VR Headsets constitute the foundational product type, with market penetration tied directly to affordability and content availability. While single-player Immersive Gaming remains the dominant use case, multiplayer VR Esports is emerging as a high-growth category.
Hardware manufacturers must secure certifications such as the FCC approval in the United States and the CE marking in Europe for their electronic devices. In China, compliance with GB standards is mandatory for market access. Data privacy frameworks like GDPR influence how platform operators manage player data and online interactions. The central strategic question for developers is whether to align with closed, curated ecosystems or embrace open standards for broader reach.
Market Dynamics
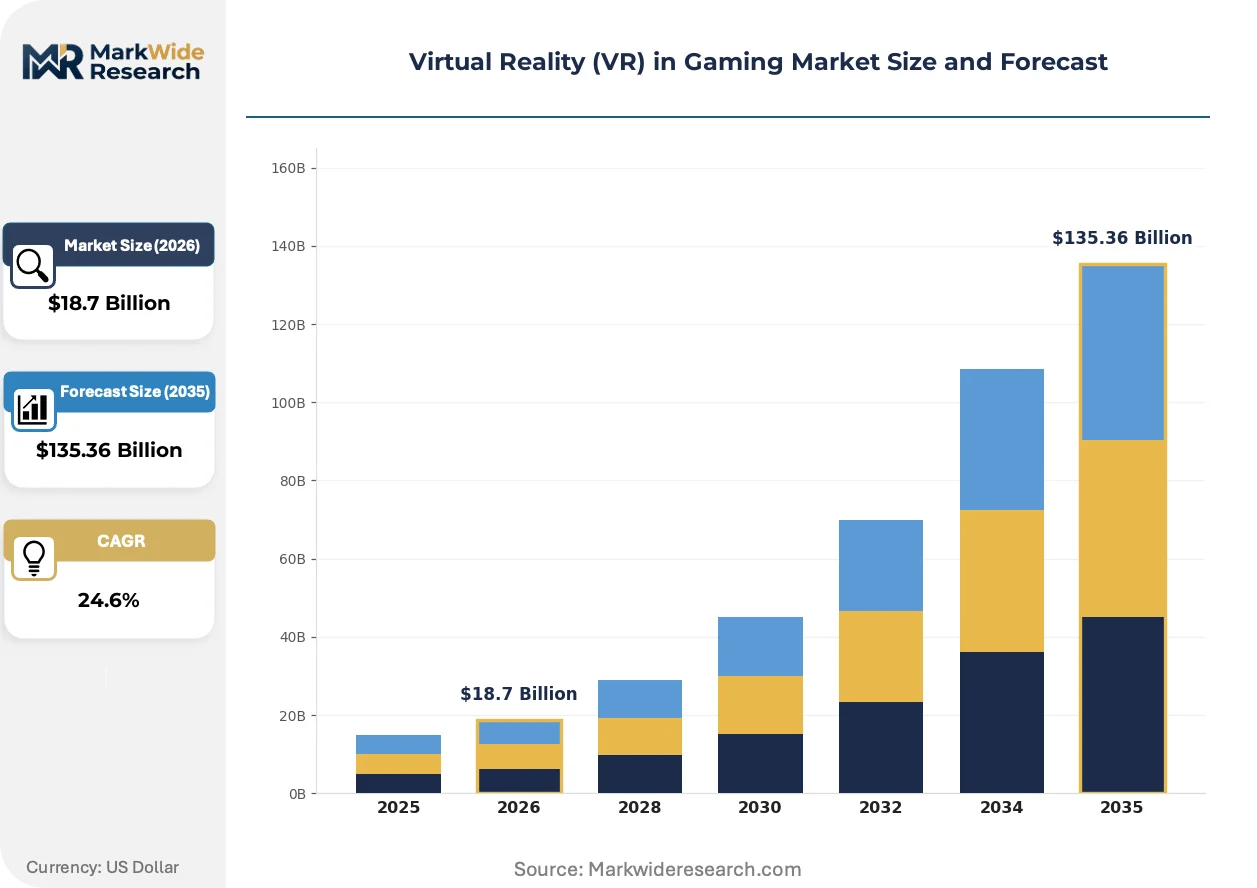
The central force shaping the market is the unbundling of hardware from closed software ecosystems. This trend, driven by the standardization of technologies like Six Degrees of Freedom tracking, is shifting consumer preference toward open-platform hardware and cross-platform content compatibility.
Growth Catalysts
- VR Esports:The emergence of competitive VR gaming leagues and tournaments creates a dedicated user base and drives demand for high-performance hardware and low-latency network infrastructure.
- Six Degrees of Freedom (6DoF) Standardization:The widespread adoption of 6DoF tracking technology as a baseline standard enables developers to create more complex, interactive, and physically engaging game mechanics.
- Concentrated Gaming Cultures:Markets with high engagement in digital entertainment, such as South Korea, provide fertile ground for VR adoption due to pre-existing consumer habits and infrastructure for competitive gaming.
Market Restraints
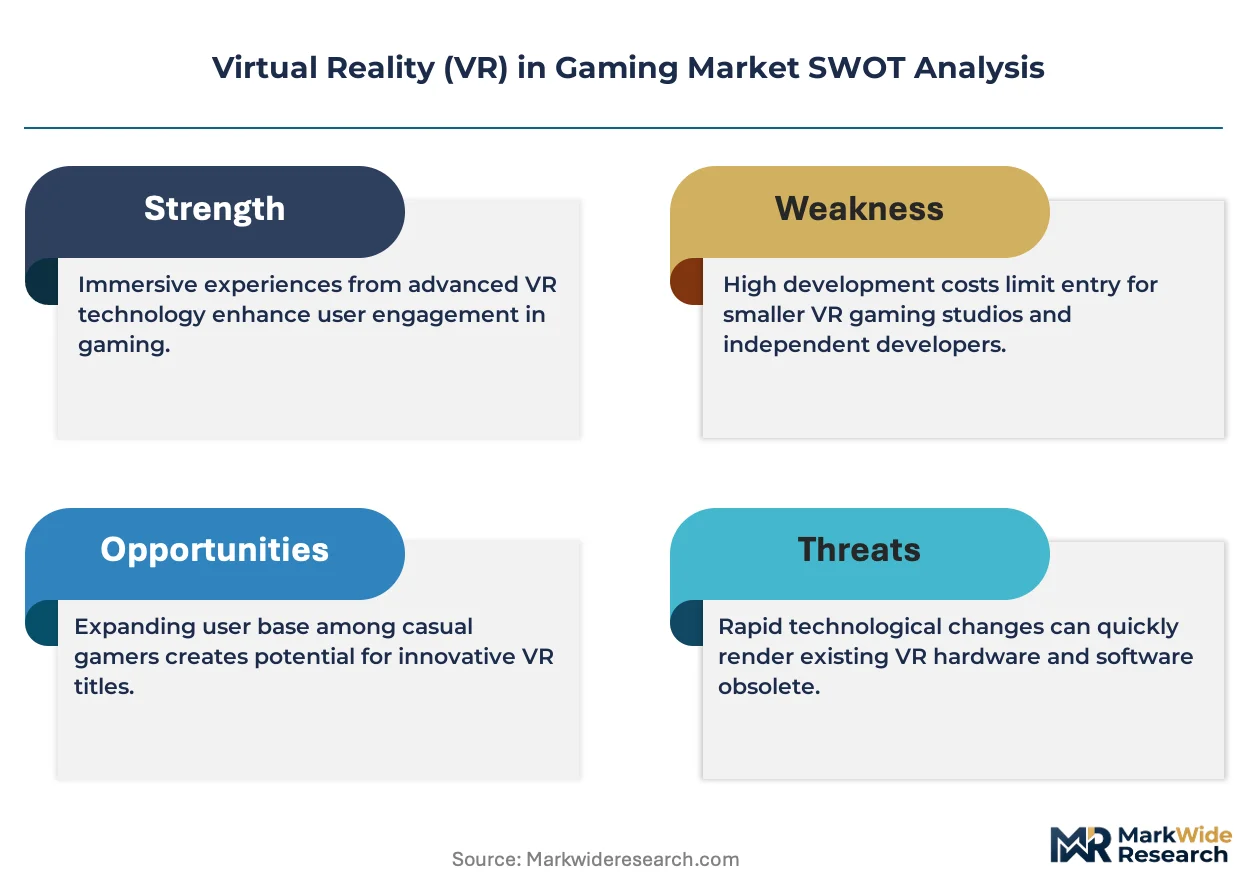
- High Hardware Cost:The significant initial investment for a capable VR headset, often coupled with the need for a powerful PC or console, remains a primary barrier to mainstream consumer adoption.
- Visually Induced Motion Sickness:A subset of users experiences discomfort and nausea, a technical hurdle linked to latency and display performance that limits session length and discourages repeat use.
- Content Exclusivity:Platform-exclusive titles fragment the game library, forcing consumers to choose an ecosystem and limiting access to content, which can stifle hardware sales for less established platforms.
Strategic Opportunities
- Location-Based Entertainment (LBE):Developing immersive, arcade-style VR experiences in dedicated physical venues offers a channel to introduce the technology to consumers without requiring personal hardware ownership.
- Social VR Platforms:Expanding beyond gaming into persistent social worlds and virtual event spaces represents a significant opportunity to leverage VR technology for broader community and entertainment applications.
- Emerging Economies:Targeting markets in Southeast Asia and Latin America, where digital infrastructure is improving and a large youth demographic shows interest in new gaming technologies, presents a key growth corridor.
Industry Challenges
- Cross-Platform Development Complexity:The lack of universal standards for input devices and haptic feedback systems increases development costs and time for studios aiming to launch games on multiple VR platforms.
- Data Privacy Compliance:Navigating regulations like GDPR for handling sensitive biometric data from eye-tracking and motion sensors creates significant operational and legal burdens for platform operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality (VR) in Gaming Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VR Headsets, Motion Controllers, VR Gloves, VR Treadmills, Haptic Suits Technology: Inside-Out Tracking, Outside-In Tracking, Six Degrees of Freedom, Room-Scale Tracking, Positional Audio Use Case: Immersive Gaming, Multiplayer Interaction, VR Esports, Educational Simulations, Fitness Training Customer Type: Individual Gamers, Gaming Cafes, VR Arcades, Training Institutes, Content Developers |
| Companies Covered | Apple, Unity Technologies, Meta, Schell Games, Epic Games, Valve, HTC, Beat Games, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality (VR) in Gaming Market Strategic Shifts & Innovations
Hardware maturation is shifting the market's focus from technical specifications to the depth and accessibility of content ecosystems. This evolution prioritizes software-driven value, including social integration and diverse content libraries, as the primary competitive differentiator for VR platforms.
Foveated rendering is a graphics optimization technique that uses eye-tracking cameras inside a headset. It renders the specific area a user is looking at in full resolution while reducing the quality in the peripheral vision. High-end PC VR and advanced standalone headsets are adopting this feature. This technology is integrating eye-tracking data into the rendering pipeline to deliver higher-fidelity graphics without requiring more powerful processors.
Europe's General Data Protection Regulation (GDPR) sets a high bar for data privacy and user consent. Its framework governs how companies must handle the personal and biometric data collected by VR systems, including head, eye, and hand movements. This regulation most directly affects platform holders and developers of social VR applications, who must now build privacy-by-design principles into their software architecture.
Consumer behavior is pivoting from one-time game purchases toward recurring subscription models. This live-service approach disrupts the traditional retail model by offering access to a curated library of games and experiences for a monthly fee. This trend is most pronounced on established platforms where a large user base makes recurring revenue models economically sustainable for developers and publishers.
Virtual Reality (VR) in Gaming Market Segmentation
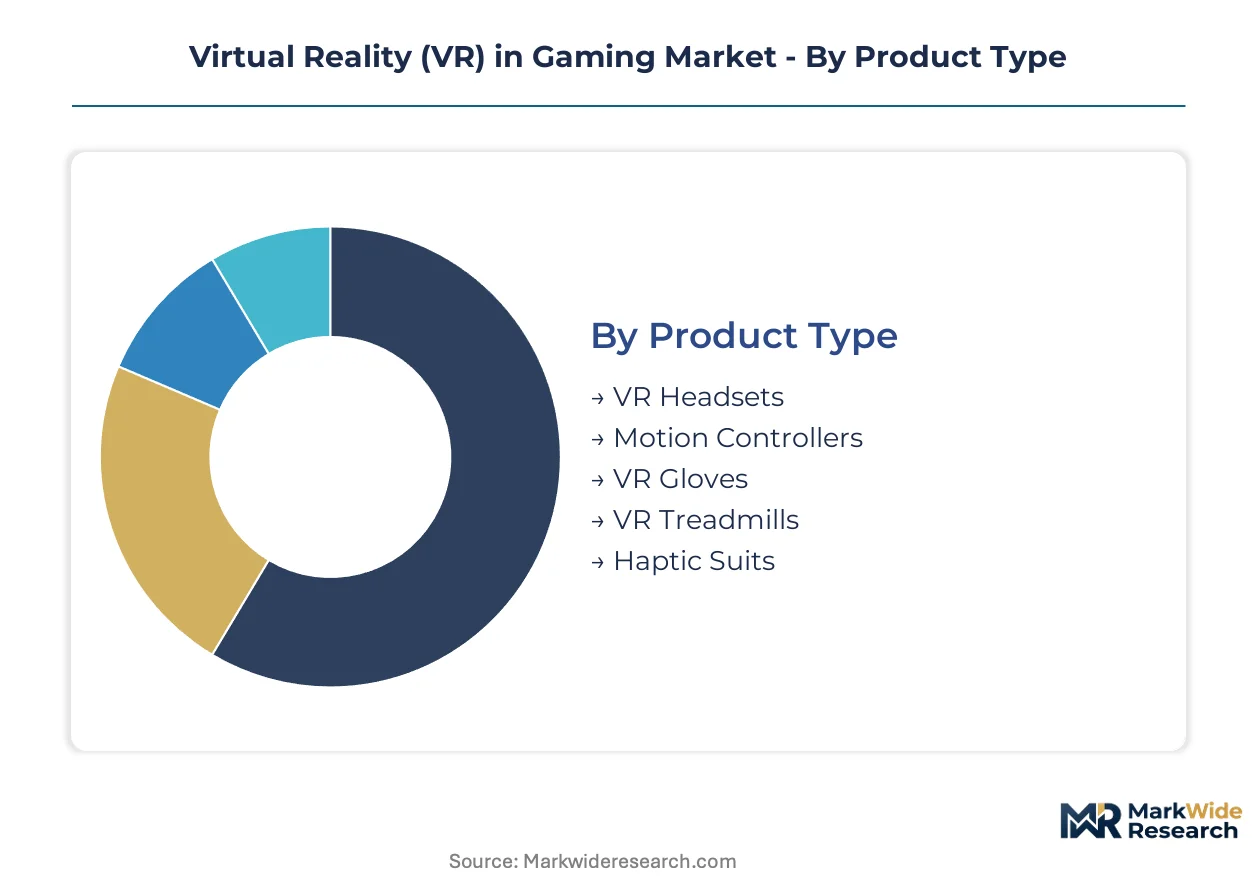
Understanding the virtual reality in gaming market through segmentation reveals distinct user needs and technological preferences. This analysis dissects the core components that drive market expansion and adoption across various user groups. Strategic insights emerge from examining how different product types, technologies, use cases, and customer profiles contribute to the overall market trajectory.
Product Type:
Supply concentration in the VR gaming market primarily flows through foundational hardware components, dictating the entry points for consumer adoption. Manufacturers prioritize scaling production for these essential devices to meet growing demand.
- VR Headsets:These head-mounted displays provide the visual and auditory immersion for VR experiences, incorporating high-resolution screens and integrated audio solutions. Demand concentrates in South Korea, driven by a strong gaming culture and increasing content availability.
- Motion Controllers:Handheld devices enable precise interaction within the virtual environment, translating user gestures and button presses into in-game actions. Their integration with 6DoF tracking enhances physical engagement for complex game mechanics.
- VR Gloves:These specialized peripherals offer advanced haptic feedback and finger-level tracking, enhancing tactile immersion for specific applications.
- VR Treadmills:Omni-directional platforms allow users to physically walk or run in place, simulating movement within large virtual spaces without spatial constraints.
- Haptic Suits:Full-body wearables provide tactile sensations across the user's torso and limbs, delivering a deeper level of physical feedback for immersive experiences.
Today's leader: VR Headsets. Tomorrow's challenger: Haptic Suits.
Technology:
Application of advanced tracking and rendering technologies defines the quality and interactivity of VR gaming experiences. Developers leverage these innovations to overcome technical barriers and enhance player immersion.
- Six Degrees of Freedom:This tracking technology allows users to move freely in three-dimensional space, detecting both rotational and translational movements. Its standardization enables more complex and interactive experiences across diverse gaming genres.
- Inside-Out Tracking:Integrated cameras on the headset track the user's position and orientation relative to the environment, eliminating the need for external base stations. This approach simplifies setup and enhances portability for standalone VR devices.
- Outside-In Tracking:External sensors or cameras placed in the physical environment monitor the headset and controller positions, offering highly accurate and low-latency positional tracking.
- Room-Scale Tracking:This technology maps a designated physical play area into the virtual environment, allowing users to physically walk around within the game space.
- Positional Audio:Spatial sound rendering creates the illusion that sounds originate from specific locations within the virtual environment, enhancing immersion and situational awareness.
The widespread adoption of Six Degrees of Freedom tracking continues to drive market expansion, while Inside-Out Tracking demonstrates the steepest expansion trajectory for accessibility.
Use Case:
Customer type influences the demand patterns for specific VR gaming applications, driving innovation towards tailored experiences. Different user segments seek distinct forms of engagement and content from VR platforms.
- Immersive Gaming:This dominant use case focuses on single-player experiences designed for deep narrative engagement and exploration within virtual worlds. Content availability and graphical fidelity remain critical for attracting individual gamers.
- VR Esports:Competitive gaming leagues and tournaments utilize VR technology, creating a high-performance category with demand for low-latency hardware and network infrastructure. This segment attracts dedicated players and spectators.
- Multiplayer Interaction:This use case encompasses social games and shared virtual spaces where multiple users interact simultaneously, fostering community and collaborative play.
- Educational Simulations:VR platforms provide realistic training environments for skill development and knowledge acquisition, extending beyond traditional entertainment.
- Fitness Training:Exercise-focused VR applications gamify physical activity, offering engaging routines and progress tracking within virtual settings.
Immersive Gaming holds the largest share of current engagement, with VR Esports rapidly gaining share among competitive players.
Customer Type:
Margin structures vary significantly across different customer types, influencing business models and content distribution strategies. Providers adapt offerings to cater to the unique economic profiles of each segment.
- Individual Gamers:These consumers purchase VR hardware and software for personal use, representing the largest and most direct market segment. Their purchasing decisions depend on affordability and content library depth.
- VR Arcades:Commercial venues offer pay-per-play VR experiences to a broad public, serving as a key channel for introducing the technology to new users. Location-based entertainment models drive their operational strategies.
- Gaming Cafes:These establishments provide access to high-end gaming equipment, including VR setups, often on an hourly rental basis. They cater to communities seeking social gaming experiences.
- Training Institutes:Educational and professional organizations leverage VR for simulations and immersive learning, requiring specialized content and robust hardware solutions.
- Content Developers:These entities create VR games and applications, influencing hardware adoption through the quality and exclusivity of their digital offerings.
Growth for Individual Gamers remains foundational, while VR Arcades continue to expand their reach in urban centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Virtual Reality in Gaming market historically scaled in regions with strong technological infrastructure and early digital entertainment adoption. These foundational areas continue to shape demand patterns for immersive gaming experiences. Infrastructure development and consumer engagement remain critical for market penetration.
South Korea
South Korea exhibits high demand for VR gaming due to its deeply ingrained esports culture and advanced broadband penetration. The Ministry of Science and ICT actively supports VR content development through various funding initiatives. Seoul's Gangnam district hosts numerous VR arcades, demonstrating a strong appetite for location-based entertainment.
United States
The United States drives significant VR gaming adoption, fueled by a large consumer base and substantial investment in entertainment technology. FCC approval processes ensure hardware compliance for market entry. Silicon Valley remains a hub for VR software innovation, attracting developers for new interactive experiences.
Germany
Germany demonstrates steady VR gaming growth, particularly for high-fidelity PC-based systems, supported by a robust engineering sector. CE marking is mandatory for all electronic devices entering the European market. Cologne hosts Gamescom, a major gaming convention that showcases new VR titles and hardware.
China
China presents immense potential for VR gaming expansion, driven by its vast youth demographic and rapid digital infrastructure upgrades. Compliance with GB standards is essential for VR hardware manufacturers operating in the country. Shenzhen's tech ecosystem fosters significant VR headset manufacturing and component supply.
Japan
Japan's gaming heritage translates into sustained interest in VR, particularly for immersive single-player experiences and niche content. METI provides guidance for technology standards and intellectual property protection. Tokyo's Akihabara district features specialized VR gaming cafes, catering to enthusiast communities.
Virtual Reality (VR) in Gaming Market Key Industry Players
The competitive structure tilts toward platform-centric ecosystems, where hardware manufacturers often align with proprietary software and content libraries. This dynamic creates distinct tiers, with major technology conglomerates forming a consolidated upper segment. Strategic archetypes include integrated platform providers, open-platform enablers, and independent content developers. Portfolio diversification through content acquisition and strategic partnerships for technology integration represent dominant competitive moves.
Integrated platform providers, such as Meta Platforms, Inc., a Delaware corporation, exemplify the strategy of leveraging extensive content libraries and social platform integration to maintain market presence and user engagement. Valve Corporation, a privately held American company known for its SteamVR platform, occupies a position as a hardware-agnostic standard for PC-based gaming, appealing to a broad range of hardware users. Sony Group Corporation, a Japanese multinational conglomerate corporation, anchors the console-tethered ecosystem, linking its VR hardware exclusively to the PlayStation platform for its dedicated consumer base. These entities define the primary competitive vectors in the market.
| Leading Market Players |
|---|
| Apple |
| Unity Technologies |
| Meta |
| Schell Games |
| Epic Games |
| Valve |
| HTC |
| Beat Games |
| Sony |
| Others |
Cost & Logistics Intelligence
Semiconductor chip costs, crucial for VR headset processors and tracking systems, influence the final retail price points for individual gamers and arcade operators. This upstream material cost directly impacts downstream hardware affordability.
Pricing Analysis
Per-unit transactional pricing for VR headsets dominates the hardware segment, while subscription models gain traction for content libraries. Price differentiation stems from display resolution and integrated content ecosystems. Pricing softness in entry-level hardware reflects intense competition from new manufacturers. Individual gamers demonstrate high price sensitivity, contrasting with VR arcades which prioritize performance, reliability, and content licensing for commercial operations.
Supply Chain Analysis
Compliance with GB standards in China reshapes sourcing strategies for VR hardware components, favoring domestic production for market access. Supply concentration centers on China for manufacturing and South Korea for advanced display panels. The market draws from a global network for microprocessors and optical components. Single-source vulnerability for specialized display technologies represents a key supply chain risk. Distribution runs through online retail channels and specialized electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The virtual reality in gaming market functions as a regulatory compounder, with GDPR influencing data handling for platform operators and driving privacy-by-design principles. This regulatory milestone shapes consumer trust and long-term engagement.
For Market Incumbents: Deepen content ecosystem integration through strategic acquisitions of independent studios, securing exclusive titles against emerging platform challengers. Invest in advanced foveated rendering R&D to maintain a technological edge and mitigate performance gaps. This strategy reinforces market position against new entrants offering cheaper, less optimized hardware.
For New Entrants and Emerging Players: Underserved educational institutions represent a significant white-space target for VR training simulations, offering a low-competition entry point. Focus on developing specialized, robust hardware and content for vocational skill development in emerging economies like Southeast Asia. A direct-to-institution sales model, emphasizing cost-effectiveness and learning outcomes, facilitates market penetration.
For Investors and Strategic Acquirers: Roll-up economics work for content developers because platform fragmentation creates opportunities for consolidating diverse game libraries. Long-term viability rests on securing intellectual property rights for popular VR titles and expanding into social VR applications. Watch for increasing cross-platform content compatibility as a signal of market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | This initiative ensures seamless content delivery and broad user access across diverse hardware ecosystems. |
| Content Library Expansion | Expanding content offerings attracts new users and retains existing subscribers within proprietary platforms. |
| Advanced Haptic Feedback R&D | Investing in haptic technologies enhances tactile immersion, differentiating high-end VR experiences. |
| Location-Based Entertainment Partnerships | Collaborating with VR arcades introduces the technology to new consumers without requiring personal hardware investment. |
| Eye-Tracking Technology Integration | Integrating eye-tracking enables foveated rendering, optimizing graphical performance and reducing computational demands. |
Research Approach
Bottom-up VR headset adoption modeling reconciled against top-down component supply tracking forms the analytical core for this study. Primary interviews with VR game developers, platform executives, arcade operators, and hardware engineers informed qualitative insights. Secondary validation drew from industry association reports, technology patent databases, and company financial disclosures. This approach ensures robust triangulation of market data.
Historical trendline analysis of hardware sales and content consumption established baseline market trajectories across the analysis window. Segmentation dimensions modeled include product type, technology, use case, and customer type, alongside geographic adoption patterns. Compound Annual Growth Rates were derived from regression analysis of historical data and projected future demand. Key forecast inputs included refresh rate advancements and content release schedules.
Underlying measurement precision varies by segment; VR headset sales carry tighter precision than haptic suit adoption. Forecasts reflect assumptions on technological maturation and consumer spending. Geopolitical instability impacting semiconductor supply represents a key risk. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
South Korea Gaming Peripherals Market
Gaming
Global Subscription-Based Gaming Market
Gaming
Online Casual Games Market
Gaming
Shooter Game Market
Gaming
Europe Casino Gambling Market
Gaming
Gaming Chair Market
Gaming
Africa Gaming Market
Gaming
Mobile Game Software Market
Gaming
MMORPG Gaming Market
Gaming
Galgames Market
Gaming
Online Strategy Games Market
Gaming
Playstation Network (PSN) Market
Gaming
Global Online Adventure Games Market
Gaming
Social Gaming Market
Gaming
Latin America Gaming Headsets Market
Gaming
Australia Gaming Accessories Market