
 Europe Serious Gaming Market | 2026-2036
Europe Serious Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Serious Gaming Market Foresight
France is reconfiguring its serious gaming development capacity through state-backed digital training incubators near Paris-Saclay. MPS Interactive Systems leverages its simulation heritage to anchor corporate training contracts across Western Europe. Tygron BV competes in geospatial serious gaming, specializing in interactive 3D environments for municipal infrastructure planning. BreakAway Games sustains defense-sector relationships through scenario-based wargaming platforms tailored to NATO standards.
Europe serious gaming denotes interactive digital systems engineered with pedagogical mechanics, real-time feedback loops, and measurable competency frameworks for non-entertainment outcomes. These platforms integrate AR/VR rendering engines, behavioral analytics middleware, and SCORM-compliant progress tracking to deliver standardized skill certification for institutional buyers. Corporate training applications currently occupy the deepest margin pools, as enterprises prioritize measurable ROI on workforce upskilling investments. Healthcare applications represent the fastest-growing segment, with VR-based therapy modules gaining reimbursement traction under updated medical device frameworks. Military end users dominate absolute volume, driven by cross-border joint exercise simulation requirements among EU member states.
The EU AI Act imposes risk-classification obligations on adaptive serious gaming systems that modify difficulty or content based on user biometric data, forcing developers toward explainable algorithm architectures. EMA and national health technology assessment bodies in Germany and France are evaluating VR therapy modules for provisional medical device status, which would unlock public reimbursement channels. Stakeholders must monitor how CSRD disclosure mandates reshape procurement criteria for publicly funded training contracts across EU institutions.
Market Dynamics
Defense ministries across France and Germany are accelerating battlefield simulation procurement, compressing vendor qualification timelines from eighteen to six months while demanding NATO-interoperable scenario libraries.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for adaptive learning algorithms are forcing developers toward explainable architectures, creating first-mover advantages for compliant platform vendors.
- Cross-border military joint exercises:NATO-standardized wargaming requirements among member states are standardizing procurement specifications and expanding addressable contract volumes.
- VR therapy reimbursement pathways:EMA and German health technology assessment bodies are evaluating provisional medical device status for therapeutic modules, unlocking public payment channels.
Market Restraints
- Specialized talent scarcity:The intersection of pedagogical design, behavioral analytics, and AR/VR engine development commands premium compensation, inflating fixed cost structures for mid-scale developers.
- Input concentration in rendering hardware:GPU and haptic controller supply chains concentrate in East Asian manufacturing clusters, exposing European assemblers to logistics volatility and currency fluctuation.
- Legacy SCORM integration friction:Institutional buyers require backward compatibility with existing learning management systems, constraining architectural innovation and extending development cycles.
Strategic Opportunities
- Netherlands urban planning cluster:Tygron BV and Delft University R&D partnerships demonstrate replicable models for municipal infrastructure simulation contracts across Benelux and Nordic markets.
- CSRD disclosure mandates:Corporate sustainability reporting requirements are reshaping procurement criteria for publicly funded training contracts, favoring vendors with documented carbon footprint methodologies.
- Convergence of digital twin and serious gaming engines:Industrial facility operators are repurposing urban planning simulation architectures for workforce safety training, opening manufacturing verticals.
Industry Challenges
- Competency framework standardization delays:Absence of cross-border certification reciprocity forces developers to rebuild assessment modules for each national procurement authority, fragmenting development resources.
- Biometric data governance complexity:GDPR and national data protection authorities impose divergent consent and retention requirements on platforms capturing physiological response metrics for adaptive difficulty adjustment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Serious Gaming Market |
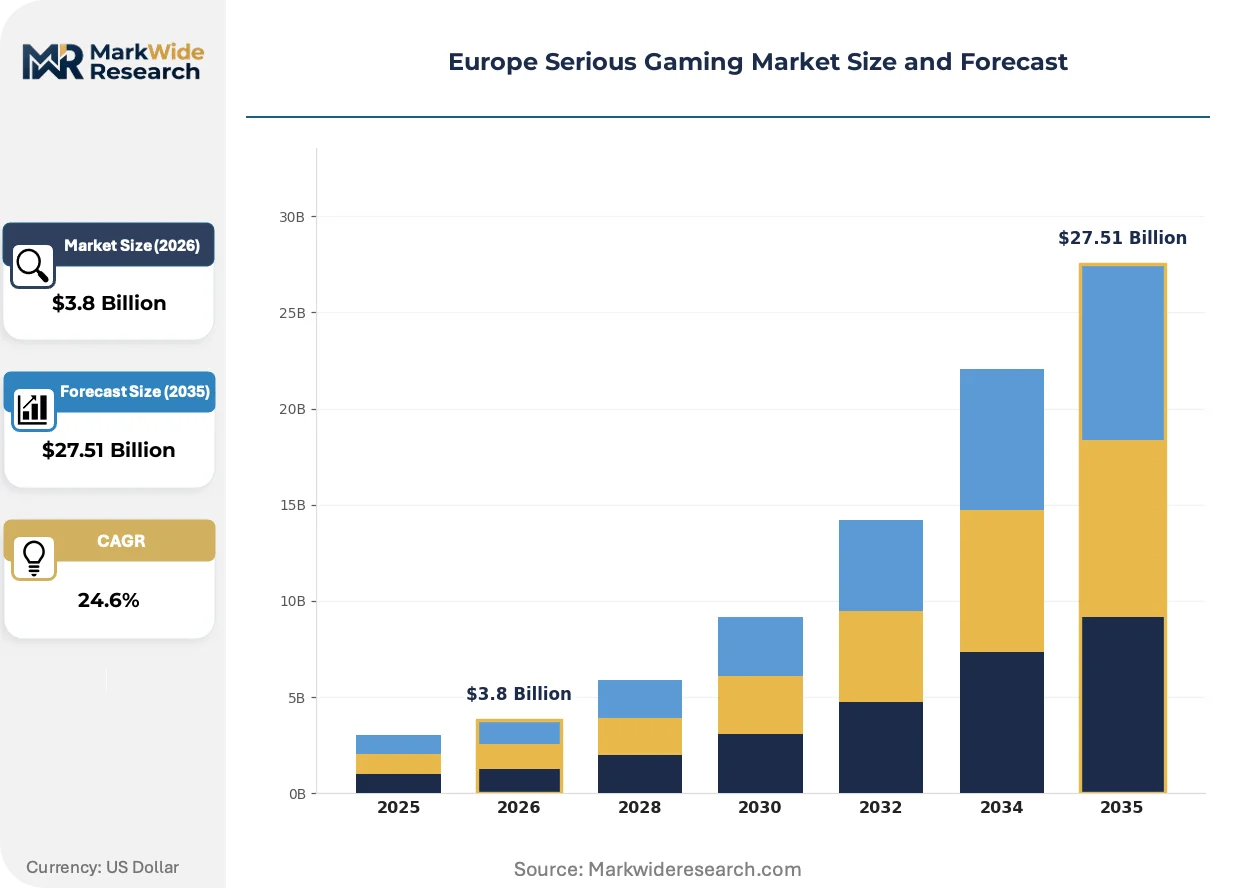
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Education, Healthcare, Corporate Training, Military Technology: AR, VR, Simulation, Mobile Gaming Application: Skill Development, Behavioral Training, Therapy, Risk Management Distribution Channel: Online, Retail, Direct Sales, Partnerships |
| Companies Covered | MPS Interactive Systems, Tygron BV, BreakAway Games, Firsthand Technology, KTM Advance, Designing Digitally Inc., Serious Games Solutions, Bedaux Serious Games, Diginext (CS Group), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Serious Gaming Market Shifts & Advancements
Real-time behavioral analytics middleware is displacing static assessment frameworks, enabling competency certification based on demonstrated performance rather than completion metrics.
Cloud-native rendering infrastructure is migrating from on-premise GPU clusters to distributed edge computing nodes. Defense and corporate training buyers are adopting hybrid deployment models to reduce latency in multi-user scenarios. This architecture is compressing capital requirements for platform vendors while expanding addressable mid-market accounts.
The EU AI Act's risk-classification framework is reclassifying adaptive serious gaming systems that modify content based on user biometric data as high-risk applications. Developers must implement explainable algorithm documentation and human oversight protocols. Healthcare VR therapy modules face the steepest compliance burden, with German and French regulators requiring pre-market conformity assessments.
Enterprise buyers are unbundling perpetual licensing in favor of consumption-based subscription models tied to active learner hours. Corporate training procurement teams are displacing capital expenditure approvals with operational budget line items. This shift is most pronounced in Netherlands and German manufacturing sectors, where workforce upskilling budgets report directly to plant operations rather than centralized IT procurement.
Europe Serious Gaming Market Segmentation
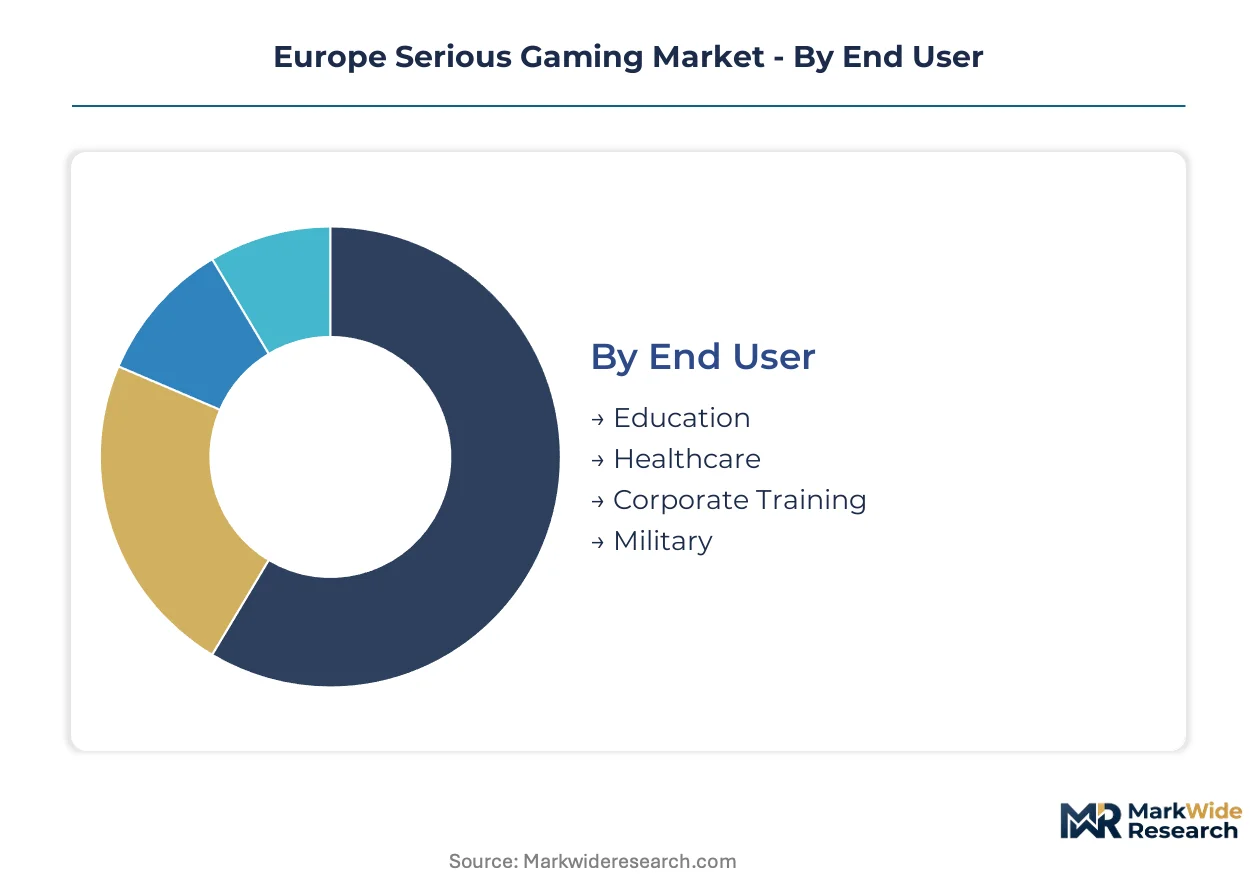
Segmentation in the Europe Serious Gaming Market reveals how procurement authority, technical architecture, and pedagogical outcome interact to determine vendor positioning. Buyers across defense, healthcare, and enterprise verticals impose divergent specifications on rendering engines, compliance frameworks, and deployment models.
End User:
Customer type determines budget authority, contract duration, and technical integration requirements across institutional procurement workflows.
- Military:Battlefield simulation platforms integrate NATO-interoperable scenario libraries with classified network deployment. Defense ministries in Germany and France compress vendor qualification timelines while mandating cross-border joint exercise compatibility.
- Corporate Training:Workforce upskilling platforms prioritize SCORM-compliant progress tracking and measurable ROI metrics. German and Dutch manufacturing sectors report training budgets directly to plant operations, accelerating operational expenditure approvals.
- Healthcare:VR therapy modules pursue provisional medical device status under EMA and national health technology assessment frameworks.
- Education:Pedagogical platforms emphasize competency certification aligned with national qualification frameworks.
Military contracts command the established revenue base. The steepest expansion runs through healthcare as reimbursement pathways mature.
Technology:
Rendering modality shapes capital intensity, latency requirements, and regulatory exposure for platform developers.
- VR:Immersive headsets with haptic feedback loops enable physiological response capture for adaptive difficulty adjustment. German regulators classify biometric-enabled VR therapy modules as high-risk under EU AI Act provisions.
- Simulation:Physics-engine platforms model urban infrastructure, military scenarios, and industrial processes with deterministic outcome validation. Dutch municipal planners anchor demand through Tygron BV and Delft University partnerships.
- AR:Overlay rendering merges physical environments with digital training layers for field-based workforce instruction.
- Mobile Gaming:Smartphone-delivered modules reduce hardware barriers for mid-market corporate accounts.
Simulation platforms anchor established deployment volumes. VR gains share fastest as healthcare reimbursement frameworks advance.
Application:
Pedagogical outcome determines content architecture, assessment methodology, and buyer procurement channel.
- Skill Development:Competency-based modules deliver standardized certification for technical trades and professional qualifications. Corporate buyers in France and Germany prioritize measurable performance outcomes over completion metrics.
- Therapy:Clinical VR applications target anxiety disorders, phobia treatment, and rehabilitation protocols. French and German health technology assessment bodies evaluate provisional medical device status for public reimbursement eligibility.
- Behavioral Training:Scenario-based platforms reshape workforce conduct through consequence simulation.
- Risk Management:Crisis simulation tools train municipal and corporate responders on coordinated emergency protocols.
Skill development retains the deepest institutional penetration. Therapy applications climb the fastest as clinical validation accumulates.
Distribution Channel:
Go-to-market configuration determines customer acquisition cost, contract customization depth, and recurring revenue predictability.
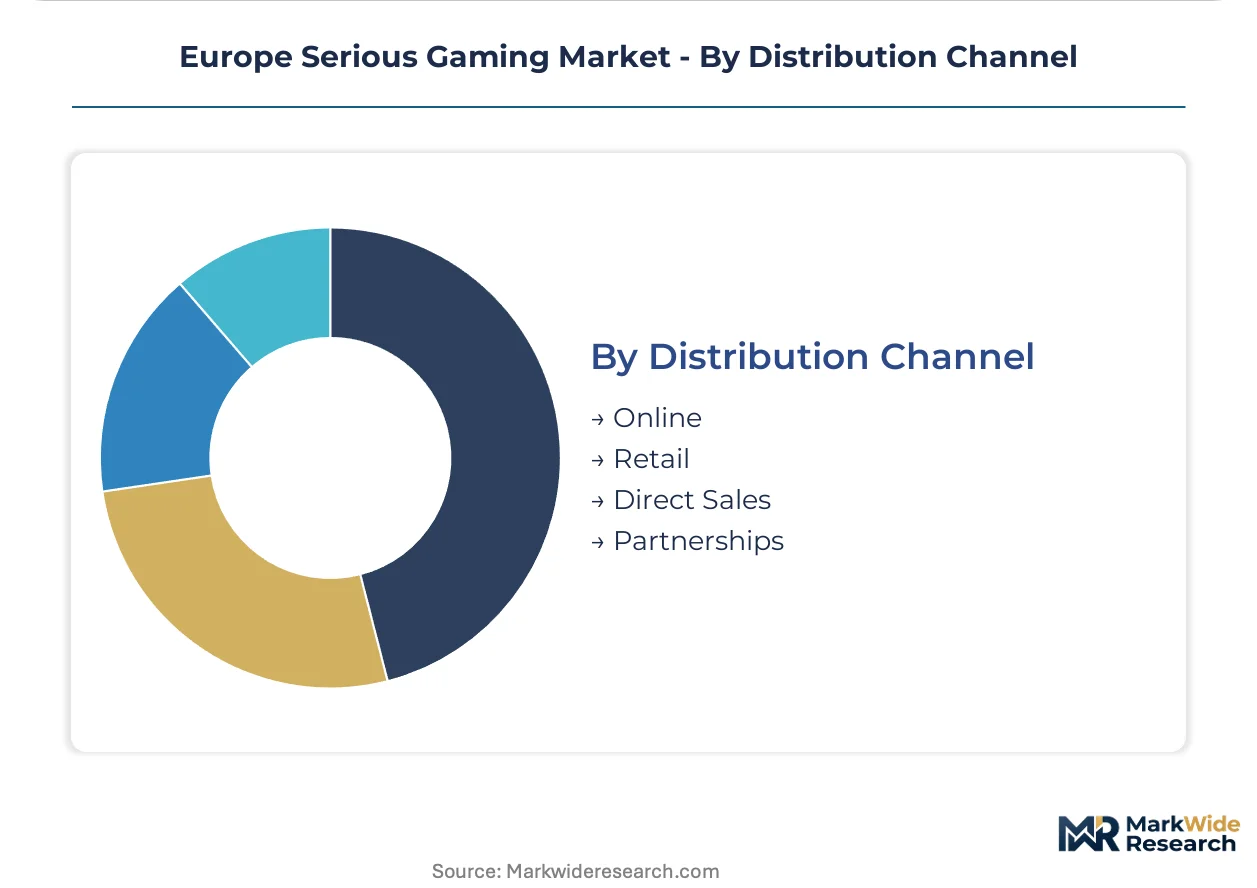
- Direct Sales:Vendor field teams manage complex procurement cycles for defense and large enterprise accounts. French state-backed digital training incubators near Paris-Saclay concentrate direct relationship development.
- Partnerships:System integrators and learning management system vendors embed serious gaming modules within broader transformation contracts. Netherlands urban planning clusters demonstrate replicable partnership models across Benelux markets.
- Online:Self-service platforms target mid-market corporate training with consumption-based subscription pricing.
- Retail:Hardware-software bundles reach education and small healthcare providers through specialized distributors.
Direct sales commands the established contract value. Partnerships expand most quickly as platform vendors seek geographic coverage without field team investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Simulation platform vendors cluster near defense procurement hubs and university R&D centers across the continent. French and German ministries compress vendor qualification timelines while Dutch municipal planners anchor urban planning demand. Regulatory divergence on biometric data governance fragments development roadmaps.
Germany
The Bundeswehr accelerates battlefield simulation procurement with NATO-interoperable scenario requirements. BSI and KBA data protection protocols impose strict consent frameworks on platforms capturing physiological metrics. Munich and Stuttgart host defense-technology clusters where vendors co-locate with Bundeswehr procurement offices.
France
Paris-Saclay digital training incubators reconfigure serious gaming development capacity through state-backed infrastructure. ANSM and CNIL enforce GDPR-aligned biometric data retention limits on adaptive learning systems. The Île-de-France corridor concentrates corporate training contract activity near major enterprise headquarters.
Netherlands
Tygron BV and Delft University partnerships demonstrate replicable municipal infrastructure simulation models. Dutch environmental and building regulations mandate stakeholder engagement tools that geospatial serious gaming platforms satisfy. The Randstad urban planning cluster exports simulation architectures to Benelux and Nordic markets.
United Kingdom
NHS England evaluates VR therapy modules for provisional medical device status under updated NICE guidance. MHRA conformity assessment requirements shape pre-market validation timelines for clinical applications. London and Cambridge health-technology clusters host behavioral analytics middleware developers serving reimbursement-tracked therapeutic platforms.
Belgium
NATO headquarters in Brussels drives standardization demand for cross-border joint exercise simulation platforms. Belgian federal procurement aligns with EU AI Act risk-classification timelines for adaptive training systems. Flanders-based system integrators embed serious gaming modules within broader defense transformation contracts.
Europe Serious Gaming Market Competitive Landscape
Defense-heritage simulation studios and geospatial specialists split the market between classified procurement cycles and municipal planning contracts. The vendor base organizes around three strategic archetypes: NATO-certified defense contractors, university-spun urban planning platforms, and healthcare-focused VR therapy developers. Consolidation pressure concentrates in the corporate training mid-market where scale advantages determine LMS integration partnerships. M&A activity targets behavioral analytics middleware capabilities while geographic expansion follows defense ministry co-location strategies.
Among defense-heritage specialists, MPS Interactive Systems and BreakAway Games occupy positions shaped by NATO-standardized procurement relationships. Tygron BV exemplifies the geospatial simulation archetype emerging from Dutch university R&D partnerships. These three entities represent distinct competitive vectors: classified military scenario libraries, municipal infrastructure visualization engines, and cross-vertical platform architectures.
| Leading Market Players |
|---|
| MPS Interactive Systems |
| Tygron BV |
| BreakAway Games |
| Firsthand Technology |
| KTM Advance |
| Designing Digitally Inc. |
| Serious Games Solutions |
| Bedaux Serious Games |
| Diginext (CS Group) |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp freight corridor shapes cost dynamics across the Europe Serious Gaming Market, concentrating GPU and haptic controller logistics through Benelux distribution hubs while downstream price differentiation reflects certification tier and rendering hardware sourcing.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for adaptive serious gaming platforms, separating high-risk biometric-enabled systems from standard SCORM-compliant modules. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and NATO-interoperability status. Cost compression in mid-market corporate training subscriptions is intensifying because enterprise buyers unbundle perpetual licenses for consumption-based models. Healthcare VR therapy developers show least price sensitivity due to reimbursement pathway investments, while education sector procurement teams demonstrate highest elasticity.
Supply Chain Analysis
Tariff exposure between Taiwan and Germany dominates supply chain risk calculations for rendering hardware procurement. GPU and haptic controller manufacturing concentrates in Taiwan, South Korea, and China, while European assemblers source behavioral analytics middleware from domestic software clusters. Raw material dependencies span advanced semiconductor substrates, precision motion sensors, and optical display components. Single-source vulnerability in East Asian foundry capacity exposes vendors to logistics volatility. Distribution runs through specialized AV integrators and defense procurement channels rather than open retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Serious Gaming Market rewards vendors who command scarce intersections between pedagogical design expertise and AR/VR engine architecture, with talent gaps widening faster than university pipeline output.
For Market Incumbents: Insulate NATO-certified scenario libraries through exclusive Bundeswehr and French defense ministry co-location strategies. Deepen in-house production of behavioral analytics middleware to reduce dependency on third-party licensing. Acquire specialist competency framework developers before EU AI Act compliance mandates consolidate procurement around explainable algorithm vendors. For New Entrants and Emerging Players: Establish a beachhead in Netherlands municipal infrastructure simulation, where Tygron BV partnership models demonstrate replicable contract structures across Benelux and Nordic markets. Target healthcare VR therapy modules pursuing EMA provisional medical device status, as reimbursement pathway maturity outpaces incumbent coverage. Deploy cloud-native rendering architectures to bypass capital-intensive on-premise GPU cluster requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from defense-heritage simulation studios with dormant urban planning or healthcare vertical capabilities. Five-to-ten year viability hinges on adaptive algorithm explainability compliance rather than raw rendering performance. Monitor German and French health technology assessment body decisions on VR therapy reimbursement eligibility as the decisive inflection signal for healthcare segment capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Explainable algorithm documentation unlocks high-risk adaptive system contracts under EMA and BSI oversight. |
| Behavioral Analytics Middleware Acquisition | Real-time competency certification engines differentiate platforms from static SCORM-compliant competitors. |
| Defense Ministry Co-location Expansion | Munich and Stuttgart clusters compress vendor qualification timelines for NATO-interoperable scenario procurement. |
| Healthcare Reimbursement Strategy | Provisional medical device status under German and French assessment frameworks unlocks public payment channels. |
| Cloud-Native Rendering Infrastructure | Distributed edge computing nodes reduce latency for multi-user defense and corporate training scenarios. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with defense procurement officers, serious gaming platform developers, health technology assessment specialists, and corporate training directors; and secondary validation through EU AI Act regulatory filings, EMA medical device evaluation records, NATO standardization agreements, and Bundeswehr procurement disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from institutional training budget disclosures and defense ministry expenditure reports.
Forecast inputs span end-user vertical adoption curves, technology deployment model transitions, and regulatory compliance timeline accelerations across the analysis window. Segmentation dimensions include rendering modality, pedagogical outcome category, procurement authority structure, and geographic regulatory cluster. CAGRs derive from logistic curve fitting to institutional adoption patterns, with scenario weighting for EU AI Act implementation pace and VR therapy reimbursement pathway maturity.
Sensitivities concentrate around EMA medical device classification decisions, Bundeswehr procurement cycle compression sustainability, and East Asian semiconductor supply continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Game Engine Management Market
Gaming
Online Strategy Games Market
Gaming
3D Gaming Technology Market
Gaming
Gaming Software Market
Gaming
Mobile MOBA Games Market
Gaming
Middle East and Africa Gaming Headsets Market
Gaming
Online Casino Market
Gaming
Traditional Casual Games Market
Gaming
Gaming As a Service Market
Gaming
Simulation Video Game Market
Gaming
North America Casino Gambling Market
Gaming
Videogames Market
Gaming
Social Gaming Market
Gaming
Shooter Game Market
Gaming
Australia Casino Tourism Market
Gaming
Saudi Arabia Entertainment and Amusement Market