
 Gaming As a Service Market | 2026-2036
Gaming As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming As a Service Market Insights
South Korea is rewriting competitive dynamics in cloud gaming infrastructure through nationwide 5G coverage and government-backed digital content funds. Microsoft Corporation leverages its Azure data center footprint to sustain low-latency streaming across multiple continents. Sony Corporation anchors its position through exclusive content libraries and console-integrated subscription tiers. NVIDIA Corporation differentiates via GPU virtualization technology that powers third-party streaming services.
Gaming As a Service delivers interactive software experiences through remote server processing, with video streams compressed at 60 frames per second and sub-50 millisecond latency thresholds for real-time playability. The model eliminates local hardware dependencies while enabling cross-platform progression and instant library access. Cloud-Based delivery dominates structural investment as hyperscalers compete on edge node density, while Mobile platform adoption leads subscriber growth due to emerging market smartphone penetration. Subscription service type captures the most predictable revenue pools, though Pay-Per-Use models attract episodic gamers seeking title-specific access without recurring commitments.
FCC broadband infrastructure rules in the United States, GDPR data processing requirements across Europe, and China's MIIT content licensing framework collectively shape market access and operational compliance for platform operators. These regulations determine where personal gameplay data may reside, how age verification functions deploy, and which titles receive distribution approval. Stakeholders must monitor evolving spectrum allocation decisions and cross-border data sovereignty negotiations that could redefine service architecture requirements.
Market Dynamics
Cloud gaming infrastructure is concentrating around hyperscaler data center networks, with edge node proximity emerging as the decisive competitive variable for latency-sensitive interactive streaming.
Growth Catalysts
- 5G Network Deployment:South Korea's nationwide 5G coverage and FCC broadband expansion rules in the United States reduce latency thresholds below 50 milliseconds, enabling real-time gameplay without local hardware.
- Subscription Service Models:Cross-platform progression and instant library access attract individual gamers seeking predictable monthly costs over discrete hardware purchases.
- GPU Virtualization:Advances in server-side graphics processing eliminate dependency on consumer-grade graphics cards, democratizing access to high-fidelity gaming experiences.
Market Restraints
- Data Center Capital Intensity:Hyperscalers must deploy edge nodes within 50 kilometers of population centers, requiring sustained infrastructure investment that smaller competitors cannot match.
- Input Cost Volatility:Graphics processing unit supply constraints and memory chip pricing fluctuations compress margins for platform operators dependent on hardware refresh cycles.
- Regulatory Fragmentation:GDPR data residency requirements across Europe and China's MIIT content licensing framework create operational friction for cross-border service architecture.
Strategic Opportunities
- Emerging Market Smartphone Penetration:India and Southeast Asian markets present underpenetrated subscriber pools where mobile-first cloud gaming bypasses console infrastructure gaps.
- Regulatory Tailwinds:South Korea's government-backed digital content funds and spectrum allocation policies subsidize domestic platform development and international expansion.
- Technology Convergence:Integration of artificial intelligence-driven compression algorithms with 5G network slicing enables adaptive bitrate streaming for variable connection quality.
Industry Challenges
- Specialized Talent Scarcity:Platform operators face acute shortages of network engineers capable of optimizing edge node distribution for sub-50 millisecond latency guarantees.
- Content Licensing Complexity:Exclusive distribution agreements and intellectual property fragmentation across publishers create subscriber acquisition friction.
- Certification Timeline Compression:Age verification systems and data protection compliance across multiple jurisdictions extend go-to-market timelines for new service launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming As a Service Market |
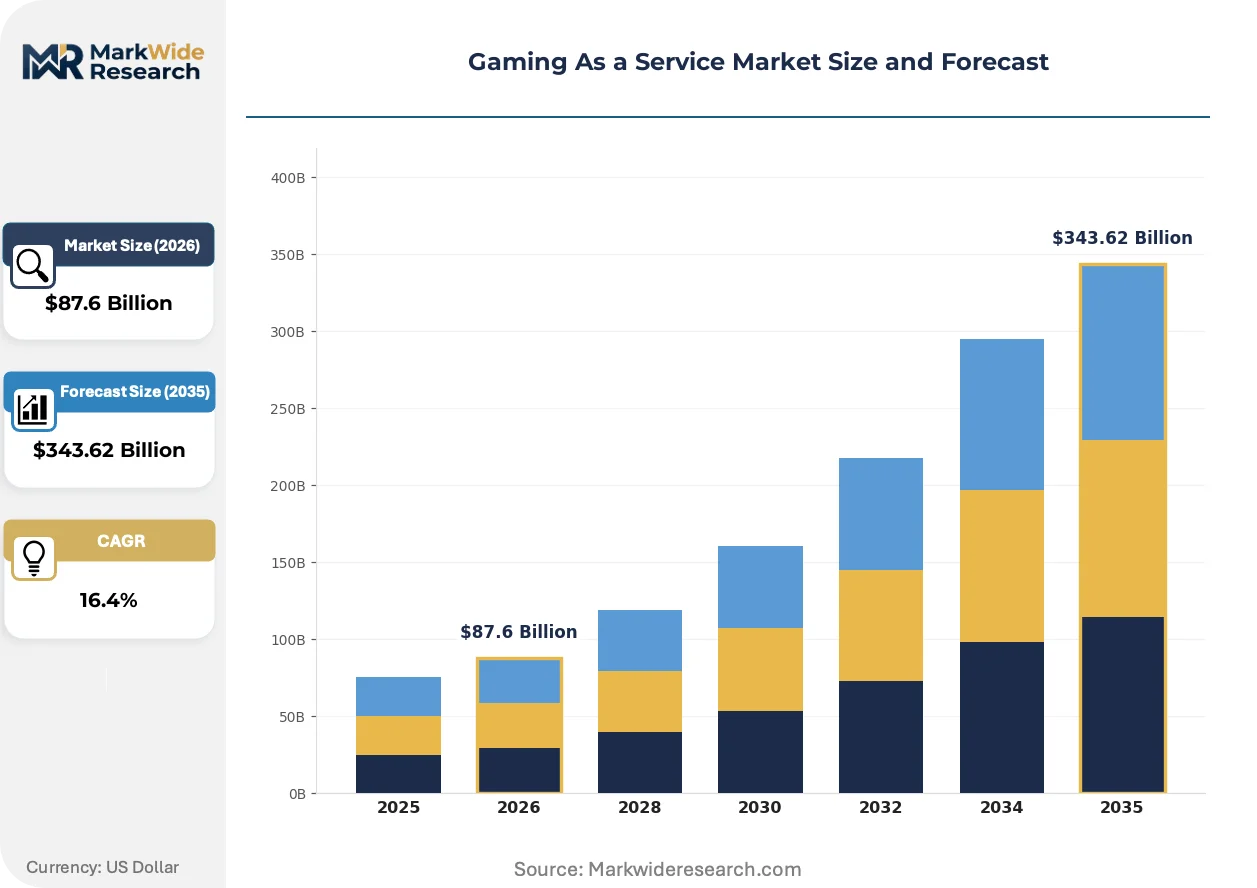
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $343.62 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription, On-Demand, Pay-Per-Use, Bundled Services Delivery Model: Cloud-Based, Edge Computing, Hybrid, Client-Server Platform Type: Console, PC, Mobile, VR End User: Individual Gamers, E-Sports Teams, Educational Institutions, Corporate Clients |
| Companies Covered | Microsoft Corporation, Sony Corporation, Google LLC, NVIDIA Corporation, Electronic Arts Inc., Tencent Holdings Ltd., Apple Inc., Nintendo Co. Ltd., Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming As a Service Market Trends and Innovations
Interactive software delivery is migrating from device-centric ownership models to streaming-centric access paradigms, compressing hardware replacement cycles while expanding addressable audiences.
Edge computing architecture is migrating from centralized hyperscale data centers toward distributed metropolitan nodes. Telecommunications operators in Germany and Japan are deploying micro data centers within 30 kilometers of subscriber concentrations. This migration from regional concentration to hyperlocal presence enables sub-30 millisecond latency for competitive multiplayer titles.
GDPR's data processing requirements are reshaping how platform operators architect gameplay telemetry storage. European regulators now mandate explicit consent mechanisms for biometric data collection in immersive experiences. Publishers serving EU audiences are responding by localizing data residency and deploying granular privacy dashboards.
Consumption patterns among episodic gamers favor pay-per-use access over recurring subscription commitments. This behavioral shift disrupts platform revenue predictability and pressures operators to unbundle library access into title-specific rental tiers. The phenomenon is most visible in the United States, where casual mobile users resist monthly fees for intermittent play sessions.
Gaming As a Service Market Segmentation
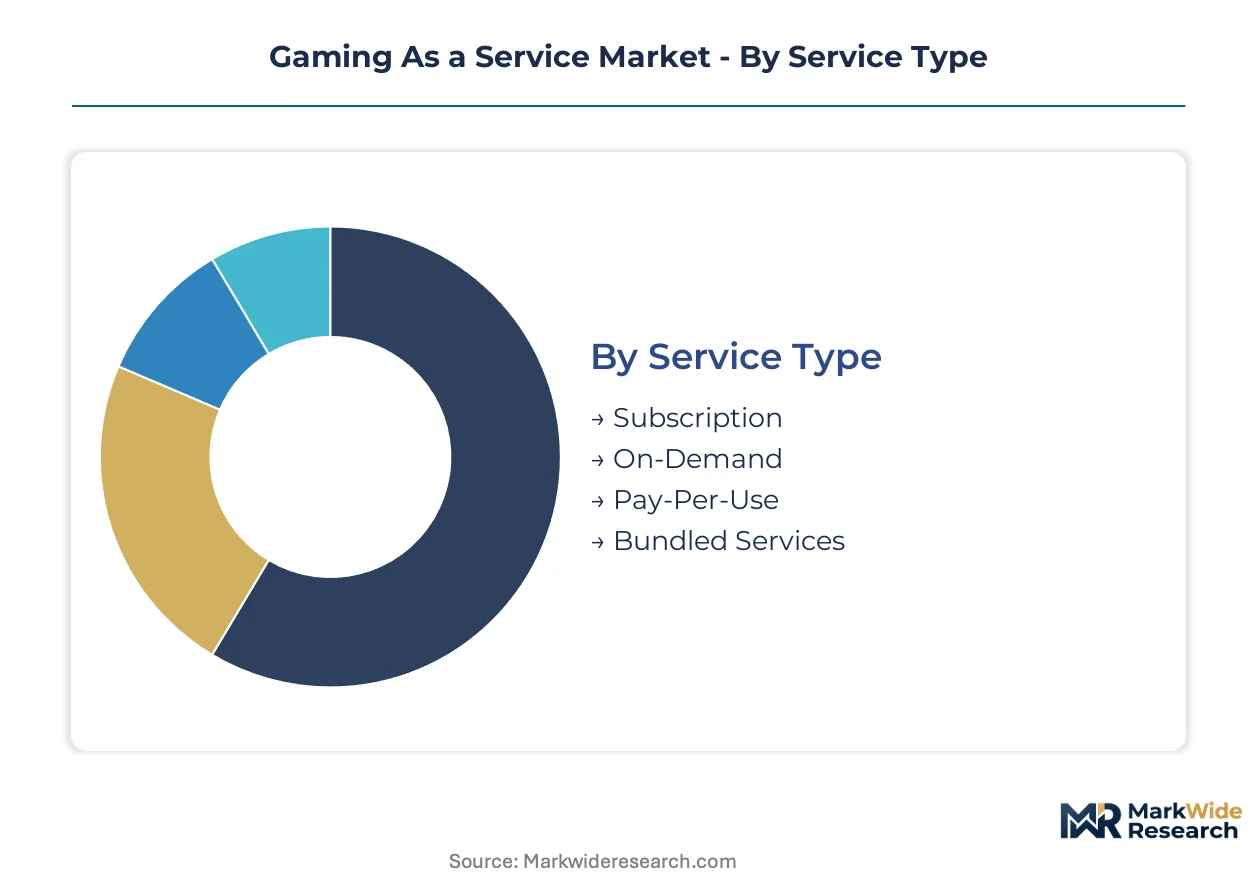
Service architecture in Gaming As a Service determines infrastructure investment intensity and customer lifetime value profiles. Segmentation reveals where platform operators concentrate engineering resources and which delivery modes command premium pricing.
Service Type:
After-sales service intensity varies dramatically across monetization models, with subscription tiers demanding continuous content refresh and pay-per-use requiring instant provisioning without retention infrastructure.
- Subscription:Recurring monthly access to curated game libraries with cloud save synchronization and cross-platform progression. Demand concentrates in the United States where FCC broadband expansion enables reliable streaming, though subscriber acquisition costs escalate as exclusive content licensing fees rise.
- On-Demand:Instant library access without recurring commitment, typically priced per session or hourly. Individual gamers in South Korea favor this model for episodic engagement with AAA titles, driven by government-backed digital content funds that subsidize domestic platform infrastructure.
- Pay-Per-Use:Title-specific rental tiers for single-game access without subscription overhead.
- Bundled Services:Combined gaming access with telecommunications or hardware purchase agreements.
By volume, Subscription leads. By growth pace, Pay-Per-Use is ahead.
Delivery Model:
Cost tier differentiation separates hyperscaler-backed cloud deployments from capital-light hybrid approaches, with edge computing commanding infrastructure premiums for competitive latency guarantees.
- Cloud-Based:Centralized hyperscale data center processing with video stream compression at 60 frames per second. Microsoft Corporation leverages its Azure footprint across multiple continents to sustain this model, while GPU virtualization advances eliminate consumer graphics card dependencies.
- Edge Computing:Distributed metropolitan nodes within 50 kilometers of subscribers for sub-30 millisecond latency. Telecommunications operators in Germany and Japan deploy micro data centers near population concentrations, with 5G network slicing enabling adaptive bitrate streaming.
- Hybrid:Blended local processing with remote rendering for variable connection quality.
- Client-Server:Traditional architecture with heavier local hardware requirements and lighter streaming dependency.
By deployment scale, Cloud-Based dominates. By expansion trajectory, Edge Computing climbs the fastest.
Platform Type:
Customer type fragmentation drives divergent technical specifications, with mobile-first architectures prioritizing bandwidth efficiency over visual fidelity.
- Mobile:Smartphone-optimized streaming with touch control overlays and adaptive resolution scaling. India and Southeast Asian markets present underpenetrated subscriber pools where mobile-first cloud gaming bypasses console infrastructure gaps entirely.
- Console:Integrated subscription tiers tied to proprietary hardware ecosystems with exclusive content libraries. Sony Corporation anchors this segment through console-integrated offerings that leverage established install bases.
- PC:Keyboard-mouse precision and ultrawide display support for enthusiast segments.
- VR:Immersive experiences requiring sub-20 millisecond motion-to-photon latency and biometric data collection governed by GDPR consent mechanisms.
By subscriber count, Mobile leads. By revenue per user, Console is ahead.
End User:
Maturity gradients separate individual consumer adoption from institutional procurement cycles, with corporate and educational segments demanding customized service level agreements.
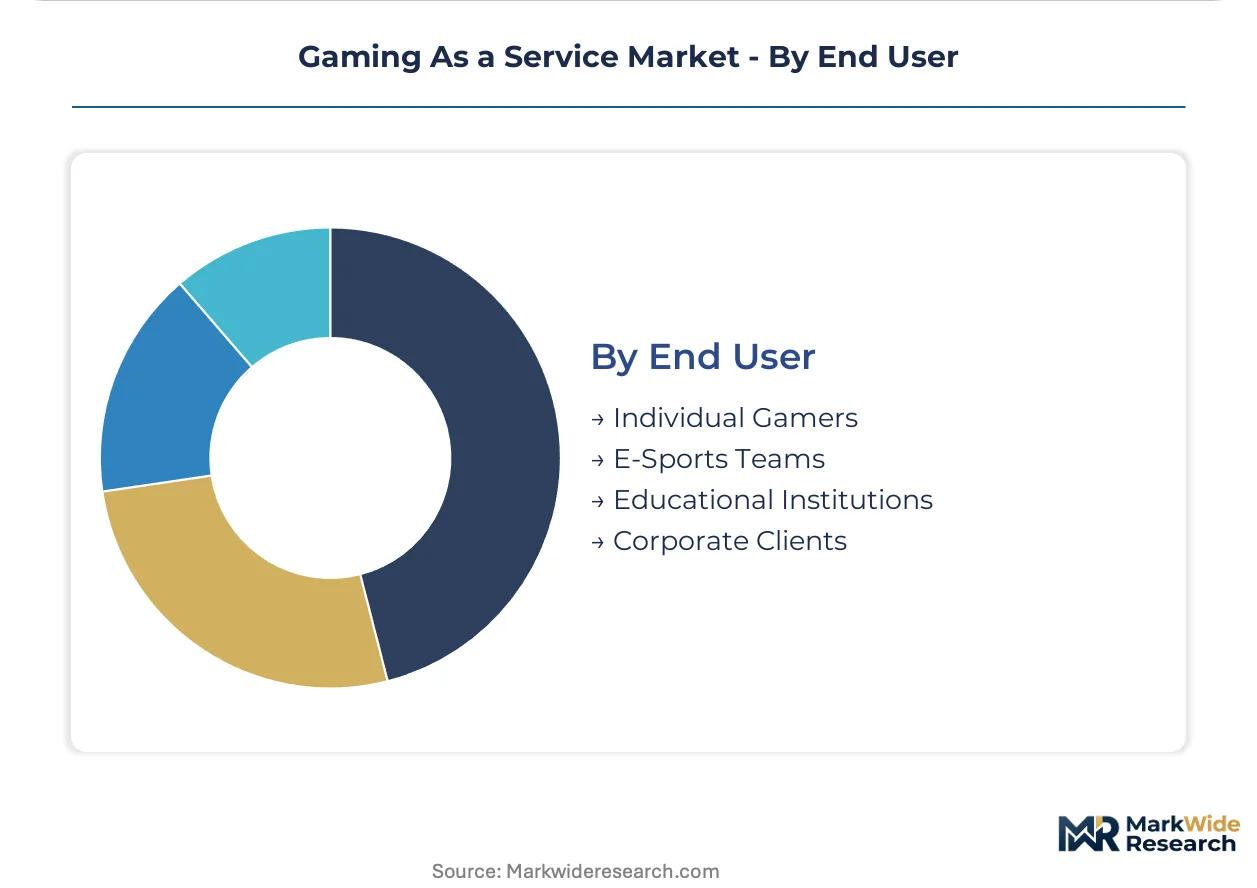
- Individual Gamers:Mass-market consumers seeking cross-platform progression and instant library access. South Korea's nationwide 5G coverage reduces latency thresholds below 50 milliseconds for this segment, while GDPR data residency requirements shape European service architecture.
- E-Sports Teams:Professional competitors requiring guaranteed sub-30 millisecond latency for tournament integrity and spectator streaming integration.
- Educational Institutions:Curriculum-integrated game-based learning with administrative oversight tools and age verification systems.
- Corporate Clients:Team-building and training applications with enterprise security compliance and usage analytics dashboards.
By addressable population, Individual Gamers leads. By contract value growth, Corporate Clients is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC broadband infrastructure rules anchor the United States as the dominant geography, with data center investments and spectrum allocation policies shaping competitive deployment timelines across national markets.
United States
Individual gamers drive cloud gaming adoption through FCC-enabled broadband expansion and Azure data center proximity. The regulator's infrastructure rules accelerate edge node deployment within 50 kilometers of metropolitan concentrations. Seattle and Northern Virginia host hyperscaler facilities sustaining low-latency streaming across multiple continents.
South Korea
Nationwide 5G coverage reduces latency thresholds below 50 milliseconds for real-time gameplay. Government-backed digital content funds subsidize domestic platform development and international expansion. Seoul anchors competitive infrastructure deployment through metropolitan edge computing clusters.
China
MIIT content licensing frameworks determine distribution approval for platform operators entering the market. Dual carbon goals shape data center energy efficiency requirements for cloud gaming infrastructure. Shenzhen and Beijing concentrate domestic platform engineering resources.
Germany
GDPR data residency requirements reshape gameplay telemetry storage architecture for EU audiences. Telecommunications operators deploy micro data centers within 30 kilometers of subscriber concentrations. Frankfurt and Munich anchor edge computing migration for sub-30 millisecond latency guarantees.
Japan
METI spectrum allocation policies enable 5G network slicing for adaptive bitrate streaming. Console-integrated subscription tiers leverage established install bases for cross-platform progression. Tokyo and Osaka metropolitan areas concentrate telecommunications operator edge node investments.
Gaming As a Service Market Competitive Landscape
Capability concentration sits with hyperscaler-backed platforms; scale advantage sits with established console ecosystems. The market structures around three tiers: cloud infrastructure operators, content-integrated hardware manufacturers, and GPU virtualization specialists. Strategic differentiation follows two dominant competitive moves—exclusive content licensing for subscriber retention, and edge node density expansion for latency-sensitive interactive streaming.
Within the hyperscaler tier, Microsoft Corporation and Amazon Web Services occupy positions defined by global data center footprint and cloud-native service architecture. Sony Corporation and Nintendo Co. Ltd. exemplify the console-integrated archetype, leveraging proprietary hardware ecosystems. NVIDIA Corporation represents the GPU virtualization specialist segment powering third-party streaming infrastructure.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Sony Corporation |
| Google LLC |
| NVIDIA Corporation |
| Electronic Arts Inc. |
| Tencent Holdings Ltd. |
| Apple Inc. |
| Nintendo Co. Ltd. |
| Amazon Web Services |
| Others |
Pricing and Supply Chain Analysis
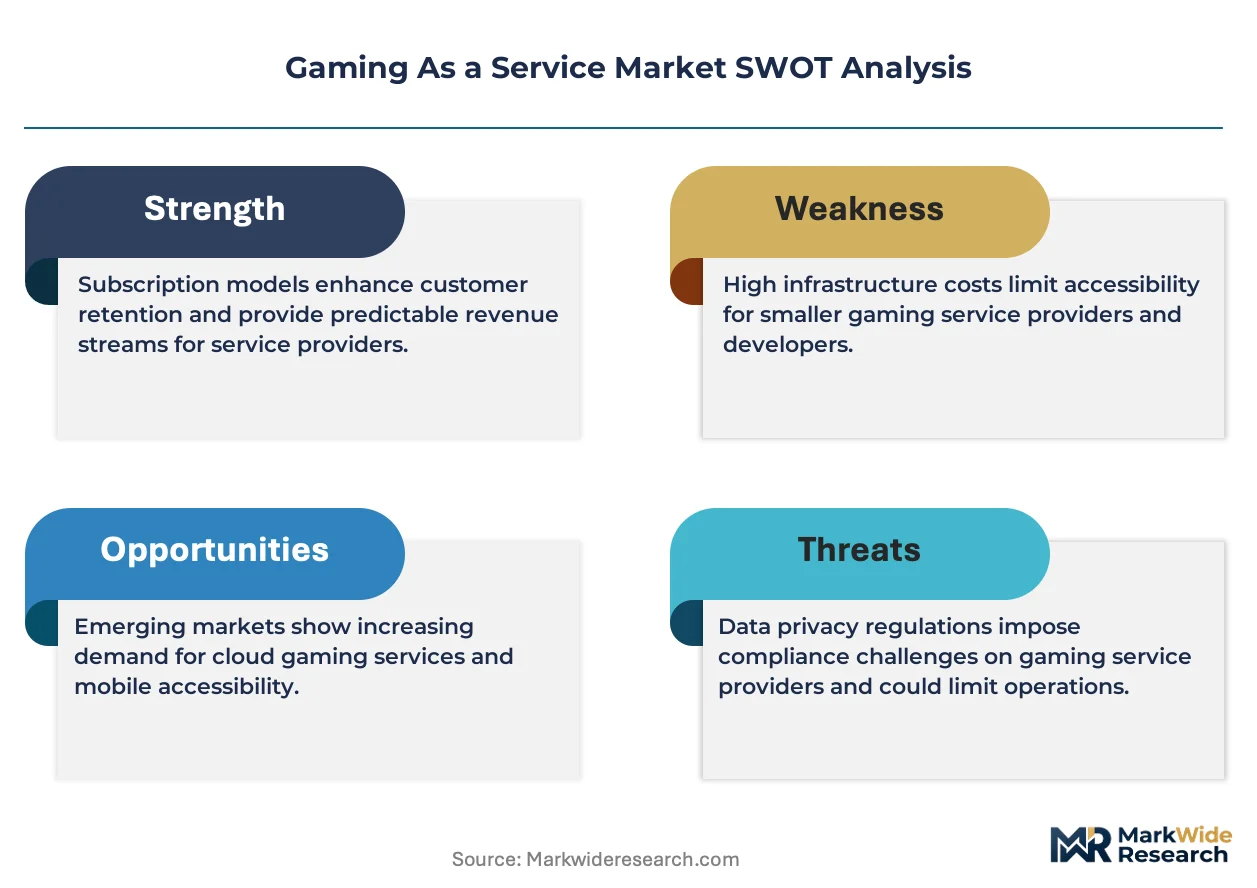
GPU supply volatility from Taiwan Semiconductor Manufacturing and Samsung Foundry constrains both subscription tier spreads and infrastructure buildout timelines. This single-source dependency forces hyperscalers to absorb margin compression while smaller operators retreat from edge node commitments.
Pricing Analysis
Subscription pricing spreads widen between the United States and Southeast Asia, with FCC-enabled broadband density supporting premium tiers in American metropolitan clusters while Indian mobile-first markets favor economy access. Three-tier pricing structure across premium, standard, and economy levels reflects latency guarantees and content library breadth. Price differentiation hinges on edge node proximity and exclusive licensing arrangements. Cost compression in economy tiers is intensifying because memory chip pricing fluctuations compress operator margins.
Supply Chain Analysis
Extended payment terms from NVIDIA Corporation and AMD shape capital deployment timelines for platform operators building server fleets. GPU fabrication concentrates in Taiwan, South Korea, and the United States, with advanced node production drawing from ASML lithography equipment and HBM memory modules. Single-source vulnerability in CoWoS packaging capacity creates bottleneck risk for virtualization hardware. Distribution runs through hyperscaler direct procurement and telecommunications operator channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud gaming represents a service-attach opportunity where subscription revenue layers expand faster than console hardware replacement cycles, rewarding operators who decouple content access from device ownership.
For Market Incumbents: Harden exclusive content pipelines against emerging mobile-native entrants by deepening first-party studio acquisitions and extending console-integrated subscription tiers. Secure GPU allocation commitments through multi-year foundry agreements to defend against supply rationing. Lock in telecommunications operator partnerships for metropolitan edge node deployment before spectrum auctions close.
For New Entrants and Emerging Players: Indian smartphone penetration presents the most penetrable subscriber pool, where mobile-first cloud gaming bypasses console infrastructure gaps entirely. Target pay-per-use monetization for episodic gamers resisting monthly commitments. Pursue white-label platform licensing to regional telecommunications operators seeking gaming revenue without proprietary engineering investment.
For Investors and Strategic Acquirers: Edge computing infrastructure specialists with metropolitan node density and 5G network slicing capabilities offer the strongest acquisition profile. Long-term viability favors operators who control both virtualization layer and last-mile delivery. Watch for FCC spectrum allocation decisions and GDPR data residency rulings as inflection indicators for infrastructure investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Node Expansion | Hyperscaler deployment within 50 kilometers of subscribers enables sub-30 millisecond latency guarantees for competitive multiplayer. |
| Exclusive Content Licensing | First-party studio acquisitions anchor subscriber retention against platform-agnostic streaming competitors. |
| GPU Virtualization Scale-Up | Server-side graphics processing eliminates consumer hardware dependencies while democratizing high-fidelity access. |
| Telecommunications Partnership | 5G network slicing agreements with Deutsche Telekom and NTT enable adaptive bitrate streaming for variable connections. |
| Regulatory Compliance Investment | GDPR data residency architecture and MIIT content licensing frameworks determine market access eligibility. |
Research Methodology
Desk research of hyperscaler capex disclosures, telecommunications operator spectrum filings, and regulatory commission dockets preceded structured interviews with cloud platform engineers, content licensing executives, network infrastructure architects, and data center procurement leads. Secondary validation drew from FCC broadband deployment maps, ETSI network standards documentation, and GPU manufacturer supply chain disclosures. Bottom-up subscriber modeling and top-down infrastructure investment analysis were triangulated against reported platform metrics.
Assumptions held 5G network coverage expansion, GPU virtualization cost curves, and content licensing fee trajectories within observed historical patterns across the analysis window. Segmentation dimensions modeled include service type, delivery model, platform type, and end user category, with regional regulatory clusters treated as distinct adoption environments. CAGRs were derived from infrastructure deployment timelines and subscriber conversion rate benchmarks.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration by console manufacturers or hyperscaler entry into exclusive content production would shift outcomes. Macroeconomic contraction affecting discretionary entertainment spending, regulatory fragmentation tightening data sovereignty requirements, or breakthroughs in client-side rendering efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
LAMEA in-Game Advertising Market
Gaming
SLG Game Market
Gaming
Video Game Software Market
Gaming
Arcade Cabinet Market
Gaming
Gaming Peripheral Market
Gaming
Social Gaming Market
Gaming
Global Game Testing Service Market
Gaming
Flat Gaming Monitors Market
Gaming
Gaming Chair Market
Gaming
United States Virtual Reality Gaming Market
Gaming
Mobile and Handheld Gaming Market
Gaming
Russia in-Game Advertising Market
Gaming
Mobile Game Controller Market
Gaming
United States Gaming Accessories Market
Gaming
Global Online Adventure Games Market
Gaming
VR Gaming Accessories Market