
 Global Tarot Cards Market | 2026-2036
Global Tarot Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tarot Cards Market Outlook
A shift from single-source paper suppliers toward multi-source pulp sourcing is pivoting how tarot publishers manage cost volatility and fiber traceability. Cartamundi leverages its Belgian manufacturing scale to control premium card stock quality across European and North American print runs. Llewellyn Worldwide anchors its position through deep backlist strength in esoteric publishing and direct-to-reader subscription channels. Naipes Heraclio Fournier competes on heritage lithography techniques that sustain collector demand for Spanish-produced decks.
Tarot cards are printed playing-card-format products, typically 78-card sets comprising 22 Major Arcana and 56 Minor Arcana suits, manufactured on 300–350 gsm art paper with matte or linen finish lamination for shuffle durability and tactile ritual use in divination, meditation, and narrative therapy. Modern decks lead volume growth as independent artists self-publish through crowdfunding platforms, while art decks command the highest per-unit margins due to limited print runs and signed packaging. Distribution through online retail channels is displacing bookstore placement as algorithms surface niche aesthetic variants to fragmented hobbyist and spiritual-reader segments.
CE marking governs toy safety and chemical migration limits for tarot products sold in European Union member states, while the FDA regulates ink formulations for U.S.-imported playing cards under indirect food-contact material guidelines. California's Proposition 65 requires explicit labeling for decks containing trace heavy metals in pigment compounds, adding compliance costs for Asian contract printers. Stakeholders must monitor how EU Green Deal packaging waste directives and emerging state-level extended producer responsibility laws in Germany and France reshape cardboard sourcing and end-of-life collection obligations for premium deck publishers.
Market Dynamics
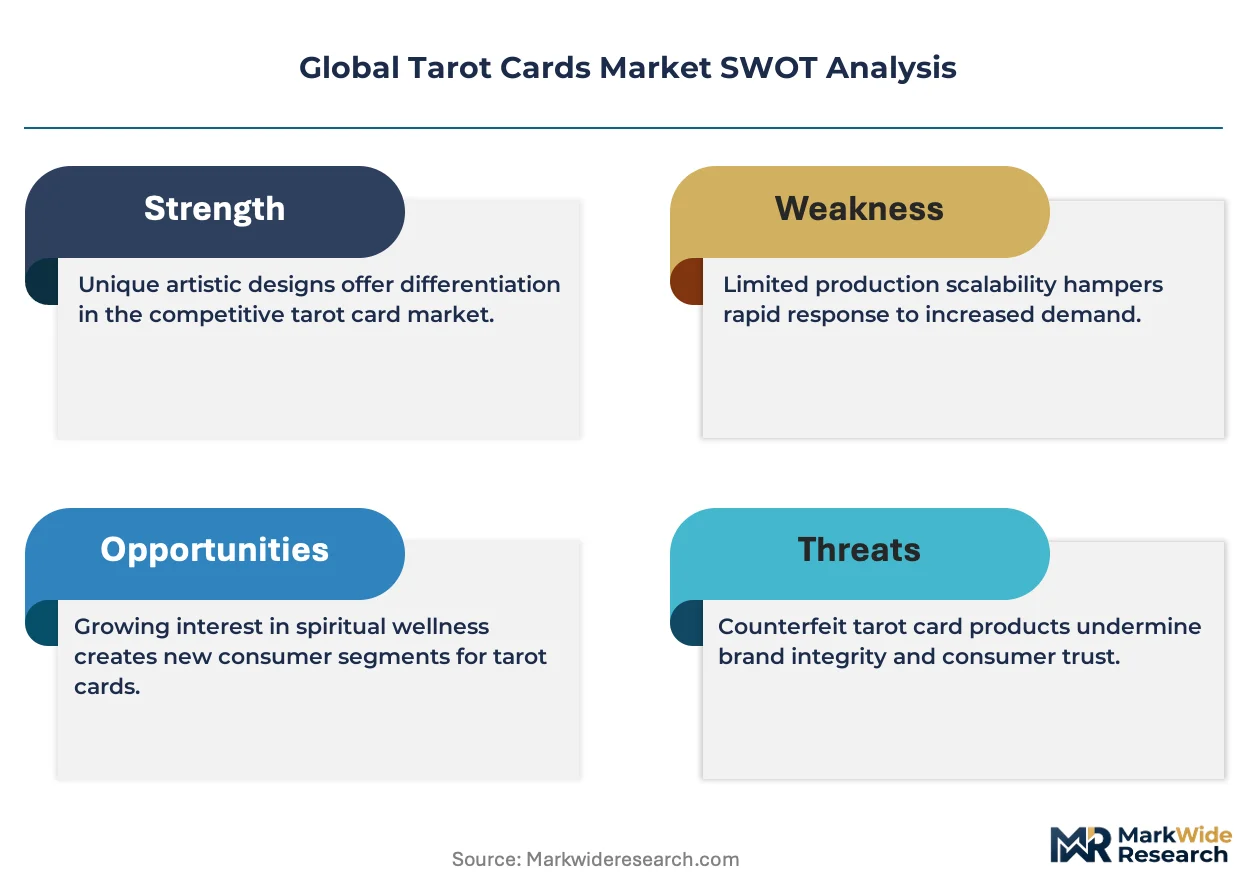
Tarot card publishers confront a structural pivot where REACH compliance in Europe and Proposition 65 in California are forcing simultaneous reformulation of pigment chemistry and packaging substrates, compressing margins for mid-tier producers while advantaging vertically integrated manufacturers with captive ink laboratories.
Growth Catalysts
- Metaphysical retail networks:Independent bookstores and witchcraft shops in the United States function as community hubs where tactile deck examination drives impulse purchases of premium editions. Staff curation surfaces emerging artists to established collector bases.
- REACH material standards:European Union chemical migration limits for paper products are accelerating substitution of petroleum-based laminates with bio-derived coatings, opening contract manufacturing opportunities for certified sustainable printers in Belgium and Germany.
- Crowdfunding platforms:Kickstarter and Backerkit enable independent illustrators to bypass traditional publishing gatekeepers, funding limited print runs through pre-orders that validate aesthetic concepts before production commitment.
Market Restraints
- Art paper cost volatility:Cotton rag and wood pulp prices fluctuate with energy markets, squeezing publishers dependent on 300–350 gsm stock for shuffle durability. Asian contract printers face margin compression when fiber costs spike.
- CE marking compliance burden:Toy safety testing and chemical documentation requirements for European Union entry impose fixed costs that disproportionately burden small-batch art deck producers with limited print runs.
- Digital divination substitutes:Smartphone applications offering algorithmic card draws and AI interpretation erode demand among casual users who prioritize convenience over tactile ritual engagement.
Strategic Opportunities
- Brazilian spiritualist communities:Candomblé and Umbanda practitioners represent an underpenetrated end-use segment where Portuguese-language decks with culturally resonant iconography command premium positioning.
- Extended producer responsibility laws:Germany's packaging waste directives and France's anti-gaspillage regulations create first-mover advantages for publishers establishing cardboard take-back programs and recyclable tuck-box designs.
- Narrative therapy applications:Licensed counselors in Australia and Canada are integrating tarot into trauma-processing protocols, opening institutional procurement channels distinct from metaphysical retail.
Industry Challenges
- Heritage lithography skill scarcity:Spanish and Italian facilities maintaining traditional Fournier and Modiano printing techniques face generational knowledge transfer gaps as master craftsmen retire without trained successors.
- FDA ink formulation documentation:United States importers must demonstrate indirect food-contact compliance for playing card pigments, creating certification timeline delays when switching between Asian contract printers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tarot Cards Market |
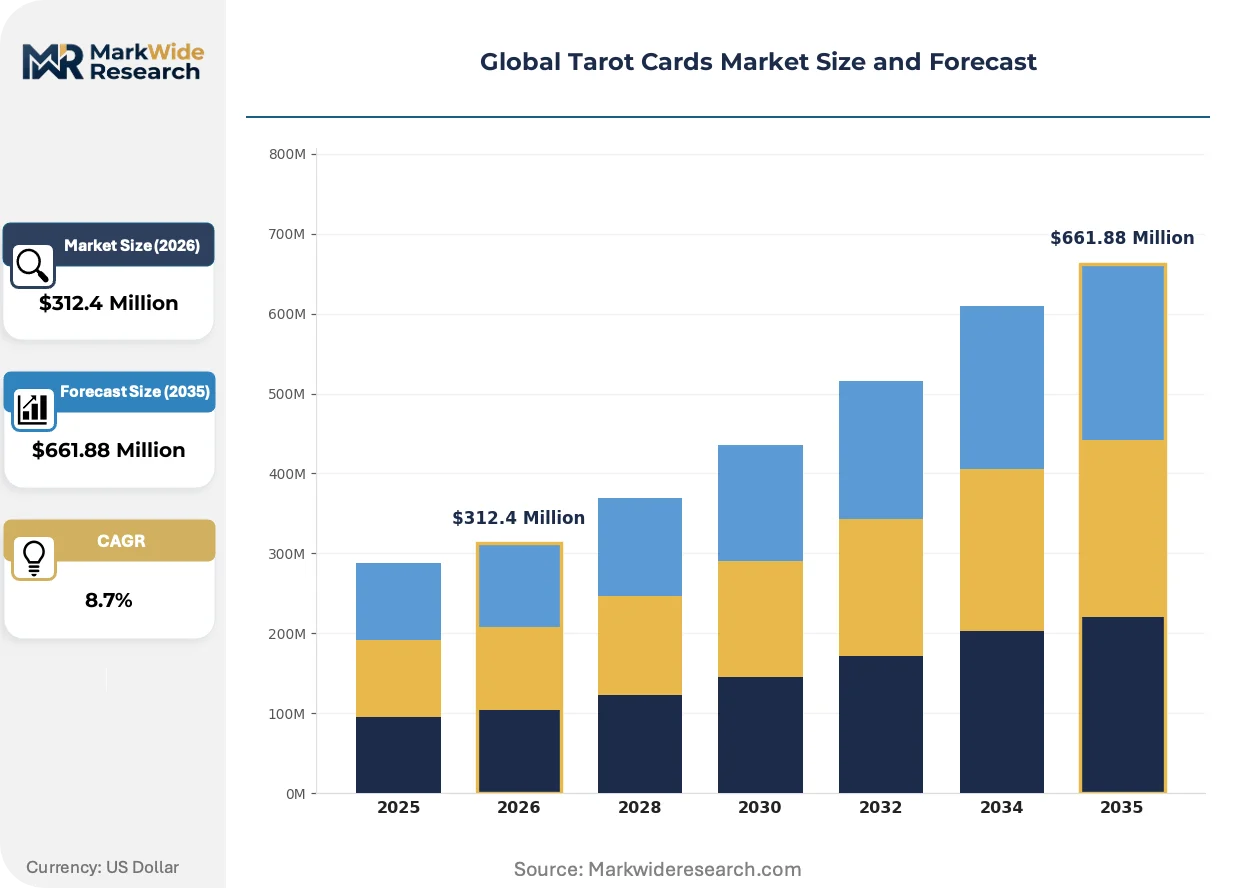
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Decks, Modern Decks, Art Decks, Themed Decks Application: Personal Use, Professional Readings, Spiritual Guidance, Entertainment End User: Individuals, Tarot Readers, Spiritual Practitioners, Hobbyists Distribution Channel: Online Retail, Bookstores, Metaphysical Shops, Craft Fairs |
| Companies Covered | Naipes Heraclio Fournier, AzureGreen, U.S. Games Systems Inc., Red Wheel/Weiser, Hay House, Cartamundi, Llewellyn Worldwide, Schiffer Publishing, Lo Scarabeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tarot Cards Market Strategic Shifts
Electrostatic flocking and augmented reality overlays are redefining tactile and digital boundaries in tarot production, while regulatory chemistry shifts and algorithmic retail discovery reshape how decks reach fragmented spiritual-reader and collector segments.
Augmented reality companion applications are electrifying the boundary between physical decks and digital interpretation layers. Premium publishers embed NFC chips or QR-linked experiences that unlock animated card meanings when scanned by smartphones. Collector segments in Japan and South Korea adopt these hybrid products fastest, compressing the traditional gap between artisanal print objects and interactive content.
EU Green Deal packaging waste directives are mandating elimination of single-use plastics in tuck-box lamination and shrink-wrapping by 2030. Belgian and German printers are retrofitting production lines for water-based coatings and molded pulp inserts. Art deck publishers with limited print runs face disproportionate adaptation costs, pushing some toward digital-only releases or regional market withdrawal.
Algorithmic curation on TikTok and Instagram is displacing bookstore browsing as the primary deck discovery mechanism. Independent artists build follower bases through process videos, then convert engagement into direct-to-consumer sales via Shopify storefronts. This pattern concentrates most visibly in the United States and United Kingdom, where metaphysical content creators monetize aesthetic niches that traditional publishing catalogs overlook.
Global Tarot Cards Market Segmentation
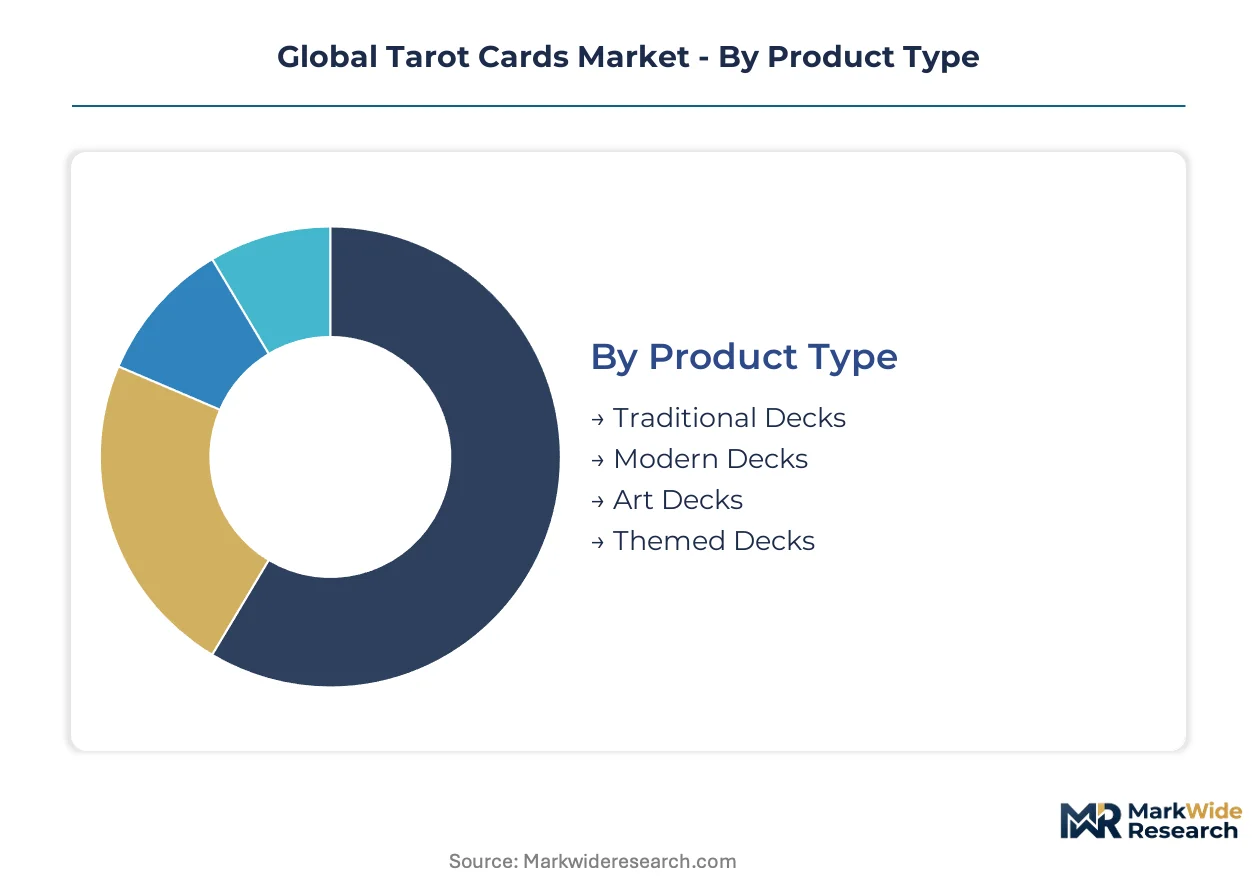
Tarot card segmentation reveals how production capabilities and ritual use cases fragment across price points and procurement channels. Understanding these divides clarifies where margin pools concentrate and which formats face substitution pressure from digital alternatives.
Product Type:
Supply concentration in Belgian and Spanish printing facilities shapes competitive dynamics across deck categories, with lithography heritage and cardstock sourcing determining which publishers capture collector premiums versus mass-market volume.
- Traditional Decks:78-card sets following Rider-Waite-Smith iconography standards, printed on 300 gsm art paper with linen finish. Demand clusters among United States spiritual practitioners seeking interpretive consistency for client readings, constrained by limited differentiation between publisher offerings.
- Modern Decks:Revised archetype imagery and inclusive representation drive Kickstarter-funded production runs. Independent illustrators in the United Kingdom and Australia convert social media followings into pre-order validation, expanding most quickly as algorithmic discovery surfaces niche aesthetics.
- Art Decks:Limited print runs with hand-numbered certificates and specialty packaging command collector premiums in Japan and South Korea.
- Themed Decks:Licensed pop culture or literary tie-ins target gift purchasers through Amazon and specialty retail.
Today's leader: Traditional Decks. Tomorrow's challenger: Modern Decks.
Application:
Cost tier stratification separates institutional procurement from impulse purchases, with therapeutic and professional use cases justifying premium cardstock and compliance documentation that casual entertainment buyers reject.
- Personal Use:Meditation and self-reflection drive repeat purchases as collectors build multi-deck libraries. United States consumers favor matte lamination for home shuffling durability.
- Professional Readings:Certified tarot readers require CE-marked decks for European Union market access, with documented chemical safety adding fixed costs per print run. Revenue concentrates in direct-to-reader subscription channels.
- Spiritual Guidance:Candomblé and Umbanda practitioners in Brazil seek Portuguese-language decks with culturally adapted iconography.
- Entertainment:Party games and novelty purchases favor lower gsm stock and simplified packaging through mass retail.
Professional Readings extract the highest per-unit margins. Personal Use delivers the steepest volume expansion.
End User:
Customer type fragmentation demands distinct marketing channels, with spiritual practitioners prioritizing provenance and certification while hobbyists respond to visual novelty and community endorsement.
- Individuals:Solitary practitioners purchasing through Instagram-discovered Shopify storefronts, climbing the fastest as algorithmic curation displaces bookstore browsing.
- Tarot Readers:Service professionals requiring deck durability across high-frequency client sessions, concentrated in United States metropolitan metaphysical retail networks.
- Spiritual Practitioners:Integrated ritual use in Wiccan and eclectic pagan communities drives demand for ethically sourced paper and biodegradable packaging.
- Hobbyists:Collector psychology sustains limited edition premiums, with Japanese buyers leading adoption of NFC-enabled hybrid decks.
Individuals dominate transaction volume. Tarot Readers sustain margin pools through professional-grade procurement.
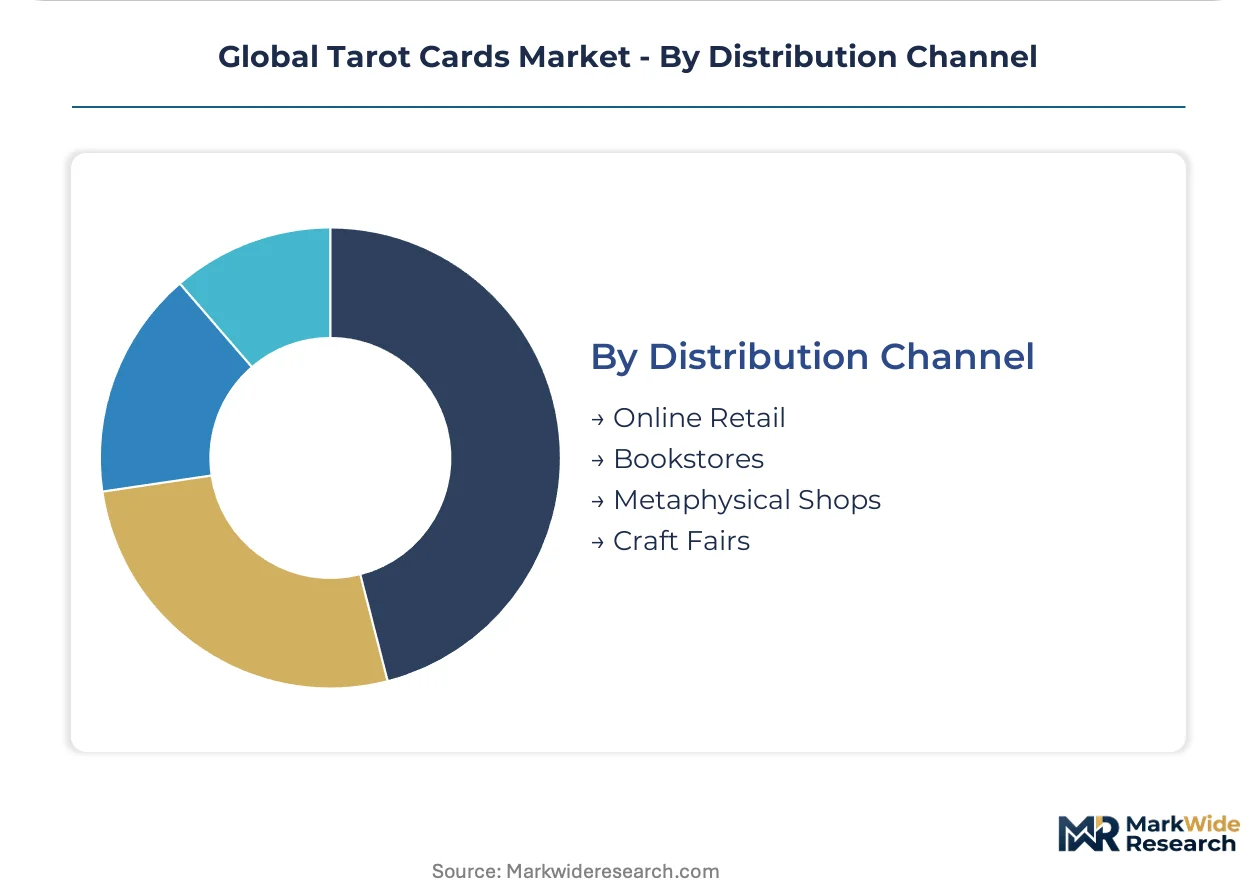
Distribution Channel:
Geography of fulfillment reshapes inventory risk, with direct-to-consumer models eliminating wholesale markdown exposure while physical retail preserves tactile evaluation for premium purchase decisions.
- Online Retail:Amazon and specialty platforms capture standard deck volume, with algorithmic recommendation engines surfacing long-tail aesthetics to fragmented segments.
- Bookstores:Barnes & Noble and independent chains curate emerging artists alongside established publishers, facing shelf space compression from declining foot traffic.
- Metaphysical Shops:United States witchcraft stores function as community hubs where staff curation drives impulse premium purchases.
- Craft Fairs:Artist-direct sales at regional spiritual gatherings in California and Oregon validate aesthetic concepts before wider production commitment.
Online Retail commands volume leadership. Metaphysical Shops defend the highest conversion rates for premium editions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between California's Proposition 65 and the European Union's REACH regime is driving production migration toward Belgian and Spanish facilities with captive compliance infrastructure, compressing margins for publishers dependent on Asian contract printers lacking chemical documentation capabilities.
United States
Metaphysical retail networks in Portland, Salem, and New Orleans sustain tactile deck examination as a primary purchase driver, with independent bookstores functioning as community hubs for emerging artist discovery. FDA indirect food-contact guidelines govern pigment formulations for imported playing cards, creating certification bottlenecks when switching between Asian suppliers. California's Proposition 65 mandates explicit heavy metal labeling, adding fixed compliance costs that favor publishers with vertically integrated ink laboratories.
Belgium
Cartamundi's Turnhout manufacturing complex anchors European premium cardstock production, leveraging REACH-compliant coating chemistry to serve both EU and North American print runs. ECHA chemical migration limits for paper products are accelerating bio-derived laminate adoption ahead of EU Green Deal packaging waste deadlines. The Flanders region concentrates lithography heritage and sustainable pulp sourcing expertise that mid-tier publishers access through contract manufacturing arrangements.
Spain
Naipes Heraclio Fournier's Vitoria-Gasteiz facility preserves heritage lithography techniques sustaining collector demand for Spanish-produced decks in Japanese and South Korean markets. ANSM toy safety documentation requirements for CE-marked exports impose fixed testing costs that disproportionately burden small-batch art deck producers. The Basque Country maintains generational printing knowledge threatened by craftsperson retirements without trained successor pipelines.
Japan
Hobbyist collectors in Tokyo and Osaka lead adoption of NFC-enabled hybrid decks combining physical cards with augmented reality interpretation layers. METI consumer safety standards govern chemical migration in paper products sold through domestic retail channels. The Kanto region concentrates specialty packaging designers serving premium art deck publishers seeking limited-edition presentation formats.
Brazil
Candomblé and Umbanda practitioners in São Paulo and Salvador represent underpenetrated demand for Portuguese-language decks with culturally adapted iconography. ANVISA pharmaceutical-adjacent oversight of ritual products remains lighter than European toy safety regimes, reducing entry barriers for independent publishers. The Southeast region concentrates spiritualist community networks that function as organic marketing channels for culturally resonant deck designs.
Global Tarot Cards Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue crowdfunding-validated aesthetic niches and algorithmic retail discovery channels. The vendor base stratifies across three tiers: heritage lithography houses with generational craft expertise, diversified playing-card manufacturers with captive compliance infrastructure, and independent artist-publishers leveraging direct-to-reader subscription models. Strategic differentiation concentrates on pigment chemistry documentation for regulatory access, cardstock sourcing for shuffle durability, and packaging sustainability for Green Deal alignment. Competitive moves prioritize backward integration into coating chemistry and geographic expansion into underpenetrated spiritualist communities.
Among heritage lithography specialists, Naipes Heraclio Fournier exemplifies craft-preservation positioning anchored in Basque Country production traditions. Cartamundi occupies the scale-driven tier with Belgian manufacturing infrastructure spanning premium and mass-market segments. Llewellyn Worldwide sits within the esoteric publishing archetype, leveraging backlist depth and direct-to-reader channels to sustain margin pools independent of retail shelf-space competition. These three represent distinct strategic postures: craft authenticity, manufacturing scale, and content-community integration.
| Leading Market Players |
|---|
| Naipes Heraclio Fournier |
| AzureGreen |
| U.S. Games Systems Inc. |
| Red Wheel/Weiser |
| Hay House |
| Cartamundi |
| Llewellyn Worldwide |
| Schiffer Publishing |
| Lo Scarabeo |
| Others |
Value Chain & Pricing Dynamics
REACH compliance deadlines in Europe are forcing publishers to reformulate pigment chemistry and packaging substrates simultaneously, compelling supply chain restructuring toward Belgian and Spanish facilities with captive compliance infrastructure and compressing margins for mid-tier producers dependent on Asian contract printers. This regulatory pressure concentrates pricing power among vertically integrated manufacturers while fragmenting cost structures across certification tiers.
Pricing Analysis
Art paper and coating chemistry pass-through dominates cost structures, with 300–350 gsm cotton rag stock and bio-derived laminates driving premium tier positioning. Price differentiation hinges on CE marking documentation and California Proposition 65 compliance tier, separating heritage lithography houses from mass-market publishers. Pricing pressure intensifies downward as Kickstarter-funded independent artists bypass traditional gatekeepers and compress mid-tier positioning. Hobbyist collectors in Japan exhibit lowest price sensitivity, while entertainment-oriented gift purchasers through Amazon represent the most elastic demand segment.
Supply Chain Analysis
REACH and CE marking qualification gates concentrate supply among Belgian, Spanish, and German printers with captive chemical documentation capabilities. Raw material dependencies center on FSC-certified wood pulp, cotton rag fiber, and water-based coating formulations. Single-source vulnerability runs through master lithography craftsmen in Spain's Basque Country facing generational knowledge transfer gaps. Distribution runs through direct-to-consumer Shopify storefronts and metaphysical retail networks, displacing traditional bookstore wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tarot cards market functions as a regulatory compounder where EU Green Deal packaging waste directives and California Proposition 65 enforcement are accelerating demand for certified sustainable production infrastructure.
For Market Incumbents: Cement compliance leadership by retrofitting coating chemistry laboratories for REACH bio-derived laminate certification and securing FSC pulp sourcing contracts ahead of Green Deal deadlines. Digital divination applications threaten tactile ritual engagement among casual users; counter through NFC-enabled hybrid deck development targeting Japanese collector segments. For New Entrants and Emerging Players: Begin with Portuguese-language deck development for Brazil's Candomblé and Umbanda practitioner communities, where ANVISA oversight remains lighter than European toy safety regimes. Crowdfunding validation through Backerkit pre-orders offers the most penetrable go-to-market angle for independent illustrators building algorithmic discovery on TikTok and Instagram. For Investors and Strategic Acquirers: Asymmetric upside sits with heritage lithography specialists possessing generational craft expertise and established CE marking documentation infrastructure. Long-term viability favors publishers with backward integration into coating chemistry and direct-to-reader subscription channels. Watch for inflection when extended producer responsibility laws in Germany and France trigger cardboard take-back program mandates.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Retrofit | Belgian and German printers capture contract manufacturing from Asian competitors lacking chemical documentation. |
| Crowdfunding Platform Launch | Independent artists validate aesthetic concepts through Kickstarter pre-orders before production commitment. |
| NFC-Enabled Hybrid Deck Development | Japanese collectors adopt augmented reality companion applications fastest, bridging physical and digital engagement. |
| Portuguese-Language Deck Localization | Brazilian spiritualist communities in São Paulo and Salvador represent underpenetrated demand for culturally adapted iconography. |
| Cardboard Take-Back Program Establishment | First-mover publishers secure advantage under Germany's packaging waste directives and France's anti-gaspillage regulations. |
Study Parameters
Direct dialogue with tarot publishers, independent illustrators, metaphysical retail buyers, and specialty printing facility managers grounded qualitative insights, cross-referenced against customs records, esoteric publishing catalogs, and crowdfunding platform disclosure data. Bottom-up and top-down triangulation validated volume estimates across product type, application, and distribution channel segments.
Bottom-up modeling projected unit economics across traditional, modern, art, and themed deck categories, while top-down analysis anchored aggregate market sizing to disclosed print run volumes and retail channel throughput. CAGRs derived from regression across algorithmic retail adoption curves, regulatory compliance cost trajectories, and spiritual practitioner community expansion patterns throughout the projection horizon.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to FDA indirect food-contact guidelines and unforeseen disruptions to FSC pulp certification availability. Deviation in REACH enforcement intensity or EU Green Deal timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Gaming Software Market
Gaming
Slot Machine Market
Gaming
Social Gaming Market
Gaming
Australia Casino Tourism Market
Gaming
Metaverse in Gaming Market
Gaming
Singapore Gaming Gadgets Market
Gaming
Traditional Casual Games Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
France Online Gambling Market
Gaming
VR Racing Gaming Market
Gaming
FPS Game Market
Gaming
Flat Gaming Monitors Market
Gaming
South Korea Virtual Reality Gaming Market
Gaming
Game API Market
Gaming
VR Gaming Console Market
Gaming
Australia Gaming Accessories Market