
 Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market | 2026-2036
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market Intelligence
Application development and co-design services are restructuring the value proposition beyond raw material supply, embedding suppliers earlier in the product design cycle. Teijin Limited specializes in carbon fiber-based thermoplastics for automotive applications, offering tailored solutions for structural parts. Solvay S.A. leverages its broad polymer portfolio to serve high-performance aerospace and industrial markets. Hexcel Corporation sustains its position through deep expertise in advanced composite technologies for primary and secondary aircraft structures.
Continuous Fiber Reinforced Thermoplastics are composite materials that combine a thermoplastic polymer matrix, such as polyamide or PEEK, with continuous reinforcing fibers like carbon or glass. These materials are produced via automated processes like tape laying, creating pre-impregnated forms prized for their high strength-to-weight ratio and recyclability. The aerospace application segment commands a significant value share due to its stringent performance and safety requirements. Polyamide-based composites represent a fast-growing product type, driven by adoption in automotive components where cost-performance balance is critical.
Regulations from bodies like the FAA in the United States and EASA in Europe mandate stringent material qualification for critical aerospace components. Concurrently, vehicle emissions standards under the EU Green Deal and China's dual carbon goals compel automotive OEMs to adopt lightweight materials. This incentivizes substitution of traditional metals. The key decision for suppliers involves balancing investment in aerospace-grade capacity against developing cost-effective solutions for mass-market automotive platforms.
Market Dynamics
The strategic decision for material suppliers is defined by the dual demand from aerospace for high-performance, certified materials and from the automotive sector for cost-effective, high-volume solutions. This bifurcation forces investment choices between specialized, low-rate production and scaled, automated manufacturing.
Growth Catalysts
- Vehicle Lightweighting Mandates:Regulations including the EU Green Deal and China's dual carbon goals compel automotive OEMs to use CFR-TPs to reduce vehicle weight and meet stringent emissions targets.
- Aerospace Modernization:The push for next-generation, fuel-efficient aircraft drives adoption in primary and secondary structures, with material selection governed by FAA and EASA airworthiness standards.
- Process Automation:Advances in automated tape laying and overmolding technologies are reducing cycle times and production costs, making CFR-TPs more economically viable for industrial equipment and sporting goods.
Market Restraints
- High Input Costs:The price of aerospace-grade carbon fiber and high-performance polymers like PEEK remains a primary barrier to entry for mass-market applications when compared to incumbent metals.
- Complex Qualification Cycles:Lengthy and capital-intensive material qualification processes, particularly under stringent FAA and EASA protocols for aerospace, significantly slow the introduction of new composite materials.
- Recycling Infrastructure Gaps:Despite the inherent recyclability of thermoplastics, the absence of a scaled, closed-loop infrastructure for composite waste limits the material's circular economy value proposition.
Strategic Opportunities
- Urban Air Mobility:The emerging UAM and drone delivery market creates a new application category for lightweight structural components, operating outside the long certification cycles of commercial aviation.
- Hydrogen Storage Vessels:Development of Type IV pressure vessels for hydrogen fuel cell vehicles presents a high-value opportunity for carbon fiber-reinforced thermoplastics due to their strength and gas impermeability.
- Medical Device Innovation:Radiolucency and biocompatibility open applications for CFR-TPs in surgical instruments and prosthetics, a segment governed by approvals from bodies like the FDA and EMA.
Industry Challenges
- Design Expertise Scarcity:A shortage of engineers skilled in composite design and finite element analysis for anisotropic materials acts as a bottleneck, hindering broader adoption by OEMs.
- Standardization Deficits:The lack of globally accepted standards for material testing protocols and data reporting complicates material equivalency and part qualification across different suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market |
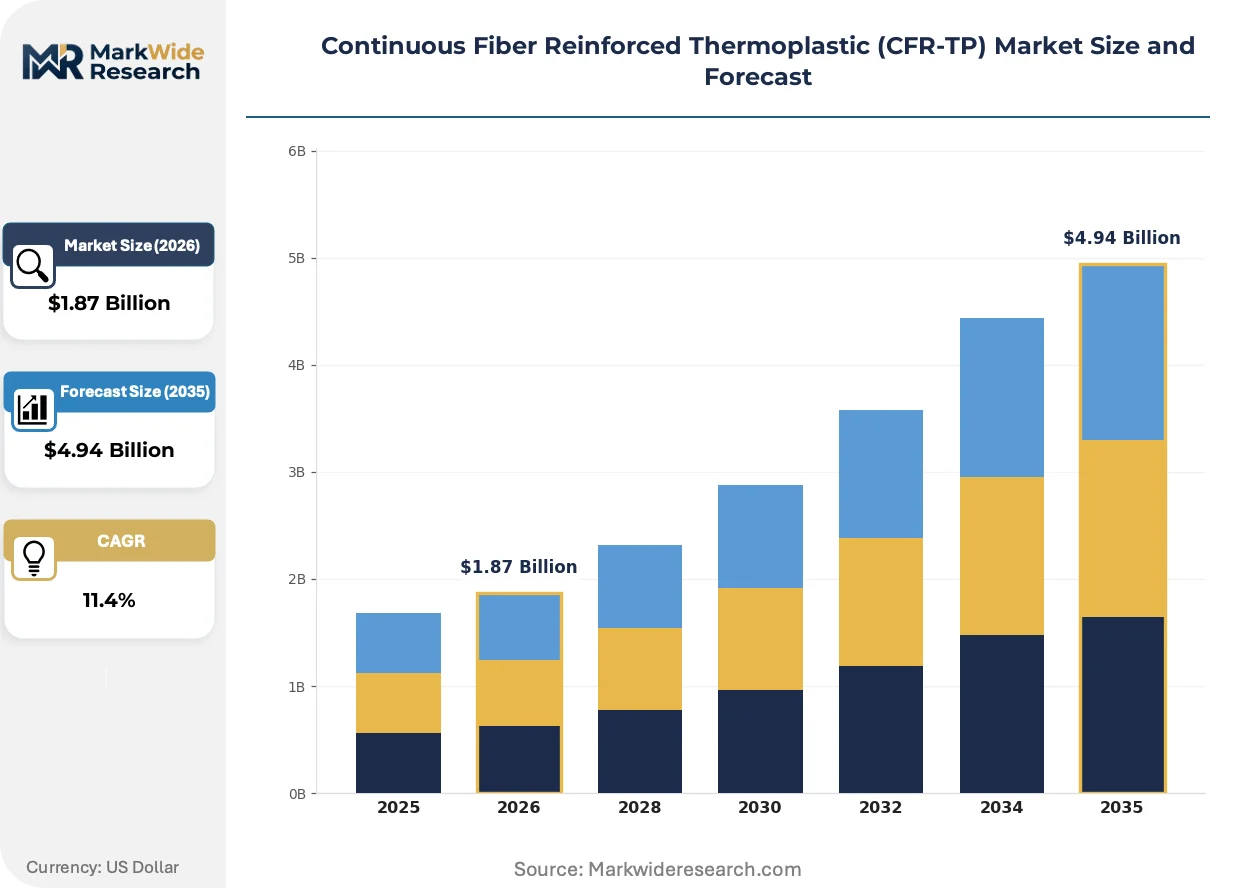
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $4.94 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyamide, Polypropylene, Polyethylene, Polycarbonate Application: Aerospace, Automotive Components, Industrial Equipment, Consumer Goods End User: Aerospace Manufacturers, Automotive OEMs, Construction Firms, Electronics Companies Technology: Injection Molding, Compression Molding, Extrusion, 3D Printing |
| Companies Covered | Hexcel Corporation, SGL Carbon SE, Teijin Limited, 3M Company, Gurit Holding AG, Toray Industries, Inc., Mitsubishi Chemical Group Corporation, Owens Corning, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market Strategic Shifts & Innovations
Integration of digital tools and process simulation is shifting the value proposition from pure material supply to holistic design and manufacturing intelligence. This change embeds material science earlier and more deeply into the product development lifecycle for complex components.
Digital twin technology provides a virtual replica of the composite manufacturing process, from fiber placement to final curing. Aerospace and high-end automotive manufacturers are adopting this to optimize production parameters and minimize physical trial-and-error prototyping. This simulation capability is converging with material science databases, enabling predictive modeling of final part performance before physical production begins.
Regulatory frameworks like the European Union's Corporate Sustainability Reporting Directive (CSRD) are creating new compliance demands. CSRD mandates detailed disclosure of environmental impacts, including material lifecycle analysis and end-of-life management. This affects CFR-TP suppliers serving the automotive sector, forcing them to validate and document the recyclability of their products.
Co-design partnerships are replacing conventional transactional procurement models for advanced materials. OEMs are embedding material specialists directly into their internal design teams from the initial concept phase, displacing the traditional siloed purchasing function. This collaborative approach is most visible within Germany's automotive industry, where complex part integration requires early-stage material expertise.
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market Segmentation
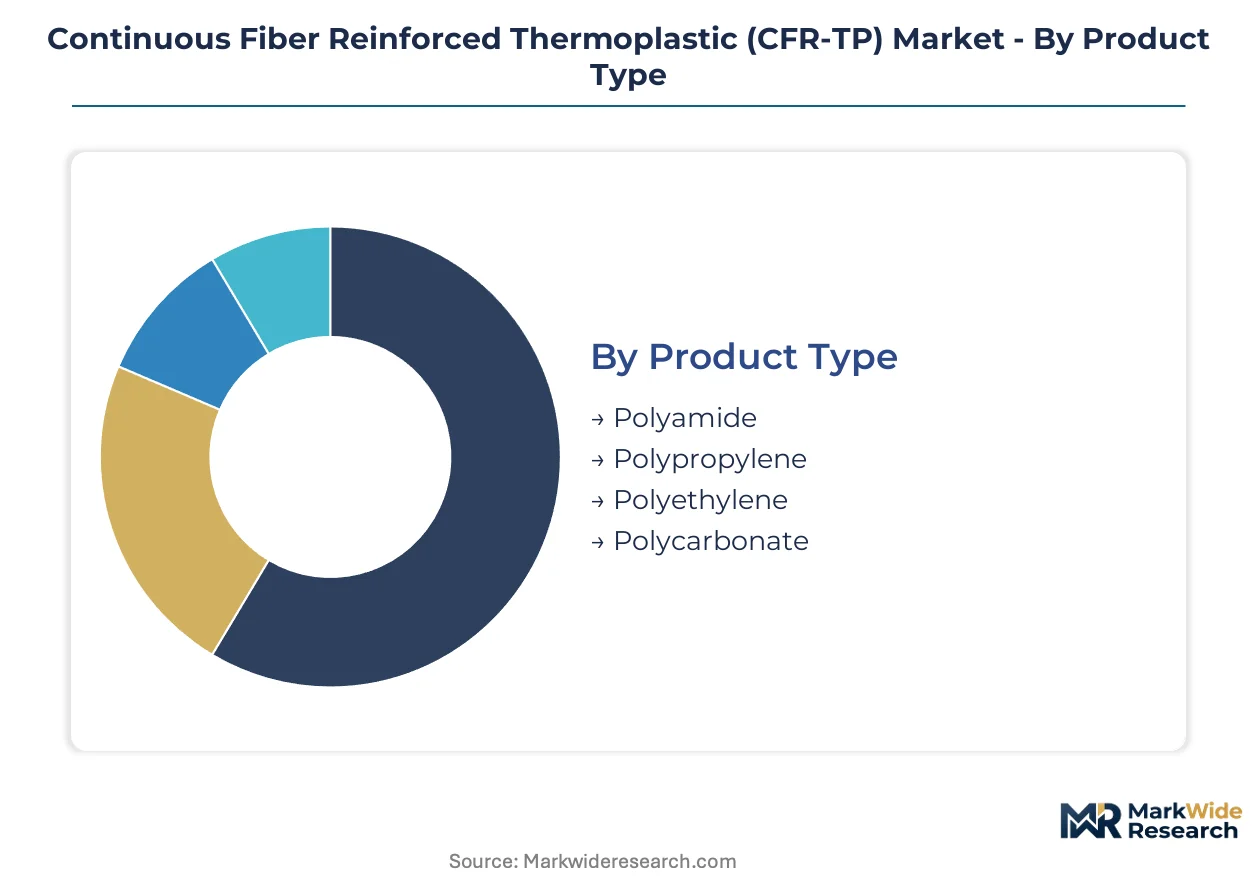
The Continuous Fiber Reinforced Thermoplastic (CFR-TP) market is segmented across product types, applications, end-users, and manufacturing technologies. Understanding these distinct segments reveals how material science innovations translate into tangible commercial value. Each category reflects varying performance demands and economic drivers across industries.
Product Type:
The selection of a CFR-TP product type often dictates the upgrade cycle for structural components, influencing material replacement timelines in critical applications. Manufacturers evaluate these material choices based on performance gains versus the cost of adopting new composite formulations. This assessment drives shifts from traditional materials to advanced thermoplastic composites.
- Polyamide:Polyamide-based CFR-TPs combine polyamide polymers with continuous fibers like glass or carbon, offering excellent impact resistance and chemical inertness. Demand concentrates in automotive components, driven by the need for lightweighting to meet stringent emissions regulations in Germany.
- Polycarbonate:Polycarbonate CFR-TPs utilize a tough, transparent thermoplastic matrix reinforced with continuous fibers, providing high strength and dimensional stability. High-performance industrial equipment and select aerospace interior parts drive demand, valuing its superior mechanical properties and thermal resistance.
- Polypropylene:Polypropylene CFR-TPs offer a cost-effective solution for semi-structural parts, finding use in consumer goods and non-critical automotive applications.
- Polyethylene:Polyethylene-based CFR-TPs provide good chemical resistance and low moisture absorption, primarily used in packaging and some sporting goods.
Polyamide sits at the top of the volume ranking due to its automotive adoption, with Polycarbonate climbing the fastest for specialized high-performance applications.
Application:
The intensity of performance requirements across various applications dictates the choice and specification of CFR-TPs, with each sector demanding unique material characteristics. Different end-use environments impose distinct stresses and regulatory hurdles on composite materials. This influences material selection and qualification processes.
- Aerospace:CFR-TPs in aerospace applications include primary and secondary structural components, interior elements, and engine parts, demanding high strength-to-weight ratios and fatigue resistance. Demand is concentrated among aircraft manufacturers in the United States and Europe, driven by FAA and EASA airworthiness standards for fuel-efficient designs.
- Automotive Components:CFR-TPs are used for automotive components such as chassis parts, battery enclosures, and body-in-white structures, providing significant weight reduction over metals. European automotive OEMs drive adoption to comply with EU Green Deal emissions targets, seeking cost-effective solutions for mass-market vehicle lightweighting.
- Industrial Equipment:CFR-TPs in industrial equipment enhance durability and reduce weight for machinery parts, robotics, and material handling systems.
- Consumer Goods:Consumer goods leverage CFR-TPs for sporting equipment, electronics casings, and durable luggage, valuing their lightweight strength and aesthetic versatility.
Demand is shifting towards high-performance applications in aerospace, while automotive components are continuously expanding their material substitution efforts.
End User:
The end-user segment defines distinct customer types, each with specific procurement processes, technical requirements, and supply chain expectations for CFR-TP materials. These varied customer profiles influence how suppliers structure their product offerings and technical support. Understanding end-user needs is crucial for market penetration.
- Aerospace Manufacturers:Aerospace manufacturers integrate CFR-TPs into aircraft structures, interiors, and engine components, requiring extensive material qualification and long-term supply agreements. Major aerospace OEMs in France and Germany drive demand, necessitating certified materials that meet stringent EASA safety and performance standards.
- Automotive OEMs:Automotive OEMs utilize CFR-TPs for structural and semi-structural parts in electric and internal combustion vehicles, focusing on high-volume production and cost efficiency. Chinese automotive companies are increasing adoption to meet dual carbon goals, driving investment in automated manufacturing processes for lightweighting solutions.
- Construction Firms:Construction firms use CFR-TPs for lightweight, corrosion-resistant rebar, structural reinforcements, and specialized facade elements in modern building projects.
- Electronics Companies:Electronics companies incorporate CFR-TPs into device housings, circuit board components, and structural frames, valuing their strength and electromagnetic transparency.
Strategic collaborations between material suppliers and Automotive OEMs are driving new product development, while Aerospace Manufacturers maintain their focus on certified, high-performance solutions.
Technology:
The maturity level of manufacturing technologies significantly impacts the cost-effectiveness and production scalability of CFR-TP components. Each processing method offers distinct advantages regarding part complexity, production volume, and material waste generation. This technological landscape shapes market accessibility and innovation.
- Injection Molding:Injection molding processes CFR-TP pellets into complex shapes, often integrating continuous fiber inserts, enabling high-volume production of intricate parts. Automotive and industrial equipment sectors drive adoption, valuing its ability to produce high-strength components efficiently at scale.
- 3D Printing:3D printing with CFR-TPs involves additive manufacturing of composite filaments, allowing for highly complex geometries and rapid prototyping of functional parts. Emerging urban air mobility (UAM) and medical device sectors drive innovation, leveraging its design freedom for customized, lightweight structures.
- Compression Molding:Compression molding uses pre-consolidated CFR-TP sheets to produce larger, flatter components with excellent surface finish, common in aerospace and automotive.
- Extrusion:Extrusion processes CFR-TPs into continuous profiles like rods, tubes, and sheets, serving applications in construction and industrial infrastructure.
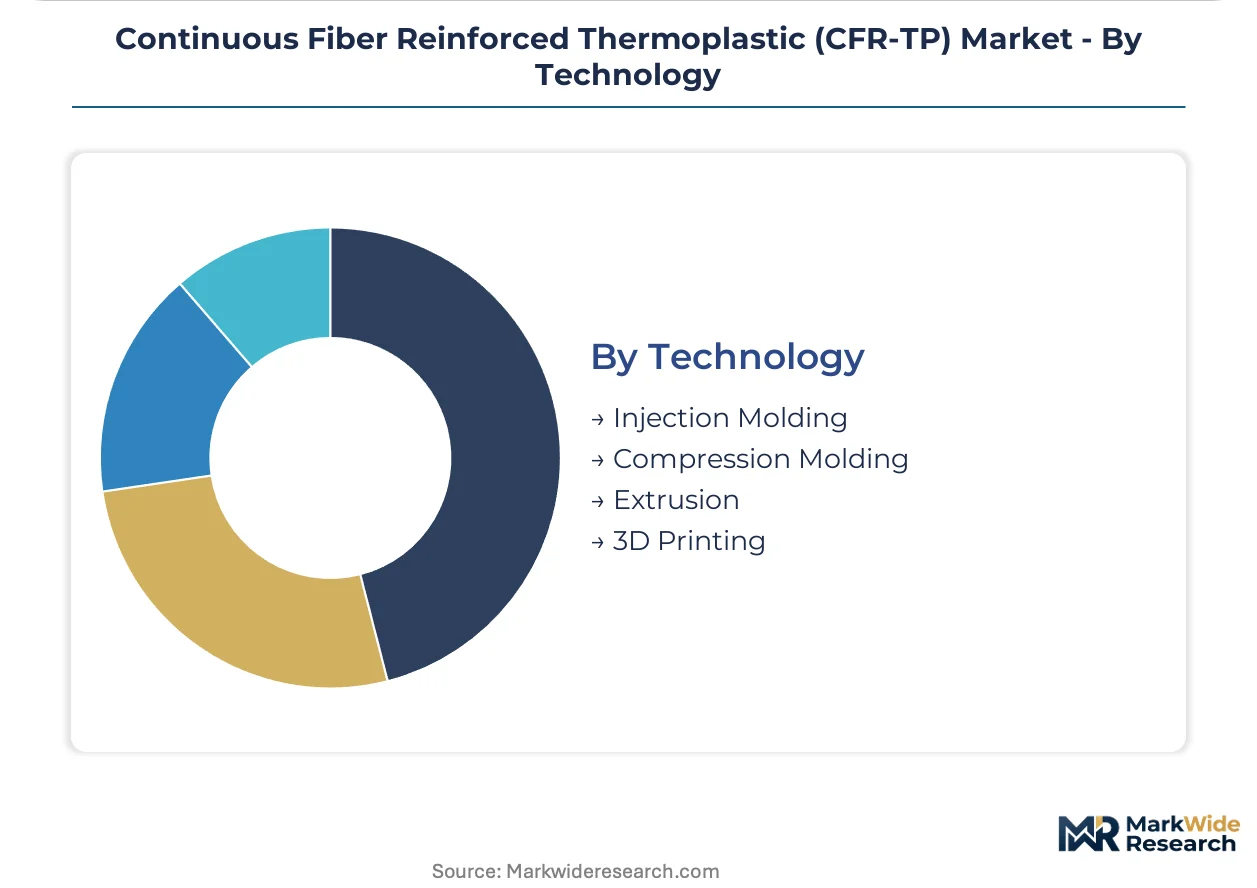
Innovation in 3D Printing is enabling new designs and rapid prototyping, while Injection Molding remains critical for high-volume, cost-efficient CFR-TP component manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive sector drives significant CFR-TP demand, while the United States focuses on high-performance aerospace applications. This bifurcation reflects differing industrial priorities and regulatory landscapes across major economies. Regional demand profiles influence material supplier investment strategies and product development roadmaps.
Germany
Automotive lightweighting initiatives and industrial equipment upgrades propel CFR-TP adoption in Germany. The EU Green Deal's stringent emissions targets compel vehicle manufacturers to integrate these advanced materials. Major automotive clusters in Bavaria and Baden-Württemberg are centers for co-design partnerships and material substitution efforts.
United States
Aerospace modernization programs and defense spending drive strong demand for CFR-TPs in the United States. FAA airworthiness standards mandate rigorous material qualification for critical aircraft components. Key aerospace manufacturing hubs in Washington State and Southern California concentrate expertise in advanced composite structures.
China
Electric vehicle battery enclosures and high-speed rail components are significant demand drivers for CFR-TPs in China. The country's dual carbon goals incentivize material innovation for lightweighting across industrial sectors. Automotive and industrial manufacturing zones in the Yangtze River Delta are seeing increased investment in automated CFR-TP production.
France
Aerospace manufacturing, particularly for commercial aircraft and defense platforms, underpins CFR-TP consumption in France. EASA certification processes guide the selection and deployment of high-performance composite materials. Toulouse, a major aerospace center, focuses on integrating advanced thermoplastics into next-generation aircraft designs.
Japan
Advanced industrial machinery and niche automotive applications contribute to CFR-TP demand in Japan. METI initiatives support research and development into sustainable materials and manufacturing processes. The Chubu region, known for its automotive and robotics industries, explores new applications for polyamide-based composites.
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting the varied requirements of aerospace versus automotive. The market structure remains somewhat fragmented, with a few large integrated players alongside numerous niche material formulators. Strategic partnerships and capacity expansion are dominant competitive moves among market participants.
Specialists in advanced composite materials, like Hexcel Corporation, exemplify the high-performance end, focusing on aerospace and defense applications requiring extensive certification. Teijin Limited represents a key player leveraging carbon fiber expertise for tailored automotive solutions and industrial applications. Solvay S.A. occupies a position across diverse markets, providing a broad polymer portfolio that enables high-performance solutions for both aerospace and industrial sectors.
| Leading Market Players |
|---|
| Hexcel Corporation |
| SGL Carbon SE |
| Teijin Limited |
| 3M Company |
| Gurit Holding AG |
| Toray Industries, Inc. |
| Mitsubishi Chemical Group Corporation |
| Owens Corning |
| Solvay S.A. |
| Others |
Cost & Logistics Intelligence
Automated tape laying and overmolding technologies are reducing production costs, which simultaneously reshapes cost economics and influences supplier investment in scaled manufacturing. This shift impacts pricing power and the concentration of supply within key regions.
Pricing Analysis
Capacity additions in China are reshaping price floors for high-volume automotive applications. Pricing operates on a contract-based long-term offtake model for aerospace, while per-unit transactional pricing dominates the automotive sector. Price differentiation stems from certification level, such as FAA or EASA approval, volume scale, and customization requirements. Cost compression in automotive components intensifies due to lightweighting mandates and fierce competition among suppliers. Aerospace manufacturers prioritize performance and qualification, making them less price-sensitive than automotive OEMs.
Supply Chain Analysis
Rigorous certification processes for aerospace components act as a significant gating factor for new material suppliers. The supply chain draws heavily on raw materials like aerospace-grade carbon fiber and high-performance polymers such as PEEK and polyamide. Geographic supply concentration includes Germany for advanced automotive applications, the United States for high-performance aerospace, and China for scaled automotive and industrial production. High input costs for specialized fibers present a structural risk. Distribution typically runs through direct supply to OEMs, often involving co-design partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Continuous Fiber Reinforced Thermoplastic market offers margin expansion potential, driven by process automation reducing production costs for industrial and automotive applications.
For Market Incumbents:Deploy targeted R&D in cost-effective formulations for mass-market automotive platforms. Invest in capacity expansion in China to meet dual carbon goals and secure market share. Counter emerging material substitution threats by offering integrated design services. Accelerate material qualification processes for new composite grades to maintain aerospace leadership.
For New Entrants and Emerging Players:3D printing capabilities offer a technology-first wedge into urban air mobility (UAM) and medical device sectors. Target niche applications requiring customized, lightweight structures with rapid prototyping. Focus on design freedom and shorter certification cycles outside traditional aerospace pathways. Leverage digital twin technology to optimize production parameters and minimize trial-and-error.
For Investors and Strategic Acquirers:Valuations sit cheapest among specialized material formulators with strong intellectual property in thermoplastic matrices. Long-term viability favors players with dual-market strategies serving both aerospace and automotive. Watch for increased M&A activity in automated manufacturing technology providers. Investment in recycling infrastructure solutions signals a commitment to circular economy principles.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Secures market share for cost-effective automotive solutions in China. |
| Co-design Service Development | Embeds suppliers earlier in OEM product development cycles. |
| Advanced Automation Investment | Reduces cycle times and production costs across industrial applications. |
| Certification Pathway Acceleration | Shortens material qualification for new aerospace-grade composites. |
| Recycling Infrastructure Partnership | Addresses circular economy demands from EU Green Deal regulations. |
Research Approach
Multiple input streams — primary interviews, secondary research, and market intelligence reports — were reconciled for data collection. Stakeholders included R&D directors, procurement leads, and application engineers from aerospace and automotive OEMs. Public filings, regulatory documents from FAA and EASA, and industry association reports provided secondary validation. Bottom-up and top-down triangulation ensured data integrity.
Data-stream reconciliation integrated historical trends with projected material science advancements across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and manufacturing technology, alongside regional regulatory impacts. CAGRs were derived using a multi-variable regression model, factoring in vehicle production forecasts and aerospace fleet modernization cycles.
The model holds under current regulatory frameworks and projected raw material price stability; deviation in carbon fiber supply or new emissions standards would shift market dynamics. Forecasts reflect documented assumptions regarding technological adoption rates. Geopolitical events impacting supply chains or trade policies could also alter the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Carbon Fiber Filament Market
Fibers
Drug Integrated Polymer Fibers Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Fiberglass Cloth Market
Fibers
Global Electronic Fiberglass Market
Fibers
Bioglass Fiber Market
Fibers
Global Concrete Fiber Market
Fibers
Global Metal Fiber Market
Fibers
Global R-Glass Fiber Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
Global Nylon Monofilament Market
Fibers
Global Fiber Reinforced Composites Market
Fibers
Polytetrahydrofuran Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Global Bicomponent Fiber Market
Fibers
Microfibrillated Cellulose (MFC) Market