
 Short Fiber Thermoplastics Market | 2026-2036
Short Fiber Thermoplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Short Fiber Thermoplastics Market Outlook
Automotive interiors is expanding as the dominant end-use vertical for short fiber thermoplastics as OEMs pursue mass reduction without sacrificing structural integrity. BASF SE leverages its integrated polyamide compounding network to supply reinforced grades directly to European tier-1 seating and dashboard manufacturers. LANXESS anchors its position through high-heat polyamide formulations engineered for under-hood applications that migrate into cabin structural elements. SABIC competes across the value chain with specialty polypropylene compounds optimized for thin-wall injection molding in interior panels.
Short fiber thermoplastics are polymer matrices—typically polypropylene, polyamide, or polycarbonate—reinforced with chopped glass or carbon fibers measuring 0.2 to 0.5 millimeters in length, compounded via twin-screw extrusion and processed primarily through injection molding to achieve strength-to-weight ratios superior to unreinforced resins. Polyamide grades dominate where thermal resistance and mechanical load-bearing capacity are paramount, particularly in powertrain-adjacent automotive modules. Polypropylene compounds represent the fastest-expanding product category as cost-sensitive consumer goods and interior automotive applications drive volume procurement from tier-1 suppliers. Injection molding technology leads processing-method selection due to its cycle-time efficiency and dimensional repeatability for complex geometries.
The EPA tailpipe-emission standards and the EU F-Gas Regulation shape material-selection criteria by compelling automakers to document lifecycle carbon impact and eliminate high-global-warming-potential processing aids. NHTSA fuel-economy mandates in the United States reinforce this trajectory by assigning compliance credit to verified weight reduction. OEMs and compounders must monitor how REACH chemical restrictions and evolving automotive-recycling directives in Europe alter fiber-surface treatment chemistries and post-consumer recyclate incorporation specifications.
Market Dynamics
Automotive OEMs face structural pressure to cut vehicle weight while maintaining crashworthiness, forcing compounders to balance fiber loading rates against injection-molding cycle times. This tension between material performance and processing economics now governs procurement negotiations across tier-1 seating, dashboard, and structural component suppliers.
Growth Catalysts
- EU Green Deal vehicle-emission frameworks:Mandates for fleet-wide CO2 reduction push German and French automakers toward glass-fiber polyamide for hood-inners and seat pans, creating specification pull through the supply chain.
- Powertrain electrification:Battery enclosure manufacturers specify short-fiber polycarbonate blends for thermal runaway containment, opening volume applications beyond traditional combustion-engine architectures.
- Injection-molding automation:Robot-assisted handling systems in Detroit and Stuttgart enable thinner-wall designs that reduce per-part resin consumption without sacrificing dimensional stability.
Market Restraints
- Glass fiber supply concentration:Chopped strand roving production clusters in China create input cost volatility for European compounders lacking backward integration into fiber manufacturing.
- REACH chemical restrictions:ECHA scrutiny of silane coupling agents forces reformulation of fiber surface treatments, extending qualification timelines for new compound grades.
- Metal substitution ceiling:High-load structural members in chassis and suspension systems retain steel or aluminum where fiber-reinforced plastics cannot meet fatigue-life requirements.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for domestic manufacturing position Mumbai-Pune corridor suppliers to capture interior panel contracts from expanding Korean and Japanese OEM operations.
- Recyclate incorporation mandates:Draft EU automotive-recycling directives create first-mover advantage for compounders mastering post-industrial glass-fiber recompounding without mechanical degradation.
- Hybrid carbon-glass systems:Convergence of chopped carbon fiber cost reduction with existing glass-fiber compounding infrastructure enables conductivity and EMI shielding in electric vehicle battery modules.
Industry Challenges
- Mold-flow simulation expertise:Shortage of engineers trained in fiber orientation prediction software slows tool design for complex geometries, particularly among mid-tier injection molders in Eastern Europe.
- UL certification timelines:Flammability testing for automotive interior applications requires 18-24 month validation cycles that mismatch annual model-year refresh schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short Fiber Thermoplastics Market |
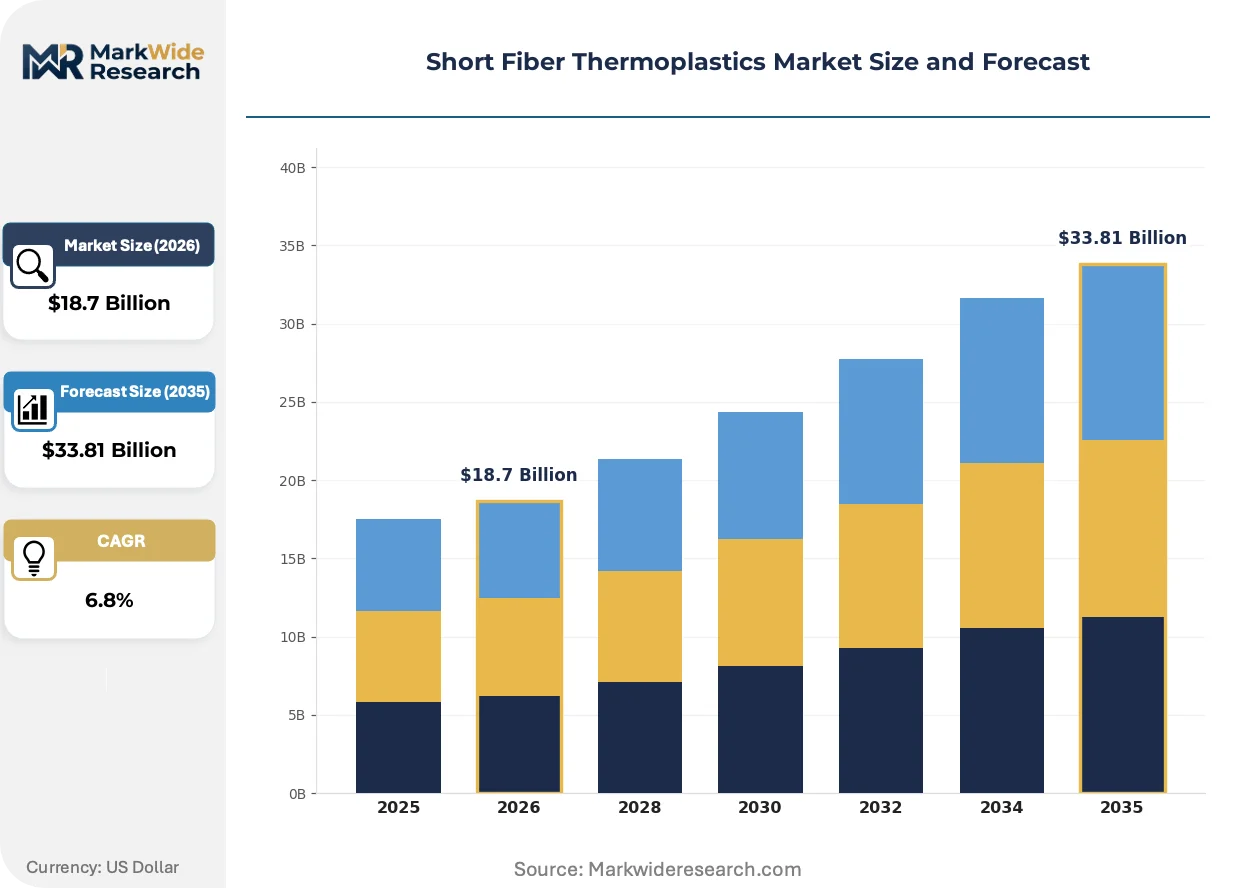
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyamide, Polycarbonate, Polyethylene Application: Aerospace, Automotive Interiors, Consumer Goods, Electronics End User: Manufacturers, OEMs, Tier-1 Suppliers, Distributors Technology: Injection Molding, Compression Molding, Thermoforming, Extrusion |
| Companies Covered | BASF SE, LANXESS, Toray Industries Inc, Avient Corporation, Solvay, SABIC, DSM N.V., DuPont de Nemours Inc, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short Fiber Thermoplastics Market Strategic Shifts
Material-process integration now determines competitive position more than standalone resin innovation. Compounders and molders are co-developing grade specifications that anticipate end-of-life recycling requirements rather than retrofitting compliance.
Long-fiber-reinforced thermoplastic pellet technology is consolidating upstream as compounders integrate pultrusion lines directly with twin-screw extrusion to control fiber length distribution. Automotive structural module suppliers in Germany and the United States are qualifying these grades for front-end carriers and instrument panel supports. The technology is consolidating supplier tiers by enabling direct-to-OEM contracts that bypass traditional distributor networks.
EPA tailpipe-emission standards and NHTSA fuel-economy mandates now require documented lifecycle carbon accounting for material substitutions. Automakers must verify that lightweighting benefits outweigh resin production emissions, shifting procurement weight toward suppliers with certified renewable electricity and closed-loop water systems. Powertrain-adjacent applications in Michigan and California face the most stringent documentation requirements, driving tier-1 suppliers to demand supply-chain transparency from compounders.
Direct material specification by OEM engineering teams is displacing traditional distributor-mediated procurement for high-volume interior programs. Tier-1 seating manufacturers in Stuttgart and Shanghai now negotiate compound formulations directly with BASF and LANXESS technical service groups, compressing the role of regional resin distributors to logistics-only functions. This pattern is most visible in dashboard and door panel contracts where design freedom and color matching require iterative collaboration between OEM studios and compounder laboratories.
Short Fiber Thermoplastics Market Segmentation
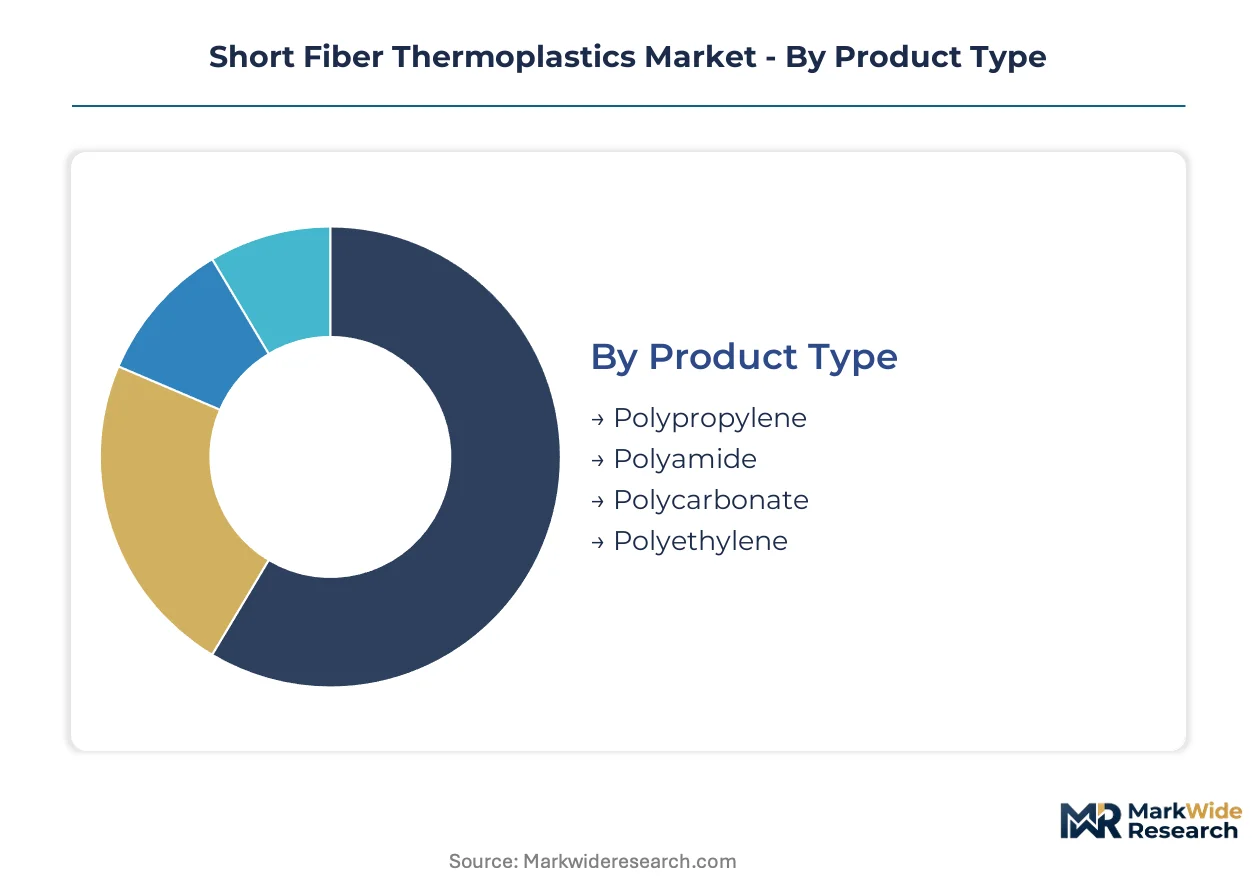
Segmentation in short fiber thermoplastics reveals how material selection diverges across performance requirements and processing economics. Compounders configure fiber loading, matrix chemistry, and additive packages differently for each product tier and end-use vertical.
Product Type:
Volume production concentrates in commodity polypropylene grades, while premium formulations command structural applications demanding thermal resistance.
- Polypropylene:Chopped glass fiber loadings of 10-40% by weight deliver cost-effective stiffness for non-structural automotive panels and appliance housings. Tier-1 suppliers in Michigan and Guangdong procure these compounds in multi-thousand-ton volumes for dashboard substrates and door trim.
- Polyamide:Glass-fiber reinforced grades withstand continuous-use temperatures above 150°C, qualifying them for powertrain-adjacent modules and under-hood components. German automakers specify PA6 and PA66 compounds for engine covers and cooling system housings.
- Polycarbonate:Flame-retardant formulations serve electronics enclosures and battery module housings where transparency or ignition resistance is required.
- Polyethylene:Lower-density compounds fill cost-sensitive consumer goods and packaging applications with minimal structural load requirements.
Mature deployment sits with polypropylene. Newer deployment is concentrated in polycarbonate blends for electrification applications.
Application:
Automotive programs absorb the majority of qualified compound volumes, while aerospace qualification timelines restrict supplier participation.
- Automotive Interiors:Seat frames, instrument panels, and door modules specify glass-fiber polyamide to cut mass versus stamped metal. Stuttgart-based OEM studios approve color-matched compounds directly with BASF and LANXESS technical groups.
- Consumer Goods:Power tool housings and appliance chassis drive polypropylene consumption through distributor networks serving Asian contract manufacturers.
- Electronics:Laptop frames and server chassis require EMI-shielding grades with conductive filler packages.
- Aerospace:Cabin interior components face stringent smoke-toxicity certifications that limit qualified compound sources to specialty suppliers.
Procurement concentration is deepest in automotive interiors. Specification activity is climbing fastest in electronics.
End User:
Direct OEM engagement is displacing traditional distributor mediation for high-volume programs requiring iterative formulation development.
- Tier-1 Suppliers:Seating and dashboard manufacturers in Detroit and Shanghai negotiate compound specifications directly with resin producers, compressing distributor roles to logistics.
- OEMs:Engineering teams at German and Japanese automakers now specify resin grades for structural modules, bypassing tier-1 material selection.
- Manufacturers:Appliance and tool producers source through regional distributors with limited technical service requirements.
- Distributors:Inventory-holding intermediaries retain relevance in fragmented markets with small lot sizes and generic grade requirements.
Backward integration is most advanced among tier-1 suppliers. Distributor influence is eroding fastest in automotive verticals.
Technology:
Cycle time efficiency and dimensional repeatability determine processing method selection across production scale tiers.
- Injection Molding:Robot-assisted cells enable thin-wall designs with 30-50 second cycle times, dominating automotive interior panel production.
- Compression Molding:Longer fiber retention suits structural semi-structural components where impact resistance outweighs surface finish requirements.
- Thermoforming:Sheet-based processing serves aircraft interior panels and mass transit seating with lower tooling investment than injection molds.
- Extrusion:Profile production lines supply construction and industrial applications with continuous geometries.
Process maturity is highest in injection molding. Adoption momentum is shifting toward compression molding for hybrid electric vehicle battery enclosures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany, China, and the United States where compounders operate integrated polyamide and polypropylene compounding networks. Consumption patterns diverge as automotive OEMs in Stuttgart and Shanghai drive specification pull while North American demand centers on fuel-economy compliance.
Germany
Stuttgart-based OEM studios specify glass-fiber polyamide grades directly with compounder technical groups for seat frames and dashboard substrates. EU Green Deal vehicle-emission frameworks mandate fleet-wide CO2 reduction, accelerating metal substitution in hood-inners and structural modules. The Baden-Württemberg supplier cluster anchors European compounding capacity with twin-screw extrusion lines serving tier-1 seating manufacturers.
China
Guangdong and Shanghai injection molders procure multi-thousand-ton volumes of reinforced polypropylene for interior panels and door trim modules. MIIT fuel-consumption standards for passenger vehicles push domestic automakers toward lightweight material architectures. The Yangtze River Delta hosts the densest concentration of glass-fiber roving production, though supply concentration creates input cost volatility for non-integrated compounders.
United States
Michigan-based tier-1 suppliers negotiate compound specifications for instrument panel supports and center console structures under NHTSA fuel-economy mandates. EPA tailpipe-emission standards require documented lifecycle carbon accounting for material substitutions, shifting procurement toward suppliers with certified renewable electricity. Detroit-area robot-assisted molding cells enable thin-wall designs that reduce per-part resin consumption.
Japan
Osaka and Nagoya automotive engineering teams qualify short-fiber polycarbonate blends for battery module housings as powertrain electrification accelerates. METI carbon-neutrality roadmaps for the automotive sector shape material-selection criteria across the supply chain. Kanto-based compounders specialize in high-heat polyamide formulations for powertrain-adjacent applications migrating into cabin structural elements.
India
Mumbai-Pune corridor suppliers position to capture interior panel contracts from expanding Korean and Japanese OEM operations. PLI scheme incentives for domestic manufacturing reduce import dependence for reinforced thermoplastic compounds. Maharashtra-based injection molders invest in qualification programs for glass-fiber polyamide grades serving emerging electric vehicle programs.
Short Fiber Thermoplastics Market Competitive Environment
Top-tier vendors anchor integrated resin compounding, while regional specialists occupy formulation niches and distributor-dependent segments. The vendor base stratifies across three tiers: multinational chemical conglomerates with backward integration into fiber and resin production; mid-scale compounders with technical service capabilities; and logistics-focused distributors handling commodity grades. Strategic archetypes include integrated resin-fiber producers, application-specific formulators, and automation-enabled molders. Competitive moves center on direct OEM specification partnerships and qualification of post-industrial recyclate grades.
Among European integrated producers, BASF SE and LANXESS occupy positions exemplifying the technical service archetype, with Stuttgart-based OEM studios negotiating formulations directly with their compounding networks. SABIC represents the scale-driven multinational segment with specialty polypropylene compounds optimized for thin-wall injection molding. These three names anchor the competitive structure without exhaustively mapping participant strategies.
| Leading Market Players |
|---|
| BASF SE |
| LANXESS |
| Toray Industries Inc |
| Avient Corporation |
| Solvay |
| SABIC |
| DSM N.V. |
| DuPont de Nemours Inc |
| Celanese Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive glass-fiber roving production in China anchors both supply security and pricing leverage for integrated compounders serving automotive tier-1 suppliers. European and North American compounders lacking backward integration into fiber manufacturing absorb input cost volatility while competing against Asian producers with Yangtze River Delta feedstock advantages.
Pricing Analysis
Short lead-time premiums for just-in-time automotive programs command pricing spreads over standard contract terms, while spot inventory discounts clear excess polypropylene compound volumes during model-year transitions. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified automotive grades from uncertified industrial formulations and generic distributor-held stock. Cost compression in commodity polypropylene is intensifying because Guangdong injection molders consolidate procurement volumes. Tier-1 seating manufacturers exhibit lowest price sensitivity due to specification lock-in, while appliance producers through regional distributors show highest sensitivity to resin index movements.
Supply Chain Analysis
Workforce availability constraints in Stuttgart and Detroit limit expansion of robot-assisted molding cells despite demand pull from OEM lightweighting programs. Chopped strand roving production concentrates in China, Germany, and the United States, while polyamide resin supply draws from Belgian and US Gulf Coast petrochemical complexes. Single-source vulnerability sits with silane coupling agent suppliers facing ECHA scrutiny under REACH chemical restrictions. Distribution runs through compounder-direct contracts for automotive programs and regional resin distributors for fragmented consumer goods applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The short fiber thermoplastics market sits in a polymer-matrix transition phase as long-fiber-reinforced thermoplastic pellet technology displaces legacy short-fiber grades in structural automotive applications.
For Market Incumbents: Acquire pultrusion line assets to integrate long-fiber pellet production with existing twin-screw extrusion capacity. Lock in direct OEM specification partnerships for battery enclosure modules before qualification timelines solidify. Counter emerging entrant compounders from India by securing renewable electricity certifications for European compounding networks. For New Entrants and Emerging Players: Enter via post-industrial glass-fiber recompounding capabilities to capture EU automotive-recycling directive premiums before incumbents master mechanical property retention in recyclate grades. Target Mumbai-Pune corridor interior panel contracts where PLI scheme incentives reduce import dependence. Lead with technical service capabilities that bypass distributor mediation for Korean and Japanese OEM localization programs. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational chemical conglomerates seeking automotive specification relationships. Five-to-ten-year viability hinges on qualification for electric vehicle battery module housings as powertrain electrification accelerates. Signal to watch: direct material specification by OEM engineering teams displacing tier-1 procurement authority in dashboard and structural module contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Production | Yangtze River Delta roving capacity secures input cost stability for Guangdong compounders. |
| Long-Fiber Pellet Qualification | German automotive structural module suppliers bypass traditional distributor networks with direct OEM contracts. |
| Recyclate Incorporation Mandate Compliance | First-mover compounders capture EU automotive-recycling directive specifications before mechanical degradation barriers resolve. |
| Direct OEM Technical Partnership | Stuttgart-based studios negotiate color-matched formulations with BASF and LANXESS laboratories. |
| Robot-Assisted Molding Cell Deployment | Detroit-area thin-wall designs reduce per-part resin consumption under NHTSA fuel-economy mandates. |
Study Parameters
Trade databases, automotive production registries, and chemical industry association filings formed the secondary backbone of this analysis. Primary interviews with tier-1 supplier procurement directors, OEM platform engineers, compounder technical service managers, and injection molding plant operators cross-validated volume assumptions. Bottom-up triangulation against top-down resin consumption estimates anchored segmentation splits across polypropylene, polyamide, polycarbonate, and polyethylene grades.
Bottom-up modeling of injection-molding cell capacity and compression-molding line utilization across the projection horizon generated volume baselines. Segmentation dimensions span matrix chemistry, fiber loading rate, end-use vertical, processing technology, and regional production cluster. CAGRs were derived from fitted growth curves calibrated to OEM lightweighting program announcements and regulatory compliance timelines. Forecast inputs incorporate MIIT fuel-consumption standards, EPA tailpipe-emission documentation requirements, and EU Green Deal fleet CO2 mandates.
Revisions become necessary when ECHA expands REACH chemical restrictions to additional silane coupling agents or when battery enclosure material specifications shift to ceramic-composite alternatives. Forecasts reflect assumptions about automotive production volumes, fiber roving supply stability, and qualification timeline continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Global Concrete Fiber Market
Fibers
Bleached Linter Cellulose Market
Fibers
Renewable Carbon Fibers Market
Fibers
Global Fiberglass Mold Market
Fibers
Thermoformed Fiber Market
Fibers
High Performance Fibers for Defense Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Vinylon Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
Viscose Staple Fiber Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Global Nylon Monofilament Market
Fibers
Global R-Glass Fiber Market
Fibers
Artificial Muscle Fibers Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market