
 Global Glass Fiber Reinforced Gypsum (GFRG) Market | 2026-2036
Global Glass Fiber Reinforced Gypsum (GFRG) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glass Fiber Reinforced Gypsum (GFRG) Market Foresight
The EU Green Deal is recalibrating material specifications across European commercial construction, pushing developers toward low-carbon interior systems. Saint-Gobain leverages its integrated gypsum-fiber manufacturing network to supply certified GFRG assemblies across France and Germany. Knauf Danoline A/S anchors the Nordic market with specialized acoustic panel formulations that meet stringent indoor air quality standards. USG Corporation competes on scale, operating high-volume production lines that serve North American institutional builders with standardized fire-rated ceiling systems.
Glass Fiber Reinforced Gypsum combines alpha gypsum plaster with alkali-resistant glass fiber reinforcement, typically achieving flexural strengths of 15-25 MPa and densities between 1,100-1,400 kg/m³ for molded architectural elements. The material serves primarily as a lightweight, non-combustible substrate for ornate interior ceilings, column covers, and performance-rated wall assemblies in commercial and institutional buildings. Panel and board configurations dominate current volume, with facade and fireproofing applications representing the fastest-expanding demand pools as code-driven fire resistance ratings tighten. Ceiling systems remain the most mature segment, while acoustic-grade GFRG tiles command premium positioning in performing arts and healthcare construction.
The EPA regulates volatile organic compound emissions from gypsum-based products under TSCA Title VI, while REACH compliance governs chemical safety for GFRG entering European markets. China's GB standards and MEE enforcement on industrial emissions shape domestic manufacturing constraints and export eligibility. India's BIS certification requirements for non-load-bearing wall panels create formal market access thresholds that foreign suppliers must satisfy. Stakeholders should monitor evolving carbon border adjustments and embodied-carbon disclosure mandates that will soon differentiate competitive positioning across major supply corridors.
Market Dynamics
Building energy codes and embodied-carbon disclosure mandates are recalibrating material specifications across commercial construction, compressing specification cycles for interior systems and rewarding suppliers with verified environmental product declarations.
Growth Catalysts
- EU Green Deal implementation:France and Germany now mandate lifecycle carbon assessments for public buildings, accelerating specification of low-carbon GFRG ceiling assemblies in institutional projects.
- Healthcare construction standards:Acoustic-grade GFRG tiles meet stringent infection-control and sound-attenuation requirements in hospital atriums and surgical suites across the United States.
- Alpha gypsum formulation advances:Improved fiber dispersion techniques boost flexural strength to 25 MPa, enabling thinner, lighter column covers in high-rise commercial cores.
Market Restraints
- Petroleum-derived additive costs:Resin modifiers and retarders in GFRG production face volatile pricing tied to crude oil benchmarks, compressing margin stability for molded element manufacturers.
- China supply concentration:Raw glass fiber roving production clusters in Shandong and Zhejiang provinces, exposing downstream fabricators to regional emissions enforcement shutdowns under MEE directives.
- Cross-laminated timber substitution:Mass timber wall and ceiling systems compete for aesthetic interior specifications in Scandinavian and Pacific Northwest commercial projects.
Strategic Opportunities
- India BIS certification pathway:Foreign GFRG suppliers meeting Bureau of Indian Standards for non-load-bearing panels unlock access to metro rail and airport terminal construction in Mumbai and Delhi.
- Facade fireproofing applications:Code-driven fire resistance rating upgrades for high-rise exterior assemblies create demand for GFRG cladding substrates in Dubai and Singapore.
- Digital fabrication convergence:Robotic milling of GFRG molds combined with parametric design software compresses custom architectural element lead times for performing arts venues.
Industry Challenges
- Skilled mold-making labor scarcity:Traditional plaster casting craftsmanship is retiring faster than CAD-CAM training programs replenish qualified pattern makers for ornamental GFRG production.
- EPD verification timelines:Third-party lifecycle assessment documentation for environmental product declarations delays specification approval by 8-14 months on LEED Platinum projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glass Fiber Reinforced Gypsum (GFRG) Market |
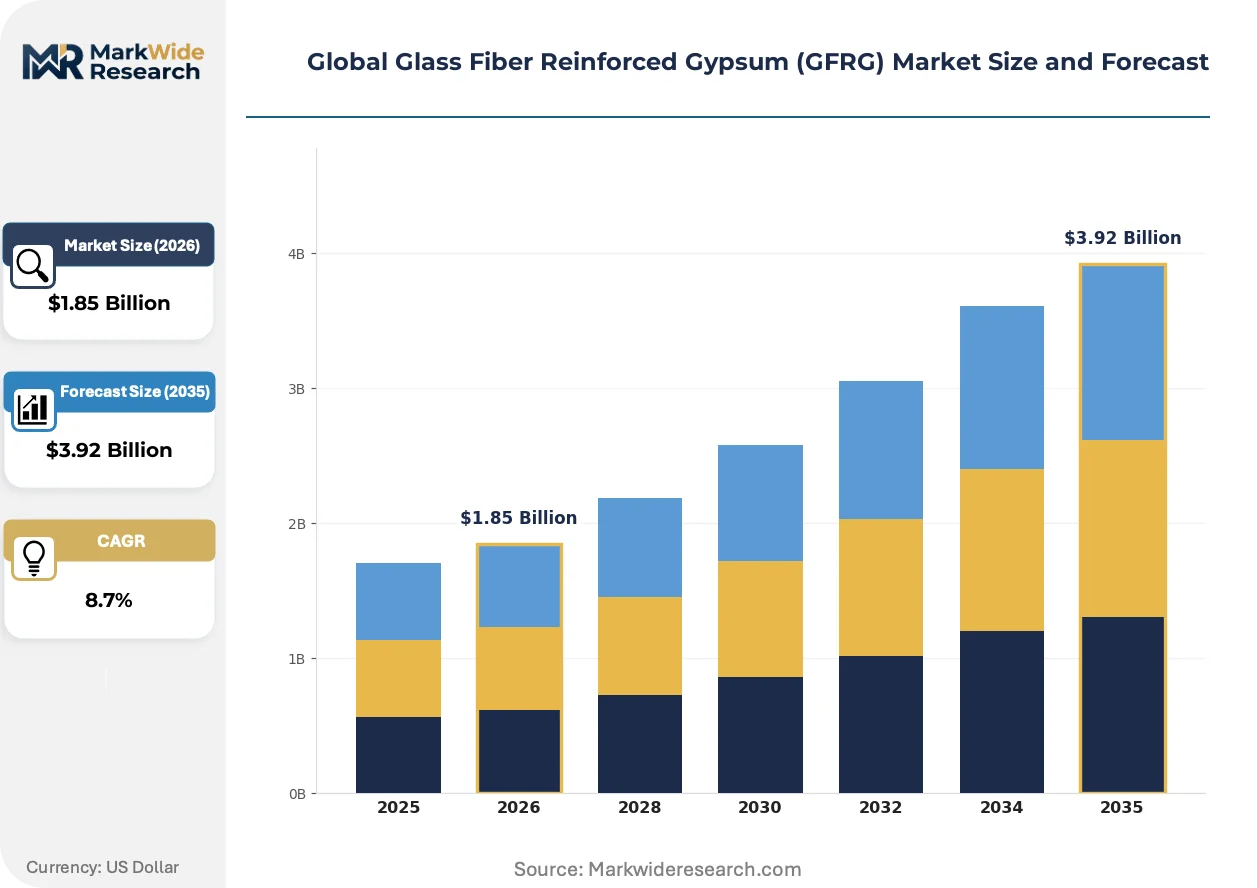
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panels, Boards, Blocks, Sheets, Tiles Application: Wall Partitioning, Ceiling Systems, Facades, Fireproofing, Acoustics End User: Residential Contractors, Commercial Developers, Institutional Builders, Renovation Specialists Installation Method: Dry Fixing, Wet Fixing, Mechanical Fastening, Adhesive Bonding |
| Companies Covered | National Gypsum, Formglas Products Ltd, Knauf Danoline A/S, CertainTeed Corporation, Chiyoda Ute Co., Ltd., USG Corporation, Saint-Gobain, Fermacell, Georgia-Pacific LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glass Fiber Reinforced Gypsum (GFRG) Market Shifts & Advancements
Digital fabrication and regulatory disclosure requirements are compressing traditional specification cycles while expanding the addressable application set for fiber-reinforced gypsum systems beyond conventional interior finishes.
High-performance acoustic GFRG formulations is expanding into healthcare and education verticals. These engineered panels achieve Noise Reduction Coefficients above 0.90 while maintaining Class A fire ratings. Hospital systems in Texas and California specify them for patient recovery zones. The technology is expanding into premium residential markets as open-plan designs prioritize sound privacy.
REACH chemical safety amendments now require granular disclosure of styrene content in unsaturated polyester resins sometimes co-formulated with GFRG edge reinforcements. German and Dutch importers demand full material ingredient documentation from Asian suppliers. Small-scale fabricators lacking in-house toxicology expertise face exclusion from Northern European public procurement.
Design-build firms now bundle GFRG ceiling installation with ongoing maintenance service agreements, unbundling the traditional material-plus-labor transaction. This model penetrates hospitality and corporate office rollouts in Atlanta and Chicago where facility managers prioritize single-source accountability. The shift compresses vendor margins while locking in multi-year replacement cycles for wear-susceptible acoustic tiles.
Global Glass Fiber Reinforced Gypsum (GFRG) Market Segmentation
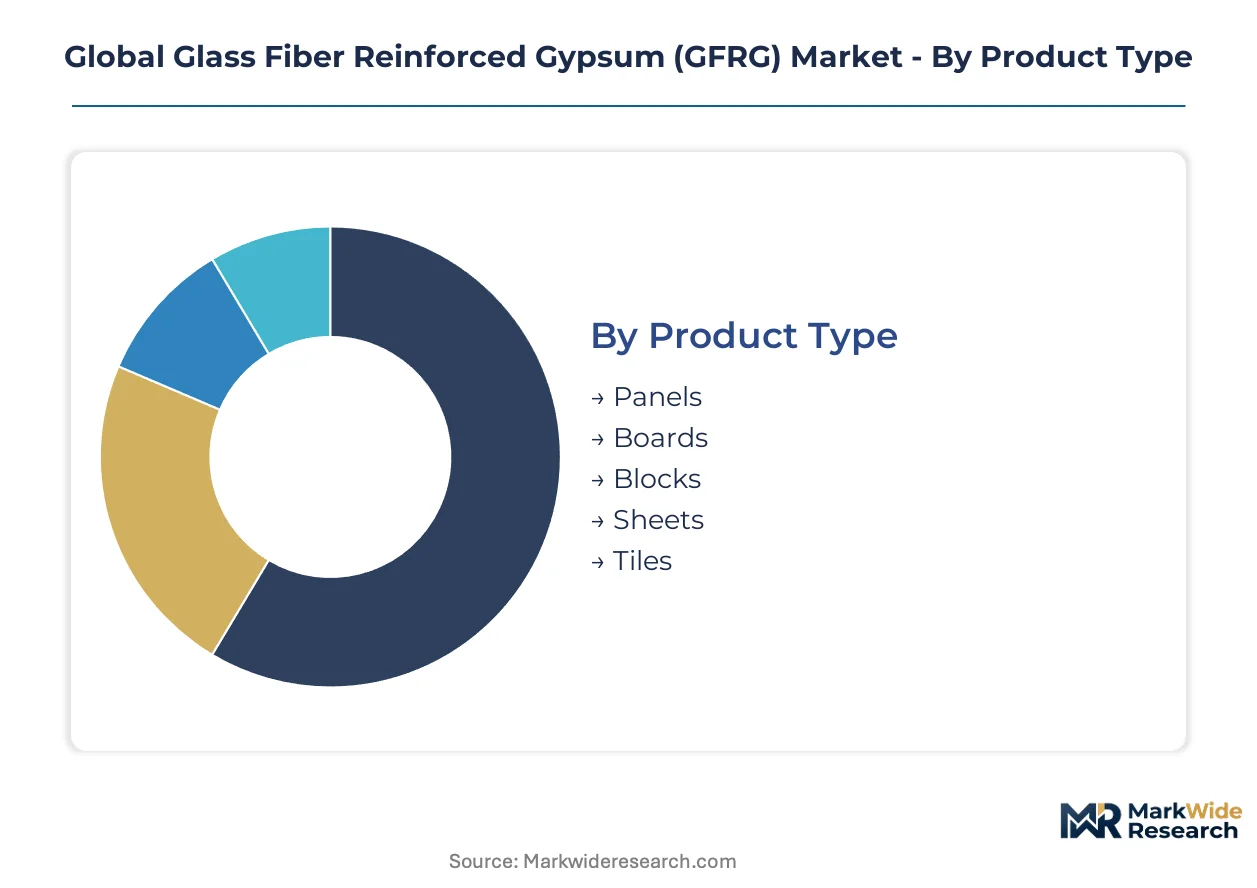
GFRG specification hinges on fire rating, acoustic performance, and installation logistics across commercial and institutional verticals. Architects and contractors weight structural load limits against mold complexity when selecting product configurations. Understanding segment interdependencies reveals where margin concentrates and where specification cycles compress.
Product Type:
Cost tier determines specification access — premium molded elements command architectural fees while standardized boards compete on volume.
- Panels:Large-format GFRG panels integrate glass fiber reinforcement at 15-25 MPa flexural strength for seamless ceiling spans in hotel atriums and convention centers. Demand clusters in metropolitan commercial corridors across the United States and Germany where LEED certification drives low-carbon interior system selection.
- Boards:Standardized board production serves high-volume institutional builders with fire-rated substrates for corridor walls and elevator shafts. USG Corporation operates dedicated lines supplying North American healthcare construction with Class A surface-burning characteristics.
- Blocks:Molded block configurations enable rapid assembly of non-load-bearing partition walls in Indian metro rail construction.
- Sheets:Thin-gauge sheets provide substrate for ornamental column covers in high-rise commercial cores.
- Tiles:Acoustic-grade tiles achieve Noise Reduction Coefficients above 0.90 for hospital surgical suites and performing arts venues.
Volume sits with boards; growth tilts toward panels.
Application:
Code evolution is recalibrating which applications absorb technical innovation versus commoditized supply.
- Ceiling Systems:The most mature GFRG segment combines alpha gypsum plaster with alkali-resistant glass fiber for lightweight ornamental and acoustic assemblies. Germany and France specify these for EU Green Deal-mandated lifecycle carbon assessments in public buildings.
- Wall Partitioning:Non-load-bearing partitions dominate Indian BIS-certified construction for Mumbai and Delhi airport terminals.
- Facades:Exterior cladding substrates gain specification in Dubai and Singapore as fire resistance rating upgrades tighten for high-rise assemblies.
- Fireproofing:Encasement systems for structural steel achieve multi-hour ratings in commercial high-rises.
- Acoustics:Engineered acoustic panels serve Texas and California hospital systems for patient recovery zones.
Ceiling systems hold installed base; facades are expanding most quickly.
End User:
Procurement sophistication separates specification influence from pure volume purchasing.
- Commercial Developers:Control specification for LEED-certified projects across North America and Europe, mandating environmental product declarations and verified embodied-carbon data.
- Institutional Builders:Healthcare and education construction in the United States drives acoustic-grade GFRG demand with stringent infection-control requirements.
- Residential Contractors:Premium residential markets adopt sound-attenuating tiles for open-plan designs.
- Renovation Specialists:Service agreements for ceiling replacement cycles lock in recurring revenue in Atlanta and Chicago hospitality markets.
Commercial developers anchor specification; institutional builders scale fastest.
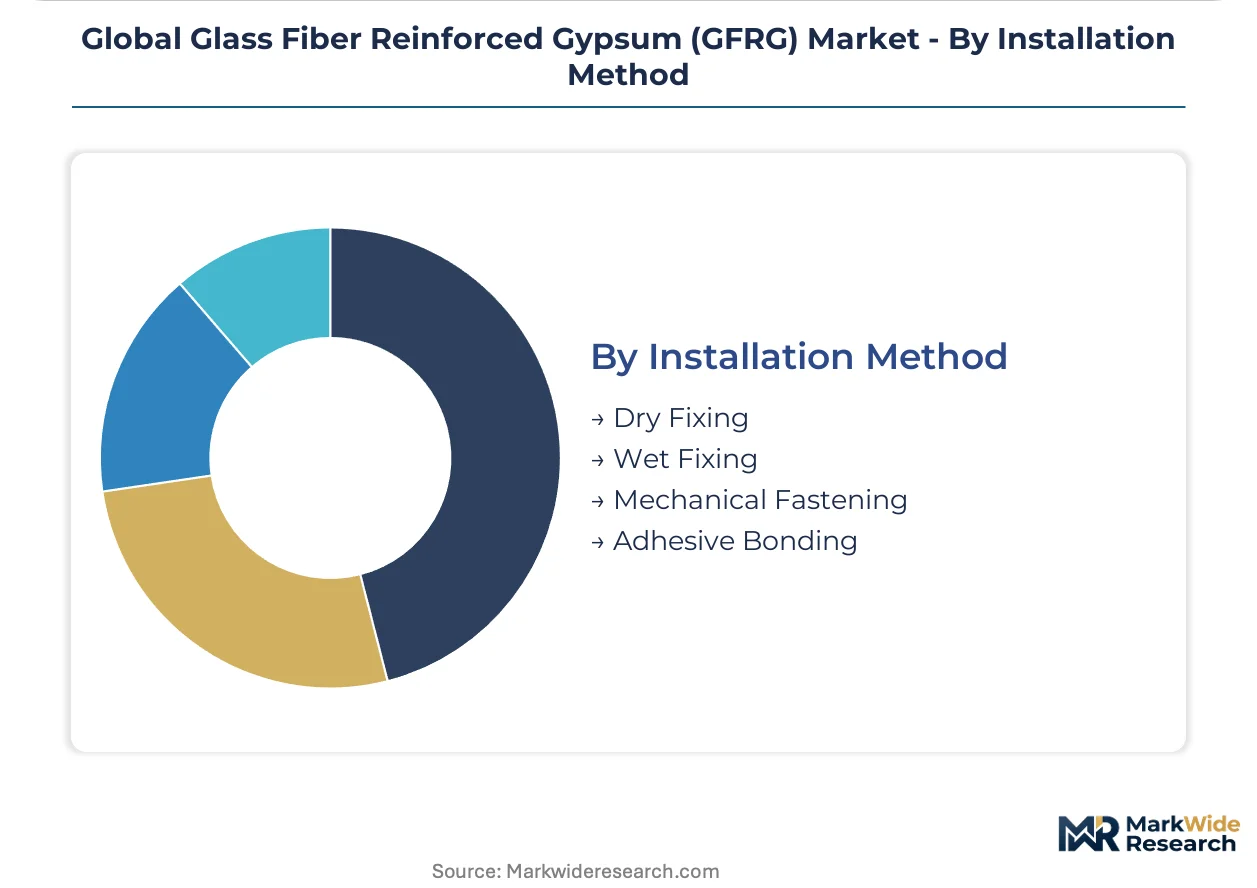
Installation Method:
Labor availability and substrate condition dictate method selection on site.
- Dry Fixing:Mechanical attachment without wet trades accelerates schedule-sensitive projects in occupied buildings.
- Wet Fixing:Traditional plaster-based bonding suits ornamental molded elements requiring seamless joints.
- Mechanical Fastening:Visible fastening systems serve utilitarian fire-rated assemblies where finish concealment is secondary.
- Adhesive Bonding:Chemical anchoring enables lightweight panel attachment to existing substrates in renovation applications.
Dry fixing dominates speed-critical projects; adhesive bonding gains in retrofit verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston, Dallas, and Austin anchor North American GFRG demand through healthcare and commercial construction corridors. Metropolitan commercial districts in Germany, China, and India concentrate specification activity for ceiling systems and facade panels.
United States
Texas and California hospital systems specify acoustic-grade GFRG tiles for surgical suites and patient recovery zones. The EPA regulates volatile organic compound emissions under TSCA Title VI for gypsum-based interior products. Atlanta and Chicago hospitality markets drive design-build service agreements for ceiling replacement cycles.
Germany
France and Germany mandate lifecycle carbon assessments for public buildings under EU Green Deal implementation. REACH compliance governs chemical safety disclosure for GFRG edge reinforcements containing unsaturated polyester resins. The Rhine-Ruhr industrial corridor concentrates manufacturing capacity for certified low-carbon ceiling assemblies.
China
Dual carbon goals recalibrate material selection criteria for interior construction in metropolitan commercial cores. GB standards and MEE enforcement on industrial emissions shape domestic manufacturing constraints and export eligibility. Shandong and Zhejiang provinces cluster raw glass fiber roving production, exposing fabricators to regional emissions enforcement shutdowns.
India
Mumbai and Delhi airport terminal construction creates demand for BIS-certified non-load-bearing GFRG wall panels. The Bureau of Indian Standards certification requirements create formal market access thresholds for foreign suppliers. Metro rail projects in Maharashtra and Delhi-NCR specify molded block configurations for rapid partition wall assembly.
United Arab Emirates
Dubai and Singapore high-rise developments specify GFRG cladding substrates as fire resistance rating upgrades tighten for exterior assemblies. MOHAP and local building codes mandate multi-hour fire ratings for structural steel encasement in commercial towers. The Dubai Design District clusters specification influence for premium architectural interior systems.
Global Glass Fiber Reinforced Gypsum (GFRG) Market Competitive Landscape
The competitive structure tilts toward integrated building materials conglomerates with captive gypsum-fiber manufacturing networks. Saint-Gobain and USG Corporation anchor scale-driven supply positions across North America and Europe. Three archetypes dominate: diversified building materials groups with mineral processing integration, specialized acoustic panel formulators serving healthcare verticals, and regional fabricators focused on custom molded architectural elements. Capacity expansion and environmental product declaration certification represent the dominant competitive moves as specification cycles compress.
Among diversified building materials groups, Saint-Gobain and USG Corporation exemplify scale-driven positions with integrated manufacturing footprints. Knauf Danoline A/S occupies a specialist tier focused on acoustic formulations. Regional fabricators including Formglas Products Ltd. and CertainTeed Corporation sit within the custom architectural element segment. Chiyoda Ute Co., Ltd. represents Japanese industrial conglomerate participation. National Gypsum and Georgia-Pacific LLC anchor North American gypsum board supply positions. Fermacell exemplifies European panel specialization.
| Leading Market Players |
|---|
| National Gypsum |
| Formglas Products Ltd |
| Knauf Danoline A/S |
| CertainTeed Corporation |
| Chiyoda Ute Co., Ltd. |
| USG Corporation |
| Saint-Gobain |
| Fermacell |
| Georgia-Pacific LLC |
| Others |
Supply & Pricing Matrix
LEED-certified commercial developers in the United States and Germany concentrate procurement volume for GFRG ceiling systems, anchoring a project-based pricing model where environmental product declaration certification commands measurable premiums over uncertified alternatives.
Pricing Analysis
Fire-resistance rating outcomes anchor value-based pricing tiers across GFRG specification. Three-tier pricing structure across premium, standard, and economy levels separates Class A fire-rated acoustic assemblies from basic corridor boards and uncertified molded elements. Price differentiation hinges on UL certification tier and volume scale, with healthcare institutional buyers showing least price sensitivity due to infection-control mandates. Cost compression in economy-grade boards is intensifying because petroleum-derived retarder inputs track volatile crude benchmarks.
Supply Chain Analysis
Direct-to-contractor channels handle specification-driven project demand while distributor networks serve high-volume institutional builders. Raw glass fiber roving production clusters in China, Germany, and the United States, with downstream fabricators drawing from Shandong and Zhejiang provinces for alkali-resistant reinforcement. Alpha gypsum plaster feeds from captive mineral processing operations or merchant chemical suppliers. Single-source vulnerability in Chinese glass fiber concentration exposes fabricators to MEE emissions enforcement shutdowns. Distribution runs through regional building materials distributors with technical specification support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH chemical disclosure requirements and EPA TSCA Title VI emissions standards erect barrier-to-entry moats favoring incumbents with in-house toxicology and lifecycle assessment capabilities.
For Market Incumbents: Anchor specification influence by deepening captive supply of alpha gypsum and alkali-resistant glass fiber against petroleum-input volatility. Defend market position through accelerated EPD certification pipelines to compress approval timelines on LEED Platinum projects, countering cross-laminated timber substitution in Scandinavian and Pacific Northwest commercial corridors. For New Entrants and Emerging Players: Capture white-space in Indian BIS-certified non-load-bearing wall panels for Mumbai and Delhi metro rail construction, where foreign supplier penetration remains limited. Target facade fireproofing applications in Dubai and Singapore high-rise markets as code-driven fire resistance upgrades outpace incumbent capacity expansion. For Investors and Strategic Acquirers: The window for entry favors specialized acoustic panel formulators with healthcare vertical relationships and verified EPD libraries. Long-term viability hinges on digital fabrication integration for parametric architectural elements. Monitor carbon border adjustment implementation timelines as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| EPD Certification Acceleration | Third-party lifecycle documentation compresses specification approval timelines on LEED Platinum healthcare projects. |
| Backward Integration into Alpha Gypsum | Captive mineral processing insulates margin stability from merchant chemical supplier price volatility. |
| Digital Fabrication Capability Buildout | Robotic mold milling combined with parametric design software reduces custom architectural element lead times. |
| BIS Certification Pathway Investment | Bureau of Indian Standards compliance unlocks access to Mumbai and Delhi airport terminal construction. |
| Facade Fireproofing Application Expansion | Code-driven fire resistance upgrades in Dubai and Singapore create demand for GFRG cladding substrates. |
Research Methodology
Document review covered building code amendments, EPA and REACH regulatory filings, and customs trade data, complemented by interviews with commercial specification architects, healthcare facility procurement managers, GFRG manufacturing plant managers, and building materials distribution channel partners. Secondary validation drew from SEC 10-K disclosures of integrated building materials conglomerates, EU EPD database entries, and BIS certification registries. Bottom-up project pipeline analysis and top-down construction spending triangulation anchored volume estimates.
Cross-referencing historical specification cycle patterns against panel input from industry stakeholders shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product configuration tier, application type, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from installed base growth rates adjusted for code-driven replacement cycles and embodied-carbon disclosure mandate implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment implementation, petroleum-derived additive cost trajectories, and skilled mold-making labor availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
Polycrystalline Alumina Fiber Market
Fibers
Ceramic Fiber Market
Fibers
Drug Integrated Polymer Fibers Market
Fibers
Global Fiberglass Market
Fibers
Fiberglass Resin Market
Fibers
Fiberglass Sunscreen Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Viscose Filament Yarn Market
Fibers
Asia-Pacific Carbon Fiber Market
Fibers
Basalt Continuous Fiber (BCF) Market
Fibers
High Performance Fibers for Defense Market
Fibers
Citrus Pulp Fiber Market
Fibers
Sisal Market
Fibers
Fiber Intermediates Market
Fibers
Acoustical Fiber Board Market