
 Europe Calcium Carbonate Market | 2026-2036
Europe Calcium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Calcium Carbonate Market Intelligence
Specialized geological expertise in identifying and developing high-purity limestone deposits is bifurcating the competitive landscape in Europe. Global producer Imerys leverages its extensive quarry network and processing capabilities to serve diverse end-markets. Omya AG specializes in high-value precipitated calcium carbonate (PCC) for specialty applications. Lhoist anchors its strategy in supplying the construction and agriculture sectors with consistent-grade ground calcium carbonate (GCC).
Calcium carbonate is an inorganic mineral compound with the chemical formula CaCO3, sourced primarily from quarrying limestone and marble. Its principal industrial function is as a filler and extender in materials like plastics, paper, and paints to reduce costs and modify physical properties. Ground Calcium Carbonate (GCC) constitutes the bulk of market volume due to its lower cost, serving the construction and paper industries. Precipitated Calcium Carbonate (PCC), in contrast, offers higher purity and controlled particle size, commanding premium pricing in pharmaceuticals and specialized plastics.
The European market operates under the stringent REACH regulation, managed by the European Chemicals Agency (ECHA), which requires registration and safety evaluation for all chemical substances. For food and pharmaceutical applications, compliance with European Food Safety Authority (EFSA) and European Pharmacopoeia standards is mandatory, dictating purity levels. Producers must navigate these complex regulatory requirements while investing in processing technologies that meet demands for finer, more consistent particle grades.
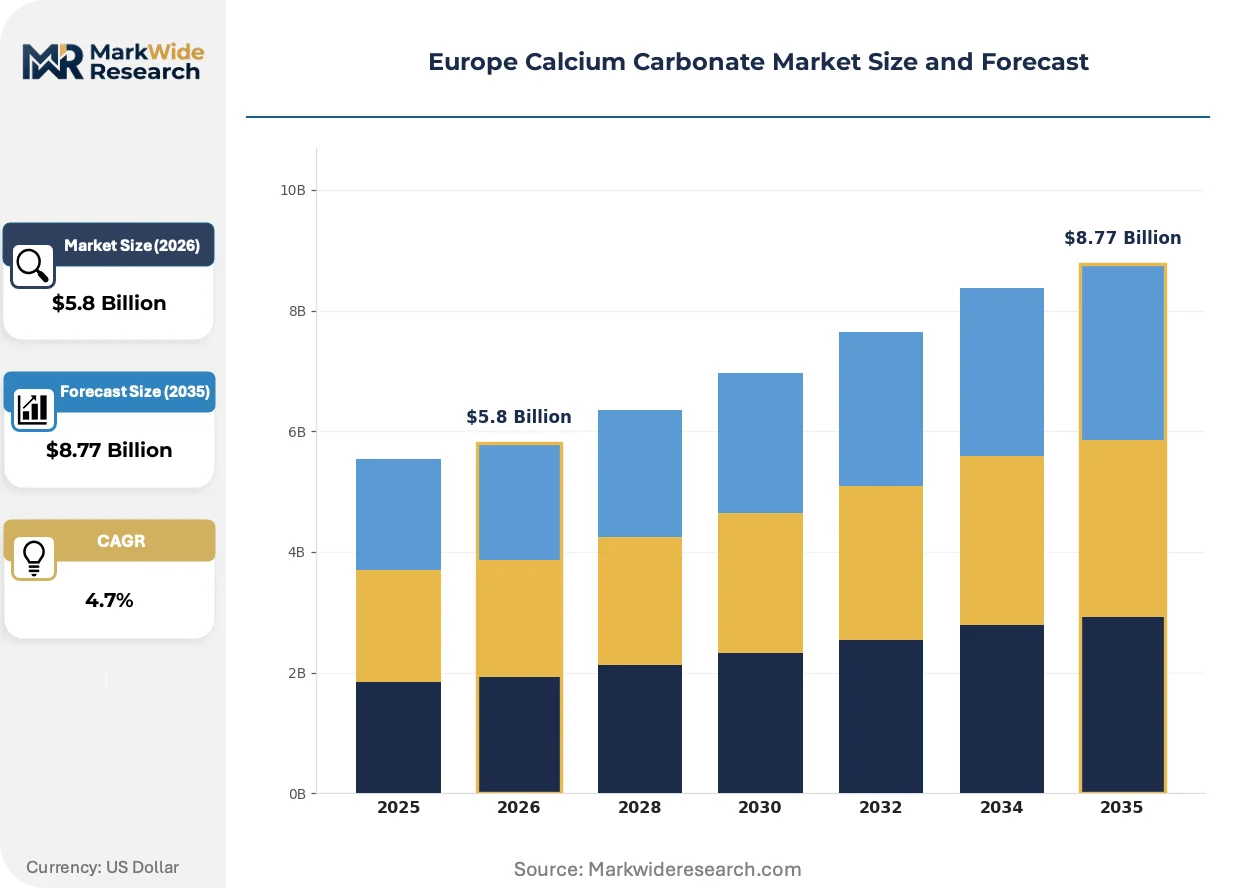
Market Dynamics
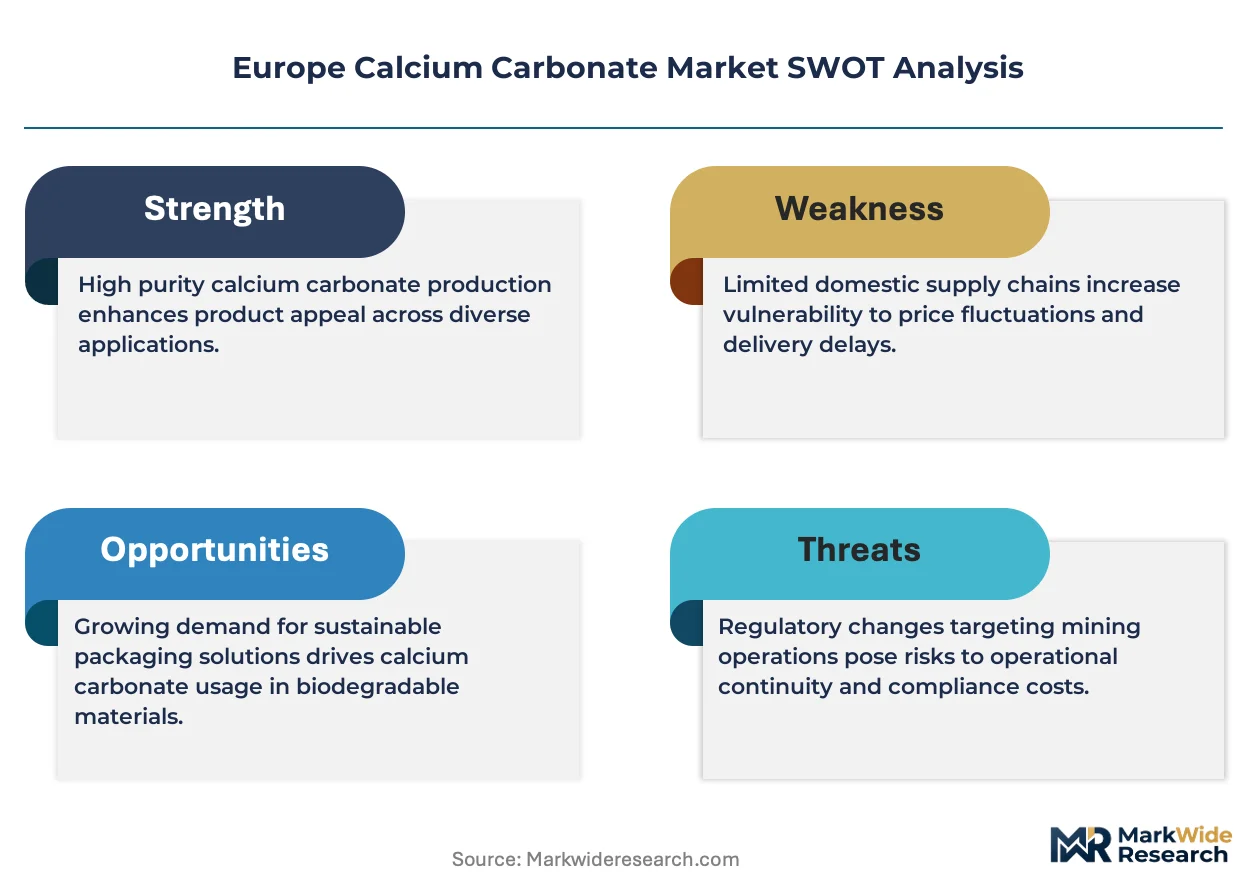
The central dynamic in the Europe Calcium Carbonate Market is the collision between the EU Green Deal's sustainability mandates and the industrial requirement for cost-effective raw materials. This tension forces producers to innovate beyond commodity supply toward functional additives that enable circularity and lightweighting in plastics, construction, and paper manufacturing.
Growth Catalysts
- Plastics Lightweighting:Demand from the European automotive industry for lighter components to improve fuel efficiency and EV range is a significant catalyst for using calcium carbonate as a functional filler in polymers.
- Sustainable Construction:Germany's focus on green building practices boosts the use of GCC in applications like paints, sealants, and concrete, where it reduces binder content and lowers the carbon footprint.
- EU Circular Economy Policy:The EU's push for recycled content in packaging creates a need for high-quality calcium carbonate grades that can enhance the performance and aesthetics of recycled polymers.
Market Restraints
- Energy Cost Volatility:The high energy consumption of grinding (GCC) and chemical synthesis (PCC) processes makes producers' cost structures highly sensitive to Europe's volatile electricity and natural gas prices.
- REACH Compliance Burden:The European Chemicals Agency's REACH regulation imposes significant testing and registration costs, creating a barrier for new grades and smaller producers entering the market.
- Substitution from Other Minerals:In certain polymer and paint applications, calcium carbonate faces a substitution threat from other functional fillers like talc and kaolin, which can offer different performance advantages.
Strategic Opportunities
- Pharma and Nutraceuticals:Developing ultra-pure, fine-particle PCC grades opens opportunities in the high-value pharmaceutical excipient and calcium supplement markets, which are governed by strict European Pharmacopoeia standards.
- Bioplastics Formulation:Calcium carbonate can serve as a nucleating agent and extender in bioplastics like PLA, offering a pathway to improve material properties and reduce costs in this growing segment.
- Eastern Europe Expansion:Industrial and construction growth in countries like Poland and Romania presents an opportunity for market expansion beyond the mature markets of Western Europe.
Industry Challenges
- Capital Investment Hurdles:The substantial capital expenditure required to establish new high-purity quarrying operations or construct advanced PCC facilities presents a significant challenge to capacity expansion.
- Logistics Complexity:Managing a low-value, high-volume bulk supply chain across Europe's diverse transport infrastructure while minimizing freight costs and carbon emissions is a persistent operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Calcium Carbonate Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Calcium Carbonate, Precipitated Calcium Carbonate, Coated Calcium Carbonate, Micronized Calcium Carbonate Application: Construction, Plastics, Paints & Coatings, Paper End User: Automotive, Food & Beverage, Pharmaceuticals, Agriculture Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Imerys, Omya AG, Lhoist, Sibelco, Carmeuse, Nordkalk Corporation, CALCIT doo, ACCM, SCHAEFER KALK GmbH & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Calcium Carbonate Market Strategic Shifts & Innovations
Material science is transforming calcium carbonate from a passive filler into a functional additive. European regulations and end-user demands for sustainability and performance are accelerating investments in surface modification, particle engineering, and novel applications that extract higher value from this abundant mineral.
Surface-treated calcium carbonate, engineered with coatings like stearic acid, improves dispersion and interfacial adhesion within polymer composites. The European plastics industry, especially in automotive and construction materials, is steadily adopting these grades for enhanced mechanical properties. The improved functionality is decomposing the traditional divide between inert fillers and performance additives, allowing producers to capture more value.
The European Union's Circular Economy Action Plan is a key regulatory driver. This framework encourages the use of recycled materials, creating demand for calcium carbonate as a processing aid and property enhancer in recycled polymer formulations. The plastics compounding sector across the EU, particularly in Germany and Italy, is most affected, adapting its formulations to meet both recycled content mandates and final product specifications.
A distinct pivot from volume-based purchasing to specification-driven procurement is occurring among sophisticated end-users. Buyers in sectors like specialty coatings and paper manufacturing now demand precise control over particle size, brightness, and surface chemistry to achieve specific performance outcomes. This trend is most pronounced in the Nordic paper sector and the German automotive coatings industry, compelling suppliers to offer deeper technical collaboration.
Europe Calcium Carbonate Market Segmentation
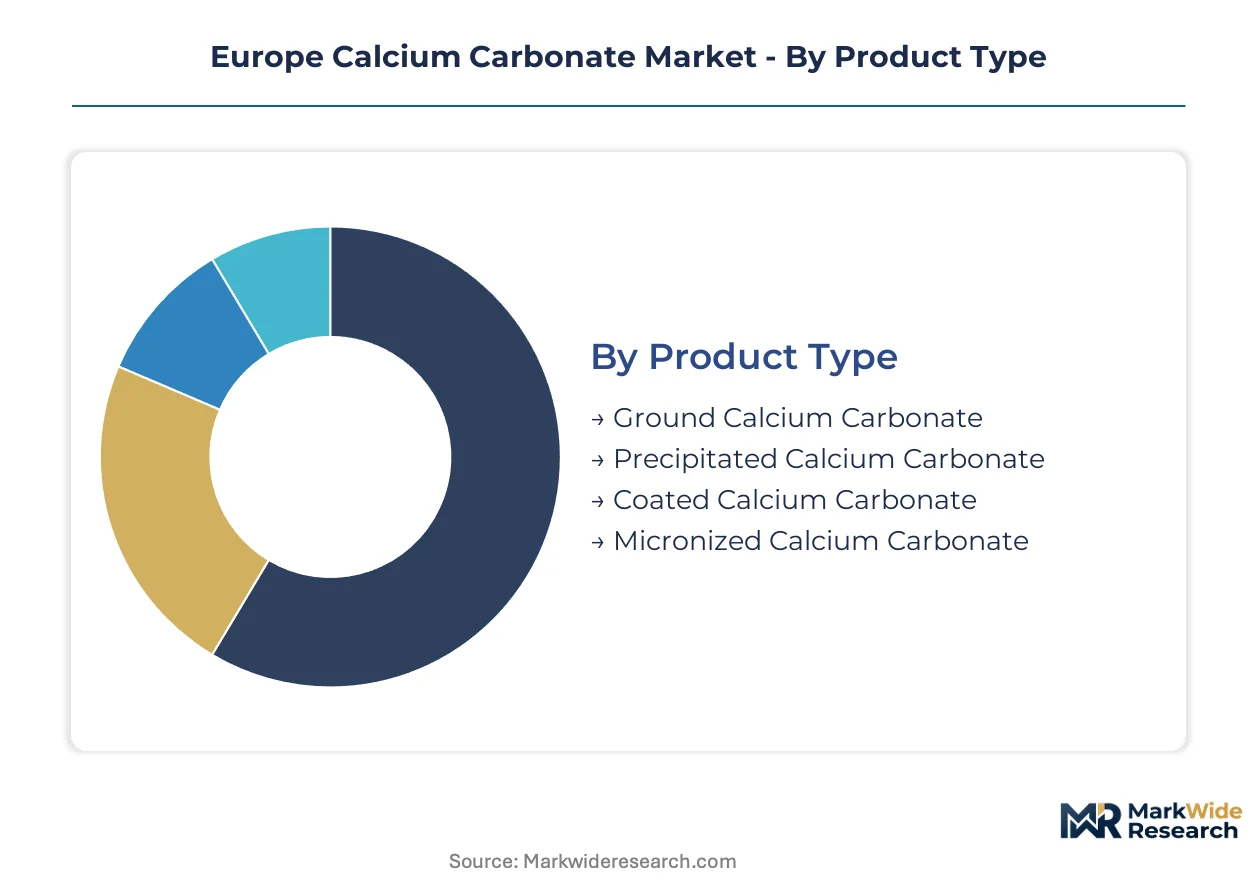
The Europe calcium carbonate market is fundamentally shaped by diverse product forms, application demands, and end-user specifications. Understanding these distinct segments reveals where value is created and captured across the supply chain. Producers differentiate offerings to meet stringent regulatory requirements and performance needs in various industrial sectors.
Product Type:
Margin pools within product types are heavily influenced by processing intensity and purity levels, with specialty grades commanding higher prices for specific performance attributes.
- Precipitated Calcium Carbonate:This synthetic form of calcium carbonate offers superior purity, controlled particle size, and specific crystal structures. Demand is concentrating in pharmaceutical and specialized plastics applications, driven by requirements for high performance and aesthetic quality.
- Ground Calcium Carbonate:Derived directly from quarried limestone, GCC is characterized by its natural mineral composition and mechanical grinding process. Construction and paper industries drive its demand across Europe, valuing its cost-effectiveness and filler properties.
- Coated Calcium Carbonate:Surface-treated grades, often with stearic acid, improve dispersion and interfacial adhesion in polymer composites.
- Micronized Calcium Carbonate:These ultra-fine particle grades enhance material properties like smoothness and gloss in paints and specialty coatings.
The dominant share belongs to Ground Calcium Carbonate, while Precipitated Calcium Carbonate is closing the gap fastest.
Application:
Applications for calcium carbonate span a range of cost tiers, from high-volume commodity uses to specialized performance-driven segments requiring tailored formulations.
- Plastics:Calcium carbonate serves as a functional filler in polymers, improving mechanical properties, reducing material costs, and enabling lightweighting. The European automotive industry drives significant demand for these grades to enhance fuel efficiency and EV range.
- Construction:This sector utilizes large volumes of GCC in concrete, sealants, and paints to reduce binder content and improve material workability. Germany's focus on green building practices boosts the use of these sustainable materials.
- Paints & Coatings:Calcium carbonate acts as an extender and pigment in paints, improving opacity and reducing titanium dioxide content.
- Paper:Used as a filler and coating pigment, calcium carbonate enhances brightness, opacity, and printability in European paper production.
The construction sector accounts for the largest volume consumption, while plastics applications are expanding most quickly.
End User:
End-user segments exhibit varying volume requirements, with some industrial sectors consuming bulk quantities and others demanding highly specialized, lower-volume grades.
- Automotive:The automotive industry uses calcium carbonate in plastic components for lightweighting, contributing to improved fuel economy and extended electric vehicle range. European manufacturers are integrating these fillers to meet stringent emissions standards.
- Pharmaceuticals:This sector requires ultra-pure PCC grades for use as excipients, binders, and calcium supplements, adhering to strict European Pharmacopoeia standards. Producers invest heavily in purification technologies for these high-value applications.
- Food & Beverage:Calcium carbonate functions as a food additive, anti-caking agent, and dietary calcium source, complying with EFSA regulations.
- Agriculture:Used for soil conditioning and pH adjustment, calcium carbonate improves soil fertility and crop yields across European farms.
Industrial end-users like automotive and construction companies drive consistent demand, while pharmaceutical buyers prioritize product purity and certification.
Distribution Channel:
Supply concentration within distribution channels varies, reflecting the scale of customer operations and the technical support required for product integration.
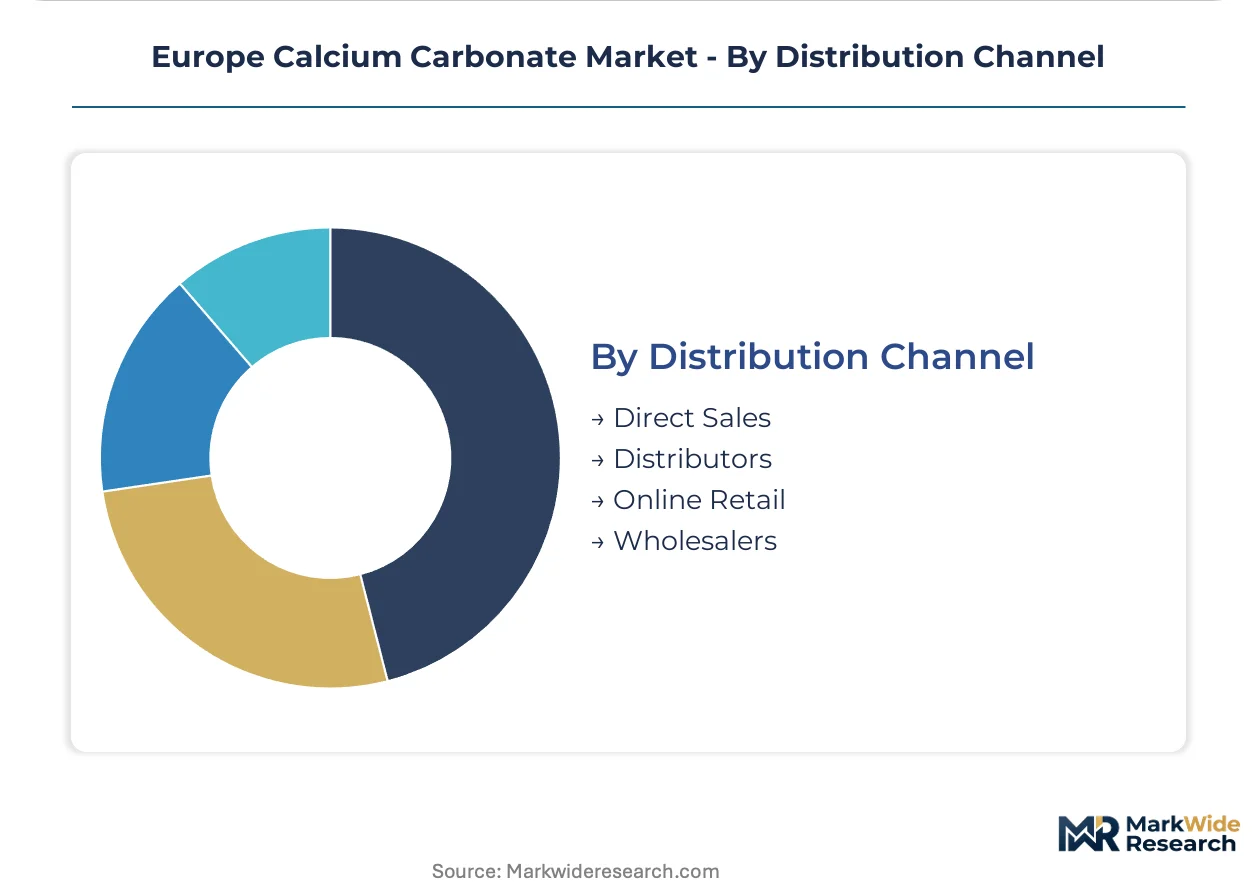
- Direct Sales:Large industrial buyers, particularly in automotive and construction, procure calcium carbonate directly from manufacturers to ensure consistent supply and technical specifications. This channel facilitates close collaboration on product development.
- Distributors:These intermediaries serve a broad base of smaller and medium-sized enterprises across Europe, offering regional inventory and logistics support. Distributors manage diverse product portfolios for various end-use applications.
- Online Retail:This emerging channel caters to niche or very small-volume buyers, offering convenience for specific, often standardized, calcium carbonate products.
- Wholesalers:Bulk material wholesalers supply calcium carbonate to a range of industries, often handling large volumes for less specialized applications.
Direct sales represents the most mature channel for high-volume transactions, while online retail is gaining share fastest for specialized products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's stringent REACH regulation significantly shapes the European calcium carbonate market. Producers must navigate complex compliance requirements for chemical substances, impacting product specifications and market access. This regulatory environment drives innovation in processing technologies to meet evolving purity and particle grade demands across the continent.
Germany
Germany's automotive industry drives demand for calcium carbonate in lightweight components to improve fuel efficiency. The EU Green Deal's focus on green building practices boosts GCC use in paints and sealants. Bavaria's automotive sector integrates these functional fillers to meet stringent emissions standards.
France
French packaging manufacturers increasingly utilize calcium carbonate to enhance recycled polymer formulations. The EU Circular Economy Action Plan encourages the use of recycled materials, boosting demand for quality additives. Île-de-France's extensive packaging industry adapts formulations to meet recycled content mandates.
Poland
Poland's expanding construction sector and general industrial growth present significant opportunities for calcium carbonate suppliers. EU cohesion policy investments support infrastructure development, increasing material consumption across the country. Silesia's robust industrial infrastructure benefits from the demand for cost-effective raw materials.
Italy
Italian plastics compounding companies demand high-quality calcium carbonate grades for performance applications. REACH compliance dictates stringent safety evaluations for all chemical substances used in industrial processes. Lombardy's plastics compounding sector adapts formulations to meet both recycled content mandates and final product specifications.
United Kingdom
The United Kingdom's paints and coatings industry utilizes micronized calcium carbonate for improved opacity and smoothness. UK REACH regulations necessitate careful registration and safety assessments for all chemical imports and domestic production. Yorkshire's paper manufacturing sector demands specific grades to enhance brightness and printability.
Europe Calcium Carbonate Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the European calcium carbonate market. This tiered structure reflects the capital intensity of quarrying and processing, alongside the need for specialized product development. Strategic archetypes include large-scale commodity suppliers, high-purity PCC specialists, and regional ground calcium carbonate providers. Companies pursue portfolio diversification and geographic expansion to secure market share.
Among the established players, Imerys exemplifies a global producer leveraging an extensive quarry network and processing capabilities to serve diverse end-markets across Europe. Omya AG, a Swiss-based company, occupies a position as a specialist in high-value precipitated calcium carbonate for pharmaceutical and specialized plastics applications. Lhoist, a Belgian group, anchors its strategy in supplying the construction and agriculture sectors with consistent-grade ground calcium carbonate for large-volume industrial uses. These companies represent different approaches to market penetration and value capture, from broad commodity supply to niche high-purity offerings, reflecting the bifurcated nature of the competitive landscape.
| Leading Market Players |
|---|
| Imerys |
| Omya AG |
| Lhoist |
| Sibelco |
| Carmeuse |
| Nordkalk Corporation |
| CALCIT doo |
| ACCM |
| SCHAEFER KALK GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Talc and kaolin substitution for calcium carbonate reshapes supply geography and pricing economics by introducing alternative performance profiles. This dynamic forces European producers to differentiate offerings beyond commodity status.
Pricing Analysis
Geographic price spreads for calcium carbonate vary significantly across Europe, reflecting regional supply-demand balances; long-term contract-based offtake agreements dominate for bulk ground calcium carbonate, while specialty precipitated calcium carbonate commands value-based pricing. Purity levels and adherence to European Pharmacopoeia standards drive price differentiation for specialty grades. Pricing softness stems from Europe's volatile electricity and natural gas prices, particularly impacting energy-intensive production. Construction and paper manufacturers exhibit high price sensitivity, contrasting with pharmaceutical buyers who prioritize purity and certification.
Supply Chain Analysis
Germany and Belgium anchor calcium carbonate processing and distribution within Europe, leveraging established industrial infrastructure. The supply chain sources primarily from abundant regional limestone deposits, with energy inputs like natural gas and electricity critical for processing. Logistics complexity across Europe's diverse transport infrastructure presents a structural risk, impacting cost and delivery efficiency. Distribution runs through direct sales channels for large industrial buyers in automotive and construction, complemented by regional distributors serving a broad base of smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe calcium carbonate market sits in a cyclical recovery phase, driven by renewed investment in European construction and infrastructure development. This recovery presents strategic opportunities for market participants to solidify positions and capture emerging demand.
For Market Incumbents: Fortify market position by investing in advanced processing technologies for finer, more consistent particle grades, countering substitution from talc and kaolin. Secure long-term energy contracts to mitigate Europe's volatile electricity and natural gas prices, stabilizing cost structures. Deepen technical collaboration with key end-users in automotive and specialty coatings. Prioritize certification investment, especially for European Pharmacopoeia standards, to maintain access to high-value pharmaceutical segments.
For New Entrants and Emerging Players: Certification fast-track programs for ultra-pure PCC grades enable entry into the high-value pharmaceutical and nutraceutical markets. Target underpenetrated segments like bioplastics formulation, offering calcium carbonate as a nucleating agent to improve material properties. Eastern Europe, specifically Poland and Romania, represents a penetrable geography due to expanding industrial and construction sectors. A go-to-market strategy centered on specialized technical support and application-specific product development will differentiate offerings.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors asset-light specialists and vertically integrated regional players. Long-term viability remains strong, underpinned by European mandates for sustainable materials and circular economy principles. Acquisition targets should include mid-sized producers with specialized PCC production capabilities or extensive, high-purity quarry networks in strategic European locations. The evolution of EU Green Deal mandates for recycled content and material specifications provides a crucial signal for future investment direction.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Eastern Europe | Industrial and construction growth in Poland and Romania creates new demand for bulk ground calcium carbonate. |
| Advanced PCC Facility Investment | Serves high-value pharmaceutical and specialized plastics applications with ultra-pure precipitated calcium carbonate grades. |
| Long-term Energy Supply Contracts | Mitigates Europe's volatile energy prices, stabilizing production costs for energy-intensive calcium carbonate producers. |
| Technical Collaboration with Automotive OEMs | Co-develops lightweighting solutions for vehicle components, helping European manufacturers meet stringent emissions standards. |
| Certification for Bioplastics Compatibility | Positions calcium carbonate as a functional additive in growing sustainable polymer segments like PLA. |
Research Approach
Two parallel data streams informed the analysis: primary interviews and secondary validation. Primary insights came from procurement leads in plastics, R&D directors in automotive, and plant managers at European calcium carbonate producers. Secondary research involved synthesizing data from Eurostat, European Chemicals Agency (ECHA) reports, and industry association publications. This approach ensured robust bottom-up data collection, triangulated with top-down market sizing for comprehensive accuracy.
The forecast boundary extends across the analysis window, utilizing a robust analytical framework. The model segmented the market by product type, application, end-user, purity level, and regional market. Compound Annual Growth Rates were derived from historical trends and projected demand drivers. Key industry-specific forecast inputs included EU Green Deal policy adoption rates and European energy price trends.
Underlying assumptions cover current regulatory frameworks and macroeconomic stability, with deviation risk concentrated in unforeseen EU policy shifts or significant energy price volatility. Forecasts reflect these documented assumptions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Propionaldehyde Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
North America Malic Acid Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Propionic Anhydride Market