
 Japan Calcium Chloride Market | 2026-2036
Japan Calcium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Calcium Chloride Market Intelligence
Buyer concentration among municipal road authorities in Hokkaido and Tohoku is expanding as regional governments consolidate winter maintenance procurement under prefectural purchasing consortia. Fuji Kasei leverages its domestic production network to serve these consolidated buyers with flake and pellet formulations. Tateyama Chemical Co., Ltd. anchors supply relationships with chemical manufacturing end users seeking high-purity grades for industrial synthesis. Nippon Soda Co., Ltd. competes through vertical integration into chlor-alkali feedstock production, controlling raw material costs across volatile chlorine markets.
Calcium chloride is an inorganic salt with the formula CaCl₂, typically produced via the Solvay process or as a byproduct of soda ash manufacturing, and functions primarily as a hygroscopic desiccant, freezing-point depressant, and cement accelerator. Flake and pellet product types dominate volume flows into de-icing and dust control applications, where margin pools remain stable despite seasonal demand swings. Liquid formulations are capturing share in food preservation and chemical manufacturing end uses, where dissolution-ready delivery reduces handling costs for industrial buyers.
METI oversees chemical substance classification and industrial safety standards, while JIS standards govern product specifications for construction and food-grade applications, together elevating compliance costs for imported material and reinforcing domestic producer advantages. The Food Industry end user segment faces additional scrutiny from the country's national food safety regulator, which mandates residue testing and additive purity thresholds that favor established Japanese suppliers with certified quality systems. Stakeholders must monitor whether prefectural consolidation of road maintenance budgets shifts procurement toward long-term supply contracts or spot-market flexibility.
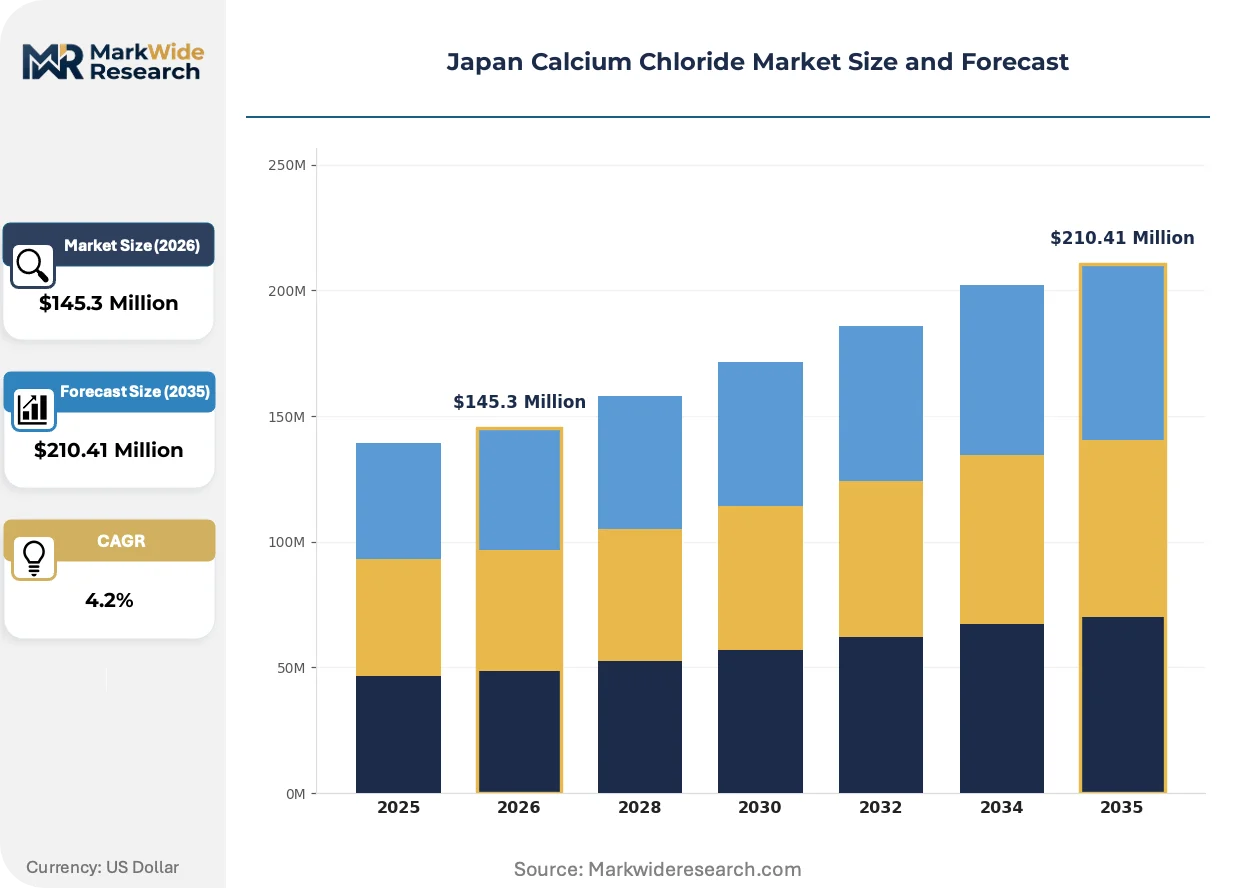
Market Dynamics
Prefectural consolidation of road maintenance budgets across northern Japan is restructuring procurement relationships, as Hokkaido and Tohoku municipalities shift from fragmented municipal purchasing toward centralized consortia with multi-year volume commitments.
Growth Catalysts
- Harsh winter intensification:Municipal highway departments in Hokkaido face extended de-icing seasons, expanding flake and pellet consumption for road safety management.
- METI purity mandates:Tightening chemical substance management frameworks for food-grade calcium chloride are elevating compliance barriers for imported material, reinforcing domestic producer advantages.
- Chlor-alkali integration:Backward integration into captive chlorine supply is insulating major producers from raw material volatility, stabilizing margin structures across production cycles.
Market Restraints
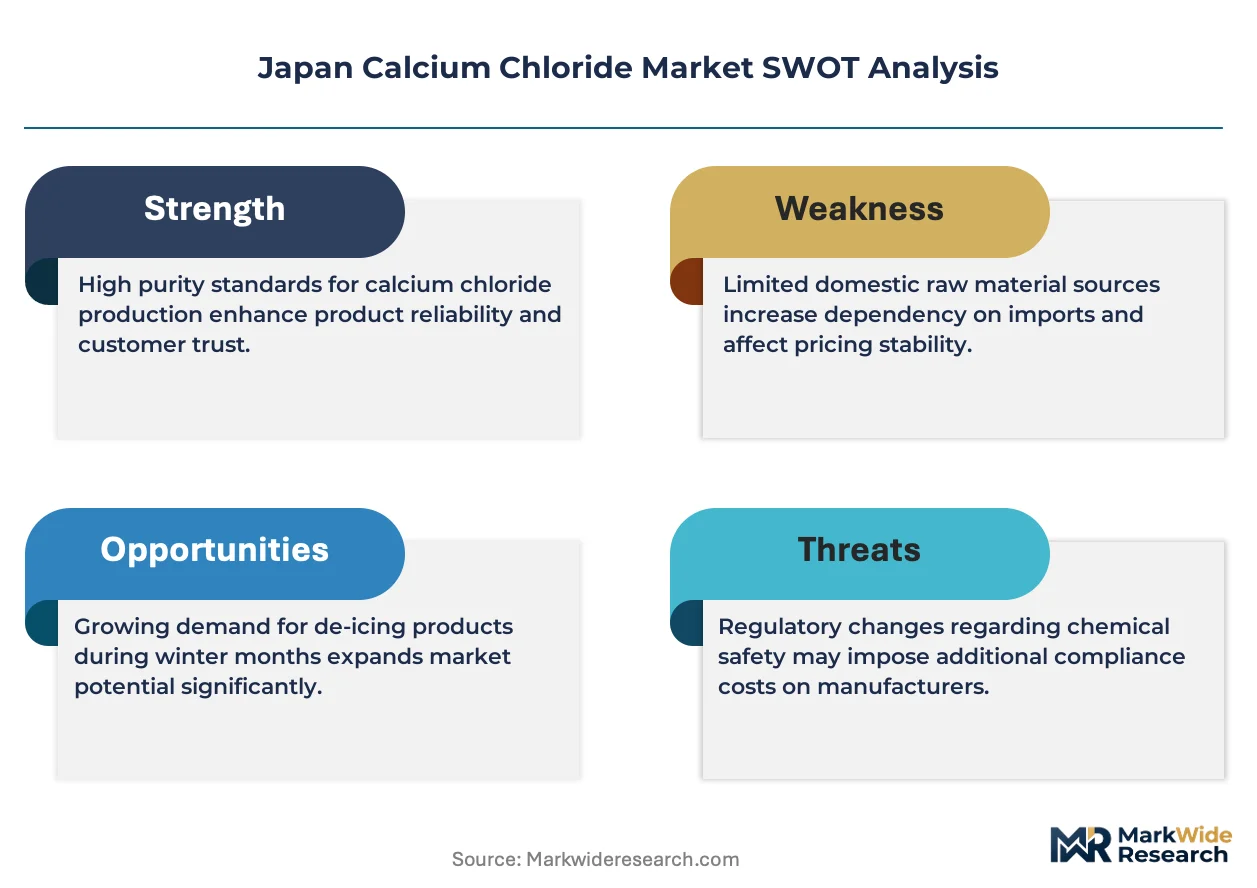
- Energy input cost volatility:Electrolytic chlorine production remains exposed to Japanese electricity pricing swings, compressing margins during peak demand periods.
- Seasonal demand asymmetry:Northern prefectures concentrate de-icing consumption in winter months, creating capacity utilization challenges for producers serving year-round industrial buyers.
- Magnesium chloride substitution:Alternative freezing-point depressants are capturing share in dust control applications where corrosion sensitivity limits calcium chloride adoption.
Strategic Opportunities
- Liquid formulation expansion:Dissolution-ready delivery formats are penetrating food preservation and chemical manufacturing end uses, reducing handling costs for industrial buyers.
- JIS certification premium:Construction-grade and food-grade certification under Japanese Industrial Standards commands price premiums over uncertified imports in quality-sensitive segments.
- Tohoku reconstruction infrastructure:Cement acceleration applications in regional infrastructure renewal are creating sustained demand outside seasonal de-icing cycles.
Industry Challenges
- Specialized logistics coordination:Hygroscopic material properties demand moisture-controlled transport and storage infrastructure, elevating distribution complexity for multi-prefecture supply networks.
- Dual-grade production scheduling:Food-grade and industrial-grade purity requirements impose batch segregation protocols, complicating capacity allocation across divergent margin pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Calcium Chloride Market |
| Market Size in 2026 | $145.3 Million |
| Market Size in 2035 | $210.41 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Pellets, Liquid, Granules Application: De-icing, Dust Control, Food Preservation, Desiccant End User: Construction, Chemical Manufacturing, Food Industry, Agriculture Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Fuji Kasei, OxyChem Corporation, Tateyama Chemical Co., Ltd., Ward Chemical Ltd., Zirax Limited, Nippon Soda Co., Ltd., TETRA Chemicals Europe AB, Tiger Calcium Services Inc., Tokuyama, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Calcium Chloride Market Strategic Shifts & Innovations
Product format innovation and regulatory compliance automation are restructuring competitive positioning in Japanese calcium chloride supply, as producers differentiate through delivery-system adaptation rather than commodity chemistry alone.
High-purity liquid calcium chloride is expanding into chemical manufacturing and food processing applications, where dissolution-ready delivery eliminates on-site handling equipment for industrial buyers. Pharmaceutical and fine chemical producers in the Kanto region are adopting tank-car delivery systems at accelerating rates. This format shift is expanding into premium segments previously dominated by solid flake procurement, compressing traditional handling-margin structures.
METI's chemical substance management frameworks are tightening residue testing protocols for food-grade material, extending certification timelines and elevating documentation burdens for imported supply. Domestic producers with established quality systems are capturing share in additive applications where purity documentation is mandatory. Food manufacturers are consolidating supplier relationships toward JIS-certified domestic sources to streamline compliance workflows.
Prefectural purchasing consortia are consolidating winter maintenance procurement under multi-year framework agreements, displacing spot-market flexibility with volume-commitment contracts. Municipal road authorities in Hokkaido are centralizing supplier selection through prefectural bidding platforms. This concentration is most visible in northern prefectures facing intensifying winter road maintenance cycles, where long-term supply security outweighs price optimization in vendor selection criteria.
Japan Calcium Chloride Market Segmentation
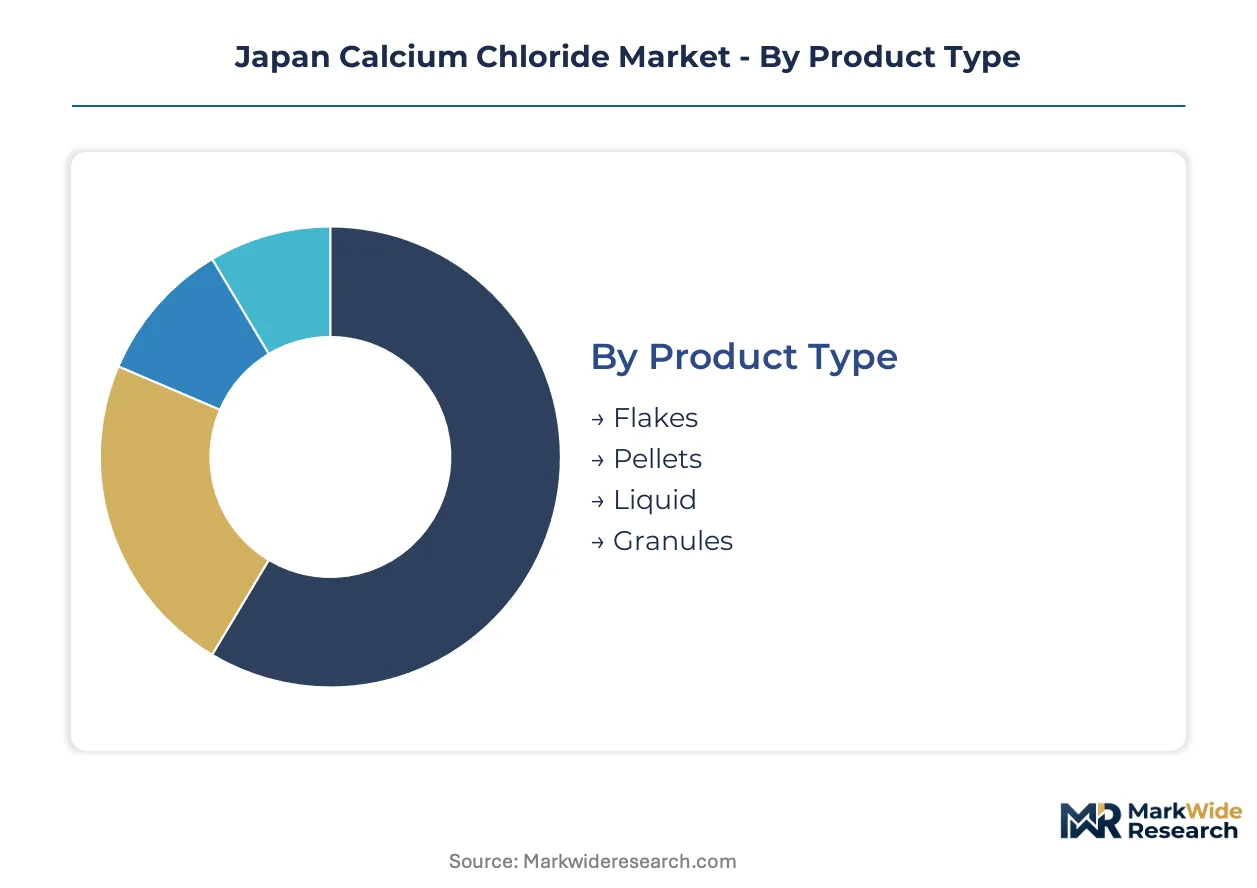
Calcium chloride supply chains in Japan fragment across four distinct dimensions, each governing procurement patterns and margin capture. Product format dictates logistics infrastructure requirements. Application segments separate seasonal from year-round demand. End-user concentration determines certification burdens. Distribution channel selection reflects buyer scale and geographic dispersion.
Product Type:
Domestic production capacity clusters around solid formulations, with liquid processing requiring specialized dissolution and tank-car infrastructure.
- Flakes:Hygroscopic flat crystals with high surface area enable rapid brine formation for road de-icing. Hokkaido municipal consortia procure flake formulations under multi-year framework agreements to secure winter supply certainty.
- Pellets:Spherical, low-dust granules with controlled dissolution rates suit automated spreading equipment. Tohoku highway departments favor pellet delivery for reduced application labor and storage stability across extended seasons.
- Liquid:Pre-dissolved calcium chloride eliminates on-site handling equipment for industrial buyers. Kanto chemical manufacturers adopt tank-car delivery for dissolution-ready feedstock.
- Granules:Coarse crystalline form with intermediate dissolution kinetics serves dust control applications. Agricultural buyers in northern prefectures specify granules for soil stabilization.
Flakes absorb the bulk of installed capacity; liquid is expanding most quickly.
Application:
Demand cycles diverge sharply between weather-dependent outdoor uses and climate-controlled industrial processes.
- De-icing:Freezing-point depression of calcium chloride brines enables effective road treatment at temperatures below sodium chloride limits. Extended winter seasons across Hokkaido and Tohoku intensify municipal procurement volumes.
- Dust Control:Hygroscopic properties bind unpaved road surface particles, suppressing particulate emissions. Mining and construction sites in rural prefectures deploy calcium chloride where water scarcity limits alternative suppression methods.
- Food Preservation:Food-grade calcium chloride functions as a firming agent in processed vegetables and tofu production. METI purity mandates elevate documentation burdens, favoring JIS-certified domestic suppliers.
- Desiccant:Anhydrous grades scavenge moisture in packaging and storage applications. Electronics and pharmaceutical manufacturers specify desiccant-grade material for humidity-sensitive product protection.
De-icing commands peak seasonal volumes; food preservation is climbing the fastest.
End User:
Buyer sophistication separates commodity procurement from certified supply relationships with audit requirements.
- Construction:Cement acceleration applications demand consistent chloride content for predictable set-time modification. Tohoku reconstruction infrastructure creates sustained demand outside de-icing seasonality.
- Chemical Manufacturing:High-purity grades serve as reagents and process chemicals in organic synthesis. Chlor-alkali producers with captive calcium chloride supply leverage backward integration for cost stability.
- Food Industry:Additive applications mandate residue testing and purity documentation under national food safety protocols. Major food manufacturers consolidate supplier relationships toward certified domestic sources.
- Agriculture:Soil amendment and dust suppression applications tolerate lower purity grades with reduced certification overhead. Regional agricultural cooperatives in northern prefectures procure through wholesale channels.
Construction absorbs the bulk of industrial-grade capacity; food industry certification requirements are expanding most quickly.
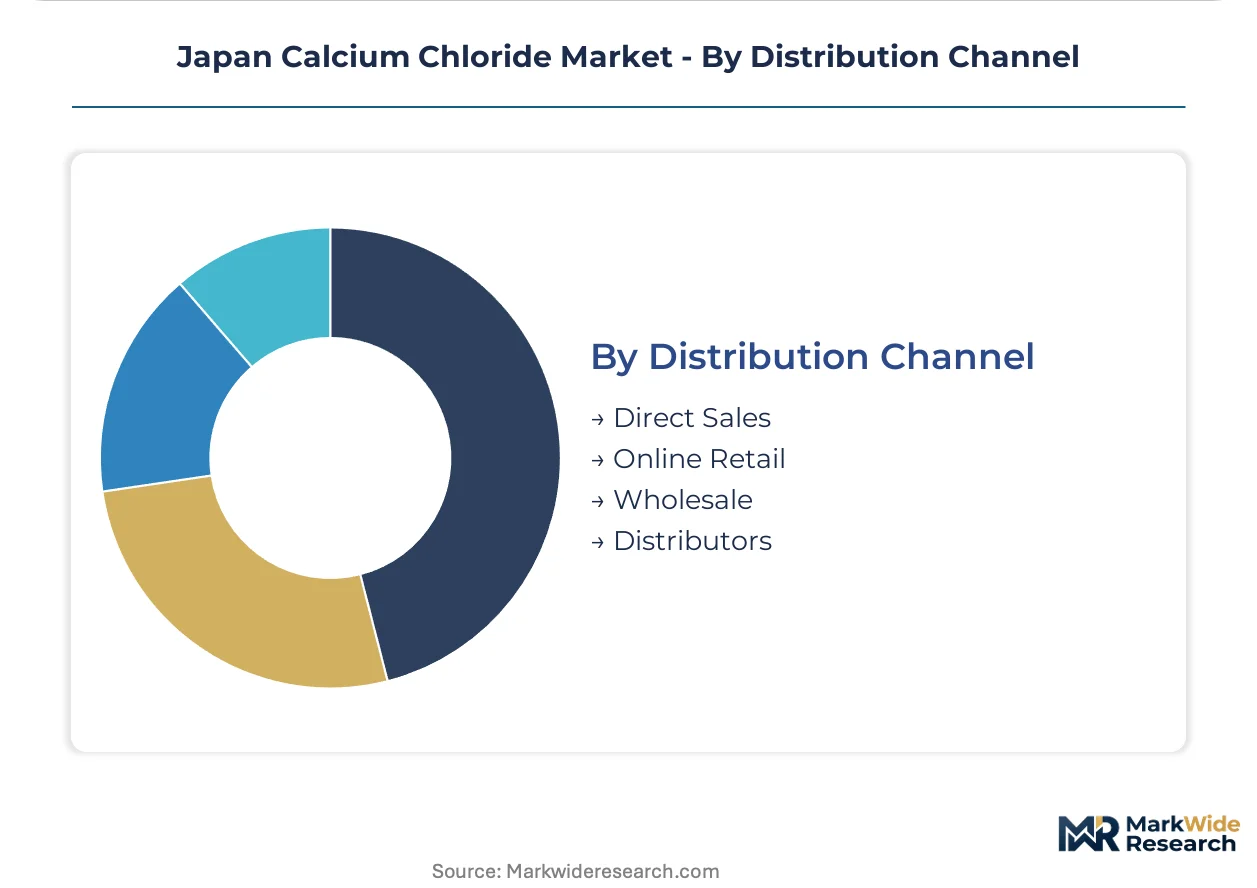
Distribution Channel:
Channel selection correlates with buyer scale, with large-volume municipal and industrial procurement bypassing intermediaries.
- Direct Sales:Producer-to-buyer relationships dominate municipal consortia and large chemical manufacturer accounts. Long-term supply agreements with prefectural bidding platforms displace spot-market transactions.
- Online Retail:E-commerce penetration remains limited to small-scale agricultural and specialty desiccant buyers. Packaging and moisture-control logistics constrain digital channel growth for bulk material.
- Wholesale:Regional distributors aggregate fragmented agricultural and small construction demand across multi-prefecture territories. Inventory positioning in northern hubs addresses seasonal surge requirements.
- Distributors:Specialized chemical distributors serve mid-scale industrial buyers requiring technical specification support. Value-added services include JIS certification documentation and application guidance.
Direct sales absorb the bulk of volume throughput; distributor technical services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlor-alkali production clusters along Japan's industrial corridor anchor calcium chloride supply geography. Hokkaido and Tohoku prefectures concentrate winter de-icing demand. Kanto chemical manufacturing absorbs high-purity industrial grades.
Hokkaido
Municipal highway departments procure flake and pellet formulations under prefectural consortia for extended de-icing seasons. METI's chemical substance management frameworks govern procurement specifications for road maintenance materials. Sapporo anchors northern distribution infrastructure serving consolidated buyer networks.
Tohoku
Reconstruction infrastructure projects generate year-round cement acceleration demand outside seasonal de-icing cycles. JIS standards certification requirements elevate compliance costs for construction-grade material. Sendai functions as the regional logistics hub coordinating multi-prefecture supply to highway departments and construction sites.
Kanto
Pharmaceutical and fine chemical manufacturers in the Tokyo metropolitan area adopt tank-car delivery systems for dissolution-ready liquid formulations. National food safety protocols mandate residue testing and additive purity thresholds for food-grade applications. Kawasaki industrial zones concentrate chemical manufacturing demand for high-purity reagent grades.
Chubu
Chlor-alkali producers leverage captive chlorine supply to stabilize raw material costs across volatile energy markets. METI oversees industrial safety standards for electrolytic production facilities. Nagoya manufacturing clusters sustain industrial-grade consumption for organic synthesis applications.
Kansai
Food processing manufacturers consolidate supplier relationships toward JIS-certified domestic sources to streamline compliance workflows. Purity documentation requirements favor established quality systems over imported material. Osaka anchors western Japan distribution networks serving food industry end users.
Japan Calcium Chloride Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized certification niches and liquid formulation services. The market structures around three to four domestic incumbents with chlor-alkali integration and a fragmented import-dependent fringe. Strategic archetypes include backward-integrated chemical conglomerates, regional distribution specialists, and quality-certified food-grade suppliers. Dominant competitive moves involve multi-year framework agreements with prefectural consortia and JIS certification investments for premium segment access.
Within the integrated producer tier, Nippon Soda Co., Ltd. and Tokuyama exemplify captive feedstock strategies that insulate margin structures from electricity pricing volatility. Fuji Kasei and Tateyama Chemical Co., Ltd. occupy positions serving consolidated municipal buyers and chemical manufacturing end users respectively. These four entities anchor competitive dynamics through differentiated access to either raw material security or certified quality systems.
| Leading Market Players |
|---|
| Fuji Kasei |
| OxyChem Corporation |
| Tateyama Chemical Co., Ltd. |
| Ward Chemical Ltd. |
| Zirax Limited |
| Nippon Soda Co., Ltd. |
| TETRA Chemicals Europe AB |
| Tiger Calcium Services Inc. |
| Tokuyama |
| Others |
Cost & Logistics Intelligence
Liquid formulation adoption in Kanto chemical manufacturing is compressing traditional handling-margin structures while simultaneously concentrating procurement power among tank-car-equipped buyers. This format shift rewards producers with dissolution infrastructure and penalizes solid-only suppliers, restructuring price-setting leverage across the value chain.
Pricing Analysis
Logistics-service bundling separates tank-car delivery agreements from unbundled flake procurement where buyers arrange their own moisture-controlled transport. Three-tier pricing structure across premium, standard, and economy levels governs the market: JIS-certified food-grade commands top tier, construction-grade industrial material occupies mid-tier, and uncertified imports fill economy segments. Cost compression in standard-tier flake supply is intensifying because prefectural consortia consolidate volume commitments and squeeze spot-market flexibility. Municipal road authorities in Hokkaido exhibit lowest price sensitivity due to supply-security priorities, while small agricultural cooperatives in northern prefectures remain most price-sensitive.
Supply Chain Analysis
Certification gating through METI chemical substance frameworks and JIS standards elevates compliance timelines and documentation burdens, favoring established domestic producers with certified quality systems. Production concentrates in Japan's Chubu and Kanto industrial corridors, with supplemental draw from South Korean chlor-alkali complexes for spot-market liquid supply. Captive chlorine feedstock, electricity inputs, and hygroscopic transport infrastructure form critical dependencies. Single-source vulnerability runs through electrolytic production exposed to Japanese electricity pricing swings. Distribution runs through direct producer-to-buyer relationships for municipal consortia and large chemical manufacturers, with regional wholesalers serving fragmented agricultural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prefectural consolidation of procurement functions is compressing supplier counts and forcing marginal players toward exit, as volume-commitment contracts favor producers with certified quality systems and captive feedstock security.
For Market Incumbents: Cement multi-year framework agreements with Hokkaido and Tohoku prefectural consortia before competitive bidding windows close. Deepen backward integration into captive chlorine supply to insulate margin structures from electricity volatility threatening electrolytic producers. METI's tightening purity mandates present a certification investment lever to capture food-grade share from import-dependent competitors lacking JIS documentation workflows. For New Entrants and Emerging Players: E-commerce channels for small-scale desiccant and specialty agricultural buyers offer a low-capital entry route bypassing direct competition with tank-car-equipped incumbents. Target dust control applications in rural mining and construction sites where magnesium chloride substitution has not yet displaced calcium chloride adoption. A technical specification support model—providing JIS certification documentation and application guidance—differentiates against commodity wholesalers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by chlor-alkali conglomerates seeking geographic expansion or certification-ready food-grade capacity. Long-term viability favors producers with integrated feedstock, established METI compliance workflows, and locked municipal supply contracts. Watch for inflection when prefectural consortia complete their transition from spot-market procurement to exclusive multi-year agreements, signaling which suppliers have secured sustainable volume foundations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorine Feedstock | Captive electrolytic supply insulates Nippon Soda and Tokuyama from electricity volatility compressing margins. |
| JIS Certification Investment | Food-grade documentation workflows capture additive share from import competitors lacking METI compliance infrastructure. |
| Long-term Supply Agreement | Prefectural consortia in Hokkaido displace spot-market transactions with volume-commitment contracts favoring established producers. |
| Liquid Formulation Capacity Expansion | Tank-car delivery systems in Kanto reduce handling costs for pharmaceutical and fine chemical manufacturers. |
| Regional Distribution Hub Consolidation | Sapporo and Sendai logistics positioning addresses seasonal surge requirements across northern prefecture networks. |
Research Approach
Trade statistics from Japan Customs, METI chemical production surveys, and JIS certification registries formed the secondary backbone of this analysis. Primary interviews with chlor-alkali plant managers, prefectural road maintenance procurement officers, food industry additive buyers, and specialized chemical distributors validated demand assumptions and pricing dynamics. Bottom-up volume estimates by product format and application triangulated against top-down market sizing derived from electrolytic capacity and consumption intensity ratios.
Historical trendline analysis across production volumes, import flows, and end-use consumption patterns established baseline growth trajectories. The forecast framework models demand across product type, application segment, end-user industry, and regional prefecture cluster throughout the projection horizon. CAGRs derive from segmented growth rate assumptions calibrated to infrastructure spending cycles, winter severity indices, and food processing output trends. Chlor-alkali capacity utilization rates and electricity pricing sensitivity inform supply-side constraints.
The model holds under stable METI regulatory enforcement and continued prefectural procurement consolidation; deviation in energy market volatility or magnesium chloride substitution acceleration would shift volume and value trajectories. Forecasts reflect documented assumptions regarding winter season extension patterns and food-grade certification adoption rates. A model refresh is warranted upon material change in METI chemical substance management frameworks or prefectural bidding platform consolidation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Aniline Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Phthalic Anhydride Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Calcium Chloride Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Benzyl Chloride Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Ethyl Mercaptan Market