
 In-Vitro Diagnostics Enzymes Market | 2026-2036
In-Vitro Diagnostics Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vitro Diagnostics Enzymes Market Intelligence
Reagent kit manufacturing revenue is fragmenting as contract enzyme suppliers and in-house formulation teams compete for margin capture. Thermo Fisher Scientific leverages its vertical integration across raw enzyme production and diagnostic platform sales to sustain pricing power. Merck KGaA anchors its position through pharmaceutical-grade enzyme supply chains that extend into clinical diagnostics. Amano Enzyme Inc. specializes in microbial fermentation-derived biocatalysts that differentiate on batch consistency and regulatory documentation.
In-vitro diagnostics enzymes are biological catalysts—typically proteins purified to specific activity units per milligram—that accelerate biochemical reactions in controlled laboratory settings for disease detection and monitoring. These enzymes operate within narrow pH and temperature ranges, with manufacturers specifying kinetic parameters such as Km and Vmax to ensure reproducible performance across automated analyzers. Proteases and amylases dominate the product type landscape due to their established roles in clinical chemistry and microbiology assays. The technology dimension shows PCR applications commanding premium positioning as molecular diagnostics expands, while immunoassay-linked enzymes occupy mature, volume-driven segments. Application-level demand for clinical chemistry enzymes remains structurally entrenched in hospital and reference laboratory workflows.
The FDA oversees enzyme-based diagnostic reagents through in vitro diagnostic device regulations, while the EMA's In Vitro Diagnostic Medical Devices Regulation in Europe tightens performance documentation requirements for imported enzyme components. ISO 13485 quality management standards govern manufacturing processes, creating compliance barriers that favor suppliers with established certification infrastructure. Stakeholders must monitor how evolving premarket notification pathways and regional quality system mandates reshape supplier qualification criteria and procurement decision frameworks.
Market Dynamics
Reference laboratories in the United States are consolidating procurement of high-activity enzyme formulations, compressing supplier margins while demanding batch-to-batch consistency documentation that only vertically integrated manufacturers can reliably deliver.
Growth Catalysts
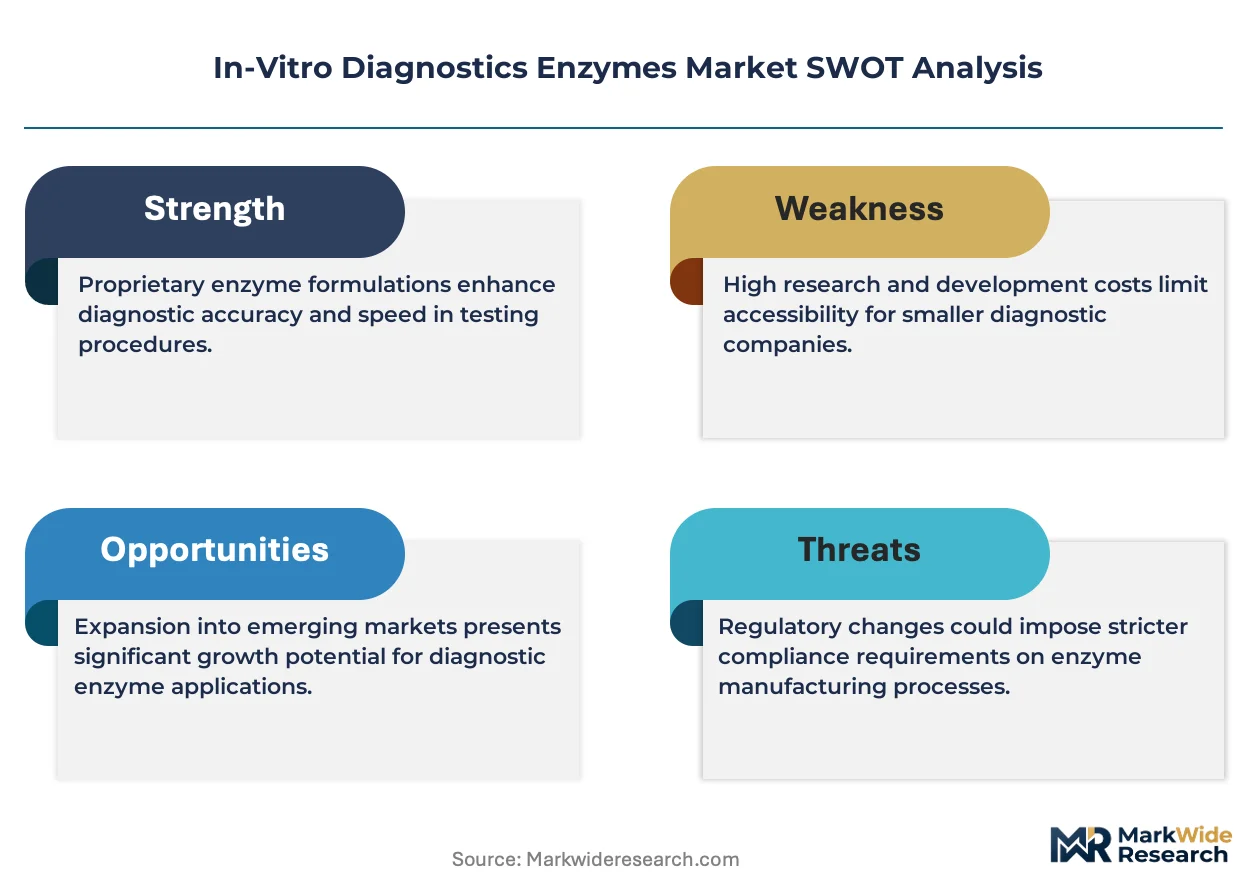
- IVDR implementation in Europe:The EMA's tightened performance documentation requirements for imported enzyme components are accelerating supplier qualification investments among established manufacturers, filtering out marginal competitors.
- Point-of-care molecular diagnostics:PCR-based infectious disease panels are expanding enzyme consumption per test as multiplexing complexity increases, driving demand for thermostable polymerases with defined kinetic parameters.
- Hospital laboratory centralization:Health system consolidation across Germany, France, and the United Kingdom is creating volume concentration that favors long-term supply agreements with certified enzyme suppliers.
Market Restraints
- Fermentation input volatility:Pharmaceutical-grade yeast extract and defined media components face price instability from agricultural commodity swings, compressing gross margins for microbial-derived enzyme producers.
- Single-source fermentation capacity:Contract manufacturing for clinical-grade enzymes concentrates among three dominant European CDMO clusters, creating geographic supply risk for North American diagnostic firms.
- Protein stability limitations:Liquid-format enzymes require cold-chain distribution infrastructure that remains underdeveloped in secondary clinical laboratory markets, constraining addressable geography.
Strategic Opportunities
- India's diagnostic infrastructure buildout:CDSCO's streamlined medical device registration pathways and government-funded health screening programs are creating first-mover advantage for enzyme suppliers establishing local formulation capabilities.
- CRISPR-diagnostic convergence:Cas enzyme integration with isothermal amplification chemistries is opening new assay architectures beyond traditional PCR workflows, requiring novel enzyme engineering partnerships.
- ISO 13485 certification arbitrage:Smaller fermentation specialists in South Korea and Japan are acquiring quality management infrastructure to qualify for European reference laboratory supplier lists previously dominated by North American incumbents.
Industry Challenges
- Bioprocess engineering talent scarcity:Clinical-grade enzyme manufacturing requires hybrid skills spanning microbial physiology, downstream purification, and regulatory documentation that academic programs produce insufficiently.
- Legacy analyzer compatibility:New enzyme formulations must demonstrate kinetic equivalence across multiple generations of automated clinical chemistry platforms, extending validation timelines.
- Multi-jurisdiction dossier maintenance:Simultaneous FDA premarket notification, EMA technical documentation, and NMPA registration in China creates parallel compliance cost burdens without harmonized submission formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vitro Diagnostics Enzymes Market |
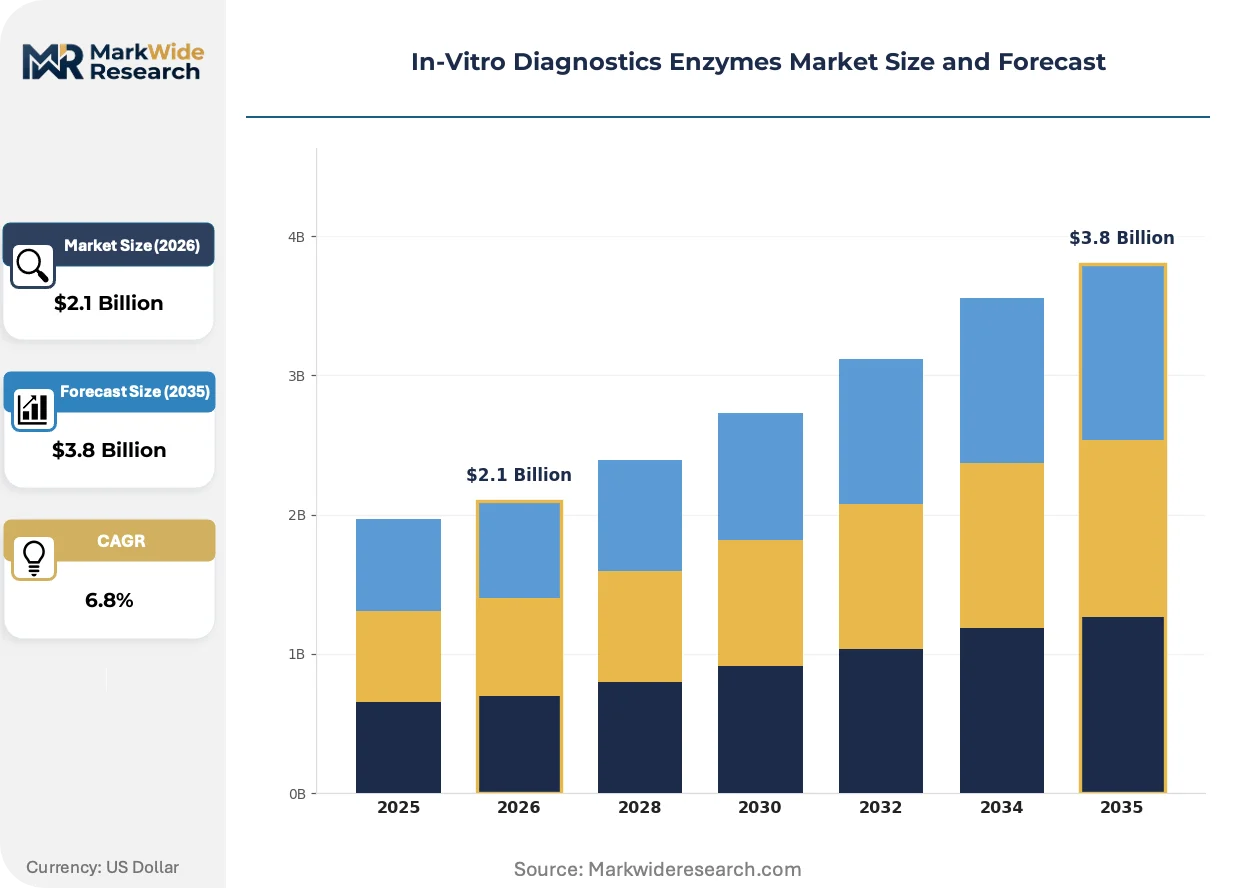
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylases, Lipases, Proteases, Lactate Dehydrogenase Technology: Immunoassays, Chromatography, PCR, Mass Spectrometry Application: Clinical Chemistry, Molecular Diagnostics, Microbiology, Hematology End User: Hospitals, Clinical Laboratories, Research Institutes, Diagnostic Centers |
| Companies Covered | Merck KGaA, F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific, Codexis, Inc., Amano Enzyme Inc., Advanced Enzymes Technologies Ltd., Biocatalysts Ltd., BBI Solutions, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vitro Diagnostics Enzymes Market Strategic Shifts & Innovations
Enzyme engineering and assay automation are converging to redefine performance specifications, with digital integration of quality control data now separating qualified suppliers from commodity competitors.
Lyophilized enzyme master mixes with embedded internal controls are digitizing quality assurance workflows by embedding lot-specific kinetic data directly into laboratory information systems. Mid-sized clinical laboratories in Spain and Italy are adopting these formats fastest, eliminating manual calibration steps while compressing assay setup time. This standardization is digitizing procurement decisions around certificate-of-analysis accessibility rather than unit pricing alone.
The FDA's evolving guidance on laboratory-developed tests is tightening analytical validation requirements for enzyme-based reagents used in internally developed assays. Diagnostic platform manufacturers must now supply more extensive stability and interference data, increasing documentation burden. High-complexity molecular diagnostics laboratories in the United States are responding by consolidating supplier relationships around vendors with dedicated regulatory affairs infrastructure.
Reference laboratories are unbundling after-sales technical support from reagent contracts, purchasing enzymes on commodity terms while sourcing application expertise through separate consulting arrangements. This disintermediation pressures traditional full-service suppliers in France and Germany to defend positioning through performance guarantees rather than bundled service. The shift is most visible among hospital networks consolidating testing across multiple sites under single procurement umbrellas.
In-Vitro Diagnostics Enzymes Market Segmentation
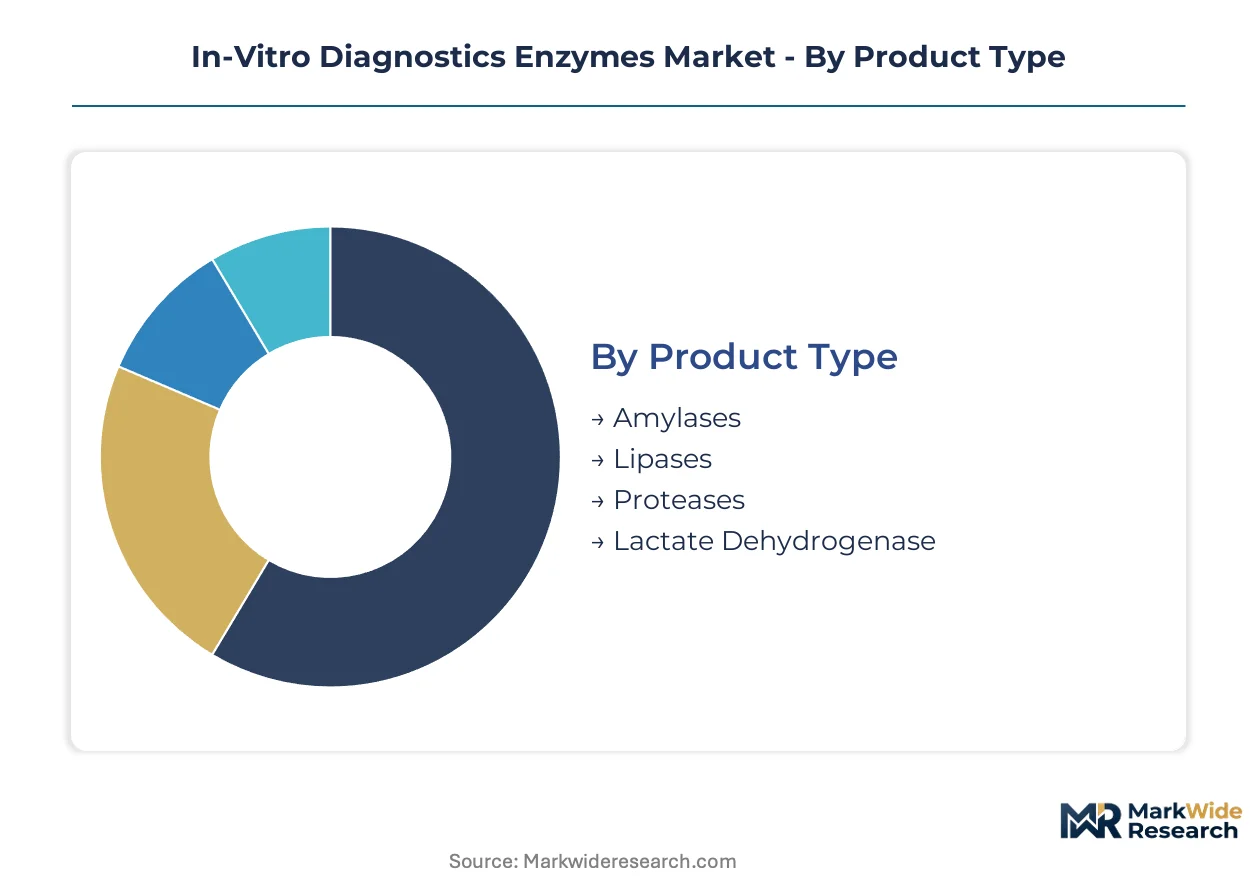
Segmentation in the In-Vitro Diagnostics Enzymes Market reveals distinct service intensity requirements across product categories. Technical support demands vary sharply between standardized clinical chemistry reagents and complex molecular diagnostics formulations.
Product Type:
After-sales technical support intensity correlates directly with enzyme stability profiles and regulatory documentation burdens.
- Proteases:These enzymes catalyze peptide bond hydrolysis with defined pH optima and temperature stability windows specified in USP-grade monographs. Hospital laboratories in the United States concentrate demand for broad-spectrum protease formulations used in coagulation and therapeutic drug monitoring assays, driven by consolidation of high-throughput chemistry platforms. By volume, Proteases leads. By growth pace, Lactate Dehydrogenase is ahead.
- Amylases:Alpha-amylase and pancreatic amylase variants serve diagnostic quantification of pancreatic function and salivary gland disorders. Reference laboratories in Germany and France prioritize liquid-stable formulations with extended open-vial stability, constrained by cold-chain infrastructure gaps in peripheral collection sites.
- Lipases:Pancreatic lipase catalytic activity measurements support acute pancreatitis diagnosis with lipase-specific substrates replacing older amylase-based protocols.
- Lactate Dehydrogenase:LDH isoenzyme profiling requires precise temperature-controlled reaction kinetics for myocardial infarction and hemolysis differential diagnosis.
Cost tier differentiation separates pharmaceutical-grade from research-grade specifications, with clinical laboratories absorbing premium pricing for batch-certified formulations.
Technology:
Application maturity determines margin structure, with established immunoassay formats facing price compression against premium-positioned molecular methods.
- PCR:Thermostable DNA polymerases with proofreading activity and defined processivity rates enable infectious disease panel expansion. Point-of-care molecular diagnostics in the United Kingdom and Spain are driving consumption of lyophilized master mixes with embedded internal controls, constrained by thermocycler platform compatibility requirements.
- Immunoassays:Horseradish peroxidase and alkaline phosphatase conjugates dominate enzyme-linked detection with standardized activity unit definitions. Clinical chemistry laboratories in Japan prioritize signal-to-noise optimization for high-sensitivity cardiac troponin assays, facing pressure from chemiluminescence displacement.
- Chromatography:Enzymatic detection post-separation supports specialized metabolic and toxicology applications.
- Mass Spectrometry:Enzymatic digestion workflows for proteomic and metabolomic clinical applications require sequencing-grade specificity.
Customer type concentration favors hospital networks for PCR, while independent laboratories sustain immunoassay volume.
Application:
Supply concentration shapes procurement leverage, with molecular diagnostics consolidating around qualified polymerase suppliers while clinical chemistry fragments across commodity enzyme sources.
- Clinical Chemistry:Enzymatic assays for glucose, cholesterol, and liver function panels constitute the installed base of automated analyzers. Hospital networks in Italy and the Netherlands are centralizing reagent procurement under five-year framework agreements, demanding kinetic equivalence documentation across analyzer generations.
- Molecular Diagnostics:Nucleic acid amplification and detection workflows require engineered enzymes with modified thermal stability and inhibitor tolerance. High-complexity laboratories in the United States are qualifying second-source polymerase suppliers to mitigate single-source dependency risks.
- Microbiology:Enzymatic identification panels and susceptibility testing support culture-based diagnostic workflows.
- Hematology:Enzymatic reagents for coagulation factor assays and hemoglobin variant detection serve specialized reference testing.
Geographic deployment patterns show clinical chemistry entrenched in mature markets, with molecular diagnostics expanding fastest in Asia-Pacific.
End User:
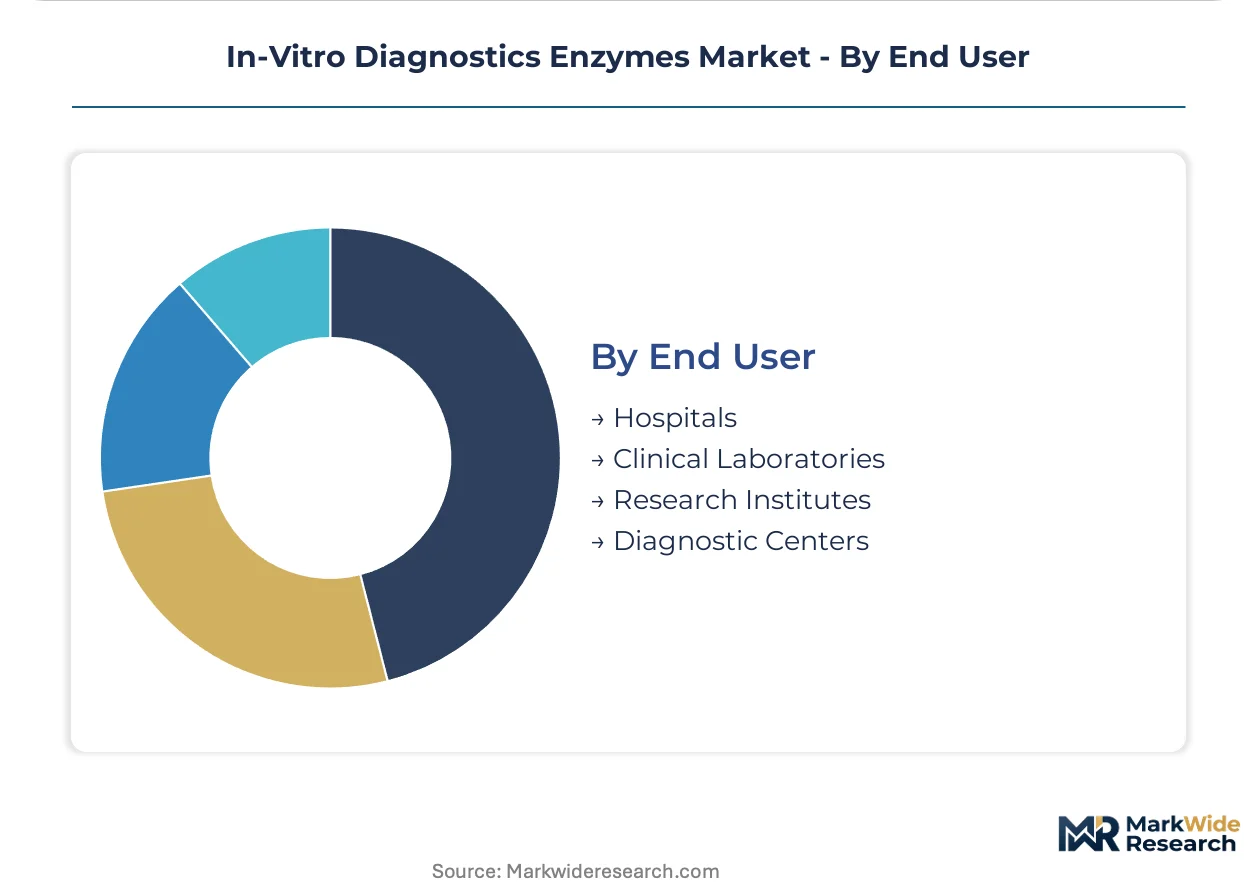
Volume scale separates procurement behavior, with reference laboratories negotiating bulk enzyme formulations against diagnostic centers purchasing kit-format reagents.
- Clinical Laboratories:Reference and hospital-affiliated laboratories process the highest test volumes with automated platform integration. Quest Diagnostics and LabCorp procurement specifications in the United States are standardizing certificate-of-analysis data formats, accelerating supplier qualification investments.
- Hospitals:Acute care settings demand rapid-turnaround enzymatic assays with minimal pre-analytical handling. German hospital networks are consolidating point-of-care testing governance under central laboratory oversight, constraining decentralized enzyme purchasing autonomy.
- Diagnostic Centers:Specialized outpatient facilities focus on wellness screening and chronic disease monitoring applications.
- Research Institutes:Academic and commercial R&D operations consume non-GMP enzymes for assay development and biomarker discovery.
Margin structure inverts across the customer base, with research institutes accepting variable pricing and clinical laboratories enforcing cost-per-test caps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts, with hospital networks in mature markets demanding certificate-of-analysis standardization while emerging-market buyers prioritize cold-chain reliability over kinetic documentation. Reference laboratories in the United States absorb premium pricing for batch-certified formulations, whereas diagnostic centers in India and Southeast Asia trade specification depth for supply security.
United States
Quest Diagnostics and LabCorp procurement specifications are standardizing certificate-of-analysis data formats, forcing supplier qualification investments. The FDA's evolving premarket notification pathways for laboratory-developed tests tighten analytical validation requirements. High-complexity molecular diagnostics laboratories in Massachusetts and California consolidate supplier relationships around vendors with dedicated regulatory affairs infrastructure.
Germany
Hospital networks centralize point-of-care testing governance under central laboratory oversight, constraining decentralized enzyme purchasing autonomy. The EMA's In Vitro Diagnostic Medical Devices Regulation tightens performance documentation requirements for imported enzyme components. Reference laboratories in Bavaria and North Rhine-Westphalia prioritize liquid-stable formulations with extended open-vial stability for peripheral collection site coverage.
China
Domestic diagnostic platform manufacturers scale enzyme consumption as infectious disease panel expansion accelerates. The NMPA registration process creates parallel compliance cost burdens without harmonized submission formats. Bioprocess engineering clusters in Jiangsu and Zhejiang provinces concentrate microbial fermentation capacity for clinical-grade enzyme production.
India
Government-funded health screening programs drive diagnostic infrastructure buildout, creating first-mover advantage for enzyme suppliers establishing local formulation capabilities. CDSCO's streamlined medical device registration pathways reduce market entry friction. Contract manufacturing partnerships in Maharashtra and Karnataka concentrate reagent kit assembly for regional distribution.
Japan
Clinical chemistry laboratories prioritize signal-to-noise optimization for high-sensitivity cardiac troponin assays, facing pressure from chemiluminescence displacement. The PMDA maintains stringent stability and interference data requirements for enzyme-based reagents. Fermentation specialists in the Kansai region acquire ISO 13485 certification infrastructure to qualify for European reference laboratory supplier lists.
In-Vitro Diagnostics Enzymes Market Key Industry Players
Capability concentration sits with vertically integrated life science conglomerates; scale advantage sits with specialized fermentation houses serving diagnostic reagent manufacturers. The market structures around three tiers: pharmaceutical-grade enzyme suppliers anchoring premium positioning, microbial fermentation specialists competing on batch consistency, and contract research organizations enabling custom enzyme engineering. Consolidation pressure intensifies as reference laboratory procurement centralization favors long-term supply agreements with certified suppliers. Strategic moves concentrate on backward integration into raw enzyme production and geographic expansion through quality management certification arbitrage.
Among diversified life science conglomerates, Merck KGaA and Thermo Fisher Scientific exemplify the vertically integrated archetype, combining raw enzyme production with diagnostic platform sales. Specialized microbial fermentation houses occupy a distinct tier, with Amano Enzyme Inc. representing the batch-consistency-focused positioning that differentiates on regulatory documentation depth. These three anchors illustrate how supplier qualification investments and quality management infrastructure separate qualified competitors from commodity enzyme sources.
| Leading Market Players |
|---|
| Merck KGaA |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific |
| Codexis, Inc. |
| Amano Enzyme Inc. |
| Advanced Enzymes Technologies Ltd. |
| Biocatalysts Ltd. |
| BBI Solutions |
| QIAGEN |
| Others |
Cost & Logistics Intelligence
Overcapacity in European contract fermentation clusters is compressing spot-market enzyme prices while tightening margins for microbial-derived biocatalyst suppliers. This utilization imbalance rewards vertically integrated manufacturers with captive production assets, forcing commodity suppliers toward long-term offtake contracts with reference laboratories.
Pricing Analysis
Long-term offtake agreements dominate procurement between reference laboratories and certified enzyme suppliers, displacing spot purchasing for high-activity formulations. Pricing stratifies across pharmaceutical-grade, clinical-grade, and research-grade certification tiers, with ISO 13485 documentation commanding substantial premiums. Cost compression in liquid-stable formats is intensifying because cold-chain infrastructure investments lag demand expansion in secondary markets. Hospital networks in Germany and the United States exhibit lowest price sensitivity, while diagnostic centers in India and Southeast Asia prioritize supply security over kinetic documentation depth.
Supply Chain Analysis
Tariff exposure between the United States and European Union member states dominates supply chain risk planning for clinical-grade enzyme importers. Manufacturing concentrates in Germany, Switzerland, and Japan for pharmaceutical-grade specifications, with microbial fermentation capacity clustering in Jiangsu and Zhejiang provinces of China. Production draws from pharmaceutical-grade yeast extract, defined fermentation media, and purified water systems as critical inputs. Single-source vulnerability concentrates among three dominant European CDMO clusters serving North American diagnostic firms. Distribution runs through direct manufacturer-to-laboratory channels for bulk formulations, with regional distributors handling kit-format reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid skill gaps spanning microbial physiology, downstream purification, and regulatory documentation constrain supplier expansion, creating durable competitive moats for incumbents with established training pipelines and quality infrastructure.
For Market Incumbents: Insulate margin position by deepening backward integration into raw enzyme production and acquiring ISO 13485-certified fermentation capacity in South Korea or Japan to arbitrage European reference laboratory supplier lists. Consolidate procurement relationships with Quest Diagnostics and LabCorp through standardized certificate-of-analysis data formats that marginalize smaller competitors lacking regulatory affairs infrastructure. For New Entrants and Emerging Players: Pursue CDSCO-registered local formulation capabilities in Maharashtra and Karnataka to capture government-funded health screening program demand in India before incumbent suppliers establish regional assembly. Target point-of-care molecular diagnostics in Spain and Italy with lyophilized master mixes featuring embedded internal controls, leveraging faster adoption curves in mid-sized clinical laboratories seeking assay setup time compression. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across CRISPR-diagnostic convergence sub-segments as Cas enzyme engineering partnerships require dedicated R&D infrastructure and novel assay architecture investments. Viable acquisition targets include microbial fermentation specialists with batch consistency documentation depth and existing relationships with diagnostic platform manufacturers. Watch for FDA premarket notification pathway revisions affecting laboratory-developed test validation requirements as the signal indicating supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Arbitrage | Japanese and South Korean fermentation specialists qualify for European reference laboratory supplier lists previously closed to them. |
| Lyophilized Master Mix Development | Laboratories in Spain and Italy eliminate manual calibration steps through lot-specific kinetic data embedded in information systems. |
| Backward Integration into Fermentation | Thermo Fisher Scientific and Merck KGaA sustain pricing power through captive supply of high-activity enzyme formulations. |
| CRISPR-Diagnostic Partnership Formation | Cas enzyme integration with isothermal amplification chemistries opens assay architectures beyond traditional PCR workflows. |
| Local Formulation Capacity Establishment | CDSCO registration pathways in Maharashtra and Karnataka enable first-mover capture of India's government-funded screening programs. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings in this analysis. Conversations with diagnostic platform manufacturers, reference laboratory procurement directors, bioprocess engineering leads, and regulatory affairs specialists informed supplier behavior and qualification investment patterns. Secondary sources include FDA premarket notification databases, EMA technical documentation filings, CDSCO medical device registration records, and ISO 13485 certification registries. Bottom-up enzyme consumption modeling triangulates against top-down diagnostic test volume projections across automated analyzer and molecular diagnostics platforms.
Calibration against historical price realizations for pharmaceutical-grade versus clinical-grade enzyme tiers validates the analytical framework across the projection horizon. Segmentation dimensions span product type, technology platform, application area, and end-user procurement scale, with regional regulatory cluster effects explicitly modeled. CAGRs derive from test volume expansion rates, assay complexity coefficients, and enzyme consumption per test metrics. Forecast inputs incorporate thermostable polymerase demand curves from infectious disease panel expansion and lyophilized format adoption trajectories in point-of-care settings.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices affecting yeast extract costs or cold-chain logistics capacity would shift the trajectory. Forecasts reflect assumptions around IVDR implementation timelines, FDA laboratory-developed test guidance evolution, and reference laboratory consolidation patterns. Material shifts in bioprocess engineering talent availability or harmonized submission format adoption across FDA, EMA, and NMPA would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Blood Urea Nitrogen Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Anatomic Pathology Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
D-Dimer Market
Diagnostics
Viral Disease Diagnosis Market
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Diagnostic Enzymes Market
Diagnostics
RT-PCR Kits Market