
 North America Antinuclear Antibody Test Market | 2026-2036
North America Antinuclear Antibody Test Market Size, Share, and Industry Trends Forecast 2026-2036
North America Antinuclear Antibody Test Market Analytics
Hospital procurement networks across North America are reshaping how antinuclear antibody tests reach end users, with integrated delivery networks consolidating purchasing decisions for immunofluorescence and ELISA platforms. Thermo Fisher Scientific leverages its diagnostic reagent manufacturing scale to supply high-throughput laboratories with standardized assay kits. Bio-Rad Laboratories anchors its position through sustained investment in quality control materials that laboratories require for CLIA-compliant ANA testing workflows. Abbott Laboratories competes by extending its automated analyzer installed base into mid-sized hospital labs seeking walkaway immunology capabilities.
An antinuclear antibody test detects autoantibodies directed against nuclear antigens in human serum, typically employing indirect immunofluorescence on HEp-2 cell substrates with titer reporting and pattern interpretation for clinical correlation. These assays serve as frontline screening tools for systemic lupus erythematosus, scleroderma, and mixed connective tissue disease in rheumatology and autoimmune disorder applications. Immunofluorescence remains the gold standard segment where margin pools concentrate due to skilled technologist requirements and interpretive complexity. Automated testing represents the fastest-growing technology dimension as laboratories face staffing constraints and seek to reduce manual microscopy burdens. Point-of-care testing occupies a nascent position with limited current penetration but holds structural interest for rheumatology clinic workflows.
FDA 510(k) premarket notification requirements govern new ANA assay clearances in the United States, while CLIA establishes laboratory quality standards that directly influence instrument and reagent purchasing specifications. Health Canada and the Canadian Standards Association maintain parallel regulatory frameworks that manufacturers must navigate for cross-border market access. Stakeholders should monitor evolving FDA guidance on multiplex autoimmune panels and potential harmonization of international reference standards that could reshape competitive positioning for assay developers.
Market Dynamics
Automated immunofluorescence platforms are collapsing the traditional microscopy bottleneck that has constrained laboratory throughput for decades. CLIA-certified diagnostic laboratories across the United States face mounting pressure to process higher autoimmune screening volumes without proportional staffing expansion.
Growth Catalysts
- CLIA Laboratory Certification Requirements:Federal quality standards mandate rigorous proficiency testing and quality control protocols that drive replacement demand for compliant assay systems. Mid-sized hospital laboratories upgrade instrumentation to maintain accreditation.
- Rheumatology Clinic Expansion:Outpatient autoimmune specialty practices proliferate in metropolitan corridors, generating pull-through demand for standardized ANA screening prior to specialist referral.
- HEp-2 Substrate Automation:Automated slide processing and digital pattern recognition algorithms reduce technologist interpretation time while preserving gold-standard immunofluorescence sensitivity.
Market Restraints
- Skilled Technologist Scarcity:Pattern interpretation expertise requires years of specialized training that laboratory education pipelines cannot replenish at replacement rates.
- Reagent Supply Concentration:Cell substrate manufacturing for HEp-2 slides concentrates among a limited supplier base, creating vulnerability to batch variability or disruption.
- Multiplex Assay Substitution:Solid-phase screening panels threaten to displace traditional immunofluorescence for initial screening in cost-sensitive settings.
Strategic Opportunities
- Canadian Market Penetration:Health Canada regulatory pathways remain less congested than FDA 510(k) queues, offering faster commercialization timelines for novel assay formats.
- Digital Pathology Integration:Cloud-based pattern libraries and telepathology consultation networks enable centralized expertise distribution across distributed laboratory networks.
- Rheumatology Point-of-Care Testing:Near-patient screening workflows in specialty clinics could compress diagnostic timelines for systemic lupus erythematosus suspicion.
Industry Challenges
- Pattern Standardization Delays:International consensus on immunofluorescence reporting nomenclature remains incomplete, complicating multi-site laboratory network harmonization.
- Capital Equipment Refresh Cycles:Automated platform acquisition requires substantial upfront investment that independent laboratories struggle to finance against reimbursement uncertainty.
- Legacy Analyzer Integration:New digital imaging systems must interface with existing laboratory information systems that use incompatible data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Antinuclear Antibody Test Market |
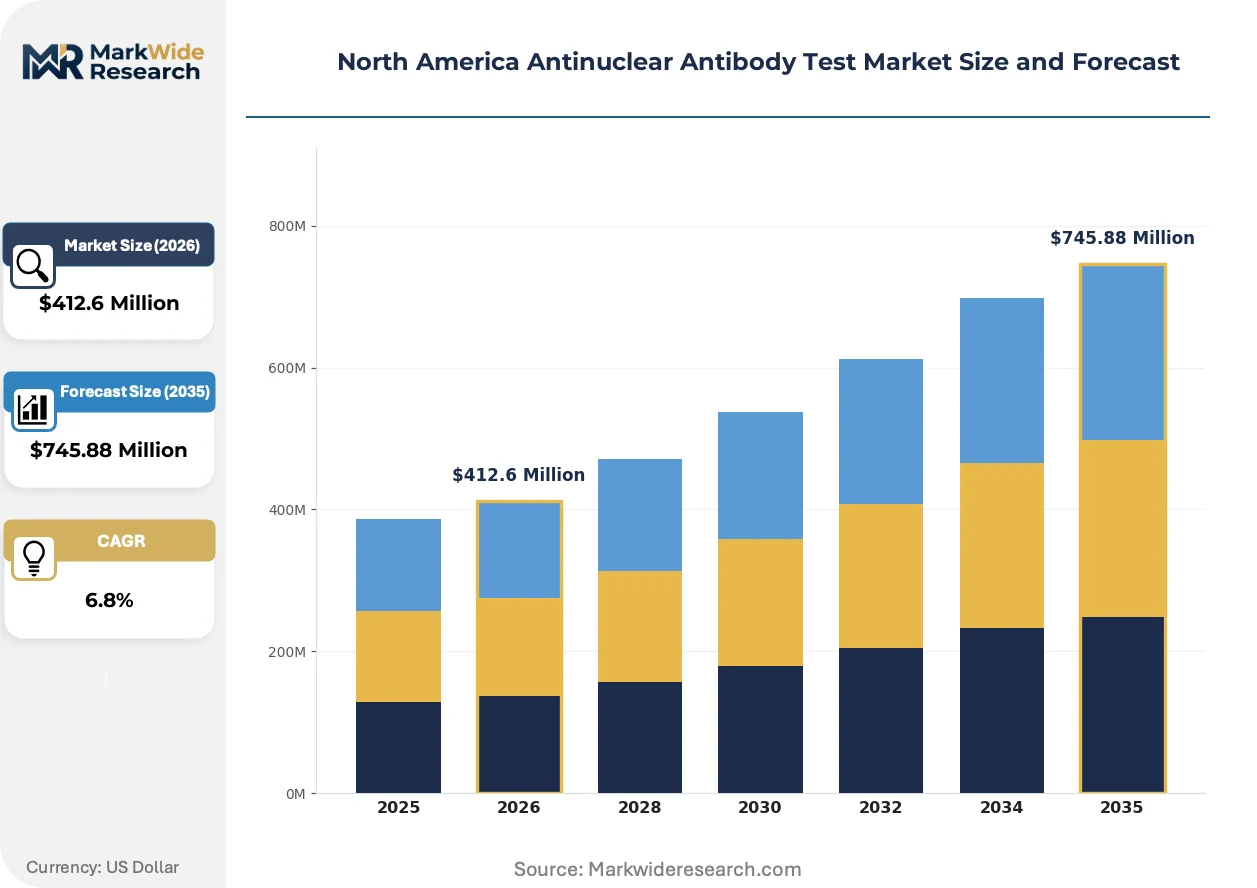
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, Immunofluorescence, Lateral Flow, Western Blot End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinics Technology: Serological Testing, Molecular Testing, Point-of-Care Testing, Automated Testing Application: Rheumatology, Autoimmune Disorders, Infectious Diseases, Cancer |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories Inc., Abbott Laboratories, Trinity Biotech plc, ERBA Diagnostics Inc., Zeus Scientific Inc., Inova Diagnostics, Immuno Concepts, Euroimmun AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Antinuclear Antibody Test Market Evolving Landscape
Artificial intelligence pattern classification and automated slide scanning are compressing the interpretive bottleneck that has limited immunofluorescence scalability. These converging technologies promise to preserve diagnostic accuracy while expanding laboratory capacity.
Digital immunofluorescence imaging with convolutional neural network classification is collapsing the historical trade-off between throughput and pattern specificity. Academic medical centers in Boston and New York deploy these systems to handle escalating autoimmune screening volumes from expanded rheumatology referrals. The technology enables remote interpretation by subspecialist pathologists, redistributing expertise across geographically dispersed laboratory networks.
FDA guidance evolution on multiplex autoimmune diagnostic panels is reshaping competitive positioning between traditional immunofluorescence and alternative screening technologies. The agency's deliberative approach to algorithm-based pattern reporting creates regulatory friction for fully automated systems while preserving space for human-over-the-loop workflows. Manufacturers navigate this uncertainty by pursuing parallel 510(k) pathways that preserve optionality across interpretive models.
Integrated delivery network procurement consolidation is compressing vendor negotiation cycles and standardizing platform selections across multi-hospital systems. Large health systems in the northeastern United States leverage volume commitments to extract favorable reagent pricing and service terms from assay manufacturers. This concentration shifts purchasing influence from individual laboratory directors toward centralized supply chain functions with standardized evaluation criteria.
North America Antinuclear Antibody Test Market Segmentation
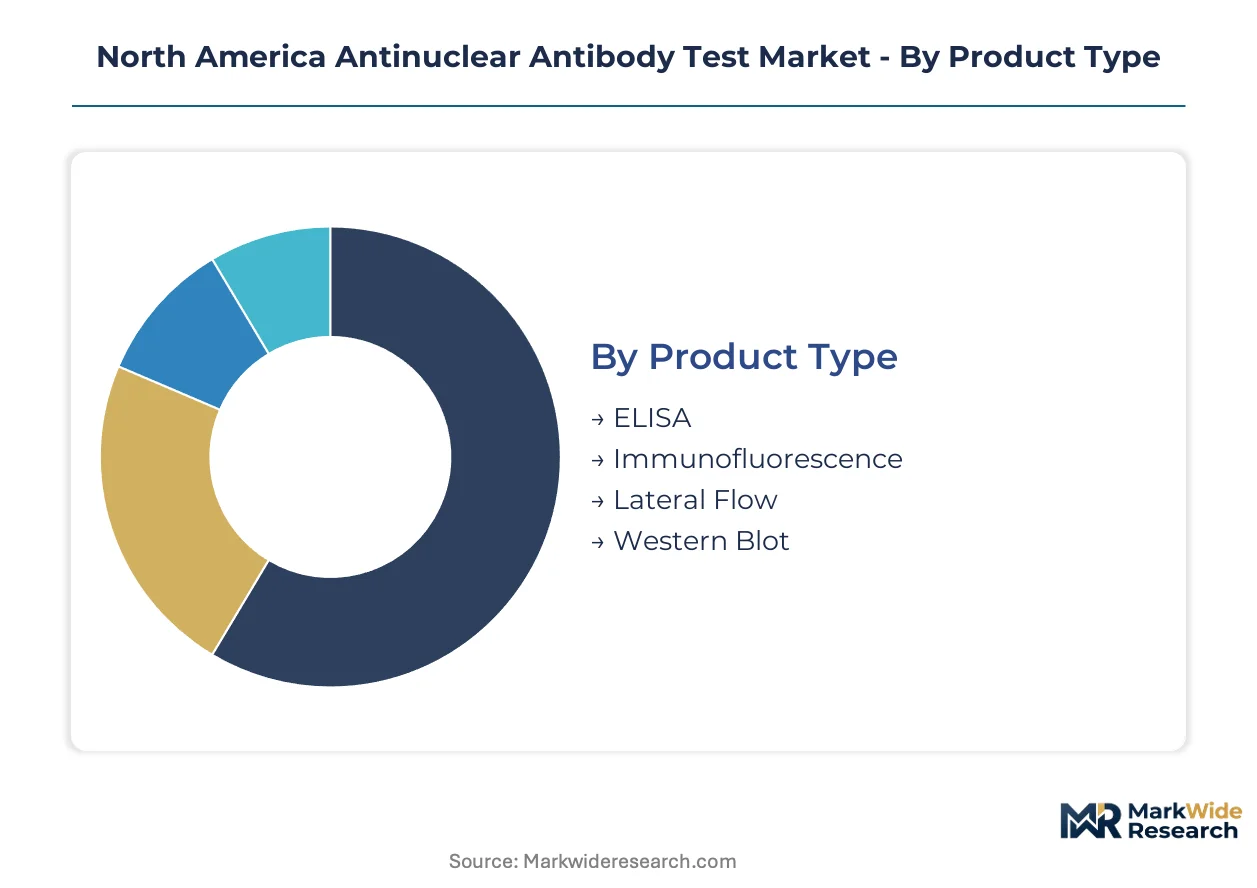
Antinuclear antibody test segmentation reveals how technology maturity, regulatory pathways, and clinical workflow requirements fragment purchasing decisions across North American healthcare delivery. Laboratories and rheumatology practices select platforms based on throughput needs, technologist availability, and reimbursement structures rather than assay sensitivity alone.
Product Type:
Cost tier differentiation separates high-complexity reference methods from streamlined screening formats that compete on operational efficiency and capital requirements.
- Immunofluorescence:HEp-2 cell substrate assays with manual or automated pattern interpretation remain the clinical gold standard for systemic lupus erythematosus screening. Demand concentrates in northeastern United States academic medical centers where subspecialist pathologists interpret complex staining patterns. CLIA-certified reference laboratories maintain these platforms despite higher technologist burden due to established reimbursement codes.
- ELISA:Enzyme-linked immunosorbent assays deliver quantitative antibody titers with standardized optical density readouts suitable for high-throughput hospital laboratories. Mid-sized hospital labs in the southeastern United States favor ELISA platforms for their walkaway automation and reduced skilled labor requirements.
- Lateral Flow:Single-use cassette formats enable rapid qualitative screening without laboratory infrastructure.
- Western Blot:Confirmatory line immunoassays resolve antibody specificity following positive screening results.
Immunofluorescence commands the established base. The steepest expansion runs through ELISA.
End User:
Customer type determines purchasing authority, with integrated delivery networks consolidating decisions that previously rested with individual laboratory directors.
- Diagnostic Laboratories:CLIA-certified independent and hospital-affiliated labs process the majority of ANA screening volumes under federal quality mandates. Large commercial laboratory networks in California and Texas deploy automated immunofluorescence and ELISA platforms to handle regional rheumatology referral demand.
- Hospitals:Inpatient and outpatient hospital laboratories require rapid turnaround for autoimmune workups in emergency and acute care settings. Hospital procurement committees in the northeastern United States negotiate system-wide reagent contracts that standardize platforms across multiple affiliated sites.
- Clinics:Rheumatology and primary care outpatient practices seek near-patient testing to compress diagnostic timelines.
- Research Institutions:Academic medical centers and pharmaceutical developers utilize ANA assays for biomarker discovery and clinical trial endpoints.
Diagnostic laboratories anchor current volume. The steepest expansion trajectory belongs to clinics.
Technology:
Maturity divides established serological methods from emerging automation and point-of-care formats that promise workflow transformation.
- Automated Testing:Robotic slide processing and digital imaging systems collapse the microscopy bottleneck that has constrained immunofluorescence throughput. Academic medical centers in Boston and New York deploy these platforms to handle escalating autoimmune screening volumes without proportional staffing expansion.
- Serological Testing:Conventional antibody detection using indirect immunofluorescence and solid-phase immunoassays dominates current reimbursement structures. Hospital laboratories across the United States retain serological platforms for their established clinical validation and regulatory clearance pathways.
- Point-of-Care Testing:Near-patient platforms enable rheumatology clinics to generate screening results during initial patient encounters.
- Molecular Testing:Nucleic acid and advanced proteomic methods remain investigational for ANA applications.
Serological testing holds the installed base. The steepest expansion runs through automated testing.
Application:
Volume concentration in autoimmune screening creates margin pools that subsidize exploratory applications in oncology and infectious disease.
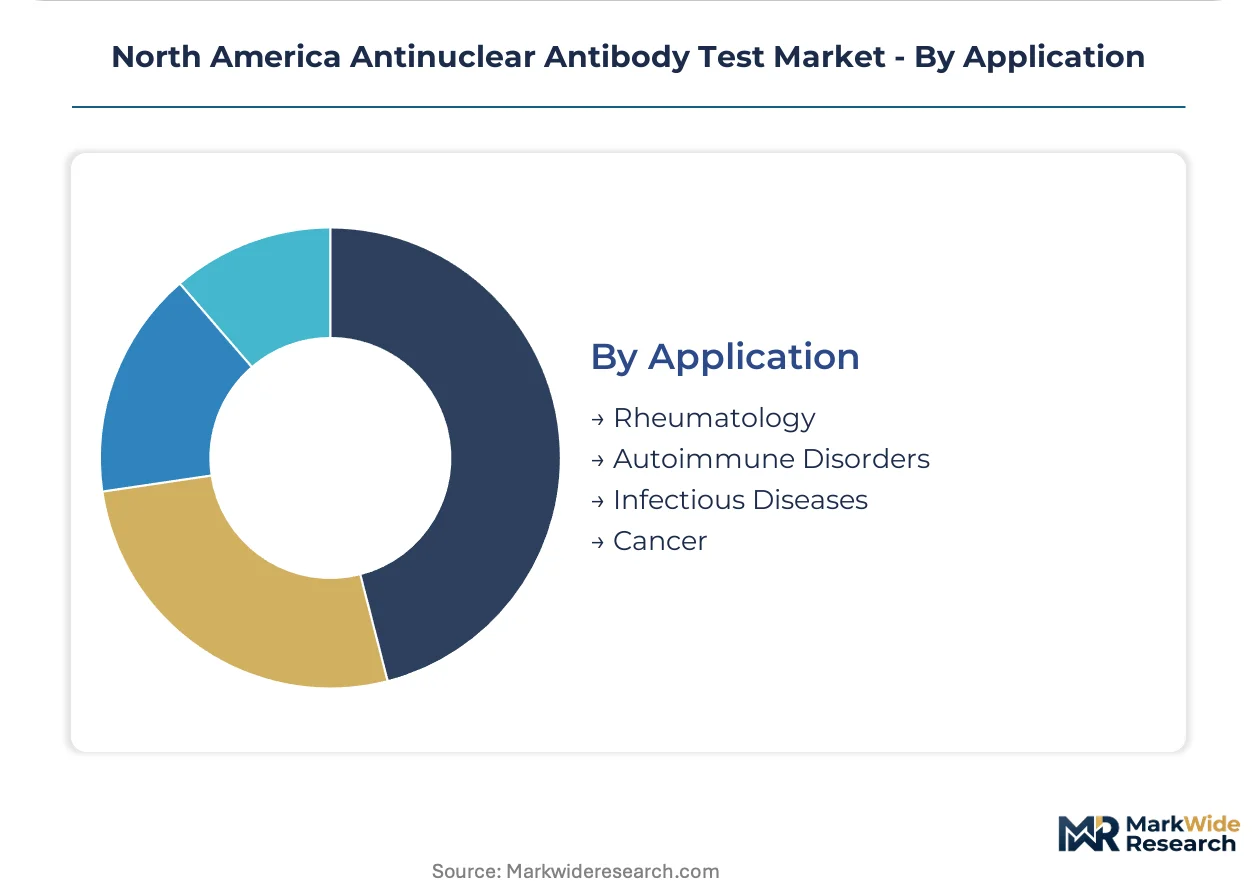
- Rheumatology:Systemic lupus erythematosus, scleroderma, and mixed connective tissue disease screening generates the core demand for ANA testing. Rheumatology practices in metropolitan United States corridors drive standardized screening protocols prior to specialist referral.
- Autoimmune Disorders:Broad screening for undifferentiated connective tissue disease captures patients with nonspecific symptoms before diagnosis. Primary care networks in the midwestern United States utilize ANA testing to triage patients for rheumatology consultation.
- Infectious Diseases:Parasitic and viral infection workups occasionally employ ANA assays to rule out autoimmune mimics.
- Cancer:Paraneoplastic autoimmune syndromes represent a niche application with limited current test volume.
Rheumatology commands the established base. The steepest expansion runs through autoimmune disorders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands pricing power through consolidated procurement networks, while Canadian laboratories benefit from faster Health Canada regulatory pathways that compress commercialization timelines for novel assay formats.
United States
Diagnostic laboratories in the northeastern corridor drive demand through academic medical center clusters in Boston and New York. FDA 510(k) premarket notification requirements govern new ANA assay clearances with deliberative timelines. Mid-sized hospital laboratories across the southeastern United States favor ELISA platforms for walkaway automation capabilities.
Canada
Health Canada regulatory pathways remain less congested than FDA queues, attracting manufacturers seeking faster market entry for automated immunofluorescence systems. Canadian Standards Association laboratory certification parallels CLIA quality mandates. Ontario and Quebec host the majority of CLIA-equivalent diagnostic infrastructure processing autoimmune screening volumes.
Mexico
Private hospital networks in Mexico City and Monterrey expand rheumatology specialty capacity, generating demand for standardized ANA screening prior to specialist referral. COFEPRIS regulatory oversight governs in vitro diagnostic registrations with evolving convergence toward international standards. Northern border states leverage cross-border laboratory networks for complex immunology referrals.
North America Antinuclear Antibody Test Market Competitive Landscape
Full-platform suppliers and specialized reagent manufacturers split the market into complementary rather than directly competing spheres. The vendor base concentrates around three strategic archetypes: diversified life science conglomerates with diagnostic divisions, pure-play immunology specialists with substrate manufacturing expertise, and automated instrumentation developers seeking immunology menu expansion. Consolidation pressure operates through integrated delivery network procurement centralization and technology licensing partnerships that extend platform compatibility.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Abbott Laboratories occupy positions spanning reagent manufacturing through automated analyzer supply, while Bio-Rad Laboratories exemplifies the specialized archetype with sustained investment in quality control materials. These three entities represent the dominant competitive anchors, with Trinity Biotech plc and ERBA Diagnostics Inc. sitting within the mid-tier instrumentation and reagent supply segment.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories Inc. |
| Abbott Laboratories |
| Trinity Biotech plc |
| ERBA Diagnostics Inc. |
| Zeus Scientific Inc. |
| Inova Diagnostics |
| Immuno Concepts |
| Euroimmun AG |
| Others |
Value Network & Pricing Analysis
The I-95 freight corridor between Boston and New York channels reagent shipments from mid-Atlantic distribution hubs to northeastern academic medical centers, with transport cost volatility amplifying price spreads between automated platform suppliers and manual assay providers while reinforcing procurement consolidation among integrated delivery networks.
Pricing Analysis
The customization-premium spread separates configured-to-order automated immunofluorescence systems from standard ELISA kit pricing, with three-tier pricing structure across premium, standard, and economy levels anchored by FDA 510(k) clearance tier and CLIA certification grade. Price differentiation hinges on digital imaging capability and remote interpretation support, with cost compression in the economy tier intensifying because of multiplex assay substitution threats. Hospital procurement committees show lowest price sensitivity, while independent reference laboratories face acute margin pressure from reimbursement uncertainty.
Supply Chain Analysis
Contract-manufacturing concentration for HEp-2 cell substrates rests with specialized bioreactor operators in the United States and Germany, with substrate slide finishing concentrated in California and Massachusetts facilities. Raw material dependencies span fetal bovine serum, fluorescence-conjugated secondary antibodies, and optical-grade glass slides. Single-source vulnerability in cell line authentication creates supply chain risk. Distribution runs through diagnostic reagent distributors serving CLIA-certified laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
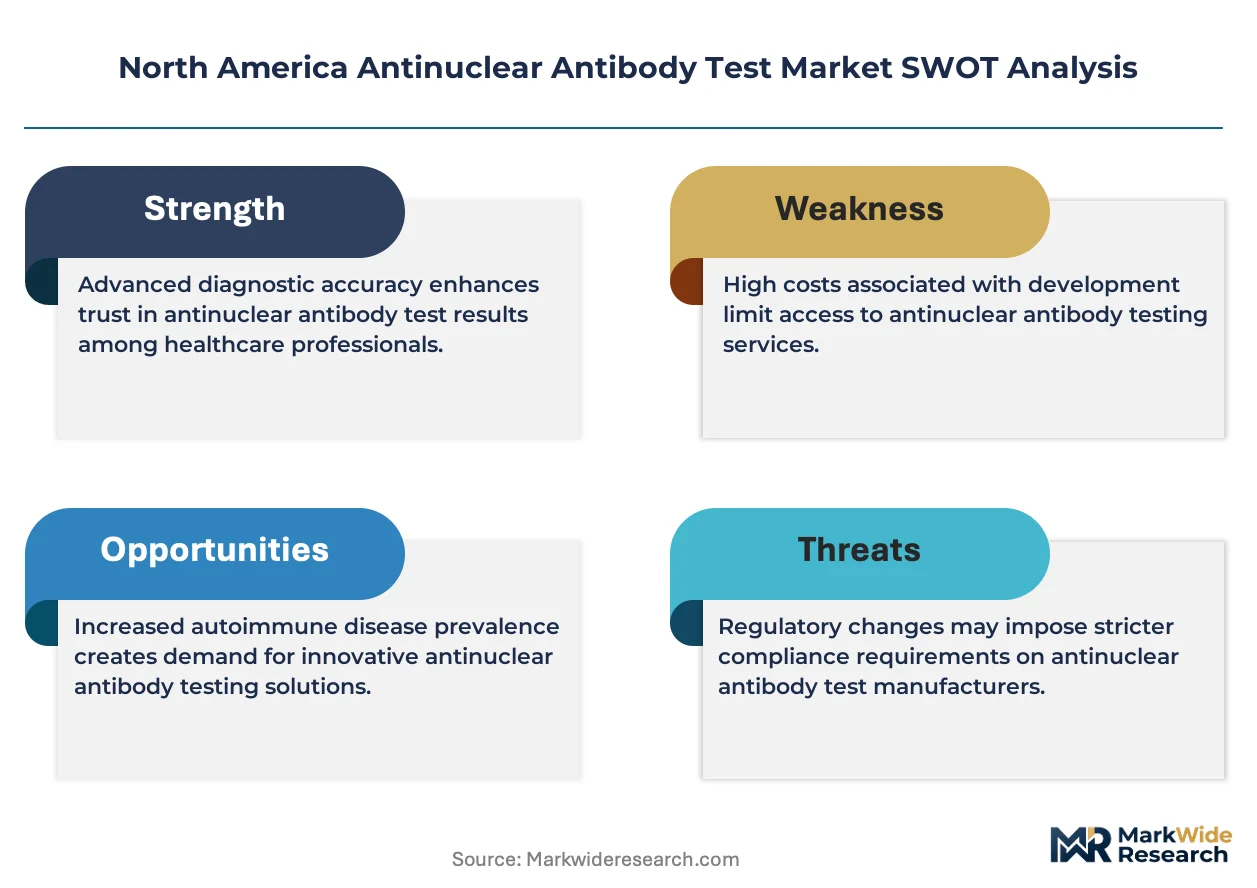
The North America antinuclear antibody test market represents an early-cycle expansion story, with automated platform adoption in mid-sized hospital laboratories providing sustained penetration tailwinds against legacy manual microscopy workflows.
For Market Incumbents: Entrench position through backward integration into HEp-2 substrate manufacturing to neutralize cell line supply vulnerability, while embedding digital pathology software into existing analyzer installed bases to defend against standalone AI pattern recognition entrants. FDA 510(k) clearance for algorithm-based interpretation represents the critical defensive lever. For New Entrants and Emerging Players: Pursue Canadian market entry through Health Canada regulatory pathways to exploit faster commercialization timelines than FDA queues, targeting Ontario and Quebec diagnostic laboratory networks with automated immunofluorescence platforms. Rheumatology point-of-care testing in metropolitan clinic clusters offers the most penetrable white-space target, with direct specialty sales bypassing hospital procurement consolidation. For Investors and Strategic Acquirers: Automated platform developers with embedded AI pattern classification capabilities anchor acquisition interest, given long-term viability through laboratory staffing constraint resolution. The signal to watch is FDA guidance evolution on algorithm-based pattern reporting, which would validate fully automated interpretive workflows and trigger valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Regulatory validation enables Medicare reimbursement and hospital procurement eligibility. |
| HEp-2 Substrate Manufacturing Scale-Up | Vertical control over cell line supply neutralizes batch variability risks for assay manufacturers. |
| Digital Pathology Integration Partnership | Cloud-based pattern libraries extend subspecialist expertise across distributed laboratory networks. |
| Integrated Delivery Network Contract | System-wide reagent pricing commitments lock out competing platform vendors. |
| CLIA Proficiency Testing Alignment | Quality control material standardization secures reference laboratory customer retention. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, CLIA laboratory certification records, and Health Canada medical device licenses preceded structured interviews with diagnostic laboratory directors, rheumatology clinic administrators, biomedical equipment procurement officers, and immunology assay product managers. Secondary validation drew from CMS Medicare reimbursement schedules, hospital GPO contract disclosures, and autoimmune disease epidemiology surveillance data. Bottom-up instrument installation tracking and top-down reagent consumption estimates were triangulated against manufacturer revenue disclosures.
Assumptions held fixed include CLIA certification requirements and FDA regulatory frameworks, while variables encompassed automated platform adoption rates and rheumatology clinic expansion trajectories across the projection horizon. The analytical framework modeled segmentation dimensions spanning assay technology, end-user facility type, automation level, and regional regulatory cluster. CAGRs were derived from installed base evolution and per-test pricing trends, with inputs from laboratory staffing constraint indices and autoimmune screening volume projections.
Sensitivities concentrate around FDA guidance timing on multiplex autoimmune panels and Health Canada regulatory queue congestion. Forecasts reflect assumptions regarding reimbursement stability and substrate supply continuity. Quarterly review of 510(k) submission volumes and CLIA laboratory accreditation trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Veterinary Diagnostic Services Market
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Professional Diagnostics Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
Global Paper Diagnostics Market