
 In Vitro Diagnostic Substrate Market | 2026-2036
In Vitro Diagnostic Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
In Vitro Diagnostic Substrate Market Foresight
Consumable substrate revenue is fragmenting across instrument-locked and open-platform supply models. Thermo Fisher Scientific leverages its vertically integrated materials science portfolio to anchor high-volume chip production for genetic testing workflows. bioMérieux SA specializes in pathogen-detection-grade slides with proprietary surface chemistries that sustain premium positioning in European clinical networks. Abbott Laboratories competes through diagnostic-system-tied substrate bundles that control replacement-part purchasing across installed immunoassay platforms.
In vitro diagnostic substrates are engineered surfaces—typically glass, plastic, or silicone-based—manufactured with controlled porosity, optical clarity, and biomolecular binding capacity to enable reproducible diagnostic reactions. These substrates serve as the physical foundation for assays detecting nucleic acids, proteins, or pathogens in clinical and research settings. The material dimension shows glass substrates dominating high-sensitivity microarray applications while polycarbonate plates capture volume in drug-development screening workflows. The end-user structure tilts toward clinical laboratories as the largest procurement pool, though research institutions represent the fastest-growing segment for custom-coated chips in biomarker discovery programs.
The FDA oversees substrate performance through in vitro diagnostic device regulations and quality-system requirements that shape manufacturing documentation and clinical validation standards. The EPA and OSHA impose chemical-handling and workplace-safety rules affecting substrate coating facilities and disposal protocols. The ISO 13485 framework governs quality management for medical-device-grade substrates, creating compliance barriers for non-certified suppliers. Stakeholders must monitor evolving FDA guidance on next-generation sequencing substrates and dual-use research policies that could restrict certain genetic-testing surface technologies.
Market Dynamics
Instrument-locked substrate supply contracts are fragmenting procurement autonomy across clinical laboratories, forcing buyers to navigate proprietary surface chemistries that tie consumable purchasing to installed-base hardware ecosystems.
Growth Catalysts
- ISO 13485 Certification Mandates:Medical-device-grade quality frameworks are elevating substrate qualification barriers, filtering out uncertified suppliers and concentrating procurement among validated manufacturers in Germany and Switzerland.
- Next-Generation Sequencing Workflows:Clinical laboratories in the United States are expanding high-throughput genetic testing infrastructure, driving premium substrate consumption for nucleic acid detection applications.
- Pathogen Detection Slides:European hospital networks are standardizing proprietary surface chemistry platforms for infectious disease diagnostics, locking in recurring substrate revenue streams.
Market Restraints
- High-Purity Silica Price Volatility:Raw material cost swings for glass substrate precursors compress margin predictability for microarray manufacturers.
- FDA Laboratory-Developed Test Oversight:Evolving device classification rules for genetic testing substrates extend validation timelines and documentation burdens.
- Polycarbonate Substitution Threat:Drug-development screening workflows are migrating toward lower-cost plastic plates, displacing glass in non-clinical volume applications.
Strategic Opportunities
- Biomarker Discovery Customization:Research institutions in Massachusetts and California are commissioning coated chips for proteomics applications, outpacing clinical segment growth.
- CE-IVD Marking Acceleration:The EU MDR transition timeline is creating first-mover advantages for substrate suppliers completing notified body conformity assessments ahead of competitors.
- Digital PCR Convergence:Partitioning microfluidics and real-time fluorescence detection are merging substrate requirements, opening design windows for multi-functional surface architectures.
Industry Challenges
- Surface Chemistry Talent Scarcity:Thin-film coating engineers with biomolecular binding expertise command premium compensation, constraining R&D expansion at mid-scale manufacturers.
- Cleanroom Capex Intensity:ISO Class 7 fabrication facilities for medical-device-grade substrates require eight-figure capital deployment, limiting facility geographic diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vitro Diagnostic Substrate Market |
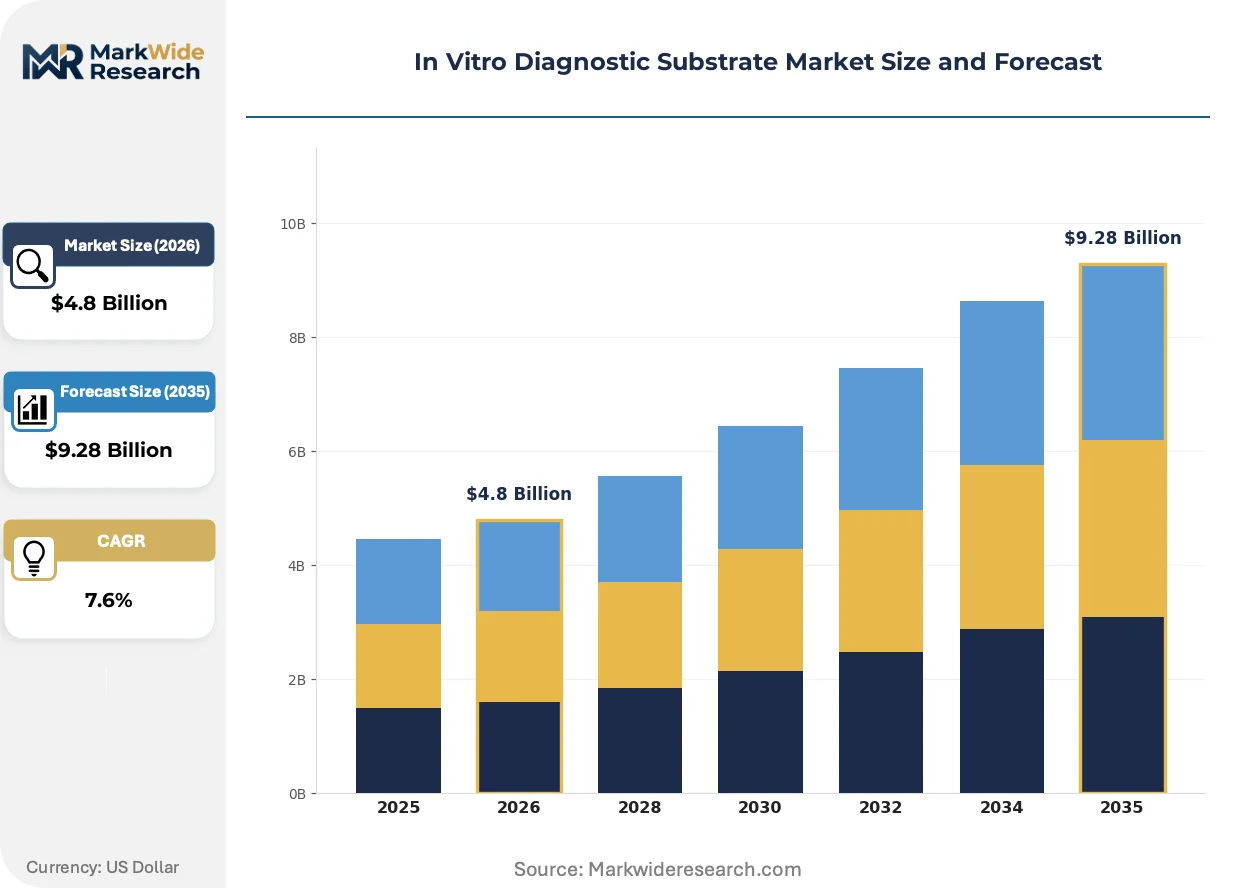
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microarrays, Chips, Plates, Slides Material: Glass, Plastic, Silicone, Polycarbonate Application: Pathogen Detection, Genetic Testing, Drug Development, Biomarker Discovery End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Diagnostic Centers |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche AG, Siemens Healthineers, Thermo Fisher Scientific, Bio-Rad Laboratories, Merck KGaA, Beckman Coulter, bioMérieux SA, Transasia Bio-Medicals Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vitro Diagnostic Substrate Market Shifts & Advancements
Surface engineering advances are compressing assay development cycles while regulatory frameworks and procurement behaviors restructure how diagnostic substrates reach end-users.
Silicon photonic biosensors are collapsing the cost-performance threshold for label-free protein detection. Academic medical centers in Boston and San Diego are piloting these substrates for cytokine profiling in immunotherapy monitoring. The technology is collapsing the historical trade-off between sensitivity and throughput that constrained ELISA-based workflows.
REACH chemical authorization requirements are restricting perfluorinated surface coatings used in legacy hydrophobic patterning. German substrate manufacturers are reformulating wettability chemistries to maintain EU market access. The regulation is accelerating fluorine-free alternatives in microarray slide production, with Swiss coating specialists capturing transition contracts.
Consolidated purchasing by reference laboratory networks is compressing supplier negotiation leverage. Quest Diagnostics and LabCorp procurement teams are unbundling substrate contracts from instrument service agreements, forcing standalone pricing discipline. This behavior is most visible in Texas and North Carolina, where regional laboratory hubs are centralizing consumable sourcing decisions.
In Vitro Diagnostic Substrate Market Segmentation
Substrate purchasing patterns fragment sharply across application workflows, with instrument-locked supply contracts and regulatory qualification tiers dictating vendor selection. Understanding these segment boundaries clarifies where procurement autonomy exists versus where hardware ecosystems constrain buyer choice.
Product Type:
After-sales service intensity varies dramatically across substrate formats, with microarray and chip platforms requiring specialized technical support and surface chemistry recalibration that plates and slides rarely demand.
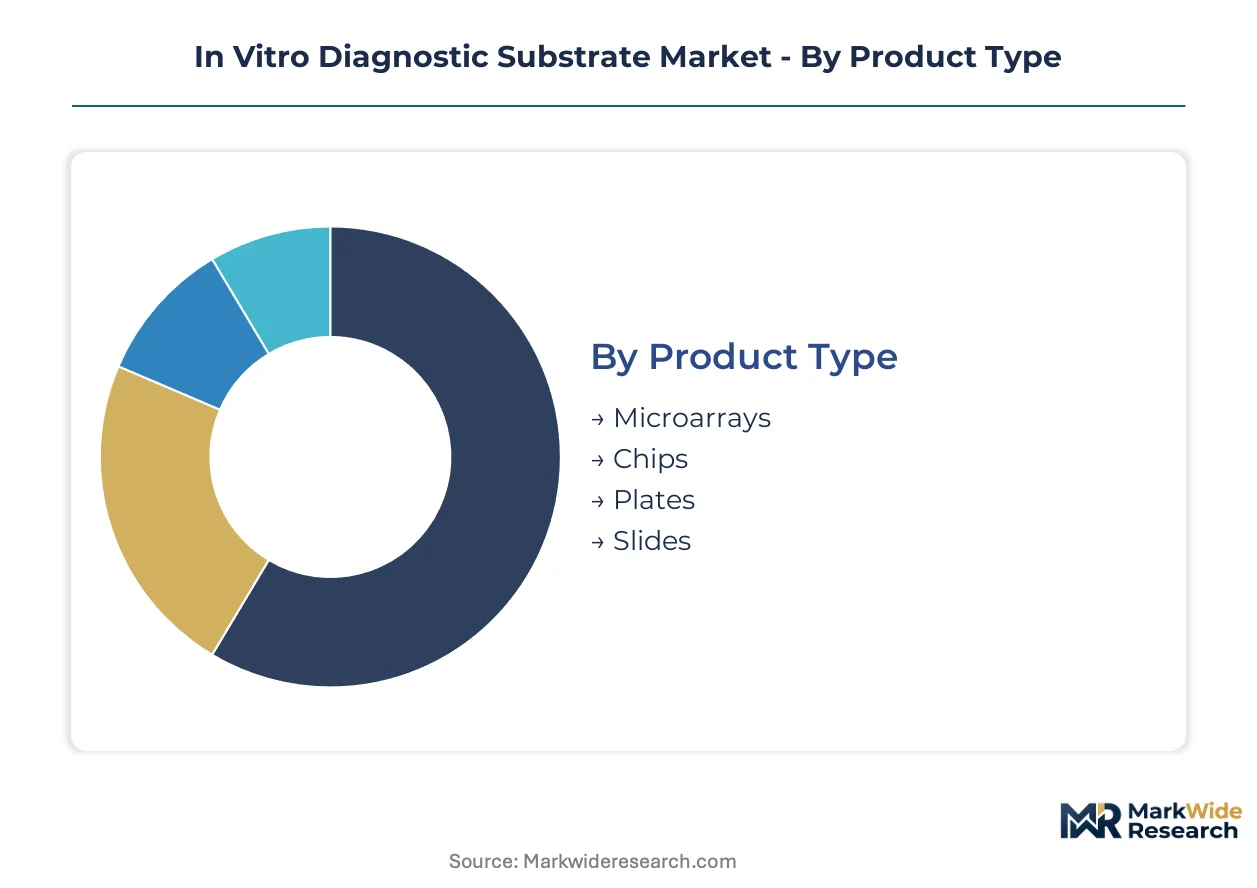
- Microarrays:High-density spotted or synthesized oligonucleotide surfaces on glass or polymer supports enable parallel detection of thousands of biomolecular targets. Demand concentrates in academic medical centers across Massachusetts and California for gene expression profiling, where ISO 13485-certified supply contracts dominate procurement.
- Chips:Microfluidic-integrated substrates with embedded electrodes, valves, or optical waveguides process minute sample volumes for point-of-care genetic testing. German and Swiss clinical networks are expanding procurement for rapid pathogen identification workflows, locking in multi-year service agreements with coating specialists.
- Plates:Standardized multi-well formats for high-throughput screening absorb bulk volume in pharmaceutical quality control laboratories.
- Slides:Single-use glass or plastic surfaces with functionalized coatings support immunohistochemistry and fluorescence microscopy in hospital pathology departments.
Microarrays hold the largest share; momentum sits with chips.
Material:
Raw material cost tiers stratify competitive positioning, with silica-based substrates commanding premium pricing against polymer alternatives that capture volume in non-regulated screening applications.
- Glass:Borosilicate or soda-lime silica substrates deliver optical clarity and thermal stability for fluorescence-based detection. FDA-regulated genetic testing laboratories in the United States specify medical-device-grade glass for clinical diagnostic workflows, extending validation timelines for uncertified suppliers.
- Silicone:Elastomeric substrates enable flexible microfluidic channel fabrication for organ-on-chip and cell culture applications. Research institutions in California and Massachusetts are commissioning custom silicone devices for biomarker discovery, outpacing clinical segment procurement growth.
- Plastic:Injection-molded polystyrene or cyclic olefin copolymer substrates reduce per-unit cost for disposable immunoassay consumables.
- Polycarbonate:Impact-resistant thermoplastic plates absorb volume in drug-development screening workflows where optical precision requirements relax.
Glass substrates hold the largest share; silicone is climbing the fastest.
Application:
Regulatory burden intensity separates clinical diagnostic applications from research-use-only workflows, with FDA and EMA oversight requirements fragmenting vendor qualification pathways.
- Genetic Testing:Nucleic acid detection substrates for sequencing, microarray, or PCR-based workflows require stringent surface chemistry consistency. United States reference laboratories are expanding high-throughput infrastructure, concentrating demand among vertically integrated suppliers with captive coating capabilities.
- Biomarker Discovery:Custom-coated proteomics and metabolomics substrates support exploratory research without clinical validation requirements. Massachusetts and California research institutions are outpacing clinical segment growth for tailored surface architectures.
- Pathogen Detection:Infectious disease diagnostic slides with proprietary chemistries lock in recurring revenue across European hospital networks.
- Drug Development:Screening plates for lead compound identification migrate toward lower-cost polycarbonate as optical specifications relax.
Genetic testing holds the largest share; biomarker discovery shows steepest expansion trajectory.
End User:
Procurement scale and technical specification authority vary across buyer types, with consolidated reference laboratory networks extracting pricing discipline that fragmented research institutions cannot replicate.
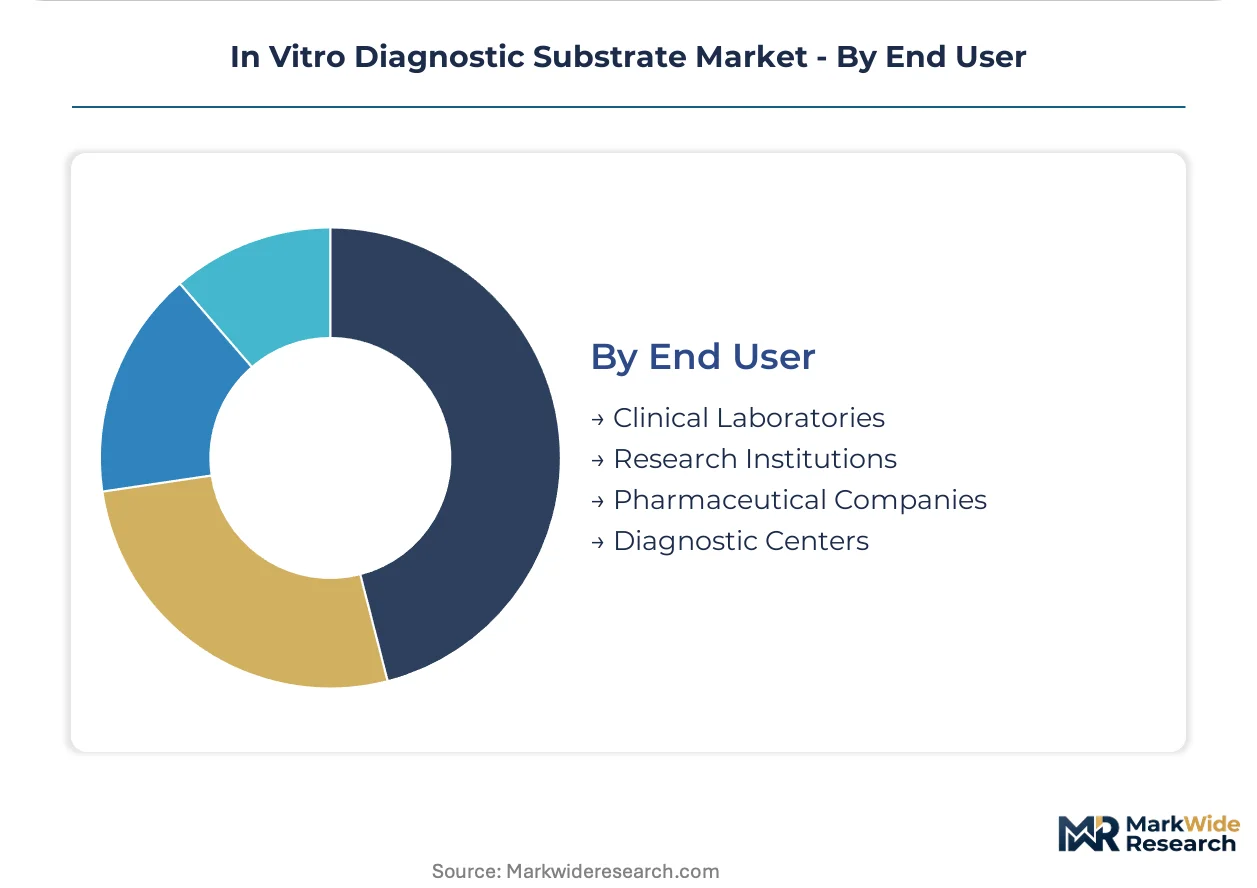
- Clinical Laboratories:Hospital-based and independent diagnostic facilities process patient samples under regulated quality systems. Quest Diagnostics and LabCorp procurement teams in Texas and North Carolina are unbundling substrate contracts from instrument service agreements, forcing standalone pricing discipline.
- Research Institutions:Academic and government laboratories commission custom surface chemistries for exploratory applications without clinical validation burdens. Massachusetts and California institutions are expanding fastest for proteomics chip procurement.
- Diagnostic Centers:Specialized outpatient facilities concentrate volume for routine immunoassay and molecular testing in urban markets.
- Pharmaceutical Companies:Drug manufacturers absorb bulk plate consumption for quality control and screening workflows.
Clinical laboratories hold the largest share; research institutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for diagnostic substrates varies sharply across geographies, with consolidated laboratory networks in mature markets extracting volume discounts while fragmented hospital procurement in emerging economies sustains premium positioning for certified suppliers.
United States
Reference laboratories in Texas and North Carolina are unbundling substrate contracts from instrument service agreements, forcing standalone pricing discipline among vendors. FDA oversight of laboratory-developed tests is extending validation timelines for genetic testing substrate suppliers. Academic medical centers in Massachusetts and California anchor demand for high-sensitivity microarray platforms.
Germany
ISO 13485 certification mandates are filtering out uncertified substrate suppliers and concentrating procurement among validated manufacturers. REACH chemical authorization requirements are restricting perfluorinated surface coatings used in legacy hydrophobic patterning. The Baden-Württemberg and Bavaria industrial clusters host precision coating specialists serving European hospital networks.
Switzerland
Swissmedic regulations for medical-device-grade substrates create compliance barriers for non-certified suppliers entering the market. Coating specialists are capturing transition contracts as German manufacturers reformulate wettability chemistries to maintain EU market access. The Basel and Zurich metropolitan areas concentrate precision surface engineering capabilities for pathogen-detection-grade slides.
China
NMPA quality-system requirements are reshaping product qualification standards for domestic and imported substrate suppliers. The country's national pharmaceutical regulator is tightening oversight of next-generation sequencing consumables. Yangtze River Delta manufacturing hubs are expanding cleanroom capacity for medical-device-grade polycarbonate plate production.
Japan
PMDA device classification rules for genetic testing substrates are fragmenting vendor qualification pathways for foreign suppliers. METI industrial policy is supporting domestic production of high-purity silica precursors for glass substrate manufacturing. The Kanto region around Tokyo anchors demand from centralized clinical laboratory networks.
In Vitro Diagnostic Substrate Market Competitive Landscape
Vertically integrated conglomerates and specialized surface chemistry firms split the market between scale-driven supply contracts and premium technology positioning. Three strategic archetypes dominate: diversified life sciences conglomerates with captive materials science portfolios, European coating specialists with proprietary surface chemistries, and regional instrument manufacturers bundling substrates with installed-base hardware. Competitive moves concentrate on backward integration into high-purity silica supply and multi-year service agreements locking in recurring revenue.
Among diversified conglomerates, Thermo Fisher Scientific and Abbott Laboratories exemplify scale-driven archetypes leveraging integrated supply chains. bioMérieux SA represents the European specialist model with concentrated expertise in pathogen-detection surface technologies. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Merck KGaA |
| Beckman Coulter |
| bioMérieux SA |
| Transasia Bio-Medicals Ltd |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese polycarbonate plate manufacturing is compressing spot-market pricing for non-clinical screening substrates while simultaneously pressuring European glass-substrate specialists to defend premium positioning through ISO 13485 certification differentiation. This utilization asymmetry between commodity plastic and medical-grade silica production is fragmenting supplier behavior into volume-driven contract manufacturers versus quality-anchored coating specialists with captive cleanroom assets.
Pricing Analysis
After-sales service revenue from multi-year surface-chemistry recalibration contracts drives lifetime value for microarray and chip platform vendors. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 13485 certification grade and cleanroom fabrication class. Cost compression in polycarbonate plates is intensifying because drug-development screening workflows are migrating toward lower-cost plastic alternatives. Pharmaceutical quality control laboratories exhibit highest price sensitivity, while academic medical centers in Massachusetts and California demonstrate lowest sensitivity due to grant-funded procurement autonomy.
Supply Chain Analysis
Contract-manufacturing concentration for medical-device-grade substrates centers on German and Swiss precision coating specialists with ISO Class 7 fabrication facilities. Geographic supply draws from Germany, Switzerland, and the United States for high-purity silica and borosilicate glass precursors. Raw material dependencies rest on high-purity silica, fluorine-free hydrophobic coatings, and cyclic olefin copolymers. Single-source vulnerability concentrates in Swissmedic-certified coating specialists serving European hospital networks. Distribution runs through consolidated reference laboratory procurement hubs in Texas and North Carolina.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface-chemistry recalibration service contracts are expanding faster than hardware revenue as clinical laboratories lock in multi-year technical support agreements for microarray platforms. This service-attach dynamic repositions substrate economics toward recurring revenue models.
For Market Incumbents: Entrench proprietary surface chemistry ecosystems by extending multi-year service agreements with European hospital networks and deepening backward integration into high-purity silica precursor supply. Polycarbonate substitution in drug-development screening threatens glass-substrate volume; defend against this by accelerating CE-IVD marking ahead of EU MDR transition deadlines. Certification investment in ISO 13485 quality systems represents the critical lever for filtering out uncertified competitors. For New Entrants and Emerging Players: Custom proteomics chips for biomarker discovery programs in Massachusetts and California represent the most penetrable entry point given research institutions' grant-funded procurement autonomy and tolerance for extended validation timelines. Swiss coating specialists capturing fluorine-free transition contracts from REACH-affected German manufacturers illustrate a second white-space target. A go-to-market angle anchored in rapid-turnaround custom surface architectures for academic medical centers bypasses the instrument-locked contract barriers dominating clinical laboratory procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-device-grade cleanroom fabrication as ISO Class 7 facility requirements demand eight-figure capital deployment. Long-term viability over the next decade favors substrate suppliers with demonstrated notified body relationships and captive coating capabilities rather than commodity plate manufacturers facing polycarbonate price erosion. Acquisition target archetype: mid-scale European coating specialists with Swissmedic or notified body conformity assessments in progress. The signal to watch is consolidation velocity among reference laboratory procurement teams unbundling substrate contracts from instrument service agreements.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVD Marking Acceleration | First-mover advantage in EU MDR transition captures hospital network procurement before competitors complete notified body assessments. |
| Backward Integration into Silica Supply | Captive high-purity precursor production insulates margin from raw material price volatility affecting microarray manufacturers. |
| Multi-Year Service Agreement Expansion | Surface-chemistry recalibration contracts lock in recurring revenue and raise switching costs for clinical laboratory customers. |
| Fluorine-Free Coating Reformulation | REACH-compliant wettability chemistries maintain EU market access as perfluorinated legacy coatings face authorization restrictions. |
| Custom Chip Development Partnership | Biomarker discovery collaborations with Massachusetts and California research institutions outpace clinical segment procurement growth. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with clinical laboratory directors, biomedical engineers at academic medical centers, procurement managers at reference laboratory networks, and thin-film coating specialists at substrate manufacturers. Secondary validation drew from FDA 510(k) filings, EMA CE-IVD registration databases, ISO 13485 certification registries, and hospital procurement contract disclosures. Bottom-up substrate volume estimates triangulated against top-down diagnostic consumables market sizing.
Calibration of segment-level growth trajectories applied across the analysis window without year-specific anchoring. Segmentation dimensions modeled include substrate format, material composition, application workflow, and end-user procurement authority. CAGRs derived from historical volume progression adjusted for regulatory timeline impacts and instrument-locked contract renewal patterns. Forecast inputs incorporated cleanroom capacity expansion announcements and REACH chemical authorization status updates.
Practitioners should monitor FDA laboratory-developed test oversight guidance, REACH chemical authorization timelines for fluorine-free alternatives, and reference laboratory procurement consolidation velocity for early signals of forecast revision. Quarterly review of notified body conformity assessment completion rates and high-purity silica precursor pricing indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Creatine Kinase Reagent Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Extraction Kits Market
Diagnostics
LDL Test Market
Diagnostics
Diabetes Testing System Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
India Molecular Diagnostic Controls Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
Global Rubella Diagnostic Testing Market