
 Romania Solar Energy Market | 2026-2036
Romania Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Solar Energy Market Outlook
Buyer concentration among Romanian energy providers is rebalancing as state-owned Hidroelectrica and private offtakers diversify procurement across independent power producers. Econergy International leverages its development pipeline across southeastern Romania to secure long-term power purchase agreements. Photon Energy Group sustains operational excellence through its proprietary monitoring platforms deployed across distributed assets. Enel Green Power Romania anchors grid-scale deployment with multi-hundred-megawatt projects in Muntenia.
Romania solar energy encompasses photovoltaic systems converting sunlight into direct current electricity through silicon-based cells, typically operating at 15-22% conversion efficiency depending on monocrystalline or polycrystalline composition, then feeding alternating current into the national grid via string or central inverters for commercial and industrial power supply. Photovoltaic technology dominates installed capacity due to modular scalability and declining module costs, while bifacial modules capture incremental margin pools by harvesting reflected irradiance from albedo surfaces. Utility-scale application leads capital deployment through centralized procurement by energy providers, whereas residential rooftop installations compete on self-consumption economics against regulated retail tariffs.
ANRE implements grid connection codes and net metering frameworks that shape project economics for homeowners and commercial operators, while EU Green Deal emissions targets and Recovery and Resilience Facility funding condition national subsidy design. BIS certification requirements for imported modules and CE marking under EU construction product regulation govern equipment market access. Stakeholders must monitor pending capacity auction schedules and grid reinforcement timelines to time development commitments against interconnection bottlenecks.
Market Dynamics
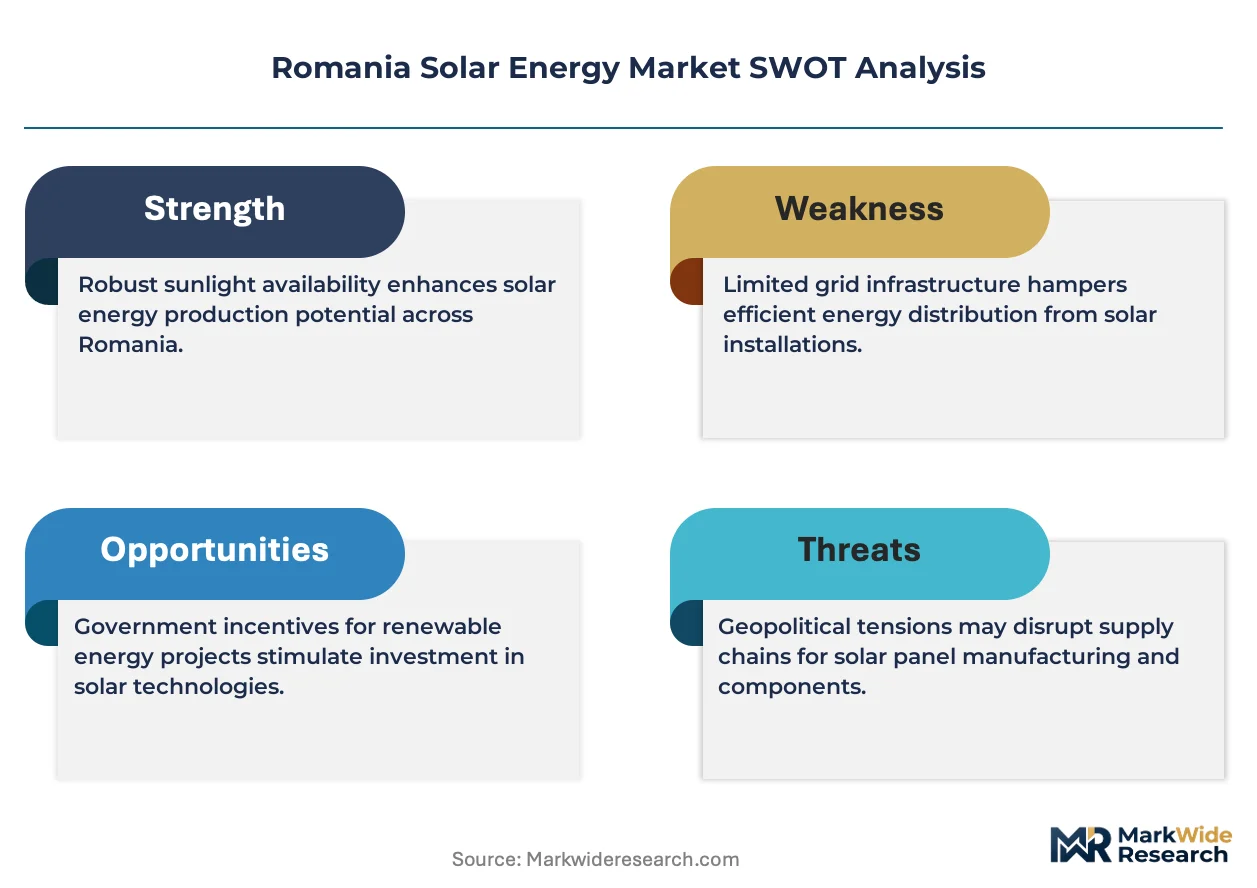
Grid interconnection bottlenecks in Oltenia and Dobrogea are forcing developers to pre-commit capital before securing connection slots, compressing project timelines and elevating development risk.
Growth Catalysts
- EU Green Deal alignment:Romania's Recovery and Resilience Facility funding streamlines permitting for utility-scale photovoltaic installations, reducing administrative delays for independent power producers.
- Bifacial module technology:Albedo harvesting from southern plains terrain boosts energy yield per hectare, improving land-use efficiency for Muntenia project clusters.
- ANRE net metering frameworks:Commercial and industrial operators monetize excess generation through feed-in mechanisms, accelerating distributed asset deployment.
Market Restraints
- Polysilicon supply concentration:Chinese ingot and wafer production dominance exposes Romanian developers to input cost volatility and logistics disruptions.
- Grid reinforcement timelines:Transelectrica transmission upgrades lag behind generation capacity additions, creating interconnection queues in high-irradiance zones.
- Module certification friction:BIS requirements for imported equipment extend procurement cycles for non-EU suppliers, compressing construction windows.
Strategic Opportunities
- Agrivoltaic convergence:Dual-use installations on Dobrogea agricultural land unlock landowner revenue streams while maintaining crop production.
- Corporate PPA expansion:Energy-intensive manufacturers in Transylvania seek direct offtake contracts to hedge against regulated retail tariff volatility.
- Energy storage pairing:Battery co-location with photovoltaic assets captures ancillary service revenues under ANRE grid codes.
Industry Challenges
- Skilled installation labor scarcity:Certified electrician and mounting system specialist shortages delay commissioning timelines across Muntenia project pipelines.
- Legacy grid integration complexity:Central inverter synchronization with aging Oltenia substation infrastructure requires custom engineering and extended testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Solar Energy Market |
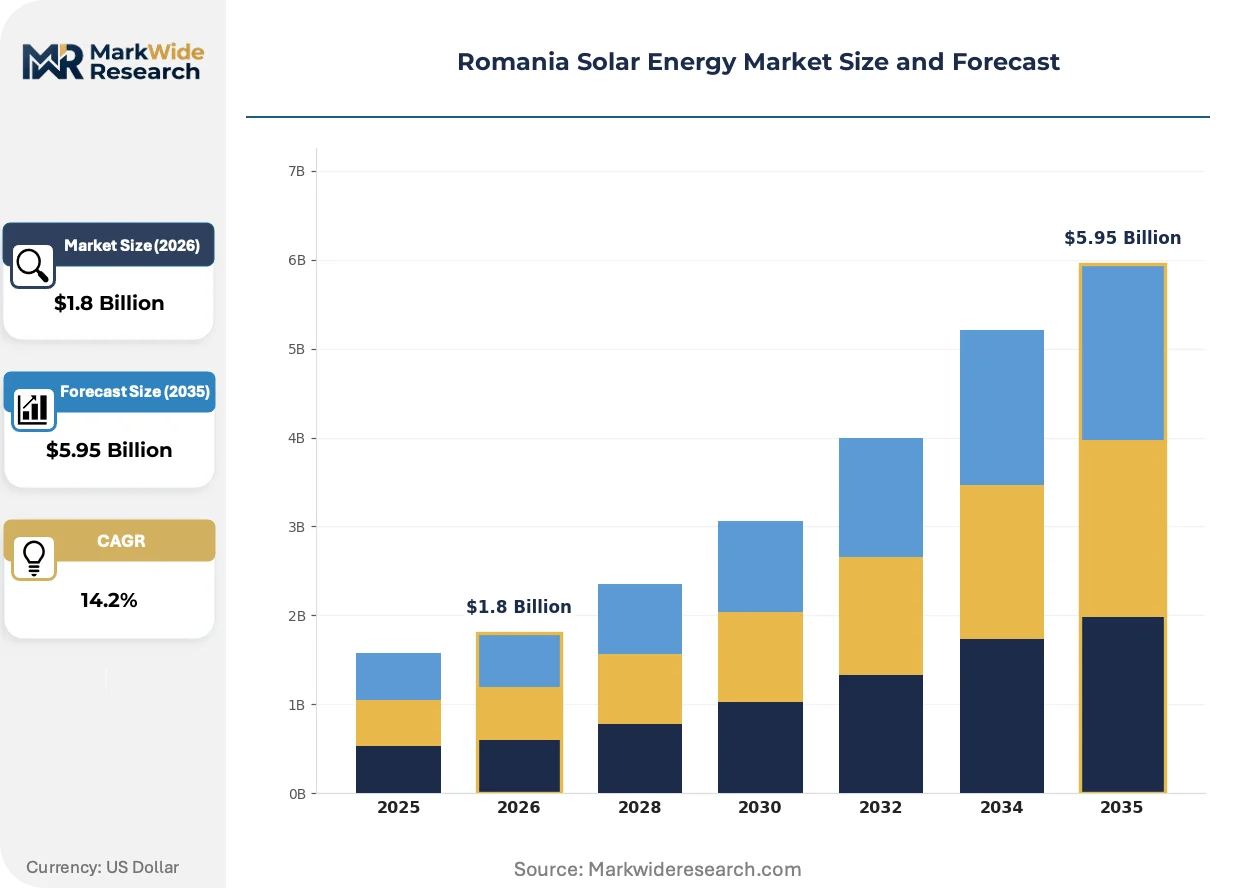
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
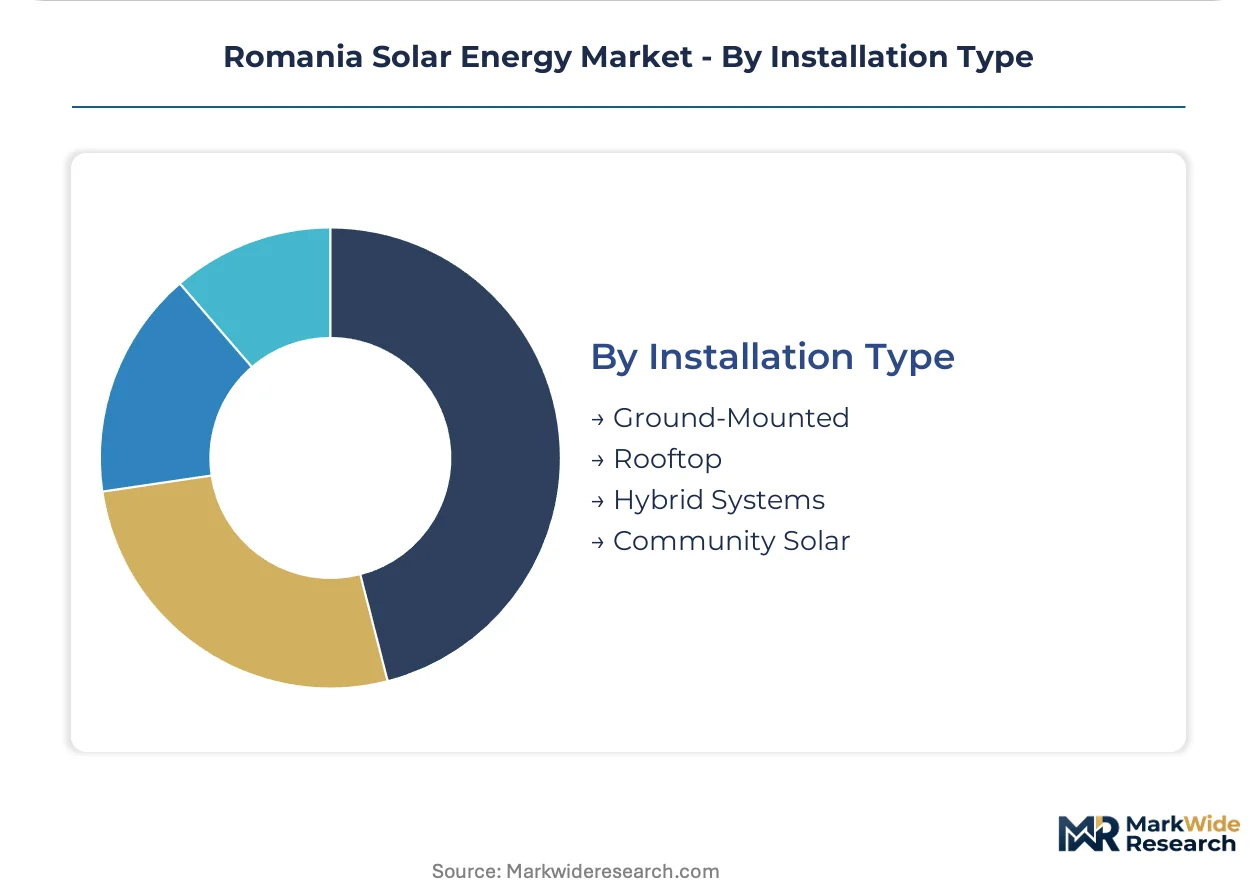
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Bifacial Modules, Thin-Film Application: Utility Scale, Residential, Commercial, Off-Grid End User: Energy Providers, Government, Private Sector, Homeowners Installation Type: Ground-Mounted, Rooftop, Hybrid Systems, Community Solar |
| Companies Covered | Econergy International, Photon Energy Group, Enel Green Power Romania, Rezlov Energy, OMV Petrom, Monsson Group, Scatec ASA, Canadian Solar Inc., Nofar Energy Romania, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Solar Energy Market Strategic Shifts
Photovoltaic technology trajectories in Romania center on efficiency gains, regulatory optimization, and procurement model evolution as developers compete for finite grid capacity.
String inverter architecture is converging with module-level power electronics to reduce mismatch losses across uneven terrain in Dobrogea solar parks. Large independent power producers are standardizing on 1500V DC systems to cut balance-of-system costs. This convergence is compressing levelized cost thresholds for projects competing in upcoming ANRE capacity auctions.
EU Green Deal emissions targets are conditioning national subsidy design through Recovery and Resilience Facility disbursement schedules. Industrial offtakers must demonstrate renewable procurement shares to qualify for green financing. Muntenia manufacturing clusters are responding by aggregating demand through energy cooperatives to meet threshold requirements.
Power purchase agreement tenors are shortening as Romanian energy providers seek flexibility amid regulatory uncertainty. Five-to-seven-year contracts are displacing fifteen-year structures in competitive tenders. This compression is most visible among private offtakers in Transylvania, where balance-sheet constraints favor shorter capital recovery periods.
Romania Solar Energy Market Segmentation
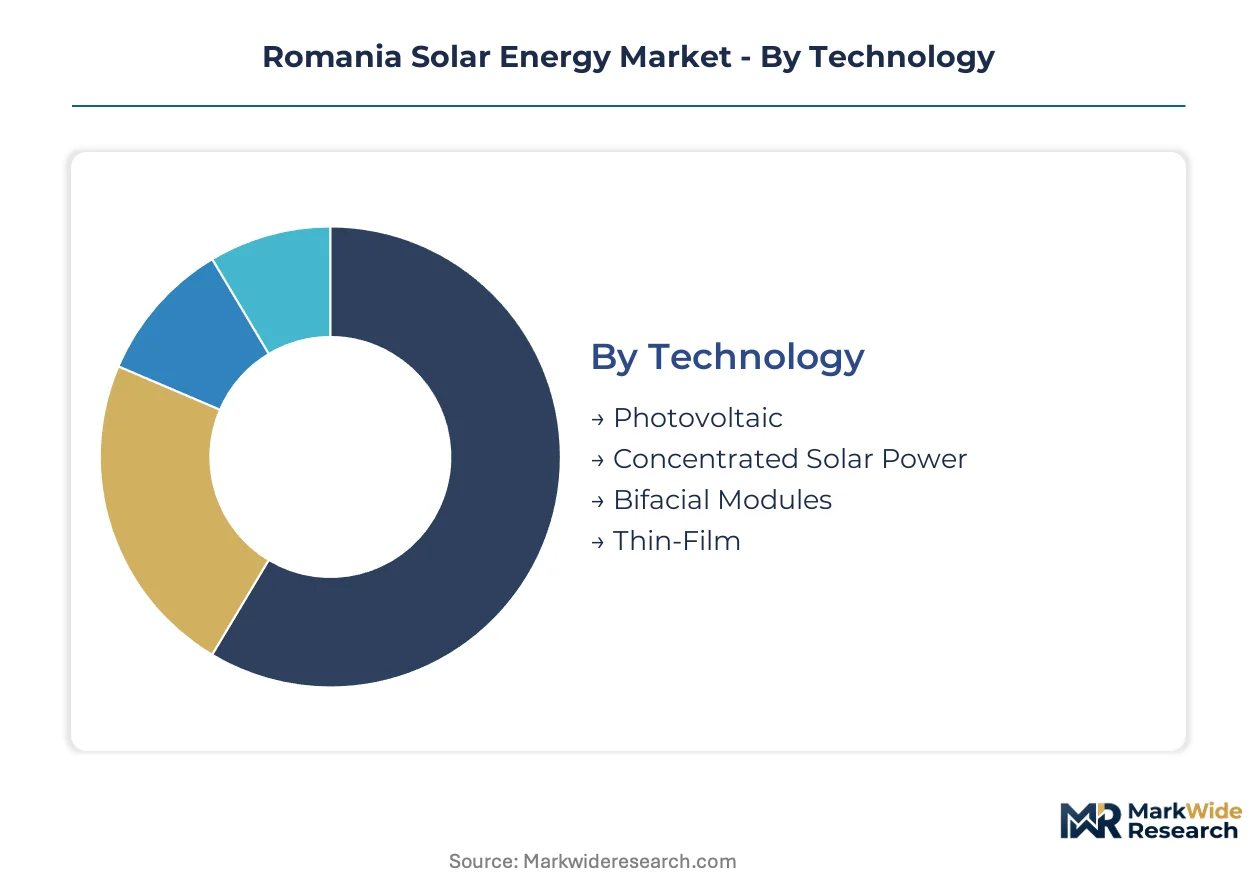
Segmentation in Romania's solar energy market reveals how technology choices, deployment configurations, and customer economics intersect with ANRE regulatory frameworks and EU Green Deal funding eligibility. Each dimension carries distinct interconnection requirements, permitting timelines, and financing structures that shape project viability across Muntenia, Oltenia, and Dobrogea development zones.
Technology:
Technology segments span standalone photovoltaic systems versus embedded concentrated solar power configurations, with bifacial and thin-film variants occupying intermediate integration positions.
- Photovoltaic:Silicon-based cells convert sunlight to direct current at 15-22% efficiency depending on monocrystalline or polycrystalline composition, feeding alternating current through string or central inverters. ANRE net metering frameworks in Oltenia and Dobrogea drive distributed deployment among commercial operators seeking feed-in tariff monetization.
- Concentrated Solar Power:Parabolic troughs and solar towers concentrate thermal energy for steam turbine generation, requiring direct normal irradiance above thresholds rarely sustained across Romania's latitudes. High capital intensity and water cooling demands constrain developer interest despite EU Green Deal decarbonization incentives.
- Bifacial Modules:Dual-sided cells harvest reflected irradiance from albedo surfaces, boosting yield per hectare on southern plains terrain. Albedo harvesting improves land-use efficiency for Muntenia project clusters where flat agricultural land dominates.
- Thin-Film:Cadmium telluride and copper indium gallium selenide layers offer flexible form factors and temperature coefficient advantages. Lower efficiency per square meter limits utility-scale competitiveness against crystalline alternatives in Romania's irradiance conditions.
Volume placements concentrate in Photovoltaic; the faster expansion belongs to Bifacial Modules.
Application:
Application segments distribute across centralized procurement by energy providers versus atomized residential and commercial self-consumption economics.
- Utility Scale:Centralized photovoltaic installations exceeding multi-megawatt thresholds connect directly to Transelectrica transmission infrastructure. Grid reinforcement bottlenecks in high-irradiance zones force developers to pre-commit capital before securing connection slots.
- Residential:Rooftop systems below net metering capacity limits serve homeowner self-consumption against regulated retail tariffs. Shorter payback periods in southern counties accelerate adoption where annual irradiance peaks.
- Commercial:Industrial rooftops and carport canopies serve manufacturing facilities seeking green financing qualification through renewable procurement shares. Muntenia manufacturing clusters aggregate demand through energy cooperatives to meet threshold requirements.
- Off-Grid:Standalone systems with battery storage serve remote agricultural operations and mountain tourism facilities beyond distribution network reach. Higher levelized costs limit addressable market despite complete energy independence.
Capital deployment clusters in Utility Scale; Commercial applications are climbing the fastest as industrial offtakers hedge tariff volatility.
End User:
End user segmentation reflects procurement authority concentration versus distributed decision-making across public and private balance sheets.
- Energy Providers:State-owned Hidroelectrica and private offtakers diversify procurement across independent power producers through competitive tenders. Shorter power purchase agreement tenors of five-to-seven years displace fifteen-year structures amid regulatory uncertainty.
- Government:Public buildings and municipal infrastructure deploy rooftop assets under Recovery and Resilience Facility disbursement schedules. Permitting streamlining for public projects accelerates administrative timelines relative to private developments.
- Private Sector:Energy-intensive manufacturers in Transylvania seek direct offtake contracts to demonstrate renewable procurement shares for green financing eligibility. Corporate PPA expansion drives demand aggregation through specialized intermediaries.
- Homeowners:Individual households evaluate self-consumption economics against net metering caps and regulated retail tariffs. Certified electrician scarcity delays commissioning timelines across residential installation pipelines.
Procurement authority concentrates among Energy Providers; Private Sector engagement is gaining share fastest as manufacturing decarbonization pressures intensify.
Installation Type:
Installation type segments vary in land use intensity, grid interconnection complexity, and community benefit distribution mechanisms.
- Ground-Mounted:Utility-scale arrays on agricultural or degraded land dominate capacity additions across southern plains. Agrivoltaic convergence on Dobrogea agricultural land unlocks dual-use revenue streams while maintaining crop production.
- Rooftop:Building-integrated and building-applied systems minimize land use conflicts and leverage existing grid connection points. Commercial and industrial rooftops in urban Muntenia clusters face structural load assessment delays.
- Hybrid Systems:Photovoltaic-battery co-location captures ancillary service revenues under ANRE grid codes and enables peak shaving for industrial offtakers. Energy storage pairing requirements extend development timelines but improve project economics.
- Community Solar:Shared ownership models aggregate multiple subscribers behind single grid interconnection points. Regulatory frameworks for virtual net metering remain underdeveloped relative to mature European markets.
Capacity additions concentrate in Ground-Mounted; Hybrid Systems show the steepest expansion trajectory as battery costs decline and grid code revenues clarify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale procurement concentrates in southern plains where irradiance levels and grid access converge, while distributed deployment accelerates in manufacturing corridors seeking green financing qualification.
Oltenia
State-owned Hidroelectrica diversifies procurement across independent power producers through competitive tenders in this southwestern region. ANRE feed-in tariff mechanisms streamline permitting timelines relative to other development zones. Craiova industrial clusters anchor manufacturing demand aggregation through energy cooperatives.
Dobrogea
Albedo harvesting from flat agricultural terrain boosts bifacial module yields per hectare across this southeastern coastal plain. Grid interconnection bottlenecks force developers to pre-commit capital before securing Transelectrica connection slots. Constanța port infrastructure supports module import logistics for utility-scale project clusters.
Muntenia
Energy-intensive manufacturers in Ploiești and Pitești manufacturing corridors seek direct corporate PPAs to hedge regulated retail tariff volatility. EU Green Deal Recovery and Resilience Facility disbursement schedules condition public building rooftop deployment. Bucharest metropolitan load centers drive distributed commercial asset growth.
Transylvania
Private offtakers in Cluj-Napoca and Brașov industrial zones favor shortened five-to-seven-year power purchase agreement tenors amid regulatory uncertainty. Shorter payback periods in southern Carpathian foothills accelerate residential rooftop adoption where annual irradiance peaks. Certified electrician scarcity delays commissioning timelines across installation pipelines.
Romania Solar Energy Market Competitive Environment
Romanian developers anchor one tier; international IPP specialists hold project development and long-term offtake contracting positions. Market structure fragments across development-stage ventures, operational asset owners, and integrated energy providers competing for finite grid capacity. Three archetypes dominate: utility-scale developers securing ANRE auction allocations, distributed asset operators monetizing net metering frameworks, and corporate PPA intermediaries aggregating industrial demand. Dominant competitive moves include pre-committing capital ahead of interconnection slot confirmation and diversifying technology portfolios across bifacial and hybrid storage configurations.
Within the utility-scale developer tier, Econergy International and Photon Energy Group exemplify independent power producer archetypes focused on southeastern Romania pipeline execution. Enel Green Power Romania occupies a position among integrated energy providers leveraging grid-scale deployment capabilities. These three anchors represent distinct strategic postures: development-specialist agility, operational platform scalability, and incumbent utility balance-sheet strength.
| Leading Market Players |
|---|
| Econergy International |
| Photon Energy Group |
| Enel Green Power Romania |
| Rezlov Energy |
| OMV Petrom |
| Monsson Group |
| Scatec ASA |
| Canadian Solar Inc. |
| Nofar Energy Romania |
| Others |
Value Chain & Pricing Dynamics
Bifacial module premiums against monofacial commodity tiers split procurement economics across Romanian developer portfolios, with albedo-capture technology commanding higher upfront capital that downstream power purchase agreements recover through yield guarantees, while polysilicon cost pass-through from Chinese ingot suppliers compresses margins on standardized crystalline contracts.
Pricing Analysis
Volume procurement by state-owned Hidroelectrica anchors the low-margin utility-scale tier, while distributed commercial operators absorb premium pricing for module-level power electronics and extended warranty coverage. Three-tier pricing structure across premium bifacial, standard monofacial, and economy thin-film levels differentiates on conversion efficiency and temperature coefficient performance. Pricing pressure stems from EU Green Deal auction competition compressing developer returns in Muntenia cluster tenders. Industrial offtakers in Transylvania manufacturing zones exhibit highest price sensitivity due to balance-sheet constraints favoring shorter payback periods.
Supply Chain Analysis
Direct-to-EPC contractor channels handle hyperscale project demand across Oltenia and Dobrogea development zones, with module manufacturers bypassing distribution intermediaries for multi-hundred-megawatt procurement volumes. Chinese ingot and wafer production, Vietnamese cell assembly, and European module finishing constitute the three-country manufacturing footprint. Polysilicon feedstock, silver metallization paste, and aluminum framing draw from concentrated Asian supply bases. Single-source vulnerability in high-purity silicon sourcing exposes Romanian developers to logistics disruption and input cost volatility. Distribution runs through Constanța port infrastructure for Black Sea delivery routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Romania's solar energy sector functions as a vertical-integration race where developers securing captive polysilicon offtake or in-house EPC capabilities capture margin that pure-play project sponsors forfeit to supply chain volatility.
For Market Incumbents: Anchor grid-scale market share through pre-commitment capital deployment ahead of ANRE interconnection slot confirmation, insulating project pipelines against Transelectrica queue bottlenecks. Consolidate around bifacial and hybrid storage technology portfolios to differentiate auction bids from commodity crystalline competitors. Threat substitution from agrivoltaic land-use competitors in Dobrogea agricultural zones demands proactive land-option contracting.
For New Entrants and Emerging Players: Energy cooperatives serving Muntenia manufacturing clusters represent the most penetrable channel partner type for demand aggregation entry. Target commercial and industrial rooftop segments where net metering frameworks reduce offtake risk and accelerate capital recovery. White-space exists in corporate PPA intermediation for Transylvania industrial zones seeking tariff hedging instruments.
For Investors and Strategic Acquirers: Re-rating potential sits with operational asset platforms possessing proprietary monitoring technology and contracted revenue streams given ANRE grid code monetization clarity. Long-term viability across the projection horizon favors developers with secured land positions in high-irradiance southern counties. Acquisition target archetype: mid-scale IPPs with shovel-ready projects and existing grid connection agreements. Signal to watch: Transelectrica transmission upgrade timelines accelerating interconnection slot availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Multi-hundred-megawatt project execution in Oltenia secures ANRE auction allocations against interconnection bottlenecks. |
| Power Purchase Agreement | Corporate offtake contracting with Transylvania manufacturers hedges revenue volatility from regulated tariff fluctuations. |
| Technology Licensing | Bifacial module yield optimization agreements with albedo assessment platforms improve land-use efficiency metrics. |
| Backward Integration into Polysilicon | Captive ingot supply agreements with Chinese producers reduce input cost exposure and procurement cycle compression. |
| Green Certification Program | EU Green Deal alignment documentation unlocks Recovery and Resilience Facility disbursement eligibility for public projects. |
Study Parameters
ANRE regulatory filings, Transelectrica grid interconnection databases, and EU Recovery and Resilience Facility disbursement records formed the secondary backbone for market sizing and policy trajectory assessment. Primary interviews with IPP project developers, EPC contractors, and utility planning officers validated deployment timelines and capital commitment patterns. Bottom-up project pipeline aggregation across Muntenia, Oltenia, and Dobrogea development zones combined with top-down national capacity target reconciliation to triangulate market value estimates.
Historical installed capacity trendlines and feed-in tariff evolution patterns established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated technology type, application scale, end-user procurement authority, and installation configuration dimensions. CAGRs derived from regression analysis of annual capacity additions against regulatory milestone schedules. Forecast inputs included polysilicon price volatility indices and grid reinforcement investment timelines from Transelectrica infrastructure planning disclosures.
Caveats apply where polysilicon supply disruption, ANRE auction schedule revisions, or Transelectrica interconnection delays could materially shift the outlook. Forecasts reflect base-case assumptions regarding EU Green Deal funding continuity and module cost decline trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Green Power Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Portugal Renewable Energy Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Solar Tree Market
Renewable Energy
Romania Power Market
Renewable Energy
Solar Cooker Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Europe Power to Gas Market