
 Europe Bioenergy Market | 2026-2036
Europe Bioenergy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bioenergy Market Foresight
Utility procurement for baseload renewable heat is hardening across Northern European district heating cooperatives and industrial off-takers. Drax Group leverages its biomass pellet supply chain to anchor long-term contracts with British power stations. Neste Corporation competes in advanced biofuels through its Rotterdam refinery expansion, while Orsted A/S dominates Danish biogas upgrading with grid-injection infrastructure.
Europe bioenergy encompasses the conversion of organic feedstocks into storable energy carriers through thermochemical or biochemical processes, typically yielding calorific values between 16-20 MJ per kilogram for solid biomass and methane purities exceeding 97% for upgraded biogas. Its primary purpose is to displace fossil-derived heat, power, and transport fuels within hard-to-electrify sectors. Biomass occupies the largest existing capacity share due to mature combustion and gasification infrastructure, while biogas captures expanding margin pools through anaerobic digestion facilities co-located with agricultural operations. Biofuels lead technology-linked growth as fermentation pathways scale for aviation and maritime blending mandates.
The EU Green Deal, the revised Renewable Energy Directive, and the F-Gas Regulation collectively shape feedstock eligibility, greenhouse gas accounting boundaries, and end-use qualification criteria across member states. EMA and national regulators enforce sustainability certification through the Union Database for biofuels, creating compliance barriers for uncertified imports. Stakeholders must monitor upcoming delegated acts on biomass cascading use and carbon farming methodologies to secure offtake positions before qualification windows narrow.
Market Dynamics
The EU Green Deal's tightened sustainability criteria for biofuel eligibility is compressing feedstock qualification windows while accelerating capital deployment into certified supply chains across Northern European district heating networks.
Growth Catalysts
- Revised Renewable Energy Directive:Tighter greenhouse gas accounting boundaries for solid biomass combustion are redirecting utility procurement toward certified woody pellet suppliers in Nordic municipalities.
- Coal-phase-out schedules:National mandates in Germany, Sweden, and Finland are forcing combined-heat-and-power retrofits that anchor long-term feedstock contracts for baseload renewable heat.
- Anaerobic digestion scaling:Agricultural co-location models for biogas upgrading are capturing expanding margin pools through grid-injection infrastructure tied to biomethane certificates.
Market Restraints
- Feedstock price volatility:Woody biomass pellet costs fluctuate with forestry harvest cycles and competing industrial offtake from construction panel manufacturers.
- Baltic supply concentration:A disproportionate share of certified sustainable pellet production clusters in Estonian and Latvian processing facilities, creating single-source vulnerability.
- F-Gas Regulation compliance costs:Refrigerant-based biogas upgrading equipment faces retrofit obligations that extend project payback periods for agricultural digester operators.
Strategic Opportunities
- Aviation blending mandates:The EU's ReFuelEU Aviation regulation creates guaranteed offtake volumes for advanced biofuel fermentation pathways targeting hard-to-electrify transport.
- Carbon farming methodologies:Delegated acts under the EU Green Deal will reward perennial energy crop cultivation with tradable carbon removal credits.
- Maritime fuel switching:Baltic and North Sea port clusters are piloting lignocellulosic bio-oil bunkering infrastructure for short-sea shipping routes.
Industry Challenges
- Sustainability certification bottlenecks:The Union Database for biofuels creates documentation backlogs for traders sourcing agricultural residues from fragmented European farm networks.
- Cascading use compliance complexity:Operators struggle to prove that woody feedstocks exhausted higher-value material applications before energy conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bioenergy Market |
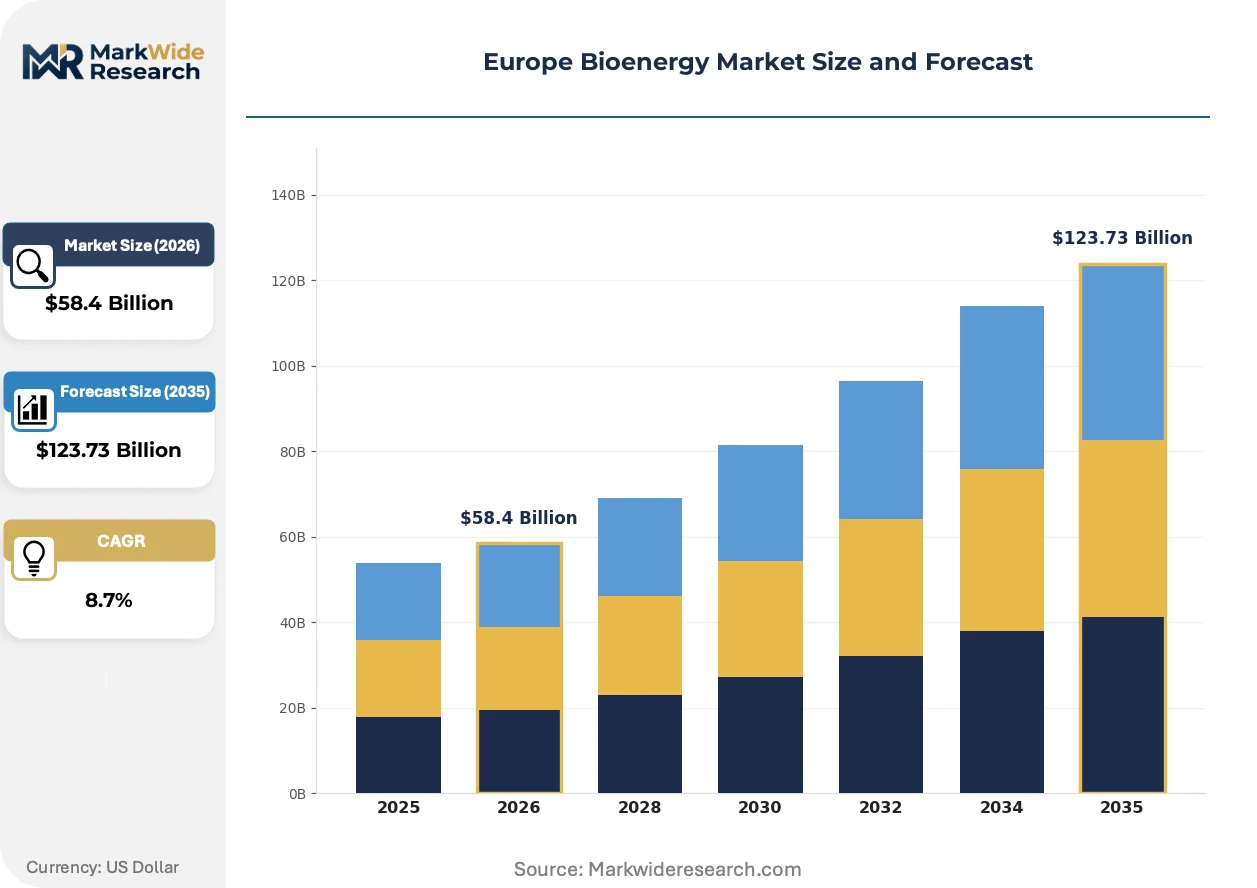
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biogas, Biomass, Biofuels, Biochar Technology: Anaerobic Digestion, Gasification, Fermentation, Pyrolysis End User: Agriculture, Power Generation, Transportation, Residential Heating Application: Electricity Generation, Heat Production, Fuel Supply, Waste Management |
| Companies Covered | UPM-Kymmene Oyj, Neste Corporation, Preem AB, Svenska Cellulosa AB, Green Fuel Nordic Oy, SunPine AB, Drax Group, Enel Green Power, Orsted A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bioenergy Market Shifts & Advancements
Thermochemical conversion pathways and biochemical fermentation advances are compressing the cost gap between fossil-derived and biomass-sourced energy carriers across European industrial heat users.
Torrefaction and steam explosion pretreatment of forestry residues is rewriting the combustion efficiency standards for large-scale biomass boilers. Scandinavian district heating cooperatives are retrofitting existing grate-fired plants with torrefied pellet feed systems that reduce particulate emissions and enable fuel switching without furnace replacement. The technology is rewriting the capital intensity threshold for coal-to-biomass conversions, allowing mid-sized municipal utilities to participate in phase-out schedules previously reserved for national champions.
The EU's delegated acts on biomass cascading use and carbon farming methodologies are tightening feedstock eligibility while creating parallel compliance tracks for different end-use categories. Industrial heat offtakers must now document supply chain provenance through mass-balance certification systems audited by national accreditation bodies. Agricultural biogas operators in Denmark and the Netherlands are responding by consolidating digester clusters to spread certification overhead across larger output volumes.
Long-term feedstock contracting is displacing spot-market purchasing among Northern European district heating utilities exposed to volatile natural gas benchmarks. Finnish and German municipal energy companies are locking in decade-long woody biomass supply agreements with indexed pricing tied to forestry stumpage rates rather than fossil fuel indices. This shift is most visible in the Baltic Sea region, where port terminal operators are reconfiguring storage infrastructure to handle contracted pellet volumes rather than traded commodities.
Europe Bioenergy Market Segmentation
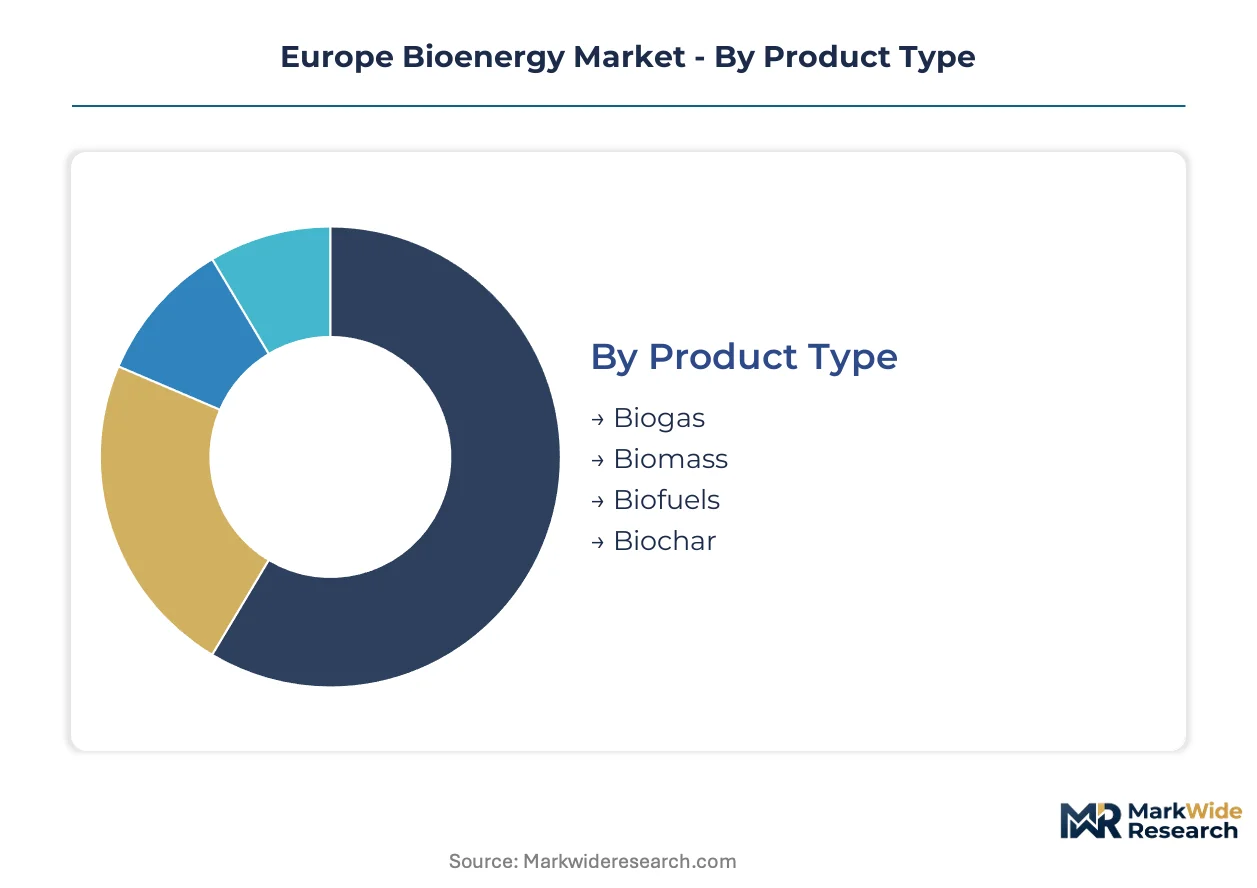
Europe bioenergy segmentation reveals how feedstock chemistry and conversion thermodynamics partition investment risk across utility, industrial, and transport offtakers. Technology maturity and regulatory qualification windows determine which pathways capture capital deployment in Nordic district heating networks versus agricultural biogas clusters.
Product Type:
Calorific density and carbon intensity specifications differentiate product economics under EU Green Deal sustainability accounting.
- Biogas:Anaerobic digestion yields methane purities exceeding 97% after upgrading, with Danish and Dutch grid-injection infrastructure capturing biomethane certificate premiums. Agricultural co-location models in Jutland and Gelderland spread certification overhead across consolidated digester clusters.
- Biomass:Solid feedstocks deliver 16-20 MJ per kilogram through combustion or gasification, anchoring baseload renewable heat contracts in Finnish and German municipal utilities executing coal-phase-out schedules. Torrefaction pretreatment is retrofitting grate-fired plants without furnace replacement.
- Biofuels:Fermentation pathways for aviation and maritime blending mandates concentrate investment in Rotterdam and Singapore refining corridors.
- Biochar:Pyrolytic carbon sequestration products serve soil amendment markets and emerging carbon removal credit frameworks.
Mature deployment sits with Biomass. Newer deployment is concentrated in Biofuels.
Technology:
Capital intensity and feedstock flexibility determine project finance availability across municipal and agricultural sponsor types.
- Anaerobic Digestion:Wet fermentation of agricultural residues and food waste operates at mesophilic or thermophilic temperatures, with Danish operators leading biogas upgrading through amine scrubbing and membrane separation. Grid-injection infrastructure in Jutland and Zealand enables biomethane certificate trading.
- Gasification:Partial oxidation of woody biomass at 800-1,400°C produces syngas for combined-cycle power or synthetic fuel synthesis, with Finnish demonstration plants testing fluidized bed configurations for forest residue feedstocks.
- Fermentation:Biochemical conversion of sugars and starches to ethanol or advanced biofuels scales for ReFuelEU Aviation mandates.
- Pyrolysis:Thermal decomposition in oxygen-limited environments yields bio-oil, syngas, and biochar fractions.
Commercial maturity clusters around Anaerobic Digestion. Steepest expansion trajectory belongs to Fermentation.
End User:
Heat demand profiles and electrification feasibility shape offtake contract duration and pricing indexation.
- Power Generation:Baseload renewable electricity and combined-heat-and-power output anchor decade-long feedstock contracts with British and Nordic utilities replacing coal capacity. Drax Group's pellet supply chain locks in port terminal storage reconfigurations.
- Transportation:Hard-to-electrify aviation and maritime sectors drive advanced biofuel offtake under blending mandates, with Rotterdam and Baltic port clusters piloting lignocellulosic bio-oil bunkering.
- Agriculture:On-farm energy demand and digestate nutrient recovery motivate digester investment.
- Residential Heating:District heating network connections in Scandinavian municipalities expand woody biomass procurement.
Contract duration is longest in Power Generation. Margin expansion is fastest in Transportation.
Application:
Energy carrier form and grid interconnection requirements segment project development timelines and permitting complexity.
- Heat Production:District heating networks in Nordic municipalities prioritize woody biomass combustion for baseload thermal output, with German and Finnish cooperatives retrofitting existing infrastructure under national coal-exit timelines.
- Electricity Generation:Grid-synchronous bioenergy capacity competes for renewable support schemes, with British power stations anchoring long-term pellet contracts.
- Fuel Supply:Liquid and gaseous bioenergy carriers serve transport decarbonization mandates.
- Waste Management:Organic residue diversion from landfill meets circular economy targets while generating energy revenue streams.
Installed capacity concentrates in Heat Production. Regulatory momentum is strongest in Fuel Supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic and German utilities concentrate baseload renewable heat procurement through long-term woody biomass contracts. National coal-exit timelines and district heating network expansions anchor demand across Northern Europe. The EU Green Deal's cascading use requirements reshape feedstock qualification from Baltic pellet terminals to Jutland biogas clusters.
Germany
Coal-phase-out mandates through 2038 force combined-heat-and-power retrofits in municipal utilities. The revised Renewable Energy Directive tightens greenhouse gas accounting for solid biomass combustion. North Rhine-Westphalia's industrial heartland anchors long-term pellet supply agreements with indexed pricing tied to forestry stumpage rates.
Sweden
District heating cooperatives expand woody biomass procurement for baseload thermal output across Scandinavian municipalities. National biofuel blending mandates under the EU Green Deal accelerate fermentation pathway investment. Stockholm's port terminals reconfigure storage infrastructure to handle contracted pellet volumes rather than traded commodities.
Finland
Municipal energy companies lock in decade-long feedstock contracts for coal-to-biomass conversions. The F-Gas Regulation imposes retrofit obligations on refrigerant-based biogas upgrading equipment. Demonstration plants in the Lakeland region test fluidized bed gasification configurations for forest residue feedstocks.
Denmark
Agricultural biogas operators consolidate digester clusters to spread certification overhead across larger output volumes. Grid-injection infrastructure in Jutland and Zealand enables biomethane certificate trading under Union Database requirements. Orsted A/S dominates biogas upgrading with pipeline connections to national gas networks.
United Kingdom
Power generation offtakers anchor long-term pellet contracts to replace coal capacity in baseload electricity. Drax Group leverages its biomass supply chain to lock in port terminal storage configurations. British sustainability criteria under post-Brexit carbon accounting diverge from EU Green Deal methodologies in feedstock eligibility windows.
Europe Bioenergy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue advanced biofuel fermentation and biogas upgrading specializations. The market structures around three maturity tiers: integrated energy conglomerates with captive supply chains, mid-scale Nordic pellet processors, and agricultural digester operators consolidating for certification efficiency. Dominant competitive moves include long-term feedstock contracting with indexed pricing and backward integration into forestry operations or anaerobic digestion feedstock security.
Within the integrated energy tier, Drax Group and Orsted A/S exemplify divergent archetypes—one anchoring solid biomass power generation through supply chain control, the other dominating biogas grid injection through infrastructure ownership. Neste Corporation represents the advanced biofuel specialization vector, while UPM-Kymmene Oyj and Svenska Cellulosa AB occupy positions linking pulp-and-paper residuals to energy conversion pathways. These five entities collectively illustrate how feedstock origin and conversion technology dictate competitive positioning under tightening EU sustainability criteria.
| Leading Market Players |
|---|
| UPM-Kymmene Oyj |
| Neste Corporation |
| Preem AB |
| Svenska Cellulosa AB |
| Green Fuel Nordic Oy |
| SunPine AB |
| Drax Group |
| Enel Green Power |
| Orsted A/S |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers and municipal utility cooperatives anchor feedstock contracting discipline across Northern European bioenergy markets, linking indexed long-term agreements to forestry stumpage rates and compressing spot-market volatility for smaller offtakers.
Pricing Analysis
The volume-versus-margin split separates baseload heat procurement from premium biomethane certificate trading. Contract-based long-term offtake dominates utility procurement, with price differentiation hinging on sustainability certification tier under Union Database requirements and delivery geography to Baltic port terminals. Pricing pressure stems from competing industrial offtake from construction panel manufacturers absorbing forestry residues. Agricultural digester operators show highest price sensitivity due to fragmented farm networks, while district heating cooperatives with indexed contracts demonstrate lowest sensitivity.
Supply Chain Analysis
Reverse-logistics flows for forestry residue collection and digestate nutrient recovery to agricultural land create circular feedstock loops that reduce virgin input dependence. Geographic supply concentrates in Estonia, Latvia, and Finland for certified woody pellet production. Raw material dependencies center on forestry harvest cycles, agricultural manure streams, and waste wood arisings. Single-source vulnerability clusters in Baltic processing facilities. Distribution runs through port terminal operators reconfiguring storage infrastructure for contracted pellet volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU Green Deal sustainability certification requirements force sub-scale agricultural digester operators and uncertified pellet traders toward exit.
For Market Incumbents: Extend feedstock security through backward integration into forestry operations or anaerobic digestion feedstock aggregation platforms. Lock in decade-long indexed contracts with German and Finnish municipal utilities before qualification windows narrow under cascading use delegated acts. Certification investment in Union Database compliance systems serves as the primary defensive lever against emerging Baltic pellet processors.
For New Entrants and Emerging Players: District heating cooperatives in secondary Scandinavian municipalities offer the most penetrable channel partner type for torrefaction pretreatment retrofits. Target agricultural biogas clusters in Jutland and Gelderland where digester consolidation spreads certification overhead. Advanced biofuel fermentation for ReFuelEU Aviation mandates provides the strongest go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Nordic pellet processors with Union Database certification but constrained working capital in Estonia and Latvia. Long-term viability over a multi-year horizon rests on feedstock origin documentation and grid-injection infrastructure access. Watch biomethane certificate premium spreads as the inflection indicator for biogas upgrading asset valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Feedstock Contracting | Finnish and German municipal utilities anchor baseload renewable heat procurement through indexed agreements tied to forestry stumpage rates. |
| Union Database Certification Investment | Agricultural biogas operators in Denmark consolidate digester clusters to spread compliance overhead across larger biomethane output volumes. |
| Torrefaction Pretreatment Retrofit | Scandinavian district heating cooperatives enable coal-to-biomass conversions without furnace replacement, rewriting capital intensity thresholds. |
| Grid-Injection Infrastructure Expansion | Orsted A/S dominates Danish biogas upgrading with pipeline connections to national gas networks enabling certificate trading. |
| Advanced Biofuel Fermentation Scale-Up | Rotterdam refining corridors capture ReFuelEU Aviation mandated offtake volumes for hard-to-electrify transport sectors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe bioenergy market analysis. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists combined with bottom-up and top-down triangulation. Secondary sources encompassed EEA emissions inventories, IEA bioenergy reports, FERC-style grid interconnection filings, and Union Database certification records. Plant-level capacity data reconciled against national coal-phase-out schedule announcements.
Data-stream reconciliation across supply-side capacity buildouts and demand-side offtake commitments shaped the analytical framework. Segmentation dimensions modeled encompassed fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derived from installed capacity trajectories and feedstock contract volume indices. Industry-specific forecast inputs included forestry harvest cycle data and biomethane certificate trading volumes.
Several conditions sit outside the modeled scope, including potential revisions to EU Green Deal delegated acts on biomass cascading use and carbon farming methodologies. Forecasts reflect assumptions about sustainability certification continuity and national coal-exit timeline adherence. Practitioners should monitor Union Database backlog clearance rates and F-Gas Regulation retrofit obligation enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioenergy
Biomass Molding Fuel Market
Bioenergy
Biogas Market
Bioenergy
Biomass Solid Fuel Market
Bioenergy
Biopower Market
Bioenergy
Global Biomass Briquette Market
Bioenergy
Organic Biogas Market
Bioenergy
Biopellets Energy Market
Bioenergy
Europe Biogas Market
Bioenergy
Biomass Wood Chip Market
Bioenergy
Micro-Scale Biogas Plant Market
Bioenergy
Bio CHP Market
Bioenergy
Bioenergy Market