
 Europe Bath Soap Market | 2026-2036
Europe Bath Soap Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bath Soap Market Intelligence
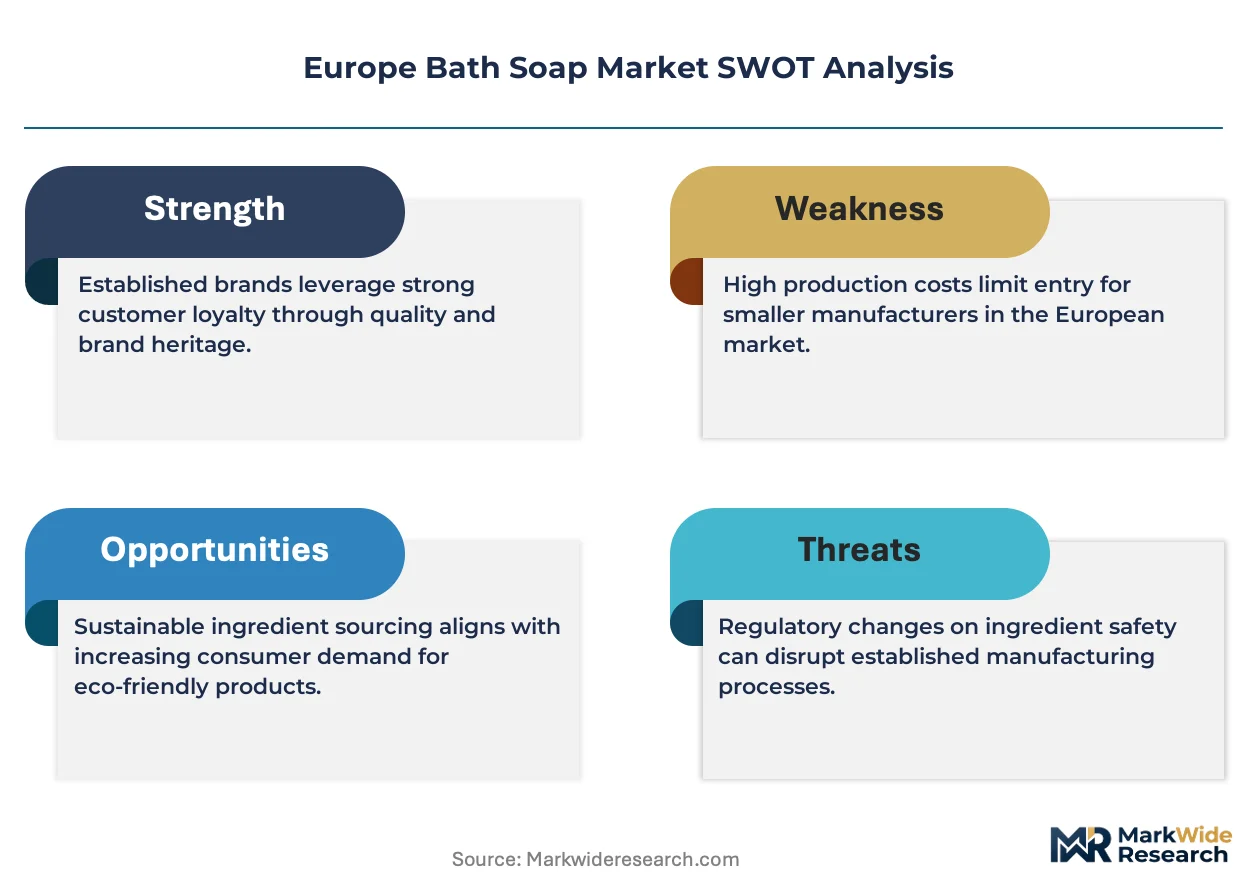
European soap manufacturers is pivoting toward concentrated production hubs in Germany and France to optimize logistics across the single market. Unilever PLC leverages its extensive private-label partnerships to sustain shelf dominance in mass retail. Beiersdorf AG anchors its competitive position through dermatological positioning and pharmacy channel control. L'Oréal S.A. differentiates via premium ingredient storytelling and selective distribution.
Bath soap denotes surfactant-based cleansing bars or liquids formulated with fatty acid salts, glycerin, and fragrance compounds, manufactured through saponification or neutralization processes, designed for personal hygiene and skin conditioning. Liquid soap occupies the fastest-expanding product type as consumers prioritize convenience and dispenser compatibility in shared bathrooms. Organic ingredient formulations command premium pricing and shelf placement in specialty stores, while synthetic antibacterial variants face margin compression from ECHA scrutiny on triclosan and related biocides.
REACH registration requirements and the EU Green Deal's chemical sustainability targets are forcing reformulation timelines and supply chain audits across the value chain. ECHA's restrictions on microplastics in rinse-off cosmetics directly impact exfoliating soap additives and packaging claims. CE marking and MDR-adjacent dermatological testing standards elevate compliance costs for entrants targeting pharmacy and clinical positioning. Stakeholders must monitor evolving biocide authorization lists and packaging waste directives to anticipate product line obsolescence.
Market Dynamics
REACH registration deadlines and EU Green Deal chemical sustainability targets are compressing reformulation timelines across European soap manufacturing, forcing simultaneous supply chain audits and raw material substitutions.
Growth Catalysts
- Urban premiumization:Dense metropolitan households in Germany and France are adopting multi-step cleansing routines that expand per-capita soap consumption beyond basic hygiene.
- Pharmacy channel expansion:Dermatological positioning through pharmacy retail networks captures higher-margin segments as consumers seek clinically validated skin conditioning.
- Biodegradable surfactant mandates:EU Green Deal targets on chemical sustainability accelerate demand for plant-derived cleansing bases that satisfy regulatory pre-approval.
Market Restraints
- Palm oil supply concentration:Southeast Asian crude palm kernel oil dependency exposes European formulators to price volatility and sustainability certification gaps.
- ECHA biocide scrutiny:Authorization reviews on triclosan and related antimicrobial agents restrict synthetic antibacterial variant pipelines and compress margins.
- Liquid packaging material costs:Recycled PET and post-consumer resin shortages elevate dispenser bottle expenses relative to bar soap wrapping.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania specialty retail channels remain fragmented, creating entry points for organic-positioned brands with pharmacy distribution partnerships.
- Refill station networks:Bulk dispensing infrastructure in Scandinavian retail cooperatives reduces single-use packaging intensity and builds consumer loyalty through repeat visits.
- CSRD-aligned ESG reporting:Mandatory corporate sustainability disclosures create procurement preference for suppliers with audited Scope 3 emissions data.
Industry Challenges
- Reformulation talent scarcity:Cosmetic chemists with combined expertise in natural emulsification and regulatory dossier preparation command premium compensation in Germany and France.
- Microplastic additive phase-outs:ECHA restrictions on exfoliating microbeads require rapid substitution with mineral or botanical alternatives without compromising skin-feel performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bath Soap Market |
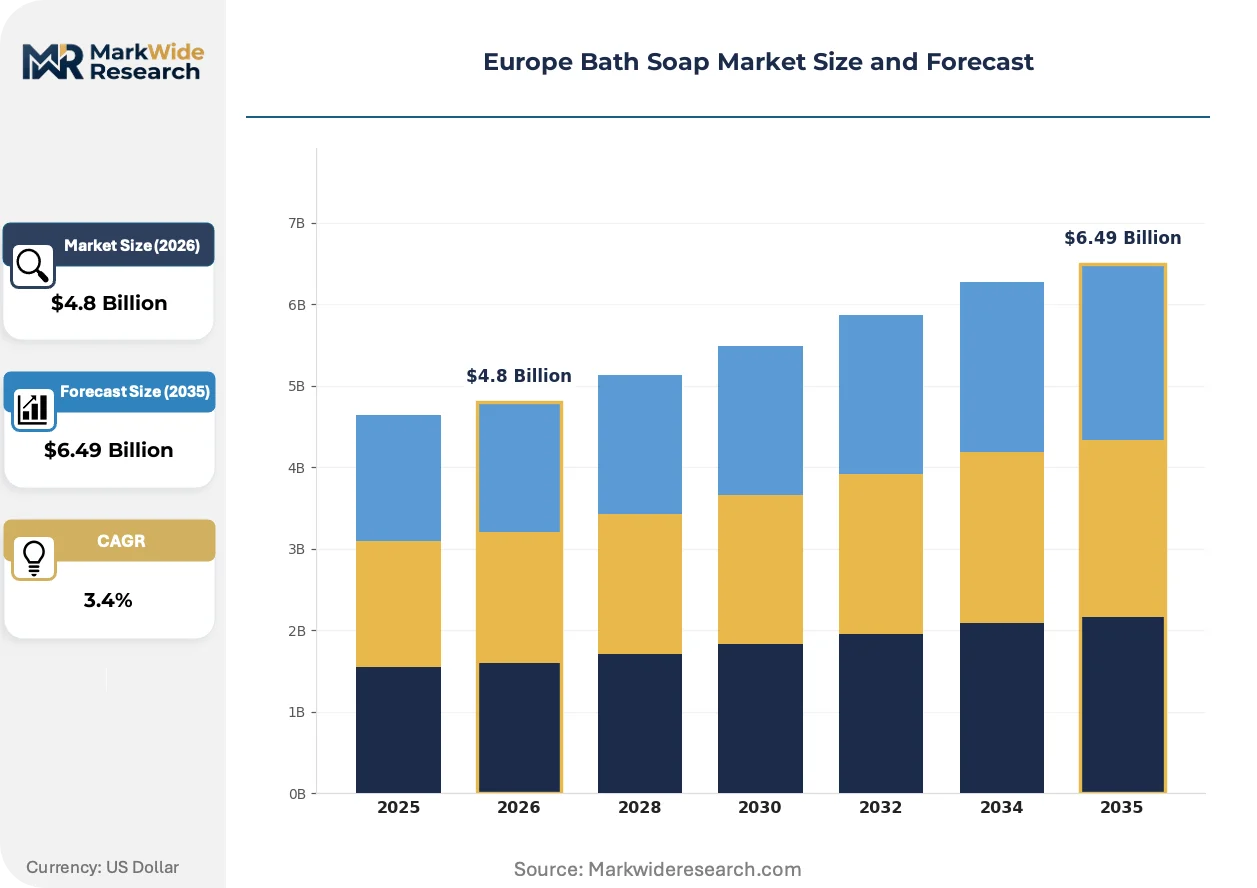
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.49 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Bar Soap, Foam Soap, Gel Soap Ingredient Type: Organic, Synthetic, Antibacterial, Herbal Packaging Type: Tubes, Bottles, Jars, Sachets Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies |
| Companies Covered | Unilever PLC, L'Oréal S.A., The Procter & Gamble Company, Beiersdorf AG, Henkel AG & Co. KGaA, Reckitt Benckiser Group PLC, Colgate-Palmolive Company, Lush Retail Ltd., The Body Shop International Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bath Soap Market Strategic Shifts & Innovations
Solid bar formats are reclaiming shelf space from liquid dispensers as waterless formulation science advances and carbon footprint auditing penetrates procurement criteria.
Cold-process saponification is decentralizing production economics by enabling smaller-batch manufacturing with lower energy inputs. Artisan producers in Spain and Italy are adopting these methods to serve regional specialty retailers. This technology is decentralizing manufacturing scale requirements and eroding the volume advantages of centralized steam-plant operations.
ECHA microplastic restrictions in rinse-off cosmetics are eliminating polyethylene exfoliants from soap formulations. Manufacturers are pivoting toward cellulose, jojoba ester, or mineral-based alternatives that satisfy the 2023-2030 phase-out timeline. Pharmacy-positioned brands face the steepest compliance costs as they must revalidate dermatological claims under revised ingredient profiles.
Refillable dispenser systems are displacing single-use bottles in shared bathroom environments across Scandinavian hospitality and corporate facilities. Bulk concentrate purchasing shifts volume toward B2B supply contracts and away from supermarket impulse buying. This pattern is most visible in Swedish and Danish institutional procurement where municipal sustainability mandates drive vendor selection.
Europe Bath Soap Market Segmentation
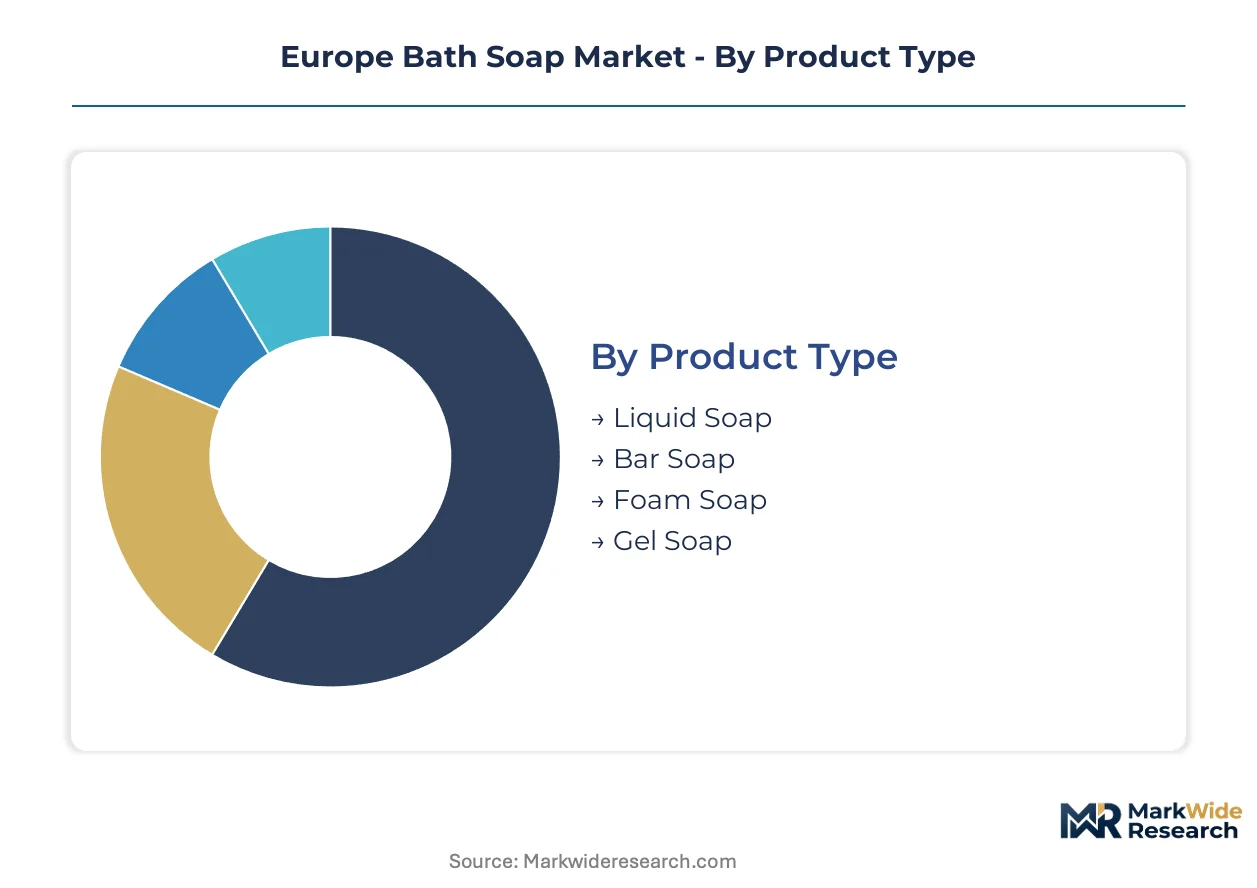
Segmentation in the Europe Bath Soap Market reveals divergent growth trajectories tied to formulation chemistry, packaging sustainability mandates, and channel-specific compliance requirements. Manufacturers must align R&D investment with the category where regulatory pressure and consumer willingness-to-pay intersect most favorably.
Product Type:
Standardization dominates at the mass-market end of this spectrum, while premium tiers demand customized rheology and fragrance delivery systems tailored to dispenser mechanics or bar hardness specifications.
- Liquid Soap:Water-based surfactant suspensions with viscosity modifiers optimized for pump-dispenser compatibility. Demand concentrates in German and French urban households where shared bathroom configurations favor hygienic, mess-free application; REACH-compliant preservative systems add formulation cost.
- Bar Soap:Solid fatty acid salts produced via saponification or syndet processing, with glycerin retention determining skin-conditioning claims. German pharmacy channels sustain premium positioning for pH-balanced dermatological bars; cold-process artisan methods are eroding centralized manufacturing advantages in Spain and Italy.
- Foam Soap:Pre-aerated formulations requiring specialized dispenser mechanisms and lower surfactant concentrations per use cycle. Scandinavian institutional procurement drives adoption through municipal sustainability mandates.
- Gel Soap:Thickened aqueous systems with clarity specifications and suspended visual additives. Brief treatment: Specialty retailers in France favor transparent gel formats for premium shelf differentiation.
Leading the category by volume: Liquid Soap. Growing fastest: Bar Soap.
Ingredient Type:
Cost tier stratification separates certified organic supply chains from commodity synthetic bases, with antibacterial variants facing margin compression under ECHA biocide scrutiny.
- Organic:Plant-derived surfactants and cold-pressed oils carrying ECOCERT or COSMOS certification, excluding petrochemical feedstocks. French and German specialty stores command disproportionate shelf placement; EU Green Deal chemical sustainability targets accelerate procurement preference.
- Synthetic:Petrochemical-derived surfactants including sodium lauryl sulfate and cocamidopropyl betaine, optimized for cost-efficient foaming performance. Mass retail in the United Kingdom depends on synthetic bases for private-label price positioning; palm oil derivative supply volatility pressures margin stability.
- Antibacterial:Biocide-containing formulations targeting triclosan, triclocarban, or benzalkonium chloride active ingredients. ECHA authorization reviews restrict pipeline development and elevate compliance documentation costs.
- Herbal:Botanical extracts and essential oil infusions positioned through traditional medicine narratives. Brief treatment: Pharmacy channels in Italy and Spain favor regionally sourced herbal actives for differentiation.
Organic commands the steepest price premium. Antibacterial faces the most severe regulatory headwinds.
Packaging Type:
Customer type segmentation separates institutional bulk purchasers from individual consumers, with refill infrastructure penetration determining format viability across Scandinavian versus Southern European markets.
- Tubes:Flexible aluminum or laminated plastic containers for viscous gel or cream soap formulations. Travel retail and hospitality amenities in France favor tube formats for portion control and brand visibility.
- Bottles:Rigid PET, HDPE, or glass containers with pump or flip-cap closures for liquid and gel variants. German supermarket channels dominate volume; recycled PET shortages elevate material costs relative to bar soap wrapping.
- Jars:Wide-mouth rigid containers for solid or semi-solid cream soap products. Brief treatment: Premium positioning in UK specialty stores supports jar formats for aesthetic bathroom display.
- Sachets:Single-use flexible pouches for trial sizes or hospitality distribution. Brief treatment: Eastern European price-sensitive markets sustain sachet demand for affordability.
Bottles capture the largest volume share. Tubes are expanding most quickly in travel and hospitality segments.
Distribution Channel:
Geography determines channel maturity, with pharmacy network density varying sharply between dermatologically sophisticated Northern European markets and underpenetrated Eastern European regions.
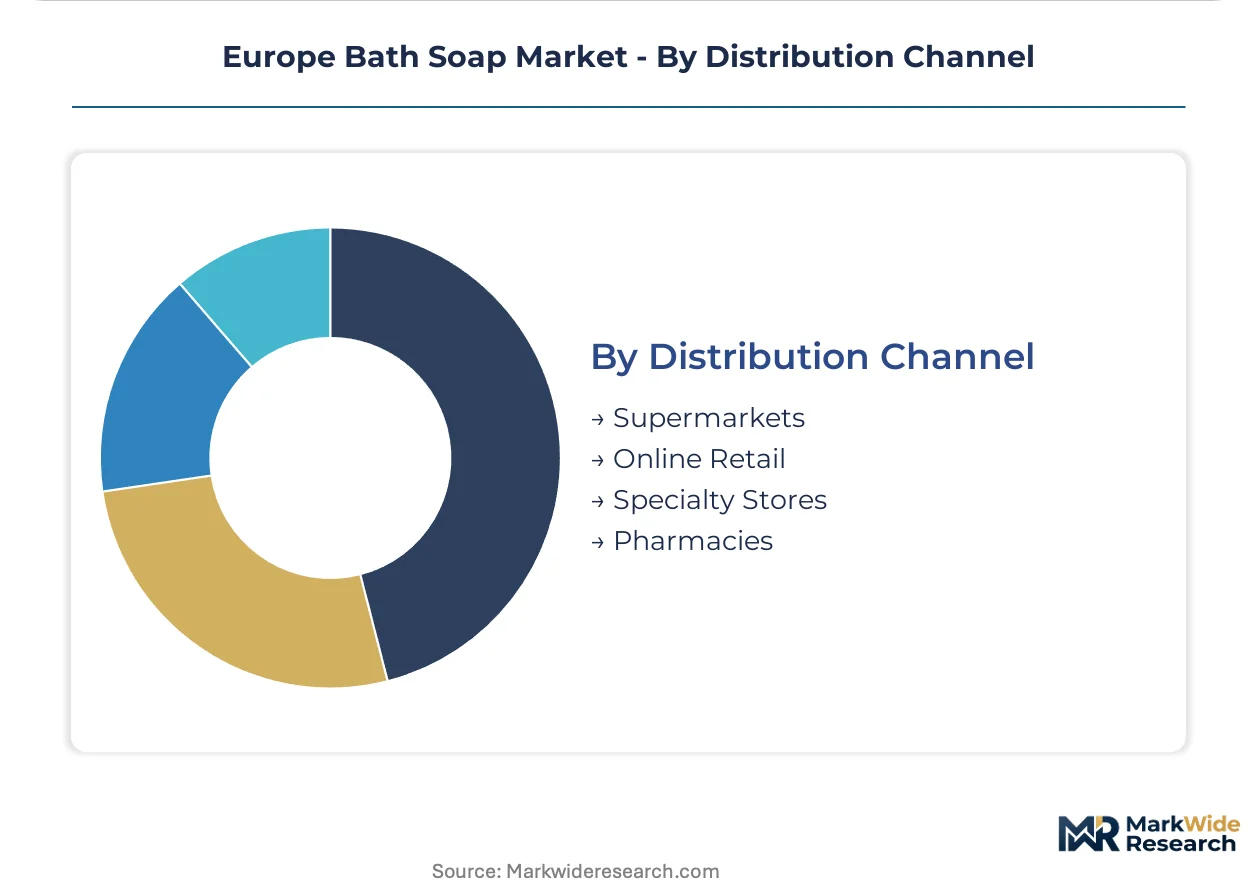
- Supermarkets:High-frequency retail with extensive private-label shelf space and promotional intensity. German and UK mass retail commands disproportionate influence over national pricing benchmarks; Unilever PLC leverages scale for shelf dominance.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription replenishment and ingredient transparency storytelling. French consumers demonstrate highest e-commerce penetration for premium organic brands; logistics costs burden liquid soap shipping economics.
- Specialty Stores:Curated assortments emphasizing clean beauty, zero-waste, or regional artisan positioning. Scandinavian retail cooperatives pioneer refill station infrastructure; Italian and Spanish cold-process producers serve fragmented regional networks.
- Pharmacies:Clinically validated dermatological positioning with pharmacist recommendation influence. Beiersdorf AG anchors competitive position through pharmacy channel control in Germany; CE marking and MDR-adjacent testing standards elevate compliance costs for entrants.
Supermarkets lead by volume. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Palm kernel oil imports through Rotterdam anchor European soap manufacturing logistics, with formulation chemistry expertise clustering in Germany's Rhine-Ruhr industrial corridor. REACH compliance infrastructure and pharmacy retail density determine competitive positioning across national markets.
Germany
Urban households in Berlin and Hamburg drive per-capita consumption through multi-step cleansing routines. ECHA biocide authorization reviews restrict triclosan-based antibacterial variants. Cologne and Düsseldorf host concentrated R&D operations where Beiersdorf AG anchors dermatological bar soap production.
France
Paris and Lyon specialty retailers command premium shelf placement for ECOCERT-certified organic formulations. EU Green Deal chemical sustainability targets accelerate plant-derived surfactant procurement. Grasse fragrance cluster supplies essential oil inputs to cold-process artisan producers in Provence.
United Kingdom
Private-label dominance in Tesco and Sainsbury's channels compresses pricing for synthetic-base mass-market variants. CSRD-aligned ESG reporting mandates elevate supplier audit requirements. Manchester and Birmingham distribution hubs optimize logistics for Irish and Nordic export routes.
Italy
Pharmacy networks in Milan and Rome favor herbal-positioned bars with regionally sourced botanical actives. Cold-process saponification methods decentralize production economics in Tuscany and Emilia-Romagna. Artisan producers serve fragmented specialty retail channels with lower minimum order quantities.
Poland
Warsaw and Kraków retail modernization creates entry points for organic-positioned brands with pharmacy distribution partnerships. Packaging waste directive compliance costs burden smaller domestic formulators. Poznań logistics zone emerges as a consolidation point for Eastern European distribution.
Europe Bath Soap Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cold-process artisan positioning and refill station infrastructure. The market exhibits moderate consolidation with multinational FMCG conglomerates controlling mass retail shelf space while regional specialists capture pharmacy and specialty channels. Three archetypes dominate: dermatologically validated pharmacy brands, private-label scale suppliers, and zero-waste artisan formulators. Competitive intensity centers on M&A activity for natural-positioned regional brands and strategic partnerships with Scandinavian retail cooperatives for refill infrastructure deployment.
Among Anglo-Dutch conglomerates, Unilever PLC exemplifies the private-label scale archetype through mass retail channel dominance. German-based Beiersdorf AG anchors the dermatological positioning tier with pharmacy network control. French-origin L'Oréal S.A. occupies the premium ingredient storytelling segment through selective distribution strategies.
| Leading Market Players |
|---|
| Unilever PLC |
| L'Oréal S.A. |
| The Procter & Gamble Company |
| Beiersdorf AG |
| Henkel AG & Co. KGaA |
| Reckitt Benckiser Group PLC |
| Colgate-Palmolive Company |
| Lush Retail Ltd. |
| The Body Shop International Limited |
| Others |
Cost & Logistics Intelligence
Palm kernel oil imports from Southeast Asia cascade through Rotterdam refining hubs into three distinct pricing tiers across European soap manufacturing. REACH-compliant surfactant reformulations and recycled PET shortages compress margins at the mass-market end while pharmacy-channel dermatological positioning sustains premium capture.
Pricing Analysis
Service bundling separates pharmacy-positioned dermatological bars with clinical validation support from unbundled mass-market synthetic bases competing on shelf price alone. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier—ECOCERT/COSMOS organic commands the steepest markup over commodity petrochemical-derived variants. Pricing pressure stems from ECHA biocide authorization reviews restricting antibacterial pipeline development and elevating compliance documentation burdens. Private-label buyers in German and UK supermarkets exhibit highest price sensitivity; pharmacy-channel consumers in France and Germany demonstrate lowest sensitivity due to clinician recommendation influence.
Supply Chain Analysis
Direct-to-pharmacy distribution handles dermatological brand demand while mass retail cooperative networks serve private-label volume. Manufacturing concentrates in Germany's Rhine-Ruhr corridor, France's Grasse fragrance cluster, and Italy's decentralized artisan regions. Raw material dependencies center on Southeast Asian crude palm kernel oil, Grasse-sourced essential oil inputs, and post-consumer resin feedstocks for dispenser packaging. Single-source vulnerability in Indonesian and Malaysian palm oil supply exposes European formulators to sustainability certification gaps and price volatility. Distribution runs through Rotterdam port consolidation for upstream inputs, with Cologne and Poznań serving as downstream logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cosmetic chemist scarcity across Germany and France props reformulation service pricing, creating durable margin pools for incumbent capacity holders. This talent bottleneck constrains rapid compliance adaptation and sustains competitive moats.
For Market Incumbents: Cement pharmacy channel control through exclusive dermatological validation partnerships that emerging artisan producers cannot replicate. Deepen backward integration into Grasse fragrance supply and certified organic surfactant sources to defend against zero-waste entrant positioning. Lock in Scandinavian retail cooperative refill infrastructure through long-term B2B supply contracts before network saturation.
For New Entrants and Emerging Players: Launch via Polish and Romanian pharmacy distribution partnerships where retail modernization outpaces incumbent coverage. Target Eastern European specialty retail fragmentation with ECOCERT-certified organic positioning at price points below German pharmacy benchmarks. Exploit cold-process saponification methods to serve Italian and Spanish regional networks with lower minimum order quantities than centralized steam-plant competitors.
For Investors and Strategic Acquirers: ECHA microplastic restriction enforcement acceleration is the leading indicator that mineral and botanical exfoliant substitute suppliers will command acquisition premiums. The market supports 5-10 year viability for mid-scale organic-positioned brands with audited Scope 3 emissions data and pharmacy channel access. Monitor refill station network penetration rates in Swedish and Danish retail cooperatives as the signal for B2B contract volume inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Surfactants | Secures ECOCERT-compliant supply chains against REACH-driven raw material substitution timelines. |
| Pharmacy Channel Expansion | Captures higher-margin dermatological segments through clinician recommendation influence in Germany. |
| Refill Station Network Deployment | Aligns with Scandinavian municipal sustainability mandates and builds repeat-visit consumer loyalty. |
| Cold-Process Saponification Adoption | Erodes centralized manufacturing scale advantages through lower-energy small-batch production economics. |
| CSRD-Aligned ESG Reporting Investment | Creates procurement preference among corporate buyers with mandatory Scope 3 emissions disclosure requirements. |
Research Approach
Trade databases, ECHA regulatory filings, and customs import records formed the secondary backbone for supply chain mapping and compliance timeline analysis. Primary interviews with cosmetic chemists at German and French formulation houses, pharmacy category buyers in Milan and Warsaw, and procurement leads at Scandinavian retail cooperatives validated demand patterns and channel dynamics. Bottom-up volume modeling across product type, ingredient certification tier, and distribution channel triangulated against top-down market sizing from production capacity assessments.
Historical consumption trendlines across German, French, and UK metropolitan households anchored the projection framework. Segmentation dimensions modeled include formulation chemistry, packaging sustainability tier, and channel-specific compliance requirements. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory phase-out timelines and urban premiumization patterns. Forecast inputs incorporated ECHA microplastic restriction implementation schedules and EU Green Deal chemical sustainability procurement mandates.
The model assumes a particular technology adoption path; alternative pathways for waterless solid bar formulations would alter the outlook if dispenser infrastructure investment stalls. Forecasts reflect base-case assumptions on REACH registration timeline adherence and palm oil certification penetration rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Halal Cosmetics Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Lipstick Market
Cosmetics & Skincare
Eyeliner Industry Status and Prospects Professional Market
Cosmetics & Skincare
Philippines Skin Care Products Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Liquid Lipstick Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Professional Scalp Care Products Market
Cosmetics & Skincare
Nail Polish Market
Cosmetics & Skincare
Hyaluronic Acid Beauty Products Market
Cosmetics & Skincare
Snail Beauty Products Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
Global Cosmetic Jar Market
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
UK Eyelash Serum Market