
 Halal Cosmetics Market | 2026-2036
Halal Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Halal Cosmetics Market Analysis
Market Context
Premium halal cosmetics is shifting away from commodity-grade alternatives through ingredient traceability, clinical validation, and specialized retail placement. Clara International Beauty Group leverages its Southeast Asian manufacturing footprint to serve pharmacy and clinic channels across Malaysia and Indonesia. Wardah Cosmetics dominates mass-market shelf space in Indonesian drugstores and modern trade outlets through aggressive SKU expansion and local brand equity.
Technical Definition and Structural Segments
Halal cosmetics comprise personal care formulations manufactured without alcohol, porcine derivatives, or other substances prohibited under Islamic law, verified through supply chain audit and certification by accredited religious authorities. These products serve Muslim consumers seeking faith-aligned beauty routines alongside growing non-Muslim demand for ethical, cruelty-free alternatives. Skincare commands the largest revenue pool due to higher per-unit pricing and repeat purchase frequency, while online sales channels represent the fastest-expanding application segment driven by direct-to-consumer halal beauty platforms. Makeup competes intensely on shade range and halal pigment sourcing, with botanical ingredient claims capturing premium positioning among millennial and Gen Z buyers.
Regulatory Frame and Outlook
Indonesia's mandatory halal certification regime enforced by the Halal Product Assurance Organizing Agency (BPJPH), Malaysia's JAKIM certification, and Saudi Arabia's Saudi Food and Drug Authority (SFDA) halal standards collectively raise compliance barriers for new entrants while rewarding pre-certified incumbents. These frameworks reshape procurement requirements, forcing reformulation of legacy products and dedicated halal production line investments. Stakeholders must monitor certification reciprocity negotiations between Southeast Asian and Gulf regulatory bodies to anticipate cross-border market access shifts.
Market Dynamics
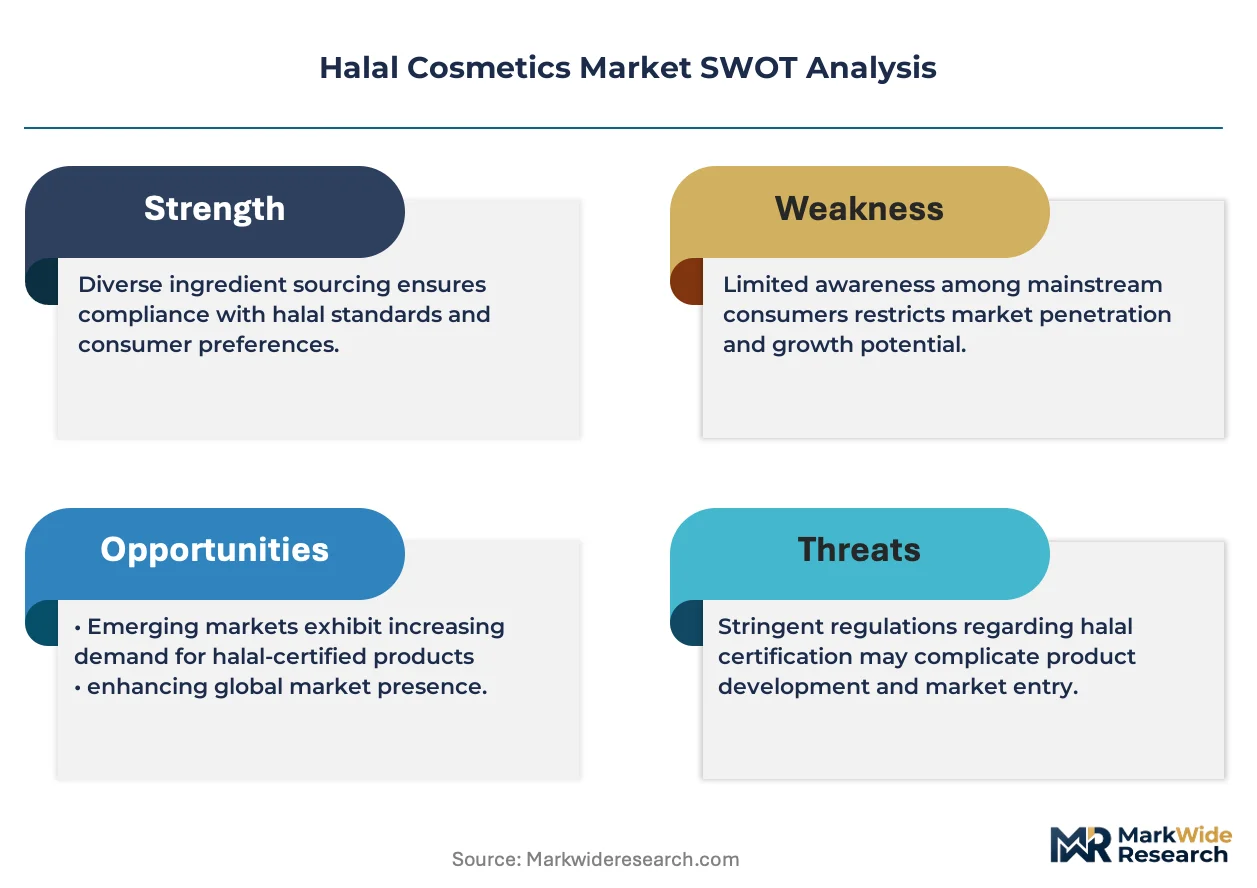
Certification reciprocity negotiations between Southeast Asian and Gulf regulatory bodies are restructuring competitive access, forcing manufacturers to maintain parallel halal production lines and audit trails across multiple jurisdictions simultaneously.
Growth Catalysts
- Indonesia's BPJPH mandatory halal law:The 2024 enforcement deadline compels reformulation across skincare and color cosmetics portfolios, creating certified product scarcity that rewards early compliance investments.
- Biotechnology-derived alternatives:Plant-based collagen and microbial fermentation processes replace porcine and bovine derivatives, resolving ingredient sourcing constraints while opening premium positioning.
- Millennial and Gen Z Muslim consumers:Faith-aligned purchasing preferences intersect with clean beauty demands, expanding addressable demand beyond traditional religious observance into ethical consumption segments.
Market Restraints
- Palm oil derivative volatility:Halal-compliant emulsifiers and surfactants depend on Malaysian and Indonesian palm supply chains exposed to EUDR deforestation due diligence requirements and price swings.
- Single-source certification bodies:JAKIM, BPJPH, and SFDA maintain non-overlapping auditor networks, multiplying compliance costs for brands seeking multi-market distribution.
- Alcohol-free preservation limits:Benzoic acid and phenoxyethanol alternatives face stability and shelf-life trade-offs that constrain formulation flexibility in liquid color cosmetics.
Strategic Opportunities
- Vietnam and Philippines halal infrastructure:Nascent certification frameworks and Muslim minority populations create first-mover advantages for brands establishing local production partnerships ahead of regulatory maturation.
- Direct-to-consumer halal beauty platforms:Dedicated e-commerce verticals bypass conventional retail slotting fees while capturing consumer data for personalized skincare regimens.
- EU Green Deal alignment:Halal cruelty-free and vegan positioning maps onto CSRD sustainability disclosure requirements, enabling dual-certification efficiency for export-oriented manufacturers.
Industry Challenges
- Cross-border formulation reconciliation:Divergent permissible ingredient lists between JAKIM and BPJPH force SKU proliferation or lowest-common-denominator compromises that dilute product performance claims.
- Halal supply chain talent scarcity:Qualified auditors and procurement specialists capable of verifying ingredient provenance through tier-three suppliers command premium compensation, constraining scaling speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halal Cosmetics Market |
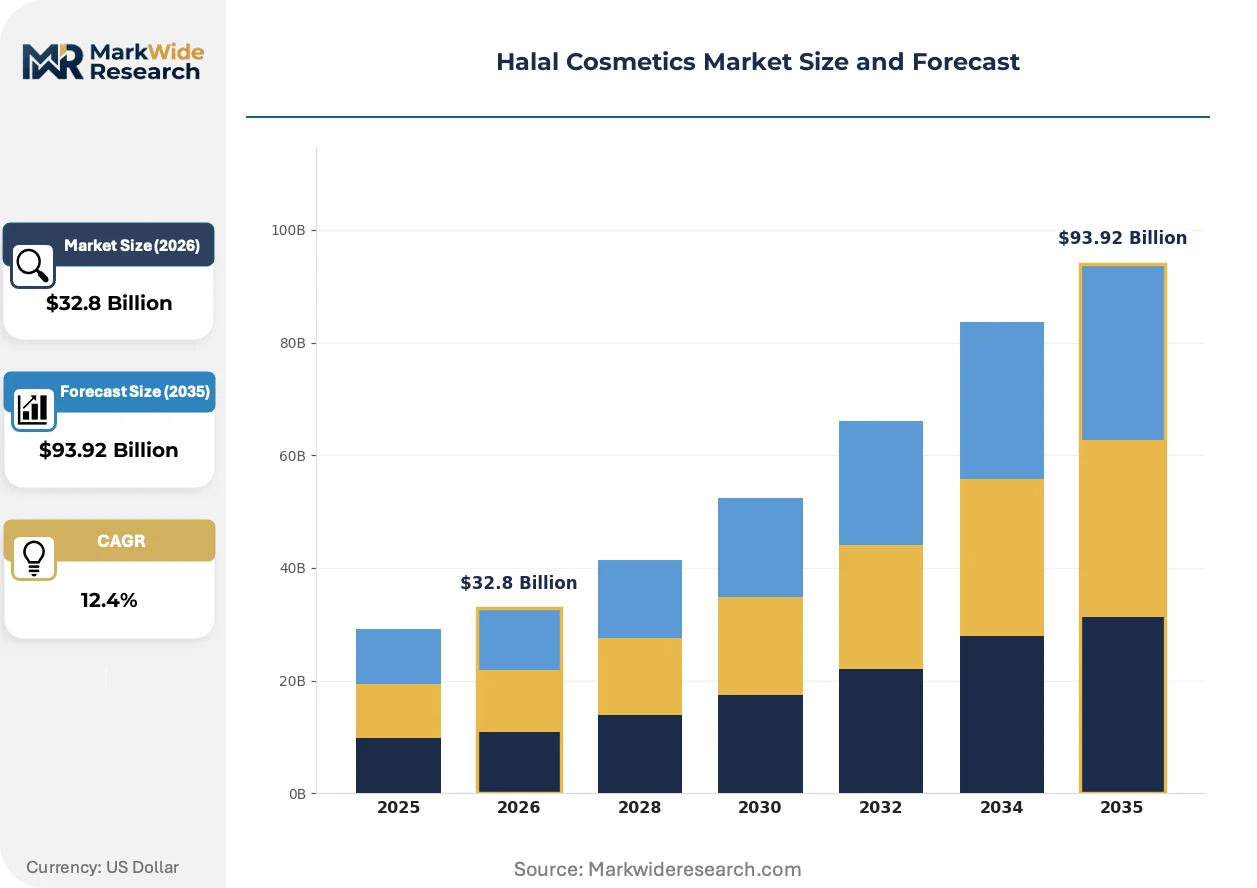
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $93.92 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Application: Personal Use, Professional Use, Retail, Online Sales Customer Type: Millennials, Gen Z, Professionals, Beauty Enthusiasts Ingredient Source: Botanical, Organic, Synthetic Free, Others |
| Companies Covered | Clara International Beauty Group, IVY Beauty Corporation, Amara Halal Cosmetics, INIKA Organic, IBA Halal Care, Wardah Cosmetics, PT Paragon Technology and Innovation, Martha Tilaar Group, PHB Ethical Beauty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halal Cosmetics Market Emerging Trajectories
Waterless and solid-format cosmetics are compressing packaging waste and reformulation complexity while aligning with Wudu-friendly usage requirements that prioritize rinse-free or minimal-water application protocols.
Biotechnology-derived halal collagen is overtaking marine and animal-sourced alternatives in premium skincare formulations. Malaysian contract manufacturers are adopting recombinant protein production at commercial scale. This shift is compressing reliance on fishery byproduct supply chains while enabling vegan-halal dual certification that commands shelf space in pharmacy and clinic channels.
REACH microplastic restrictions and ECHA labeling requirements are forcing pigment and glitter reformulation in color cosmetics. European import compliance now demands polyethene and polypropylene alternatives in rinse-off products. Halal-certified mica and mineral-based colorants are capturing share as compliant substitutes, with Turkish and Moroccan suppliers expanding processing capacity to serve EU-bound brands.
Subscription-based replenishment models are displacing traditional retail repurchase cycles in Southeast Asian urban markets. Indonesian direct-to-consumer platforms bundle skincare regimens with certification verification tools. This pattern concentrates most visibly in Jakarta and Surabaya, where smartphone penetration and logistics density support recurring revenue models that reduce customer acquisition costs for emerging halal beauty brands.
Halal Cosmetics Market Segmentation
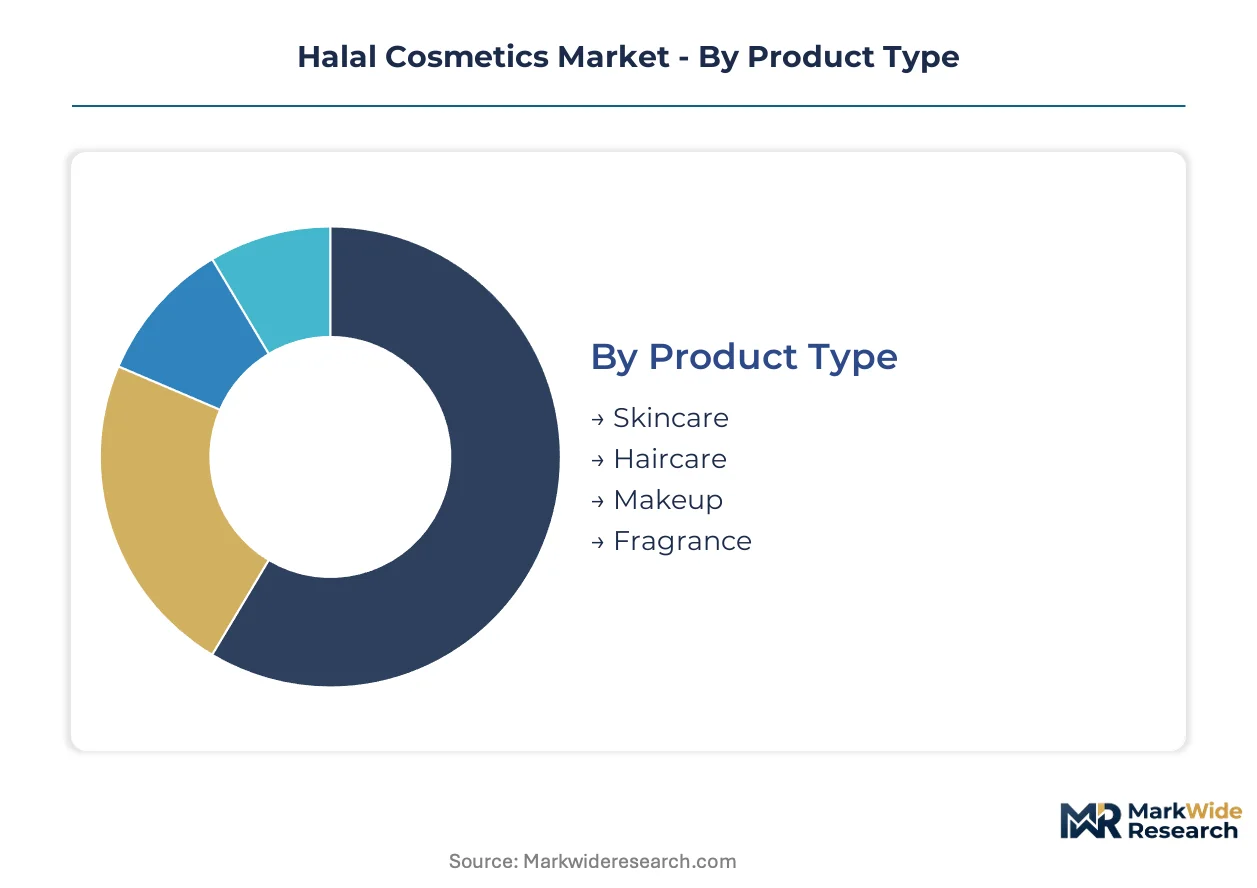
Halal cosmetics segmentation reveals distinct upgrade cycles across product categories, with skincare commanding premium replacement frequencies and application channels diverging sharply between ritual-aligned personal routines and professional salon services. Understanding these divides exposes where certification investments yield disproportionate returns.
Product Type:
Upgrade cycles vary dramatically by formulation complexity and shelf-life constraints, with liquid-based categories demanding more frequent repurchase than solid formats.
- Skincare:Serums, moisturizers, and cleansers formulated without alcohol-based penetration enhancers command the highest per-unit pricing and shortest replacement windows. Demand clusters in Indonesia and Malaysia where humid climates accelerate product turnover and pharmacy channels prioritize JAKIM-certified dermatological ranges.
- Makeup:Color cosmetics face compressed innovation cycles as pigment sourcing restrictions and alcohol-free preservation limits force continuous reformulation. Saudi Arabia's SFDA standards and Indonesia's BPJPH mandates are driving halal-compliant mica and mineral pigment adoption across foundation and eye product lines.
- Haircare:Shampoos and conditioners leverage plant-derived surfactants to replace conventional alcohol-based cleansing agents.
- Fragrance:Alcohol-free perfume oils and water-based mists serve prayer-compliant usage requirements.
Volume placements concentrate in Skincare; the faster expansion belongs to Makeup.
Application:
Channel economics separate high-touch professional validation from scaled direct-to-consumer efficiency, with regulatory compliance costs dictating viable entry points.
- Personal Use:Individual consumers purchasing for daily faith-aligned routines represent the foundational demand base, with Wudu-friendly waterless formats gaining traction among prayer-observant users in Southeast Asian urban centers.
- Professional Use:Salons and clinics require bulk certification documentation and batch-level traceability that only JAKIM-accredited manufacturers consistently supply, creating procurement concentration around Malaysian contract producers.
- Retail:Pharmacy and modern trade shelf placement demands slotting fees and certification display compliance that favors established Indonesian and Malaysian brands with existing distribution infrastructure.
- Online Sales:Direct-to-consumer platforms bypass conventional retail gatekeepers while capturing behavioral data for personalized regimen recommendations.
Revenue gravity sits with Personal Use; Online Sales are climbing the fastest as logistics density improves in Jakarta and Surabaya.
Customer Type:
Generational divides in digital fluency and ethical consumption priorities reshape marketing investment allocation across demographic cohorts.
- Millennials:This cohort balances established brand loyalty with emerging clean beauty expectations, driving demand for dual-certified vegan-halal products through pharmacy channels in Malaysia.
- Gen Z:Digital-native purchasers prioritize ingredient transparency and social media validation, accelerating adoption of blockchain-verified halal supply chains and influencer-endorsed Indonesian direct-to-consumer brands.
- Professionals:Time-constrained urban workers favor subscription replenishment models and multi-functional products that reduce decision fatigue.
- Beauty Enthusiasts:Hobbyist collectors drive limited-edition releases and shade-range expansion in color cosmetics.
Spending depth concentrates among Millennials; Gen Z is gaining share fastest through mobile-first platform engagement.
Ingredient Source:
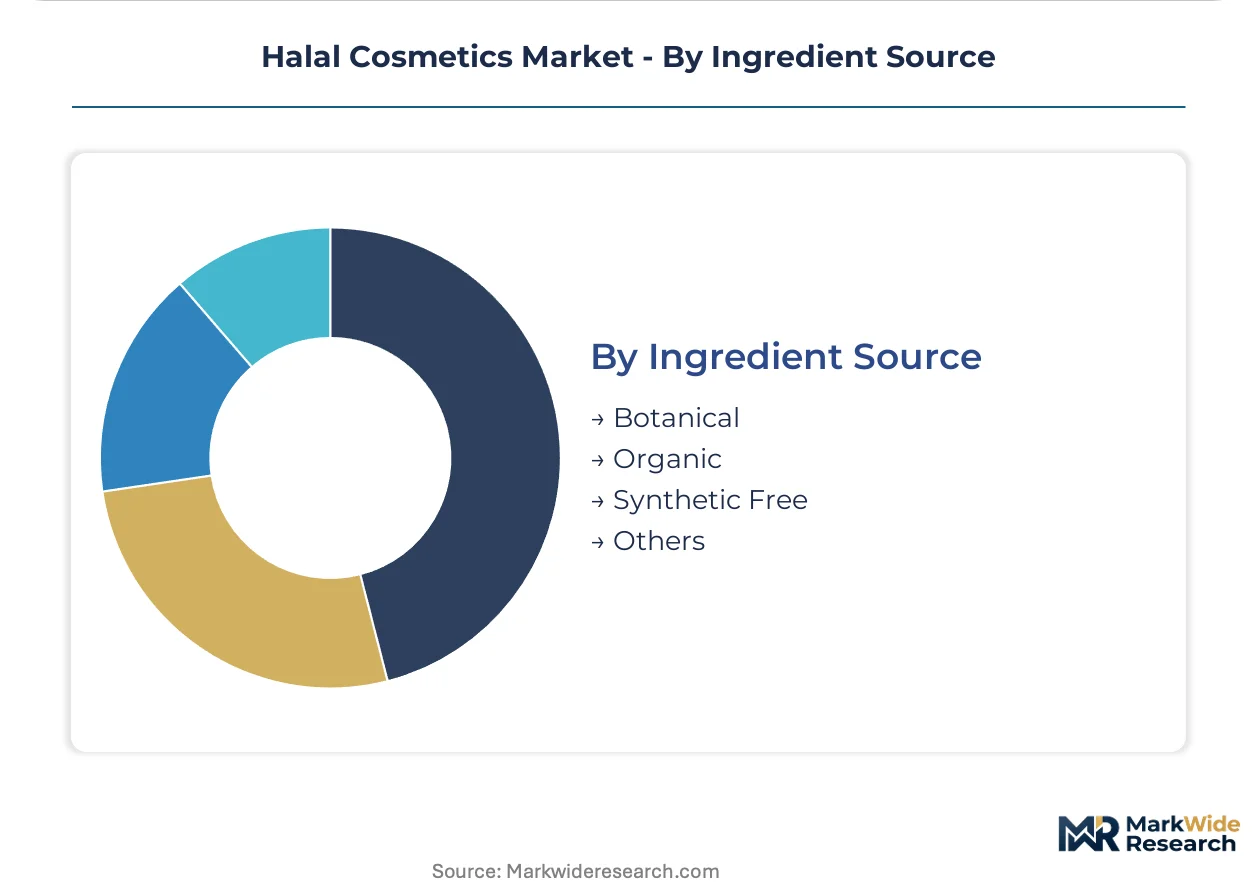
Raw material provenance determines certification complexity and premium positioning potential, with biotechnology alternatives disrupting traditional supply chains.
- Botanical:Plant-derived actives and carrier oils from Malaysian palm and Indonesian coconut supply chains dominate mass-market formulations, though EUDR deforestation due diligence requirements are tightening sourcing documentation standards.
- Organic:Certified organic halal ingredients command price premiums in pharmacy and clinic channels where clinical validation supports therapeutic claims, with demand concentrating among professional-use applications in Saudi Arabia.
- Synthetic Free:Formulations excluding petroleum-derived and chemically processed inputs appeal to clean beauty crossover segments.
- Others:Biotechnology-derived alternatives including microbial collagen and fermentation-produced actives serve vegan-halal dual certification requirements.
Production scale favors Botanical; Biotechnology alternatives under Others show the steepest expansion trajectory as Malaysian manufacturers scale recombinant protein capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta anchors halal cosmetics manufacturing and distribution across Southeast Asia, with its logistics corridors feeding certified product flows into domestic Indonesian shelves and export channels throughout the Muslim-majority world.
Indonesia
Domestic consumption of faith-aligned skincare and color cosmetics accelerates through pharmacy and modern trade expansion in Surabaya and Bandung. BPJPH mandatory halal certification deadlines compel reformulation investments across legacy portfolios. Jakarta-based contract manufacturers are scaling dedicated halal production lines to serve both local brands and export orders into Malaysia and Gulf markets.
Malaysia
Pharmacy channel penetration and clinic-grade dermatological positioning drive premium-tier demand in Kuala Lumpur and Penang. JAKIM certification requirements enforce stringent supply chain audit standards that elevate compliance costs for entrants. The Klang Valley industrial corridor concentrates formulation facilities serving cross-border distribution into Indonesia and Brunei.
Saudi Arabia
Professional salon services and luxury retail placement create high-margin opportunities for certified color cosmetics in Riyadh and Jeddah. SFDA halal standards align with Gulf Cooperation Council technical regulations, streamlining multi-market access for compliant manufacturers. The Eastern Province petrochemical cluster supplies halal-compliant emulsifier feedstocks to regional formulators.
United Arab Emirates
Dubai's free zone infrastructure and re-export hub status attract halal beauty brands seeking Middle East and Africa market access. MOHAP cosmetic registration requirements intersect with halal verification protocols, creating dual-compliance pathways. Jebel Ali logistics corridors distribute certified products into North African and Levantine markets with reduced tariff friction.
Turkey
European export orientation and domestic Muslim consumer bases converge in Istanbul and Izmir manufacturing zones. REACH microplastic restrictions and ECHA labeling requirements force pigment reformulation that aligns with halal-compliant mineral alternatives. The Marmara region processes halal-certified mica and colorant supplies for EU-bound brands.
Halal Cosmetics Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the halal cosmetics value chain, with integrated manufacturers controlling ingredient sourcing and certification audit trails while brand houses focus on formulation IP and channel placement. The vendor base concentrates around Southeast Asian production clusters where JAKIM and BPJPH accreditation creates defensible positioning. Three archetypes dominate: integrated Malaysian-Indonesian manufacturers with captive certification capabilities, European clean-beauty crossovers leveraging vegan-halal dual positioning, and Gulf-based specialists serving professional salon channels. Capacity expansion in biotechnology-derived collagen and dedicated halal production line investments represent the primary competitive vectors.
Among Southeast Asian integrated manufacturers, Clara International Beauty Group exemplifies the pharmacy-channel archetype with its Malaysian production footprint, while Wardah Cosmetics occupies the mass-market position through Indonesian drugstore dominance. INIKA Organic represents the European crossover tier, anchoring vegan-halal dual certification for premium positioning. These three entities collectively illustrate how geographic origin and channel focus stratify competitive access rather than scale alone.
| Leading Market Players |
|---|
| Clara International Beauty Group |
| IVY Beauty Corporation |
| Amara Halal Cosmetics |
| INIKA Organic |
| IBA Halal Care |
| Wardah Cosmetics |
| PT Paragon Technology and Innovation |
| Martha Tilaar Group |
| PHB Ethical Beauty |
| Others |
Supply Flow & Price Mechanics
Certification audit costs cascade through halal cosmetics manufacturing, with JAKIM and BPJPH accreditation fees compressing margins at the formulation stage before amplifying into pharmacy-channel premiums and mass-market economy tiers downstream.
Pricing Analysis
Certification-grade value anchors pricing tiers across the halal cosmetics landscape. Three-tier pricing structure across premium, standard, and economy levels separates JAKIM-accredited dermatological ranges from BPJPH-compliant mass-market SKUs and uncertified commodity alternatives. Price differentiation hinges on audit documentation depth and halal production line exclusivity. Cost compression in the mass tier is intensifying because Indonesian contract manufacturers are scaling dedicated halal capacity. Professional salon buyers exhibit lowest price sensitivity due to bulk certification requirements, while Gen Z direct-to-consumer purchasers show highest elasticity to subscription discounts.
Supply Chain Analysis
Freight cost volatility from Malaysian palm oil clusters to Jakarta formulation plants is reshaping regional sourcing patterns. Manufacturing concentrates in Indonesia, Malaysia, and Turkey. Raw material procurement draws from Indonesian coconut-derived surfactants, Malaysian palm-based emulsifiers, and Turkish mineral pigment supplies. Single-source certification vulnerability persists where JAKIM and BPJPH maintain non-reciprocal auditor networks. Distribution runs through pharmacy channel gatekeepers in Kuala Lumpur and modern trade retail in Surabaya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Halal cosmetics has become a vertical-integration race where captive certification capabilities and dedicated production line investments determine who captures pharmacy-channel premiums versus mass-market volume.
For Market Incumbents: Extend JAKIM-accredited manufacturing capacity into Vietnam and Philippines ahead of regulatory maturation. Deepen backward integration into biotechnology-derived collagen production to offset marine supply volatility. Certification reciprocity negotiations between Southeast Asian and Gulf bodies threaten margin compression for brands lacking multi-jurisdiction audit capabilities. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest customer acquisition cost route into Indonesian urban markets. Target Vietnam's nascent halal infrastructure before BPJPH-equivalent frameworks mature. Leverage blockchain-verified supply chain transparency as the primary go-to-market angle to differentiate against established Indonesian mass-market brands. For Investors and Strategic Acquirers: BPJPH mandatory halal law enforcement completion is the leading indicator that certification-scarce product windows are closing. Position for five-to-ten-year holding periods where dual-certified vegan-halal positioning captures clean beauty crossover premiums. Monitor biotechnology-derived ingredient capacity buildouts as the inflection signal for which contract manufacturers will secure pharmacy-channel exclusivity.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Capacity Expansion | JAKIM and BPJPH parallel accreditation opens Gulf and Southeast Asian pharmacy channels simultaneously. |
| Biotechnology Ingredient Integration | Microbial collagen production in Malaysian facilities reduces fishery byproduct dependency for vegan-halal dual claims. |
| Direct-to-Consumer Platform Launch | Subscription models in Jakarta and Surabaya bypass modern trade slotting fees while capturing behavioral data. |
| Cross-Border Production Partnership | Vietnamese contract manufacturing ahead of regulatory maturation secures first-mover positioning. |
| Sustainability Repositioning | EU Green Deal alignment enables CSRD-compliant export positioning for European clean beauty crossover segments. |
Methodological Framework
Document review covered BPJPH regulatory filings, JAKIM certification databases, and customs trade records, complemented by interviews with halal cosmetics brand managers, pharmacy procurement leads, contract manufacturing operations heads, and biotechnology ingredient suppliers. Secondary validation drew from EUDR deforestation compliance disclosures, REACH microplastic restriction updates, and Southeast Asian retail audit data. Bottom-up SKU-level volume estimates triangulated against top-down national halal certification issuance trends.
Historical certification penetration patterns cross-referenced against expert panel assessments of BPJPH enforcement timelines and JAKIM-SFDA reciprocity negotiations. Segmentation modeling spanned product type, application channel, customer generation cohort, and ingredient source technology across the projection horizon. CAGRs derived from certified product scarcity windows, reformulation investment cycles, and channel expansion trajectories. Forecast inputs included biotechnology manufacturing scale-up curves and palm oil derivative price elasticity assumptions.
The model holds under sustained BPJPH enforcement and stable palm supply chain conditions; deviation in certification reciprocity agreements or EUDR due diligence implementation would shift volume concentration between Southeast Asian and Gulf manufacturing hubs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
Philippines Skin Care Products Market
Cosmetics & Skincare
Natural and Organic Lipstick Market
Cosmetics & Skincare
Halal Cosmetic Products Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
Face Bronzer Market
Cosmetics & Skincare
Probiotic Skin Care Cosmetic Product Market
Cosmetics & Skincare
Deodorant Stick Market
Cosmetics & Skincare
Makeup Remover Market
Cosmetics & Skincare
Eye Shadow Stick Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
Cold Pressed Soap Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
Lip Scrub Market