
 Asia-Pacific Cosmetics Market | 2026-2036
Asia-Pacific Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cosmetics Market Insights
Market Context
Premium cosmetic pricing is decoupling from mass-market value propositions across Asia-Pacific, as ingredient transparency and clinical positioning command widening margin spreads. L'Oréal SA leverages its dermatological science heritage to anchor prestige tier positioning in China and Japan. Amorepacific Corporation differentiates through fermented botanical R&D and channel control across Korean duty-free and domestic specialty retail. Shiseido Co., Ltd. competes by extending its skin-biology expertise into personalized diagnostics and sensorial formulation.
Technical and Structural Dynamics
Cosmetics comprise chemically formulated preparations—emulsions, suspensions, or anhydrous systems—designed for topical application to cleanse, beautify, or alter skin, hair, or nail appearance, with stability specifications typically requiring pH ranges of 4.0–7.5 and preservative efficacy against standardized microbial challenge tests. Skincare dominates value generation across Asia-Pacific, where anti-aging serums and barrier-repair essences capture the deepest margin pools, while online retail grows fastest as live-stream commerce and social-platform storefronts displace traditional department store traffic. Haircare remains comparatively mature in Japan but accelerates in India and Southeast Asia as salon culture and scalp-health awareness expand.
Regulatory Framework and Outlook
China's NMPA implements pre-market registration for special cosmetics and post-market surveillance through adverse-effect reporting, while South Korea's MFDS enforces functional cosmetics approval for whitening and anti-wrinkle claims, and Japan's Ministry of Health, Labour and Welfare maintains quasi-drug classification for medicated products with active ingredients. These frameworks shape demand by determining which formulations gain market access and what clinical substantiation investments brands must make. Stakeholders must monitor regulatory harmonization pressures across ASEAN cosmetic directive alignment and China's evolving animal-testing exemptions for imported general cosmetics.
Market Dynamics
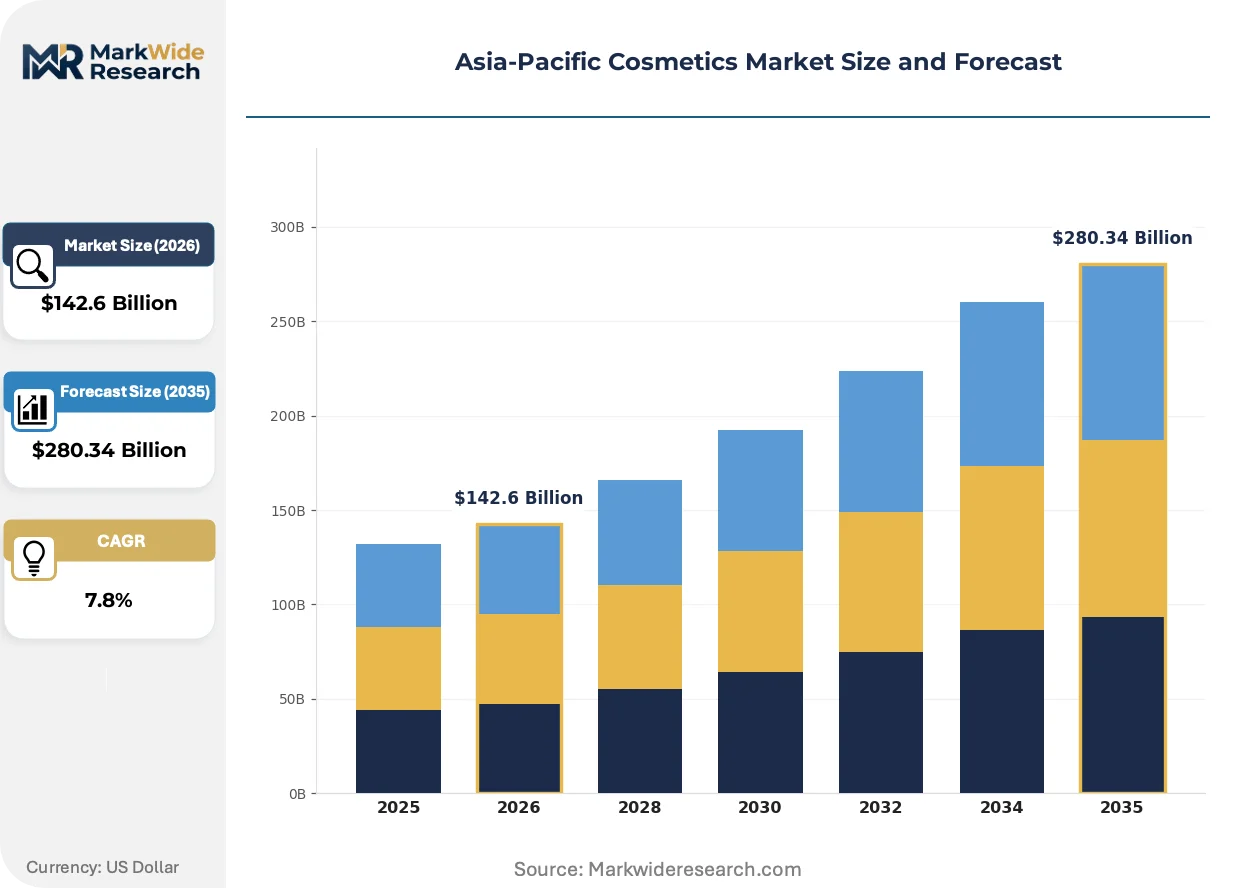
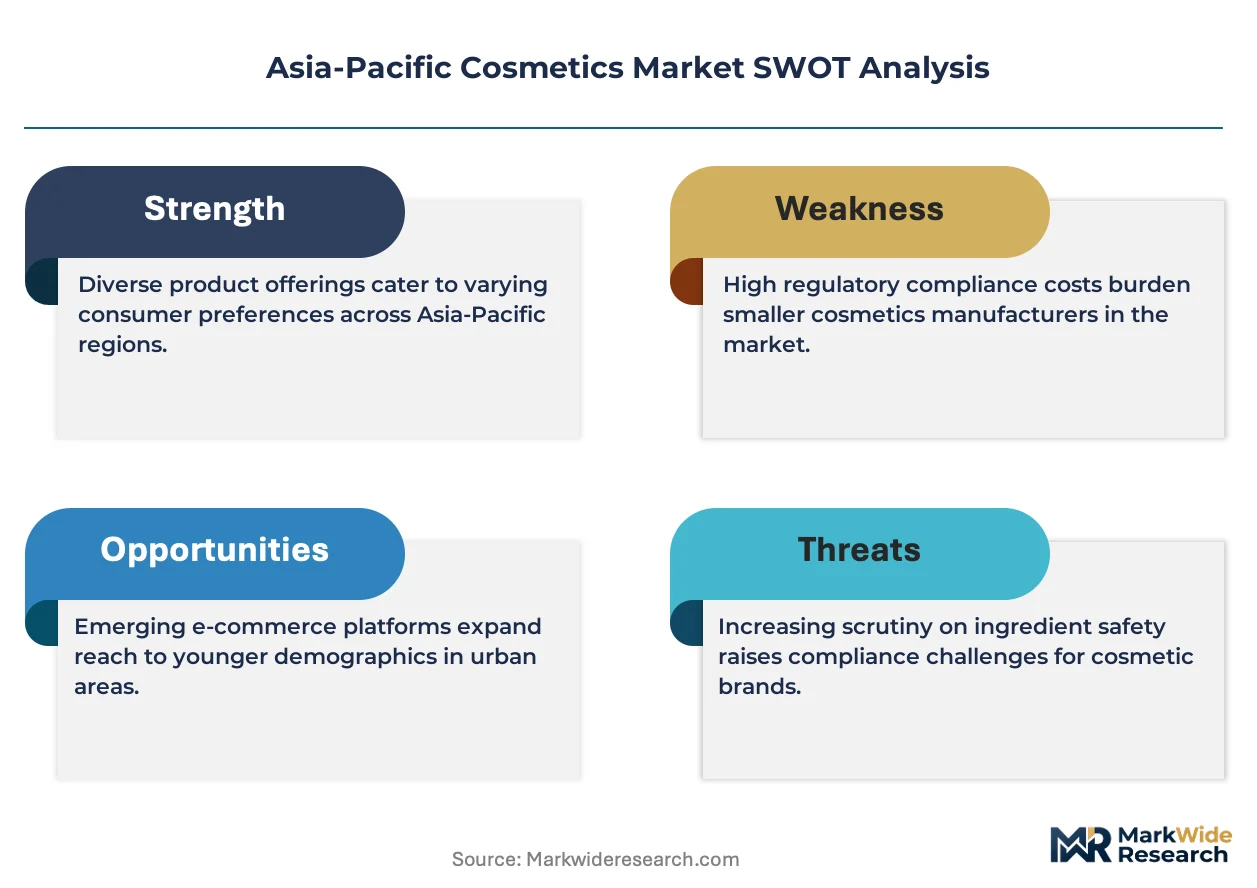
China's NMPA ingredient safety tightening is forcing simultaneous reformulation across mass and prestige tiers, compressing product development timelines while elevating compliance costs for brands serving the region's largest consumer base.
Growth Catalysts
- Live-stream commerce infrastructure:Platform-native storefronts on Douyin and Xiaohongshu are collapsing traditional retail intermediaries in China and South Korea, accelerating trial-to-purchase conversion for skincare launches.
- MFDS functional cosmetics pathway:South Korea's streamlined whitening and anti-wrinkle claim approvals are shortening time-to-market for evidence-based products, anchoring Seoul-Incheon as regional R&D export hub.
- Male grooming norm shift:Social stigma erosion across India, Indonesia, and Vietnam is opening addressable population segments previously excluded from skincare and color cosmetics categories.
Market Restraints
- Botanical raw material volatility:Fermented extracts and hanbang ingredients face harvest-dependent supply swings, concentrating sourcing risk with Korean and Chinese agricultural cooperatives.
- NMPA registration backlog:Pre-market approval queues for special cosmetics extend commercialization timelines, freezing inventory commitments for imported prestige launches.
- Silicone substitution pressure:Clean beauty positioning is displacing cyclopentasiloxane and dimethicone in foundations, forcing texture reformulation without performance equivalence.
Strategic Opportunities
- India tier-two urbanization:Surat, Jaipur, and Lucknow present underpenetrated distribution white space as organized retail and e-commerce logistics reach secondary cities.
- Biotech-fermentation convergence:Precision fermentation of rare actives is enabling domestic production of previously imported peptides and ceramides, collapsing cost structures for mid-market brands.
- ASEAN directive harmonization:Alignment of cosmetic safety standards across Indonesia, Thailand, and Vietnam is reducing multi-country registration duplication, streamlining Southeast Asia expansion.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in emulsion stability and preservative systems is concentrating with senior talent at established houses, constraining indie brand technical capabilities.
- Clinical substantiation capex:In-vivo efficacy studies for functional claims require dedicated testing facilities, creating capital barriers for challenger brands without dermatological partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cosmetics Market |
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $280.34 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Fragrance, Haircare Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Department Stores Customer Type: Women, Men, Teenagers, Professionals Formulation: Organic, Synthetic, Natural, Mineral |
| Companies Covered | The Estée Lauder Companies Inc., Procter & Gamble, L'Oréal SA, LG Household & Health Care, Amorepacific Corporation, Shiseido Co., Ltd., Kao Corporation, Henkel AG & Co. KGaA, Unilever PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cosmetics Market Trends and Innovations
Ingredient traceability and biotech-derived actives are converging to redefine product architecture across Asia-Pacific, compressing the traditional boundary between naturals and synthetics while elevating transparency as a pricing determinant.
Precision fermentation is modularizing active ingredient supply chains. Bioreactor-cultured squalane and hyaluronic acid are achieving cost parity with plant-derived and animal-derived equivalents. Mid-market brands in China and South Korea are adopting these inputs fastest, collapsing the historical premium attached to rare botanical sourcing.
China's NMPA animal-testing exemption expansion for imported general cosmetics is altering market access economics. Brands previously confined to cross-border e-commerce can now pursue domestic registration without alternative testing waivers. European and American houses with cruelty-free positioning are accelerating physical retail expansion in Shanghai and Chengdu in response.
Subscription-based replenishment is displacing discretionary repurchase cycles in Japan and Australia. Skincare routines with predictable consumption rates are migrating to auto-ship models, compressing customer acquisition costs for direct-to-consumer operators. This pattern is most visible in serum and sunscreen categories where usage cadence is highest.
Asia-Pacific Cosmetics Market Segmentation
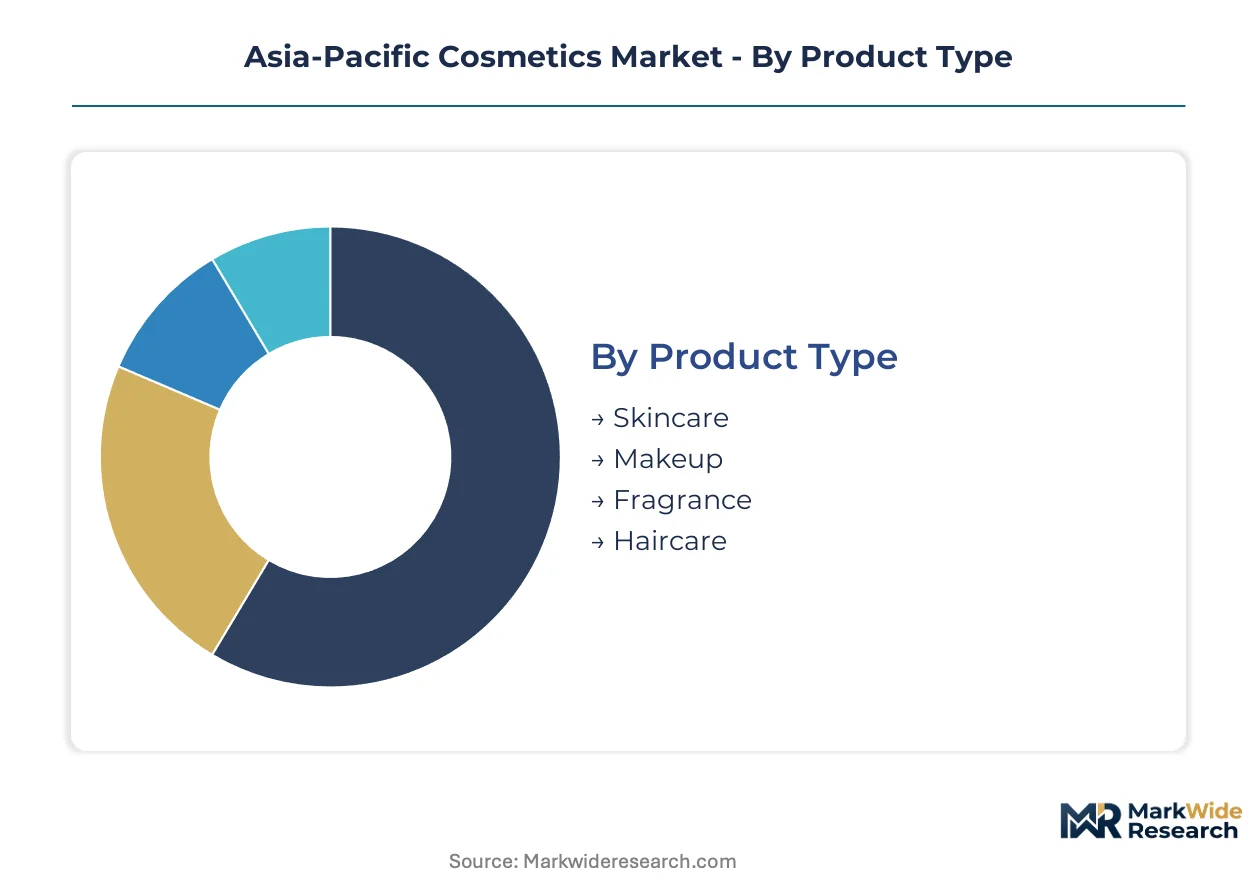
Segmentation in Asia-Pacific cosmetics reveals how formulation technology, channel infrastructure, and demographic targeting intersect to determine margin capture. Understanding these divisions exposes where R&D investment concentrates and which customer acquisition models are displacing legacy retail.
Product Type:
Formulation complexity and clinical positioning separate value tiers, with bioactive delivery systems commanding premium pricing against commodity bases.
- Skincare:Emulsion-based serums and barrier-repair essences incorporate fermented actives and peptide complexes. Demand concentrates in South Korea's Seoul-Incheon cluster, where MFDS functional cosmetics approvals anchor export manufacturing and domestic premium positioning.
- Makeup:Hybrid formulations merging color payoff with skincare benefits—tinted sunscreens, serum-infused foundations—dominate NMPA registration pipelines. China's live-stream commerce infrastructure accelerates trial-to-purchase for K-beauty color launches targeting tier-one cities.
- Fragrance:Niche and artisanal scents with regional botanical signatures—oud, cherry blossom, green tea—occupy growing shelf space in Japanese department stores and Chinese duty-free channels.
- Haircare:Scalp-health positioning and salon-grade treatments expand fastest in India and Southeast Asia as professional service culture penetrates secondary cities.
Mature deployment sits with Skincare. Newer deployment is concentrated in Haircare.
Distribution Channel:
Channel economics in Asia-Pacific are restructuring around platform-native commerce and experience-driven retail, collapsing traditional intermediary margins.
- Online Retail:Douyin and Xiaohongshu storefronts integrate live-stream demonstration with instant purchase, compressing customer acquisition costs for direct-to-consumer skincare brands. Auto-ship replenishment models for serums and sunscreens are displacing discretionary repurchase cycles in Japan and Australia.
- Specialty Stores:Korean beauty flagships and Japanese skin-biology boutiques control sensorial trial environments. Amorepacific's domestic network and Shiseido's personalized diagnostic counters anchor prestige tier positioning through consultation-based selling.
- Supermarkets:Mass-market cleansing and basic moisturizers occupy high-velocity shelf space, with private label expansion accelerating in India's organized retail growth corridors.
- Department Stores:Traffic erosion to digital channels forces floor-space consolidation, though Chinese and Japanese flagship locations retain importance for fragrance discovery and gift purchasing.
Volume leadership belongs to Online Retail. Margin expansion concentrates with Specialty Stores.
Customer Type:
Demographic targeting in Asia-Pacific is fragmenting as social norm shifts unlock previously excluded segments and professional identity drives category entry.
- Women:Multi-step skincare routines and color cosmetics remain the core revenue base, with anti-aging and brightening claims capturing deepest engagement across Chinese and Korean markets.
- Men:Fastest-expanding addressable population as stigma erosion in India, Indonesia, and Vietnam opens skincare and grooming categories. Male-specific lines with simplified positioning and matte texture profiles are gaining shelf space.
- Teenagers:Acne management and entry-level sun protection drive first-brand relationships, with social platform influence determining trial patterns.
- Professionals:Time-compressed routines favoring multifunction products—BB creams, cushion compacts, hybrid moisturizers—align with urban commuting cultures in Tokyo, Shanghai, and Singapore.
Established spend concentration sits with Women. Fastest addressable market expansion is occurring with Men.
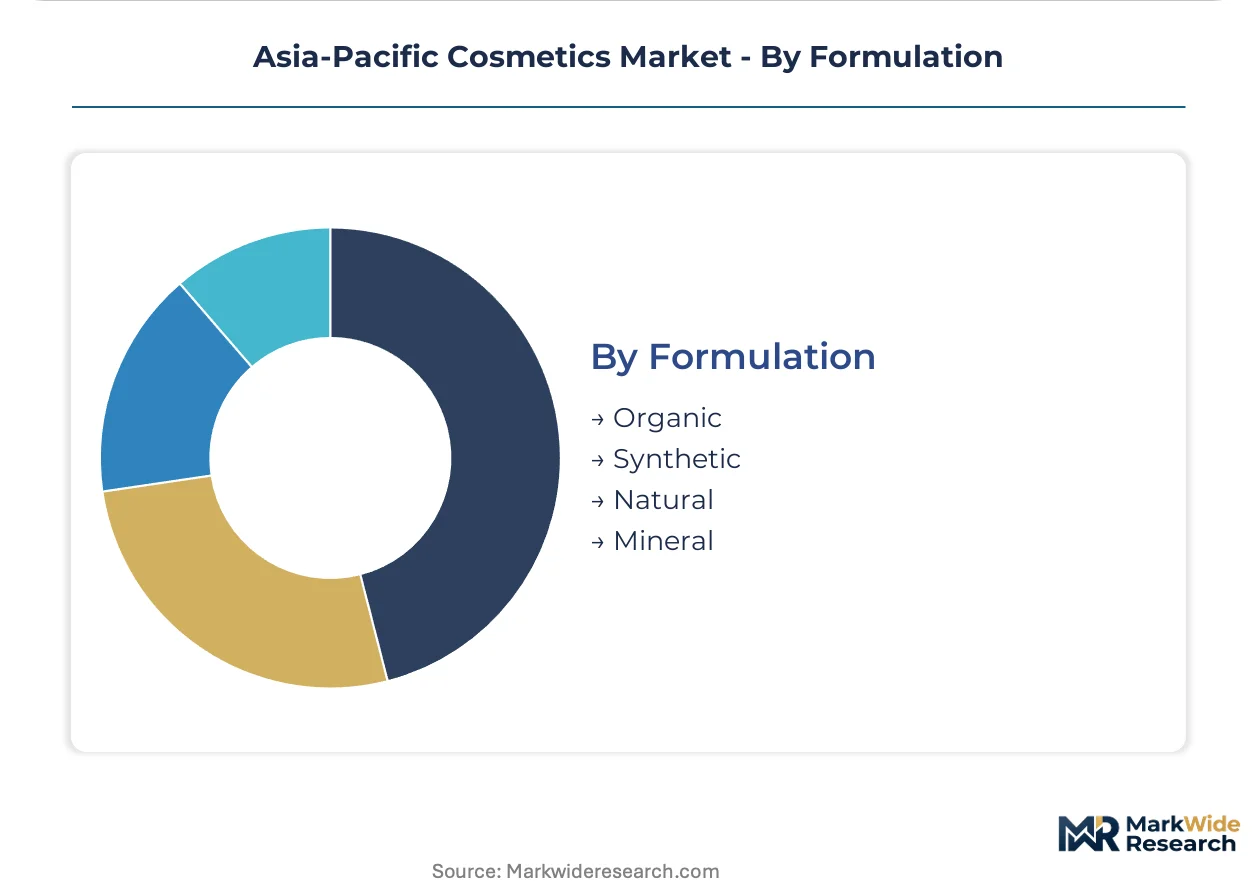
Formulation:
Raw material sourcing and regulatory substantiation requirements divide formulation approaches, with biotechnology disrupting traditional botanical supply chains.
- Organic:Certified agricultural inputs face harvest-dependent volatility, concentrating sourcing risk with Korean and Chinese cooperatives supplying hanbang and fermented extract houses.
- Synthetic:Precision fermentation of squalane, hyaluronic acid, and peptides is achieving cost parity with plant-derived equivalents, collapsing historical premiums attached to rare botanical sourcing.
- Natural:Clean beauty positioning drives silicone substitution and preservative system reformulation, though texture and stability challenges persist without cyclopentasiloxane and dimethicone.
- Mineral:Sunscreen actives and color cosmetics leverage inorganic UV filters and pigment suspensions, with NMPA safety tightening forcing titanium dioxide and zinc oxide grade verification.
Scale concentration sits with Synthetic. Technology transition momentum favors Natural.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Incheon corridor anchors Asia-Pacific cosmetics R&D and export manufacturing, with K-beauty innovation pipelines feeding demand across China, Southeast Asia, and beyond.
China
Live-stream commerce on Douyin and Xiaohongshu collapses traditional retail intermediaries, accelerating trial-to-purchase conversion for skincare launches. NMPA pre-market registration for special cosmetics extends commercialization timelines, freezing inventory commitments for imported prestige brands. Shanghai and Chengdu anchor physical retail expansion as animal-testing exemptions for general cosmetics open domestic registration pathways.
South Korea
MFDS functional cosmetics approvals for whitening and anti-wrinkle claims shorten time-to-market for evidence-based products. Seoul-Incheon concentrates fermented botanical R&D and duty-free export manufacturing. Amorepacific's domestic specialty network controls sensorial trial environments through consultation-based selling.
Japan
Skin-biology expertise and personalized diagnostics drive prestige tier positioning in Tokyo and Osaka. METI quasi-drug classification for medicated products shapes formulation investments and clinical substantiation requirements. Subscription-based auto-ship models for serums and sunscreens displace discretionary repurchase cycles.
India
Social stigma erosion opens male grooming categories previously excluded from skincare and color cosmetics. Organized retail expansion in Surat, Jaipur, and Lucknow presents underpenetrated distribution white space. BIS standards alignment and e-commerce logistics growth accelerate tier-two urbanization.
Vietnam
Salon culture penetration and scalp-health awareness expand haircare addressable markets in Ho Chi Minh City and Hanoi. ASEAN cosmetic directive harmonization reduces multi-country registration duplication. Clean beauty positioning drives silicone substitution in foundations without performance equivalence.
Asia-Pacific Cosmetics Market Competitive Landscape
Capital-heavy producers with integrated manufacturing compete with asset-light brand houses that outsource formulation and fill. The Asia-Pacific market structures around three tiers: multinational conglomerates with dermatological science heritage, regional champions controlling domestic specialty retail, and indie challengers dependent on platform-native commerce. Consolidation pressures intensify as NMPA compliance costs and clinical substantiation capex create capital barriers for smaller entrants. Dominant competitive moves include strategic partnerships with biotech fermentation suppliers and geographic expansion through cross-border e-commerce storefronts.
Among French-headquartered conglomerates, L'Oréal SA exemplifies the dermatological science archetype, leveraging research heritage to anchor prestige positioning in China and Japan. Amorepacific Corporation represents the regional champion model, with channel control across Korean duty-free and domestic specialty retail. Shiseido Co., Ltd. occupies a position bridging Japanese skin-biology expertise and personalized diagnostic capabilities.
| Leading Market Players |
|---|
| The Estée Lauder Companies Inc. |
| Procter & Gamble |
| L'Oréal SA |
| LG Household & Health Care |
| Amorepacific Corporation |
| Shiseido Co., Ltd. |
| Kao Corporation |
| Henkel AG & Co. KGaA |
| Unilever PLC |
| Others |
Pricing and Supply Chain Analysis
Fermented botanical extract indices and bioreactor-grade squalane benchmarks cascade through Asia-Pacific cosmetics supply chains, compressing margin spreads for mid-market brands while elevating premium positioning for clinical-grade formulations with MFDS functional cosmetics approvals.
Pricing Analysis
Value-based pricing anchored to clinical substantiation outcomes commands the widest spreads in this market. Three-tier pricing structure across premium, standard, and economy levels separates MFDS-approved functional cosmetics from basic emulsion bases, with certification grade and geographic delivery cost as primary differentiation drivers. Pricing pressure stems from NMPA reformulation mandates elevating compliance capex. Mass-market buyers exhibit highest price sensitivity, while prestige tier purchasers prioritize ingredient transparency over absolute cost.
Supply Chain Analysis
Dual-sourcing requirements for fermented actives and peptide complexes are now standard among Korean and Chinese formulators seeking to mitigate harvest-dependent volatility. Supply concentrates in South Korea, China, and Japan for bioreactor-cultured inputs and botanical extraction. Raw material dependencies center on precision-fermentation squalane, hyaluronic acid, and hanbang agricultural cooperatives. Single-source vulnerability in rare botanical sourcing creates structural risk. Distribution runs through platform-native storefronts on Douyin and Xiaohongshu alongside Seoul-Incheon export manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific cosmetics sits in a technology-transition phase where precision fermentation is displacing traditional botanical extraction, collapsing cost structures for previously premium actives while demanding new capital deployment from legacy houses.
For Market Incumbents: Lock in backward integration into bioreactor-cultured active production to defend margin position against indie challengers leveraging cost-parity inputs. Secure exclusive partnerships with Seoul-Incheon fermentation specialists before capacity constraints tighten. Channel control through Korean duty-free networks remains critical for prestige tier defense.
For New Entrants and Emerging Players: Enter via India's tier-two urban corridors—Surat, Jaipur, Lucknow—where organized retail penetration lags e-commerce logistics expansion. Target male grooming segments in Indonesia and Vietnam where social stigma erosion outpaces incumbent product development cycles. Deploy live-stream commerce infrastructure from launch to collapse customer acquisition costs.
For Investors and Strategic Acquirers: The window for entry favors biotech-fermentation specialists with scalable active ingredient platforms over traditional botanical houses. Long-term viability hinges on regulatory navigation capabilities across NMPA and MFDS frameworks. Watch NMPA animal-testing exemption expansion velocity as the inflection signal for European and American cruelty-free brand physical retail penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Fermentation Scale-Up | Domestic production of squalane and peptides collapses import dependency for mid-market brands. |
| MFDS Functional Cosmetics Approval | Streamlined whitening and anti-wrinkle pathways anchor Seoul-Incheon as regional R&D export hub. |
| Live-Stream Commerce Infrastructure | Douyin and Xiaohongshu storefronts displace department store traffic for skincare launches. |
| India Tier-Two Distribution Expansion | Surat, Jaipur, and Lucknow present underpenetrated white space as logistics networks mature. |
| NMPA Compliance Investment | Pre-market registration capabilities determine market access for imported prestige formulations. |
Research Methodology
Trade flow databases, MFDS registration filings, and NMPA adverse-effect reporting systems formed the secondary backbone, cross-referenced with primary interviews spanning formulation chemists at established houses, regulatory affairs leads navigating pre-market approval queues, procurement directors at Korean fermentation suppliers, brand managers deploying live-stream commerce infrastructure, and category buyers at Chinese platform-native retailers. Bottom-up volume modeling triangulated against top-down value estimates derived from duty-free channel audit data.
Historical trendline analysis of ingredient cost structures and channel migration patterns informed the analytical framework across the projection horizon, with segmentation dimensions spanning product type, distribution channel, customer demographic, and formulation technology. CAGRs emerged from regression against regulatory approval velocity and biotech-fermentation capacity expansion. Forecast inputs incorporated NMPA registration backlog duration and live-stream commerce conversion rate trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA regulatory acceleration or deceleration scenarios. Deviation in MFDS functional cosmetics approval timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Face Bronzer Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
Hyaluronic Acid Beauty Products Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
Makeup Setting Powder Market
Cosmetics & Skincare
Anti-Pollution Skin Care Products Market
Cosmetics & Skincare
Malaysia Skin Care Products Market
Cosmetics & Skincare
Makeup Remover Pen Market
Cosmetics & Skincare
North America Face Compact Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
Microbiome Cosmetic Products Market
Cosmetics & Skincare
Marine Hyaluronic Water Cream Market
Cosmetics & Skincare
Vietnam Skin Care Products Market
Cosmetics & Skincare
Bath Soap Market
Cosmetics & Skincare
Matte Lipstick Market