
 Hyaluronic Acid Beauty Products Market | 2026-2036
Hyaluronic Acid Beauty Products Market Size, Share, and Industry Trends Forecast 2026-2036
Hyaluronic Acid Beauty Products Market Foresight
ISO 10993 biocompatibility certification is collapsing the field of viable suppliers, forcing smaller formulators out of medical-grade segments. Bloomage Biotechnology Corporation Limited leverages captive fermentation capacity to anchor its position in pharmaceutical-grade sodium hyaluronate. Shiseido Company, Limited differentiates through proprietary low-molecular-weight processing technology that commands premium positioning in Japanese department store channels.
Hyaluronic acid beauty products are topical and injectable formulations containing glycosaminoglycan polymers that retain up to 1000 times their molecular weight in water, manufactured through microbial fermentation or avian extraction for dermal hydration and volume restoration. Serums dominate value pools due to higher active concentrations and repeat purchase frequency, while masks compete on trial-driven volume in Asian multi-step skincare routines. The vegan formulation segment is accelerating fastest as clean beauty certifications from ECOCERT and COSMOS reshape ingredient sourcing requirements across European pharmacy channels.
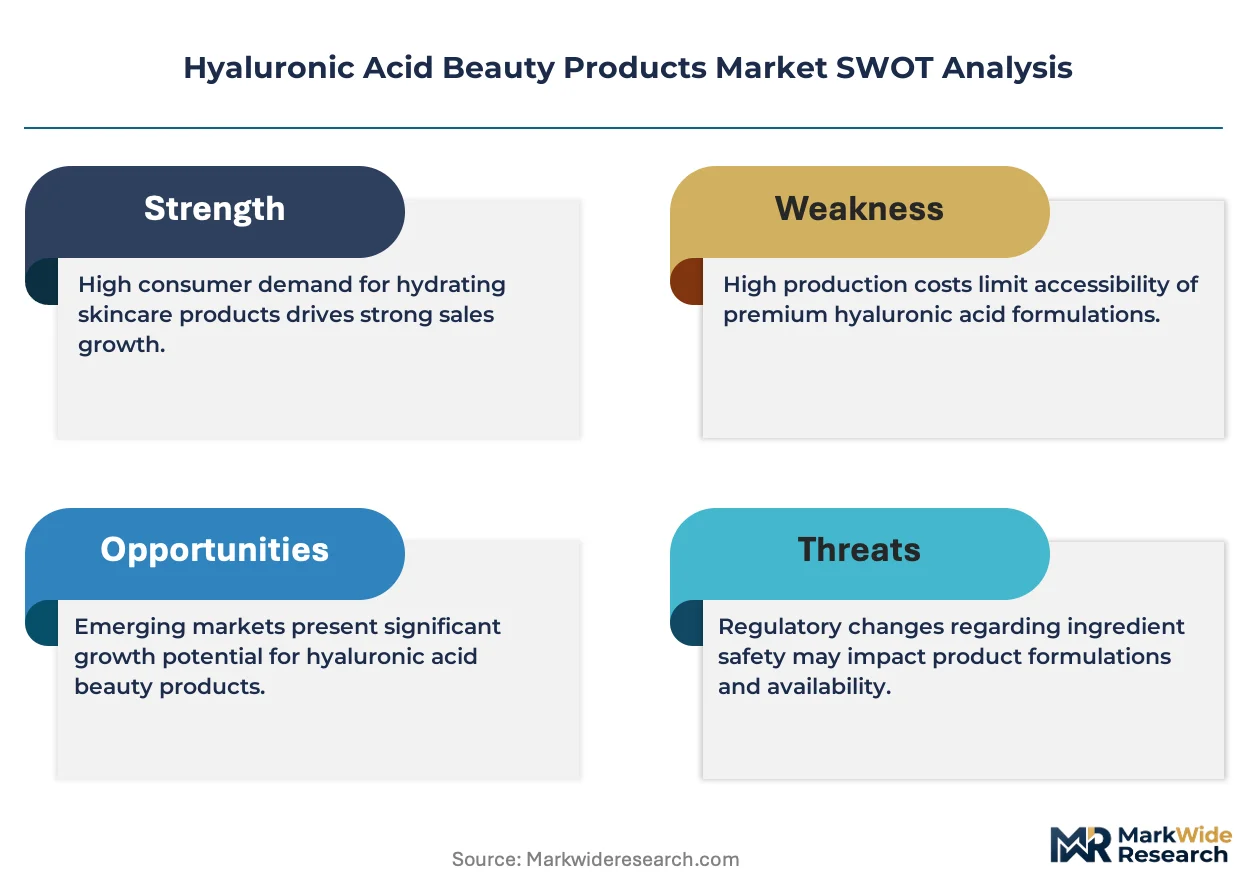
FDA oversight of dermal fillers as Class III medical devices and the EU MDR's tightened biocompatibility documentation are elevating compliance costs and consolidating market access among vertically integrated manufacturers. China's NMPA now requires animal-free sourcing declarations for imported hyaluronic acid used in cosmetic injections, reshaping supplier qualification protocols for cross-border brands. Stakeholders must monitor evolving clean-label certification thresholds and regional divergence in medical-cosmetic classification boundaries to preserve market access.
Market Dynamics
The EU MDR's tightened biocompatibility documentation requirements are collapsing the field of viable suppliers, forcing smaller formulators out of medical-grade segments and consolidating market access among vertically integrated manufacturers with captive fermentation capacity.
Growth Catalysts
- Seoul Metropolitan Beauty Cluster:South Korea's dense concentration of aesthetic clinics and professional spa channels is deepening adoption of injectable-grade serums, creating a self-reinforcing demand center for high-purity sodium hyaluronate.
- ISO 10993 Certification:The biocompatibility standard's elevation as a procurement gatekeeper is filtering out subscale suppliers and concentrating volume among pharmaceutical-grade manufacturers with dedicated quality infrastructure.
- Microbial Fermentation:This production method's displacement of avian extraction is eliminating animal-source contamination risks while enabling molecular-weight precision that avian-derived material cannot match.
Market Restraints
- Input Cost Volatility:Pharmaceutical-grade glucose and yeast extract prices fluctuate with agricultural commodity cycles, compressing margins for fermentation-dependent producers without long-term supply contracts.
- Supplier Concentration Risk:China's dominance in microbial fermentation capacity creates geographic single-point vulnerability for brands dependent on cross-border active pharmaceutical ingredient sourcing.
- Regulatory Friction:China's NMPA now requires animal-free sourcing declarations for imported hyaluronic acid used in cosmetic injections, adding documentation burden and inspection delays for non-fermentation suppliers.
Strategic Opportunities
- Clean Beauty Certification:ECOCERT and COSMOS standards are reshaping ingredient sourcing requirements across European pharmacy channels, creating premium positioning for vegan-formulation specialists.
- Low-Molecular-Weight Processing:Proprietary fractionation technology enabling deeper dermal penetration is commanding price premiums in Japanese department store channels where efficacy demonstration drives purchase decisions.
- Professional Channel Expansion:Medical spa and clinic networks in Germany and France are expanding service menus beyond injectables to include pre- and post-treatment topical protocols, opening recurring revenue streams for serum formulators.
Industry Challenges
- Compliance Timeline Compression:The EU MDR's 2021 implementation deadline forced simultaneous documentation overhauls across multiple product lines, straining regulatory affairs teams and delaying market re-entry for reformulated SKUs.
- Cross-Border Qualification Protocols:Divergent clean-label certification thresholds between ECOCERT, COSMOS, and emerging national standards require parallel testing programs that fragment R&D budgets and extend development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyaluronic Acid Beauty Products Market |
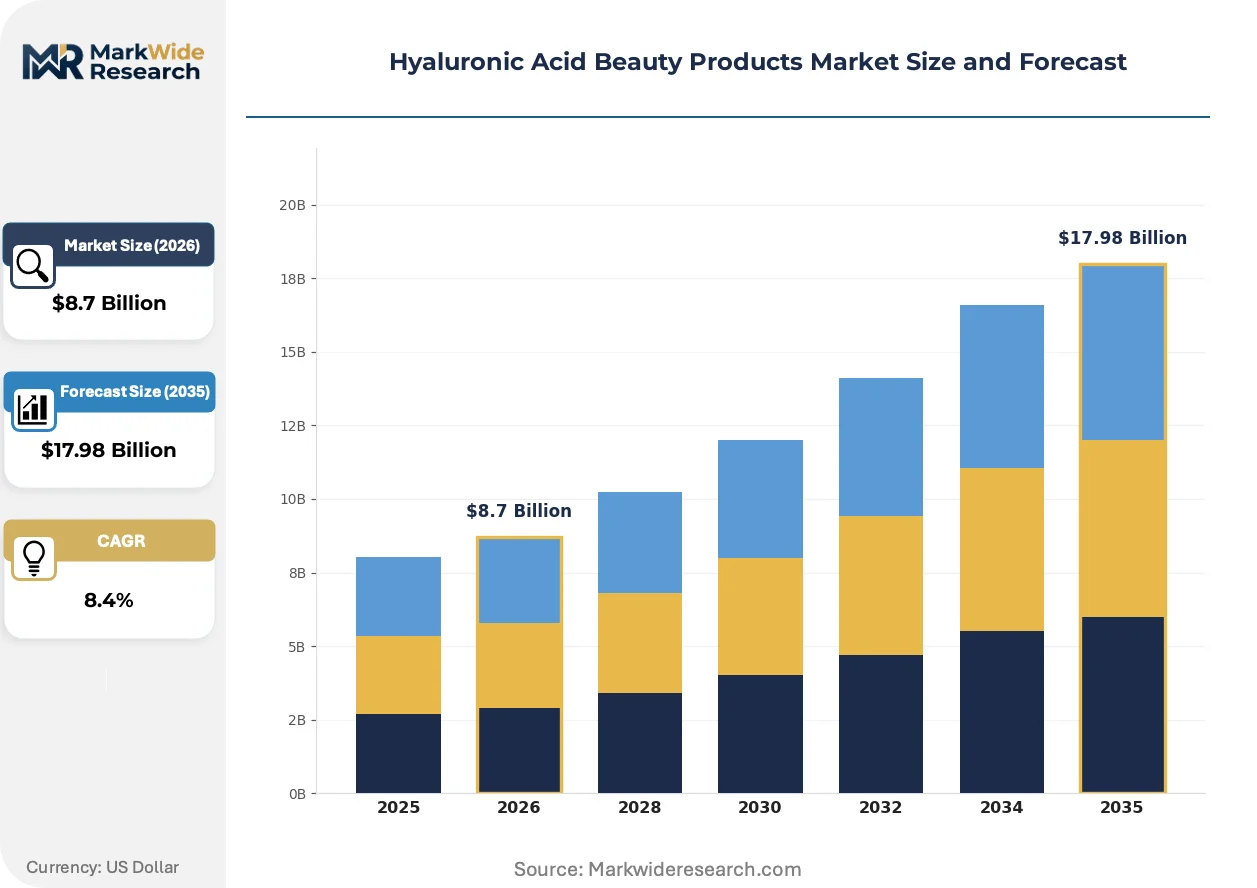
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Creams, Masks, Gels End User: Women, Men, Professionals, Spa Users Formulation: Natural, Organic, Synthetic, Vegan Distribution Channel: Online, Retail Stores, Salons, Pharmacies |
| Companies Covered | Bloomage Biotechnology Corporation Limited, Contipro AS, Givaudan SA, Shiseido Company, Limited, LG Household & Health Care Ltd., Kewpie Corporation, Fufeng Group, Allergan Aesthetics LLC, Galderma Laboratories L.P., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyaluronic Acid Beauty Products Market Shifts & Advancements
Biotechnology-driven molecular engineering is decomposing traditional boundaries between cosmetic and medical-grade hyaluronic acid, while regulatory convergence and channel specialization are reshaping how value flows through the value chain.
Low-molecular-weight fractionation technology is decomposing the historical premium attached to injectable dermal fillers. Korean aesthetic clinics now specify sub-50 kDa serums for at-home maintenance protocols, compressing the efficacy gap between professional and retail channels. This molecular precision is enabling formulators to command medical-grade pricing in cosmetic-only applications.
The EU MDR's biocompatibility documentation mandates are elevating compliance costs for dermal filler manufacturers. Class III medical device classification now requires ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization testing for every formulation variant. European suppliers with established quality management systems are absorbing smaller competitors unable to sustain the documentation burden.
Clean-label certification is displacing ingredient-list transparency as the primary purchase trigger in European pharmacy channels. German and French consumers now prioritize ECOCERT and COSMOS seals over brand heritage when selecting hyaluronic acid serums. This preference shift is forcing heritage brands to reformulate around vegan fermentation sources and eliminate residual animal-derived processing aids.
Hyaluronic Acid Beauty Products Market Segmentation
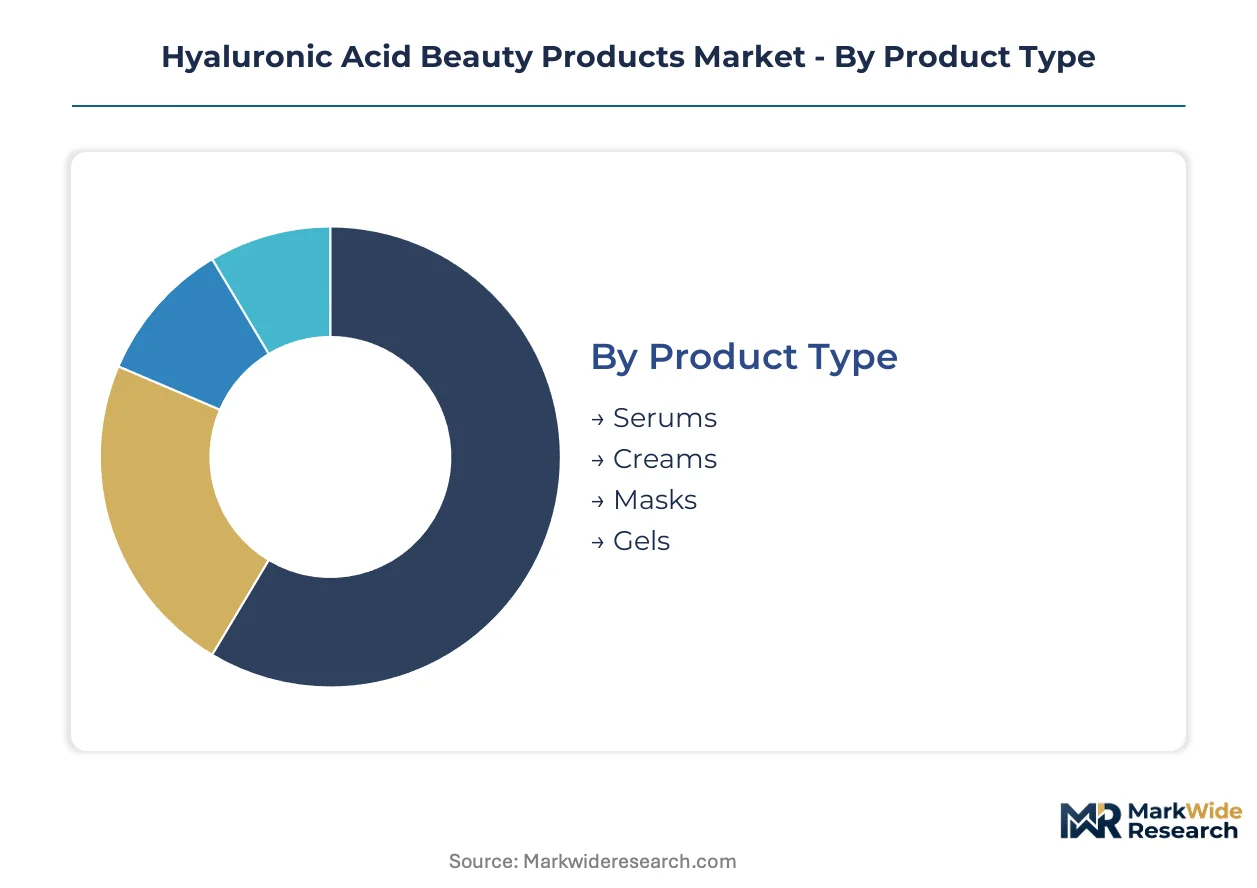
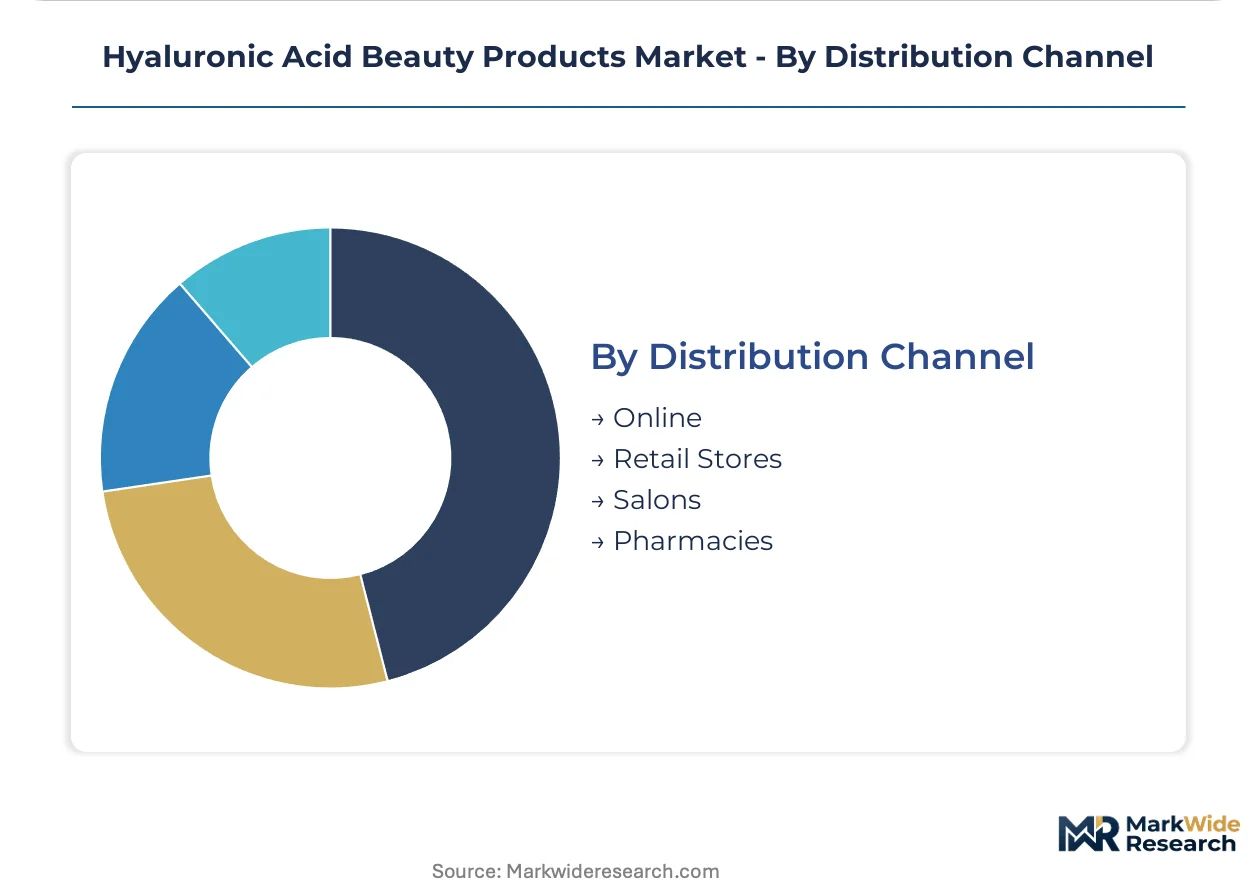
Channel specialization in hyaluronic acid beauty products creates distinct margin profiles and regulatory pathways. Each segment category routes through different procurement gatekeepers, from pharmacy certification requirements to professional clinic protocols.
Product Type:
Channel-mix dynamics concentrate high-margin serums in professional and premium retail channels, while masks and gels flow through volume-driven mass-market pathways.
- Serums:High-concentration aqueous formulations with molecular weights ranging from 50-1000 kDa enable precise dermal penetration claims. Seoul's aesthetic clinics specify pharmaceutical-grade serums for at-home maintenance protocols, compressing the efficacy gap between professional and retail applications.
- Masks:Sheet and hydrogel formats deliver intensive hydration through occlusive delivery mechanisms. South Korean multi-step skincare routines drive repeat trial purchases through subscription boxes and airport retail, creating volume concentration distinct from serum economics.
- Creams:Emulsion-based vehicles combining hyaluronic acid with occlusive agents for sustained moisture retention. Mass-market positioning in European pharmacy chains emphasizes ECOCERT compliance over concentration metrics.
- Gels:Lightweight, non-comedogenic textures targeting younger demographics and humid climate applications. Online direct-to-consumer brands favor gel formats for their shipping stability and lower formulation cost base.
Serums dominate installed base value. Masks are where expansion concentrates fastest.
End User:
Customer-type segmentation reveals divergent price elasticity and purchase frequency patterns across demographic and professional boundaries.
- Women:The core consumer base spans preventive aging applications in the 25-35 cohort through corrective treatments in the 50+ segment. Japanese department store channels command premium positioning through efficacy demonstration protocols tailored to this demographic.
- Men:Emerging segment concentrated in urban professional cohorts seeking simplified regimens. Korean male grooming specialists now stock hyaluronic acid as a standard post-shave hydrator, normalizing the ingredient beyond cosmetic stigma.
- Professionals:Dermatologists and aesthetic practitioners specify medical-grade formulations for pre- and post-procedure protocols. Germany's medical spa networks are expanding service menus to include professional-only topical systems.
- Spa Users:Experience-driven consumers seeking immediate visible results from professional application environments. French thalassotherapy centers incorporate hyaluronic acid into marine-based treatment protocols.
Women anchor current revenue. Men represent the steepest expansion trajectory.
Formulation:
Ingredient sourcing claims now function as primary purchase triggers in certified channels, displacing traditional brand loyalty.
- Vegan:Microbial fermentation-derived sodium hyaluronate eliminates animal-source contamination risks while satisfying clean beauty certification requirements. China's NMPA now mandates animal-free sourcing declarations for imported cosmetic injections, reshaping supplier qualification protocols.
- Natural:Plant-derived alternatives and minimally processed fermentation extracts targeting consumers seeking ingredient list transparency. European pharmacy consumers prioritize ECOCERT and COSMOS seals over heritage brand recognition.
- Organic:Formulations meeting COSMOS organic certification thresholds for agricultural input sourcing. Supply constraints on certified organic glucose feedstocks limit scale and concentrate production among established fermentation operators.
- Synthetic:Chemically modified cross-linked variants for enhanced stability and residence time in dermal applications. Class III medical device classification under FDA and EU MDR frameworks restricts this segment to vertically integrated manufacturers with dedicated quality infrastructure.
Vegan formulations dominate new product development. Synthetic variants concentrate where medical-cosmetic boundaries blur.
Distribution Channel:
Channel selection determines regulatory exposure, margin structure, and consumer education requirements.
- Pharmacies:European pharmacy channels enforce ECOCERT and COSMOS compliance as table stakes, creating premium positioning for certified vegan formulations. German and French consumers now prioritize certification seals over brand heritage.
- Salons:Professional service environments enable medical-grade product application without prescription requirements. Korean aesthetic clinics deepen adoption of injectable-grade serums through membership-based maintenance protocols.
- Online:Direct-to-consumer platforms enable molecular-weight specificity and subscription replenishment models. Cross-border e-commerce faces documentation delays from China's NMPA animal-free sourcing declaration requirements.
- Retail Stores:Department store and specialty beauty retail depend on tactile trial and immediate gratification. Japanese channels reward proprietary low-molecular-weight processing technology with premium positioning.
Pharmacies dominate certified-formulation volume. Salons capture the highest per-transaction value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS registration pathways for aesthetic device imports are tightening documentation requirements for Seoul-based clinic networks. This regulatory pressure is redistributing procurement toward domestic fermentation suppliers with established quality infrastructure.
South Korea
Seoul's Gangnam district aesthetic clinics specify pharmaceutical-grade serums for membership-based maintenance protocols. MFDS now mandates ISO 10993 biocompatibility documentation for all imported dermal fillers. The Seoul Capital Area concentrates over 60 percent of national medical spa channel volume.
China
NMPA animal-free sourcing declarations are reshaping supplier qualification for cross-border cosmetic injection brands. The Yangtze River Delta fermentation cluster supplies captive sodium hyaluronate to domestic pharmaceutical-grade manufacturers. Shanghai-based clinic chains are deepening adoption of microbial-derived serums for post-procedure protocols.
Japan
PMDA oversight of quasi-drug classifications elevates compliance costs for low-molecular-weight topical formulations. METI's support for biotechnology R&D is accelerating proprietary fractionation technology development. Osaka-based department store channels command premium positioning for efficacy-demonstrated serums.
Germany
EU MDR Class III medical device classification is filtering subscale dermal filler suppliers from pharmacy and clinic channels. BfArM enforcement of biocompatibility documentation is consolidating procurement among vertically integrated manufacturers. Bavaria's medical spa networks are expanding pre- and post-treatment topical service menus.
United States
FDA Class III medical device oversight of dermal fillers requires PMA or 510(k) pathways for market entry. The IRA's pharmaceutical pricing provisions are pressuring cost structures for injectable-grade materials. California's Los Angeles and San Francisco aesthetic clinic clusters drive demand for high-purity maintenance serums.
Hyaluronic Acid Beauty Products Market Competitive Landscape
Player mix skews toward fermentation-based biotechnology specialists with captive pharmaceutical-grade capacity. The vendor base concentrates among East Asian manufacturers with integrated quality management systems. Three archetypes dominate: microbial fermentation operators, proprietary processing technology licensors, and professional channel-focused formulators. Competitive moves center on backward integration into glucose feedstock supply and ISO 10993 certification acquisition to secure clinic network procurement.
Within the fermentation-specialist tier, Bloomage Biotechnology Corporation Limited and Kewpie Corporation exemplify archetypes of captive capacity deployment. Shiseido Company, Limited occupies a position representing proprietary low-molecular-weight processing differentiation. These three anchors illustrate how geographic concentration in East Asian biotechnology clusters intersects with divergent strategic positioning across retail and professional channels.
| Leading Market Players |
|---|
| Bloomage Biotechnology Corporation Limited |
| Contipro AS |
| Givaudan SA |
| Shiseido Company, Limited |
| LG Household & Health Care Ltd. |
| Kewpie Corporation |
| Fufeng Group |
| Allergan Aesthetics LLC |
| Galderma Laboratories L.P. |
| Others |
Supply & Pricing Matrix
ISO 10993 biocompatibility certification gates both supplier qualification and price differentiation simultaneously, concentrating procurement power among pharmaceutical-grade manufacturers while collapsing margins for subscale formulators unable to sustain documentation burdens. The regulatory threshold forces a bifurcation where certified players command medical-grade premiums and uncertified competitors retreat to cosmetic-only positioning.
Pricing Analysis
Cost-plus contracts with pharmaceutical-grade glucose indexation anchor long-term supply agreements between fermentation operators and clinic networks. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and mass-market tiers reflects ISO certification status and molecular-weight precision capabilities. Cost compression in cosmetic-grade serums is intensifying because Korean aesthetic clinics now specify sub-50 kDa formulations for at-home maintenance protocols. Professional channel buyers exhibit the lowest price sensitivity due to membership-based patient retention models, while mass-market online consumers drive aggressive promotional discounting.
Supply Chain Analysis
Shanghai Port customs clearance for animal-free sourcing declarations creates a chokepoint that underwrites delivery timeline risk for cross-border brands dependent on Chinese fermentation capacity. Microbial fermentation supply concentrates in China, South Korea, and Japan, with the Yangtze River Delta cluster feeding captive sodium hyaluronate to domestic pharmaceutical-grade manufacturers. Pharmaceutical-grade glucose and yeast extract feedstocks draw from agricultural commodity markets, exposing margin stability to input cost volatility. Single-source vulnerability runs through China's dominance in fermentation infrastructure, where NMPA documentation requirements now delay non-fermentation supplier qualification. Distribution runs through professional clinic networks in Seoul and Osaka for premium tiers, European pharmacy chains for certified vegan formulations, and direct-to-consumer platforms for trial-driven mask volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. ISO 10993 certification investment generates switching costs that lock clinic networks into qualified supplier relationships.
For Market Incumbents: Compound regulatory entrenchment by accelerating ISO 10993-5 and ISO 10993-10 certification acquisition for formulation variants ahead of EU MDR documentation deadlines. Deepen backward integration into pharmaceutical-grade glucose supply contracts to buffer agricultural commodity volatility. The threat of Korean aesthetic clinics consolidating procurement around domestic fermentation suppliers with established MFDS quality infrastructure demands preemptive capacity positioning in the Seoul Capital Area. For New Entrants and Emerging Players: COSMOS certification fast-track programs open white-space positioning in German and French pharmacy channels where heritage brands lag vegan reformulation timelines. Target men's grooming segments in Korean urban professional cohorts where hyaluronic acid normalization as a post-shave standard creates trial entry points. The most penetrable geography is Bavaria's expanding medical spa networks, where pre- and post-treatment topical service menus lack dedicated serum formulators. A direct-to-consumer subscription model with molecular-weight specificity claims bypasses incumbent pharmacy shelf dominance. For Investors and Strategic Acquirers: EU MDR's tightened biocompatibility documentation reshapes the acquisition landscape toward vertically integrated fermentation operators with captive pharmaceutical-grade capacity. The five-to-ten year viability window favors targets with established quality management systems absorbing documentation-burdened competitors. Acquisition archetype: East Asian biotechnology specialists with integrated glucose feedstock supply and ISO 10993 certification infrastructure. The signal to watch is MFDS registration pathway tightening for imported aesthetic devices, which redistributes procurement toward domestic fermentation suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Certification Acquisition | Biocompatibility documentation gates clinic network procurement and collapses competitor field. |
| Backward Integration into Glucose Supply | Captive pharmaceutical-grade feedstock contracts buffer agricultural commodity price volatility. |
| Professional Channel Expansion | German and French medical spa networks open recurring revenue for pre- and post-treatment protocols. |
| Low-Molecular-Weight Processing Investment | Sub-50 kDa fractionation technology commands premium positioning in Japanese department stores. |
| COSMOS Certification Fast-Track | Clean beauty seals displace brand heritage as primary purchase trigger in European pharmacy channels. |
Research Methodology
Operator-level perspectives from fermentation plant managers, regulatory affairs leads at dermal filler manufacturers, pharmacy category buyers in Germany and France, and aesthetic clinic procurement directors anchored the qualitative base. These primary interviews combined with secondary validation from FDA 510(k) filings, EMA MDR documentation databases, MFDS registration records, and NMPA animal-free sourcing declaration requirements. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against regional channel value flows ensured consistency.
Sensitivity analysis across the analysis window tested forecast robustness to regulatory timeline compression and input cost volatility assumptions. The analytical framework modeled segmentation dimensions including product type, end-user demographic, formulation certification tier, and distribution channel regulatory exposure. CAGRs derived from installed base growth rates and replacement cycle analysis across professional and retail channel mixes. Molecular-weight precision capabilities and clean beauty certification penetration served as industry-specific forecast inputs.
Underlying assumptions cover EU MDR documentation compliance timelines and NMPA import declaration processing efficiency, with deviation risk concentrated in regulatory enforcement intensity and agricultural commodity price cycles. Practitioners should keep alternative scenarios live as biocompatibility certification thresholds and clean-label standard convergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Halal Cosmetics Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
Global Cosmetic Applicator Foam Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
Massaging Cosmetic Applicators Market
Cosmetics & Skincare
Tinted Cosmetics Market
Cosmetics & Skincare
Natural Baby Skin Care Products Market
Cosmetics & Skincare
Waterproof Temporary Tattoo Sticker Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
Retinol Eye Cream Market
Cosmetics & Skincare
Bath Soap Market
Cosmetics & Skincare
Russia Lip Care Products Market
Cosmetics & Skincare
Philippines Skin Care Products Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market