
 Japan Bath Soap Market | 2026-2036
Japan Bath Soap Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Bath Soap Market Intelligence
Supermarket and pharmacy procurement for bath soap is consolidating around fewer but larger retail banners with private-label ambitions. Kao Corporation leverages its integrated supply chain to dominate mass-market shelf space across Japan. Lion Corporation competes through specialized antibacterial formulations for institutional buyers. Shiseido Company, Limited anchors the premium tier with skincare-positioned soap lines in department store channels.
Bath soap comprises surfactant-based cleansing bars or liquids formulated with fatty acid salts, typically sodium or potassium stearate, designed to remove oils, dirt, and microorganisms from skin surfaces during personal hygiene routines. Bar soap formulations remain the volume backbone, though liquid and foam variants are capturing faster growth in urban households seeking dispenser convenience. Natural and moisturizing formulations command disproportionate margin pools as consumers trade up from standard antibacterial lines, while gel soap occupies a narrow specialty niche in travel and gift segments.
METI oversees chemical substance safety under Japan's Industrial Safety and Health Act, directly affecting surfactant classifications and labeling requirements for domestic soap manufacturers. The Act on Securing Quality, Efficacy and Safety of Products Including Pharmaceuticals and Medical Devices, administered by PMDA, imposes strict bounds on functional claims for medicated soaps. Stakeholders must monitor pending revisions to cosmetic ingredient disclosure rules that could reshape competitive positioning between transparent natural-positioned brands and conventional antibacterial offerings.
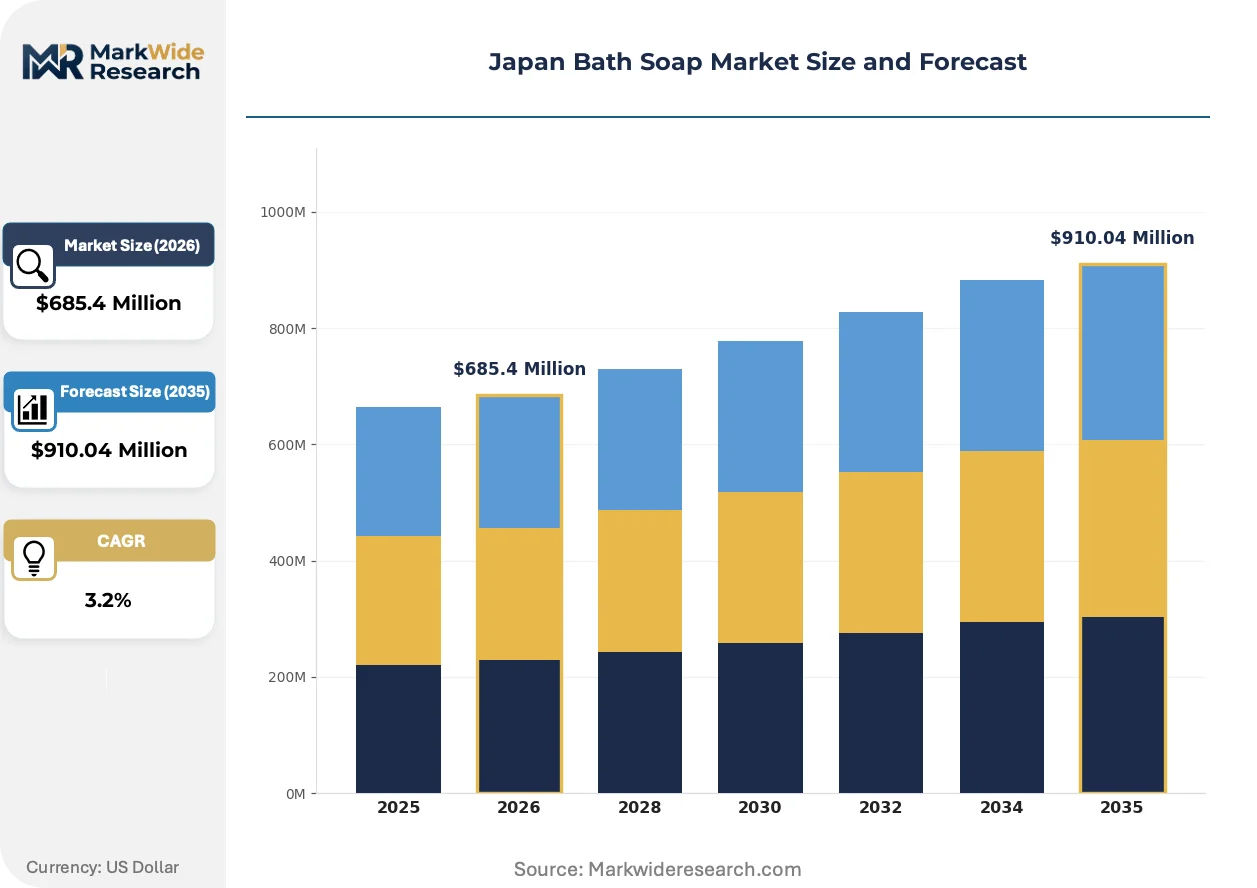
Market Dynamics
Urban professional households in Tokyo and Osaka are driving a structural pivot toward premium skincare-positioned soaps, compressing volume share of standard antibacterial bars while expanding margin pools for moisturizing and natural-positioned formulations.
Growth Catalysts
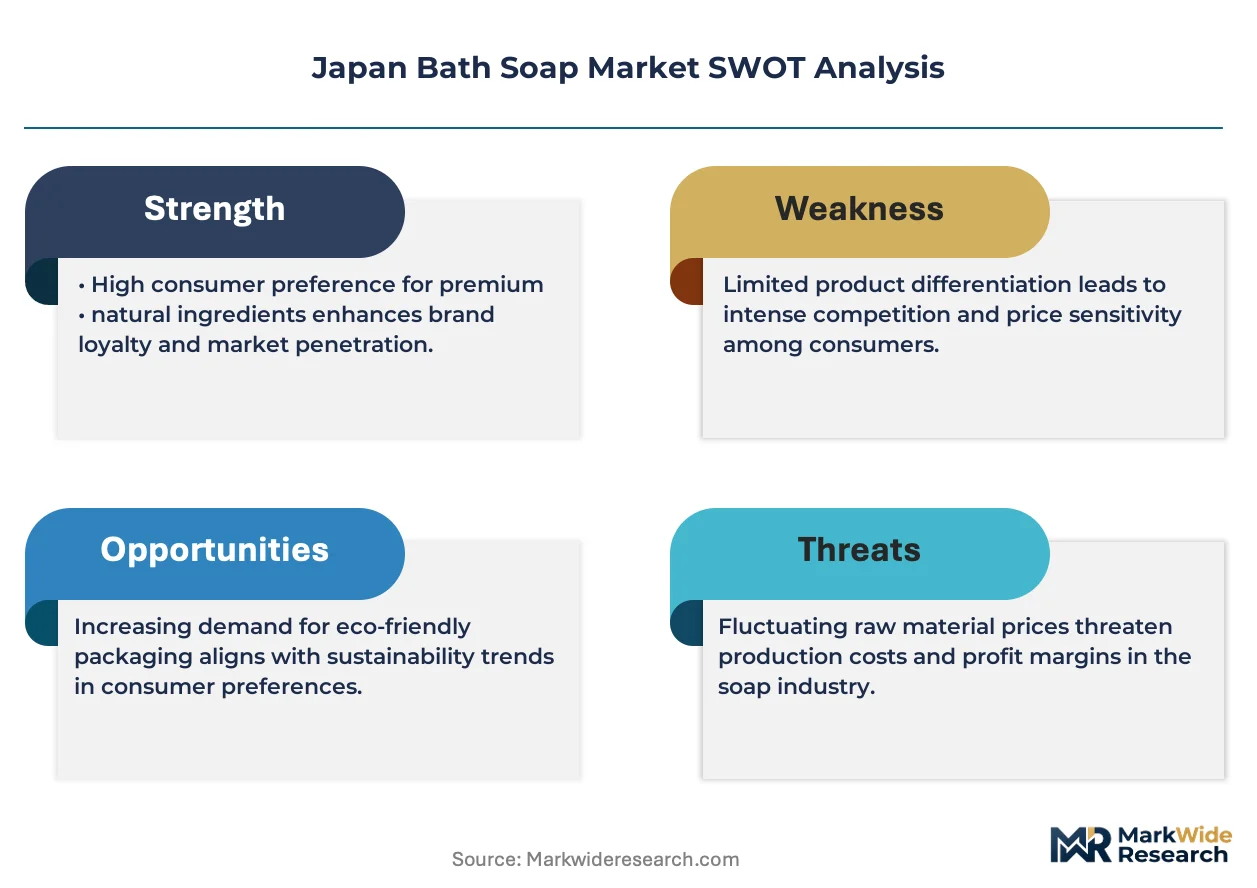
- Act on Securing Quality, Efficacy and Safety of Products Including Pharmaceuticals and Medical Devices:PMDA enforcement of functional claim boundaries for medicated soaps creates tiered positioning opportunities for transparent natural-ingredient brands.
- Metropolitan concentration:Tokyo and Osaka household density supports specialized retail formats and dispenser-compatible liquid soap adoption at faster velocity than rural markets.
- Surfactant innovation:Fatty acid salt alternatives with enhanced skin-barrier compatibility are pulling formulation upgrades across department store channels.
Market Restraints
- Palm oil and coconut oil price volatility:Primary feedstock cost swings compress margin stability for mass-market bar soap producers dependent on commodity fatty acid chains.
- Retail banner consolidation:Supermarket and pharmacy procurement centralization around fewer large banners strengthens private-label bargaining power against branded manufacturers.
- Functional claim restrictions:PMDA boundaries on antibacterial efficacy assertions limit differentiation space for conventional medicated soap lines.
Strategic Opportunities
- Travel and gift segments:Gel soap specialty formats remain underdeveloped relative to bar and liquid volumes, offering white space for compact premium positioning.
- Ingredient disclosure acceleration:Pending METI revisions to cosmetic labeling rules favor early-mover natural-positioned brands with established transparent supply chains.
- Institutional antibacterial demand:Healthcare and hospitality procurement for specialized formulations represents expansion terrain beyond saturated household channels.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in surfactant-skin compatibility testing constrains R&D throughput for premium line extensions.
- Dual regulatory navigation:Simultaneous METI chemical safety and PMDA functional claim compliance extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Bath Soap Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $910.04 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Bar Soap, Foam Soap, Gel Soap Formulation: Natural, Organic, Antibacterial, Moisturizing End User: Adults, Children, Seniors, Specialty Users Distribution Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores |
| Companies Covered | Unilever Group, Johnson & Johnson K.K., Kao Corporation, Pelican, Pola Orbis Holdings Inc., Lion Corporation, Procter & Gamble Co., Fancl Corporation, Shiseido Company, Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Bath Soap Market Strategic Shifts & Innovations
Formulation chemistry and retail channel structure are undergoing simultaneous recalibration as consumer preference fragments across convenience, transparency, and skincare efficacy dimensions.
Foam pump dispenser formats are consolidating share in urban Tokyo and Osaka households where counter space and hand-drying convenience outweigh unit-economy considerations of traditional bar formats. Young professional buyers with dual-income schedules adopt these formats at faster replacement cycles than multi-generational rural households. This consolidation is compressing shelf-space allocation for standard bar soaps in metropolitan pharmacy chains.
Japan's Act on Securing Quality, Efficacy and Safety of Products Including Pharmaceuticals and Medical Devices is tightening functional claim substantiation requirements for soaps marketed with antibacterial or dermatological benefits. Manufacturers must now navigate PMDA review boundaries that previously allowed broader efficacy language. Medicated soap segments face the steepest compliance recalibration, with several lines repositioning toward general cleansing claims or investing in clinical substantiation.
Department store channel buyers are fragmenting procurement across skincare-positioned soap lines that emphasize ingredient provenance over price positioning. This behavior is displacing volume-driven promotional stacking that historically dominated seasonal purchasing. The shift is most visible in Tokyo's Ginza and Osaka's Umeda retail clusters where premium soap assortments now anchor beauty floor layouts previously reserved for color cosmetics.
Japan Bath Soap Market Segmentation
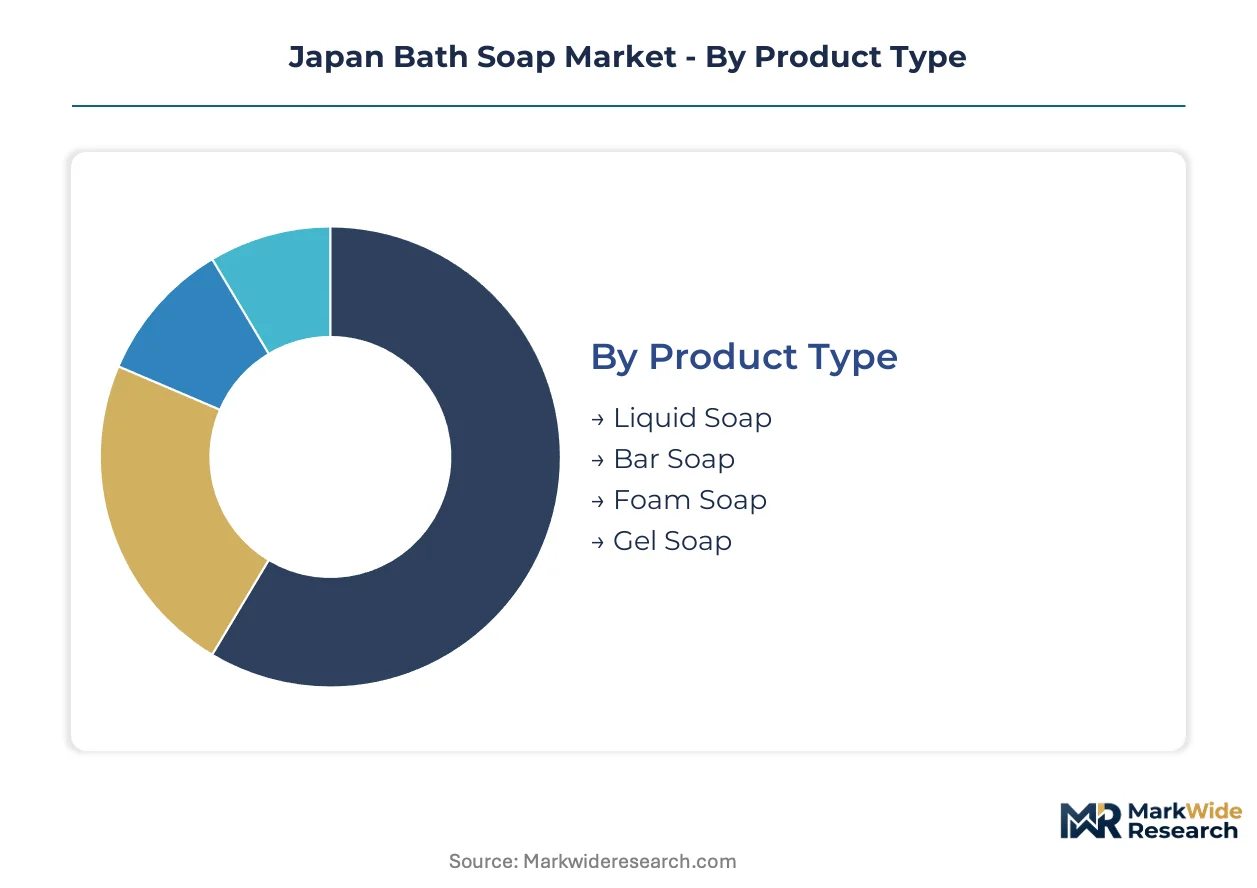
Segmentation in Japan's bath soap market reveals how regulatory boundaries and channel access reshape competitive positioning. PMDA functional claim restrictions and METI labeling requirements fragment opportunities across formulation types, while metropolitan retail concentration favors specific product formats.
Product Type:
PMDA review thresholds vary sharply across formats, with medicated liquid and foam variants facing stricter efficacy substantiation than standard bar soaps.
- Bar Soap:Sodium and potassium stearate formulations dominate mass-market shelf space in Tokyo and Osaka supermarkets. Volume concentration persists among multi-generational rural households where unit economics outweigh dispenser convenience.
- Liquid Soap:Surfactant-based pump formats capture replacement-cycle premiums in dual-income professional households. Demand clusters in metropolitan pharmacy chains where counter space constraints and hand-drying convenience drive adoption velocity.
- Foam Soap:Pre-lathered dispenser systems target urban bathroom environments with premium positioning.
- Gel Soap:Compact specialty formats occupy narrow travel and gift segments with limited retail penetration.
Leading the category by volume: Bar Soap. Growing fastest: Liquid Soap.
Formulation:
Cost tier stratification separates premium natural-positioned lines from commodity antibacterial bars, with margin pools concentrating in transparent-ingredient segments.
- Natural:Plant-derived surfactant alternatives with enhanced skin-barrier compatibility command department store placement in Ginza and Umeda clusters. Pending METI disclosure revisions favor early-mover brands with established supply chain transparency.
- Moisturizing:Glycerin-enriched and ceramide-infused variants target aging demographics and seasonal dryness concerns. Tokyo professional households trade up from standard lines, expanding margin pools faster than volume.
- Antibacterial:Triclosan and benzalkonium chloride formulations face PMDA claim restrictions that compress differentiation space.
- Organic:Certified ingredient sourcing meets niche demand in premium channels with limited mass-market distribution.
Highest margin capture: Natural. Steepest expansion trajectory: Moisturizing.
End User:
Application-specific requirements drive formulation specialization, with dermatological sensitivity and age-related skin conditions fragmenting product development priorities.
- Adults:Working-age consumers in metropolitan areas drive premium skincare-positioned adoption with faster replacement cycles and dispenser-format preference.
- Seniors:Aging skin compatibility requirements pull moisturizing and low-irritant formulations, with demand concentrating in pharmacy channels.
- Children:Hypoallergenic and tear-free specifications govern product safety thresholds for pediatric use.
- Specialty Users:Dermatological condition-specific needs create narrow prescription-adjacent segments with clinical substantiation requirements.
Largest addressable base: Adults. Fastest volume shift: Seniors.
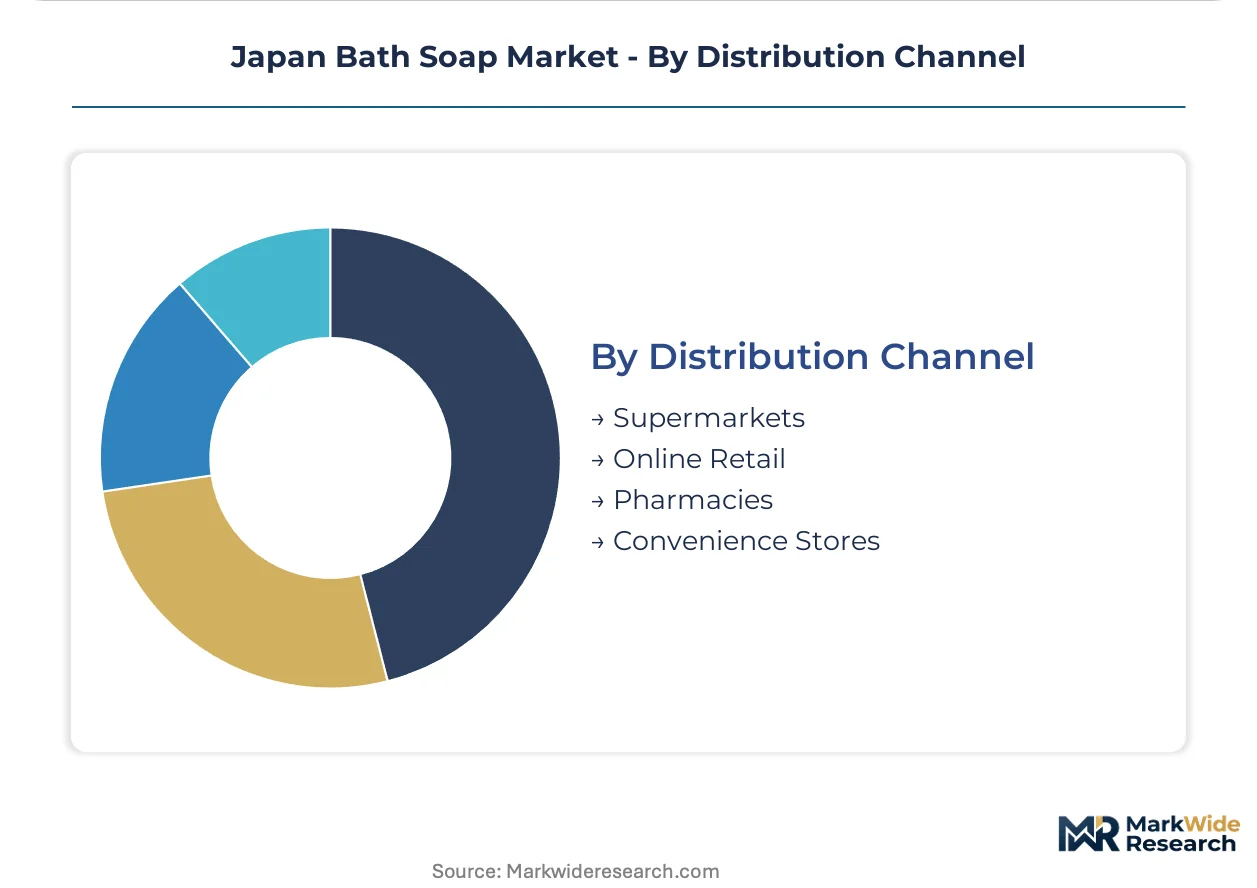
Distribution Channel:
Customer type fragmentation separates institutional procurement from household purchasing, with banner consolidation reshaping supplier bargaining dynamics.
- Supermarkets:Private-label ambitions among consolidated retail banners compress branded manufacturer shelf space, with Kao Corporation leveraging integrated supply chains to defend mass-market position.
- Pharmacies:Medicated soap authorization and skincare consultation services support premium formulation placement, particularly in Tokyo and Osaka metropolitan chains.
- Online Retail:Subscription replenishment models and ingredient transparency content attract natural-positioned brand discovery.
- Convenience Stores:Compact format and travel-size dominance limits category depth to emergency replenishment and impulse segments.
Volume concentration: Supermarkets. Channel gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Palm oil and coconut oil feedstock dependencies shape Japan's bath soap supply geography, with metropolitan demand clusters in Tokyo and Osaka driving specialized formulation requirements distinct from rural consumption patterns.
Kanto/Tokyo
Dual-income professional households in Tokyo's 23 wards drive premium liquid and foam soap adoption at faster replacement cycles than national averages. METI's chemical substance safety oversight under the Industrial Safety and Health Act directly affects surfactant classifications for manufacturers operating in this corridor. Shibuya and Ginza retail clusters anchor department store placement for skincare-positioned soap lines.
Kansai/Osaka
Osaka's merchant-class consumer culture sustains demand for traditional bar soap formats alongside emerging dispenser-compatible variants. PMDA enforcement of functional claim boundaries for medicated soaps creates compliance complexity for producers serving this market. Umeda and Namba retail districts concentrate pharmacy chain procurement for moisturizing and natural-positioned formulations.
Chubu/Nagoya
Automotive industry employment density in Aichi Prefecture supports institutional antibacterial soap demand from manufacturing and healthcare facilities. Japan's Act on Securing Quality, Efficacy and Safety of Products Including Pharmaceuticals and Medical Devices shapes procurement specifications for medicated lines. Nagoya metropolitan pharmacies serve as distribution nodes for aging demographic moisturizing formulations.
Kyushu
Fukuoka's growing startup ecosystem attracts younger professional households adopting foam pump formats at rates approaching Tokyo levels. METI labeling requirements under pending cosmetic disclosure revisions favor early-mover natural brands with transparent supply chains. Kitakyushu industrial zones maintain residual demand for standard antibacterial bars in blue-collar employment segments.
Hokkaido
Extended heating seasons and low ambient humidity drive disproportionate consumption of glycerin-enriched moisturizing soaps across Sapporo and Asahikawa. PMDA functional claim restrictions limit differentiation for conventional medicated lines targeting dermatological sensitivity concerns. Sapporo's compact urban core supports convenience store replenishment patterns distinct from mainland metropolitan channels.
Japan Bath Soap Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue natural-positioned transparency and institutional specialization. The vendor base clusters around three concentration nodes: integrated chemical conglomerates with captive fatty acid supply, skincare-specialized houses with department store channel access, and hygiene-focused manufacturers with institutional procurement relationships. Strategic archetypes include mass-market shelf-space defenders, premium ingredient-provenance marketers, and antibacterial formulation specialists. Dominant competitive moves encompass backward integration into surfactant production and portfolio diversification across bar, liquid, and foam formats.
Within the integrated conglomerate tier, Kao Corporation and Lion Corporation exemplify scale-driven positioning with supply chain control advantages. Shiseido Company, Limited anchors the premium skincare-positioned segment with department store channel presence. Among international operators, Unilever Group and Procter & Gamble Co. represent global-format adaptation strategies for Japanese metropolitan preferences. Johnson & Johnson K.K. and Fancl Corporation occupy positions emphasizing dermatological compatibility and ingredient transparency respectively.
| Leading Market Players |
|---|
| Unilever Group |
| Johnson & Johnson K.K. |
| Kao Corporation |
| Pelican |
| Pola Orbis Holdings Inc. |
| Lion Corporation |
| Procter & Gamble Co. |
| Fancl Corporation |
| Shiseido Company, Limited |
| Others |
Cost & Logistics Intelligence
Foam pump dispenser adoption across Tokyo and Osaka professional households simultaneously compresses per-unit economics for bar soap manufacturers while concentrating procurement power among metropolitan pharmacy chains. This format transition feeds back into fatty acid salt sourcing decisions as liquid surfactant formulations displace traditional sodium stearate production runs.
Pricing Analysis
Warranty and clinical substantiation bundling separates medicated soap tiers from standard cleansing lines, with PMDA-reviewed antibacterial formulations commanding placement premiums in pharmacy channels. Three-tier pricing structure across premium, standard, and economy levels reflects ingredient provenance transparency and METI disclosure compliance status. Cost compression in mass-market bar segments is intensifying because private-label banner consolidation strengthens retailer bargaining leverage. Rural multi-generational households exhibit highest price sensitivity, while Ginza department store buyers prioritize skin-barrier compatibility over unit cost.
Supply Chain Analysis
Direct-to-institutional channels handle healthcare and hospitality procurement for specialized antibacterial formulations, bypassing fragmented retail intermediaries. Malaysia, Indonesia, and the Philippines anchor palm oil and coconut fatty acid feedstock supply for Japanese surfactant producers. Raw material dependencies center on crude palm oil, coconut oil, and petroleum-derived synthetic alcohols. Single-source vulnerability concentrates in Southeast Asian oleochemical processing hubs exposed to El Niño precipitation disruption. Distribution runs through integrated chemical conglomerates with captive fatty acid production, supplemented by spot market sourcing for specialty esters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's bath soap sector sits in a formulation-transition phase as pre-lathered foam dispensers replace traditional bar formats among urban professional buyers. This technology shift demands recalibrated supply chain and channel strategies across stakeholder archetypes.
For Market Incumbents: Extend surfactant-skin compatibility R&D pipelines to defend department store placement against natural-positioned challengers. Backward integration into oleochemical feedstock production mitigates palm oil price volatility exposure. Accelerate METI disclosure compliance to preempt labeling rule revisions that favor transparent-ingredient competitors.
For New Entrants and Emerging Players: Enter via gel soap travel and gift segments where retail penetration remains underdeveloped relative to bar and liquid volumes. Target Fukuoka's young professional demographic adopting foam formats at Tokyo-comparable rates. Deploy subscription replenishment models through online retail to bypass consolidated supermarket banner gatekeeping.
For Investors and Strategic Acquirers: Re-rating potential sits with skincare-specialized houses possessing department store channel access given PMDA functional claim restrictions that compress conventional medicated line differentiation. Long-term viability favors brands with established transparent supply chains and clinical substantiation capabilities. Watch METI cosmetic ingredient disclosure implementation timing as inflection indicator for natural-positioned brand valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Surfactant Innovation Investment | Enhanced skin-barrier compatibility formulations capture premium placement in Ginza and Umeda retail clusters. |
| Backward Integration into Oleochemicals | Captive palm oil and coconut fatty acid supply stabilizes margin exposure to commodity price swings. |
| Direct-to-Consumer Channel Launch | Subscription models bypass consolidated supermarket procurement and enable ingredient transparency storytelling. |
| Clinical Substantiation Program | PMDA-compliant efficacy documentation defends medicated soap positioning against functional claim restrictions. |
| Sustainability Repositioning | Transparent supply chain certification aligns with pending METI cosmetic labeling disclosure requirements. |
Research Approach
Trade publications, PMDA regulatory filings, and METI industrial statistics formed the secondary backbone, supplemented by customs records tracking palm oil and coconut oil import flows. Primary interviews with surfactant R&D directors, pharmacy chain category buyers, department store beauty floor managers, and institutional procurement officers at healthcare facilities validated formulation and channel assumptions. Bottom-up unit consumption modeling across Tokyo, Osaka, and Nagoya metropolitan clusters triangulated against top-down value estimates from retail audit data.
Historical trendline analysis of bar-to-liquid format substitution patterns informed projection assumptions across the analysis window. Segmentation dimensions modeled include product format, formulation chemistry, end-user demographic, and distribution channel structure. CAGRs derived from weighted average of segment growth trajectories, with specific inputs from dual-income household formation rates and PMDA medicated soap approval timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under palm oil price volatility extremes and METI disclosure rule acceleration scenarios. Forecasts reflect documented assumptions regarding urban professional adoption curves and institutional procurement specifications. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Israel Cosmetics Products Market
Cosmetics & Skincare
BB Cream Market
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Microbiome Cosmetic Products Market
Cosmetics & Skincare
Malaysia Skin Care Products Market
Cosmetics & Skincare
South America Cosmetics Products Market
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
Silicone Makeup Sponge Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
United Arab Emirates Cosmetic Products Market
Cosmetics & Skincare
Sun Care Market
Cosmetics & Skincare
Retinol Eye Cream Market
Cosmetics & Skincare
Private Label Cosmetics Manufacturing Service Market
Cosmetics & Skincare
Global Cosmetic Applicator Foam Market
Cosmetics & Skincare
Setting Spray Market