
 Baby Skincare Market | 2026-2036
Baby Skincare Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Skincare Market Analysis
Buyer concentration is shifting as millennial and Gen Z parents fragment across direct-to-consumer channels, specialty boutiques, and subscription services rather than consolidating in mass retail. Johnson & Johnson Services Inc. leverages its hospital-channel heritage to sustain credibility among first-time parents. The Himalaya Drug Company Ltd. anchors its position through Ayurvedic ingredient differentiation in South Asian and Middle Eastern markets. Beiersdorf AG competes via dermatological science credentials transferred from its adult skincare portfolio.
Baby skincare encompasses dermatologically formulated topical preparations designed for infant epidermal barrier support, typically featuring pH-balanced compositions between 4.5 and 5.5, hypoallergenic testing protocols, and exclusion of parabens, phthalates, and synthetic fragrances to prevent transepidermal water loss in immature skin. Moisturizers occupy the largest revenue pool as parents integrate daily barrier maintenance into infant hygiene routines. Cleansers represent the fastest-expanding category as liquid and foam formats displace traditional soap bars. Sunscreens command premium pricing due to mineral-filter formulation complexity and pediatrician endorsement requirements.
The FDA governs infant cosmetic safety through monograph compliance and adverse-event reporting mandates, while REACH restricts chemical substances in products entering European markets. The EU AI Act and CSRD are introducing supply-chain transparency obligations that affect ingredient sourcing disclosures. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances as these cascade into raw-material qualification processes.
Market Dynamics
EU REACH restrictions on endocrine-disrupting chemicals are forcing reformulation cycles across infant cosmetic portfolios, compressing product development timelines while elevating R&D spend requirements for barrier-support formulations.
Growth Catalysts
- China birth-rate stabilization policies:Government incentives for larger families are expanding the addressable infant population base, with per-capita spending on dermatological products rising in tier-one cities.
- REACH chemical substance restrictions:Regulatory pressure is accelerating clean-label innovation, pushing manufacturers toward bio-based emollients and mineral-derived actives that command premium positioning.
- Liquid cleanser format adoption:Foam and liquid formulations are displacing traditional soap bars in daily infant hygiene routines, expanding category revenue per household.
Market Restraints
- Shea butter and jojoba oil price volatility:Climate-sensitive agricultural inputs face harvest uncertainty, compressing gross margins for natural-positioned brands dependent on specific botanical supply chains.
- Pediatrician endorsement bottlenecks:Limited clinical trial infrastructure for infant dermatology creates credential scarcity, slowing new entrant credibility building and concentrating authority with established hospital-channel players.
- Synthetic fragrance substitution pressure:Parent preference shifts toward unscented formulations eliminate a key differentiation vector, commoditizing mid-tier positioning and compressing marketing effectiveness.
Strategic Opportunities
- Subscription commerce penetration:Direct-to-consumer replenishment models capture recurring revenue and first-party data, with millennial parents showing elevated willingness to automate diaper-rash cream and moisturizer purchases.
- EU CSRD supply-chain transparency mandates:Early compliance with ingredient sourcing disclosure requirements creates differentiation in European markets ahead of enforcement timelines.
- Mineral sunscreen formulation complexity:Zinc oxide and titanium dioxide blending expertise represents a technical moat, with pediatrician endorsement requirements limiting competitive entry.
Industry Challenges
- Pediatric dermatology formulation expertise scarcity:Specialized knowledge in infant epidermal barrier science concentrates in legacy pharmaceutical and hospital-supply organizations, constraining independent brand technical credibility.
- Cross-border e-commerce customs fragmentation:Divergent national labeling and ingredient disclosure requirements create fulfillment complexity for direct-to-consumer brands expanding beyond home markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Skincare Market |
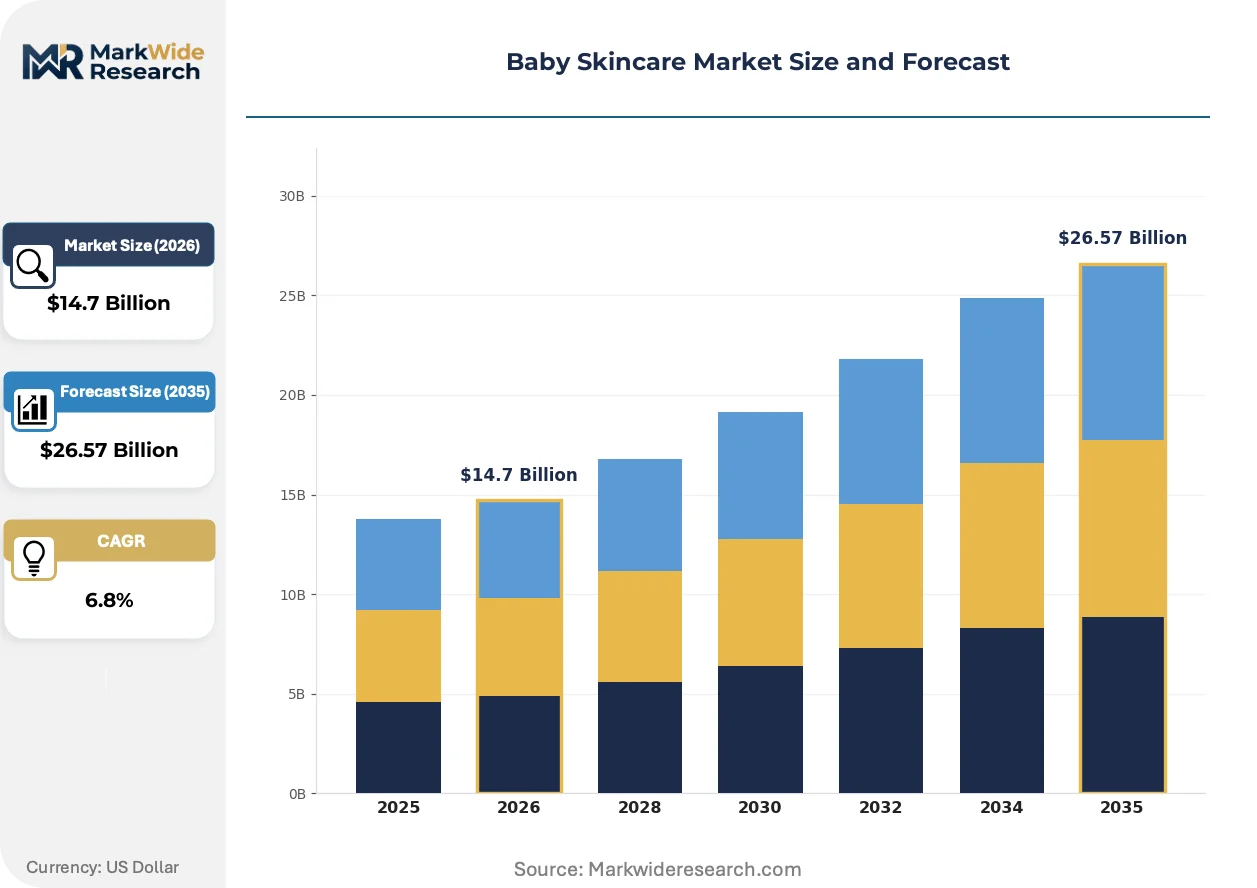
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Diaper Creams, Sunscreens Application: Daily Care, Sensitive Skin, Rashes, Sun Protection End User: Newborns, Infants, Toddlers, Parents Packaging Type: Tubes, Bottles, Jars, Sachets |
| Companies Covered | Unilever Plc, The Himalaya Drug Company Ltd., Johnson & Johnson Services Inc., Burt’s Bees Inc., Dabur India Limited, The Procter & Gamble Company, Beiersdorf AG, Mustela, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Skincare Market Emerging Trajectories
Microbiome-conscious formulation science is redefining product architecture, with brands investing in prebiotic and postbiotic active development to support developing skin flora rather than simply protecting against moisture loss.
Biometric skin analysis tools integrated into mobile applications are electrifying parent engagement, enabling personalized regimen recommendations based on infant-specific barrier condition assessments. Tech-forward millennial parents in South Korea and China are adopting these diagnostic services at accelerated rates. The data feedback loops are compressing traditional trial-and-error product selection cycles and shifting loyalty dynamics toward algorithm-guided brands.
EU AI Act provisions on automated decision-making are reshaping ingredient screening protocols, requiring human-in-the-loop validation for AI-assisted safety assessments. Formulation teams must now document manual review checkpoints in product development workflows. Premium organic segments in Germany and France are responding with explicit "non-AI-curated" marketing to differentiate artisan positioning.
Parent information-seeking behavior has fragmented across video-native platforms, with TikTok and Xiaohongshu displacing traditional parenting magazines as primary discovery channels. Influencer dermatologists and pediatric nurse practitioners are accumulating authority that rivals institutional medical endorsement. This shift is most pronounced in Chinese urban markets, where live-commerce integration enables immediate purchase conversion from educational content.
Baby Skincare Market Segmentation
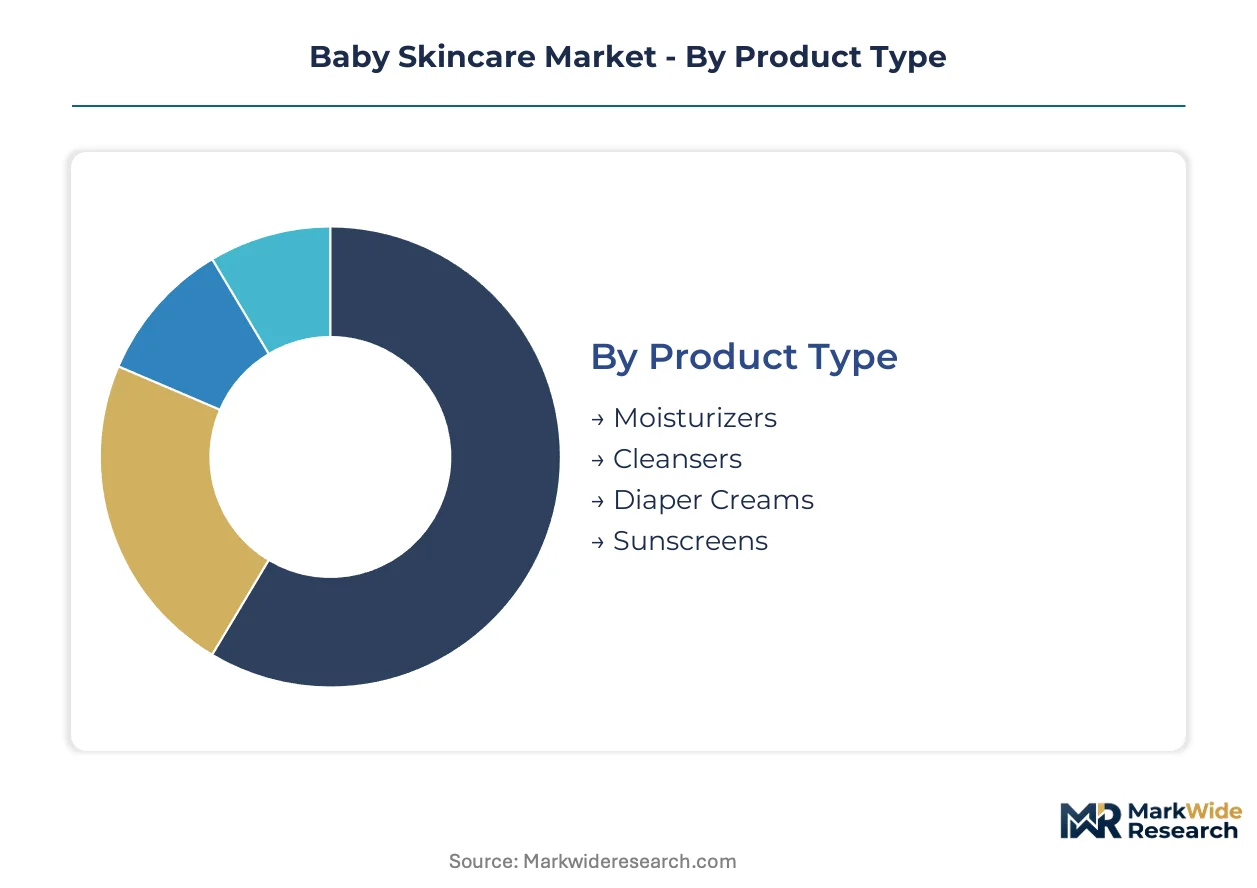
Segmentation in baby skincare reveals how formulation science, usage context, and purchasing authority fragment revenue pools. Parents navigate distinct product architectures for barrier maintenance versus acute condition treatment, while packaging formats signal convenience premiums that reshape channel economics.
Product Type:
Volume concentrates in daily-use essentials, while premium pricing accrues to specialized protection formats requiring dermatological validation.
- Moisturizers:pH-balanced emollient formulations between 4.5 and 5.5 dominate household penetration as parents integrate daily barrier maintenance into infant hygiene routines. Demand clusters in tier-one Chinese cities where per-capita spending on dermatological products has risen alongside birth-rate stabilization policies.
- Cleansers:Liquid and foam formats are displacing traditional soap bars through superior rinsing properties and parent preference for pump-dispensed convenience. South Korean millennial parents adopt foam cleansers at accelerated rates, compressing trial-and-error selection cycles through biometric skin analysis integration.
- Diaper Creams:Zinc oxide barrier formulations address moisture-induced irritation in the diaper zone, with subscription commerce capturing recurring replenishment revenue from automated purchase behaviors.
- Sunscreens:Mineral-filter compositions utilizing zinc oxide and titanium dioxide command premium positioning due to formulation complexity and pediatrician endorsement requirements that limit competitive entry.
Today's leader: Moisturizers. Tomorrow's challenger: Cleansers.
Application:
Usage context determines formulation intensity, with acute-condition applications justifying higher price points despite lower purchase frequency.
- Daily Care:Routine cleansing and moisturizing protocols represent the foundational revenue base, with millennial parents in urban Chinese markets integrating biometric-guided regimen selection into standard practice.
- Sensitive Skin:Hypoallergenic-tested compositions exclude parabens, phthalates, and synthetic fragrances to prevent transepidermal water loss in immature epidermal barriers, attracting premium positioning in German and French organic segments.
- Rashes:Therapeutic-grade barrier preparations address diaper dermatitis and heat rash, with clinical trial infrastructure scarcity concentrating credibility among hospital-channel heritage brands.
- Sun Protection:Pediatrician-endorsed mineral sunscreens face EU REACH-driven reformulation cycles as endocrine-disrupting chemical restrictions force clean-label innovation toward bio-based emollients.
Daily Care commands current volume. Sensitive Skin is climbing the fastest as clean-label regulatory pressure elevates premium positioning.
End User:
Developmental stage dictates skin barrier maturity, with newborn-specific formulations requiring the most stringent safety protocols.
- Newborns:Ultra-gentle compositions address epidermal barrier immaturity in the first four weeks, with first-time parents prioritizing hospital-channel credibility over price sensitivity.
- Infants:Expanded product compatibility accompanies barrier maturation, enabling broader ingredient tolerance and format experimentation.
- Toddlers:Active lifestyle exposure increases sunscreen and cleanser demand, with biometric skin analysis tools guiding personalized regimen adaptation.
- Parents:Purchasing authority concentrates with millennial and Gen Z digital-native consumers fragmenting across direct-to-consumer channels, specialty boutiques, and subscription services rather than mass retail consolidation.
Newborns anchor premium pricing. Parents as decision-makers are gaining share fastest through influencer dermatologist authority accumulation on video-native platforms.
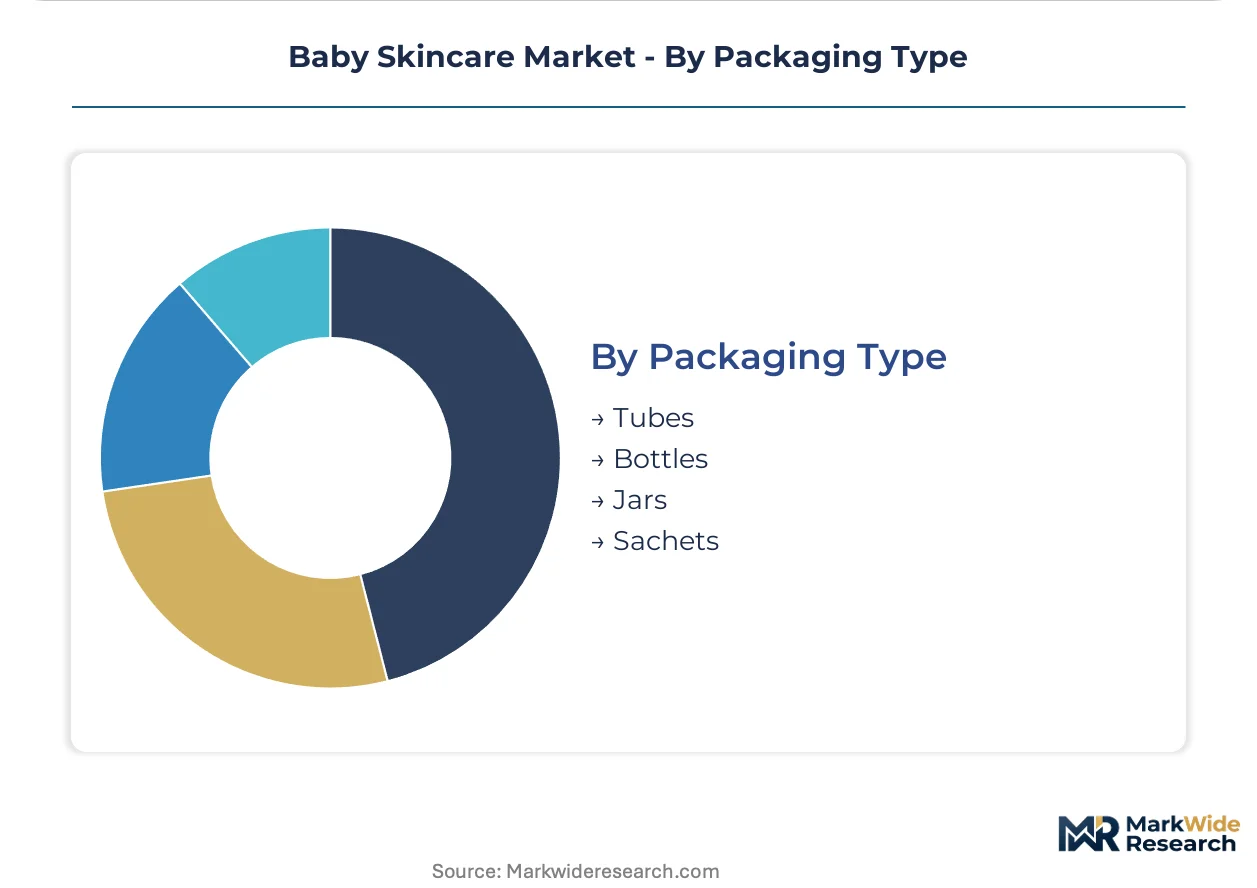
Packaging Type:
Format selection reflects usage context and contamination-risk management, with single-use options addressing travel and trial scenarios.
- Tubes:Collapsible aluminum or laminate structures dominate diaper cream and moisturizer formats, enabling precise dosage control and hygienic dispensing.
- Bottles:Pump and flip-cap closures accommodate liquid cleanser and lotion volumes, with millennial parents showing elevated willingness to automate replenishment through subscription models.
- Jars:Wide-mouth containers serve thick balm and cream consistencies, though finger-dip contamination concerns are accelerating squeeze-tube substitution in premium positioning.
- Sachets:Single-serve pouches address travel and trial-size demand, with cross-border e-commerce customs fragmentation complicating fulfillment for direct-to-consumer brands expanding beyond home markets.
Tubes hold current preference. Bottles are expanding most quickly through subscription commerce penetration and pump-dispensed convenience adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands premium per-capita spending on infant dermatological products, while Germany drives regulatory innovation through REACH chemical restrictions that reshape formulation standards worldwide.
China
Birth-rate stabilization policies and tier-one city wealth concentration expand the addressable infant population base. NMPA cosmetic safety regulations enforce stringent ingredient disclosure requirements for imported formulations. Shanghai and Beijing anchor demand clusters where millennial parents integrate biometric skin analysis tools into daily hygiene routines.
Germany
Organic segment premiumization in German and French markets accelerates clean-label ingredient sourcing. ECHA REACH restrictions on endocrine-disrupting chemicals force reformulation cycles across infant cosmetic portfolios. The Rhine-Ruhr industrial corridor hosts specialized bio-based emollient suppliers serving dermatological formulation houses.
United States
Hospital-channel heritage brands sustain credibility among first-time parents seeking pediatrician-endorsed products. FDA monograph compliance and adverse-event reporting mandates govern infant cosmetic safety protocols. Greater Boston and the Research Triangle concentrate clinical trial infrastructure for infant dermatology studies.
South Korea
Millennial parents adopt foam cleanser formats and biometric-guided regimen selection at accelerated rates. MFDS cosmetic safety standards align with EU chemical restrictions while permitting novel preservative systems. Seoul anchors tech-forward parent engagement through mobile-integrated skin diagnostic services.
India
Ayurvedic ingredient differentiation attracts premium positioning in South Asian and Middle Eastern export markets. BIS cosmetic standards and CDSCO safety protocols create compliance thresholds for domestic and imported formulations. Maharashtra and Gujarat concentrate contract manufacturing capacity for herbal-derived baby skincare exports.
Baby Skincare Market Vendor Landscape
North American producers anchor one tier through hospital-channel credibility and pediatrician endorsement networks; European specialists hold premium positioning via dermatological science credentials and regulatory-compliant clean-label portfolios. The vendor base fragments across three strategic tiers: multinational consumer goods conglomerates with infant care line extensions, pharmaceutical heritage brands with clinical trial infrastructure, and emerging direct-to-consumer challengers leveraging subscription commerce. Dominant competitive moves include portfolio diversification into microbiome-conscious formulations and strategic partnerships with biometric skin analysis platform developers.
Within the pharmaceutical heritage tier, Johnson & Johnson Services Inc. and Beiersdorf AG exemplify hospital-channel credibility transfer and dermatological science extension respectively. The Himalaya Drug Company Ltd. occupies a position representing Ayurvedic ingredient differentiation archetypes in emerging market export strategies. Among multinational consumer goods conglomerates, Unilever Plc and The Procter & Gamble Company sit within the scale-driven mass-market tier, while Burt's Bees Inc. anchors the natural-positioned premium segment. Dabur India Limited represents the traditional medicine heritage archetype competing through botanical supply chain control.
| Leading Market Players |
|---|
| Unilever Plc |
| The Himalaya Drug Company Ltd. |
| Johnson & Johnson Services Inc. |
| Burt's Bees Inc. |
| Dabur India Limited |
| The Procter & Gamble Company |
| Beiersdorf AG |
| Mustela |
| Kimberly-Clark Corporation |
| Others |
Supply Flow & Price Mechanics
Parent preference for unscented, mineral-filter formulations is compressing differentiation vectors and forcing supply chains toward certified clean-label ingredient sourcing that elevates cost structures across all tiers.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for botanical-derived emollients, though premium tiers anchored by zinc oxide sunscreen expertise maintain structural insulation. Three-tier pricing structure across premium, standard, and economy levels stratifies by pediatrician endorsement density and organic certification grade. Cost compression in mid-tier moisturizers is intensifying because REACH-driven reformulation cycles have elevated R&D amortization. First-time parents in tier-one Chinese cities exhibit the lowest price sensitivity, while mass-market households in India demonstrate acute responsiveness to unit-cost positioning.
Supply Chain Analysis
Freight cost volatility from Middle Eastern shea butter corridors and Southeast Asian jojoba oil routes is amplifying margin pressure for natural-positioned brands. Manufacturing concentrates in India, China, and Germany, with each hub feeding distinct regulatory compliance specifications. Formulation draws from climate-sensitive agricultural inputs including shea butter, jojoba oil, and bio-based emollients. Single-source vulnerability in pediatrician endorsement networks constrains new entrant credibility building. Distribution runs through hospital-channel heritage networks, direct-to-consumer subscription platforms, and cross-border e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as millennial parents in Shanghai and Beijing redirect spending toward microbiome-conscious formulations with prebiotic actives.
For Market Incumbents: To counter direct-to-consumer subscription challengers, Johnson & Johnson Services Inc. and Beiersdorf AG should deepen hospital-channel exclusivity agreements while accelerating in-house production of bio-based emollient actives to capture REACH compliance premiums. For New Entrants and Emerging Players: Enter via biometric skin analysis platform partnerships in South Korea and China, where tech-forward millennial parents show accelerated adoption of algorithm-guided regimen selection. White-space concentrates in subscription commerce penetration for diaper cream replenishment and mineral sunscreen pediatrician endorsement acquisition. For Investors and Strategic Acquirers: Asymmetric upside sits with Ayurvedic heritage brands possessing captive botanical supply chains and established Middle Eastern export corridors. Long-term viability hinges on regulatory compliance agility across REACH, FDA monograph, and NMPA disclosure regimes. Watch for inflection signals in EU CSRD early-compliance differentiation and AI Act human-in-the-loop validation documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome Formulation Development | Prebiotic and postbiotic R&D investments by Mustela and Burt's Bees Inc. redefine barrier-support science. |
| Biometric Platform Partnership | Mobile-integrated skin diagnostic services in Seoul compress trial-and-error product selection cycles. |
| Subscription Commerce Launch | Automated replenishment models capture recurring revenue from millennial parent purchase automation. |
| REACH Compliance Acceleration | Early bio-based emollient sourcing creates European market differentiation ahead of enforcement timelines. |
| Pediatrician Endorsement Acquisition | Clinical trial infrastructure scarcity makes hospital-channel credibility transfer a defensible moat. |
Methodological Framework
Coverage spans China, Germany, the United States, South Korea, and India, with primary inputs from each market cluster. Interviews with brand managers, category buyers at specialty retailers, supply planners, and regulatory affairs leads combined with secondary validation from NMPA cosmetic safety filings, ECHA REACH substance restrictions, FDA monograph compliance records, and Nielsen retail audit data. Bottom-up demand modeling and top-down supply triangulation anchored volume and value estimates.
Segmentation dimensions were modeled at product type, application context, developmental stage, and packaging format granularity across the analysis window. CAGRs derived from trend extrapolation against policy inflection points including EU birth-rate incentives and CSRD transparency mandates. Forecast inputs incorporated shea butter price volatility indices and pediatric dermatology clinical trial completion rates.
Inputs from NMPA, ECHA, and FDA regulatory databases were available through the study window; gaps in real-time subscription commerce transaction data introduce uncertainty bands around direct-to-consumer channel projections. Forecasts reflect assumptions about millennial parent digital-native purchasing persistence and REACH chemical restriction enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
North America Deodorants Market
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
Eye Cream Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
GCC Halal Cosmetics Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Liquid Makeup Market
Cosmetics & Skincare
Waterproof Temporary Tattoo Sticker Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
Global Cosmetic Antioxidant Market
Cosmetics & Skincare
Reusable Makeup Remover Pad Market
Cosmetics & Skincare
Halal Cosmetics Market