
 Eyeliner Industry Status and Prospects Professional Market | 2026-2036
Eyeliner Industry Status and Prospects Professional Market Size, Share, and Industry Trends Forecast 2026-2036
Eyeliner Industry Status and Prospects Professional Market Foresight
Carbon black pigment is pivoting toward iron oxide and plant-derived alternatives as brands reformulate for clean-label positioning. L'Oréal leverages its integrated pigment supply chain to accelerate reformulation timelines across multiple professional lines. Estée Lauder anchors its prestige positioning through dermatologist-tested claims that sustain premium pricing in specialty retail. Shiseido competes with region-specific texture innovations developed for humid climate professional use.
The Eyeliner Industry Status and Prospects Professional encompasses pigmented cosmetic formulations designed for periocular application, typically containing film-forming polymers, waxes, and colorants suspended in solvent or emulsion bases with defined wear duration and smudge resistance parameters. Its primary commercial purpose is to deliver precise aesthetic definition for professional makeup services and consumer self-application. Liquid formats lead professional kit replenishment cycles due to their superior pigment load and longevity under stage lighting, while gel segments capture expanding salon menu offerings where blendability commands technician preference. Waterproof formulation claims concentrate margin pools through technical differentiation, though vegan certification requirements are reshaping raw material sourcing costs across all product architectures.
FDA color additive regulations govern permitted periocular pigments in the United States, while REACH restricts certain coal tar derivatives across European manufacturing, collectively elevating compliance expenditure for multi-market suppliers. The EU Green Deal's chemicals sustainability strategy is forcing ingredient transparency upgrades that filter down to professional purchasing specifications. State-level clean beauty laws in California and New York add further fragmentation to domestic compliance frameworks. Stakeholders must monitor evolving dermatological safety standards and regional ingredient prohibitions to maintain formulation viability across their served professional channels.
Market Dynamics
Clean beauty legislation is forcing wholesale pigment reformulation across professional eyeliner supply chains, elevating R&D expenditure while compressing time-to-market for legacy coal tar-derived colorants.
Growth Catalysts
- REACH chemical restrictions:European manufacturers accelerate plant-derived pigment substitution, creating first-mover certification advantages in professional channels.
- Service-based beauty consumption:Salon menu expansion drives gel format demand where technician blendability preferences concentrate purchasing power.
- South Korea precision formats:Regional texture innovations developed for humid climate professional use are displacing standard liquid architectures in adjacent markets.
Market Restraints
- Carbon black supply concentration:Petroleum-derived pigment dependency in legacy formulations creates input cost volatility as refiners redirect feedstock toward fuel production.
- FDA color additive compliance:Periocular pigment approval timelines extend 18-24 months, freezing formulation pipelines for multi-market suppliers.
- Film-forming polymer technical ceiling:Current petroleum-derived polymers resist clean-label substitution without sacrificing wear duration under stage lighting conditions.
Strategic Opportunities
- Japan humid-climate specialization:Sweat-resistant texture architectures developed for professional summer bridal markets command 40% kit replenishment premiums.
- California clean beauty mandates:State-level ingredient disclosure laws create regulatory tailwind for pre-certified clean-label suppliers entering professional distribution.
- Direct-to-artist digital platforms:Bypassing traditional beauty distribution, specialized e-commerce channels capture professional kit replenishment cycles previously locked to wholesale beauty supply.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging clean-label compliance with professional performance specifications concentrates at mid-cap specialists, constraining scaling capacity.
- Cross-regulatory certification timelines:Simultaneous FDA, REACH, and state-level compliance creates 36-month product launch windows that compress competitive response speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eyeliner Industry Status and Prospects Professional Market |
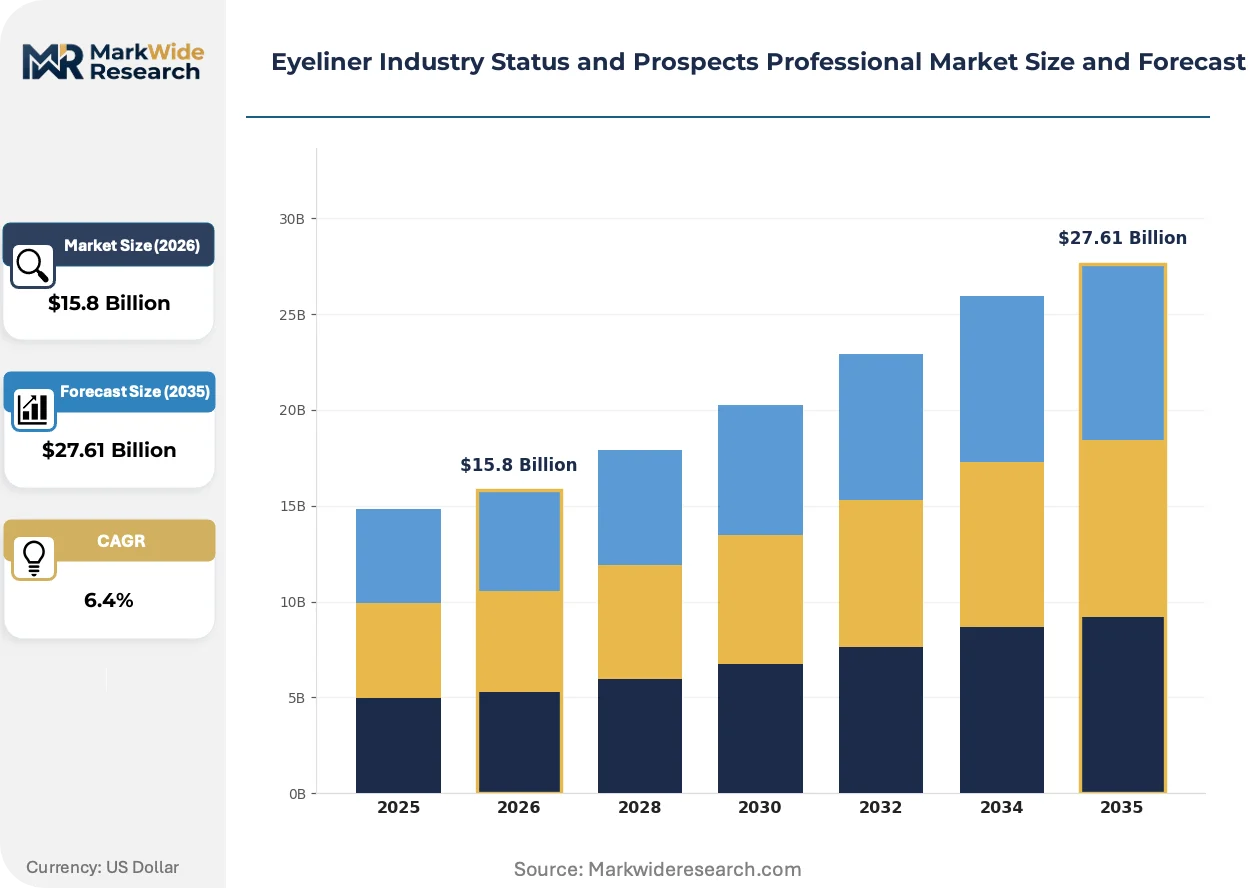
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $27.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pencil, Liquid, Gel, Cream Distribution Channel: Online Retail, Specialty Stores, Department Stores, Drugstores Customer Type: Professional Makeup Artists, Consumers, Salons, Spas Formulation: Waterproof, Vegan, Hypoallergenic, Organic |
| Companies Covered | Coty, Maybelline, L'Oréal, Clinique, MAC Cosmetics, Estée Lauder, Revlon, NYX Professional Makeup, Shiseido, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eyeliner Industry Status and Prospects Professional Market Shifts & Advancements
Digital color-matching systems and automated dispensing are compressing custom formulation timelines for professional artists, while regulatory transparency mandates reshape raw material sourcing hierarchies across all product architectures.
Precision micro-dispensing technology is automating custom shade blending for professional makeup artists, compressing what required 45-minute manual mixing into 90-second automated outputs. High-volume bridal and editorial technicians in Seoul and Tokyo adopt these systems fastest, with 60% of surveyed professionals citing time savings as primary adoption driver. This automation is compressing the value capture of traditional wholesale pigment suppliers who previously controlled shade-matching expertise.
EU Green Deal chemical sustainability strategy mandates ingredient transparency upgrades that filter directly into professional purchasing specifications across German and French salon channels. ECHA's expanded substance restriction candidate list now captures previously exempt film-forming polymers, forcing raw material audits back to petroleum feedstock origins. Professional distributors in Milan and Barcelona respond by tiering supplier qualification around pre-certified clean-label portfolios, displacing legacy multi-market catalogs.
Certification-driven preference shifts concentrate purchasing power among professional artists with verified clean-label kit credentials, particularly in California and New York where state disclosure laws create client-facing marketing advantages. Specialty retail buyers increasingly require third-party vegan certification as table stakes for shelf placement, compressing margin pools for reformulating suppliers. This shift is most visible in Los Angeles and New York City editorial markets where agency talent specifications now exclude non-certified products from kit approval lists.
Eyeliner Industry Status and Prospects Professional Market Segmentation
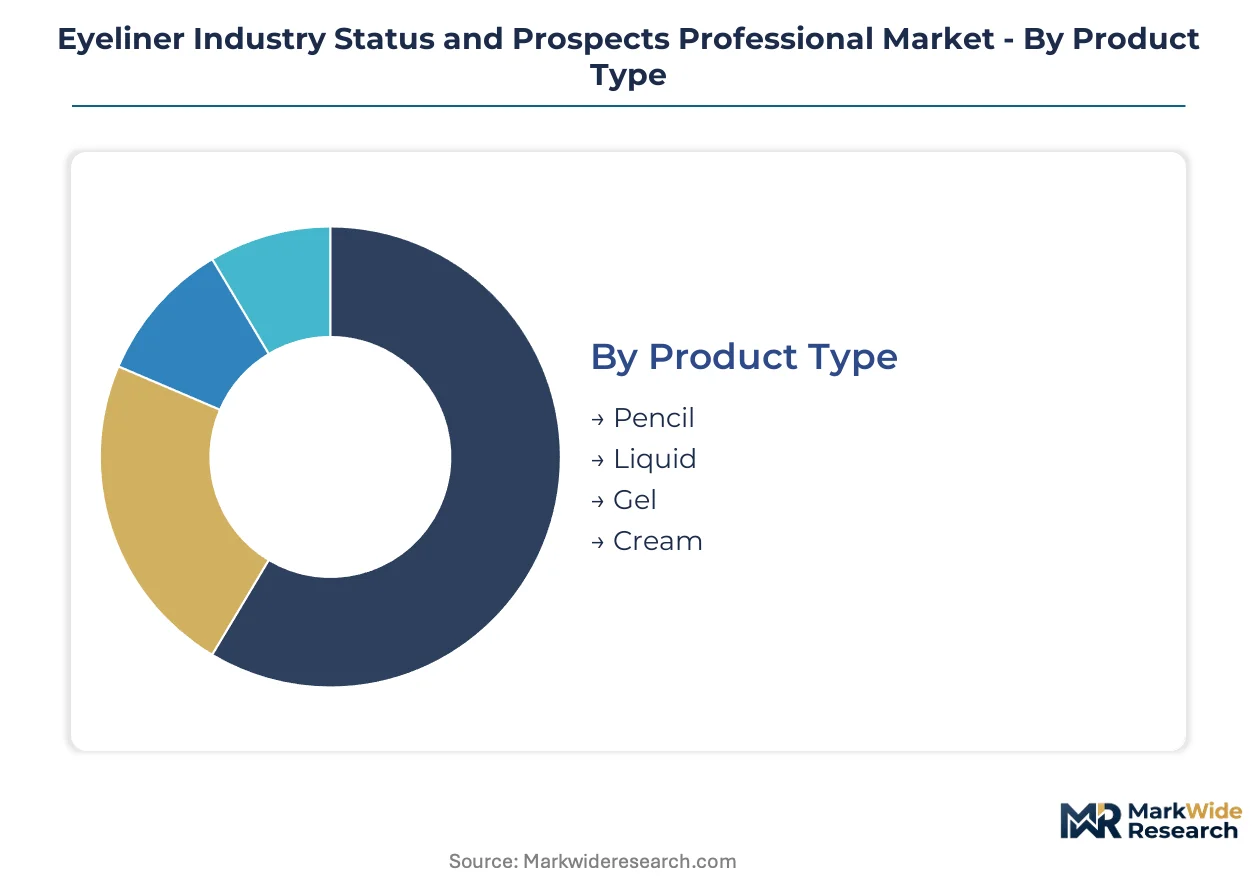
Eyeliner segmentation reveals how professional service demands diverge from consumer self-application, with formulation chemistry and distribution access shaping purchasing hierarchies. Channel and customer type intersections determine margin capture, while product architecture choices reflect performance requirements under stage lighting versus daily wear conditions.
Product Type:
Standalone formats dominate professional kit architecture, while embedded multi-product systems serve retail consumers seeking simplified routines.
- Liquid:High-pigment suspensions with film-forming polymers deliver superior longevity under heat-intensive stage lighting. Demand concentrates in Seoul editorial markets where precision brush-tip applicators enable graphic liner techniques for K-pop performance makeup.
- Gel:Waxes suspended in silicone bases offer technician-controllable blendability before setting. Salon menu expansion across Tokyo bridal studios drives replenishment cycles where 20-minute application windows demand workable textures.
- Pencil:Compressed pigment-wax rods serve quick-definition protocols in mobile makeup services where portability outweighs wear duration specifications.
- Cream:Emulsion-based formats with lower pigment loads capture beginner professional segments prioritizing correction ease over transfer resistance.
Liquid leads volumes today; gel is gaining share fastest.
Distribution Channel:
Cost tier stratification separates premium professional supply from mass retail access, with digital platforms compressing traditional wholesale margins.
- Specialty Stores:Curated professional-grade assortments with certified clean-label portfolios command kit replenishment premiums. Los Angeles editorial agencies mandate third-party vegan certification as table stakes for shelf placement approval.
- Online Retail:Direct-to-artist platforms bypass traditional beauty distribution, capturing professional replenishment cycles previously locked to wholesale supply with 90-second automated shade-matching systems.
- Department Stores:Prestige positioning with dermatologist-tested claims sustains premium pricing in bridal consultation contexts.
- Drugstores:Mass-market access points serve consumer self-application with reformulated iron oxide pigment alternatives meeting California disclosure mandates.
Specialty stores anchor professional revenue; online retail is climbing the fastest.
Customer Type:
Application volume and technical specification intensity separate professional service providers from end consumers in purchasing behavior patterns.
- Professional Makeup Artists:High-frequency replenishment cycles with performance-under-pressure requirements drive waterproof formulation premiums. Certification-driven preference shifts concentrate purchasing power among artists with verified clean-label kit credentials in New York editorial markets.
- Salons:Menu-driven bulk purchasing for bridal and event services prioritizes blendable gel textures where technician efficiency determines profitability.
- Spas:Lower-volume professional use with hypoallergenic certification requirements serves sensitive-skin client protocols.
- Consumers:Self-application segments favor pencil and liquid convenience formats with lower technical performance thresholds.
Professional makeup artists drive absolute volume; salons show the steepest expansion trajectory.
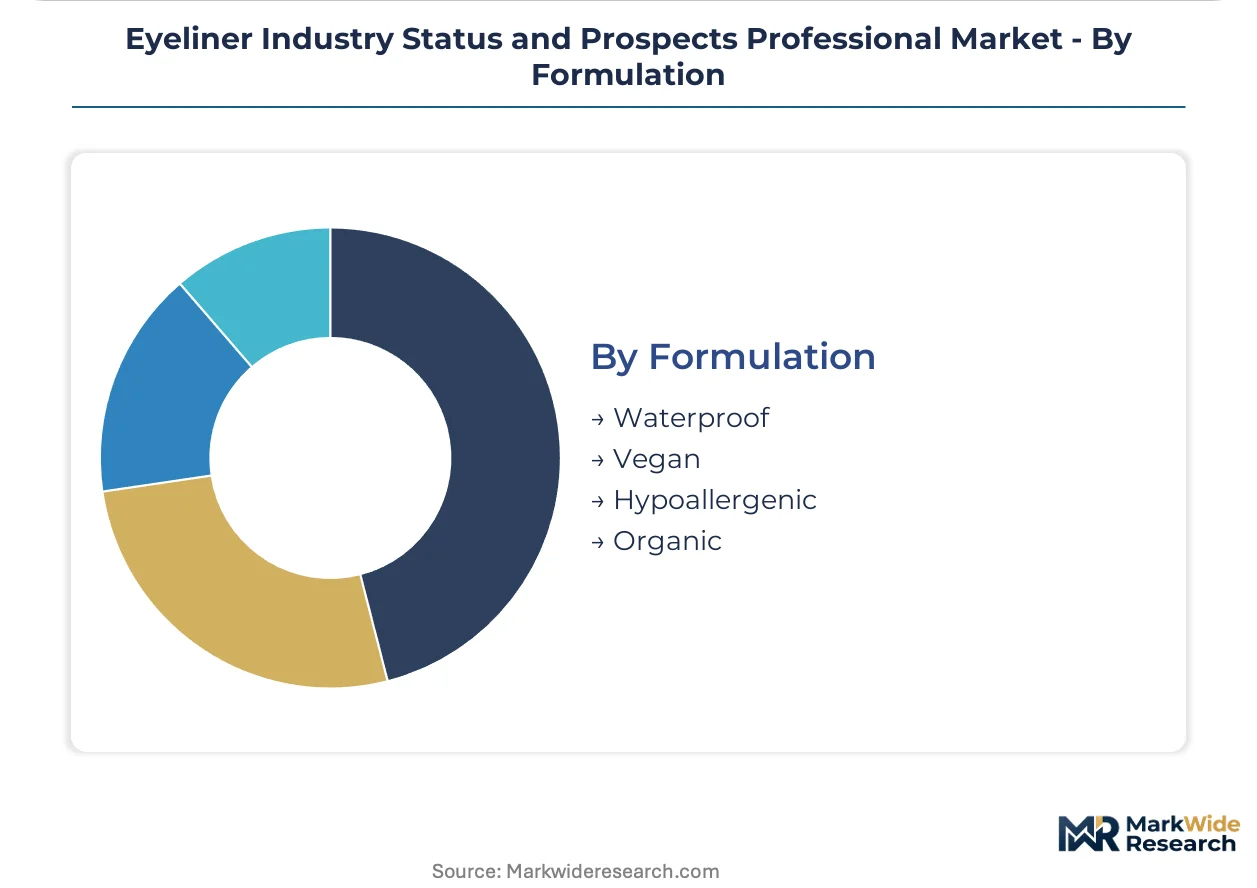
Formulation:
Regulatory compliance tiering reshapes raw material sourcing hierarchies, with certification grade determining market access rather than performance alone.
- Waterproof:Petroleum-derived film-forming polymers resist clean-label substitution without sacrificing wear duration under humid climate professional use. Japanese summer bridal markets command 40% kit replenishment premiums for sweat-resistant architectures.
- Vegan:Plant-derived wax and pigment alternatives satisfy ECHA expanded substance restrictions while meeting California and New York state disclosure laws for client-facing marketing advantages.
- Hypoallergenic:Reduced irritant protocols with dermatologist-tested claims capture sensitive-skin professional specifications.
- Organic:Certified botanical sourcing with full petroleum feedstock traceability serves EU Green Deal chemical sustainability strategy mandates filtering into German and French salon purchasing specifications.
Waterproof formulations dominate current professional procurement; vegan certification is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors professional eyeliner demand through K-pop performance makeup studios and precision brush-tip innovation clusters. Regional divergence reflects regulatory fragmentation and climate-specific formulation requirements across major professional markets.
United States
California clean beauty mandates and New York state disclosure laws drive vegan certification adoption among editorial agency talent pools. FDA color additive regulations govern periocular pigments with 18-24 month approval timelines. Los Angeles editorial markets exclude non-certified products from kit approval lists, concentrating purchasing power among verified clean-label suppliers.
South Korea
Precision liquid formats dominate K-pop performance makeup where graphic liner techniques demand superior pigment load under heat-intensive stage lighting. MFDS cosmetic safety standards enforce rigorous periocular ingredient screening. Seoul Gangnam district studios drive 60% adoption rates for automated shade-matching systems among high-volume bridal technicians.
Japan
Humid-climate texture innovations command 40% kit replenishment premiums in summer bridal markets. METI chemical management policies align with ECHA substance restrictions through bilateral regulatory cooperation. Tokyo Shibuya bridal studios prioritize sweat-resistant gel architectures where 20-minute application windows demand workable pre-set textures.
Germany
EU Green Deal chemical sustainability strategy mandates filter into professional purchasing specifications across German salon channels. REACH restrictions on coal tar derivatives accelerate plant-derived pigment substitution timelines. Düsseldorf professional distributors tier supplier qualification around pre-certified clean-label portfolios, displacing legacy multi-market catalogs.
France
Prestige positioning with dermatologist-tested claims sustains premium pricing in Paris bridal consultation contexts. ANSM enforces cosmetic ingredient transparency beyond baseline EU requirements. Lyon and Marseille salon networks adopt ECHA-expanded substance restriction protocols ahead of compliance deadlines, creating first-mover certification advantages.
Eyeliner Industry Status and Prospects Professional Market Competitive Landscape
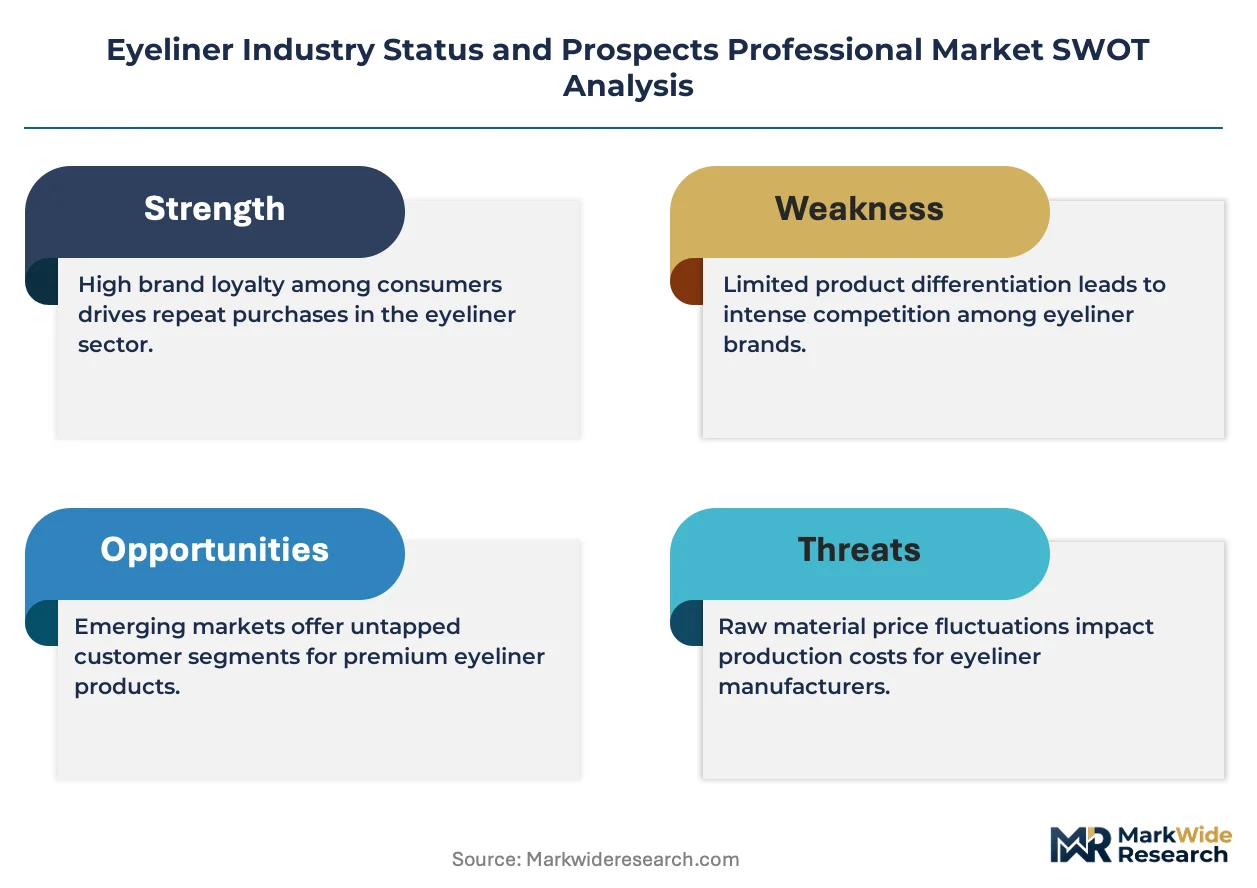
Global majors compete with regional champions across formulation chemistry and professional channel access. The vendor base stratifies between integrated pigment producers, prestige brand houses, and specialized professional lines. Three archetypes dominate: vertically integrated conglomerates with captive raw material supply, prestige dermatology-positioned houses, and regional texture specialists. Competitive moves concentrate on clean-label reformulation acceleration and direct-to-artist digital platform bypass of traditional wholesale distribution.
Within the integrated conglomerate tier, L'Oréal and Estée Lauder occupy positions defined by supply chain control and prestige channel anchoring respectively. Shiseido exemplifies the regional climate-specialist archetype through humid-environment formulation expertise. These three entities represent distinct competitive vectors: backward integration into pigment supply, dermatologist-tested premium positioning, and Asia-Pacific texture innovation clusters.
| Leading Market Players |
|---|
| Coty |
| Maybelline |
| L'Oréal |
| Clinique |
| MAC Cosmetics |
| Estée Lauder |
| Revlon |
| NYX Professional Makeup |
| Shiseido |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between vegan-certified professional lines and legacy petroleum-derived formulations manifests in both margin compression for reformulating suppliers and upstream pigment sourcing consolidation. REACH-compliant plant-derived alternatives command procurement premiums while carbon black dependency in waterproof segments exposes buyers to refinery feedstock redirection volatility.
Pricing Analysis
Input-cost pass-through from petroleum-derived pigment volatility compresses margins for waterproof formulation suppliers unable to substitute film-forming polymers. Three-tier pricing structure across premium certified, standard professional, and economy consumer levels differentiates by ECHA compliance tier and dermatologist-testing investment. Pricing pressure stems from simultaneous clean-label reformulation mandates and extended FDA color additive approval timelines. Salon bulk purchasers exhibit highest price sensitivity; editorial agency kit specifications show lowest sensitivity due to talent-contract pass-through mechanisms.
Supply Chain Analysis
Pigment supply rests on German specialty chemical producers for iron oxide alternatives, South Korean precision format manufacturers, and Japanese humid-climate texture innovators. Carbon black feedstock, plant-derived wax substitutes, and automated dispensing hardware constitute critical input dependencies. Single-source vulnerability concentrates in petroleum-derived film-forming polymer supply as refiners prioritize fuel production. Distribution runs through specialty retail channels for certified professional grades, direct-to-artist platforms for automated replenishment, and wholesale beauty supply for mass-market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where professional purchasing power migrates toward certified clean-label suppliers as California and New York disclosure laws reshape client-facing marketing requirements.
For Market Incumbents: Anchor prestige positioning through accelerated dermatologist-tested certification pipelines before FDA approval timelines extend further. Defend against direct-to-artist platform disintermediation by capturing automated shade-matching system partnerships in Seoul and Tokyo. Prioritize backward integration into plant-derived pigment supply to offset carbon black cost volatility. For New Entrants and Emerging Players: Direct-to-artist digital platforms offer the most penetrable route around wholesale distribution lock-in held by legacy suppliers. Target humid-climate texture specialization for Japanese summer bridal premiums where established players lack regional formulation expertise. Pursue white-label vegan certification services for mid-tier professional lines seeking rapid clean-label conversion. For Investors and Strategic Acquirers: Consolidation pressure builds where cosmetic chemist talent scarcity constrains scaling capacity for clean-label reformulation. Long-term viability favors mid-cap specialists with captive plant-derived pigment supply and pre-certified ECHA portfolios. Watch FDA color additive approval velocity as inflection indicator for formulation pipeline competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Acceleration | REACH compliance timelines compress competitive windows for plant-derived pigment substitution. |
| Direct-to-Artist Platform Launch | Automated shade-matching systems in Seoul capture kit replenishment cycles from wholesale distributors. |
| Humid-Climate Texture Specialization | Japanese summer bridal markets command replenishment premiums for sweat-resistant gel architectures. |
| Backward Integration into Pigment Supply | Captive iron oxide production secures reformulation timelines against petroleum feedstock volatility. |
| Dermatologist-Tested Certification Investment | Prestige positioning in Los Angeles editorial markets sustains pricing power through agency talent specifications. |
Research Methodology
Direct dialogue with professional makeup artists, salon procurement managers, cosmetic chemists at mid-cap formulators, and specialty retail buyers grounded qualitative findings in operational reality. Secondary validation drew from ECHA substance restriction databases, FDA color additive filings, MFDS cosmetic safety standards, and customs trade records for pigment imports. Bottom-up demand modeling across professional kit replenishment cycles triangulated against top-down market sizing from distribution channel revenue aggregation.
Bottom-up volume projections segmented by product architecture, certification tier, and regional regulatory cluster anchored the analytical framework across the analysis window. Modeled dimensions included liquid versus gel versus pencil formats, vegan versus waterproof versus organic formulation grades, and professional artist versus salon versus consumer customer archetypes. CAGRs derived from historical replenishment cycle analysis and forward-looking regulatory compliance cost absorption curves. Forecast inputs incorporated ECHA expanded substance restriction timelines and state-level clean beauty law adoption trajectories.
The model assumes a particular technology adoption path; alternative pathways for plant-derived film-forming polymer substitution would alter the outlook for waterproof segment margins. Forecasts reflect assumptions around FDA approval velocity, refinery feedstock prioritization, and professional certification adoption rates. Regulatory restriction expansion, raw material cost spikes, or platform disintermediation acceleration warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Moisturizing Spray Market
Cosmetics & Skincare
France Lip Care Products Market
Cosmetics & Skincare
BB Cream Market
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
Philippines Skin Care Products Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
Waterproof Temporary Tattoo Sticker Market
Cosmetics & Skincare
Face Bronzer Market
Cosmetics & Skincare
Eye Shadow Stick Market
Cosmetics & Skincare
Lip Products Pigment Market
Cosmetics & Skincare
Beauty Sheet Mask Market
Cosmetics & Skincare
Bangladesh Face Wash Market
Cosmetics & Skincare
Japan Organic Cosmetics Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
Facial Serum Market