
 Bar Soap Market | 2026-2036
Bar Soap Market Size, Share, and Industry Trends Forecast 2026-2036
Bar Soap Market Analysis
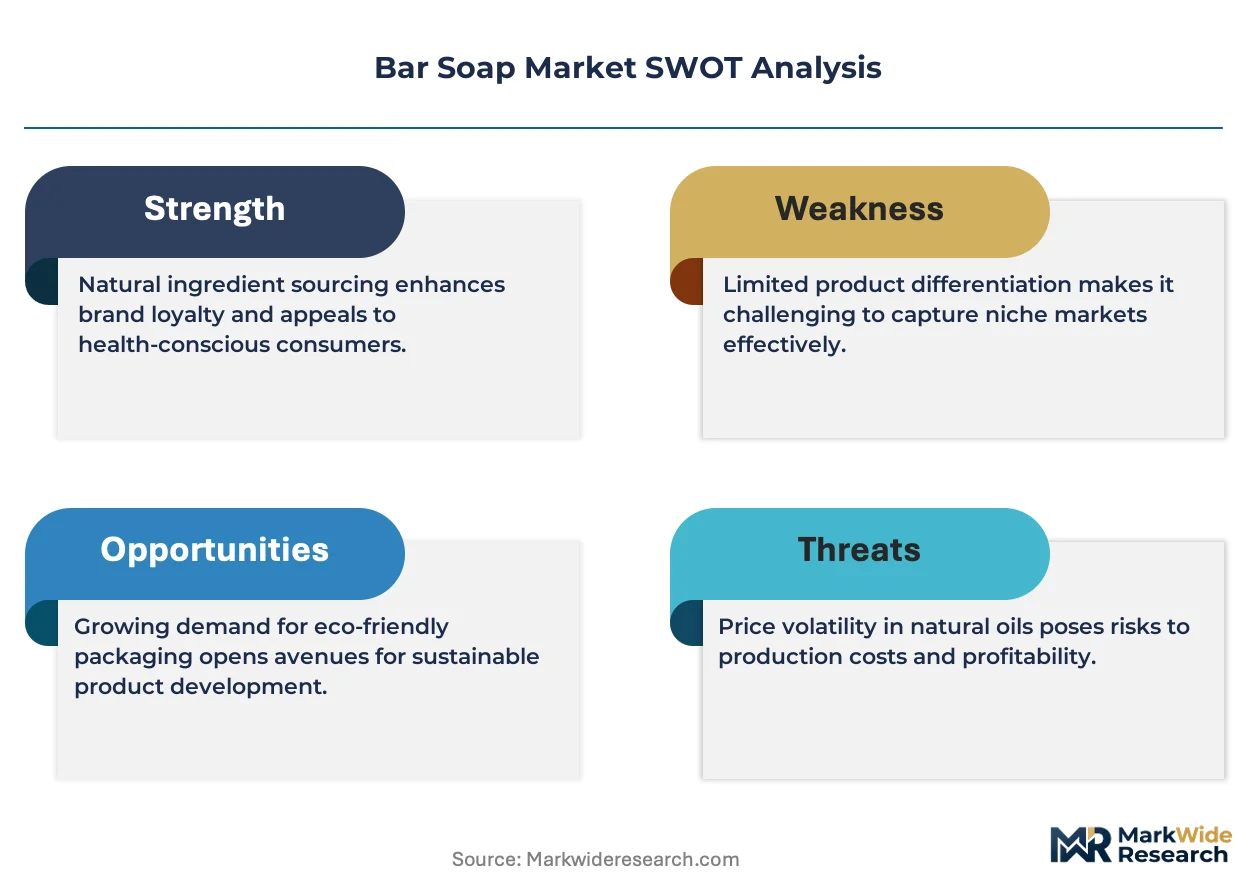
The price-performance gap between premium artisanal bars and mass-market commodity soap is hardening as ingredient transparency becomes a decisive purchase trigger. Unilever leverages its global procurement network to sustain cost leadership in synthetic base formulations across emerging markets. Procter & Gamble differentiates through dermatological certification programs that anchor its premium positioning in North American pharmacy channels. Beiersdorf AG specializes in glycerin-enriched bars that command higher shelf space allocations in European wellness retail.
Bar soap denotes a solid cleansing agent produced through saponification of fats or oils with alkali, typically containing 80-85% soap base with added moisturizers, fragrances, or active ingredients, manufactured via continuous soap-making or cold-process methods for personal hygiene and surface cleaning applications. The antimicrobial segment dominates institutional procurement from hotels and wellness centers where sanitation protocols mandate bactericidal claims, while organic formulations capture the fastest household growth as clean-label preferences migrate from skincare into daily cleansing routines. Natural formulation bars concentrate margin pools through ingredient storytelling and supply chain traceability that synthetic alternatives cannot easily replicate.
India's BIS mandates minimum total fatty matter content for bathing bars, directly elevating raw material costs for non-compliant producers and accelerating formal sector consolidation. The EU REACH framework restricts certain synthetic preservatives and fragrance allergens, compelling reformulation investments that favor larger manufacturers with dedicated toxicology departments. Stakeholders must monitor evolving state-level plastic packaging bans in India and Indonesia that will force rapid transitions toward paper wrapping and bulk dispensing formats before enforcement timelines crystallize.
Market Dynamics
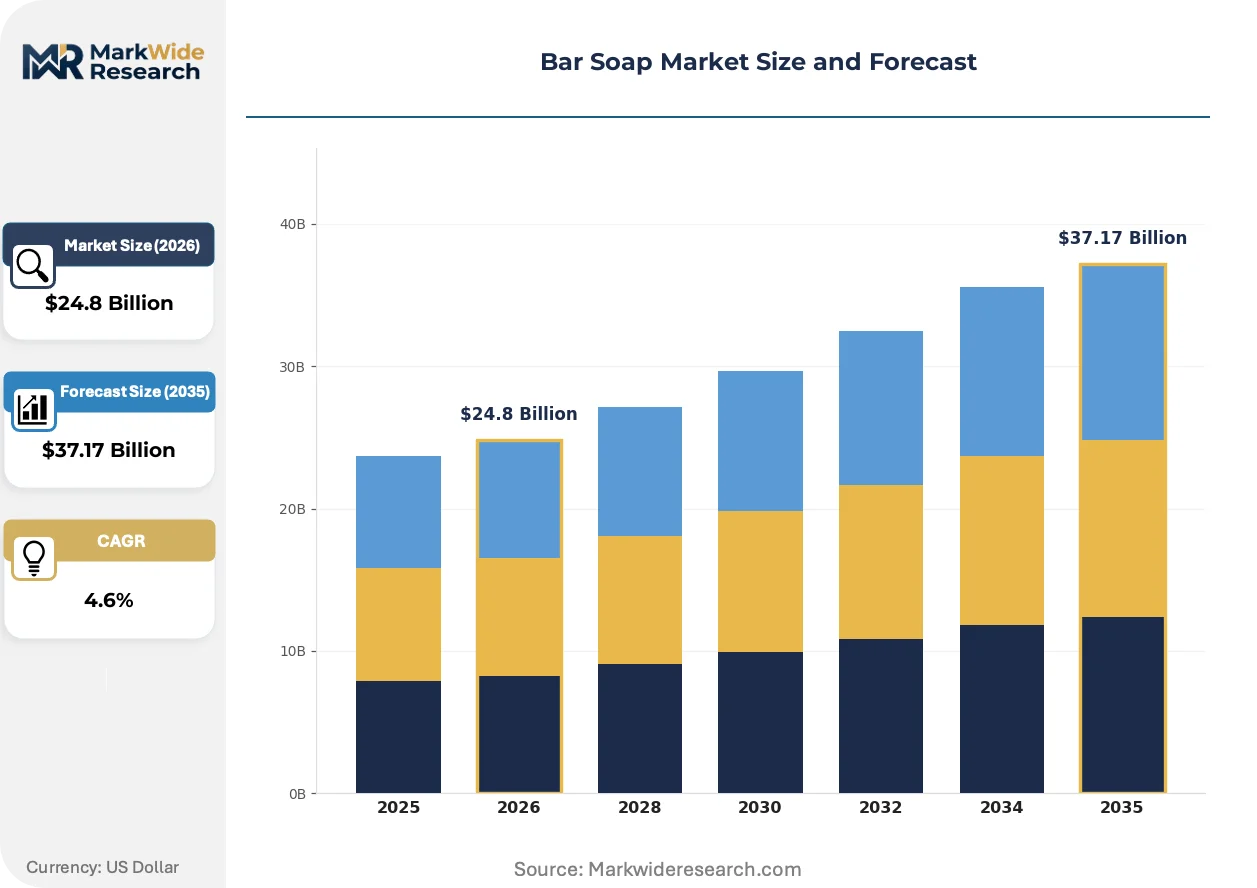
Ingredient transparency mandates and supply chain traceability requirements are compressing margins for synthetic-base producers while concentrating margin pools among natural-formulation specialists with verified sourcing documentation.
Growth Catalysts
- Emerging-market household formalization:Consumers across India, Indonesia, and Vietnam trade up from unbranded alternatives to packaged bathing bars, expanding the addressable base for compliant manufacturers.
- REACH-driven reformulation:The EU framework restricts synthetic preservatives and fragrance allergens, compelling investments that favor producers with dedicated toxicology departments and accelerating formal sector consolidation.
- Wet-bathing culture persistence:Southeast Asian markets sustain high per-capita usage rates through traditional bathing practices that resist liquid-soap substitution.
Market Restraints
- Palm oil price volatility:Fatty acid inputs constitute the dominant raw material cost for saponification-based production, exposing margins to commodity swings in Malaysian and Indonesian supply.
- BIS compliance costs:India's minimum total fatty matter mandates elevate raw material thresholds for non-compliant producers, forcing facility upgrades or exit.
- Liquid cleanser substitution:Body wash and shower gel formats capture shelf space in modern trade channels across urban China and South Korea.
Strategic Opportunities
- State-level plastic packaging bans:India's and Indonesia's emerging prohibitions on plastic wrapping force rapid transitions toward paper and bulk dispensing formats before enforcement crystallizes.
- Herbal certification anchoring:India's growing preference for Ayurvedic and plant-based formulations creates white space for domestic producers with verified botanical supply chains.
- Wellness retail channel expansion:European pharmacy and specialty beauty channels allocate premium shelf space to glycerin-enriched and dermatologically tested bars.
Industry Challenges
- Cold-process manufacturing scale-up:Artisanal production methods face throughput constraints when transitioning from craft batches to commercial volumes without quality degradation.
- Multi-jurisdiction compliance synchronization:Producers exporting across BIS, REACH, and FDA jurisdictions must maintain parallel formulation and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bar Soap Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobial, Moisturizing, Organic, Exfoliating Formulation: Natural, Synthetic, Glycerin-Based, Herbal End User: Households, Hotels, Salons, Wellness Centers Packaging Type: Eco-Friendly, Plastic, Glass, Bulk |
| Companies Covered | Reckitt Benckiser, Henkel, Unilever, Kao Corporation, Beiersdorf AG, Procter & Gamble, Colgate-Palmolive, Kimberly-Clark, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bar Soap Market Emerging Trajectories
Formulation chemistry and packaging substrates are undergoing simultaneous transformation as regulatory pressure intersects with consumer preference migration toward verifiable natural content.
Cold-process saponification is absorbing premium positioning in North American and European markets. Small-batch producers and mid-scale manufacturers adopt this method to preserve glycerin content and enable superfatting claims. The technology is absorbing margin compression from synthetic-base commodity competition by anchoring price premiums through ingredient storytelling.
REACH fragrance allergen restrictions are forcing systematic reformulation across European-exporting facilities. The regulation bans specific synthetic preservatives and mandates disclosure of sensitizer compounds above threshold concentrations. Natural-formulation bars with limited ingredient lists capture fastest household growth as clean-label preferences migrate from skincare into daily cleansing.
Ingredient verification through blockchain-enabled supply chain documentation is reshaping procurement criteria for premium-tier buyers. Wellness retailers and direct-to-consumer channels demand batch-level traceability for palm oil and botanical inputs. This pattern concentrates most visibly in German and Nordic markets where environmental certification bodies influence stocking decisions.
Bar Soap Market Segmentation
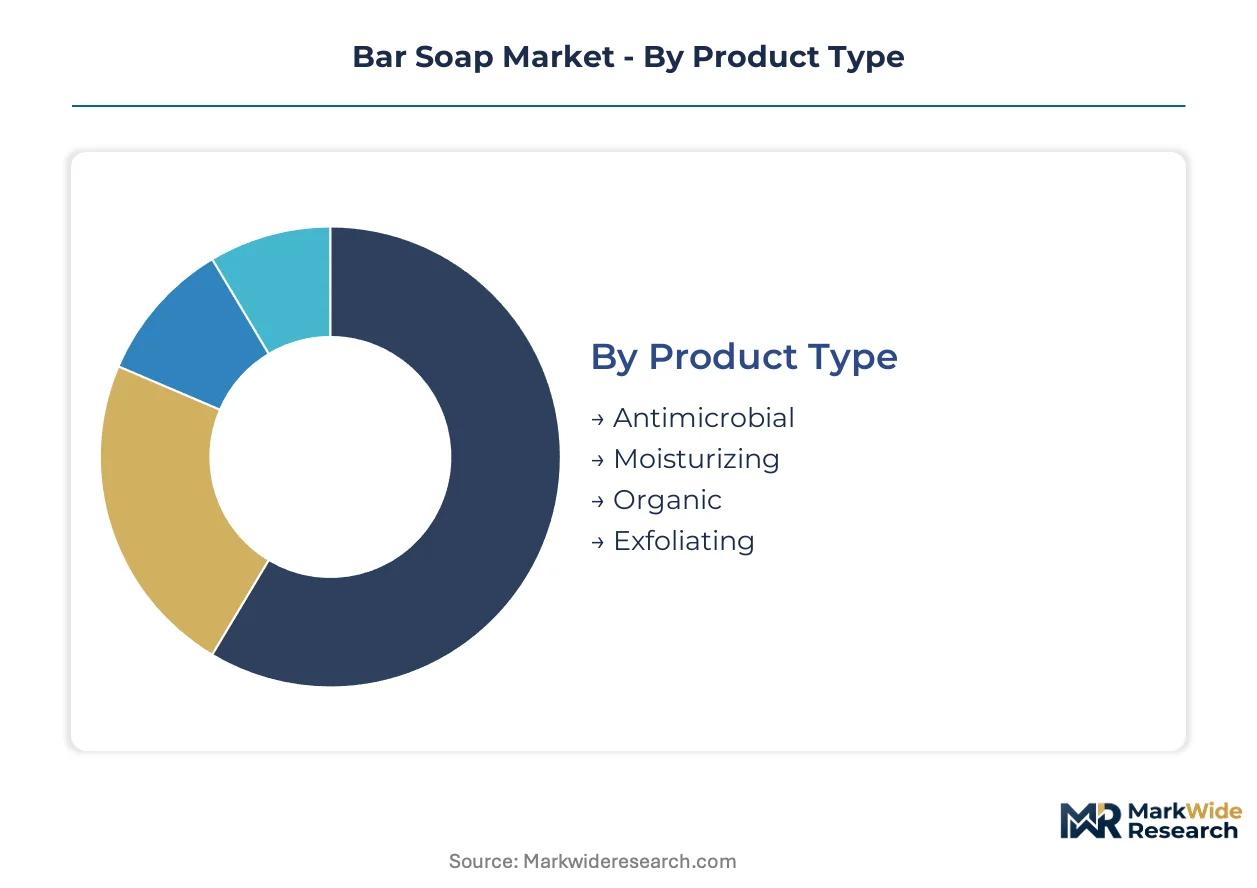
Bar soap manufacturers navigate divergent upgrade cycles across consumer and institutional channels. Households replace bars based on sensory preference shifts and ingredient transparency demands, while hotels and wellness centers follow procurement calendars tied to sanitation certification renewals.
Product Type:
Upgrade cycles vary sharply between institutional mandates and household discretionary replacement.
- Antimicrobial:Formulated with bactericidal agents meeting institutional sanitation protocols. Hotels and wellness centers in Southeast Asia sustain concentrated procurement volumes where wet-bathing cultures elevate hygiene standards. BIS quality mandates in India accelerate formal sector adoption over unbranded alternatives.
- Moisturizing:Glycerin-enriched or superfatted compositions targeting dermatological positioning. European pharmacy channels allocate premium shelf space to these bars as clean-label preferences migrate from skincare into daily cleansing routines.
- Organic:Certified botanical bases with supply chain traceability documentation. Natural-formulation specialists capture margin concentration through verified sourcing that synthetic alternatives cannot replicate.
- Exfoliating:Contains physical abrasives or enzymatic agents for skin renewal claims. Niche positioning in specialty beauty retail with limited volume scale.
Antimicrobial sits at the top of the volume ranking, with Organic climbing the fastest.
Formulation:
Raw material cost structures and regulatory compliance burdens stratify competitive positioning across chemistry types.
- Natural:Saponification of plant-derived fats and oils without synthetic additives. REACH fragrance allergen restrictions in Europe compel systematic reformulation investments that favor producers with dedicated toxicology departments.
- Synthetic:Petroleum-derived surfactant bases enabling cost leadership at scale. Unilever leverages global procurement networks to sustain margin positions across emerging markets where price sensitivity dominates.
- Glycerin-Based:Cold-process methods preserve humectant content for skin-conditioning claims. Beiersdorf AG specializes in this chemistry to command premium allocations in European wellness retail.
- Herbal:Ayurvedic and plant-based formulations with botanical certification. India's growing preference for traditional medicine creates white space for domestic producers with verified supply chains.
Synthetic dominates current volume, though Natural formulation gains share fastest as clean-label migration accelerates.
End User:
Procurement authority and specification complexity fragment demand patterns across buyer categories.
- Households:Individual purchase decisions driven by ingredient storytelling and sensory preference. Emerging economies in India, Indonesia, and Vietnam trade up from unbranded alternatives to packaged bathing bars.
- Hotels:Bulk procurement with antimicrobial certification requirements. Sanitation protocols mandate bactericidal claims in institutional settings.
- Salons:Professional-grade positioning with brand affiliation to service experience. Limited volume concentration relative to hospitality and household channels.
- Wellness Centers:Premium positioning aligned with holistic health positioning. Dermatological certification programs anchor supplier selection in North American pharmacy channels.
Households generate the largest absolute volume, with Wellness Centers expanding most quickly on per-unit value metrics.
Packaging Type:
Regulatory enforcement timelines and retail channel requirements force rapid substrate transitions.
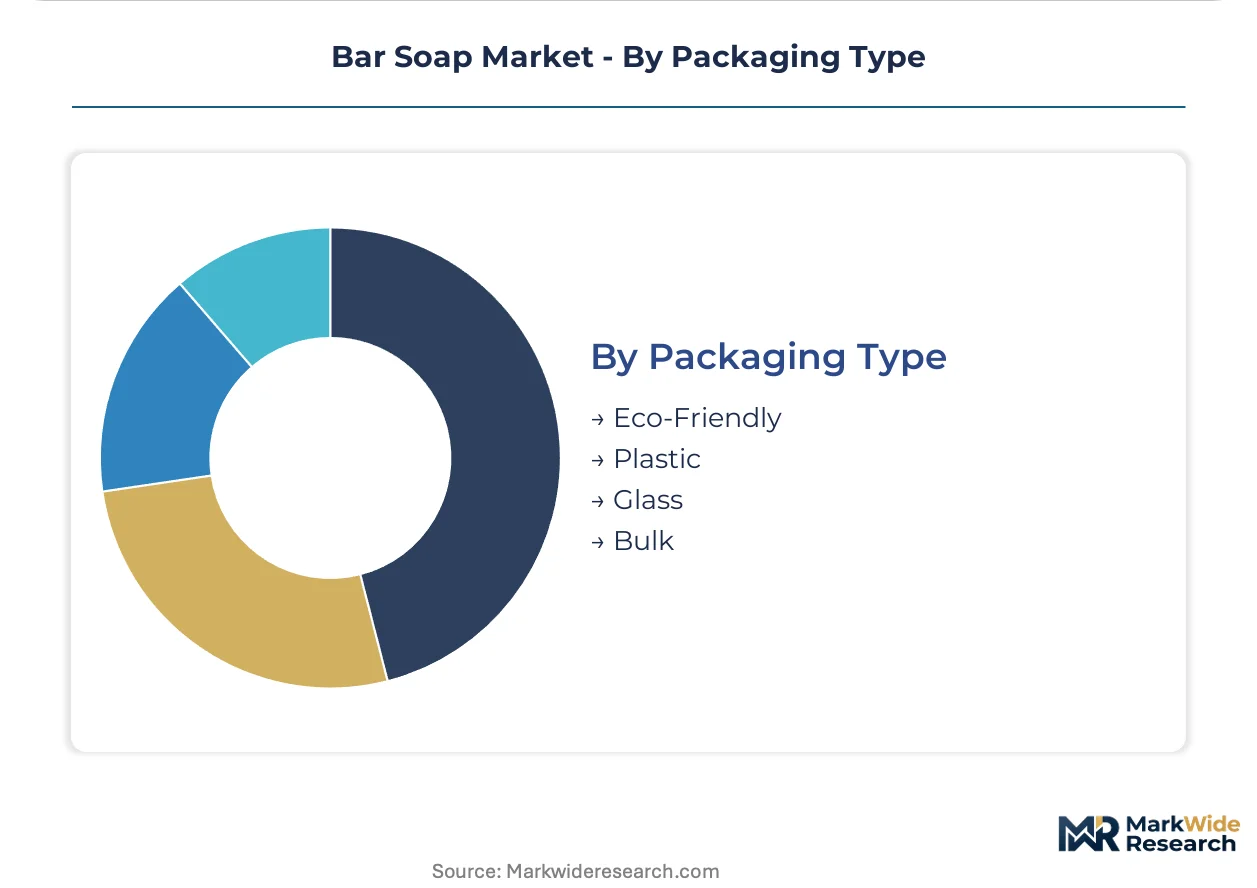
- Eco-Friendly:Paper wrapping and compostable materials responding to state-level plastic bans. India's and Indonesia's emerging prohibitions force transitions before enforcement crystallizes.
- Plastic:Conventional wrapping facing regulatory phase-out. Producers must maintain parallel packaging systems during transition periods.
- Glass:Premium positioning with reuse and refill potential. Limited adoption due to weight and fragility constraints in wet-bathing environments.
- Bulk:Unwrapped bars for dispenser systems in institutional and zero-waste retail. Blockchain-enabled supply chain documentation supports batch-level traceability for palm oil inputs.
Plastic remains volume-dominant pending enforcement, while Eco-Friendly packaging scales fastest on regulatory momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and Indonesia diverge sharply in regulatory trajectory despite shared wet-bathing cultures. Where India imposes BIS quality mandates that elevate raw material thresholds, Indonesia accelerates plastic packaging prohibitions that reshape substrate economics. These divergent policy vectors compress margins differently across the two largest emerging-volume markets.
India
Household formalization drives volume expansion as consumers abandon unbranded alternatives for packaged bathing bars. BIS mandates minimum total fatty matter content, forcing facility upgrades among non-compliant producers and accelerating consolidation toward organized manufacturers. Maharashtra and Gujarat host concentrated soap-making clusters where cold-process artisanal methods scale toward commercial volumes.
Indonesia
Traditional wet-bathing practices sustain per-capita usage rates that resist liquid-soap substitution. State-level plastic packaging bans compel rapid transitions toward paper wrapping and bulk dispensing formats before enforcement timelines crystallize. Java-based manufacturing hubs absorb reformulation investments to meet emerging eco-friendly packaging requirements.
United States
Dermatological certification programs anchor premium positioning in pharmacy channels where consumers prioritize ingredient transparency over cost. FDA oversight of cosmetic labeling intersects with state-level clean beauty legislation in California and New York. Midwest production facilities leverage soybean oil feedstocks to offset palm oil price volatility affecting coastal competitors.
Germany
REACH fragrance allergen restrictions compel systematic reformulation investments that favor manufacturers with dedicated toxicology departments. ECHA documentation requirements concentrate margin pools among natural-formulation specialists with verified supply chain traceability. Bavarian and North Rhine-Westphalian wellness retail channels allocate premium shelf space to glycerin-enriched bars with blockchain-enabled ingredient verification.
Vietnam
Rising household disposable income triggers trade-up from unbranded to branded bathing bars across urban centers. The country's national standards body elevates quality thresholds through progressive technical regulations mirroring ASEAN harmonization frameworks. Ho Chi Minh City and Hanoi manufacturing zones attract regional packaging suppliers adapting to paper-based substrate transitions.
Bar Soap Market Vendor Landscape
Top-tier vendors anchor mass-market volume through global procurement networks, while mid-scale natural-formulation specialists capture concentrated margin pools. The vendor base stratifies across three tiers: multinational FMCG conglomerates with synthetic-base cost leadership, regional herbal specialists with verified botanical supply chains, and artisanal cold-process producers scaling toward commercial throughput. Consolidation accelerates through facility acquisitions in India and Indonesia, while technology licensing agreements spread cold-process methods to mid-scale manufacturers seeking premium positioning.
Within the mass-market tier, Unilever and Procter & Gamble exemplify scale-driven positioning through synthetic-base formulations and dermatological certification programs respectively. Beiersdorf AG occupies a specialized position in glycerin-enriched chemistry. These three entities represent divergent strategic archetypes: procurement-optimized cost leadership, regulatory-anchored premium positioning, and humectant-focused wellness retail penetration.
| Leading Market Players |
|---|
| Reckitt Benckiser |
| Henkel |
| Unilever |
| Kao Corporation |
| Beiersdorf AG |
| Procter & Gamble |
| Colgate-Palmolive |
| Kimberly-Clark |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Palm oil and coconut fatty acid inputs flow from Indonesian and Malaysian plantations through commodity traders to saponification facilities, with price volatility in these upstream markets compressing margins for synthetic-base producers while natural-formulation specialists capture premium tiers through verified sourcing documentation.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for mass-market synthetic bars as regional producers scale continuous soap-making output. Three-tier pricing structure across premium cold-process, standard glycerin-enriched, and economy synthetic tiers anchors differentiation on certification grade and ingredient transparency. Pricing pressure stems from REACH-driven reformulation investments that favor larger manufacturers with dedicated toxicology departments. Households in emerging economies exhibit highest price sensitivity, while European pharmacy channels show least sensitivity due to dermatological certification requirements.
Supply Chain Analysis
Dual-sourcing requirements from European wellness retailers mandate multi-supplier qualification for palm oil and botanical inputs, forcing producers to maintain parallel documentation systems. Manufacturing concentrates in India, Indonesia, and Vietnam where wet-bathing cultures sustain concentrated demand. Fatty acid feedstocks, fragrance compounds, and packaging substrates constitute critical input dependencies. Single-source vulnerability in Malaysian palm oil supply creates exposure to commodity price swings. Distribution runs through modern trade channels in urban centers and traditional wholesale networks in rural emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bar Soap Market functions as a geographic-arbitrage play where producers exploit regulatory cost differentials between BIS-mandated India and plastic-ban-accelerating Indonesia to optimize formulation and packaging investments.
For Market Incumbents: Deploy blockchain-enabled supply chain documentation as a defensive lever against emerging natural-formulation specialists. Consolidate position through acquisition of cold-process artisanal producers in Maharashtra and Gujarat clusters to capture premium positioning. Counter liquid cleanser substitution threats by anchoring antimicrobial certification in Southeast Asian hospitality procurement. Reinforce channel control through exclusive pharmacy shelf space agreements in Germany and Nordic markets.
For New Entrants and Emerging Players: Direct-to-consumer subscription models offer the lowest barrier to entry for Ayurvedic-certified herbal bars targeting diaspora households in North America. White space concentrates in Indonesia's paper-packaging transition ahead of enforcement crystallization. Penetrate Vietnam's urban household formalization wave through traditional medicine storytelling. Leverage wellness influencer partnerships to bypass modern trade slotting fees.
For Investors and Strategic Acquirers: Consolidation pressure builds where BIS compliance costs force facility upgrades among non-compliant Indian producers. Long-term viability favors natural-formulation specialists with verified botanical supply chains and cold-process scale-up capability. Target acquisition archetype: mid-scale regional herbal producers with Ayurvedic certification and underutilized production capacity. Watch palm oil price volatility as the signal indicating margin compression timing for synthetic-base exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Acid Supply | Captive palm oil sourcing from Indonesian estates insulates margins from commodity volatility. |
| Cold-Process Capacity Scale-Up | Commercial throughput expansion in Gujarat clusters enables premium-tier volume capture. |
| Blockchain Supply Chain Verification | German wellness retailers demand batch-level traceability for palm oil and botanical inputs. |
| Paper Packaging Transition | Pre-enforcement positioning in Maharashtra and Java avoids regulatory disruption. |
| Ayurvedic Certification Investment | BIS-aligned herbal standards create defendable positioning in India's formalizing household channel. |
Methodological Framework
Coverage spans India, Indonesia, Vietnam, Germany, and the United States, with primary inputs from each market gathered through structured interviews with brand managers, category buyers at modern trade retailers, supply planners, and cold-process artisanal producers. Secondary validation draws from BIS technical regulations, ECHA REACH documentation, customs and trade flow data, and retail audit databases. Bottom-up volume modeling triangulates against top-down value estimates across synthetic and natural formulation chemistry types.
Granularity extends to product-type level for antimicrobial, moisturizing, organic, and exfoliating segments; formulation chemistry for natural, synthetic, glycerin-based, and herbal bases; and packaging substrate transitions across plastic, paper, and bulk dispensing formats. CAGRs derive from trend extrapolation adjusted for regulatory enforcement timelines and household formalization rates. Forecast inputs include palm oil futures curves, BIS compliance cost estimates, and REACH reformulation investment schedules.
The model assumes a particular technology adoption path; alternative pathways for cold-process saponification scale-up would alter the outlook if throughput constraints prove insurmountable. Forecasts reflect assumptions about BIS enforcement intensity, plastic packaging ban implementation timelines, and liquid cleanser substitution rates in urban China and South Korea. Deviation in palm oil price volatility or REACH fragrance allergen expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
Intimate Wash Care Products Market
Beauty & Personal Care
UV Nail Gel Market
Beauty & Personal Care
Face Makeup Market
Beauty & Personal Care
Europe Hair Conditioner Market
Beauty & Personal Care
Malaysia Aromatherapy Products Market
Beauty & Personal Care
Personalized Beauty Devices Market
Beauty & Personal Care
Philippines Beauty & Personal Care Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Depilatories Market
Beauty & Personal Care
United Kingdom Cosmetics Products Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
Deodorant and Antiperspirants Market
Beauty & Personal Care
Beard Straightener Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Europe Cosmetics Market