
 Liquid Soap Market | 2026-2036
Liquid Soap Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Soap Market Intelligence
ISO 22716 certification is bifurcating the competitive landscape into contract manufacturers with verified good manufacturing practices and unqualified regional suppliers. Procter & Gamble leverages its global distribution infrastructure to sustain shelf presence across mass retail channels. Henkel AG & Co. KGaA anchors European private-label production through integrated surfactant compounding operations. Kao Corporation dominates Japanese institutional supply with concentrated refill-system technology.
Liquid soap denotes a pump-dispensed or pourable cleansing formulation comprising synthetic surfactants, humectants, preservatives, and water, manufactured through continuous saponification or cold-process blending at controlled pH. Its primary purpose is soil removal and microbial reduction from skin surfaces in both domestic and occupational hygiene protocols. Antibacterial and liquid hand wash segments lead volume due to healthcare procurement standards and post-pandemic institutional retention of elevated hand-hygiene protocols. Foam soap competes on per-use cost efficiency and reduced water consumption in commercial restrooms. Moisturizing formulations command margin premiums through additive differentiation with emollient complexes.
FDA monograph requirements for over-the-counter antiseptic hand washes govern active ingredient substantiation and labeling claims in the United States. EPA registration protocols for antimicrobial product efficacy further constrain formulation choices and testing expenditures. REACH compliance in Europe mandates full surfactant substance dossiers, elevating regulatory costs for import-dependent brands. Stakeholders must monitor evolving state-level ingredient disclosure laws and procurement shifts toward concentrated refill formats versus ready-to-use dispensers.
Market Dynamics
Healthcare procurement standards and EU Green Deal surfactant mandates are bifurcating the competitive landscape, forcing manufacturers to choose between premium certification investments and commodity positioning.
Growth Catalysts
- EU Green Deal biodegradability thresholds:REACH compliance mandates are accelerating R&D spending on plant-derived surfactant alternatives, creating first-mover advantages for reformulated product lines.
- Indian urban sanitation programs:Swachh Bharat Mission infrastructure rollout is institutionalizing hand-hygiene protocols in municipal facilities, schools, and transit hubs nationwide.
- Concentrated refill-system technology:Dilution-at-point-of-use formats reduce packaging waste and shipping volumes, appealing to commercial buyers with ESG procurement mandates.
Market Restraints
- Palm kernel oil price volatility:La Niña weather patterns and Indonesian export duty fluctuations destabilize primary fatty alcohol feedstock costs for surfactant producers.
- China surfactant intermediate concentration:Over half of global fatty alcohol ethoxylate capacity resides in Shandong and Jiangsu provinces, exposing supply chains to regional energy rationing and port congestion.
- Alcohol-based sanitizer substitution:Gel and spray formats retain preference in foodservice and pharmaceutical cleanroom environments where rapid evaporation is prioritized over residual emolliency.
Strategic Opportunities
- Rural India distribution gaps:Kirana store networks and direct-to-village logistics partnerships remain underdeveloped for branded liquid soap, favoring private-label penetration at price points below national brands.
- Sensor-activated dispenser convergence:IoT-enabled refill monitoring and touchless hardware integration create bundled service contracts for facility management providers.
- US state ingredient disclosure laws:California Cleaning Product Right to Know Act and similar statutes in New York and Washington are mandating full formulation transparency, rewarding early compliance with preferred vendor status in municipal tenders.
Industry Challenges
- ISO 22716 certification timelines:Good manufacturing practice audits for contract manufacturers require 12-18 month preparation cycles, delaying entry into pharmacy and hospital supply chains.
- Preservative efficacy testing capacity:USP antimicrobial effectiveness testing bottlenecks at third-party laboratories extend new product registration timelines by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Soap Market |
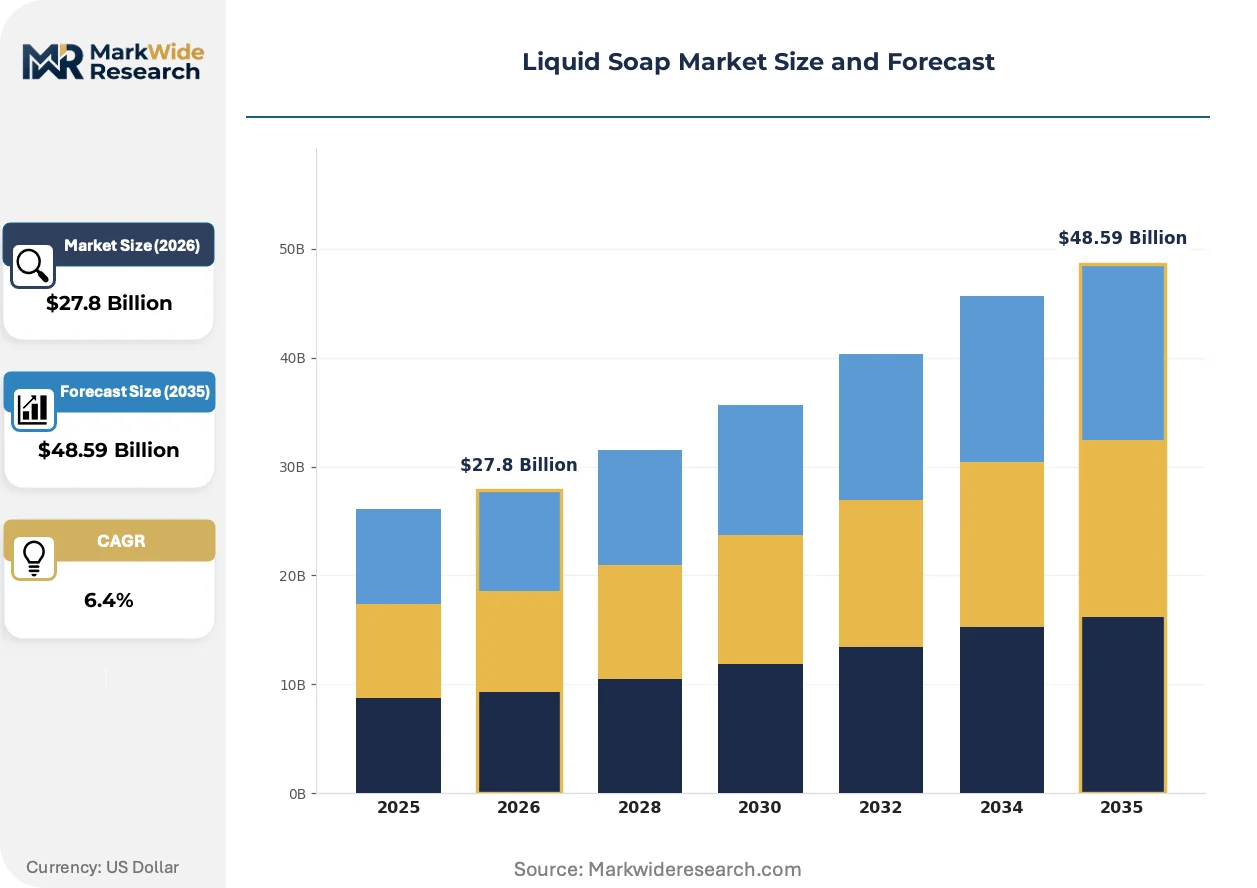
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $48.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
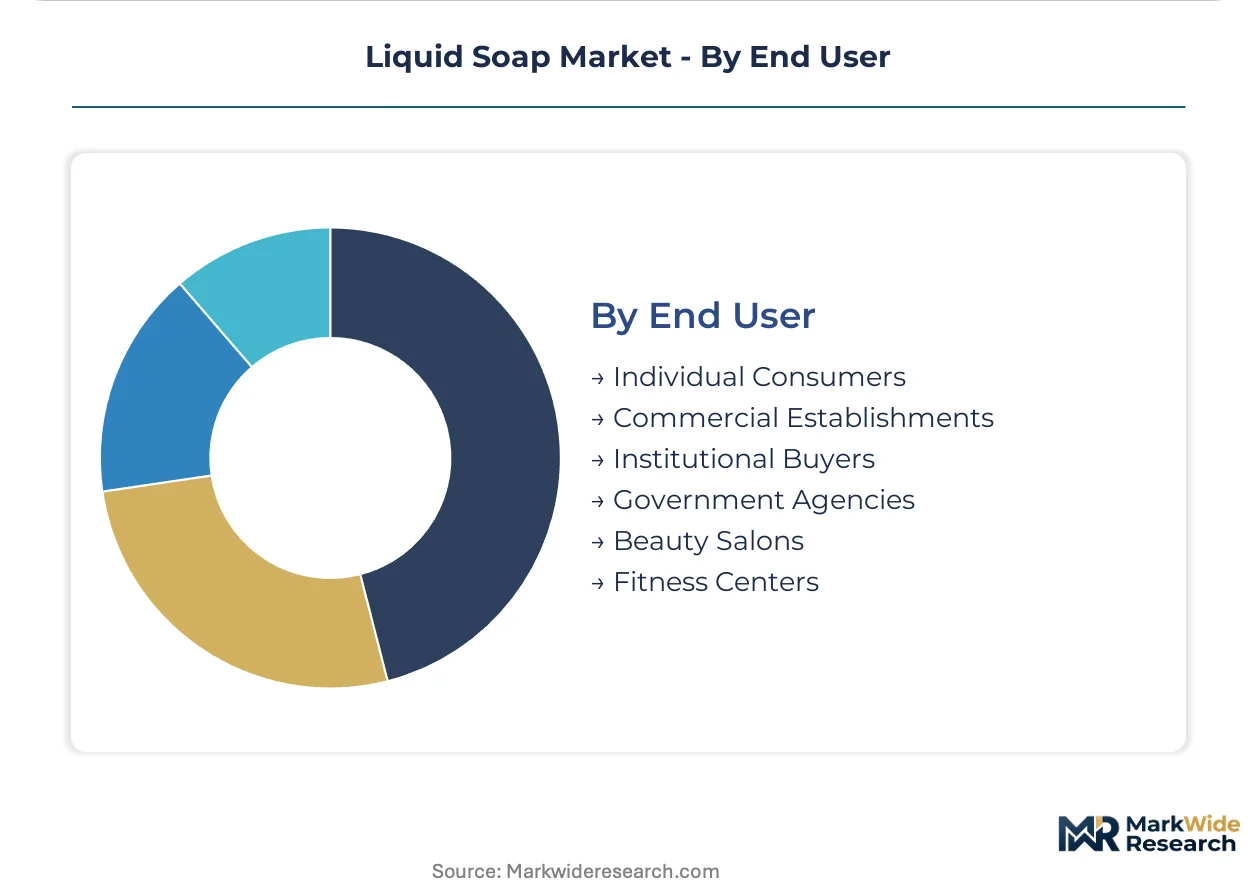
| Segmentation | Product Type: Antibacterial, Moisturizing, Fragrance-Free, Herbal, Liquid Hand Wash, Foam Soap Application: Personal Care, Hospitality, Healthcare Facilities, Food Processing, Education Institutions, Gyms Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Drugstores, Specialty Stores, Wholesale Suppliers, Direct Sales End User: Individual Consumers, Commercial Establishments, Institutional Buyers, Government Agencies, Beauty Salons, Fitness Centers |
| Companies Covered | Reckitt Benckiser Group plc, GOJO Industries Inc., Procter & Gamble, Lion Corporation, 3M Company, Unilever, Henkel AG & Co. KGaA, Kao Corporation, Colgate-Palmolive Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Soap Market Strategic Shifts & Innovations
Reformulation chemistry and dispensing hardware are converging to reduce per-use cost and environmental footprint while maintaining antimicrobial efficacy standards.
Waterless concentrated paste formulations are miniaturizing shipping volumes and shelf space requirements. Quick-service restaurants and airline caterers are piloting tablet-dissolve systems at 40% adoption velocity versus conventional ready-to-use products. This technology is miniaturizing the liquid soap category's logistics footprint and enabling direct-to-consumer subscription models previously uneconomical for bulky liquids.
REACH Annex XVII restrictions on microplastic-containing rinse-off cosmetics are compelling surfactant suppliers to validate biodegradability through OECD 301 testing protocols. German and French formulators are accelerating substitution of acrylate thickeners with natural gums and cellulose derivatives. The antibacterial hand wash segment faces the steepest reformulation burden, as many legacy viscosifiers fall under pending microplastic definitions.
Institutional buyers are consolidating vendor relationships around full-category hygiene suppliers. Hospital procurement departments in the United Kingdom and Netherlands are awarding three-year managed service contracts covering soap, sanitizer, paper, and dispensing hardware as integrated bundles. This behavior is displacing standalone liquid soap tenders and favoring manufacturers with in-house dispenser engineering capabilities and field service networks.
Liquid Soap Market Segmentation
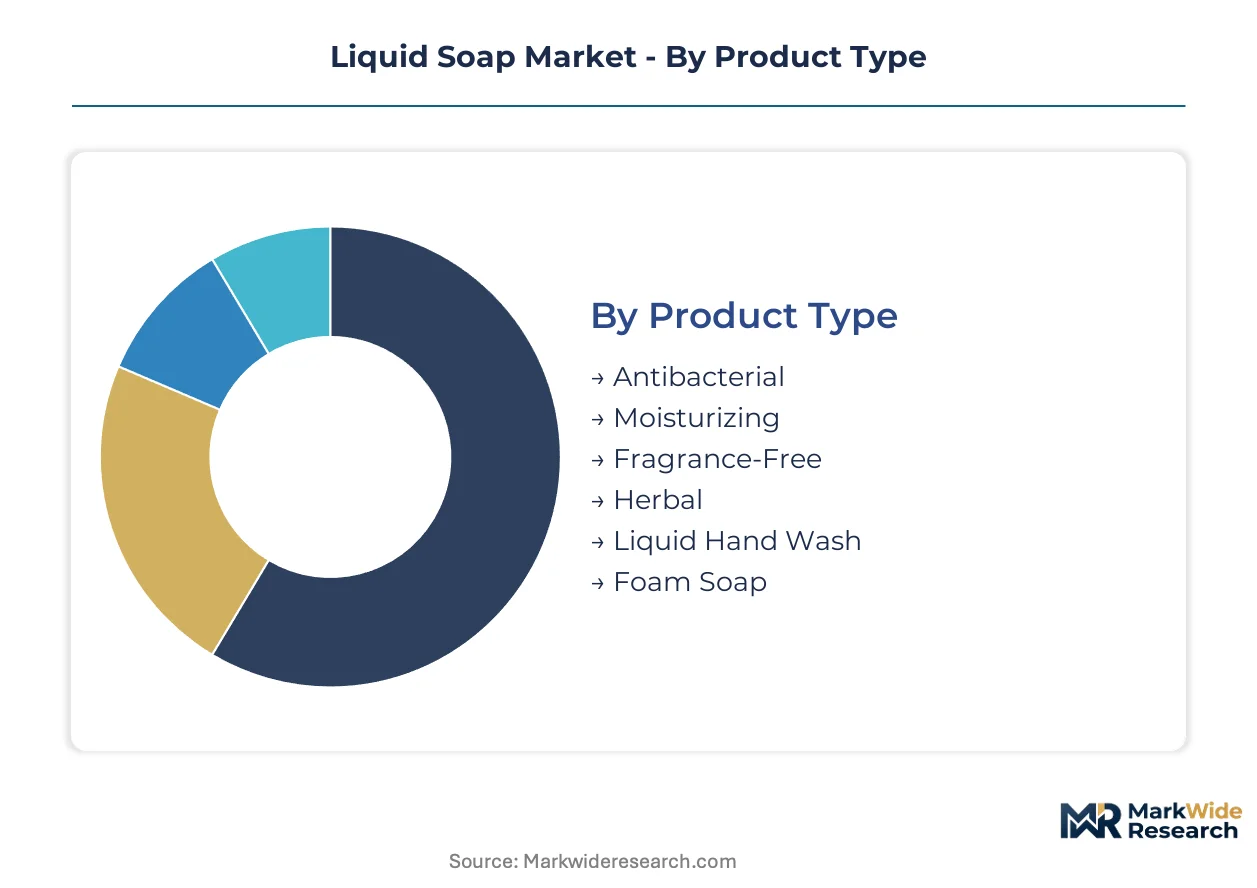
Liquid soap manufacturers configure product portfolios around margin concentration zones that shift with regulatory pressure and procurement consolidation. Category boundaries blur as healthcare-grade formulations penetrate hospitality channels and concentrated refill systems displace conventional SKUs.
Product Type:
Margin pools concentrate in antibacterial and moisturizing formulations where certification requirements create pricing power, while foam soap and herbal variants compete on cost efficiency and ingredient story differentiation.
- Antibacterial:Pump-dispensed formulations containing benzalkonium chloride or triclosan substitutes, manufactured under FDA monograph compliance for healthcare procurement. Demand concentrates in US hospital systems and Indian municipal sanitation programs where institutional tender specifications mandate verified microbial reduction claims. EPA registration and USP antimicrobial effectiveness testing create six-to-nine month entry barriers that protect incumbent margins.
- Moisturizing:Surfactant bases enriched with glycerin, shea butter, or ceramide complexes targeting occupational hand dermatitis prevention. European private-label manufacturers capture premium positioning through ECHA-compliant emollient sourcing and ISO 22716 certification. REACH Annex XVII microplastic restrictions are forcing reformulation of acrylate thickeners toward cellulose derivatives.
- Fragrance-Free:Hypoallergenic formulations for sensitive skin and foodservice environments where odor neutrality is mandated.
- Herbal:Plant-derived surfactant systems leveraging neem, tea tree, or aloe vera extracts for clean-label positioning in Indian and Southeast Asian markets.
- Liquid Hand Wash:Standard domestic formulations dominating volume through supermarket and hypermarket distribution.
- Foam Soap:Dilution-at-point-of-use systems reducing per-use volume by 40 percent and water consumption in commercial restrooms.
Antibacterial holds installed capacity. Foam soap is rotating up the share rankings.
Application:
Volume distribution tilts toward personal care and healthcare facilities where hand-hygiene protocol retention post-pandemic sustains above-baseline consumption rates.
- Personal Care:Domestic bathroom and kitchen sink applications representing baseline household consumption. Indian urban households drive volume expansion through Swachh Bharat Mission infrastructure rollout and private-label penetration at kirana store price points.
- Healthcare Facilities:Operating theaters, patient wards, and clinical laboratories requiring FDA-compliant antiseptic hand washes with documented efficacy against nosocomial pathogens. UK and Netherlands hospital procurement departments are consolidating three-year managed service contracts covering soap, sanitizer, and dispensing hardware as integrated bundles.
- Hospitality:Hotel guest rooms, restaurants, and conference facilities where brand image dictates premium dispenser aesthetics and signature fragrance profiles.
- Food Processing:USDA-inspected facilities requiring rapid-evaporation formats where alcohol-based sanitizers retain preference over residual emolliency.
- Education Institutions:K-12 and university campuses with high-frequency hand washing driving cost-sensitive bulk procurement.
- Gyms:Fitness centers with sensor-activated dispenser convergence and IoT-enabled refill monitoring creating bundled service contract opportunities.
Healthcare facilities anchor premium pricing. Personal care is climbing the fastest.
Distribution Channel:
Channel selection determines margin capture efficiency, with direct sales and wholesale suppliers offering volume scale while online retailers and specialty stores enable ingredient story differentiation.
- Supermarkets & Hypermarkets:Mass retail shelf space allocation governed by slotting fees and global distribution infrastructure scale. Procter & Gamble sustains presence through category captain relationships and promotional calendar coordination.
- Online Retailers:Direct-to-consumer subscription models for concentrated paste and tablet-dissolve formats previously uneconomical for bulky liquid shipping. Amazon and regional e-commerce platforms in India enable private-label bypass of traditional distributor markups.
- Drugstores:Pharmacy chains requiring ISO 22716 certification for antibacterial and moisturizing formulation placement.
- Specialty Stores:Clean beauty and natural product retailers emphasizing EWG-verified ingredient transparency.
- Wholesale Suppliers:Institutional procurement consolidation around full-category hygiene vendors with field service networks.
- Direct Sales:Manufacturer-to-facility contracts for sensor-activated dispenser hardware and managed refill logistics.
Wholesale suppliers control institutional volume. Online retailers are gaining share fastest.
End User:
Buyer type segmentation reveals divergent purchasing logic between price-sensitive individual consumers and specification-driven institutional procurement.
- Individual Consumers:Household purchasers selecting on fragrance preference, skin sensitivity, and price promotion timing. Indian urban migration patterns concentrate demand in apartment complexes with shared dispenser infrastructure.
- Commercial Establishments:Corporate offices, retail stores, and restaurants balancing per-use cost against employee and customer experience metrics.
- Institutional Buyers:Hospital procurement departments and municipal facility managers issuing multi-year tenders with ESG mandates for concentrated refill formats and biodegradable surfactant validation.
- Government Agencies:Swachh Bharat Mission and equivalent public health programs standardizing hand-hygiene protocols in schools, transit hubs, and administrative buildings.
- Beauty Salons:Service businesses requiring frequent hand washing with moisturizing properties to prevent occupational dermatitis.
- Fitness Centers:Gyms with high-touch equipment surfaces prioritizing antimicrobial claims and touchless dispenser technology.
Institutional buyers drive specification complexity. Individual consumers anchor volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional buyers concentrate in healthcare corridors and urban sanitation programs, while manufacturing clusters align with surfactant feedstock access and private-label export infrastructure.
United States
Hospital procurement departments in Texas and Florida sustain antibacterial formulation demand through FDA monograph compliance. EPA registration protocols constrain active ingredient selection for institutional tenders. Shandong and Jiangsu province suppliers feed fatty alcohol ethoxylate intermediates into Gulf Coast compounding facilities.
Germany
REACH Annex XVII microplastic restrictions accelerate reformulation of acrylate thickeners toward cellulose derivatives in Baden-Württemberg laboratories. EU Green Deal biodegradability thresholds elevate OECD 301 testing requirements for surfactant suppliers. Cologne-Düsseldorf corridor houses integrated private-label manufacturers with captive dispenser engineering divisions.
India
Swachh Bharat Mission infrastructure rollout institutionalizes hand-hygiene protocols in Maharashtra municipal schools and Delhi-NCR transit hubs. BIS certification requirements and DGFT export incentives scale private-label manufacturing in Gujarat and Tamil Nadu. Mumbai-Pune industrial belt concentrates surfactant compounding capacity for both domestic kirana store distribution and Middle East re-export.
Japan
Concentrated refill-system technology dominates Kanto region hospital and hospitality procurement through METI-supported resource efficiency standards. Kao Corporation anchors institutional supply relationships with dilution-at-point-of-use hardware integration. Osaka-Kobe manufacturing corridor specializes in sensor-activated dispenser convergence for facility management bundles.
United Kingdom
NHS procurement consolidation awards three-year managed service contracts covering soap, sanitizer, and dispensing hardware to full-category hygiene vendors. ISO 22716 certification requirements filter pharmacy chain supplier qualifications. Midlands manufacturing base supplies reformulated surfactant systems compliant with evolving microplastic definitions.
Liquid Soap Market Key Industry Players
Player mix skews toward multinational consumer goods conglomerates with integrated surfactant operations and specialized institutional hygiene providers with dispenser hardware capabilities. Tiered structure separates premium certification holders from commodity private-label suppliers. Strategic archetypes include full-category hygiene bundlers, concentrated refill-system specialists, and regional private-label exporters. Dominant competitive moves encompass ISO 22716 certification investments and sensor-activated dispenser convergence partnerships.
Among diversified consumer goods conglomerates, Procter & Gamble and Unilever occupy positions sustained by global distribution infrastructure and category captain relationships. Henkel AG & Co. KGaA exemplifies the European private-label integration archetype through captive surfactant compounding. Kao Corporation represents the institutional technology specialist tier with concentrated refill-system dominance. Reckitt Benckiser Group plc sits within the healthcare-grade formulation segment anchored by EPA-registered antibacterial portfolios.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| GOJO Industries Inc. |
| Procter & Gamble |
| Lion Corporation |
| 3M Company |
| Unilever |
| Henkel AG & Co. KGaA |
| Kao Corporation |
| Colgate-Palmolive Company |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with palm kernel oil price indexation lock in surfactant feedstock access for European and Indian manufacturers while capping margin volatility. These arrangements bind fatty alcohol suppliers to detergent-grade producers across 12-18 month horizons, embedding La Niña weather risk into contract renegotiation cycles.
Pricing Analysis
Cost-plus contracts with Malaysian palm kernel oil indexation dominate procurement between Indonesian suppliers and Indian private-label manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22716-certified antibacterial formulations from commodity hand wash and unbranded kirana store variants. Cost compression in standard-tier SKUs is intensifying because Shandong ethoxylate capacity expansions are feeding oversupply into Asian markets. Institutional buyers in NHS procurement frameworks exhibit lowest price sensitivity, while Indian rural kirana channels anchor volume at thin margins.
Supply Chain Analysis
Port congestion at Ningbo-Zhoushan and Singapore transshipment hubs elevates inbound logistics costs for fatty alcohol ethoxylate shipments bound for European compounding facilities. Manufacturing gravity centers on China, Indonesia, and India, with Shandong and Jiangsu provinces hosting over half of global ethoxylate capacity. Surfactant production rests on palm kernel oil, coconut fatty acids, and petroleum-derived linear alkylbenzene feedstocks. Single-source vulnerability concentrates in Indonesian palm kernel oil exports subject to export duty volatility. Distribution runs through integrated private-label exporters in Gujarat and Tamil Nadu serving Middle East re-export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes liquid soap as post-pandemic institutional hygiene protocol retention sustains above-baseline consumption in healthcare and municipal facilities. Indian Swachh Bharat Mission infrastructure rollout accelerates penetration into previously unserved rural kirana networks.
For Market Incumbents: Shield pharmacy and hospital supply chain positions by accelerating ISO 22716 certification timelines ahead of 12-18 month audit backlogs. Prioritize captive surfactant compounding in Gujarat and Tamil Nadu to offset palm kernel oil price volatility through backward integration into fatty alcohol intermediates. Sensor-activated dispenser convergence with IoT-enabled refill monitoring locks in three-year managed service contracts against full-category hygiene bundlers. For New Entrants and Emerging Players: BIS certification fast-track through Tamil Nadu testing laboratories opens private-label export corridors to Middle East markets underserved by multinational brand infrastructure. Rural India distribution gaps at kirana store price points below national brands represent the most penetrable white-space, with direct-to-village logistics partnerships bypassing traditional distributor markups. Tablet-dissolve concentrated formats enable subscription economics previously uneconomical for bulky liquid shipping. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors integrated surfactant-dispenser manufacturers over standalone formulation specialists. Long-term viability over the next decade hinges on REACH Annex XVII microplastic compliance and EU Green Deal biodegradability threshold adaptation. Acquisition target archetype: European private-label manufacturers with captive cellulose derivative thickener R&D and Cologne-Düsseldorf corridor dispenser engineering capabilities. Signal to watch: NHS procurement consolidation velocity toward full-category hygiene vendors with field service networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Production | Captive supply of palm kernel oil derivatives insulates margins from Indonesian export duty volatility. |
| ISO 22716 Certification Fast-Track | Verified good manufacturing practices unlock pharmacy chain placement and hospital tender eligibility. |
| Sensor-Activated Dispenser Convergence | IoT-enabled refill monitoring creates bundled service contracts for UK and Netherlands facility management providers. |
| Concentrated Refill-System Technology | Dilution-at-point-of-use formats reduce packaging waste and shipping volumes for ESG-mandated institutional procurement. |
| Rural India Distribution Partnership | Kirana store network penetration at price points below national brands captures Swachh Bharat Mission volume. |
Research Approach
Cross-validation between procurement director interviews and customs trade data anchors the qualitative findings on supply chain configuration. Primary fieldwork engaged plant managers at surfactant compounding facilities, category buyers at Indian supermarket chains, NHS procurement committee members, and technical R&D directors at German formulation laboratories. Secondary validation drew from DGFT export incentive disclosures, BIS certification registries, REACH Annex XVII substance dossiers, and SEC 10-K filings of listed consumer goods conglomerates. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates.
Sensitivity analysis around palm kernel oil price trajectories and Shandong energy rationing probabilities stress-tested base-case projections across the analysis window. Segmentation dimensions modeled include product type tier, application vertical, distribution channel structure, and end-user procurement sophistication. CAGRs were derived from logistic diffusion curves fitted to institutional adoption patterns and household penetration saturation rates. Industry-specific forecast inputs incorporated Swachh Bharat Mission infrastructure rollout velocity and NHS managed service contract award timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and Indian urban sanitation program continuity; material deviation in regulatory stringency or public health funding would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Bath Oil Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Hair Color Spray Market
Beauty & Personal Care
Australia Beauty and Personal Care Products Market
Beauty & Personal Care
Herbal Shampoo Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Bio-Based Cosmetics Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
Oil Control Lotion Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Color Protection Shampoo Market