
 Color Cosmetics OEM and ODM Market | 2026-2036
Color Cosmetics OEM and ODM Market Size, Share, and Industry Trends Forecast 2026-2036
Color Cosmetics OEM and ODM Market Insights
Digital formulation tools and AI-driven shade-matching technology is fragmenting traditional R&D pipelines across the color cosmetics contract manufacturing sector. COSMAX leverages proprietary skin-analysis platforms to anchor its position in customized foundation development. Intercos sustains competitive intensity through integrated color science laboratories in Italy and the United States. Kolmar Korea dominates water-based lipstick innovation, extending its technical lead across Asian beauty supply chains.
Color cosmetics OEM and ODM services encompass third-party design, formulation, and production of decorative beauty products, with specifications spanning pigment load concentrations of 15-40%, ISO 22716 GMP compliance, and shelf-life stability testing under accelerated aging protocols at 40°C and 75% relative humidity. These services enable brand owners to commercialize products without captive manufacturing infrastructure. Foundation and lipstick categories command the deepest margin pools due to complex emulsion chemistry and premium positioning, while eyeliner and mascara segments compete on applicator innovation and wear-resistance claims. Online retail and specialty stores represent the fastest-growing distribution channels, diverging from department store concentration as direct-to-consumer beauty brands proliferate.
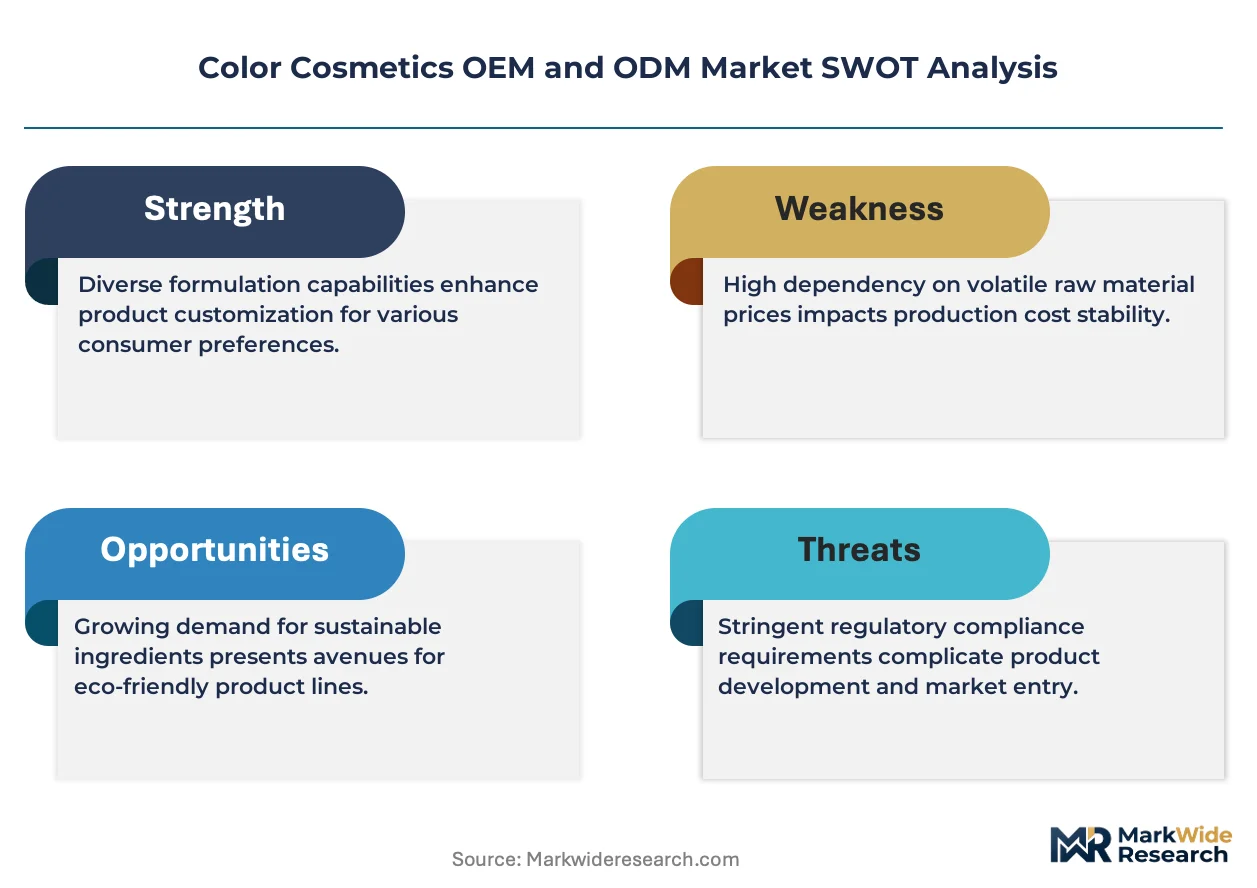
REACH in Europe, MoCRA in the United States, and China's GB standards collectively tighten raw material traceability and safety substantiation requirements for color additives and preservatives. These frameworks elevate compliance costs for smaller contract manufacturers while creating accreditation barriers that favor scaled OEM and ODM operators with dedicated regulatory affairs teams. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as PFAS-free reformulation mandates threaten existing long-wear product portfolios and demand accelerated ingredient substitution timelines.
Market Dynamics
AI-driven shade-matching platforms are fragmenting traditional R&D pipelines by compressing formulation cycles from months to weeks, forcing contract manufacturers to rebuild technical capabilities around digital-first workflows or surrender margin to algorithm-native competitors.
Growth Catalysts
- MoCRA compliance mandates:FDA's expanded facility registration and adverse event reporting requirements in the United States are accelerating brand migration toward scaled OEM partners with dedicated regulatory affairs infrastructure.
- K-beauty supply chain concentration:South Korean contract manufacturers dominate water-based lipstick and cushion foundation innovation, anchoring global demand for technical color cosmetics production.
- Direct-to-consumer channel expansion:Online retail and specialty store distribution is displacing department store concentration, creating volume pull for flexible, small-batch OEM operators serving indie beauty brands.
Market Restraints
- Pigment cost volatility:Titanium dioxide and iron oxide supply disruptions from Chinese mining consolidation are compressing margin pools in foundation and lipstick categories.
- PFAS-free reformulation mandates:EPA and state-level restrictions on per- and polyfluoroalkyl substances threaten existing long-wear product portfolios, demanding accelerated ingredient substitution timelines.
- ISO 22716 GMP certification concentration:Accreditation barriers favor scaled operators with dedicated quality systems, excluding smaller contract manufacturers from premium brand procurement pools.
Strategic Opportunities
- Men's color cosmetics underpenetration:South Korea and Japan exhibit nascent demand for male-targeted BB creams and concealers, creating first-mover positioning for specialized OEM formulation.
- EU Green Deal chemical substitution incentives:REACH-aligned bio-based pigment development programs offer regulatory tailwinds for manufacturers investing in natural-derived colorant R&D.
- AI-physical convergence:Integration of skin-analysis hardware with cloud-based formulation databases enables mass-customized foundation production at unit economics competitive with standard SKUs.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation science programs in the United States and Europe are producing insufficient graduates to staff expanded R&D teams at mid-scale OEMs.
- Accelerated aging protocol capex:Shelf-life stability testing infrastructure at 40°C and 75% relative humidity requires climate-controlled facility investments that strain sub-$50M revenue manufacturers.
- Cross-border IP enforcement complexity:Shade-matching algorithm patents and proprietary pigment dispersions face weak protection in Chinese manufacturing jurisdictions, complicating technology licensing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Color Cosmetics OEM and ODM Market |
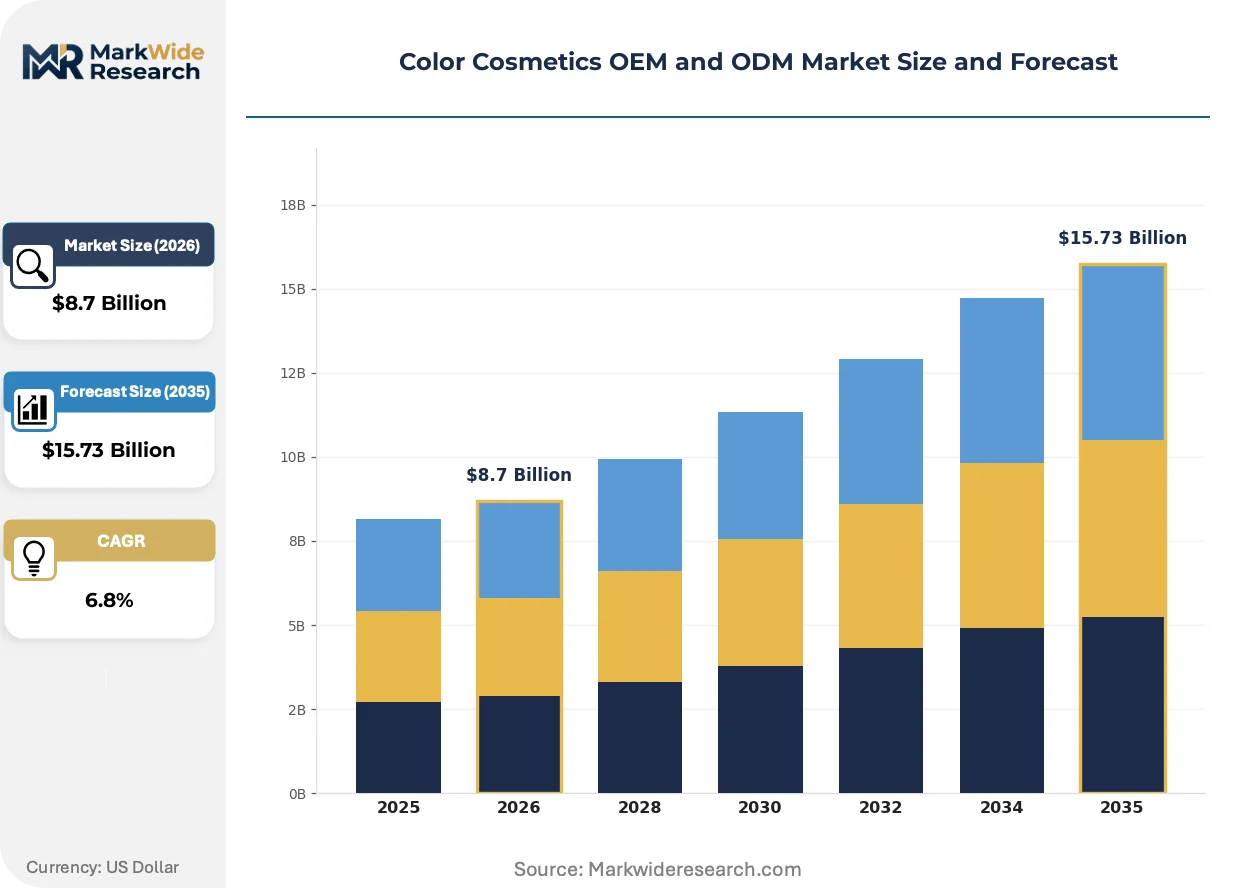
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foundation, Lipstick, Eyeliner, Mascara Consumer Demographic: Teenagers, Adults, Seniors, Professionals Application: Personal Care, Fashion Events, Media, Everyday Use Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets |
| Companies Covered | KDC/One, Intercos, COSMAX, Kolmar Korea, Nihon Kolmar, Cosmo Beauty, Cosmecca Korea, Mana Products, Schwan Cosmetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Color Cosmetics OEM and ODM Market Trends and Innovations
Digital tools are compressing the boundary between physical formulation and virtual prototyping, enabling contract manufacturers to serve fragmented brand demand with precision-matched color systems. Three forces are actively restructuring competitive positioning.
Cloud-based spectrophotometry paired with machine learning color prediction is virtualizing the traditional bench chemist's role in shade development. Indie beauty brands with limited R&D budgets are adopting these platforms fastest, typically reducing iteration cycles from twelve weeks to ten days. This compression is virtualizing competitive advantage away from legacy laboratory infrastructure toward algorithmic accuracy and database scale.
REACH's expanded substance restrictions and the EU's per- and polyfluoroalkyl substance bans are forcing reformulation of long-wear lipsticks and waterproof mascaras across European brand portfolios. Manufacturers must substantiate safety dossiers for all color additives above 0.1% concentration, elevating documentation costs. Premium positioning segments are responding fastest, using regulatory compliance as a differentiation signal in clean beauty marketing.
Beauty brands are unbundling after-sales shade consultation from product purchase, shifting toward subscription-based color-matching services with replenishment fulfillment. Direct-to-consumer channels in the United States are displacing traditional counter-based trial, demanding OEM partners capable of single-unit customization at mass-production economics. This reconfiguration is most visible in foundation categories, where algorithm-matched skin tone precision now drives repurchase loyalty more than brand heritage.
Color Cosmetics OEM and ODM Market Segmentation
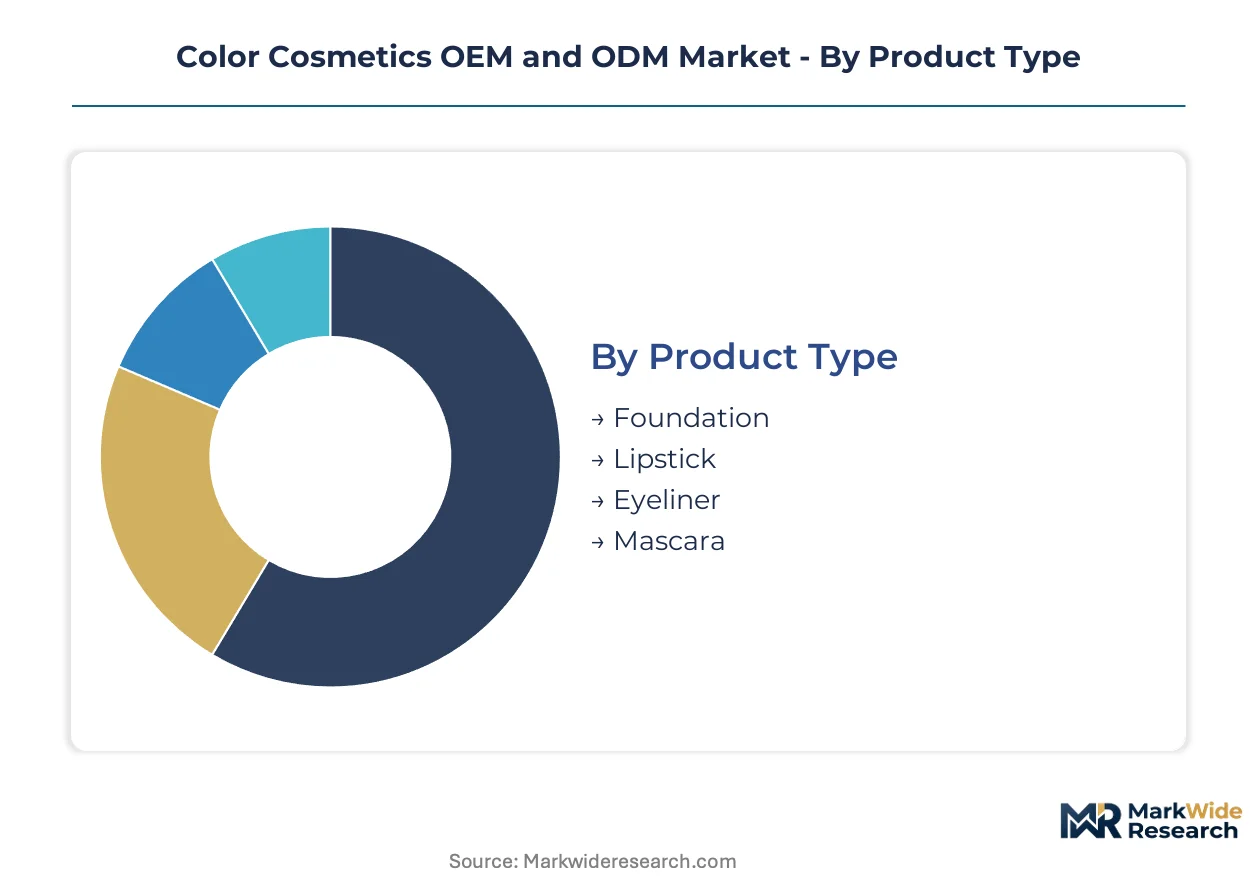
Color cosmetics OEM and ODM services fragment across formulation complexity, end-user requirements, and channel logistics. Each dimension reshapes technical specifications, batch economics, and regulatory documentation burdens for contract manufacturers.
Product Type:
Cost tier determines margin capture and R&D intensity across decorative beauty categories.
- Foundation:Complex emulsion chemistry with 15-40% pigment load demands ISO 22716 GMP climate-controlled facilities. Premium positioning in South Korea and the United States concentrates volume with manufacturers offering skin-analysis-integrated shade matching.
- Lipstick:Water-based innovation from South Korean contract manufacturers anchors technical leadership. MoCRA-compliant safety substantiation for color additives above 0.1% concentration elevates documentation costs and favors scaled OEM operators.
- Eyeliner:Precision applicator engineering competes on wear-resistance claims without PFAS-derived long-wear chemistry.
- Mascara:Viscosity control and brush-fiber integration dominate formulation differentiation.
Foundation commands the established base. The steepest expansion runs through water-based lipstick formats.
Consumer Demographic:
Application frequency and price sensitivity vary sharply across life-stage and professional requirements.
- Teenagers:Entry-point color experimentation drives demand for small-batch, trend-responsive production with compressed 4-6 week formulation cycles.
- Adults:Volume concentration in working-age consumers spans everyday office-appropriate neutrals to occasion-driven statement products.
- Seniors:Hydration-focused formulations with skincare-actives integration capture underpenetrated demand in Japan and Western Europe.
- Professionals:Broadcast and photography-grade products require high-definition finish specifications with zero flashback under LED lighting conditions.
Adults retain volume dominance. Professionals are climbing the fastest as content creation economies expand.
Application:
Performance specifications diverge between daily utility and specialized environmental exposure.
- Personal Care:Standard wear-time claims with moderate water resistance satisfy routine consumer expectations.
- Fashion Events:Runway and editorial applications demand 12-16 hour adhesion under heat and humidity stress.
- Media:Film and television production requires silicone-free, non-reflective finishes compatible with 4K camera capture.
- Everyday Use:Mass-market positioning competes on price-per-gram with simplified regulatory documentation.
Everyday use anchors volume scale. Media applications are gaining share fastest as streaming content production multiplies.
Distribution Channel:
Channel logistics reshape batch size economics and packaging customization requirements.
- Online Retail:Direct-to-consumer fulfillment demands single-unit customization at mass-production unit economics. AI-driven shade-matching platforms enable subscription-based replenishment models.
- Specialty Stores:Sephora and Ulta Beauty procurement pools require ISO 22716 certification and dedicated quality systems that exclude smaller contract manufacturers.
- Department Stores:Counter-based trial is displacing toward experiential service models with lower inventory depth.
- Supermarkets:Mass-market price points compress margin pools and favor high-volume, low-SKU-count production runs.
Specialty stores command the established premium base. Online retail shows the steepest expansion trajectory as indie brand proliferation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Direct-to-consumer beauty brands in the United States and South Korea are pulling contract manufacturing volume toward specialized OEM partners with regulatory compliance infrastructure and digital formulation capabilities.
United States
Indie beauty proliferation through Sephora and Ulta Beauty procurement pools demands ISO 22716 GMP certification from contract manufacturers. MoCRA mandates from FDA elevate adverse event reporting and facility registration burdens. New York and Los Angeles anchor formulation development clusters where AI-driven shade-matching platforms compress R&D cycles.
South Korea
K-beauty export momentum concentrates water-based lipstick and cushion foundation production with technical specialists. MFDS cosmetic safety standards enforce rigorous documentation for color additives above threshold concentrations. Seoul Capital Area contract manufacturers dominate global supply chains for innovative texture formats.
Italy
Premium positioning in color science leverages integrated laboratory infrastructure for luxury brand partnerships. REACH substance restrictions from ECHA drive reformulation of long-wear products away from PFAS chemistry. Milan and Lombardy host specialized pigment dispersion facilities serving European heritage beauty houses.
China
Domestic beauty brand expansion creates volume pull for flexible small-batch OEM operators serving tier-one cities. NMPA cosmetic registration requirements and GB standards tighten raw material traceability protocols. Yangtze River Delta manufacturing clusters in Shanghai and Jiangsu Province concentrate technical color cosmetics capacity.
France
Clean beauty positioning aligns with EU Green Deal chemical substitution incentives for bio-based pigment development. ANSM enforces stringent safety substantiation for preservatives and colorants in decorative products. Paris and Île-de-France anchor regulatory affairs expertise for brands navigating REACH complexity.
Color Cosmetics OEM and ODM Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Consolidation favors scaled operators with dedicated regulatory affairs teams and climate-controlled GMP facilities. Three archetypes dominate: multinational full-service platforms, regional technical specialists, and niche formulation boutiques. Competitive intensity manifests through strategic partnerships with direct-to-consumer brands and geographic expansion into underpenetrated male cosmetics segments.
Among Asia-Pacific-based manufacturers, COSMAX, Kolmar Korea, and Intercos exemplify distinct competitive positioning. COSMAX occupies a position centered on proprietary digital skin-analysis platforms. Kolmar Korea anchors water-based lipstick innovation capacity. Intercos represents integrated color science laboratory infrastructure spanning European and North American markets.
| Leading Market Players |
|---|
| KDC/One |
| Intercos |
| COSMAX |
| Kolmar Korea |
| Nihon Kolmar |
| Cosmo Beauty |
| Cosmecca Korea |
| Mana Products |
| Schwan Cosmetics |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Yangtze River Delta freight corridors carry titanium dioxide and iron oxide shipments from Chinese mining consolidation zones to South Korean contract manufacturers, concentrating input cost volatility in foundation and lipstick production while enabling three-tier pricing stratification across premium ISO 22716-certified facilities, mid-tier flexible batch operators, and economy-scale supermarket suppliers.
Pricing Analysis
Cost-plus contracts with iron oxide and titanium dioxide indexation dominate procurement between raw material suppliers and contract manufacturers. Price differentiation hinges on ISO 22716 GMP certification tier and customization depth for AI-integrated shade-matching services. Pricing pressure intensifies in mass-market foundation categories as Chinese pigment supply disruptions compress margin pools. Indie beauty brands exhibit highest price sensitivity, while luxury heritage houses absorb premium positioning costs.
Supply Chain Analysis
Tariff exposure between China and the United States threatens titanium dioxide feedstock flows for foundation pigment loads. Supply concentrates in China, South Korea, and Italy, with Chinese mining consolidation controlling iron oxide extraction. Raw material dependencies center on titanium dioxide, iron oxide, and bio-based pigment alternatives under EU Green Deal substitution programs. Distribution runs through direct-to-consumer online channels and Sephora-Ulta specialty store procurement pools, bypassing declining department store inventory depth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist talent scarcity constrains mid-scale OEM expansion, with United States and European universities producing insufficient graduates to staff AI-integrated R&D teams and climate-controlled stability testing facilities.
For Market Incumbents: Build regulatory affairs moats through dedicated MoCRA compliance infrastructure and REACH-aligned bio-based pigment R&D programs. COSMAX and Kolmar Korea anchor competitive positioning through proprietary digital platforms; smaller operators must consolidate or surrender margin to algorithm-native competitors. Capacity additions in Seoul Capital Area and Milan-Lombardy clusters reinforce technical leadership against emerging flexible batch specialists. For New Entrants and Emerging Players: Build out men's color cosmetics formulation capabilities in South Korea and Japan, where male-targeted BB cream demand remains underpenetrated. White-space concentration runs through subscription-based shade-matching services with single-unit customization economics. Direct-to-consumer brand partnerships offer the most penetrable go-to-market channel, bypassing ISO 22716 certification barriers that exclude smaller manufacturers from Sephora and Ulta procurement pools. For Investors and Strategic Acquirers: Regional technical specialists with integrated color science laboratories and established MFDS or FDA facility registrations represent the priority acquisition archetype. Long-term viability across the analysis window depends on digital-physical convergence capabilities and PFAS-free reformulation pipelines. The signal to watch is accelerated state-level EPA restrictions on per- and polyfluoroalkyl substances forcing portfolio-wide ingredient substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Shade-Matching Platform Integration | COSMAX's proprietary skin-analysis systems compress foundation R&D cycles from months to weeks. |
| MoCRA Compliance Infrastructure Investment | FDA facility registration and adverse event reporting capabilities anchor brand migration toward scaled OEM partners. |
| Bio-Based Pigment R&D Program | EU Green Deal chemical substitution incentives reward REACH-aligned natural colorant development in French and Italian laboratories. |
| Men's Color Cosmetics Formulation Expansion | South Korean and Japanese male-targeted BB cream demand creates first-mover positioning for specialized contract manufacturers. |
| Direct-to-Consumer Channel Partnership | Single-unit customization at mass-production economics enables subscription-based replenishment models displacing department store counters. |
Research Methodology
The analysis maps foundation, lipstick, eyeliner, and mascara OEM/ODM sub-sectors, each validated through formulation chemists, regulatory affairs directors, brand procurement managers, and specialty store category buyers. Primary interview intelligence combined with FDA MoCRA facility registration databases, MFDS cosmetic safety filings, ECHA REACH substance restriction updates, and EU Green Deal program documentation. Secondary validation drew from customs pigment trade flows, ISO 22716 certification registries, and SEC filings of listed contract manufacturers. Bottom-up volume modeling and top-down value triangulation anchored market size estimation.
Assumptions held fixed include MoCRA enforcement intensity, REACH substance restriction timelines, and PFAS regulatory phase-out schedules across EPA and state jurisdictions. Segmentation dimensions modeled encompass product type complexity, consumer demographic life-stage, application performance specifications, and distribution channel logistics. CAGRs derived from weighted average growth across premium and mass-market tier demand trajectories. Forecast inputs incorporated AI-physical convergence adoption curves and K-beauty export momentum indices.
Stress conditions across titanium dioxide supply disruption severity, cosmetic chemist graduate pipeline constraints, and PFAS-free reformulation cost pass-through were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and brand outsourcing propensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Nail Polish Market
Cosmetics & Skincare
Natural Baby Skin Care Products Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
Lip Scrub Market
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Canada Cosmetic Products Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
Setting Spray Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
North America Face Compact Market
Cosmetics & Skincare
J-Beauty Products Market
Cosmetics & Skincare
Lip Oil Market