
 Myanmar Skin Care Products Market | 2026-2036
Myanmar Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Myanmar Skin Care Products Market Insights
Premium-grade formulations with enhanced active ingredient concentrations is redrawing competitive boundaries in Myanmar's skin care sector. Unilever leverages its extensive rural distribution network to sustain mass-market penetration across provincial townships. L'Oréal anchors its position through specialized dermatological testing protocols adapted for tropical humidity conditions. Shwe Pyi Nann competes as the dominant local manufacturer, occupying the traditional thanaka-integrated product niche that foreign brands cannot replicate.
Skin care products encompass topical formulations designed to cleanse, protect, and enhance epidermal condition through emulsions containing humectants, occlusives, and active compounds such as niacinamide or retinoids, manufactured via cold-process or hot-process emulsification with pH stabilization between 4.5 and 6.5. Moisturizers and sunscreens lead volume as structural staples, while natural ingredient variants record the fastest trajectory as consumer wariness toward synthetic preservatives intensifies. Professional end users command disproportionate margin pools through bulk procurement for salon-grade treatments, whereas online distribution channels are displacing traditional pharmacy reliance among urban teenagers seeking K-beauty influenced routines.
Myanmar's Food and Drug Administration enforces cosmetic safety standards that mandate ingredient labeling and restrict mercury-based skin lightening compounds, compelling reformulation investments from multinational suppliers. The Ministry of Commerce's import licensing requirements for finished cosmetics create regulatory friction that benefits locally manufactured alternatives. Stakeholders must monitor enforcement consistency at port-of-entry inspection points and assess whether domestic production incentives will alter the current import-dependent supply structure.
Market Dynamics
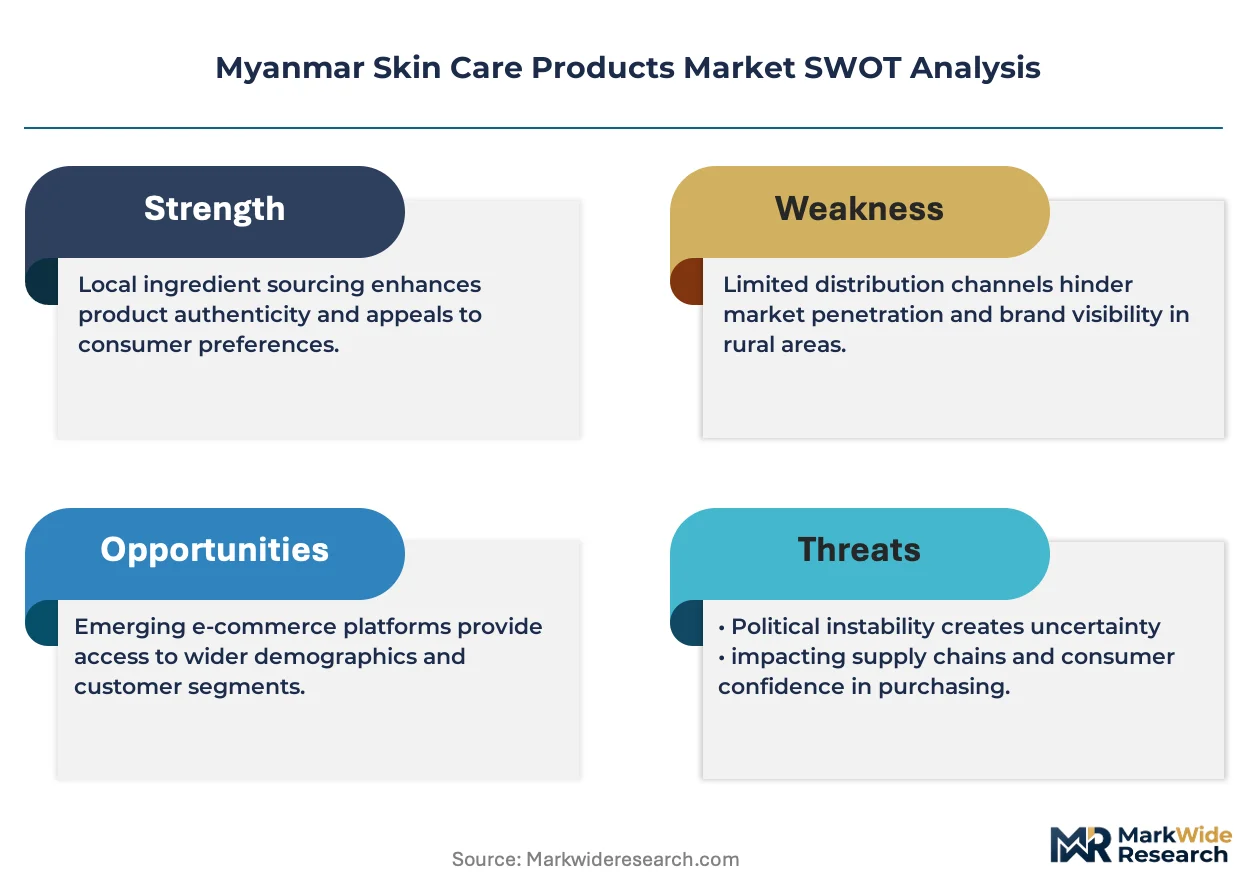
The Myanmar Food and Drug Administration's tightened cosmetic ingredient disclosure rules are forcing reformulation investments across import-dependent supply chains, compressing margins for multinational suppliers while creating regulatory shelter for domestic thanaka-integrated manufacturers.
Growth Catalysts
- Wedding Economy Expansion:Professional salon channels serving pre-wedding preparation segments command disproportionate margin pools through bulk procurement of facial treatment protocols. Urban millennials in Yangon and Mandalay drive premium-tier facial care adoption for ceremonial occasions.
- Thanaka Heritage Integration:Traditional botanical formulations incorporating thanaka bark extract occupy a defensible product niche that foreign competitors cannot replicate without cultural authenticity. Shwe Pyi Nann anchors domestic manufacturing capacity in this segment.
- Tropical Humidity Adaptation:Specialized dermatological testing protocols for high-humidity conditions enable product differentiation in sunscreen and moisturizer categories. L'Oréal leverages this technical barrier to sustain premium positioning.
Market Restraints
- Import Licensing Friction:The Ministry of Commerce's finished cosmetics import licensing requirements create port-of-entry bottlenecks that delay product launches and inflate working capital requirements for foreign suppliers.
- Mercury Compound Restrictions:FDA prohibitions on mercury-based skin lightening compounds force reformulation of legacy whitening products, stranding existing inventory and requiring R&D redeployment.
- Rural Distribution Cost Structure:Unilever's extensive provincial township network operates on thin margins due to fragmented retail density and high last-mile logistics costs relative to urban corridors.
Strategic Opportunities
- K-Beauty Digital Channel Penetration:Online distribution platforms are displacing traditional pharmacy reliance among urban teenagers seeking Korean-influenced skincare routines, opening direct-to-consumer pathways.
- Natural Ingredient Certification Tailwind:Consumer wariness toward synthetic preservatives intensifies demand for clean-label formulations, rewarding domestic suppliers with access to indigenous botanical supply chains.
- Professional Salon Vertical Integration:Bulk procurement relationships with wedding and festival preparation segments enable captive demand capture and recurring revenue streams for treatment-grade product lines.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Qualified cosmetic chemists capable of pH stabilization between 4.5 and 6.5 in tropical manufacturing conditions command premium compensation, constraining domestic production scale-up.
- Cold-Process Emulsification Capex:Hot-process and cold-process emulsification equipment for active compound preservation requires imported machinery subject to foreign exchange volatility and extended procurement timelines.
- Ingredient Disclosure Compliance Complexity:FDA-mandated labeling requirements for humectants, occlusives, and retinoid concentrations demand specialized regulatory affairs capabilities that smaller domestic manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myanmar Skin Care Products Market |
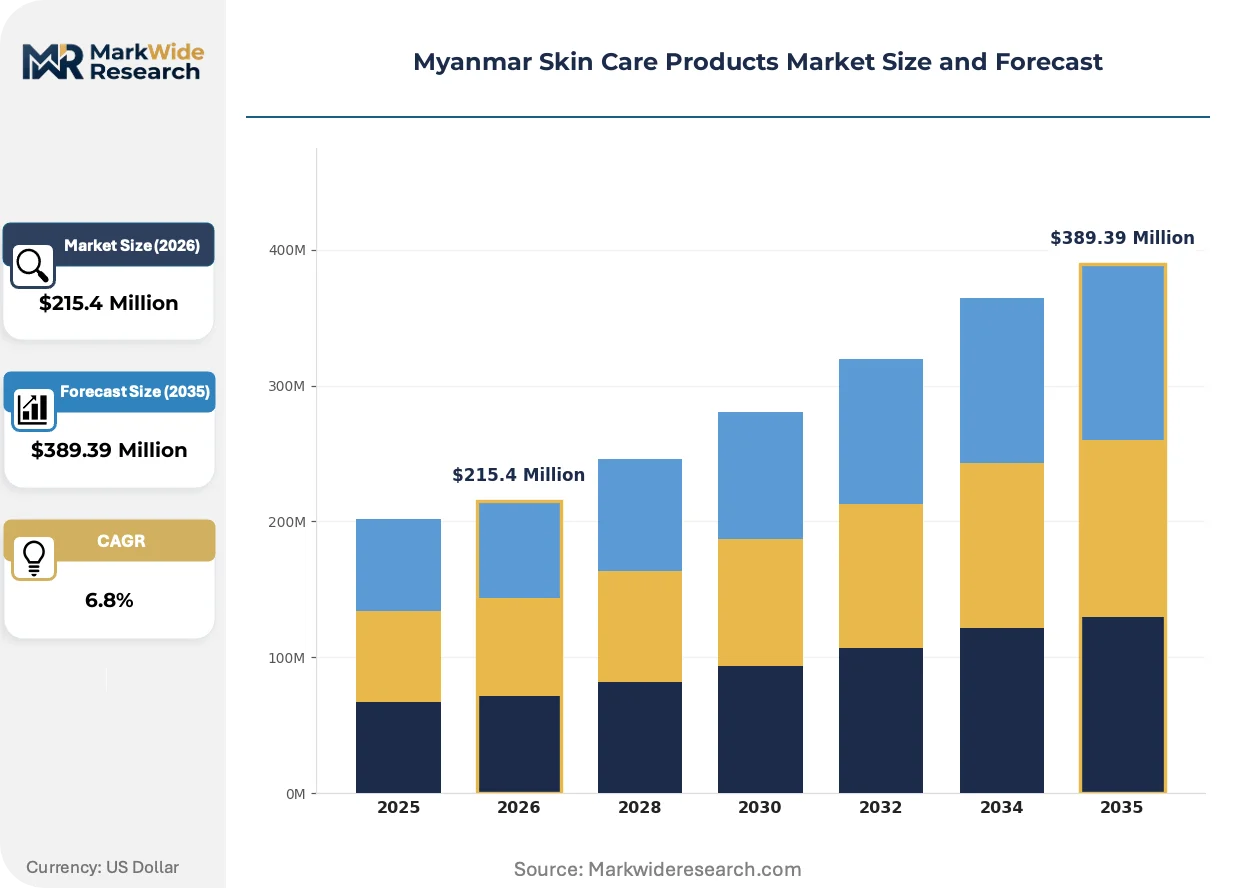
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Exfoliators, Sunscreens End User: Women, Men, Teenagers, Professionals Distribution Channel: Online, Supermarkets, Pharmacies, Beauty Salons Ingredient Type: Natural, Organic, Chemical, Synthetic |
| Companies Covered | Unilever, L’Oréal, Procter & Gamble, Beiersdorf, Shiseido, Kao Corporation, Estee Lauder, Revlon, Shwe Pyi Nann, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myanmar Skin Care Products Market Trends and Innovations
Digital channel proliferation and regulatory tightening are simultaneously fragmenting traditional distribution hierarchies while elevating technical barriers to market entry, reshaping how formulations reach end users across urban and rural divides.
Cold-process emulsification technology is decomposing the traditional hot-process manufacturing hierarchy by preserving heat-sensitive active compounds like niacinamide and retinoids at lower temperatures. Premium-tier manufacturers serving Yangon's professional salon channel are adopting these systems to claim enhanced efficacy positioning. This technical shift is compressing shelf-life advantages historically held by mass-market competitors relying on synthetic preservative stabilization.
Myanmar's Food and Drug Administration has implemented mandatory ingredient labeling requirements that expose previously opaque formulation compositions to competitive benchmarking. Multinational suppliers face accelerated disclosure timelines that compress proprietary advantage windows for active compound combinations. Domestic thanaka-integrated manufacturers benefit from simplified botanical ingredient lists that satisfy transparency demands without revealing chemically complex competitive secrets.
Urban teenagers seeking Korean-influenced skincare routines are abandoning pharmacy-dependent procurement in favor of cross-border e-commerce platforms and social commerce channels. This behavioral pivot fragments traditional wholesale-distributor-retail hierarchies that historically controlled product access outside Yangon and Mandalay. Professional salon operators now face margin pressure as clients source equivalent treatment-grade formulations through unlicensed digital intermediaries.
Myanmar Skin Care Products Market Segmentation
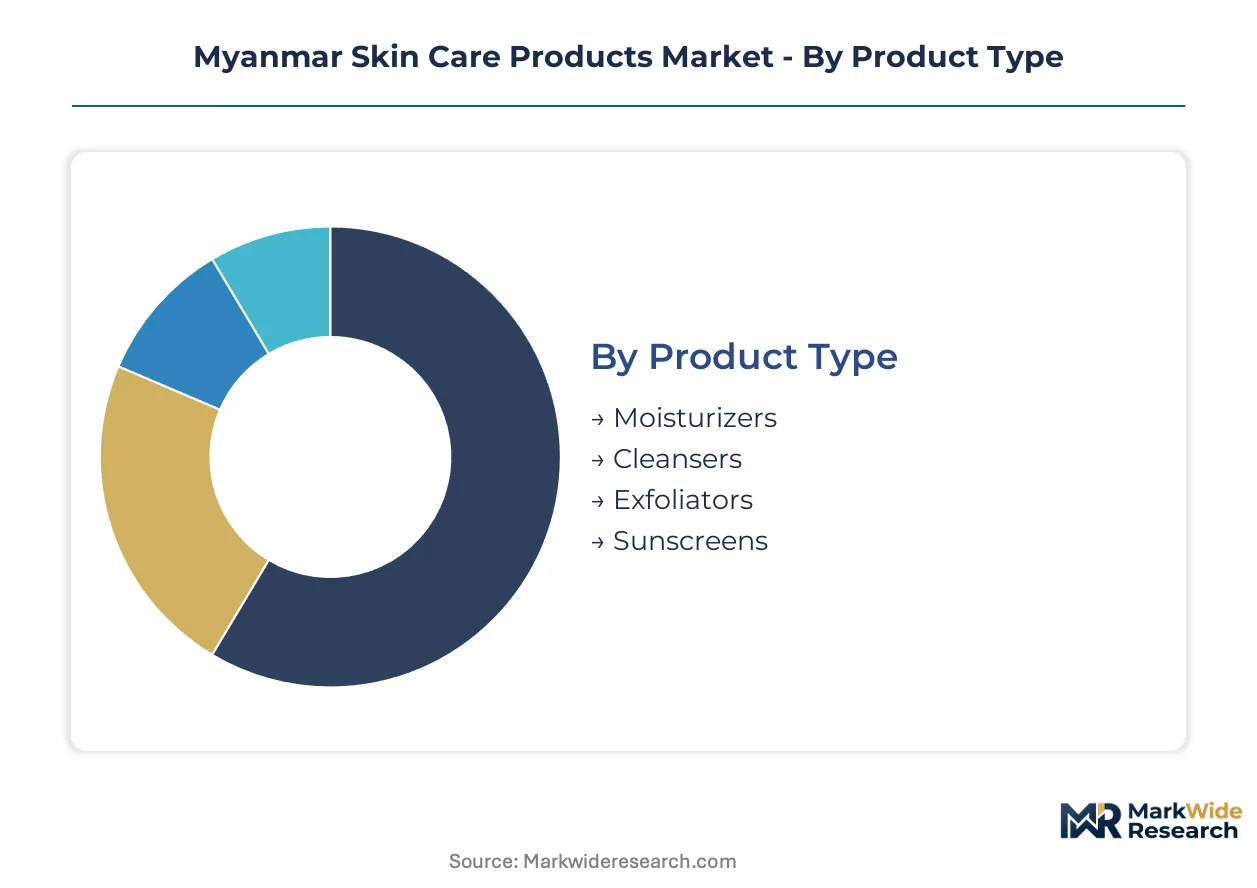
Segmentation in Myanmar's skin care sector reveals how regulatory pressure and channel fragmentation are redrawing profit pools. Manufacturers must align formulation investments with specific end-user rituals and distribution economics rather than pursuing uniform national strategies.
Product Type:
Margin concentration follows functional necessity and reformulation complexity, with sun protection and hydration commanding premium positioning.
- Moisturizers:Emulsion-based formulations containing humectants and occlusives stabilize epidermal barrier function in tropical humidity. Yangon's professional salon channel drives bulk procurement for pre-wedding facial protocols, with L'Oréal leveraging dermatological testing adapted to local climate conditions.
- Sunscreens:SPF-rated formulations with photostabilized UV filters face stringent Myanmar FDA disclosure requirements for active ingredient concentrations. Urban millennials in Mandalay prioritize premium-tier adoption for daily ceremonial preparation, creating defensible margin pools despite import licensing friction.
- Cleansers:Surfactant-based emulsions with pH-balanced formulations serve mass-market daily hygiene rituals across provincial townships.
- Exfoliators:Acid-based and mechanical formulations targeting cell turnover encounter consumer wariness toward synthetic preservatives in emerging clean-label segments.
Moisturizers hold installed capacity. Sunscreens are rotating up the share rankings.
End User:
Demand volume concentrates in demographic segments with established grooming rituals and disposable income access, while growth velocity favors emerging adopters.
- Women:Traditional thanaka-integrated routines and K-beauty influenced multi-step regimens coexist across generational divides. Wedding economy expansion in Yangon and Mandalay sustains professional salon channel dependence for ceremonial preparation.
- Teenagers:Digital-native procurement through cross-border e-commerce platforms displaces pharmacy reliance, with Korean-influenced skincare routines expanding most quickly among urban secondary school populations.
- Men:Emerging facial care adoption concentrates in white-collar employment corridors with exposure to regional grooming trends.
- Professionals:Salon operators and aesthetic practitioners command disproportionate margin pools through treatment-grade bulk procurement.
Women retain dominant volume share. Teenagers are climbing the fastest in absolute growth contribution.
Distribution Channel:
Channel economics reflect infrastructure maturity and regulatory shelter, with digital pathways eroding traditional intermediaries.
- Beauty Salons:Professional treatment venues capture recurring revenue through wedding and festival preparation segments. Bulk procurement relationships with domestic thanaka-integrated manufacturers like Shwe Pyi Nann provide cost advantages over import-dependent competitors.
- Online:Social commerce and cross-border platforms fragment traditional wholesale hierarchies. Urban teenagers seeking K-beauty formulations bypass licensed retail, pressuring salon operator margins through unlicensed digital intermediaries.
- Supermarkets:Mass-market penetration depends on Unilever's rural township network with thin margins from fragmented retail density.
- Pharmacies:Traditional access points for dermatological formulations face displacement as digital channels expand.
Beauty Salons maintain professional-grade concentration. Online is gaining share fastest among urban demographic cohorts.
Ingredient Type:
Formulation philosophy determines regulatory compliance burden and consumer trust positioning, with botanical sourcing creating domestic competitive shelter.
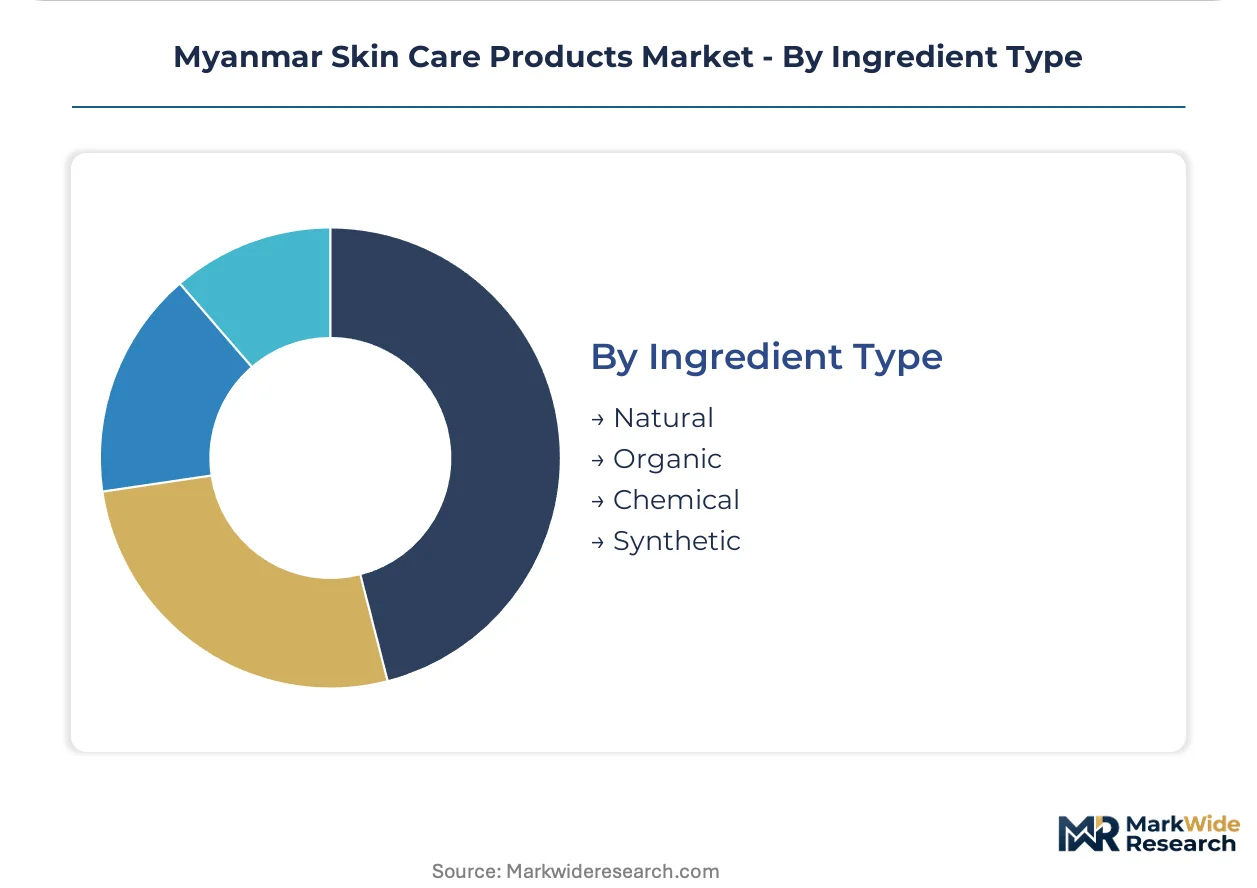
- Natural:Thanaka bark extract and indigenous botanical supply chains occupy culturally authentic positioning that foreign manufacturers cannot replicate. Shwe Pyi Nann anchors production capacity with simplified ingredient lists satisfying FDA transparency demands.
- Organic:Certified clean-label formulations command premium positioning among consumer segments wary of synthetic preservatives, though domestic certification infrastructure remains underdeveloped.
- Chemical:Synthetic active compounds including niacinamide and retinoids require cold-process emulsification equipment subject to foreign exchange volatility and extended procurement timelines.
- Synthetic:Preservative-stabilized mass-market formulations face reformulation pressure as consumer preference shifts accelerate.
Natural ingredients hold cultural defensibility. Organic is rotating up the share rankings on certification tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Myanmar's skin care trade flows predominantly through Thailand and China, with finished cosmetics entering via Yangon's port infrastructure while raw botanical ingredients exit toward regional formulation centers.
Yangon Region
Urban millennials drive premium-tier facial care adoption through professional salon channels serving wedding preparation segments. The Myanmar Food and Drug Administration enforces cosmetic ingredient disclosure rules that compress margins for import-dependent suppliers. Yangon's Bahan and Kamayut townships concentrate high-end retail infrastructure where L'Oréal maintains dermatological testing protocols.
Mandalay Region
Ceremonial occasion demand sustains bulk procurement relationships with domestic thanaka-integrated manufacturers. Ministry of Commerce import licensing requirements create regulatory friction benefiting local production. Mandalay's Maha Aungmyay and Chanayethazan districts anchor professional salon density for festival preparation segments.
Southern Myanmar
Cross-border e-commerce penetration from Thailand disrupts traditional pharmacy-dependent procurement patterns among younger demographics. The central bank's foreign exchange volatility affects cold-process emulsification equipment imports. Myeik and Dawei coastal zones concentrate indigenous botanical supply chains feeding natural ingredient formulations.
Central Dry Zone
Rural distribution networks operate on thin margins due to fragmented retail density across Magway and Sagaing divisions. Unilever leverages extensive provincial township penetration for mass-market cleanser and moisturizer categories. The region's thanaka cultivation belts supply Shwe Pyi Nann with culturally authentic raw material inputs.
Myanmar Skin Care Products Market Competitive Landscape
Listed leaders compete with private specialists across formulation philosophy and channel access, creating a tiered structure where multinational scale advantages confront domestic regulatory shelter. The market fragments across three strategic archetypes: global FMCG conglomerates with rural distribution depth, premium dermatological specialists with tropical-adapted protocols, and heritage-anchored local manufacturers with botanical supply control. Dominant competitive moves include portfolio diversification into natural ingredient certifications and backward integration into indigenous raw material sourcing.
Among European-based dermatological specialists, L'Oréal occupies a position exemplifying premium-tier positioning through humidity-adapted testing infrastructure. Unilever, a British-Dutch conglomerate, represents mass-market penetration archetypes with extensive provincial network coverage. Shwe Pyi Nann, a Myanmar private limited company, anchors the heritage-integrated tier with thanaka supply chain control that foreign competitors cannot replicate.
| Leading Market Players |
|---|
| Unilever |
| L'Oréal |
| Procter & Gamble |
| Beiersdorf |
| Shiseido |
| Kao Corporation |
| Estee Lauder |
| Revlon |
| Shwe Pyi Nann |
| Others |
Pricing and Supply Chain Analysis
Cold-process emulsification equipment substitution for hot-process systems is redrawing procurement geography and pricing economics in Myanmar's skin care sector, as manufacturers source temperature-controlled machinery from Thailand and China while absorbing foreign exchange volatility into capital expenditure planning.
Pricing Analysis
Current-generation cold-process formulations command premium positioning against prior-generation hot-process alternatives and nascent next-gen biotechnology platforms. Three-tier pricing structure across premium, standard, and economy levels separates dermatologically tested salon-grade products from mass-market pharmacy offerings and rural township staples. Price differentiation centers on certification grade against Myanmar FDA disclosure standards and volume scale in wedding-economy bulk procurement. Cost compression in the mass-market tier is intensifying because Unilever's rural network operates on thin margins from fragmented retail density. Urban teenagers seeking K-beauty routines through digital channels exhibit lowest price sensitivity, while provincial township consumers remain most responsive to unit economics.
Supply Chain Analysis
Inventory lead times for cold-process emulsification equipment extend procurement cycles and inflate working capital requirements for domestic manufacturers scaling production capacity. Geographic supply concentration centers on Thailand for finished cosmetic machinery, China for active compound precursors including niacinamide and retinoid formulations, and India for surfactant and emulsifier intermediates. Raw material dependencies rest on thanaka bark from Myanmar's Central Dry Zone cultivation belts, photostabilized UV filters from Chinese chemical manufacturers, and imported preservative systems from ASEAN suppliers. Supply chain risk hinges on single-source vulnerability for tropical-adapted dermatological testing protocols controlled by European specialists. Distribution runs through professional salon channels for premium tiers, cross-border e-commerce platforms for K-influenced segments, and Unilever's provincial township networks for mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Myanmar's skin care market represents a high-growth disruption driven by regulatory tightening around cosmetic ingredient disclosure, which simultaneously elevates technical barriers for import-dependent suppliers and creates competitive shelter for domestic thanaka-integrated manufacturers.
For Market Incumbents: Fortify salon channel control through exclusive bulk procurement contracts with wedding and festival preparation segments, while deepening backward integration into thanaka cultivation belts to secure raw material cost advantages against foreign competitors facing import licensing friction. Invest in cold-process emulsification capacity to claim enhanced efficacy positioning against hot-process mass-market rivals.
For New Entrants and Emerging Players: Digital-native service layers where incumbents under-serve present immediate white-space opportunity, specifically cross-border e-commerce fulfillment for Korean-influenced skincare routines among Mandalay's urban teenagers. Target the professional salon vertical in secondary cities with treatment-grade natural formulations. Pursue direct-to-consumer social commerce as the primary go-to-market angle to bypass entrenched wholesale-distributor hierarchies.
For Investors and Strategic Acquirers: Capital is best deployed toward domestic thanaka-integrated manufacturers with captive botanical supply chains and simplified regulatory compliance profiles, as these archetypes capture structural advantages from Myanmar FDA disclosure requirements that foreign competitors cannot replicate. Long-term viability over the next decade rests on regulatory shelter durability and digital channel penetration rates. Monitor enforcement consistency at Yangon port-of-entry inspection points as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Thanaka Supply Chain Backward Integration | Captures culturally authentic raw material sourcing that foreign brands cannot replicate under Myanmar FDA rules. |
| Cold-Process Emulsification Capacity Buildout | Preserves heat-sensitive niacinamide and retinoid efficacy for premium salon-grade positioning in tropical humidity. |
| Professional Salon Vertical Integration | Locks in recurring revenue from wedding economy bulk procurement across Yangon and Mandalay ceremonial segments. |
| Cross-Border E-Commerce Channel Launch | Bypasses Ministry of Commerce import licensing friction for K-beauty influenced digital-native consumer acquisition. |
| Natural Ingredient Certification Program | Addresses consumer wariness toward synthetic preservatives through clean-label transparency satisfying FDA disclosure mandates. |
Research Methodology
Desk research of trade flow databases, Myanmar FDA regulatory filings, and ASEAN cosmetic industry publications preceded structured interviews with formulation chemists, professional salon operators, import licensing consultants, and distribution channel managers across Yangon and Mandalay. Primary fieldwork with domestic manufacturers like Shwe Pyi Nann and multinational local representatives supplemented secondary validation from customs records and provincial retail audit data. Bottom-up demand modeling across consumer segments triangulated against top-down supply-side capacity assessments.
Variance decomposition across product type, end user demographic, distribution channel, and ingredient philosophy dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectories weighted by margin concentration and channel economics. Forecast inputs incorporated wedding economy expansion rates, cold-process equipment import timelines, and digital channel penetration velocity among urban teenagers.
Underlying assumptions cover sustained enforcement of cosmetic ingredient disclosure rules and stable foreign exchange conditions for capital equipment procurement, with deviation risk concentrated in regulatory consistency at port-of-entry inspection points and central bank liquidity management affecting import-dependent supply chains. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
Pillow Spray Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Sun Care Products Market
Cosmetics & Skincare
Global Cosmetic Jar Market
Cosmetics & Skincare
Silicone Makeup Sponge Market
Cosmetics & Skincare
Italy Lip Care Products Market
Cosmetics & Skincare
Organic Makeup Remover Market
Cosmetics & Skincare
Lip Scrub Market
Cosmetics & Skincare
Eyeliner Industry Status and Prospects Professional Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Caffeine Eye Creams Market
Cosmetics & Skincare
Facial Serum Market
Cosmetics & Skincare
Japan Bath Soap Market