
 UK Eyelash Serum Market | 2026-2036
UK Eyelash Serum Market Size, Share, and Industry Trends Forecast 2026-2036
UK Eyelash Serum Market Insights
Subscription-based direct-to-consumer financing is rewriting competitive access in the UK eyelash serum sector, lowering capital barriers for emerging brands. Revitalash leverages its specialist positioning in premium lash care to sustain premium price points against mass-market entrants. The Estée Lauder Companies anchors shelf presence through department store concessions and pharmacy partnerships across Boots and John Lewis. UKLash competes aggressively on digital-native marketing, occupying influencer-driven channels that bypass traditional retail gatekeepers.
Eyelash serums are cosmetic formulations containing biotin, peptides, prostaglandin analogues, or plant-derived extracts designed to enhance lash length, density, and structural integrity through follicle stimulation and keratin support. Manufacturing requires sterile aqueous or emulsion bases with precise pH control between 6.8 and 7.4 to ensure ocular compatibility and preservative efficacy. Growth Enhancer serums lead value generation due to higher active-ingredient concentrations and clinical positioning, while Conditioning Formula products dominate unit volumes through lower price points and broader retail accessibility. Distribution through online retail channels is expanding fastest, capturing consumers who research ingredient transparency and compare peptide formulations before purchase.
The UK Office for Product Safety and Standards enforces post-Brexit cosmetic safety requirements, while Trading Standards monitors claims compliance under the UK Cosmetics Regulation derived from retained EU law. MHRA scrutiny of prostaglandin-containing products shapes formulation choices, pushing brands toward peptide-based alternatives that avoid medicinal classification. The EU REACH framework continues influencing ingredient sourcing decisions for UK manufacturers maintaining European export pathways. Stakeholders must monitor evolving border compliance costs and ingredient restriction timelines to calibrate R&D investment against regulatory risk.
Market Dynamics
Post-Brexit regulatory divergence between the UK Cosmetics Regulation framework and retained EU REACH standards is forcing reformulation cycles that compress R&D timelines and elevate compliance costs for active peptide developers.
Growth Catalysts
- Prostaglandin analogue substitution:MHRA scrutiny of medicinal-classified lash treatments accelerates migration toward peptide-based formulations that retain cosmetic classification while delivering comparable follicle stimulation efficacy.
- Greater London aesthetic service density:Concentration of premium beauty clinics in the capital creates clustered demand pull for professional-grade lash serums with clinical positioning and higher active ingredient loadings.
- EU REACH ingredient sourcing alignment:UK manufacturers maintaining European export pathways benefit from established supply relationships with certified peptide and biotin suppliers under harmonized safety assessment protocols.
Market Restraints
- Active ingredient cost volatility:Peptide synthesis and prostaglandin analogue procurement face input cost pressure from pharmaceutical sector competition for contract manufacturing capacity.
- Single-source supply concentration:Sterile aqueous base manufacturing for ocular-compatible formulations clusters with specialized UK pharmaceutical contract manufacturers, creating bottleneck risk.
- pH stability technical limitation:Narrow 6.8-7.4 compatibility window for preservative efficacy and ocular safety constrains formulation flexibility and shelf-life extension.
Strategic Opportunities
- South East England salon network expansion:Underpenetrated professional channel presence outside Greater London offers whitespace for clinic-grade serum distribution through regional aesthetic training academies.
- Subscription direct-to-consumer financing:Digital-native recurring revenue models bypass traditional pharmacy and department store gatekeepers while capturing lifetime value from ingredient-educated consumers.
- UKCA marking regulatory tailwind:Post-Brexit product safety mark creates competitive differentiation for domestic manufacturers against EU-imported competitors navigating dual conformity assessment.
Industry Challenges
- Cosmetic safety assessor talent scarcity:Qualified safety assessors credentialed under both UK Cosmetics Regulation and retained EU frameworks command premium compensation, constraining smaller brand scale-up.
- Border compliance reconfiguration capex:Divergent UK-EU ingredient restriction timelines force parallel inventory management systems and dual-label packaging investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Eyelash Serum Market |
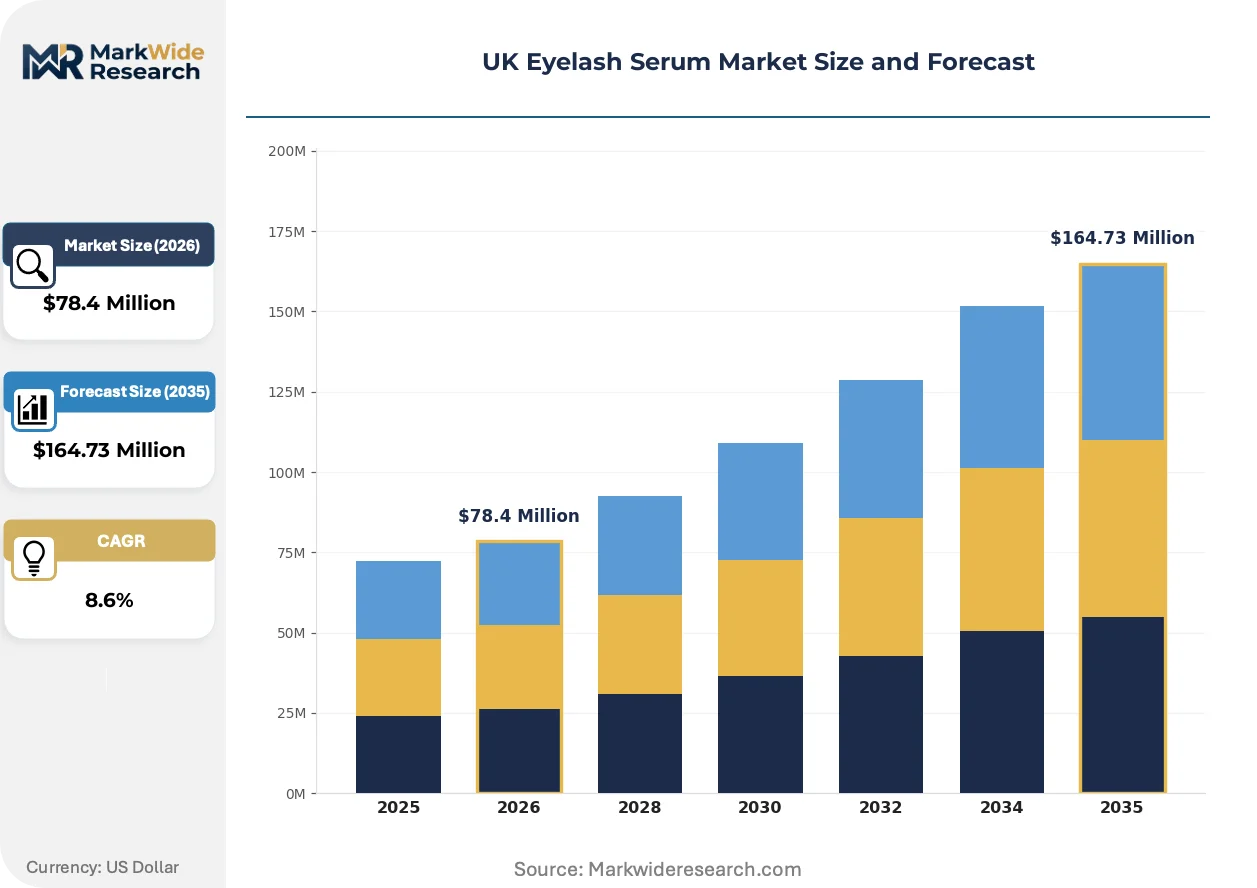
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $164.73 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conditioning Serum, Growth Enhancer, Nourishing Formula, Volumizing Serum, Repair Treatment Application: Eyelash Lengthening, Lash Thickening, Lash Strengthening, Sensitive Eye Use Distribution Channel: Online Retail, Specialty Beauty Stores, Pharmacies, Department Stores, Salon Direct Customer Type: Female Consumers, Beauty Professionals, Cosmetic Retailers, Dermatology Clinics |
| Companies Covered | Revitalash, L'Oréal, The Estée Lauder Companies, Shiseido, Grande Cosmetics, UKLash, RapidLash, The Ordinary, Mavala, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Eyelash Serum Market Trends and Innovations
Digital ingredient transparency tools and AI-driven personalization are compressing the path from consumer research to purchase decision, while regulatory technology automates compliance documentation across divergent UK-EU frameworks.
Peptide sequencing and biomimetic keratin support formulations are virtualizing traditional prostaglandin-dependent efficacy claims. Premium beauty clinics in Greater London and Manchester are adopting these technologies fastest, replacing medicinal-classified treatments with cosmetic-grade alternatives that avoid MHRA pharmaceutical scrutiny. The shift is virtualizing competitive positioning around clinical credibility without regulatory burden.
The UK Cosmetics Regulation's retained EU safety assessment requirements now diverge from ECHA updates on peptide allergenicity thresholds. This friction forces dual-track safety dossier maintenance for brands serving both markets, elevating compliance overhead most acutely for mid-scale manufacturers lacking dedicated regulatory affairs functions.
Ingredient literacy among consumers is reshaping channel economics. Buyers now research specific peptide chains and biotin concentrations before purchase, bypassing traditional retail advice. This behavior concentrates online direct-to-consumer growth in Greater London and the South East, where digital research intensity correlates with disposable income for premium positioning.
UK Eyelash Serum Market Segmentation
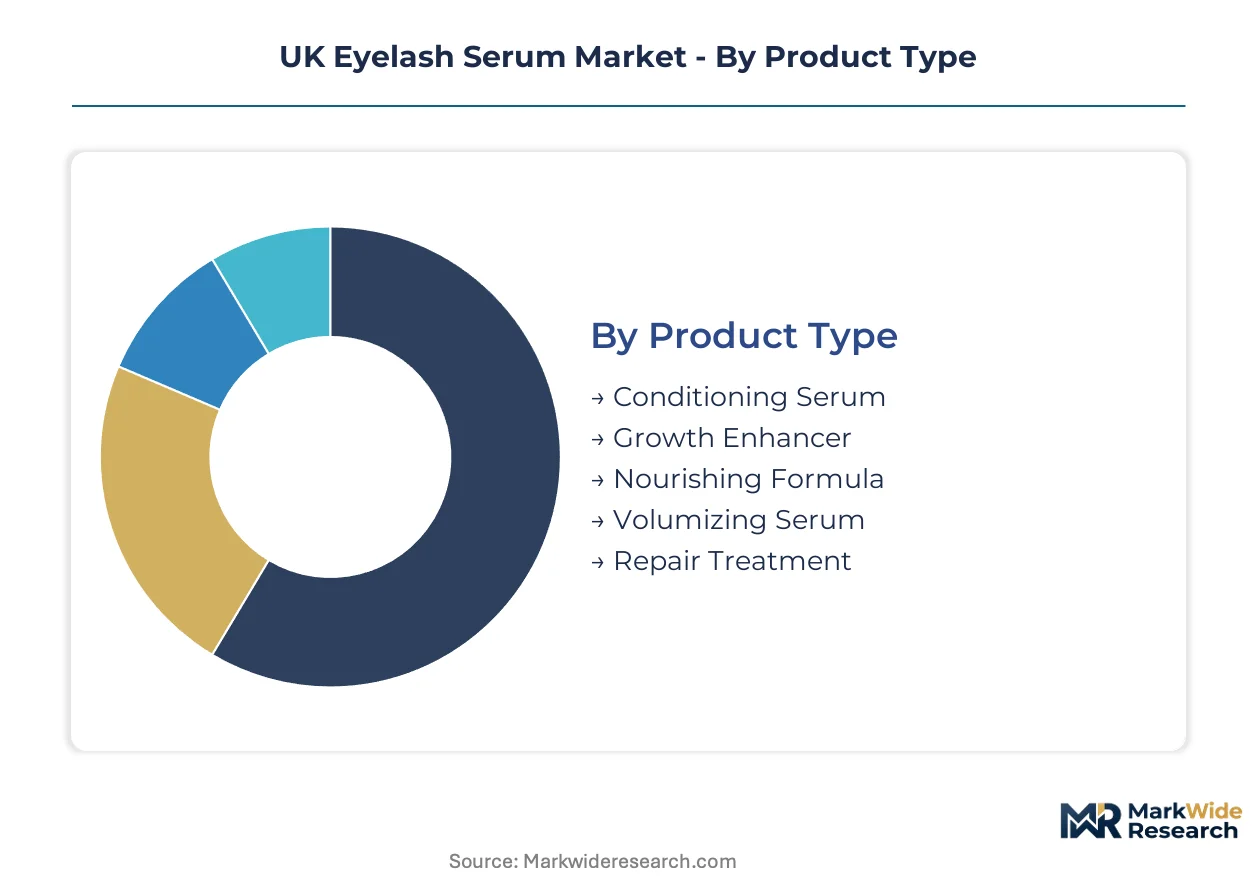
Segmentation in the UK eyelash serum market reveals distinct consumption patterns across formulation intensity, channel preference, and professional versus at-home application settings. Understanding these divides enables precise inventory positioning and regulatory pathway selection for active ingredient classifications.
Product Type:
Cycle times vary sharply across this dimension—daily-use conditioning formats turn inventory fastest while clinical-grade growth treatments command extended purchase deliberation and higher per-unit margins.
- Growth Enhancer:High-concentration peptide and prostaglandin analogue formulations designed for measurable lash extension within 8-12 week cycles. Demand clusters in Greater London aesthetic clinics where MHRA-compliant cosmetic classification avoids pharmaceutical dispensing requirements.
- Conditioning Serum:Biotin and panthenol-based daily maintenance formulations with lower active loading and broader retail accessibility. South East England pharmacy chains and Boots concessions move the highest unit volumes through impulse-adjacent placement.
- Nourishing Formula:Plant-derived extract blends targeting hydration and brittleness reduction for consumers avoiding synthetic actives.
- Volumizing Serum:Film-forming polymer and fiber-coating technologies delivering immediate cosmetic effect rather than biological stimulation.
- Repair Treatment:Intensive keratin-support concentrates for post-extension damage recovery, positioned through salon professional channels.
Conditioning Serum anchors the volume base while Growth Enhancer gains share at the steepest rate.
Application:
Cost tier stratification separates premium clinical positioning from mass-market accessibility across intended use cases.
- Eyelash Lengthening:Primary efficacy claim supported by prostaglandin analogues or biomimetic peptide chains targeting anagen phase extension. Greater London consumers drive premium pricing tolerance for measurable length outcomes.
- Lash Thickening:Density-focused formulations employing multi-peptide complexes and biotin cofactors to increase follicle shaft diameter. Manchester and Birmingham urban markets show strongest uptake among younger demographics.
- Lash Strengthening:Keratin infrastructure support for damage-prone lashes, prevalent in professional channel distribution through aesthetic training academies.
- Sensitive Eye Use:Preservative-minimized, pH-buffered formulations excluding fragrance and prostaglandin analogues for contact lens wearers and reactive skin types.
Eyelash Lengthening commands the premium tier while Sensitive Eye Use climbs fastest as ingredient literacy drives avoidance behavior.
Distribution Channel:
Volume concentration skews toward digital-native purchasing in high-disposal-income geographies, with professional channels retaining stickiest customer relationships.
- Online Retail:Direct-to-consumer and marketplace platforms capturing ingredient-researching buyers who compare peptide specifications before purchase. South East England postcodes generate disproportionate traffic for subscription-model serums.
- Specialty Beauty Stores:Space NK and Cult Beauty curating editorial-positioned indie brands with clean beauty credentials and transparent supply chains.
- Pharmacies:Boots and Superdrug chains leveraging pharmacist consultation for sensitive-eye and post-treatment recovery formulations.
- Department Stores:John Lewis and Selfridges concessions sustaining premium brand discovery through tactile trial and gift-with-purchase mechanics.
- Salon Direct:Clinic-grade professional exclusives bypassing retail markup, concentrated in Greater London and Manchester aesthetic service clusters.
Pharmacies sustain the broadest unit base while Online Retail expands most quickly through subscription financing models.
Customer Type:
Maturity gradients separate established consumption patterns from emerging professional adoption curves across buyer categories.
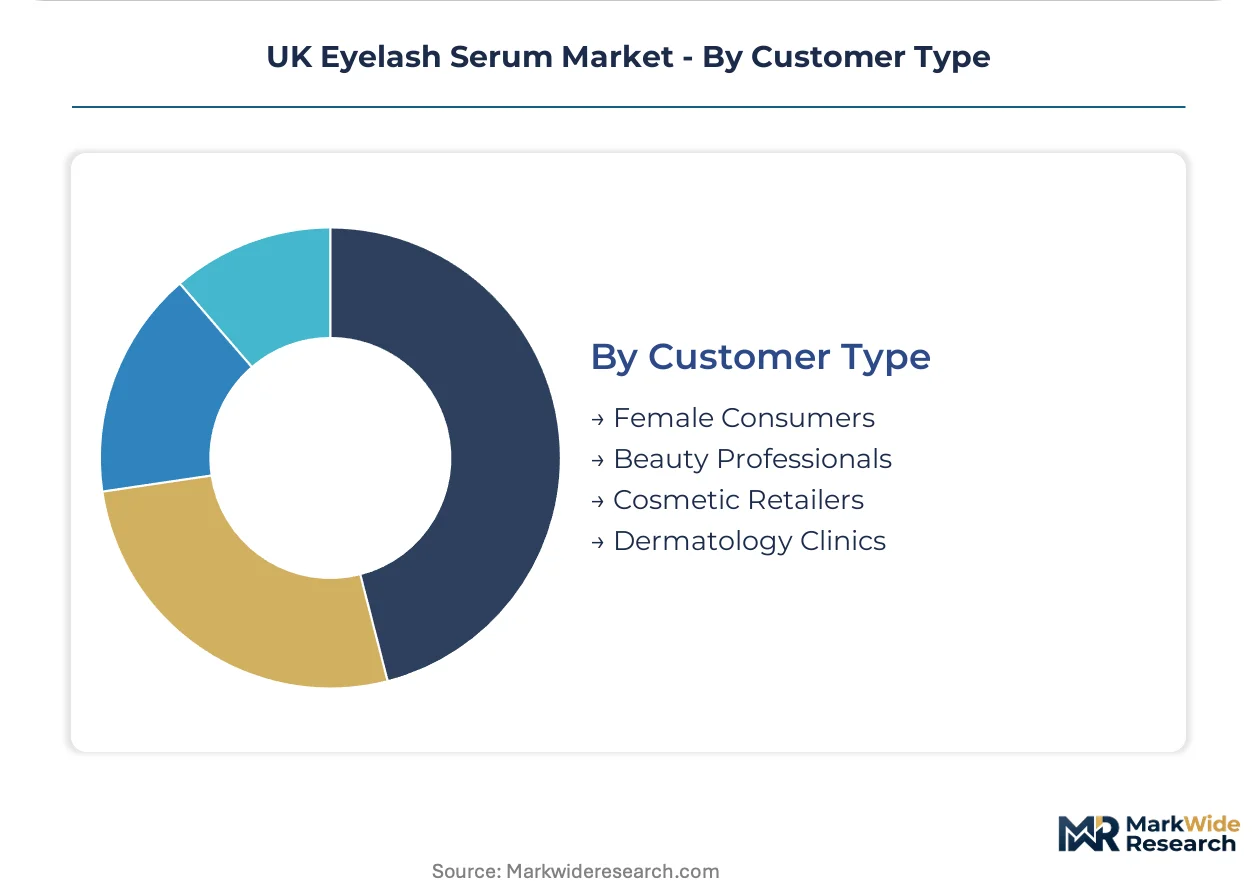
- Female Consumers:Individual purchasers spanning mass-market to luxury tiers, with South East England and Greater London postcodes showing highest per-capita serum expenditure and digital research intensity.
- Beauty Professionals:Lash technicians and aesthetic practitioners sourcing clinic-grade formulations for retail resale and treatment upsell, concentrated in London training academy networks.
- Cosmetic Retailers:Buyers for indie beauty boutiques and regional pharmacy chains selecting curated assortments based on margin and turnover velocity.
- Dermatology Clinics:Medical-aesthetic hybrid practices prescribing post-procedure recovery serums with documented safety dossiers for patient compliance.
Female Consumers anchor volume throughput while Beauty Professionals drive the steepest adoption curve through training channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-Brexit regulatory divergence between the UK Cosmetics Regulation and retained EU frameworks is reshaping formulation strategies across domestic manufacturing clusters. This policy friction concentrates R&D investment in Greater London and the South East, where safety assessor talent and MHRA-proximate testing facilities cluster most densely.
Greater London
Premium aesthetic clinics in Chelsea, Mayfair, and Knightsbridge drive concentrated demand for clinical-grade Growth Enhancer serums with peptide-based actives. The UK Office for Product Safety and Standards enforces cosmetic safety dossier requirements that favor MHRA-compliant formulations avoiding medicinal classification. Shoreditch and Soho house the densest concentration of direct-to-consumer beauty startups leveraging subscription financing models.
South East England
High-disposable-income consumers in Surrey, Kent, and Berkshire postcodes generate disproportionate online retail traffic for ingredient-transparent peptide serums. Trading Standards monitors claims compliance under retained EU-derived cosmetic advertising rules. Brighton and Guildford anchor regional distribution hubs serving pharmacy chains and indie beauty boutiques with Conditioning Formula products.
Midlands
Manchester and Birmingham urban markets show strongest uptake of Lash Thickening formulations among younger demographics seeking density outcomes without prostaglandin analogues. The UK's post-Brexit REACH alignment pressures manufacturers to maintain dual safety dossiers for European export compatibility. Birmingham's Jewellery Quarter hosts emerging contract manufacturing capacity for sterile aqueous base production.
Scotland
Edinburgh and Glasgow aesthetic service clusters are expanding professional channel adoption of salon-direct Repair Treatment serums for post-extension damage recovery. Scottish Trading Standards applies UK Cosmetics Regulation enforcement with particular scrutiny of online marketplace claims. Dundee's life sciences corridor offers peptide synthesis partnerships for domestic brands seeking supply chain resilience.
Wales
Cardiff and Swansea retail pharmacies sustain steady Conditioning Serum volumes through Boots and Superdrug chain presence with lower premium-tier penetration than English counterparts. The Welsh Government's economic development programs support cosmetic manufacturing SME scaling with regulatory compliance grants. Wrexham's pharmaceutical heritage provides contract manufacturing options for pH-stable ocular-compatible formulations.
UK Eyelash Serum Market Competitive Landscape
On the supply side, the industry is bifurcating between mass-market conglomerates with pharmacy and department store shelf dominance and digital-native specialists capturing subscription-driven lifetime value. Strategic archetypes include heritage beauty houses with multi-brand portfolios, peptide-formulation specialists with clinical positioning, and influencer-marketed direct-to-consumer disruptors. Competitive moves center on regulatory compliance differentiation through UKCA marking and subscription financing infrastructure to bypass traditional retail gatekeepers.
Within the heritage conglomerate tier, L'Oréal and The Estée Lauder Companies exemplify scale-driven distribution leverage through Boots, John Lewis, and Selfridges concessions. Revitalash and UKLash occupy contrasting positions—one representing premium specialist clinical credibility, the other exemplifying digital-native channel disruption through influencer-driven acquisition. These three anchors illustrate how formulation intensity and channel strategy separate premium positioning from mass-market accessibility.
| Leading Market Players |
|---|
| Revitalash |
| L'Oréal |
| The Estée Lauder Companies |
| Shiseido |
| Grande Cosmetics |
| UKLash |
| RapidLash |
| The Ordinary |
| Mavala |
| Others |
Pricing and Supply Chain Analysis
Birmingham's Jewellery Quarter contract manufacturing cluster anchors domestic sterile aqueous base production, concentrating formulation capacity for ocular-compatible serums and feeding downstream pricing power to peptide-specialist brands against import-dependent competitors navigating UKCA marking compliance costs.
Pricing Analysis
Certification level creates the primary spread between clinic-grade Growth Enhancer formulations and mass-market Conditioning Serums, with MHRA-compliant cosmetic classification commanding premium positioning against uncertified imports. Three-tier pricing structure across premium peptide-based, standard biotin-formulated, and economy plant-extract tiers reflects active ingredient concentration and safety dossier depth. Cost compression in the standard tier is intensifying because pharmaceutical sector competition for contract manufacturing capacity elevates peptide synthesis input costs. Price-sensitive consumers in Wales and the Midlands gravitate toward pharmacy-chain Conditioning Serums, while Greater London buyers show lowest sensitivity for measurable length outcomes.
Supply Chain Analysis
Peptide synthesis feedstock draws from Switzerland, South Korea, and domestic Dundee life sciences partnerships, with biotin cofactor sourcing concentrated in China and India for cost efficiency. Sterile aqueous base manufacturing rests on specialized UK pharmaceutical contract manufacturers clustered in Birmingham and Wrexham, creating single-source vulnerability for pH-stable ocular-compatible formulations. Tariff exposure on EU-imported active ingredients following post-Brexit divergence elevates landed cost unpredictability for brands maintaining European export pathways. Distribution runs through salon-direct professional channels in Greater London and Manchester aesthetic clusters, alongside pharmacy chain concessions and digital-native subscription platforms capturing South East England's ingredient-researching consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK eyelash serum market operates as a regulatory entrenchment story, where MHRA compliance dossiers and UKCA marking requirements create switching costs that defend incumbent positions against unqualified entrants.
For Market Incumbents: Insulate market position by deepening backward integration into peptide synthesis partnerships with Dundee and Birmingham manufacturing clusters, reducing exposure to pharmaceutical sector capacity competition. Secure channel control through exclusive salon-direct distribution agreements with Greater London aesthetic training academies, defending against digital-native disruptors bypassing traditional retail gatekeepers.
For New Entrants and Emerging Players: South East England pharmacy chain white space outside Boots and Superdrug dominance represents the most penetrable entry point for Conditioning Serum volume capture. Manchester and Birmingham urban Lash Thickening segments among younger demographics offer density-focused formulation opportunities without prostaglandin analogue regulatory burden. Go-to-market execution should prioritize influencer-driven digital acquisition with transparent peptide chain disclosure to capture ingredient-literate consumers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors peptide-formulation specialists with established MHRA cosmetic classification and UKCA marking infrastructure over prostaglandin-dependent legacy portfolios facing medicinal reclassification risk. Long-term viability rests on regulatory compliance scalability across divergent UK-EU frameworks rather than single-market concentration. Monitor ECHA peptide allergenicity threshold updates as the critical inflection signal for dual-track safety dossier cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Substitution R&D Investment | Biomimetic formulation development bypasses MHRA pharmaceutical scrutiny while retaining follicle stimulation efficacy claims. |
| Salon-Direct Channel Expansion | Professional exclusives through Greater London aesthetic academies capture sticky customer relationships and treatment upsell revenue. |
| UKCA Marking Compliance Infrastructure | Domestic conformity assessment differentiation elevates competitive positioning against EU-imported competitors navigating dual certification. |
| Subscription Financing Platform Buildout | Recurring revenue models bypass Boots and John Lewis gatekeepers while capturing lifetime value from ingredient-educated South East consumers. |
| Dundee Peptide Sourcing Partnership | Scottish life sciences corridor integration reduces single-source dependency on Swiss and South Korean contract manufacturers. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with cosmetic safety assessors, peptide formulation chemists, Boots category buyers, and Greater London aesthetic clinic directors; and secondary validation through UK Office for Product Safety and Standards guidance documents, MHRA borderline determination notices, ECHA peptide allergenicity assessments, and Boots annual report beauty category disclosures. Bottom-up triangulation across distribution channel volume estimates and top-down validation against retail audit data anchored market sizing integrity.
Forecast inputs incorporated formulation type segmentation by active ingredient intensity, application purpose by efficacy claim, distribution channel by professional versus retail accessibility, and customer type by individual versus professional purchaser across the projection horizon. CAGRs were derived from regression analysis of historical peptide adoption curves and regulatory substitution timelines, with sensitivity testing against MHRA classification boundary shifts and EU REACH divergence scenarios.
Practitioners should monitor ECHA peptide allergenicity threshold revisions and UK-EU regulatory divergence acceleration for early signals of compliance cost escalation requiring forecast recalibration. Cross-checking against Boots and Superdrug published category growth benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Cosmetic Mirror Market
Cosmetics & Skincare
Natural Cosmetic Color Market
Cosmetics & Skincare
GCC Halal Cosmetics Market
Cosmetics & Skincare
Chile Cosmetics Products Market
Cosmetics & Skincare
Retinol Eye Cream Market
Cosmetics & Skincare
Halal Cosmetics Market
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
Eyeliner Pen Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Israel Cosmetics Products Market
Cosmetics & Skincare
France Lip Care Products Market
Cosmetics & Skincare
Mushroom Cosmetics Market
Cosmetics & Skincare
Asia-Pacific Face Compact Market
Cosmetics & Skincare
Makeup Remover Market
Cosmetics & Skincare
Makeup Setting Powder Market
Cosmetics & Skincare
Japan Bath Soap Market