
 Herbal Soap Market | 2026-2036
Herbal Soap Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Soap Market Analysis
Skilled Ayurvedic formulation chemists is redrawing competitive boundaries as brands race to authenticate herbal claims with laboratory-verified ingredient profiles. Mamaearth leverages direct-to-consumer digital channels to sustain rapid customer acquisition. Himalaya anchors its position through decades of clinical herbal research. Biotique competes on price-accessible Ayurvedic positioning in mass retail.
Herbal soap denotes surfactant-based cleansing bars or liquids incorporating botanical extracts, essential oils, or plant-derived actives as primary functional ingredients, typically manufactured through cold-process saponification or melt-and-pour methods with pH balancing between 5.5 and 8.0 to preserve skin barrier integrity. Bar soap dominates volume in rural and price-sensitive segments where unit economics favor solid formats and minimal packaging. Liquid soap captures faster growth in urban households and hospitality channels where dispenser compatibility and perceived hygiene drive preference. Neem and tea tree oil formulations command premium positioning in medicated and acne-care sub-segments where antimicrobial claims require substantiation.
India's BIS standards for Ayurvedic cosmetics, the EU REACH regulation on chemical safety, and the FDA's cosmetic labeling requirements in the United States collectively elevate compliance costs while filtering out unsubstantiated herbal claims. These frameworks reward brands with verified supply chains and documented ingredient traceability. Stakeholders must monitor evolving botanical sourcing regulations and certification schemes to secure market access and consumer trust.
Market Dynamics
India's BIS herbal product standards and the EU's REACH chemical safety protocols are tightening ingredient disclosure requirements, forcing brands to rebuild supply chains around laboratory-verified botanical traceability. This regulatory compression is redrawing competitive boundaries as authentication capabilities separate compliant operators from unsubstantiated claimants.
Growth Catalysts
- Ayurvedic heritage consumer trust:India's tier-two cities demonstrate concentrated demand for heritage-positioned formulations where regional Ayurvedic knowledge validates premium pricing.
- REACH chemical safety protocols:The EU's expanded substance registration requirements reward brands with documented supply chains, creating market access barriers for unsubstantiated competitors.
- Cold-process saponification:This manufacturing method preserves volatile botanical actives that degrade in conventional heat processing, enabling functional differentiation in medicated sub-segments.
Market Restraints
- Wild-harvested botanical volatility:Neem and tea tree oil supply concentrates in Maharashtra and Karnataka, exposing formulations to monsoon-dependent harvest fluctuations.
- Essential oil input cost instability:Lavender and sandalwood extracts face price pressure from competing aromatherapy and pharmaceutical demand channels.
- pH stability technical ceiling:Cold-process methods struggle to maintain 5.5-8.0 skin-barrier ranges when incorporating high-acid botanical extracts like citrus or berry derivatives.
Strategic Opportunities
- Boutique hospitality amenity specifications:Premium hotel procurement teams now mandate herbal formulations for guest amenities, creating a B2B channel with volume concentration and brand exposure value.
- FSSAI cosmetic-digitization alignment:India's food safety regulator is expanding into cosmetic traceability systems, offering first-mover advantage to brands pre-integrated with digital ingredient logging.
- Dispenser-compatible liquid formats:Urban household and commercial washroom infrastructure is standardizing around refillable pump systems that favor liquid over bar formats.
Industry Challenges
- Ayurvedic formulation chemist scarcity:Laboratory verification of traditional claims requires rare expertise combining classical text knowledge with chromatographic analytical methods.
- Dual certification timeline compression:Brands targeting both BIS Ayurvedic standards and EU REACH compliance face overlapping documentation demands with incompatible testing protocols.
- Blockchain traceability integration:Retailers are mandating farm-to-shelf digital logging that legacy ERP systems cannot accommodate without substantial middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Soap Market |
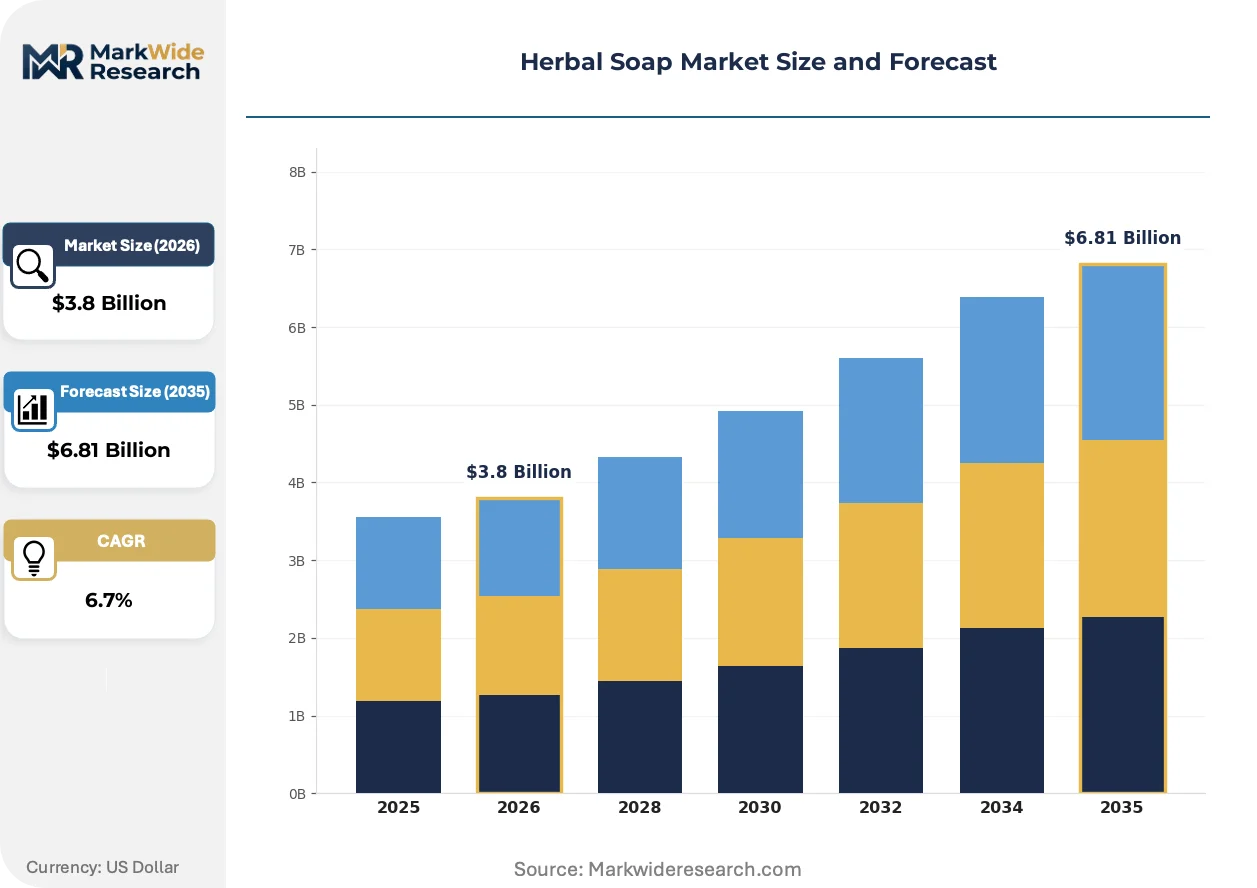
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Bar Soap, Foaming Soap, Glycerin Soap Key Ingredient: Aloe Vera, Tea Tree Oil, Lavender, Neem Packaging Type: Plastic Bottles, Glass Jars, Paper Boxes, Sachets Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Mamaearth, Khadi Natural, Unilever, ITC, Wipro Consumer Care, Dabur, Biotique, Zicail, Himalaya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Soap Market Emerging Trajectories
Formulation science is bifurcating around authentication capabilities as brands compete to substantiate herbal claims with verifiable laboratory profiles rather than heritage positioning alone. This shift is compressing the market into evidence-based operators and legacy claimants facing regulatory exclusion.
Supercritical CO2 extraction is bifurcating the active-ingredient supply tier by enabling precise terpene and flavonoid isolation without thermal degradation. Specialty chemical suppliers in Germany and Switzerland are scaling this capacity to serve cosmetic formulators seeking standardized botanical potency. The technology is compressing commodity extract margins while creating premium tiers for fingerprint-verified ingredient profiles.
REACH's extended substance registration deadlines are forcing reformulation cycles as ECHA adds botanical allergens to the candidate list. Manufacturers must either eliminate flagged compounds or generate full toxicological dossiers that smaller suppliers cannot fund. Liquid soap formulations containing limonene and linalool face the most immediate compliance pressure in export-oriented production facilities.
Direct-to-consumer digital channels are displacing traditional pharmacy and grocery distribution for heritage-positioned brands. Subscription models with personalized skin-type matching algorithms are capturing urban millennial households in Mumbai and Bangalore. This channel rotation is most visible among brands building Instagram-native communities around ingredient transparency storytelling rather than retail shelf presence.
Herbal Soap Market Segmentation
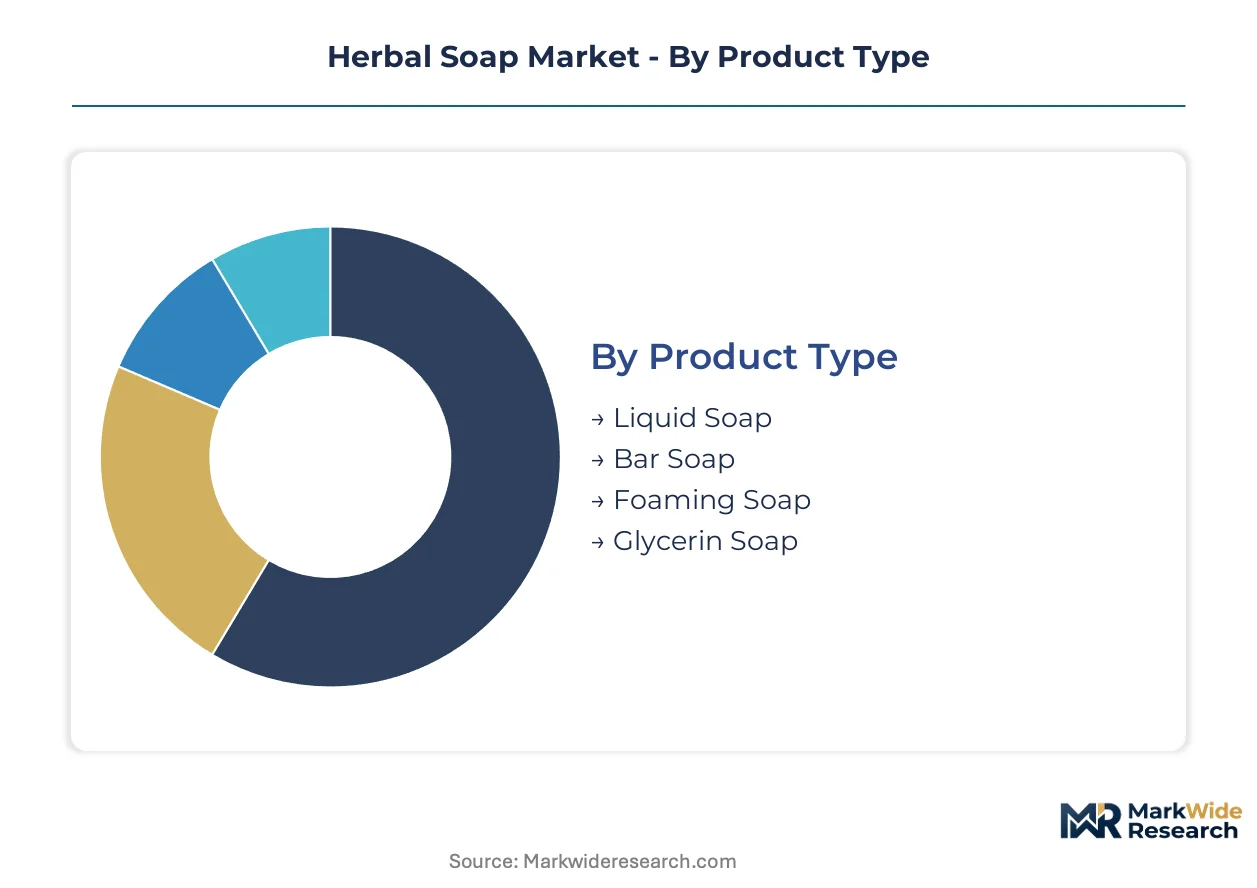
Herbal soap segmentation reveals how regulatory pressure on ingredient disclosure is fragmenting the market between laboratory-verified premium tiers and heritage-positioned mass formats. Each dimension carries distinct compliance burdens and margin structures that reshape competitive positioning.
Product Type:
REACH substance registration deadlines and BIS Ayurvedic standards impose divergent testing protocols on solid versus liquid formats, forcing brands to optimize manufacturing methods around specific regulatory pathways.
- Bar Soap:Cold-process saponification preserves volatile botanical actives that degrade under thermal stress. Rural Indian households and price-sensitive Southeast Asian markets favor this format for its minimal packaging cost and extended shelf stability.
- Liquid Soap:Melt-and-pour methods with pH buffering between 5.5 and 8.0 enable dispenser compatibility in urban hospitality channels. EU export facilities face immediate reformulation pressure as ECHA adds limonene and linalool to allergen candidate lists.
- Foaming Soap:Aerated delivery systems require specialized pump mechanisms that concentrate procurement among German and Swiss dispensing equipment suppliers.
- Glycerin Soap:Transparent base formulations attract artisanal positioning in Japanese and South Korean cosmetic markets where visual clarity signals purity.
Bar soap handles the majority of throughput; liquid soap is the fastest mover on share.
Key Ingredient:
Supply geography dictates cost tier accessibility, with monsoon-dependent Indian harvests creating volatility that premium brands offset through captive farming contracts.
- Aloe Vera:Cultivation concentrates in Rajasthan and Gujarat where arid conditions yield higher mucopolysaccharide content. Mass-market Indian brands leverage this domestic availability for price-accessible hydration claims.
- Tea Tree Oil:Australian Melaleuca alternifolia plantations supply standardized terpinen-4-ol concentrations for acne-care sub-segments. REACH-compliant toxicological dossiers separate export-grade suppliers from commodity traders.
- Lavender:Provence and Bulgarian harvests face competing aromatherapy demand that compresses cosmetic-grade allocation during peak pharmaceutical procurement cycles.
- Neem:Maharashtra and Karnataka wild-harvesting exposes formulations to climate-dependent yield fluctuations that BIS traceability requirements are forcing toward plantation cultivation.
Neem dominates heritage-positioned volume; tea tree oil is expanding most quickly in medicated applications.
Packaging Type:
EU Single-Use Plastics Directive and India's extended producer responsibility frameworks are accelerating material substitution timelines that favor glass and paper alternatives in premium tiers.
- Plastic Bottles:HDPE and PET formats retain cost advantage in mass retail through existing blow-molding infrastructure across Tamil Nadu and Maharashtra manufacturing clusters.
- Glass Jars:Heavier unit economics restrict this format to gift-boxed premium positioning in Middle Eastern and European hospitality amenity specifications.
- Paper Boxes:Bar soap wrapping meets FSC certification requirements that German and French retailers increasingly mandate for shelf access.
- Sachets:Single-use foil laminates dominate rural Indian trial-size distribution where unit affordability overrides waste concerns.
Plastic bottles carry the volume base; paper boxes are climbing the fastest on regulatory tailwinds.
Distribution Channel:
Digital traceability integration separates channels by authentication capability, with direct-to-consumer platforms capturing urban millennial households that demand farm-to-shelf visibility.
- Online Retail:Subscription algorithms with skin-type matching capture Mumbai and Bangalore households. Instagram-native brands bypass retail slotting fees through community-driven ingredient transparency storytelling.
- Supermarkets:Modern trade chains in Delhi NCR and Pune enforce blockchain traceability mandates that filter out legacy suppliers with paper-based documentation systems.
- Specialty Stores:Ayurvedic apothecaries in Kerala and Karnataka maintain consultation-based selling that validates premium pricing through practitioner endorsement.
- Pharmacies:CDSCO-registered medicated claims require clinical substantiation that limits this channel to Himalaya and comparable heritage brands with decades of research documentation.
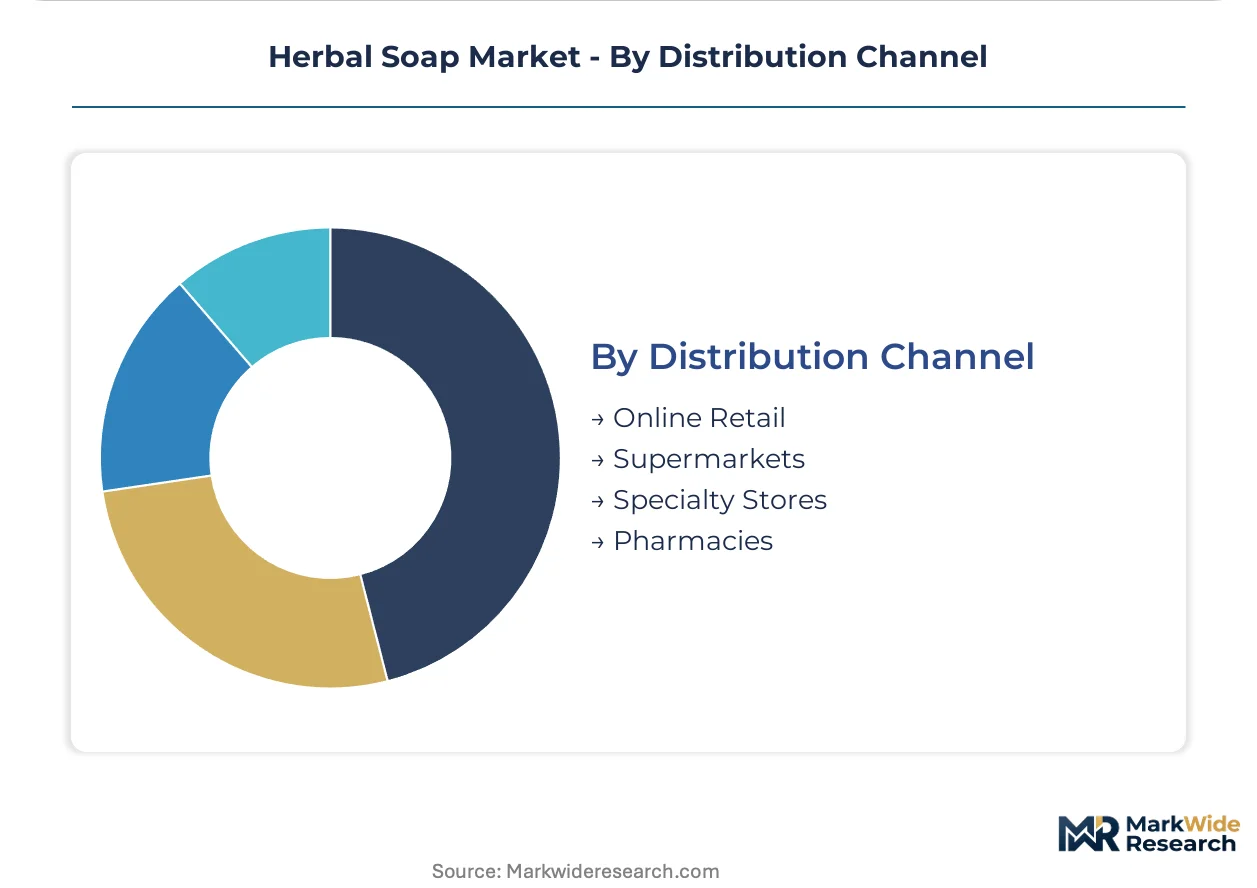
Supermarkets handle the majority of unit movement; online retail is gaining share fastest among urban demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Herbal soap consumption patterns diverge sharply across geographies, with Indian households favoring bar formats rooted in Ayurvedic tradition while German and Japanese markets drive liquid dispenser adoption in commercial settings.
India
Tier-two cities in Maharashtra and Karnataka generate concentrated demand for neem-based heritage formulations. BIS standards for Ayurvedic cosmetics mandate laboratory-verified ingredient traceability, forcing supply chain upgrades. Manufacturing clusters in Pune and Bengaluru are integrating cold-process saponification lines to preserve volatile botanical actives.
Germany
REACH substance registration deadlines are accelerating reformulation cycles for export-bound liquid soaps containing limonene and linalool. ECHA's expanding allergen candidate list creates compliance barriers for unsubstantiated botanical claims. Specialty chemical suppliers in Bavaria are scaling supercritical CO2 extraction capacity for standardized terpene isolation.
United States
FDA cosmetic labeling requirements elevate documentation burdens for herbal positioning claims, favoring brands with verified supply chains. Urban millennial households in California and New York drive subscription-based direct-to-consumer channels. Instagram-native brands bypass traditional retail slotting fees through community-driven ingredient transparency storytelling.
Japan
Transparent glycerin soap formats attract artisanal positioning in Tokyo and Osaka cosmetic markets where visual clarity signals purity. METI standards on cosmetic manufacturing practices reward documented quality management systems. Kanto region formulators are developing pH-buffered liquid systems compatible with automated dispenser infrastructure.
Brazil
Price-sensitive mass retail segments in São Paulo and Rio de Janeiro favor bar soap for minimal packaging economics. ANVISA registration requirements for cosmetic claims filter out unsubstantiated herbal positioning. Northeastern plantation projects are cultivating aloe vera to reduce import dependency on Rajasthan and Gujarat supply.
Herbal Soap Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidation pressure intensifying around authentication capabilities. The market structure separates evidence-based operators with laboratory-verified supply chains from heritage-positioned claimants facing regulatory exclusion. Two strategic archetypes dominate: vertically integrated Ayurvedic heritage brands with captive botanical sourcing, and digitally native direct-to-consumer specialists leveraging subscription algorithms. Competitive moves concentrate on M&A for supply chain control and partnerships with specialty chemical suppliers for standardized extract potency.
Within the heritage-integrated tier, Himalaya and Dabur occupy positions anchored by decades of clinical documentation and classical text knowledge. Among digitally native specialists, Mamaearth exemplifies the Instagram-community archetype built on ingredient transparency storytelling rather than retail shelf presence. These three anchors represent the bifurcation between laboratory-substantiated legacy positioning and algorithm-driven customer acquisition.
| Leading Market Players |
|---|
| Mamaearth |
| Khadi Natural |
| Unilever |
| ITC |
| Wipro Consumer Care |
| Dabur |
| Biotique |
| Zicail |
| Himalaya |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 extraction substituting conventional solvent-based methods redraws supply geography toward German and Swiss specialty chemical suppliers while compressing commodity extract margins and elevating premium-tier pricing power for standardized botanical potency.
Pricing Analysis
Long-term offtake contracts with Maharashtra and Karnataka neem plantations anchor pricing for heritage-positioned brands, while spot-market lavender and sandalwood procurement exposes formulators to aromatherapy demand cycles. Three-tier pricing structure across laboratory-verified premium, BIS-compliant standard, and price-accessible economy levels separates brands by authentication capability. Cost compression in wild-harvested botanical inputs is intensifying because BIS traceability mandates accelerate plantation cultivation timelines. Rural Indian households exhibit highest price sensitivity, whereas boutique hospitality procurement teams absorb premium positioning for guest amenity specifications.
Supply Chain Analysis
Inventory lead times stretch 8-14 months for monsoon-dependent neem and tea tree oil harvests, forcing brands to carry buffer stocks through volatile growing seasons. Raw material sourcing concentrates in India, Australia, and Bulgaria for neem, tea tree oil, and lavender respectively. Formulation draws from essential oil extracts, surfactant bases, and pH stabilizers as core inputs. Single-source vulnerability in Maharashtra wild-harvesting exposes supply continuity to climate disruption. Distribution runs through modern trade chains, direct-to-consumer platforms, and Ayurvedic apothecaries with divergent traceability requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Herbal soap sits in early-cycle expansion as boutique hospitality amenity specifications and subscription-based direct-to-consumer channels extend penetration beyond traditional pharmacy and grocery distribution.
For Market Incumbents: Fortify supply chain control through captive neem plantation contracts in Karnataka and backward integration into cold-process saponification capacity. Invest in dual BIS-REACH certification documentation to outpace smaller competitors facing overlapping testing protocol incompatibilities. Channel control through blockchain-traceable retail partnerships filters out legacy suppliers with paper-based systems. For New Entrants and Emerging Players: Differentiate on laboratory-verified ingredient fingerprinting rather than heritage positioning alone. Target tier-two Indian cities where Ayurvedic knowledge validates premium pricing but laboratory-substantiated claims remain scarce. Deploy Instagram-native community building with farm-to-shelf transparency storytelling to bypass retail slotting fees. For Investors and Strategic Acquirers: Secondary-cycle assets sit with digitally native direct-to-consumer specialists possessing subscription algorithms and skin-type matching capabilities but lacking captive botanical sourcing. Five-to-ten year viability hinges on regulatory compliance moats deepening around authentication infrastructure. Watch for ECHA allergen candidate list expansions triggering reformulation cost spikes as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Plantation Cultivation | Maharashtra and Karnataka neem contracts secure supply continuity against wild-harvest volatility. |
| Dual Certification Investment | Simultaneous BIS Ayurvedic and EU REACH compliance creates market access barriers for undercapitalized rivals. |
| Supercritical CO2 Extraction Partnership | German and Swiss specialty chemical suppliers enable standardized terpene isolation without thermal degradation. |
| Blockchain Traceability Integration | Farm-to-shelf digital logging satisfies modern trade chain mandates in Delhi NCR and Pune. |
| Direct-to-Consumer Platform Launch | Subscription algorithms with skin-type matching capture urban millennial households in Mumbai and Bangalore. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of BIS regulatory filings, ECHA substance registrations, customs trade data, and Ayurvedic cosmetics industry associations. Conversations with formulation chemists, procurement managers at boutique hospitality chains, retail category buyers, supply chain directors at heritage brands, and specialty chemical supplier technical leads informed demand and competitive dynamics. Bottom-up volume modeling triangulates against top-down value projections from trade flow analysis.
Segmentation dimensions modeled span product type, key ingredient, packaging format, and distribution channel across the projection horizon. CAGRs derive from trend extrapolation of laboratory verification adoption, regulatory compliance cost trajectories, and channel shift velocities. Forecast inputs incorporate cold-process saponification capacity expansion timelines and supercritical CO2 extraction technology diffusion curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of BIS and REACH disclosure requirements would require recalibration. Forecasts reflect assumptions around monsoon pattern stability and essential oil input cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Thailand Skin Care Products Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
Halal Cosmetics Market
Cosmetics & Skincare
Natural Baby Skin Care Products Market
Cosmetics & Skincare
Deodorant Stick Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Tinted Cosmetics Market
Cosmetics & Skincare
BB Cream Market
Cosmetics & Skincare
Snail Beauty Products Market
Cosmetics & Skincare
Global Cosmetic Applicator Foam Market
Cosmetics & Skincare
Sun Care Products Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Israel Cosmetics Products Market
Cosmetics & Skincare
Vietnam Skin Care Products Market