
 Professional Scalp Care Products Market | 2026-2036
Professional Scalp Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Professional Scalp Care Products Market Insights
Dermatology clinics and medical spas are redrawing demand patterns in professional scalp care, pulling volume away from traditional salon-only distribution. L'Oreal Group leverages its dermatological heritage through La Roche-Posay to anchor credibility in clinical channels. Olaplex, Inc. differentiates via bond-building chemistry that sustains premium positioning among color-damaged scalp protocols. Kao Corporation dominates Japanese professional markets with salon-exclusive distribution controls.
Professional scalp care products comprise clinically formulated topical preparations designed for trichological assessment and treatment, typically incorporating active concentrations of piroctone olamine, salicylic acid, or botanical stem cell extracts at pH levels calibrated to scalp microbiome balance. These products serve licensed professionals performing diagnostic scalp analysis and therapeutic intervention beyond cosmetic cleansing. Shampoos and treatments capture the deepest margin pools where clinical efficacy claims command professional pricing power. Serums represent the fastest-expanding category as practitioners integrate leave-on actives into multi-session regimens. Conditioners remain mature in salon channels but gain traction in dermatology settings where barrier repair functions support post-procedure protocols.
REACH and the EU Green Deal mandate ingredient transparency and restrict certain preservative systems, forcing reformulation cycles that favor botanical and fermentation-derived actives. FDA oversight of cosmetic versus drug claims shapes how brands position scalp anti-dandruff and hair growth products across US professional channels. Stakeholders must monitor evolving classification boundaries between cosmetic scalp care and regulated dermatological therapeutics as professional practice scopes expand.
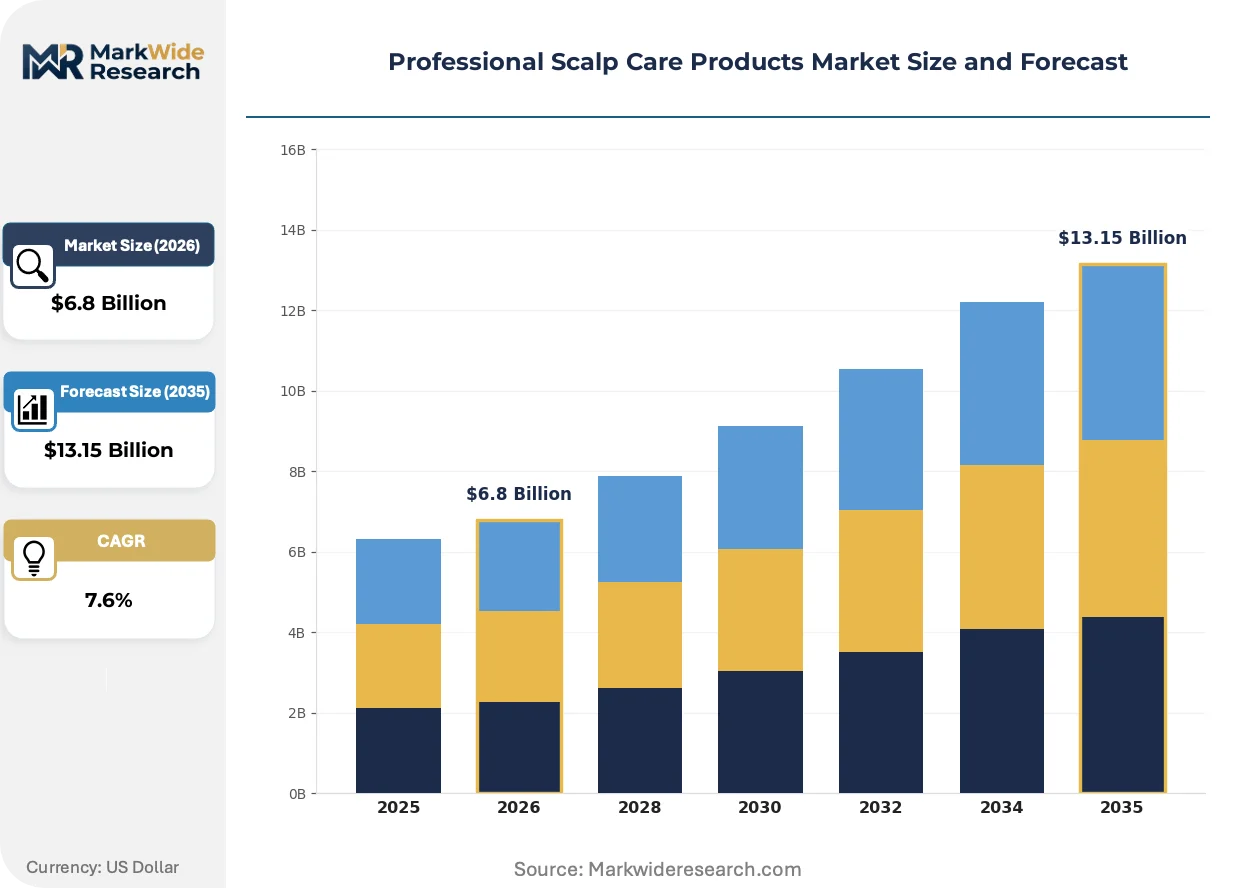
Market Dynamics
Clinical channel migration is restructuring professional scalp care distribution, as dermatology clinics and medical spas capture volume from traditional salon networks through diagnostic protocols and therapeutic positioning. This shift demands reformulation cycles and credentialing investments that favor science-backed brands.
Growth Catalysts
- REACH chemical disclosure mandates:EU Green Deal transparency requirements accelerate botanical and fermentation-derived active adoption, creating first-mover advantages for compliant formulators.
- Trichology salon chains:Germany's dedicated scalp wellness centers build professional education infrastructure that expands addressable practitioner bases.
- Scalp microbiome diagnostics:pH-calibrated topical systems enable personalized treatment protocols that justify premium professional pricing tiers.
Market Restraints
- Raw material concentration:Piroctone olamine and salicylic acid supply chains cluster in Asian chemical manufacturing hubs, exposing formulators to input volatility.
- Regulatory classification friction:FDA cosmetic-drug boundary ambiguity forces dual-track development for anti-dandruff and growth claims, extending time-to-market.
- Technical efficacy validation:Clinical substantiation requirements for professional channels demand dermatological testing budgets that exclude smaller entrants.
Strategic Opportunities
- Post-procedure dermatology protocols:Barrier repair conditioners gain traction in medical settings where scalp recovery following laser and injection treatments creates new prescription-adjacent positioning.
- Leave-on serum expansion:Multi-session regimens integrate concentrated actives into recurring revenue models that deepen practitioner relationships.
- Salon-digital hybrid education:Virtual trichology certification programs extend professional product access to stylists in underserved secondary markets.
Industry Challenges
- Trichologist certification scarcity:Licensed diagnostic practitioners remain concentrated in metropolitan clusters, limiting protocol rollout velocity.
- Legacy salon inventory systems:Professional scalp care SKUs require temperature-controlled storage and rotation management that conflicts with conventional backbar infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Professional Scalp Care Products Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Treatments, Serums End User: Salons, Individuals, Dermatologists, Spa Professionals Ingredient: Natural Extracts, Chemical Compounds, Oils, Botanicals Packaging Type: Bottles, Tubs, Sachets, Pumps |
| Companies Covered | L'Oreal Group, The Procter & Gamble Company, Unilever PLC, Beiersdorf AG, Kao Corporation, Shiseido Co., Ltd., The Estée Lauder Companies Inc., Aveda Corporation, Olaplex, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Professional Scalp Care Products Market Trends and Innovations
Biotechnology-derived actives and diagnostic integration are redefining efficacy standards in professional scalp care, compressing the gap between cosmetic treatment and clinical intervention. Formulation science now targets measurable microbiome outcomes rather than superficial conditioning benefits.
Botanical stem cell extracts are displacing synthetic anti-fungal agents in premium professional protocols. Medical spas in Germany and South Korea adopt these fermentation-derived systems for sensitive scalp presentations. The shift is compressing synthetic active margins while rewarding vertically integrated biotech suppliers with captive cultivation capacity.
REACH authorization procedures and EU Green Deal chemical restriction roadmaps force preservative system overhauls across European professional channels. Formulators face substance-by-substance re-evaluation timelines that extend 18-36 months. Salon-exclusive brands with established dermatological partnerships navigate this transition faster than mass-market professional lines.
Subscription-based professional replenishment models are capturing recurring revenue from independent stylists and small clinic chains. Traditional distributor-rep relationships face disintermediation as direct-to-practitioner platforms aggregate purchasing power. This pattern concentrates most visibly in Japanese and South Korean markets where salon software integration enables automated inventory forecasting.
Professional Scalp Care Products Market Segmentation
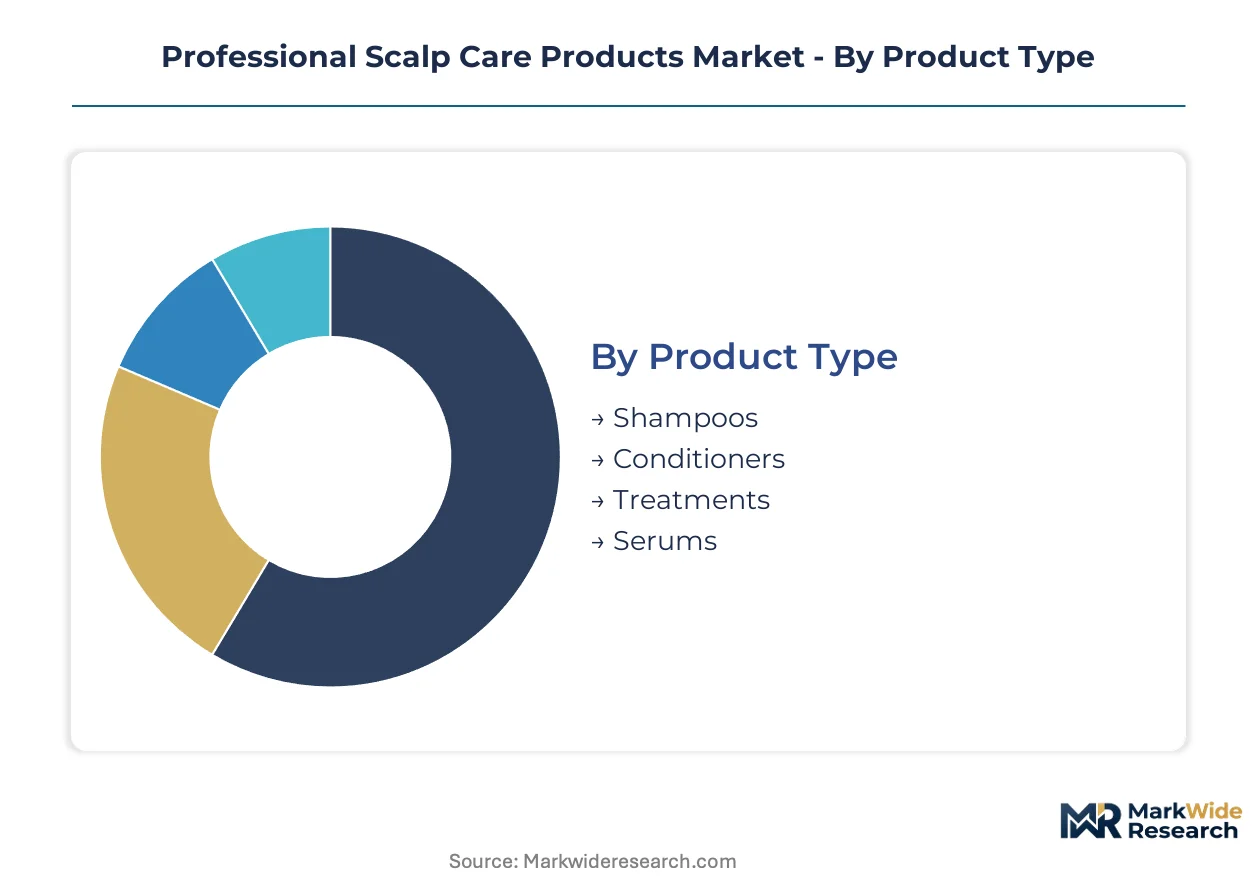
Professional scalp care segmentation reflects divergent efficacy standards across clinical and cosmetic channels. Product formulations, end-user protocols, and packaging systems each face distinct substitution pressures from over-the-counter alternatives and in-house salon blends.
Product Type:
Shampoos face the most acute substitution threat from retail masstige lines, while serums maintain protective moats through concentration-dependent delivery systems.
- Shampoos:Clinically formulated cleansing bases incorporate piroctone olamine or salicylic acid at microbiome-calibrated pH levels. Demand concentrates in German trichology chains where diagnostic protocols justify professional-only distribution against retail substitutes.
- Serums:Leave-on concentrates deliver stem cell extracts and fermentation-derived actives through sustained-release vehicles. Medical spas in Seoul and Frankfurt integrate these into multi-session regimens that lock in recurring professional purchase.
- Conditioners:Barrier repair formulations support post-procedure recovery protocols in dermatology settings.
- Treatments:Intensive topical systems address specific scalp pathologies beyond daily maintenance.
Shampoos retain volume leadership; serums hold the steepest expansion curve.
End User:
Channel cost structures segment the market, with dermatology clinics absorbing premium pricing for clinical substantiation while independent stylists face margin compression.
- Dermatologists:Licensed practitioners prescribe protocol-driven regimens with documented efficacy outcomes. Concentrated demand in US metropolitan clusters and German medical centers supports prescription-adjacent positioning.
- Salons:Traditional professional channels leverage stylist recommendation authority. Japanese salon-exclusive distribution controls through Kao Corporation demonstrate how captive supply agreements defend against retail diversion.
- Spa Professionals:Medical spas blend diagnostic technology with therapeutic positioning in South Korean and UAE wellness clusters.
- Individuals:Direct-to-consumer professional lines bypass credentialing requirements through virtual consultation platforms.
Dermatologists command the highest per-unit spend; spa professionals are climbing the fastest as medical aesthetics converges with scalp wellness.
Ingredient:
Raw material sourcing geography determines formulation flexibility, with fermentation-derived actives offering regulatory advantages under REACH authorization timelines.
- Botanicals:Plant stem cell extracts from dedicated cultivation facilities displace synthetic anti-fungals in premium European protocols. Vertical integration into captive bioreactor capacity rewards early movers.
- Natural Extracts:Cold-pressed seed oils and herbal concentrates serve sensitive scalp presentations. German medical spas prioritize these for patient populations with contact dermatitis histories.
- Chemical Compounds:Piroctone olamine and synthetic actives retain cost advantages in high-volume salon channels.
- Oils:Essential fatty acid blends support barrier function in post-procedure applications.
Botanicals capture the deepest margin pools; natural extracts are gaining share fastest as EU Green Deal restrictions accelerate.
Packaging Type:
Inventory velocity and storage requirements segment professional procurement, with temperature-sensitive actives demanding specialized logistics infrastructure.
- Pumps:Airless delivery systems preserve oxidation-sensitive actives in clinical settings. Demand clusters in dermatology practices where single-patient dispensing protocols reduce contamination risk.
- Bottles:Standard professional sizes dominate high-rotation salon backbars. Japanese software-integrated replenishment platforms automate forecasting for these SKUs.
- Sachets:Single-use formats support trial protocols and travel retail in premium spa channels.
- Tubs:Wide-mouth containers accommodate mask and treatment textures requiring spatula application.
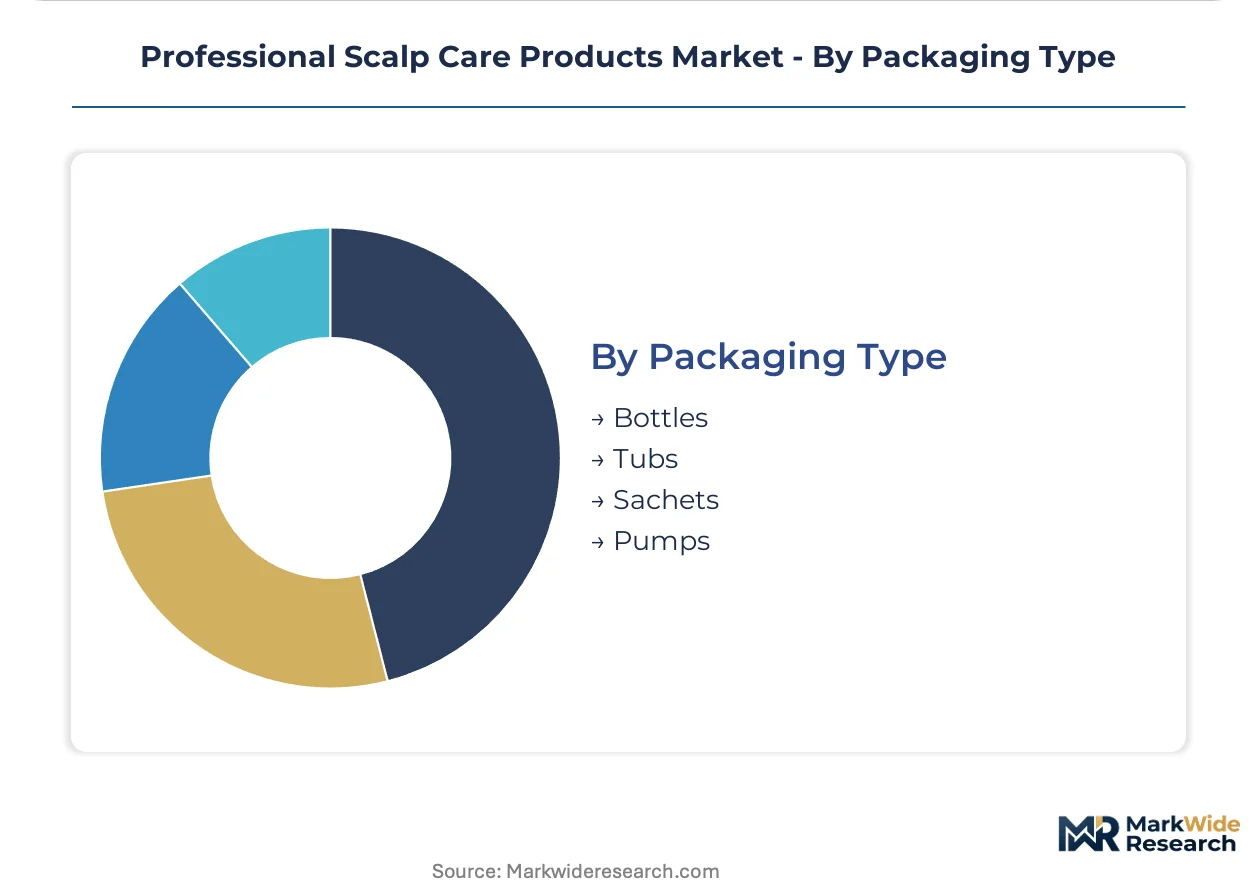
Bottles retain volume leadership; pumps hold the steepest expansion curve as clinical channel share rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for professional scalp care formulations, connecting German trichology centers to Asian active ingredient suppliers through direct rail links to the Rhine-Ruhr industrial corridor.
United States
FDA cosmetic-drug claim boundaries shape product positioning across dermatology clinics in New York and Los Angeles. The agency's enforcement discretion letters guide how anti-dandruff and growth formulations navigate professional channel classification. Boston's medical aesthetics corridor integrates scalp diagnostics into post-procedure wellness protocols.
Germany
REACH authorization timelines accelerate botanical active adoption across Frankfurt and Munich medical spas. ECHA substance-by-substance evaluations force preservative system overhauls that favor fermentation-derived alternatives. Düsseldorf's trichology salon chains build dedicated scalp wellness centers with practitioner certification infrastructure.
Japan
METI salon software integration standards enable automated inventory forecasting for professional backbar replenishment. Tokyo's Ginza and Shibuya districts concentrate medical spa adoption of pH-calibrated topical systems. Osaka's chemical manufacturing hubs supply piroctone olamine for regional formulators.
South Korea
MFDS cosmetic safety assessments govern how scalp microbiome claims enter professional channels in Seoul and Busan. The regulator's ingredient disclosure requirements align with EU Green Deal transparency standards. Gangnam's medical aesthetics cluster drives leave-on serum adoption in multi-session regimens.
United Arab Emirates
MOHAP cosmetic registration pathways determine market entry for clinical-grade scalp treatments in Dubai and Abu Dhabi. The regulator's halal certification requirements influence preservative system selection. Dubai Healthcare City's wellness infrastructure imports German and Korean professional protocols.
Professional Scalp Care Products Market Competitive Landscape
Listed leaders compete with private specialists across clinical credibility and salon distribution control, creating a tiered structure where dermatological heritage commands premium positioning. Consolidation pressures concentrate around regulatory compliance capabilities and captive bioreactor capacity for botanical actives. Three archetypes dominate: multinational beauty conglomerates with dermatology divisions, Japanese salon-exclusive specialists, and bond-chemistry innovators. Competitive moves center on M&A for diagnostic technology assets and backward integration into fermentation-derived active production.
Within the dermatology-channel tier, L'Oreal Group and Beiersdorf AG exemplify how European heritage anchors clinical credibility, while Kao Corporation occupies a position as the archetypal Japanese salon-exclusive operator. Olaplex, Inc. represents the bond-building chemistry specialist archetype that sustains premium positioning among color-damaged protocols.
| Leading Market Players |
|---|
| L'Oreal Group |
| The Procter & Gamble Company |
| Unilever PLC |
| Beiersdorf AG |
| Kao Corporation |
| Shiseido Co., Ltd. |
| The Estée Lauder Companies Inc. |
| Aveda Corporation |
| Olaplex, Inc. |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month lead times for piroctone olamine procurement from Asian chemical hubs compress margin buffers for European formulators facing REACH compliance deadlines, concentrating pricing power among vertically integrated suppliers with captive fermentation capacity.
Pricing Analysis
Volume-discount tiering separates salon-exclusive professional lines from mass-market alternatives through certification-grade differentiation. Premium clinical channels absorb higher per-unit costs for dermatological testing documentation, while independent stylists face margin compression from retail masstige substitution. Price erosion runs through standard salon tiers as software-integrated replenishment platforms aggregate purchasing power. Dermatology clinics demonstrate lowest price sensitivity due to protocol-driven reimbursement positioning.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes expose formulators to input volatility for microbiome-calibrated active ingredients. Piroctone olamine and salicylic acid production clusters in China, Japan, and South Korea, with botanical stem cell extraction capacity concentrating in German and South Korean bioreactor facilities. Single-source vulnerability persists for fermentation-derived actives under extended ECHA authorization timelines. Distribution runs through Port of Hamburg rail connections to Rhine-Ruhr industrial corridors serving Düsseldorf trichology chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
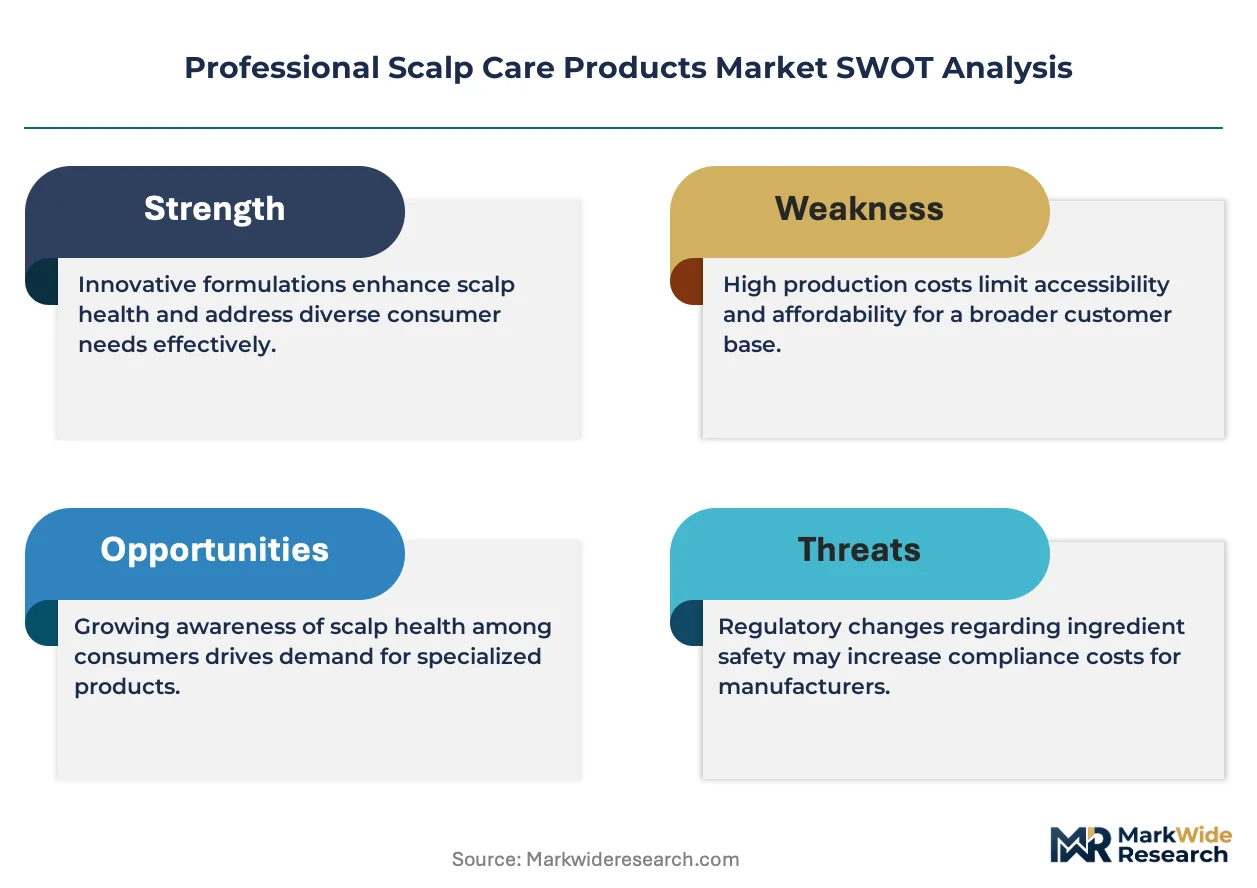
Professional scalp care sits at a high-growth inflection as scalp microbiome diagnostics compress the boundary between cosmetic treatment and clinical intervention, with EU Green Deal chemical restrictions accelerating botanical active adoption.
For Market Incumbents: Fortify regulatory compliance capabilities through backward integration into captive bioreactor capacity for fermentation-derived actives. Secure exclusive distribution controls with German trichology salon chains building dedicated scalp wellness centers. Invest in dermatological testing infrastructure to defend clinical channel positioning against retail masstige encroachment. For New Entrants and Emerging Players: EU REACH fast-track authorization for botanical preservatives offers entry pathway into premium European medical spa channels. Target post-procedure dermatology protocols in Boston and Frankfurt where barrier repair conditioners gain prescription-adjacent traction. Deploy virtual trichology certification platforms to access independent stylists in underserved secondary markets. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational beauty conglomerates divesting non-core professional divisions lacking dermatological credibility. Long-term viability hinges on diagnostic technology integration and captive active ingredient production. Watch for FDA enforcement discretion letters clarifying cosmetic-drug boundaries as inflection signal for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bioreactor Capacity | Captive fermentation-derived active production secures REACH compliance advantages for German formulators. |
| Virtual Trichology Certification Platform | Software-integrated education extends professional product access to stylists beyond metropolitan clusters. |
| Post-Procedure Protocol Development | Barrier repair positioning in Boston medical aesthetics corridors creates prescription-adjacent revenue streams. |
| Salon-Digital Hybrid Distribution | Direct-to-practitioner platforms disintermediate traditional distributor relationships in Japanese markets. |
| Diagnostic Technology Acquisition | pH-calibrated topical systems enable personalized treatment protocols justifying premium professional pricing. |
Research Methodology
A standing panel of trichology practitioners, dermatology clinic procurement managers, salon chain operators, and cosmetic formulation chemists provided ongoing calibration against secondary validation from ECHA substance evaluations, MFDS cosmetic safety assessments, METI software integration standards, and customs trade data for active ingredient flows. Bottom-up practitioner interviews triangulated with top-down regulatory filing analysis.
Consistency checks against external benchmarks validated volume and value outputs across product type, end-user channel, ingredient sourcing geography, and packaging format dimensions throughout the projection horizon. CAGRs derived from segmented demand modeling incorporating clinic expansion rates, salon software adoption curves, and REACH authorization timeline assumptions.
Underlying assumptions cover regulatory enforcement continuity and clinical channel migration velocity, with deviation risk concentrated in FDA cosmetic-drug classification shifts and raw material supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Waterproof Temporary Tattoo Sticker Market
Cosmetics & Skincare
Sun Care Products Market
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
Italy Lip Care Products Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Night Cream Market
Cosmetics & Skincare
Israel Cosmetics Products Market
Cosmetics & Skincare
Canada Cosmetic Products Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Asia-Pacific Halal Cosmetics Market
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Global Cosmetic Shea Butter Market
Cosmetics & Skincare
Cosmetic Mirror Market
Cosmetics & Skincare
Sweden Cosmetics Products Market