
 Global Cosmetic Jar Market | 2026-2036
Global Cosmetic Jar Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetic Jar Market Analysis
Packaging engineering talent is bifurcating between legacy injection-molding expertise and emerging bio-resin formulation skills, creating a talent gap that slows plant conversions in mature markets. Berry Global Group Inc. leverages its North American blow-molding infrastructure to sustain high-volume plastic jar output for mass-market skincare lines. Amcor Plc anchors its position through integrated recycling streams that supply post-consumer resin to cosmetic brands. Huhtamaki Oyj competes by specializing in fiber-based barrier coatings that replace conventional plastic jars for solid cosmetics.
A cosmetic jar is a rigid primary packaging container, typically cylindrical with a threaded neck or snap-fit finish, designed to hold semi-solid formulations such as creams, balms, and masks at volumes ranging from 5 milliliters to 500 milliliters. Glass jars dominate prestige fragrance and skincare segments where chemical inertness and premium heft justify higher unit costs, while plastic variants lead in body care and hair masking products where drop resistance and lightweight shipping reduce breakage losses. The closure type dimension shows screw caps maintaining volume leadership across all regions, though pump dispensers are gaining share in hygiene-conscious markets where finger-dip contamination concerns have intensified. Eco-friendly packaging design represents the fastest-expanding margin pool as brands reformulate jar substrates to meet emerging extended producer responsibility frameworks.
The FDA regulates cosmetic jar materials through 21 CFR guidelines for indirect food additives, while the EU REACH framework restricts phthalates and heavy metals in colored glass and plastic resins, forcing reformulation cycles among suppliers serving both markets. China's SAMR enforces GB standards for packaging migration limits that foreign jar manufacturers must certify before import clearance. Stakeholders must monitor how diverging recycled-content mandates across FDA, ECHA, and SAMR jurisdictions reshape material sourcing strategies and capital allocation for new molding equipment.
Market Dynamics
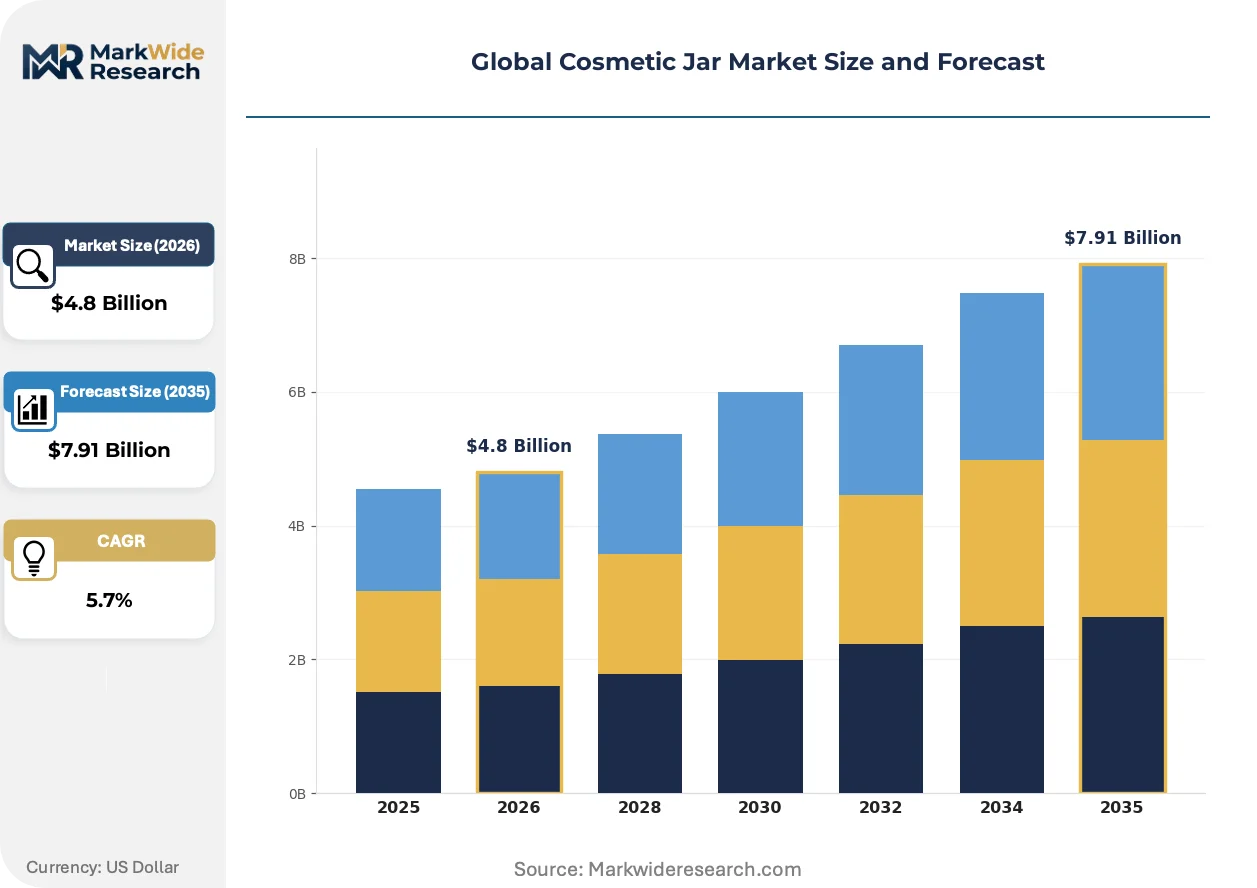
Post-consumer recycled content mandates under the EU Green Deal are forcing resin reformulation across cosmetic jar supply chains, compressing margins for converters while opening certification premiums for early adopters.
Growth Catalysts
- EU Green Deal recycled content mandates:Brands must source PCR resin for jars sold in Europe, creating guaranteed offtake for certified suppliers.
- Skincare balm texture innovation:Thicker, waterless formulations require jar packaging over tubes, expanding addressable volume for rigid containers.
- China domestic consumption concentration:Rising per-capita cosmetic spending in tier-two cities sustains jar demand for local heritage brands.
Market Restraints
- PCR resin supply concentration:Food-grade recycled polypropylene remains scarce in North America, limiting jar production scale-up for mass-market lines.
- REACH heavy metal restrictions:Cobalt and cadmium limitations in colored glass force reformulation of signature brand hues, extending R&D cycles.
- Flexible pouch substitution:Stand-up pouches with dispensing fitments capture hair mask volume previously held by plastic jars.
Strategic Opportunities
- India BIS certification gap:Domestic jar production l behind import quality standards, creating localization openings for molders meeting pharmaceutical-grade specs.
- Solid cosmetic bar migration:Shampoo and conditioner bars require fiber-based jar alternatives, expanding Huhtamaki's barrier coating addressable market.
- SAMR import clearance acceleration:Streamlined GB standard certification for foreign jar manufacturers reduces time-to-shelf for premium European glass entrants.
Industry Challenges
- Bio-resin formulation expertise scarcity:Packaging engineers with both polymer science and cosmetic compatibility knowledge command premiums that slow plant conversions.
- Multi-jurisdiction compliance stacking:Simultaneous FDA indirect food additive, REACH SVHC, and SAMR migration testing extends certification timelines by eight to fourteen months.
- Legacy injection-molding asset stranding:Conventional equipment lacks temperature precision for PLA and PHA processing, forcing capital-intensive retooling decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetic Jar Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Metal, Bamboo Closure Type: Screw Cap, Flip Top, Pump Dispenser, Snap On End User: Retail, E-commerce, Wholesale, Direct Sales Packaging Design: Custom, Standard, Eco-friendly, Luxury |
| Companies Covered | Berry Global Group Inc., Huhtamaki Oyj, Albea Cosmetics America Inc., Cosmopak Corp., Sonoco Products Company, Amcor Plc, Libo Cosmetics Co. Ltd., Graham Packaging Company, Aptar Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetic Jar Market Emerging Trajectories
Material science breakthroughs and regulatory stringency are converging to redefine cosmetic jar substrate selection, with sustainability credentials now determining shelf placement rather than merely supporting brand storytelling.
Mono-material polypropylene jars with integrated in-mold labels are displacing multi-component constructions that previously combined incompatible resins. Premium skincare brands in South Korea and Germany have adopted these designs at scale since 2023. This shift is compressing demand for separate label substrates and adhesive systems while simplifying end-of-life sorting for municipal recycling streams.
REACH Annex XVII restrictions on intentionally added microplastics extend to glitter and exfoliant-bearing jars, forcing reformulation of decorative container finishes. The regulation's industrial consequence is a pivot toward mineral-based pearlescent coatings. Decorative jar segments serving color cosmetics are most affected, with Italian and French suppliers accelerating ceramic-print transfer investments to maintain visual differentiation.
Direct-to-consumer refill subscription models are restructuring primary packaging economics, with brands retaining jar ownership and consumers purchasing formulation inserts. This pattern concentrates in North American clean beauty verticals where return logistics infrastructure exists. The operational burden shifts to jar durability engineering and reverse supply chain hygiene protocols rather than unit cost minimization.
Global Cosmetic Jar Market Segmentation
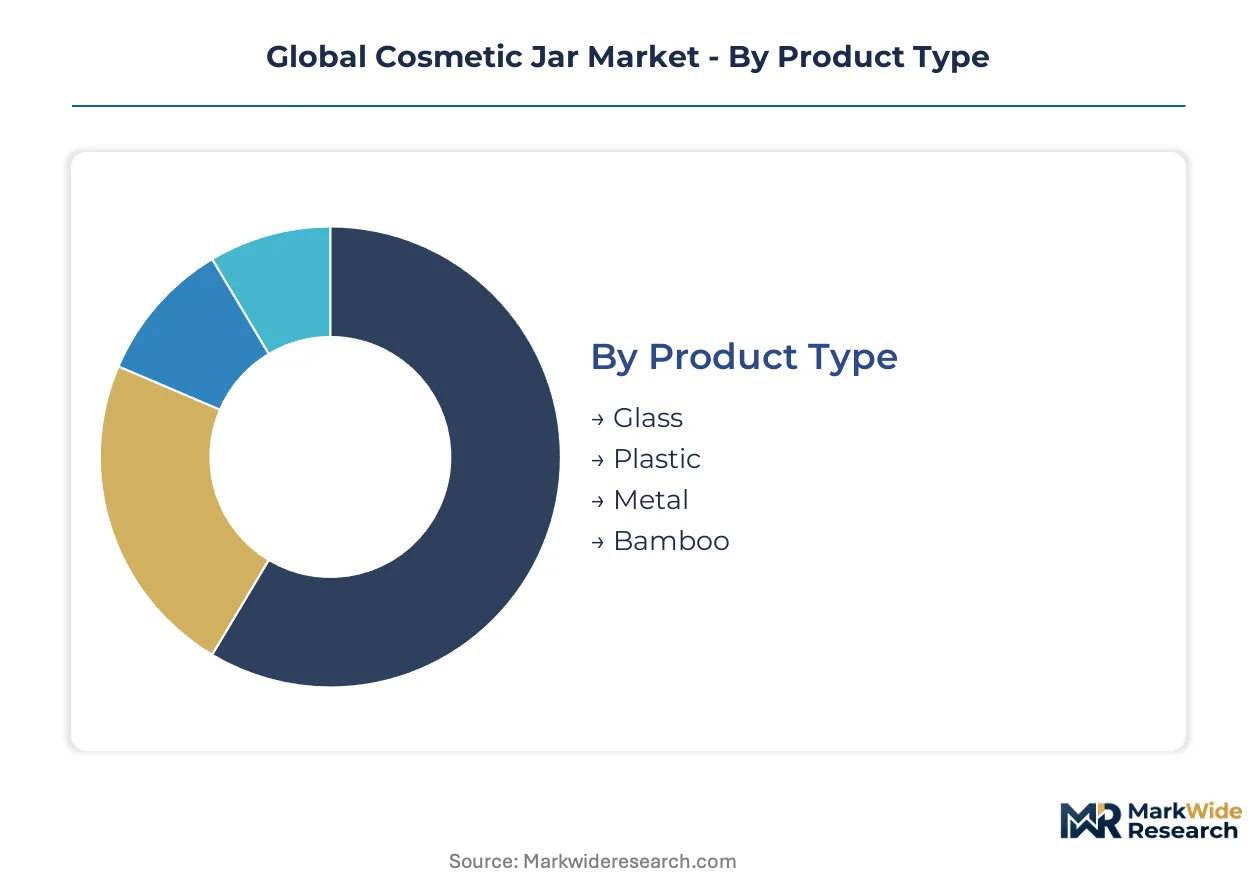
Cosmetic jar purchasing flows through distinct channel pathways that reshape which material and closure specifications dominate. Understanding these channel-material pairings reveals where margin pools concentrate and where supply constraints pinch hardest.
Product Type:
Channel mix splits sharply between prestige retail counters favoring heavier substrates and e-commerce fulfillment demanding drop-resistant lightweighting.
- Glass:Borosilicate and soda-lime formulations deliver chemical inertness for retinol and acid-based skincare. Demand concentrates in German and French prestige fragrance houses where counter heft signals quality, though EU carbon border adjustments threaten air-freighted glass economics.
- Plastic:Polypropylene and PET variants dominate body care and hair masking segments shipped through Amazon and Tmall fulfillment centers. South Korean brands are accelerating mono-material PP adoption to preempt EPR sorting failures.
- Metal:Aluminum tins serve solid perfume and balm formats in zero-waste retail channels. The substrate appeals to refill subscription operators seeking dent resistance through reverse logistics cycles.
- Bamboo:Laminated grass-fiber composites target clean beauty verticals in California and Nordic markets. SAMR import hurdles for organic coatings limit China penetration despite raw material abundance.
By volume, Plastic leads. By growth pace, Bamboo is expanding most quickly.
Closure Type:
Cost tier stratification separates mass-market commodity closures from precision-engineered dispensing systems commanding 4-8x unit premiums.
- Screw Cap:Threaded polypropylene closures remain the default for jar formats above 100 milliliters. Indian domestic manufacturers are capturing share from Chinese molders as BIS certification timelines compress.
- Flip Top:Hinged polyethylene designs serve single-hand access scenarios in hair masking and body scrub applications. The format sacrifices seal integrity versus screw threads, limiting adoption for active-ingredient skincare.
- Pump Dispenser:Airless piston systems with jar-integrated pumps are gaining share in Japanese and US hygiene-conscious markets where finger-dip contamination concerns have intensified. METI guidance on preservative reduction accelerates this shift.
- Snap On:Press-fit closures dominate sample and travel-size jars under 30 milliliters. The format enables automated capping lines that reduce per-unit labor costs for promotional volumes.
By installed base, Screw Cap dominates. By margin expansion, Pump Dispenser is climbing the fastest.
End User:
Customer type determines order fragmentation, with wholesale buyers consolidating SKUs and direct sales fragmenting into micro-batches.
- Retail:Department store and specialty beauty chains demand MOQs above 50,000 units with color-matched batch consistency. Sephora and Douglas specifications now mandate 30% PCR content for plastic jar listings.
- E-commerce:Direct-to-consumer brands order 5,000-15,000 unit runs with rapid design iteration cycles. The channel favors unprinted stock jars with sleeve labels enabling seasonal pivots without mold retooling.
- Wholesale:Professional salon and spa distributors prioritize 500-milliliter bulk formats with pump closures. The segment tolerates longer lead times in exchange for 40-60% unit cost reductions versus retail equivalents.
- Direct Sales:Avon and Oriflame-style networks require jar durability through repeated demonstration handling. The channel specifications emphasize scratch-resistant surface finishes over substrate sustainability credentials.
By revenue concentration, Retail leads. By order velocity, E-commerce is gaining share fastest.
Packaging Design:
Margin structure separates specification tiers where certification premiums attach to verified sustainability claims versus undifferentiated commodity supply.
- Custom:Proprietary mold investments with exclusive surface textures and dimensional signatures. L'Oréal and Estée Lauder deploy these for franchise product lines where shelf recognition drives repurchase.
- Standard:Catalog-off-the-shelf dimensions minimizing mold capex for launch-phase brands. The tier concentrates among Korean and Chinese indie beauty entrants testing market response before custom commitments.
- Eco-friendly:Ocean-bound plastic, post-consumer glass, and carbon-neutral aluminum certified to EMAS or Cradle to Cradle standards. EU Green Deal procurement mandates are guaranteeing offtake for verified suppliers.
- Luxury:Crystal glass, zamak metal overcaps, and lacquered finishes with hand-assembly components. The segment concentrates in Swiss and Italian fragrance houses where unit economics absorb 12-20x material cost multiples.
By volume, Standard leads. By margin expansion, Eco-friendly is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR certification requirements for GB standard compliance dominate import pathways into China, the world's largest cosmetic consumption geography. Divergent recycled-content mandates across FDA, ECHA, and SAMR jurisdictions force material sourcing strategies that vary sharply by destination market.
China
Domestic heritage brands in tier-two cities drive jar demand for premium creams and balms. SAMR enforces GB standards for packaging migration limits that foreign manufacturers must certify before import clearance. Shanghai and Guangzhou clusters host molders scaling mono-material PP production to preempt EPR sorting failures.
United States
Clean beauty verticals concentrate refill subscription models in California and New York Metro, restructuring primary packaging economics. FDA regulates jar materials through 21 CFR guidelines for indirect food additives. Pacific Northwest logistics infrastructure supports reverse supply chains for jar durability cycling.
Germany
Prestige fragrance houses demand borosilicate and soda-lime glass where counter heft signals quality. EU Green Deal recycled content mandates force resin reformulation across supply chains. Baden-Württemberg and North Rhine-Westphalia host converters capturing certification premiums for early PCR adoption.
South Korea
Skincare brands accelerate mono-material polypropylene jar adoption with integrated in-mold labels. METI guidance on preservative reduction accelerates airless pump dispenser share gains. Seoul Capital Area molders lead decorative finish innovation as REACH Annex XVII restricts intentionally added microplastics.
India
Domestic jar production lags behind import quality standards, creating localization openings for pharmaceutical-grade molders. BIS certification timelines compress as Indian manufacturers capture share from Chinese suppliers. Maharashtra and Gujarat clusters scale threaded polypropylene closure output for regional body care lines.
Global Cosmetic Jar Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in blow-molding infrastructure and integrated recycling streams. The middle layer fragments across regional molders serving mass-market lines with catalog-off-the-shelf specifications. Three archetypes dominate: resin-integrated conglomerates with captive PCR supply, mono-material specialists capturing EPR-compliant share, and fiber-based barrier coating innovators displacing conventional plastic. Competitive moves center on backward integration into post-consumer resin sorting and technology licensing for bio-resin processing precision.
Among North American resin-integrated players, Berry Global Group Inc. and Graham Packaging Company occupy positions defined by high-volume plastic jar output and mass-market skincare line relationships. European specialists Amcor Plc and Huhtamaki Oyj exemplify divergent sustainability pathways—one anchored through integrated recycling streams supplying post-consumer resin, the other competing via fiber-based barrier coatings for solid cosmetic formats. These four names represent the competitive spectrum from scale-driven PCR certification to substrate substitution innovation.
| Leading Market Players |
|---|
| Berry Global Group Inc. |
| Huhtamaki Oyj |
| Albea Cosmetics America Inc. |
| Cosmopak Corp. |
| Sonoco Products Company |
| Amcor Plc |
| Libo Cosmetics Co. Ltd. |
| Graham Packaging Company |
| Aptar Group Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day resin certification lead times for EU Green Deal compliance concentrate pricing power among pre-certified molders while squeezing converters without backward integration into post-consumer resin sorting. This inventory-to-certification lag separates premium-tier suppliers commanding certification markups from mass-market players absorbing margin compression.
Pricing Analysis
Geographic price spreads of 15-25% separate German glass converters serving prestige fragrance houses from Indian polypropylene molders supplying regional body care lines. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with EU EMAS-verified eco-friendly jars commanding 40-60% premiums over undifferentiated catalog stock. Cost compression in mass-market plastic tiers is intensifying because food-grade recycled polypropylene scarcity forces virgin resin substitution. E-commerce direct-to-consumer brands exhibit highest price sensitivity, while Swiss and Italian fragrance houses absorb 12-20x material cost multiples for luxury crystal and zamak finishes.
Supply Chain Analysis
Just-in-time resin procurement dominates European converters responding to EU Green Deal mandate volatility, while Chinese molders maintain strategic stockpiles of virgin polypropylene to buffer GB standard certification delays. Supply concentrates in China, Germany, and South Korea for molded jar output, with raw material dependencies on Saudi and Qatari polypropylene feedstock, Belgian soda-lime glass batch, and Malaysian bamboo fiber laminates. Single-source vulnerability to REACH Annex XVII reformulation cycles for cobalt and cadmium-free colored glass poses structural risk. Distribution runs through Sephora and Douglas retail procurement for prestige tiers, Alibaba and Amazon fulfillment centers for mass-market e-commerce, and regional salon distributors for professional bulk formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-resin formulation expertise with simultaneous polymer science and cosmetic compatibility knowledge commands wage premiums that slow plant conversions, creating a bottleneck that reshapes competitive timelines across substrate transitions.
For Market Incumbents: Compound backward integration into post-consumer resin sorting to secure PCR certification ahead of EU Green Deal enforcement waves. Add blow-molding capacity in Baden-Württemberg or North Rhine-Westphalia to capture German prestige fragrance demand while preempting carbon border adjustment penalties on air-freighted glass. Defend against Huhtamaki's fiber-based barrier coating substitution by accelerating mono-material PP adoption with integrated in-mold labels. For New Entrants and Emerging Players: SAMR GB standard fast-track certification for foreign manufacturers creates entry velocity for premium European glass entrants into Shanghai and Guangzhou clusters. Target India's BIS certification gap where domestic jar production lags pharmaceutical-grade specifications, enabling localization capture from Chinese suppliers. Pursue solid cosmetic bar packaging as the most penetrable white-space, leveraging fiber-based jar alternatives for shampoo and conditioner formats in California clean beauty verticals. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underutilized blow-molding assets stranded by PLA and PHA temperature precision requirements. Five-to-ten-year viability hinges on converters with captive PCR supply chains and EPR-compliant mono-material capabilities. Watch for inflection when EU Green Deal recycled content mandates tighten beyond current 30% thresholds, triggering consolidation among uncertified mid-tier molders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PCR Sorting | Captive post-consumer resin supply secures EU Green Deal certification premiums ahead of mandate enforcement. |
| Mono-Material PP Conversion | In-mold label integration simplifies EPR sorting compliance for South Korean and German skincare brands. |
| SAMR Certification Fast-Track | Streamlined GB standard clearance reduces time-to-shelf for premium borosilicate glass entrants into China. |
| Solid Cosmetic Barrier Coating | Fiber-based jar alternatives capture shampoo and conditioner bar migration in Nordic and California markets. |
| India BIS Localization | Pharmaceutical-grade molding capacity addresses quality gap versus Chinese imports for regional body care lines. |
Methodological Framework
Operator-level perspectives from packaging plant managers, cosmetic brand procurement leads, regulatory affairs specialists at resin suppliers, and retail category buyers anchored the qualitative base. Primary interviews triangulated with secondary validation from FDA 21 CFR filings, ECHA REACH SVHC updates, SAMR GB standard notifications, and customs trade data tracking polypropylene and glass jar import flows. Bottom-up volume modeling across material substrates and closure types converged with top-down market sizing from converter capacity disclosures.
Sensitivity analysis tested forecast robustness across PCR resin availability scenarios and REACH restriction timelines over the projection horizon. Segmentation dimensions modeled include material substrate, closure mechanism, end-user channel, and packaging design tier, with regional regulatory clusters capturing divergent FDA, ECHA, and SAMR compliance pathways. CAGRs derived from weighted average of historical volume trajectories and policy-driven demand shifts, incorporating METI preservative reduction guidance and EU carbon border adjustment implementation pace as industry-specific inputs.
Decision-makers should treat outputs as directional under base assumptions of steady EU Green Deal enforcement and stable China domestic consumption growth; material deviation in either would warrant model refresh. Revision becomes warranted when food-grade recycled polypropylene supply scarcity crosses thresholds that force widespread virgin resin substitution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
United Arab Emirates Cosmetic Products Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Body Cream Jars Market
Cosmetics & Skincare
Sun Care Products Market
Cosmetics & Skincare
Setting Spray Market
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
Global Cosmetic Antioxidant Market
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
Japan Organic Cosmetics Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
BB Cream Market
Cosmetics & Skincare
Massaging Cosmetic Applicators Market
Cosmetics & Skincare
South America Cosmetics Products Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Tea Based Face Masks Market