
 Zero-Waste Shampoo Market | 2026-2036
Zero-Waste Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Zero-Waste Shampoo Market Analysis
The EU Green Deal is expanding compliance obligations for cosmetic packaging across member states. Ethique leverages its New Zealand origins to anchor premium bar positioning in European specialty retail. HiBAR competes through concentrated solid formulations that eliminate plastic bottles entirely. Lush Retail Ltd. controls vertically integrated manufacturing and direct-store distribution networks across North America and Europe.
Zero-waste shampoo denotes solid bars, refillable liquids, or powdered concentrates formulated without synthetic surfactants or petroleum-derived packaging, typically comprising saponified oils, plant-based cleansers, and essential oil fragrances designed for scalp and hair cleansing without disposable containers. The bar segment dominates unit economics through minimal packaging and shipping weight advantages, while refill systems capture recurring revenue through aluminum bottle return programs. Biodegradable surfactant formulations lead material innovation as formulators replace sodium lauryl sulfate with gentler alkyl polyglucosides derived from coconut and corn sugars.
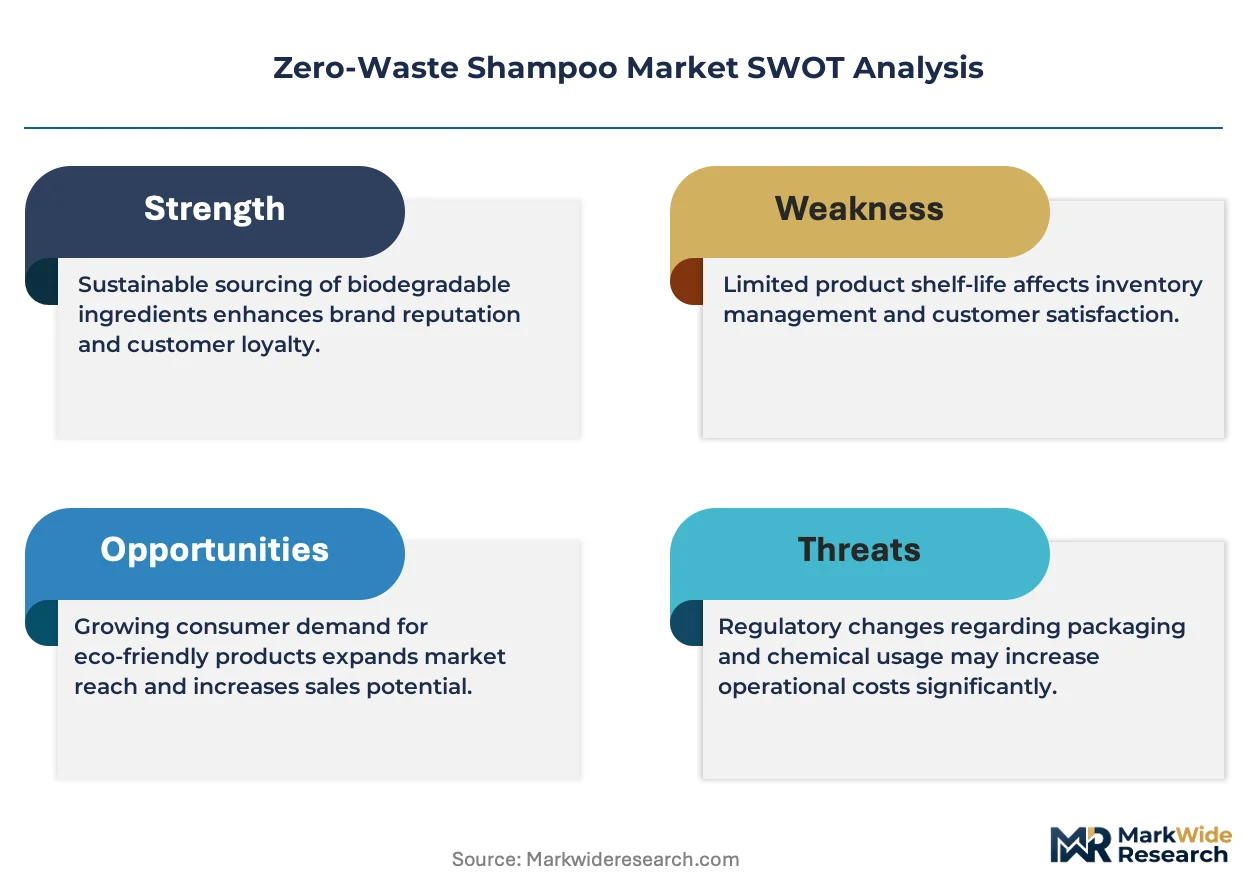
REACH in Europe governs chemical safety in cosmetic ingredients, while the FDA in the United States regulates cosmetic labeling claims and manufacturing practices under the Federal Food, Drug, and Cosmetic Act. The EU Packaging and Packaging Waste Directive mandates extended producer responsibility schemes that shift cost burdens toward brands using single-use materials. Stakeholders must monitor evolving state-level plastic bans in California and New York and assess whether solid-format production investments outpace refill infrastructure buildout in their target markets.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing the transition timeline for cosmetic brands, forcing simultaneous investment in solid-format manufacturing and refill infrastructure while consumer preference in urban corridors accelerates toward plastic-free alternatives.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Extended producer responsibility schemes shift cost burdens toward single-use packaging, incentivizing brands to eliminate disposable containers through solid bar or refillable formats.
- Alkyl polyglucoside surfactants:Coconut and corn sugar-derived cleansers replace sodium lauryl sulfate in biodegradable formulations, meeting ECHA safety standards while improving scalp tolerance profiles.
- German retail infrastructure:Munich and Berlin host dense networks of zero-waste specialty stores and bulk refill stations that normalize bar shampoo purchasing for mainstream consumers.
Market Restraints
- Raw material concentration:Coconut oil supply chains cluster in Southeast Asian processing hubs, exposing European formulators to price volatility and shipping cost spikes.
- Performance perception gaps:Solid bar formats face residual consumer skepticism regarding lather quality and hair type suitability compared to liquid alternatives.
- REACH compliance timelines:Novel plant-derived surfactants require extended safety dossier preparation, delaying product launches by 18-24 months versus conventional ingredients.
Strategic Opportunities
- French pharmacy channel:Dermocosmetic retail networks remain underpenetrated by zero-waste brands, offering premium positioning through dermatologist endorsement pathways.
- Subscription refill models:Aluminum bottle return programs generate recurring revenue streams while locking in customer lifetime value through automated replenishment.
- Powder concentrate technology:Waterless formulations reduce shipping weight by 80% and enable at-home dilution, opening direct-to-consumer logistics advantages.
Industry Challenges
- Formulation chemist scarcity:Expertise in saponification science and solid surfactant stabilization remains concentrated among legacy soap manufacturers, constraining R&D scaling.
- Dual-format manufacturing capex:Brands must fund parallel liquid compounding and solid bar pressing equipment during the transition window.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero-Waste Shampoo Market |
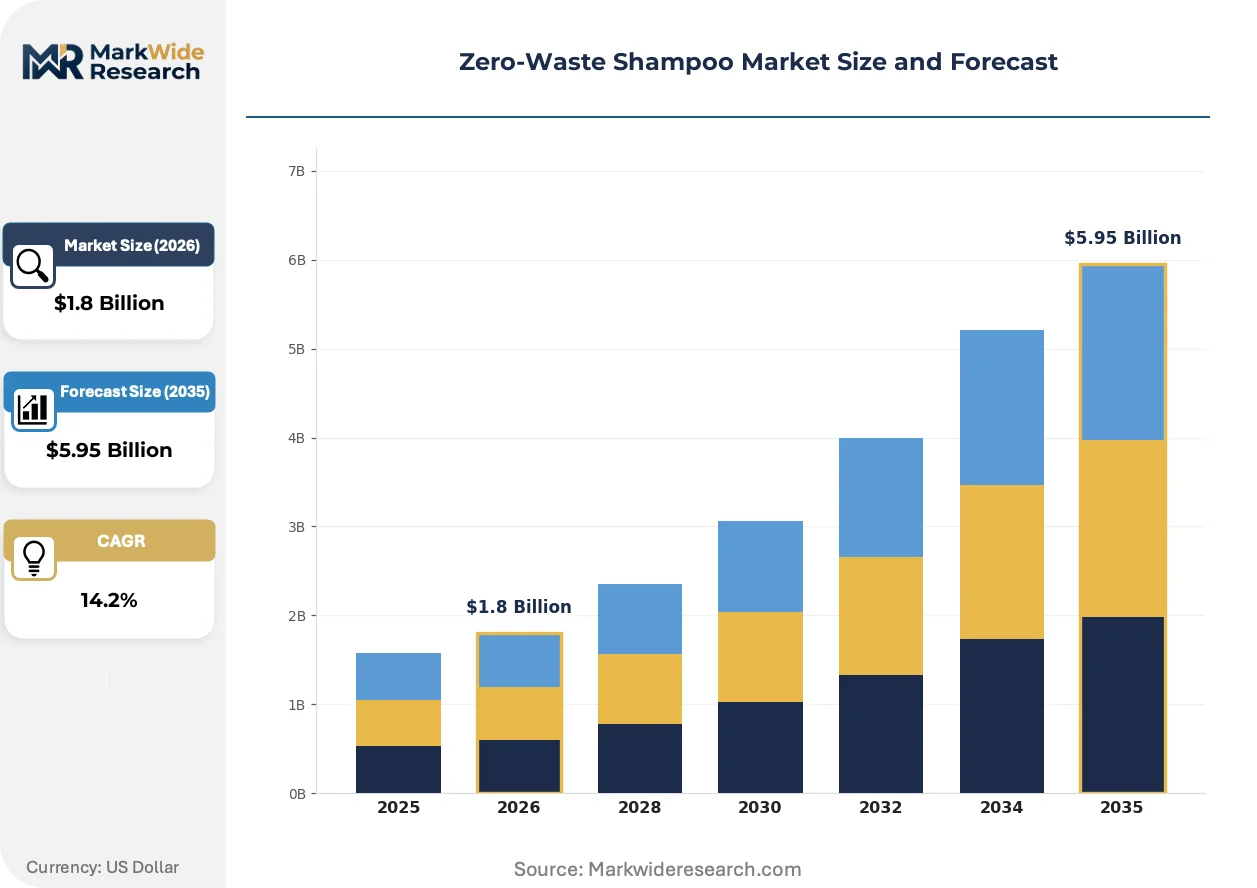
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Refills, Powders, Samples Material: Natural Ingredients, Organic, Biodegradable Surfactants, Essential Oils Consumer Type: Eco-Conscious Consumers, Millennials, Families, Salon Professionals Distribution Channel: Online, Specialty Stores, Pharmacies, Eco-Friendly Shops |
| Companies Covered | Ethique, HiBAR, Lush Retail Ltd., J.R. Liggett, Ltd, Plaine Products, Beauty and the Bees, Oregon Soap Company, Rocky Mountain Soap, The Refill Shoppe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero-Waste Shampoo Market Emerging Trajectories
Formulation chemistry is converging with packaging engineering as brands engineer products specifically for container-free distribution, while regulatory pressure compresses the viable timeline for plastic-dependent business models.
Biodegradable surfactant technology is converging with cold-process saponification methods to create solid bars that perform across hard and soft water conditions without synthetic stabilizers. Boutique hotels in Scandinavian markets are adopting these formulations for amenity programs. The convergence is compressing the performance gap between natural and conventional cleansers, forcing liquid incumbents to accelerate bar-format development.
REACH authorization requirements for novel cosmetic ingredients are tightening dossier standards for plant-derived alternatives, extending pre-market approval timelines. Formulators are responding by prioritizing existing INCI-listed ingredients with established safety profiles. Small and mid-sized brands face disproportionate compliance burdens relative to multinational resource bases.
Urban consumers are shifting toward refill station purchasing, carrying personal containers to neighborhood bulk retailers rather than buying pre-packaged units. This pattern disrupts traditional supermarket and pharmacy distribution in metropolitan France and Benelux corridors. Independent zero-waste retailers capture margin previously allocated to packaging and brand marketing spend.
Zero-Waste Shampoo Market Segmentation
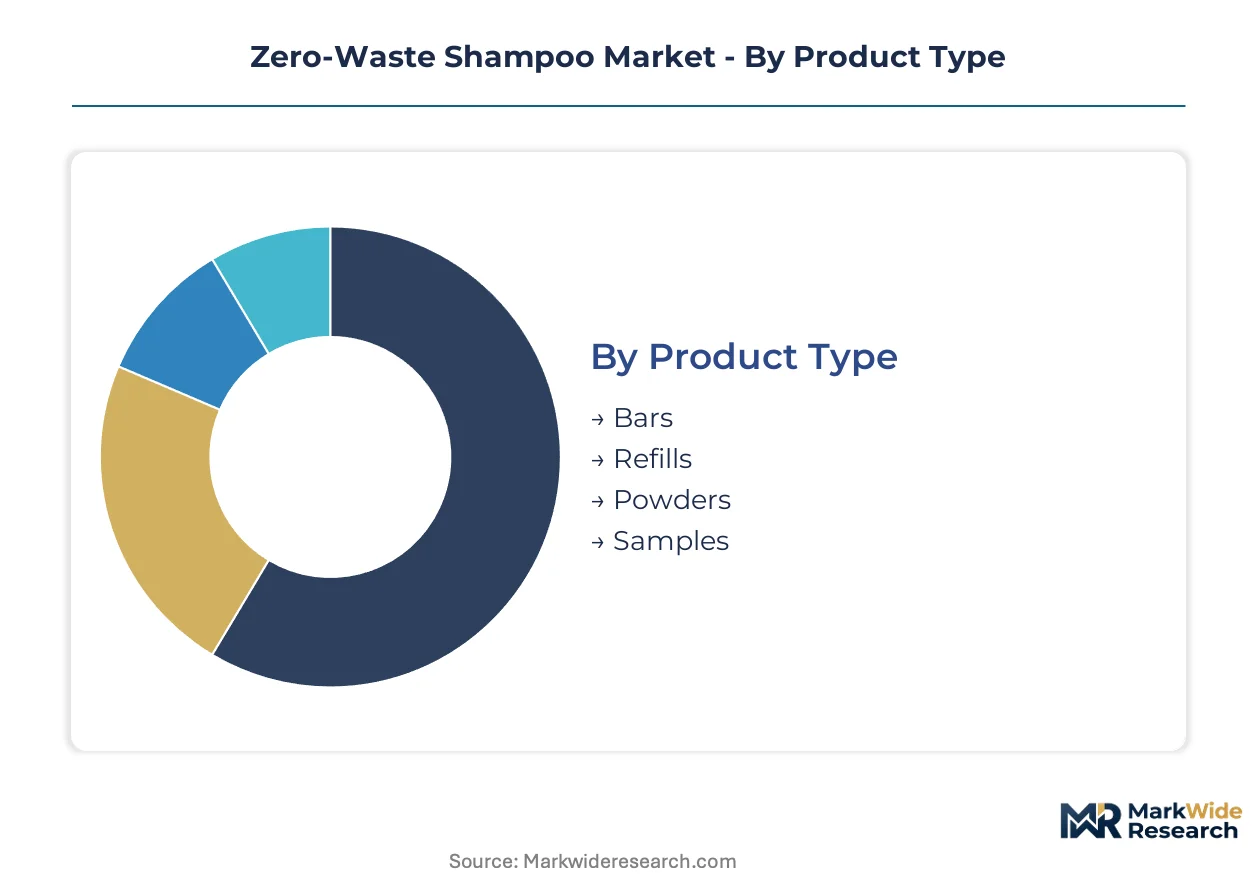
Zero-waste shampoo brands engineer distinct product architectures to capture consumers at different stages of plastic-free transition. Each segment demands specialized formulation chemistry and distribution infrastructure that shapes capital allocation and margin profiles.
Product Type:
Consumers upgrade from liquid bottles through graduated format transitions, with each product type requiring different manufacturing equipment and retail partnerships.
- Bars:Solid formulations combine saponified coconut and olive oil bases with alkyl polyglucoside surfactants, pressed into 80-120 gram units that eliminate packaging entirely. Demand concentrates in German urban corridors where refill station density normalizes bar purchasing for mainstream households, though hard water compatibility remains a formulation constraint in limestone regions.
- Refills:Concentrated liquid or paste formulations packaged in aluminum return bottles or compostable pouches for at-home dilution. Salon professionals in France drive commercial adoption through backbar bulk purchasing, attracted by per-wash cost advantages over pre-bottled alternatives.
- Powders:Waterless concentrates comprising dry surfactant blends and botanical extracts that activate with tap water. Direct-to-consumer channels in the United Kingdom favor this format for shipping weight reduction.
- Samples:Trial-size bars or single-use powder sachets designed for first-time conversion from conventional liquids. Eco-friendly shops in Scandinavian markets deploy these for low-risk customer acquisition.
Bars sit at the top of the volume ranking, with powders climbing the fastest.
Material:
Raw material sourcing strategy separates premium positioning from mass-market penetration, with certification tiers determining pharmacy access versus supermarket placement.
- Natural Ingredients:Plant-derived cleansers including soap nuts, shikakai, and reetha extracts formulated without synthetic preservatives. German consumers prioritize this category for scalp sensitivity concerns, though batch consistency challenges constrain scale.
- Organic:Certified organic oils and botanicals meeting ECOCERT or Soil Association standards with full supply chain traceability. French pharmacy channels require this certification for shelf placement, creating a margin premium over conventional natural claims.
- Biodegradable Surfactants:Alkyl polyglucosides and other sugar-derived cleansers that degrade within 28 days in aquatic environments. REACH dossier requirements for novel surfactants extend development timelines.
- Essential Oils:Fragrance and functional ingredients from steam-distilled plant material, replacing synthetic perfumes. UK consumers show preference for lavender and tea tree profiles.
Natural ingredients dominate current volume, with biodegradable surfactants expanding most quickly as formulators replace sodium lauryl sulfate.
Consumer Type:
Customer lifetime value varies sharply across demographic segments, with professional channels offering recurring bulk purchases versus household trial-and-error patterns.
- Eco-Conscious Consumers:Primary adopters who prioritize plastic elimination over performance metrics, typically urban dwellers with access to zero-waste retail infrastructure. Berlin and Amsterdam host dense concentrations.
- Millennials:Digital-native buyers purchasing through subscription models and social commerce, sensitive to ingredient transparency and brand storytelling.
- Families:Multi-person households seeking cost-efficient bulk formats with gentle formulations for children. Refill systems capture this segment through volume discounts.
- Salon Professionals:Licensed hairdressers purchasing backbar quantities for client services, requiring consistent lather performance across water hardness variations.
Eco-conscious consumers anchor current revenue, with salon professionals gaining share fastest as wholesale distribution matures.
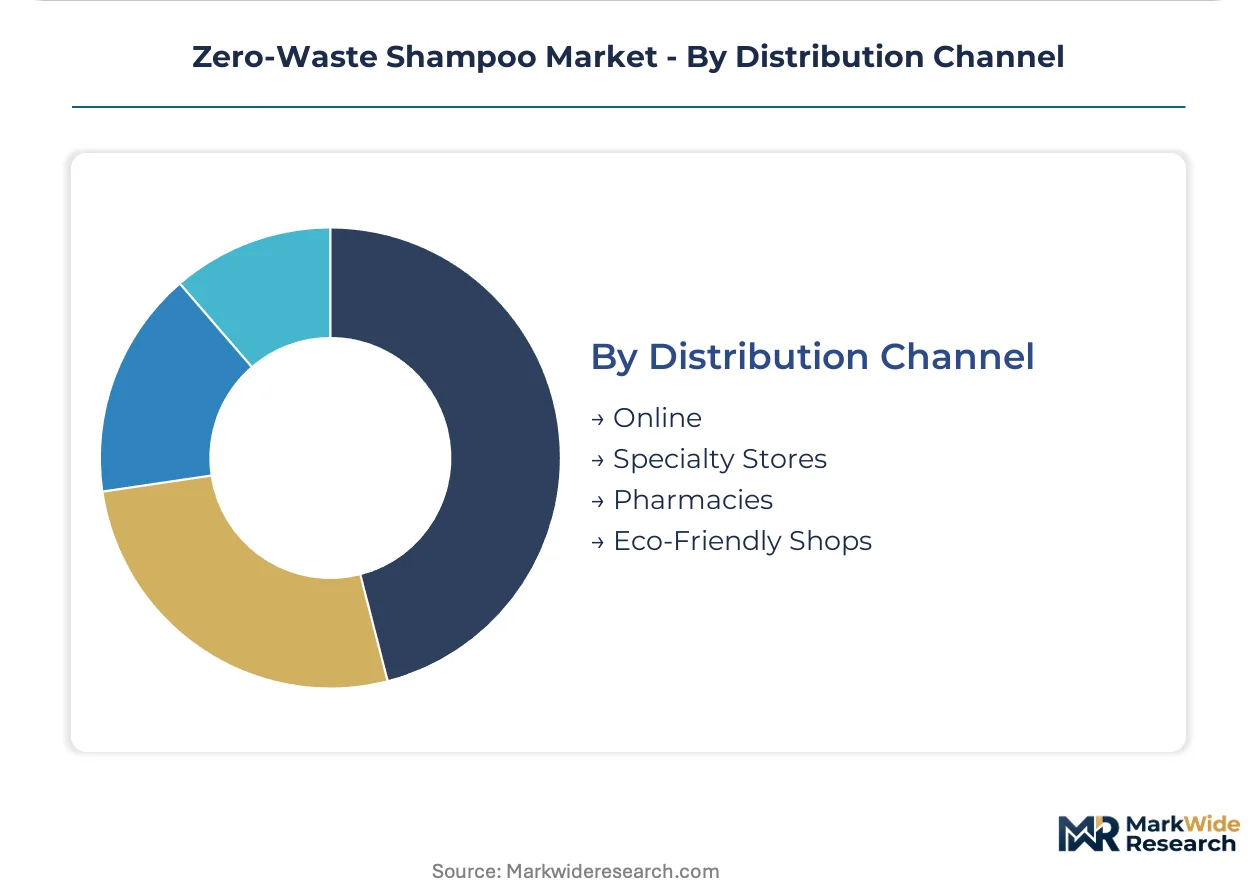
Distribution Channel:
Channel selection determines margin capture versus customer education burden, with each route demanding distinct packaging and merchandising investments.
- Online:Direct-to-consumer and marketplace sales enabling subscription replenishment and educational content delivery. Powder concentrates exploit this channel for shipping efficiency.
- Specialty Stores:Independent zero-waste retailers offering bulk refill stations and bar sampling. French and Belgian urban corridors sustain the densest store networks.
- Pharmacies:Dermocosmetic retail requiring dermatological testing and regulatory dossiers. Underpenetrated by zero-waste brands despite premium pricing tolerance.
- Eco-Friendly Shops:Sustainability-focused chains and cooperatives with established plastic-free customer bases. Scandinavian markets show highest per-store throughput.
Online channels lead transaction volume, with pharmacies expanding most rapidly as brands invest in dermocosmetic certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with saponification expertise cluster in German industrial regions and New Zealand's specialty manufacturing zones, anchoring production capacity for solid-format innovation.
Germany
Munich and Berlin host dense networks of zero-waste specialty stores and bulk refill stations normalizing bar shampoo purchasing for mainstream consumers. The EU Packaging and Packaging Waste Directive mandates extended producer responsibility schemes shifting cost burdens toward single-use materials. Bavaria's chemical processing corridor near Leverkusen concentrates surfactant R&D facilities developing alkyl polyglucoside alternatives to sodium lauryl sulfate.
France
Dermocosmetic retail networks in Paris and Lyon remain underpenetrated by zero-waste brands despite premium pricing tolerance from pharmacy customers. REACH authorization requirements for novel cosmetic ingredients tighten dossier standards for plant-derived alternatives. The Île-de-France region houses regulatory consulting firms specializing in ECOCERT organic certification pathways for cosmetic entrants.
United Kingdom
Direct-to-consumer channels favor powder concentrate formats for shipping weight reduction, particularly in London and Manchester urban corridors. The country's national pharmaceutical regulator enforces cosmetic labeling standards under retained EU law post-Brexit. Brighton and Bristol sustain independent zero-waste retailer clusters capturing margin previously allocated to packaging and brand marketing spend.
United States
California and New York state-level plastic bans compress transition timelines for cosmetic brands serving eco-conscious urban consumers. The FDA regulates cosmetic labeling claims and manufacturing practices under the Federal Food, Drug, and Cosmetic Act. The Pacific Northwest corridor from Portland to Seattle anchors boutique hotel amenity adoption of solid formulations for sustainability programs.
New Zealand
Specialty retail positioning leverages geographic origin for premium bar anchoring in European export markets. The country's environmental regulations emphasize aquatic biodegradability standards for surfactant formulations. Auckland concentrates contract manufacturing capacity serving Asia-Pacific distribution networks with cold-process saponification capabilities.
Zero-Waste Shampoo Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across solid-format manufacturing versus brand marketing specialization. The vendor base distributes across vertically integrated retailers, contract manufacturers, and direct-to-consumer pure-plays. Three archetypes dominate: legacy soap makers with saponification expertise, vertically integrated specialty retailers controlling store networks, and digital-native subscription brands exploiting powder concentrate logistics. Competitive moves concentrate on pharmacy channel certification investments and aluminum bottle return program infrastructure buildout.
Among vertically integrated specialists, Lush Retail Ltd. exemplifies captive retail network control spanning manufacturing and direct-store distribution across North America and Europe. New Zealand-origin Ethique occupies a position anchoring premium bar positioning through geographic provenance storytelling in European specialty retail. HiBAR sits within the formulation-innovation tier, representing concentrated solid expertise eliminating plastic bottles entirely through chemistry-first positioning.
| Leading Market Players |
|---|
| Ethique |
| HiBAR |
| Lush Retail Ltd. |
| J.R. Liggett, Ltd |
| Plaine Products |
| Beauty and the Bees |
| Oregon Soap Company |
| Rocky Mountain Soap |
| The Refill Shoppe |
| Others |
Supply Flow & Price Mechanics
Formulation chemists with saponification expertise cluster in Germany's chemical processing corridor near Leverkusen and New Zealand's Auckland manufacturing zone, with labor-cost differentials between these hubs driving pricing-tier spreads across premium bar formulations and mass-market alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ECOCERT-certified organic bars from natural-ingredient mid-tier offerings and basic saponified oil economy formats. Price differentiation rests on certification grade and supply chain traceability depth, with pharmacy-channel premiums widening as dermatological testing costs layer onto base formulations. Cost compression in the economy tier is intensifying because Southeast Asian coconut oil price volatility feeds directly into base material costs. Salon professionals show least price sensitivity due to per-wash cost accounting, while family households purchasing refill systems exhibit highest elasticity.
Supply Chain Analysis
EU Green Deal domestic-content mandates reshaping sourcing are pressuring European brands to relocate alkyl polyglucoside surfactant production from Southeast Asian processing hubs. Raw material dependencies center on coconut oil from Indonesia and the Philippines, corn sugar feedstock from the United States, and essential oil distillates from France and Bulgaria. Single-source vulnerability concentrates in Southeast Asian oleochemical processing, where typhoon disruptions and shipping chokepoints at the Strait of Malacca create structural exposure. Distribution runs through specialty zero-waste retailers in German and French urban corridors, with direct-to-consumer powder concentrates bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The zero-waste shampoo market functions as a regulatory compounder, with EU Packaging and Packaging Waste Directive extended producer responsibility schemes accelerating format transitions faster than organic consumer adoption curves would predict.
For Market Incumbents: Deploy pharmacy channel certification investments to capture dermatologist endorsement premiums before smaller competitors complete REACH dossier preparation. Incumbent brands must fund parallel solid-bar pressing and liquid-compounding equipment during the transition window, as dual-format manufacturing capex requirements squeeze mid-tier players with constrained balance sheets. Backward integration into captive saponification capacity insulates margin pressure from formulation chemist scarcity in German industrial regions. For New Entrants and Emerging Players: The gap between premium ECOCERT-certified positioning and economy-tier natural claims offers white-space entry for mid-market brands with transparent supply chain storytelling. New entrants should target French dermocosmetic pharmacy networks, where zero-waste penetration remains underdeveloped despite premium pricing tolerance from pharmacy customers. A powder concentrate direct-to-consumer launch exploits shipping weight advantages and subscription lock-in mechanics without competing for crowded bar-format shelf space. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with cold-process saponification capabilities and established Asia-Pacific distribution networks. Long-term viability over the next decade hinges on aluminum bottle return program infrastructure and refill station network density rather than single-transaction bar sales. Investors should monitor state-level plastic ban acceleration in California and New York as the signal indicating which geographic markets will compress transition timelines fastest.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Channel Certification | ECOCERT organic certification unlocks dermocosmetic retail placement in French pharmacy networks. |
| Aluminum Return Program Buildout | Subscription refill models generate recurring revenue through automated replenishment infrastructure. |
| Powder Concentrate Launch | Waterless formulations reduce shipping weight by eighty percent for direct-to-consumer logistics. |
| Biodegradable Surfactant R&D | Alkyl polyglucoside alternatives to sodium lauryl sulfate meet REACH authorization requirements. |
| Zero-Waste Retail Partnership | Bulk refill station placement in Berlin and Munich normalizes bar purchasing for mainstream households. |
Methodological Framework
Direct dialogue with formulation chemists, zero-waste retail buyers, salon professional purchasing managers, and regulatory affairs specialists at cosmetic brands grounded qualitative insights in operational reality. Secondary validation drew from EU Packaging and Packaging Waste Directive implementation documents, ECHA REACH dossier filings, ECOCERT certification databases, and customs records tracking coconut oil and surfactant trade flows. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segmented outputs across product type, material certification tier, consumer archetype, and distribution channel fed into analytical framework construction throughout the forecast period. CAGRs derived from modeled adoption curves for solid-format penetration rates, refill system subscription retention, and powder concentrate direct-to-consumer velocity. Industry-specific inputs included EU Green Deal compliance timeline assumptions and state-level plastic ban propagation patterns.
Caveats apply where REACH authorization delays for novel plant-derived surfactants or Southeast Asian supply chain disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and consumer format-switching elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
Brazil Dermocosmetics Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
Cosmetics Foundation Market
Beauty & Personal Care
Global Personal Care Market
Beauty & Personal Care
Delivery Systems in Personal Care Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Bath and Shower Products Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Colombia Beauty and Personal Care Products Market
Beauty & Personal Care
Hair Removal Epilator Market
Beauty & Personal Care
Lip Care Market
Beauty & Personal Care
Bangladesh Shampoo Market
Beauty & Personal Care
Online Cosmetics Market