
 Philippines Skin Care Products Market | 2026-2036
Philippines Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Skin Care Products Market Insights
Premium-grade dermo-cosmetic formulations is bifurcating the Philippines skin care landscape into clinically positioned and mass-market tiers. L'Oréal Philippines leverages its dermatological science heritage to anchor professional channel credibility. Beiersdorf Philippines differentiates through sensitive-skin specialization and pharmacy-led distribution. Splash Corp competes via locally calibrated formulations tuned to tropical humidity and melanin-rich skin needs.
Skin care products encompass topically applied formulations containing active ingredients such as niacinamide, hyaluronic acid, and zinc oxide, manufactured through emulsification, encapsulation, or fermentation processes, designed to cleanse, protect, or correct epidermal conditions. The product type dimension shows serums capturing margin pools through concentrated actives, while sunscreens gain structural priority given equatorial UV exposure and rising skin-cancer awareness. Application-wise, anti-aging and hydration segments dominate daily-use frequency, with acne treatment occupying a distinct adolescent-to-young-adult channel.
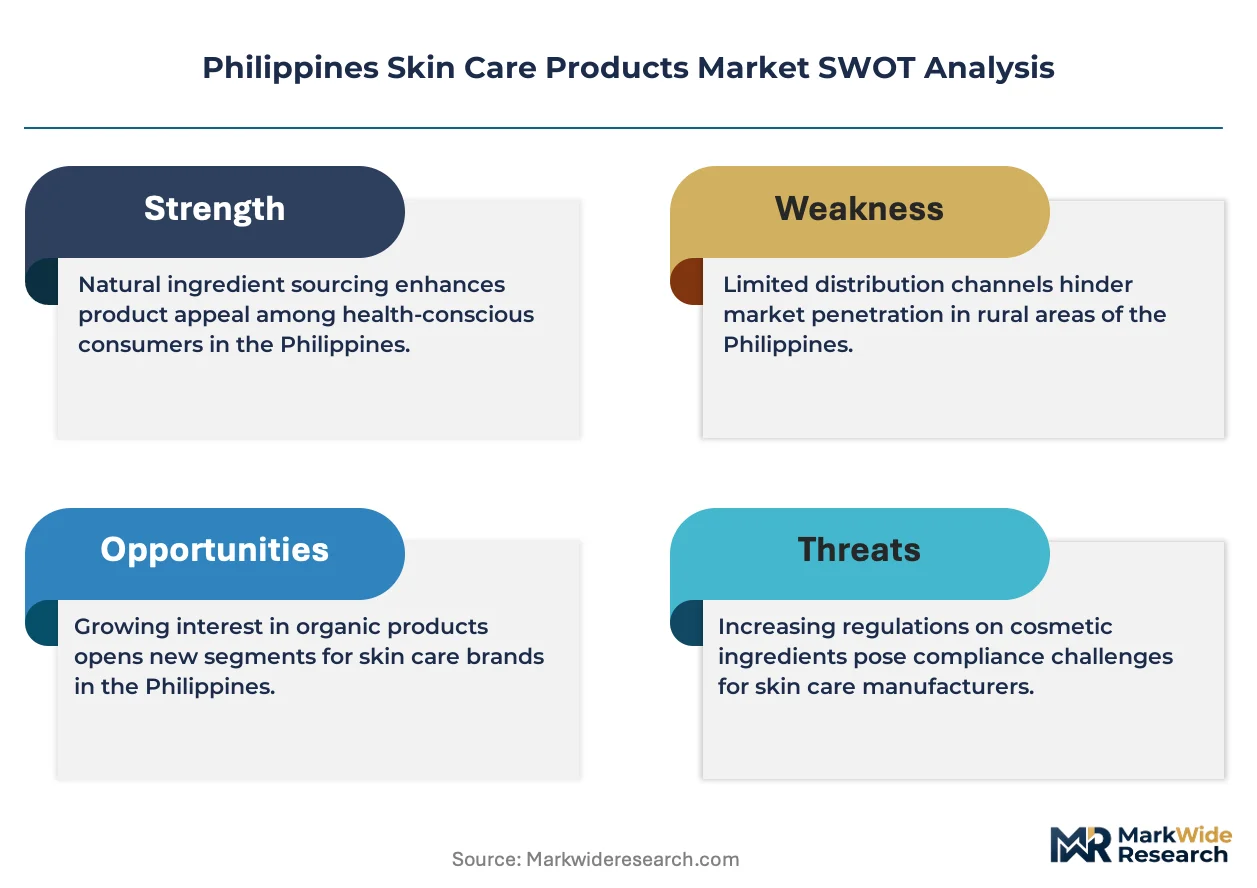
The Philippines Food and Drug Administration enforces cosmetic product notification and ingredient safety assessments, while the ASEAN Cosmetics Directive harmonizes labeling and banned-substance lists across member states, elevating compliance costs for imported formulations. The Bureau of Philippine Standards validates quality claims through localized testing protocols. Stakeholders must monitor regulatory convergence between national FDA requirements and evolving ASEAN standards to preempt market access friction.
Market Dynamics
Regulatory convergence between the Philippines FDA and ASEAN Cosmetics Directive is compressing formulation timelines while elevating compliance barriers for imported actives. This structural pressure is forcing domestic manufacturers toward localized encapsulation capabilities and regional supply partnerships.
Growth Catalysts
- ASEAN Harmonized Standards:The ASEAN Cosmetics Directive's mutual recognition framework reduces duplicate testing costs for products certified in Singapore or Thailand entering Philippine distribution channels.
- Metro Manila Dermatology Channel:Professional clinics in the capital region anchor prescription-strength retinoid and peptide adoption, creating spillover demand into pharmacy retail.
- Encapsulation Technology:Liposome and niosome delivery systems improve niacinamide stability in tropical humidity, enabling higher-concentration serum formulations.
Market Restraints
- Import Tariff Volatility:Korean and Japanese active ingredient suppliers face fluctuating duties under the Philippines' Most Favored Nation tariff schedule, destabilizing cost planning for mid-tier brands.
- Single-Source Fermentation Capacity:Domestic hyaluronic acid production concentrates in Cavite-based biotech facilities, creating geographic supply risk during monsoon disruptions.
- Preservative Restrictions:The Philippines FDA's tightened paraben and formaldehyde-releaser limits force reformulation of legacy mass-market moisturizers.
Strategic Opportunities
- Mindanao Underserved Cohorts:Davao and Cagayan de Oro present pharmacy channel expansion potential for sun-damage prevention portfolios targeting outdoor agricultural workers.
- Telemedicine-Tied Subscription:Dermatologist video consultations paired with automated serum replenishment bypass traditional retail markup structures.
- BIKAS Program Alignment:The Department of Trade and Industry's domestic manufacturing incentives reduce capital equipment duties for local encapsulation line investments.
Industry Challenges
- Formulation Chemist Scarcity:Philippine universities produce limited graduates trained in tropical-stability testing protocols, forcing brands to sponsor foreign certification programs.
- Legacy ERP Integration:Family-owned distributors in Cebu and Iloilo lack inventory systems capable of tracking batch-level ASEAN notification numbers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Skin Care Products Market |
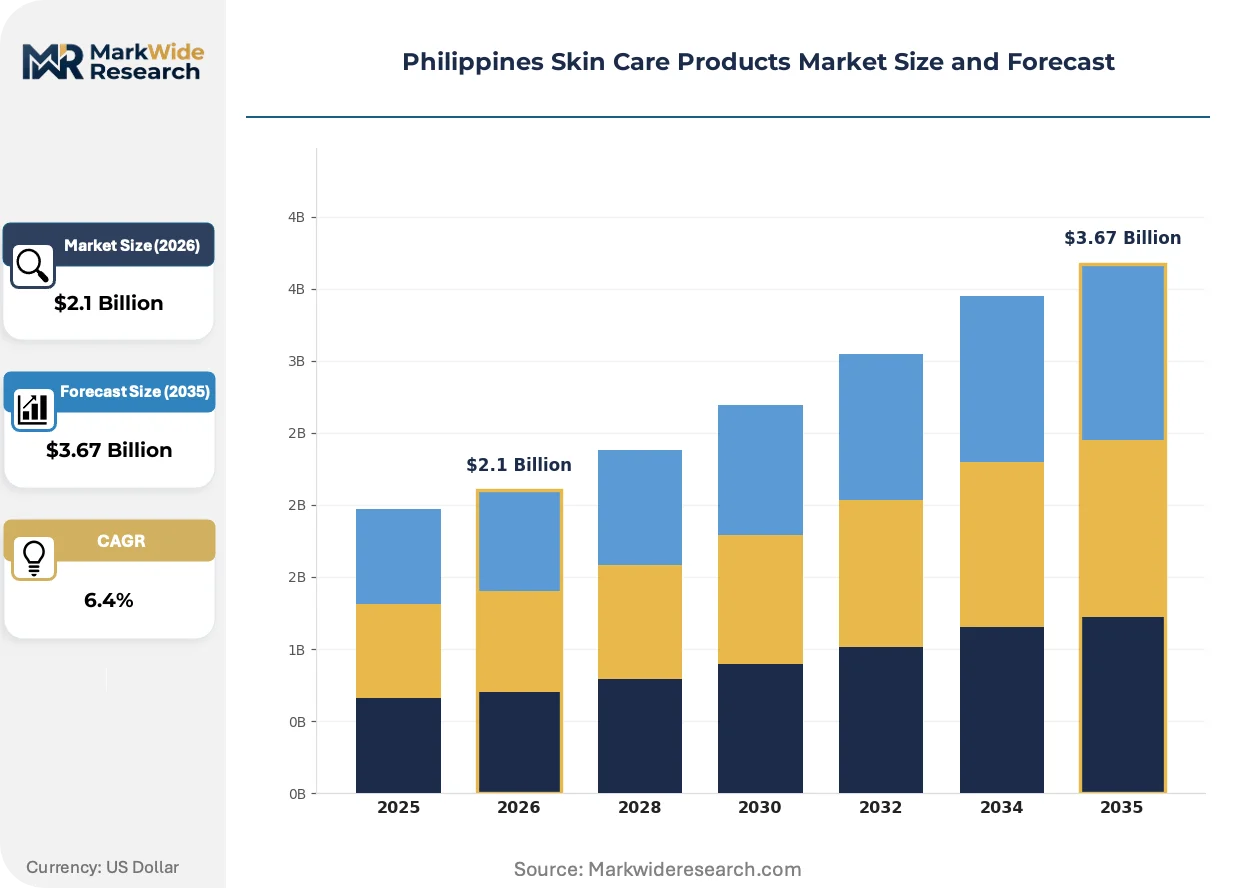
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleansers, Moisturizers, Serums, Sunscreens Application: Daily Care, Anti-Aging, Acne Treatment, Hydration End User: Women, Men, Teens, Professionals Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Unilever Philippines, Procter & Gamble Philippines, L'Oréal Philippines, Avon Cosmetics Philippines, Beiersdorf Philippines, Johnson & Johnson Philippines, Shiseido Philippines, Kao Philippines, Splash Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Skin Care Products Market Trends and Innovations
Biotechnology-derived actives and digital diagnostic tools are compressing the gap between professional dermatology and at-home regimen customization. These shifts are redistributing margin capture toward brands with clinical credibility and direct consumer data access.
Encapsulated retinoid delivery is miniaturizing the effective dose required for hyperpigmentation correction, enabling stable formulation in single-use ampoules. Metro Manila dermatology clinics prescribe these formats for patient compliance programs. The technology is compressing per-treatment costs while elevating pharmacy channel margins.
The Philippines FDA's 2024 cosmetic notification portal upgrade mandates digital ingredient disclosure uploads, accelerating transparency expectations. Domestic manufacturers absorb compliance costs faster than importers reliant on headquarters documentation workflows. Smaller Cebu-based brands leverage this friction to defend shelf space against delayed-entry multinationals.
Clinic-validated purchasing is displacing impulse retail selection among Filipino consumers aged 25-40. Dermatologist social media content drives e-commerce traffic to brand-owned sites, bypassing traditional department store beauty counters. This behavioral shift concentrates most visibly in sun protection and anti-aging categories within Greater Manila.
Philippines Skin Care Products Market Segmentation
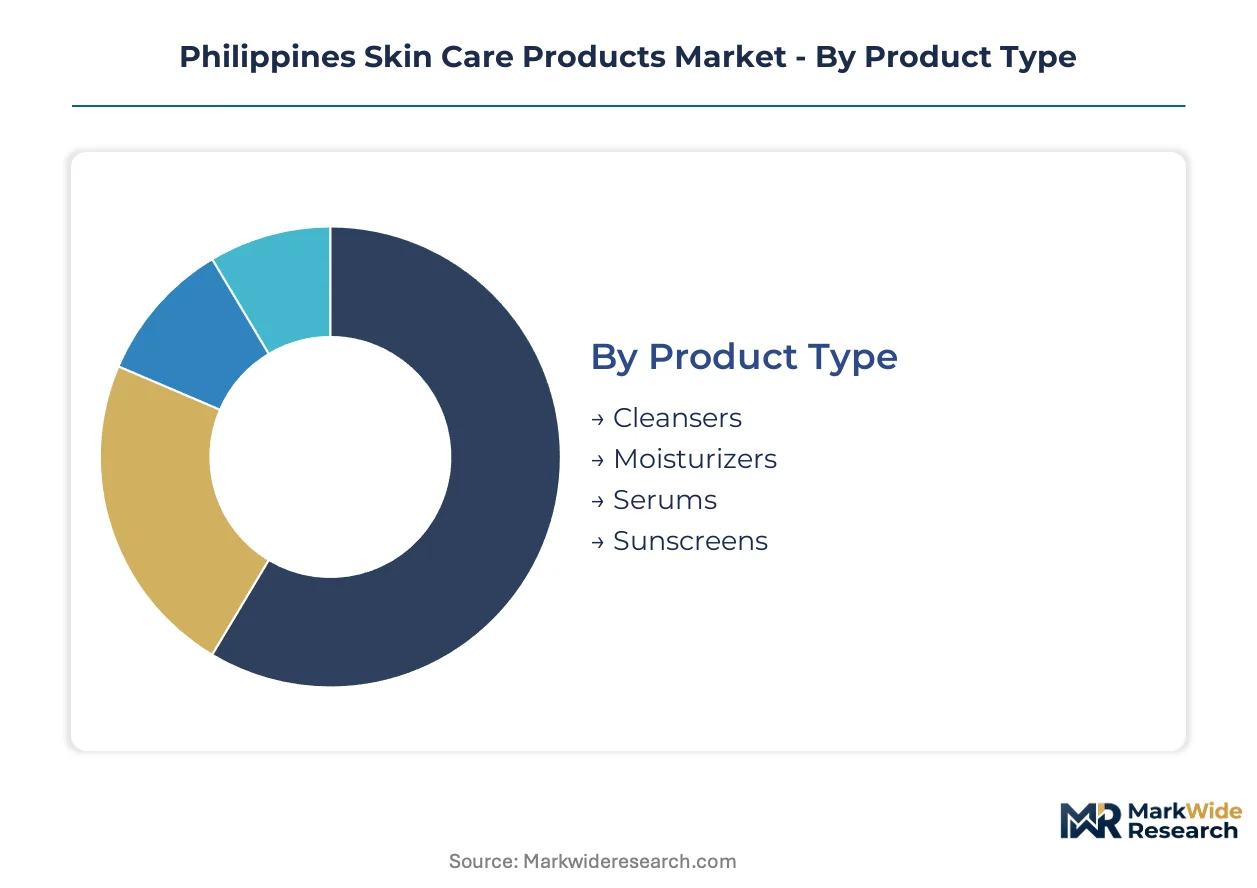
Segmentation in the Philippines skin care market reveals distinct procurement patterns across tropical climate adaptation, professional endorsement channels, and digital-native purchasing behaviors. Understanding these divides enables targeted formulation investments and channel-specific margin capture strategies.
Product Type:
Domestic manufacturing concentrates in cleansers and moisturizers tuned to humidity resistance, while serums and advanced sunscreens rely heavily on Korean and Japanese ingredient imports through Manila port facilities.
- Cleansers:Foaming and micellar formulations dominate mass-market shelves, with local producers leveraging coconut-derived surfactants for cost advantage. Demand clusters in Metro Manila drugstore chains where tropical oil-control claims drive repeat purchase frequency among office workers.
- Moisturizers:Gel-cream hybrids with niacinamide and hyaluronic acid anchor pharmacy channel positioning. Cebu-based manufacturers supply Visayas and Mindanao distribution networks, reducing freight exposure to monsoon logistics disruptions.
- Serums:Concentrated actives in airless pump formats command premium shelf space in dermatology clinic retail.
- Sunscreens:SPF 50+ PA++++ ratings with invisible-finish claims address melanin-rich skin photoprotection needs.
Moisturizers command the established base. The steepest expansion runs through serums.
Application:
Volume concentration skews toward daily maintenance regimens, while margin capture concentrates in condition-specific treatments requiring professional guidance or clinical validation claims.
- Daily Care:Basic cleansing-toning-moisturizing routines sustain supermarket and convenience store velocity. Mass-market brands manufacture these lines domestically in Cavite and Laguna facilities to minimize import duty exposure on finished goods.
- Anti-Aging:Retinoid and peptide formulations drive pharmacy channel growth, with Metro Manila dermatologists prescribing clinic-exclusive ampoule formats. Patient compliance programs create subscription-like replenishment patterns.
- Acne Treatment:Benzoyl peroxide and salicylic acid formulations target adolescent demographics through school-proximate retail.
- Hydration:Hyaluronic acid and ceramide products address barrier repair needs in air-conditioned workplace environments.
Daily Care anchors volume throughput. Anti-Aging claims the fastest margin expansion trajectory.
End User:
Professional channel credibility concentrates in women and dermatologist-referred patients, while men and teens represent conversion opportunities through digital education and social media influencer partnerships.
- Women:The core purchasing demographic across all channels, with 25-40 age cohorts driving premium serum and sunscreen adoption. Metro Manila working professionals prioritize clinic-validated brands for workplace appearance investment.
- Men:Simplified two-step routines (cleanser-moisturizer) gain traction through e-commerce bundling and gym-proximate retail placement.
- Teens:Acne-focused regimens concentrate in pharmacy and online channels, with price sensitivity favoring domestic mass-market brands.
- Professionals:Dermatologist-referred patients purchase prescription-strength retinoids and medical-grade sunscreens through clinic dispensing.
Women retain the revenue base. Men represent the steepest adoption climb.
Distribution Channel:
Channel strategy must reconcile inventory carrying costs against patient education requirements, with professional credibility concentrating in pharmacies and dermatology clinics while volume scales through modern trade and digital platforms.
- Online Retail:Brand-owned sites and marketplace storefronts bypass traditional retail markups, with dermatologist social media content driving direct traffic. Subscription models for serum replenishment gain traction among Metro Manila professionals.
- Supermarkets:Mass-market cleansers and basic moisturizers sustain high-velocity turnover, with domestic brands leveraging shelf-space negotiations against multinational incumbents.
- Pharmacies:Watsons and Mercury Drug anchor dermo-cosmetic credibility, with trained beauty advisors influencing niacinamide and retinoid selection.
- Specialty Stores:Department store beauty halls concentrate premium brand presence, though foot traffic erosion shifts investment toward e-commerce fulfillment.
Pharmacies hold the professional endorsement anchor. Online retail captures the steepest volume expansion.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic encapsulation facilities cluster in Cavite and Laguna provinces, with finished goods distribution radiating through Metro Manila, Cebu, and Davao hubs. The Philippines FDA's cosmetic notification portal and ASEAN harmonized standards govern cross-border formulation movements. Regional procurement patterns split between imported Korean and Japanese actives and locally manufactured humidity-resistant bases.
Metro Manila
Dermatology clinics in Makati and Quezon City anchor prescription-strength retinoid and peptide adoption, creating spillover demand into Mercury Drug and Watsons pharmacy channels. The Department of Trade and Industry's BIKAS program incentivizes capital equipment investments for local encapsulation lines in adjacent Cavite facilities. Brand-owned e-commerce fulfillment centers in Taguig bypass traditional department store beauty counters for serum replenishment subscriptions.
Central Visayas
Cebu-based manufacturers supply gel-cream moisturizers with niacinamide across Visayas and Mindanao distribution networks, reducing monsoon-season freight exposure. The Philippines FDA's 2024 digital notification portal upgrade accelerates compliance for domestic producers versus import-dependent competitors. Mandaue industrial zones host family-owned distributors upgrading legacy ERP systems to track batch-level ASEAN notification numbers.
Davao Region
Outdoor agricultural workers in Davao del Sur and Compostela Valley drive pharmacy channel expansion for SPF 50+ sun-damage prevention portfolios. The ASEAN Cosmetics Directive's mutual recognition framework reduces duplicate testing costs for products certified in Singapore entering Mindanao distribution. Cagayan de Oro serves as the northern Mindanao logistics hub for clinic-validated sunscreen brands targeting professional demographics.
Calabarzon
Biotech fermentation capacity for hyaluronic acid concentrates in Cavite facilities, creating geographic supply risk during typhoon disruptions. The Bureau of Philippine Standards validates quality claims through localized tropical-stability testing protocols. Laguna-based contract manufacturers produce coconut-derived surfactants for mass-market foaming cleansers distributed through supermarket chains nationwide.
Philippines Skin Care Products Market Competitive Landscape
Concentration sits with multinational dermatological science heritage brands and domestic tropical-formulation specialists. The market structure tiers into clinic-credentialed premium positioning, pharmacy-channel dermo-cosmetic credibility, and mass-market humidity-adapted value lines. Strategic archetypes include science-backed professional channel anchors, sensitive-skin specialization players, and locally calibrated tropical-climate formulators. Competitive moves center on dermatologist partnership networks and domestic encapsulation capacity investments.
Within the multinational tier, L'Oréal Philippines and Beiersdorf Philippines anchor professional channel credibility through dermatological science positioning and pharmacy-led distribution. Splash Corp exemplifies the domestic specialist archetype with locally calibrated formulations tuned to tropical humidity and melanin-rich skin needs. These three players collectively represent the competitive tension between imported clinical heritage and indigenous climate adaptation capabilities.
| Leading Market Players |
|---|
| Unilever Philippines |
| Procter & Gamble Philippines |
| L'Oréal Philippines |
| Avon Cosmetics Philippines |
| Beiersdorf Philippines |
| Johnson & Johnson Philippines |
| Shiseido Philippines |
| Kao Philippines |
| Splash Corp |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for Korean-imported niacinamide concentrates compress pricing power for mid-tier Philippine brands while rewarding domestic encapsulation investments in Cavite. This lead-time exposure concentrates margin capture among vertically integrated players with regional supply partnerships.
Pricing Analysis
The Philippines FDA's cosmetic notification requirements dictate the pricing tier structure by elevating compliance costs disproportionately for import-dependent brands. Pricing stratifies across dermatologist-validated premium lines, pharmacy-channel dermo-cosmetics, and mass-market humidity-adapted formulations. Cost compression in the mid-tier intensifies because Japanese active ingredient suppliers face tariff volatility under Most Favored Nation schedules. Teens and young adults in acne treatment segments exhibit highest price sensitivity, while dermatologist-referred professionals accept premium positioning for prescription-strength retinoids.
Supply Chain Analysis
Seventy-five day lead times for airless pump packaging components from South Korean suppliers create inventory carrying cost pressure across Metro Manila fulfillment networks. Active ingredient sourcing draws from South Korea, Japan, and domestic Cavite fermentation facilities for hyaluronic acid. Single-source geographic concentration in Cavite biotech capacity generates typhoon-season supply vulnerability. Distribution runs through pharmacy chains, brand-owned e-commerce fulfillment centers, and supermarket mass-market channels with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists trained in tropical-stability protocols remain scarce across Philippine universities, forcing brands to sponsor foreign certification programs and constraining domestic R&D scaling.
For Market Incumbents: Compound dermatologist partnership networks in Metro Manila to anchor prescription-strength credibility against emerging telemedicine-tied subscription entrants. Expand Cavite encapsulation capacity under BIKAS program incentives to reduce Korean import dependency. Control pharmacy channel beauty advisor training programs to defend shelf space against delayed-entry multinationals. For New Entrants and Emerging Players: Telemedicine-integrated serum replenishment subscriptions represent the most penetrable service-layer gap where incumbents under-serve Metro Manila working professionals. Target Mindanao agricultural worker cohorts in Davao with SPF 50+ sun-damage prevention portfolios through pharmacy channel expansion. Launch through dermatologist social media content partnerships to bypass traditional department store beauty counter gatekeeping. For Investors and Strategic Acquirers: Long-term, this sits as a domestic manufacturing capability play because ASEAN harmonized standards increasingly favor localized production with faster FDA notification turnaround. Acquire Cebu-based manufacturers with upgraded ERP systems capable of batch-level ASEAN tracking. Watch Philippines FDA enforcement intensity on paraben and formaldehyde-releaser limits as signal for reformulation-driven consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Encapsulation Capacity Investment | BIKAS program incentives reduce capital equipment duties for Cavite-based liposome production lines serving niacinamide serum formulations. |
| Dermatology Clinic Partnership Network | Makati and Quezon City prescription channels anchor prescription-strength retinoid adoption with spillover into Mercury Drug retail. |
| Telemedicine-Tied Subscription Launch | Video consultation integration bypasses traditional pharmacy markup structures for automated serum replenishment among professionals. |
| Mindanao Pharmacy Channel Expansion | Davao and Cagayan de Oro distribution networks target underserved agricultural worker demographics with sun-damage prevention portfolios. |
| Tropical-Stability R&D Certification | Foreign-trained formulation chemist programs address humidity-resistant encapsulation protocols missing from Philippine university curricula. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across dermatology clinic administrators, pharmacy chain beauty advisors, Cavite contract manufacturing plant managers, and Cebu-based distribution partners. Secondary validation incorporated Philippines FDA cosmetic notification portal records, ASEAN Cosmetics Directive harmonization documentation, Bureau of Philippine Standards testing protocols, and Department of Trade and Industry BIKAS program filings. Bottom-up volume builds from product-type and channel segmentation triangulated against top-down market sizing from trade flow analysis.
Across the projection horizon, analytical frameworks modeled product type, application, end user, and distribution channel dimensions with regional disaggregation for Metro Manila, Central Visayas, Davao Region, and Calabarzon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Forecast inputs included tropical climate adaptation requirements, professional channel endorsement velocity, and digital-native purchasing behavior shifts.
Material uncertainties — regulatory enforcement intensity on preservative restrictions, Korean import tariff schedule volatility, monsoon season logistics disruptions — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Organic Color Cosmetics Products Market
Cosmetics & Skincare
Israel Cosmetics Products Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
Probiotic Skin Care Cosmetic Product Market
Cosmetics & Skincare
Cosmetic Mirror Market
Cosmetics & Skincare
Italy Lip Care Products Market
Cosmetics & Skincare
E Commerce Cosmetic and Fragrance Market
Cosmetics & Skincare
Eyeliner Pen Market
Cosmetics & Skincare
Waterproof Eyebrow Liner Market
Cosmetics & Skincare
North America Bath Soap Market
Cosmetics & Skincare
South America Cosmetics Products Market
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market
Cosmetics & Skincare
Private Label Cosmetics Manufacturing Service Market
Cosmetics & Skincare
Face Compact Market