
 Antimicrobial Packaging Market | 2026-2036
Antimicrobial Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Packaging Market Analysis
A capital-intensity divergence between integrated resin producers and film converters is redrawing competitive boundaries in antimicrobial packaging. Amcor plc leverages its global extrusion network to sustain cost advantages across high-volume food accounts. Huhtamaki Oyj anchors its position through specialized fiber-based active packaging for ready-to-eat segments. BASF SE differentiates via controlled-release additive chemistry that extends shelf-life performance in premium meat applications.
Antimicrobial packaging incorporates biologically active agents—silver ions, organic acids, or chitosan compounds—into polymer matrices or surface coatings at loadings typically between 0.5% and 5% by weight, designed to inhibit microbial colonization on packaged surfaces. The technology serves primarily to reduce food spoilage, control healthcare-associated infections in sterile medical supplies, and protect moisture-sensitive electronics from biofilm formation. Plastic substrates dominate material value flows due to compatibility with extrusion-based active agent dispersion, though biodegradable alternatives are gaining formulation attention as European single-use directives tighten. Active packaging technology leads functional innovation, with nano-coatings representing the fastest-developing sub-area for precision-release medical applications.
FDA food contact substance notifications govern antimicrobial migration limits in the United States, while EFSA evaluates active agent safety under EU food contact regulations, and REACH restricts certain biocidal additives across European supply chains. These frameworks shape R&D priorities, forcing reformulation investments and creating compliance moats for firms with established regulatory dossiers. Stakeholders must monitor evolving biocidal product regulations in major economies, as reclassification of silver-based additives could abruptly alter approved ingredient lists and manufacturing qualifications.
Market Dynamics
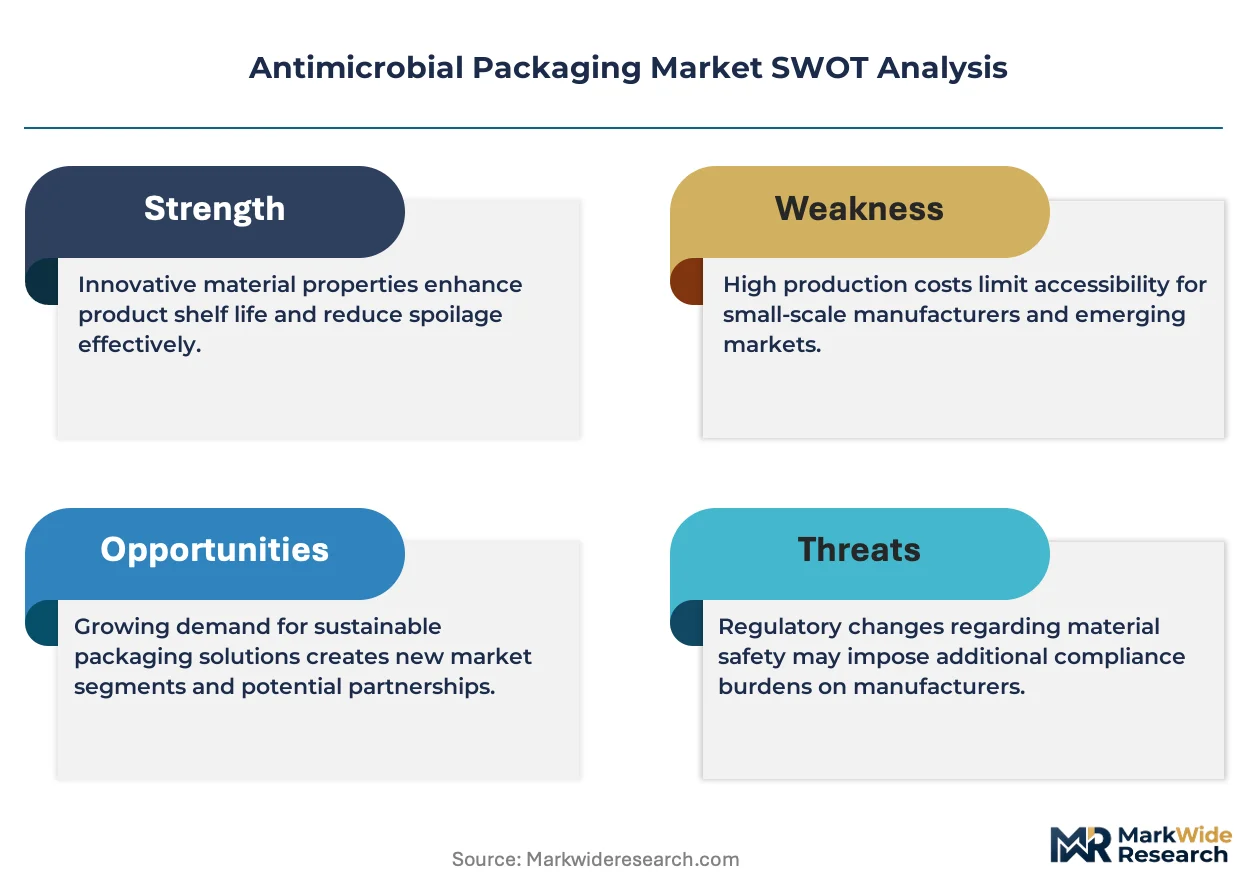
The EU's F-Gas Regulation and REACH compliance requirements are forcing resin producers and film converters to reformulate antimicrobial additives, redrawing cost structures and supplier qualifications across European supply chains.
Growth Catalysts
- REACH-driven material substitution:European converters are accelerating adoption of chitosan-based and organic acid antimicrobial systems to replace restricted biocidal additives, expanding the addressable formulation space for compliant suppliers.
- Fresh food retail consolidation:German and French supermarket chains are mandating antimicrobial films for private-label meat and produce categories to reduce spoilage losses and meet corporate sustainability targets.
- Active packaging integration:Controlled-release nano-coatings are enabling precision antimicrobial delivery in premium medical device packaging, opening high-margin applications beyond food.
Market Restraints
- Silver ion supply concentration:Over 60% of antimicrobial-grade silver compound production sits with Chinese and South Korean specialty chemical producers, creating input vulnerability for Western film manufacturers.
- Migration testing costs:FDA food contact substance notifications require extensive migration studies costing $200,000-$500,000 per formulation, erecting capital barriers for mid-scale additive developers.
- Biodegradable performance gap:PLA and PHA substrates exhibit inferior active agent dispersion and release kinetics versus polyethylene, limiting substitution in high-performance applications.
Strategic Opportunities
- Indian food processing expansion:FSSAI's tightening food safety standards and the PLI scheme for food processing equipment are creating first-mover openings for antimicrobial packaging suppliers in cold chain infrastructure.
- Healthcare-associated infection control:Japanese hospitals are adopting antimicrobial sterile barrier systems for surgical kits, driven by METI's medical device quality initiatives and aging demographics.
- Extended producer responsibility mandates:The EU Green Deal's packaging waste regulations are incentivizing mono-material antimicrobial designs that simplify recycling while maintaining shelf-life performance.
Industry Challenges
- Active agent stability engineering:Maintaining antimicrobial efficacy through extrusion temperatures above 180°C requires specialized encapsulation expertise that resides with a narrow pool of polymer scientists.
- Multi-jurisdiction dossier management:Simultaneous compliance with FDA notifications, EFSA evaluations, and China's GB standards demands dedicated regulatory affairs capacity that strains mid-tier additive houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Packaging Market |
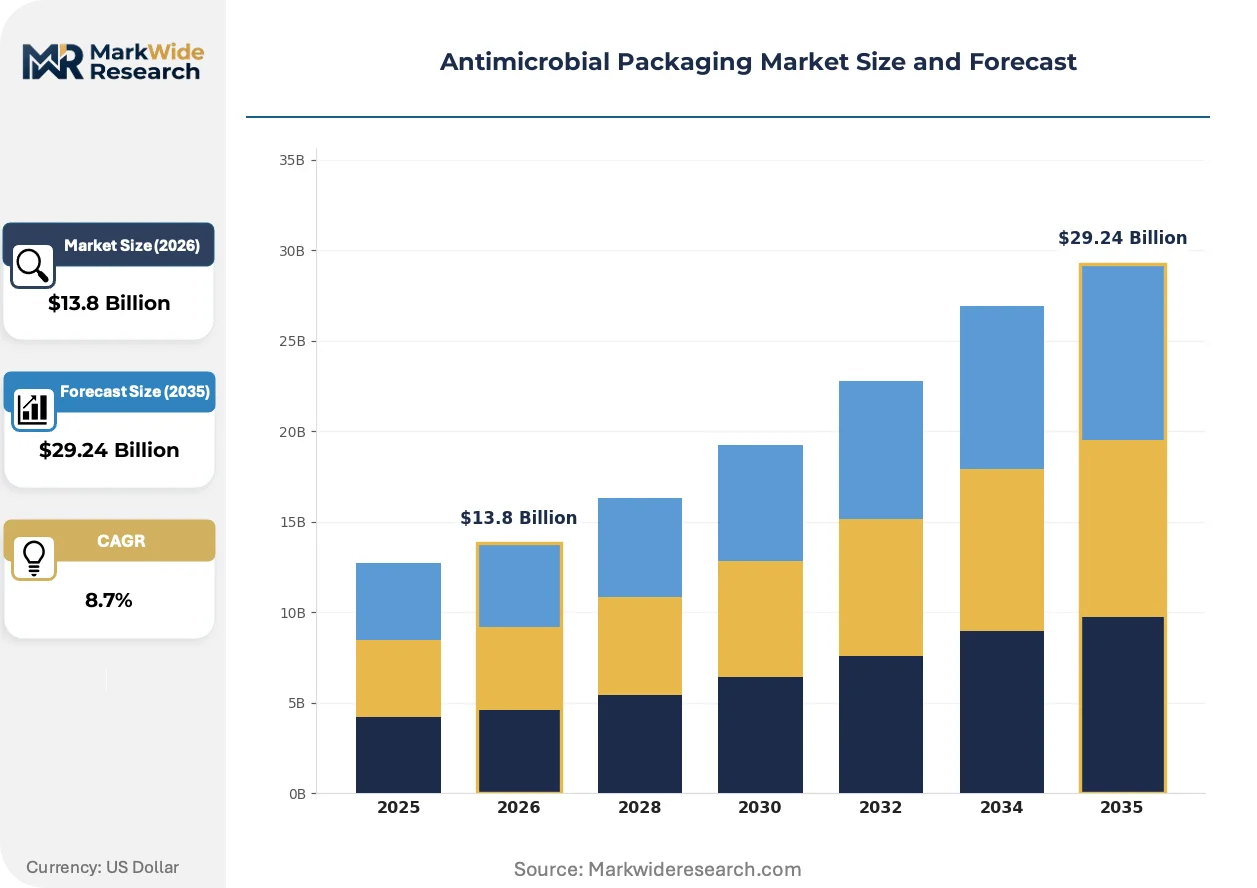
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $29.24 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Metal, Biodegradable Application: Food Packaging, Medical Supplies, Personal Care, Electronics End User: Food Industry, Pharmaceuticals, Cosmetics, Electronics Manufacturers Technology: Active Packaging, Passive Packaging, Hybrid Packaging, Nano-coatings |
| Companies Covered | Berry Global Group, Huhtamaki Oyj, Amcor plc, Avery Dennison Corporation, Sonoco Products Company, Sealed Air Corporation, Tetra Pak, BASF SE, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Packaging Market Emerging Trajectories
Nano-engineered release mechanisms and bio-based carrier systems are displacing conventional masterbatch approaches, while regulatory fragmentation across major economies is forcing parallel development tracks for antimicrobial formulations.
Electrospun nanofiber antimicrobial coatings are fragmenting the medical packaging segment by enabling surface-area-maximized active agent distribution at sub-micron thicknesses. Cardiovascular device manufacturers in Switzerland and Germany are piloting these systems for implantable sterile barriers. The technology is compressing conventional dip-coating and spray-application equipment markets by eliminating secondary processing steps.
EFSA's 2023 updated guidance on food contact biocides has tightened toxicological data requirements for silver-based additives, forcing reformulation investments across European supply chains. The regulation is accelerating R&D migration toward organic acid and chitosan alternatives in meat and dairy packaging categories. French and Italian converters are responding by consolidating supplier relationships with dossier-complete additive houses to shorten qualification timelines.
Direct supplier relationships between antimicrobial additive developers and major food retailers are displacing traditional distributor channels in high-volume accounts. Walmart and Carrefour are establishing technical specifications that bypass converter intermediaries for critical performance parameters. This pattern is most visible in the United States and France, where retail consolidation has concentrated procurement leverage among fewer than ten national chains.
Antimicrobial Packaging Market Segmentation
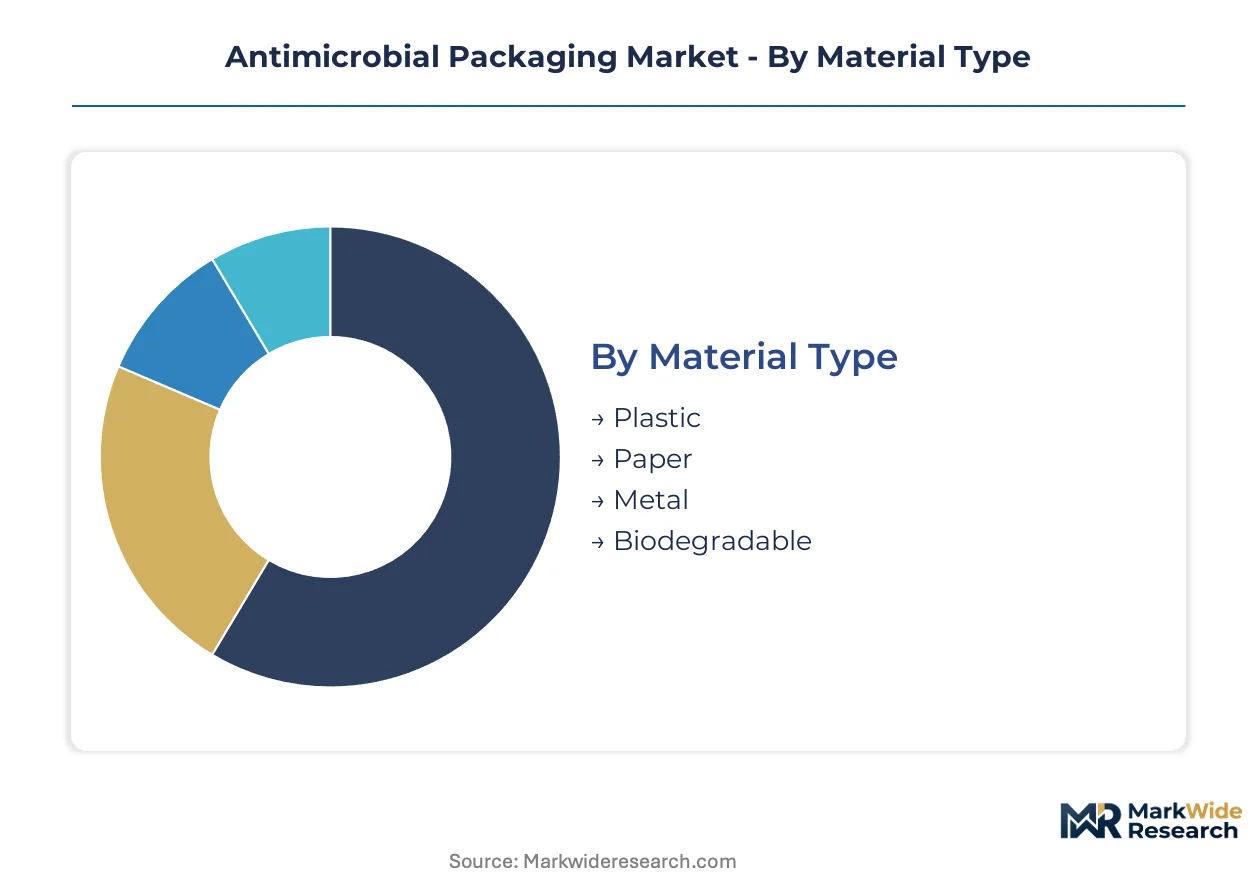
Antimicrobial packaging markets fragment across material chemistry, functional technology, and end-use compliance requirements. Each segmentation axis carries distinct regulatory burdens and channel economics that reshape supplier priorities.
Material Type:
Channel flows diverge sharply: plastics dominate high-volume food retail through extrusion-compatible masterbatch systems, while biodegradable alternatives command premium positioning in European regulated environments.
- Plastic:Polyethylene and polypropylene matrices accommodate silver-ion and organic acid dispersion at 0.5-5% loadings with standard extrusion equipment. German and French supermarket chains specify plastic antimicrobial films for private-label meat categories to reduce spoilage losses under corporate sustainability mandates.
- Biodegradable:PLA and PHA substrates face active-agent dispersion challenges versus conventional polymers but gain formulation attention as EU single-use directives tighten. REACH compliance requirements are accelerating converter migration toward chitosan-based systems in these substrates.
- Paper:Fiber-based active packaging serves ready-to-eat segments through surface-integrated organic acid treatments.
- Metal:Aluminum and steel antimicrobial coatings protect moisture-sensitive electronics from biofilm formation in sterile barrier applications.
Plastic dominates installed base. Biodegradable is where expansion concentrates.
Application:
Margin structures vary threefold across applications, with medical supplies commanding qualification-intensive pricing and food packaging operating on volume-scaled efficiencies.
- Food Packaging:Active agent integration targets spoilage reduction in meat, produce, and dairy categories with shelf-life extension of 30-50%. FDA food contact notifications govern migration limits in the United States, while EFSA evaluates active agent safety under EU regulations.
- Medical Supplies:Sterile barrier systems for surgical kits and implantable devices require precision-release nano-coatings with sub-micron thickness control. Japanese hospitals are adopting these systems under METI medical device quality initiatives.
- Personal Care:Antimicrobial films protect cosmetic formulations from microbial contamination during shelf storage and transport.
- Electronics:Moisture-sensitive components require biofilm-inhibiting packaging for semiconductor and precision instrument protection.
Food Packaging anchors volume throughput. Medical Supplies is where margin expansion concentrates.
End User:
Procurement authority is shifting: major food retailers now establish technical specifications that bypass converter intermediaries, while pharmaceutical buyers prioritize dossier-complete suppliers.
- Food Industry:Retail consolidation in the United States and France has concentrated leverage among fewer than ten national chains mandating antimicrobial films for private-label categories. Walmart and Carrefour direct supplier relationships are displacing traditional distributor channels.
- Pharmaceuticals:Sterile packaging for drug delivery systems demands multi-jurisdiction dossier management across FDA notifications, EFSA evaluations, and China's GB standards.
- Cosmetics:Brand owners specify antimicrobial primary packaging for preservative-reduced formulations.
- Electronics Manufacturers:Precision component suppliers require moisture and biofilm protection for cleanroom-handled devices.
Food Industry dominates procurement volume. Pharmaceuticals is where technical qualification barriers concentrate.
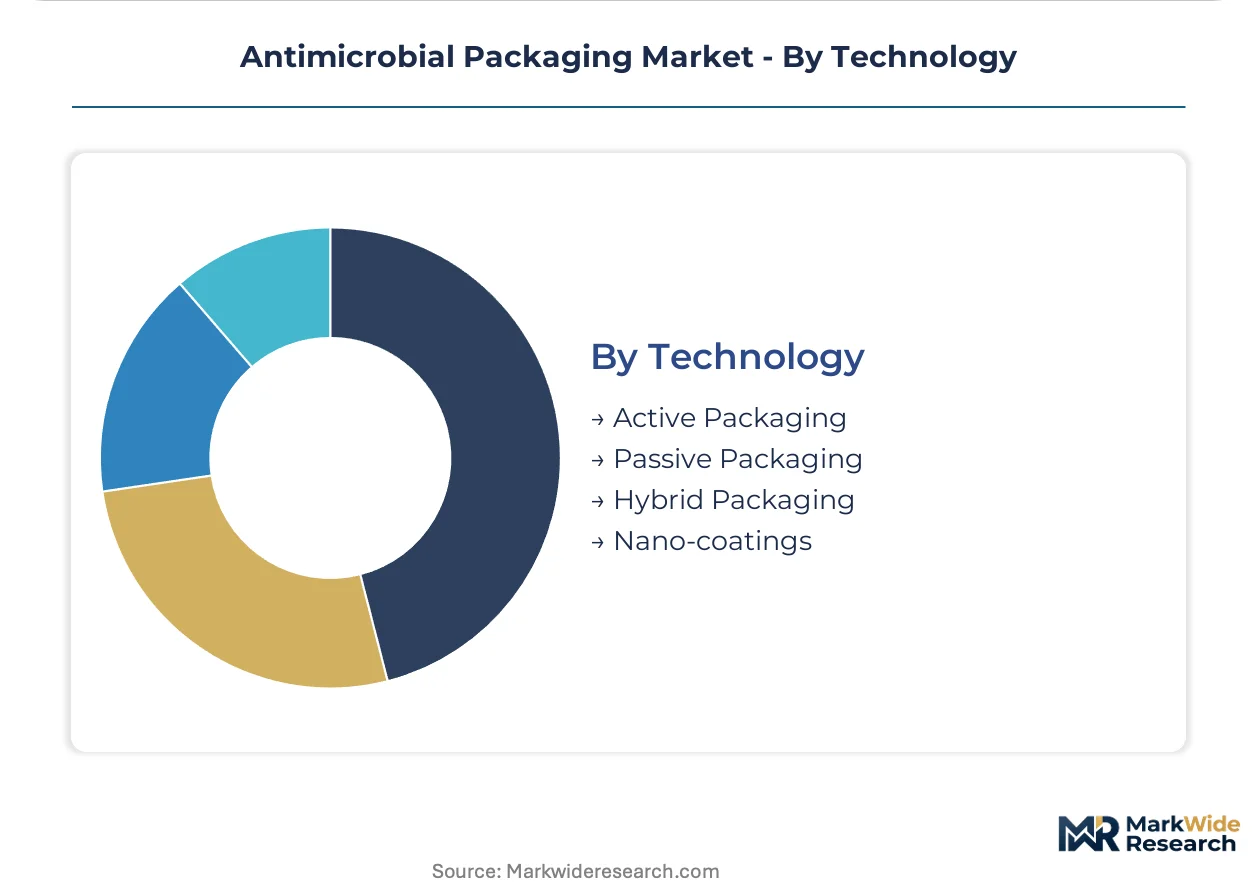
Technology:
Development tracks are diverging under regulatory fragmentation: nano-engineered systems advance in medical precision while hybrid architectures address food sector cost pressures.
- Active Packaging:Controlled-release additive chemistry extends shelf-life performance through intentional migration of silver ions, organic acids, or chitosan compounds. EFSA's tightened toxicological requirements for silver-based additives are accelerating R&D migration toward organic acid alternatives.
- Nano-coatings:Electrospun nanofiber systems maximize surface-area distribution at sub-micron thicknesses, eliminating secondary processing steps. Cardiovascular device manufacturers in Switzerland and Germany are piloting these for implantable sterile barriers.
- Passive Packaging:Inherent antimicrobial properties through material selection without active agent integration.
- Hybrid Packaging:Combined active-passive architectures balance performance and cost in mid-tier food applications.
Active Packaging dominates commercial deployment. Nano-coatings is where steepest expansion trajectory concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where FDA food contact notifications erect qualification moats, while European converters absorb reformulation costs under REACH pressure without commensurate price recovery.
United States
Walmart and Carrefour procurement teams now establish direct technical specifications with antimicrobial additive developers, bypassing traditional converter intermediaries. FDA food contact substance notifications govern migration limits and shape product development timelines. Midwest food processing corridors around Chicago and Minneapolis anchor converter operations serving high-volume meat and dairy accounts.
Germany
Fresh food retail chains mandate antimicrobial films for private-label meat categories to reduce spoilage losses under corporate sustainability targets. The EU F-Gas Regulation tightens material specifications for packaging films and forces resin producer reformulation. The Rhine-Ruhr industrial cluster concentrates extrusion capacity serving pan-European supermarket supply chains.
France
Supermarket consolidation has concentrated procurement leverage among fewer than ten national chains driving antimicrobial film adoption. EFSA evaluates active agent safety under EU food contact regulations with tightened toxicological data requirements. The Lyon-Grenoble corridor hosts cardiovascular device manufacturers piloting electrospun nanofiber sterile barrier systems.
Japan
Hospitals adopt antimicrobial sterile barrier systems for surgical kits under METI medical device quality initiatives and aging demographics. The national pharmaceutical regulator maintains stringent dossier requirements for implantable device packaging. The Kansai region around Osaka concentrates sterile medical supply manufacturing and packaging converter operations.
India
FSSAI tightening food safety standards and the PLI scheme for food processing equipment create first-mover openings in cold chain infrastructure. The central food regulator accelerates compliance timelines for antimicrobial migration in dairy and meat categories. Maharashtra and Gujarat industrial corridors concentrate food processing expansion and converter investment.
Antimicrobial Packaging Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where integrated resin producers compete on formulation chemistry while film converters battle on extrusion scale and account relationships. The vendor base clusters around three strategic archetypes: global packaging conglomerates with captive additive sourcing, specialized active agent houses with regulatory dossier depth, and regional converters serving single-country retail accounts. Dominant competitive moves include backward integration into controlled-release additive chemistry and geographic expansion through distributor displacement in high-growth Asian markets.
Among diversified packaging conglomerates, Amcor plc, Huhtamaki Oyj, and Mondi Group exemplify scale-driven positions where global extrusion networks sustain cost advantages across high-volume food accounts. These companies occupy archetype positions that balance regulatory compliance capacity with manufacturing footprint breadth. BASF SE anchors the specialized chemical supplier tier, representing formulation expertise that extends shelf-life performance through controlled-release additive chemistry. The competitive dynamic pits these archetypes against one another in account negotiations where retailers increasingly specify performance parameters directly.
| Leading Market Players |
|---|
| Berry Global Group |
| Huhtamaki Oyj |
| Amcor plc |
| Avery Dennison Corporation |
| Sonoco Products Company |
| Sealed Air Corporation |
| Tetra Pak |
| BASF SE |
| Mondi Group |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German supermarket chains and film converters lock in silver-ion masterbatch supply while fixing unit costs against REACH-driven reformulation volatility. These contracts insulate high-volume food accounts from spot-market swings in antimicrobial-grade additive pricing.
Pricing Analysis
The customization-premium spread widens as EFSA's tightened toxicological requirements force meat and dairy packers toward dossier-complete organic acid systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and active-agent stability. Cost compression in standard-grade polyethylene films intensifies because Chinese silver compound suppliers concentrate production leverage. Private-label retail chains exhibit highest price sensitivity, while cardiovascular device manufacturers accept premium positioning for nano-coating precision.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for antimicrobial-grade silver compounds and specialized chitosan feedstocks. Supply concentrates in China and South Korea for silver-ion production, Germany and France for extrusion capacity, and India for emerging chitosan sourcing. The chain draws from petrochemical resin networks, active agent masterbatch specialists, and medical-grade coating equipment. Single-source vulnerability runs through Chinese specialty chemical producers controlling over half of antimicrobial-grade silver output. Distribution runs through converter-direct relationships with major retailers, displacing traditional additive distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized encapsulation expertise for high-temperature extrusion survives with a narrow pool of polymer scientists, creating defendable moats for holders of this capability.
For Market Incumbents: Compound regulatory dossier depth through backward integration into controlled-release additive chemistry, locking out mid-tier challengers facing EFSA migration study costs. Add extrusion capacity in Maharashtra and Gujarat industrial corridors to capture Indian cold chain expansion before local converters consolidate. FDA notification backlogs represent the critical threat to timeline-sensitive accounts. For New Entrants and Emerging Players: Lead with chitosan-based formulation platforms in European biodegradable substrates, where REACH compliance accelerates material substitution faster than incumbent reformulation cycles. India's FSSAI tightening creates the most penetrable geography for first-mover antimicrobial film suppliers. Bypass converter intermediaries by securing direct technical specifications with French supermarket procurement teams. For Investors and Strategic Acquirers: Dossier-complete additive houses with EFSA-evaluated organic acid platforms represent the priority acquisition archetype, as retailers consolidate supplier relationships to shorten qualification timelines. Long-term viability hinges on multi-jurisdiction regulatory capacity spanning FDA, EFSA, and China's GB standards. Watch for silver-ion reclassification announcements as the inflection signal that would abruptly rewrite approved ingredient lists and manufacturing qualifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Chemistry | Captures margin from controlled-release masterbatch production while erecting FDA notification barriers. |
| Direct Retailer Specification Partnerships | Walmart and Carrefour procurement teams now bypass converter intermediaries for critical performance parameters. |
| Biodegradable Substrate Formulation Investment | PLA and PHA compatibility with chitosan systems addresses EU single-use directive compliance. |
| Multi-Jurisdiction Dossier Expansion | Simultaneous FDA, EFSA, and GB standard coverage strains mid-tier additive houses and concentrates share. |
| Indian Cold Chain Infrastructure Positioning | FSSAI tightening and PLI scheme incentives create first-mover openings in Maharashtra and Gujarat corridors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA food contact substance notifications, EFSA scientific opinions, EU customs trade data, and SEC filings from packaging conglomerates. Primary interviews engaged film converter operations managers, antimicrobial additive R&D directors, supermarket category buyers, and regulatory affairs specialists at medical device manufacturers. Secondary validation drew from REACH registration databases, FSSAI compliance circulars, and Japanese METI medical device quality guidelines. Bottom-up volume estimates from extrusion capacity and masterbatch loading rates triangulate against top-down market sizing from end-use consumption patterns.
Segmentation dimensions modeled include material chemistry, functional technology platform, end-use compliance requirements, and geographic regulatory cluster across the analysis window. CAGRs derive from installed base erosion rates, substitution elasticity between active agent systems, and penetration curves in cold chain infrastructure. Industry-specific forecast inputs incorporate EFSA evaluation timelines for novel food contact substances and Indian PLI scheme disbursement schedules for food processing equipment.
Forecasts assume regulatory continuity in FDA food contact notifications, REACH biocidal product regulations, and FSSAI antimicrobial migration standards; material policy shifts would require re-modeling active agent approval trajectories and reformulation investment schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Special Effects Laminate Films Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
Insulation Film Market