
 Global Stretch and Shrink Film Market | 2026-2036
Global Stretch and Shrink Film Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stretch and Shrink Film Market Intelligence
On-site application optimization services, bundled with film supply contracts, is hardening the relationship between suppliers and large-volume end-users. This service-led approach secures long-term commitments. Berry Global Inc. leverages its extensive manufacturing scale to offer competitive pricing on these bundled contracts. Amcor plc differentiates through its focus on sustainable and high-performance films for specialized applications like food and pharmaceutical packaging.
Stretch and shrink films are highly engineered flexible packaging materials, typically produced from Linear Low-Density Polyethylene (LLDPE). These films are designed with specific elastic recovery and puncture resistance properties for unitizing and protecting products during transit and storage. While industrial bundling remains the largest application sector by volume, demand for printed packaging films for consumer goods is growing rapidly. Cast film production methods dominate due to their clarity and quiet unwind characteristics, favored in automated warehousing.
Regulatory frameworks like the US FDA's food contact substance notifications and the European Union's Regulation (EU) No 10/2011 on plastic materials shape material selection. These rules mandate strict compliance for films used in food packaging, influencing polymer and additive choices. Navigating the evolving landscape of recycled content mandates and extended producer responsibility schemes will define future competitive advantage for film manufacturers.
Market Dynamics
The market's central dynamic is the tension between escalating sustainability mandates and the performance demands of high-speed logistics. Demand for films with higher recycled content, driven by frameworks like the EU Green Deal, is concentrating investment in new material formulations and recycling infrastructure.
Growth Catalysts
- Food Packaging Evolution:Demand from the food and beverage sector for advanced films that extend the shelf-life of perishable goods, particularly fresh produce and meats, is a primary volume driver.
- E-commerce Logistics:The expansion of e-commerce fulfillment centers, especially in Southeast Asian markets like Vietnam and Indonesia, creates substantial demand for pallet unitization and load stability films.
- Recycled Content Mandates:Regulatory pressure and corporate sustainability goals are accelerating the development and adoption of stretch and shrink films containing certified post-consumer recycled (PCR) content.
Market Restraints
- Feedstock Price Volatility:Film pricing is highly sensitive to fluctuations in the cost of Linear Low-Density Polyethylene (LLDPE) resin, which is tied to global oil and natural gas markets.
- Performance Trade-offs with PCR:Incorporating high percentages of recycled content can compromise critical film properties such as puncture resistance, load containment force, and clarity, creating technical hurdles for manufacturers.
- Substitution from Corrugated Materials:In certain secondary packaging applications, particularly for case-ready displays, rigid and semi-rigid corrugated solutions present a viable substitute for shrink film bundling.
Strategic Opportunities
- Bio-based Polymers:Developing films from bio-based or compostable polymers offers a path to capture demand from brands seeking to eliminate fossil-fuel-based plastics from their packaging portfolio.
- Pharmaceutical Cold Chain:High-performance films for securing and protecting temperature-sensitive pharmaceuticals and biologics during transit represent a high-value, underpenetrated application segment.
- Smart Films for Traceability:Integrating QR codes, digital watermarks, or RFID technology into films can provide enhanced supply chain visibility and anti-counterfeiting solutions, opening new service-based revenue models.
Industry Challenges
- Regulatory Divergence:Manufacturers face complexity in navigating disparate food contact material regulations, such as the US FDA's notification process versus the European Union's Regulation (EU) No 10/2011.
- Capital Investment for Cast Film:Shifting production to meet demand for high-clarity cast films, favored in automated environments, requires significant capital expenditure on specialized extrusion lines.
- Recycling Infrastructure Gaps:The lack of harmonized collection and sorting infrastructure for flexible polyethylene films limits the available supply of high-quality post-consumer resin for film production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stretch and Shrink Film Market |
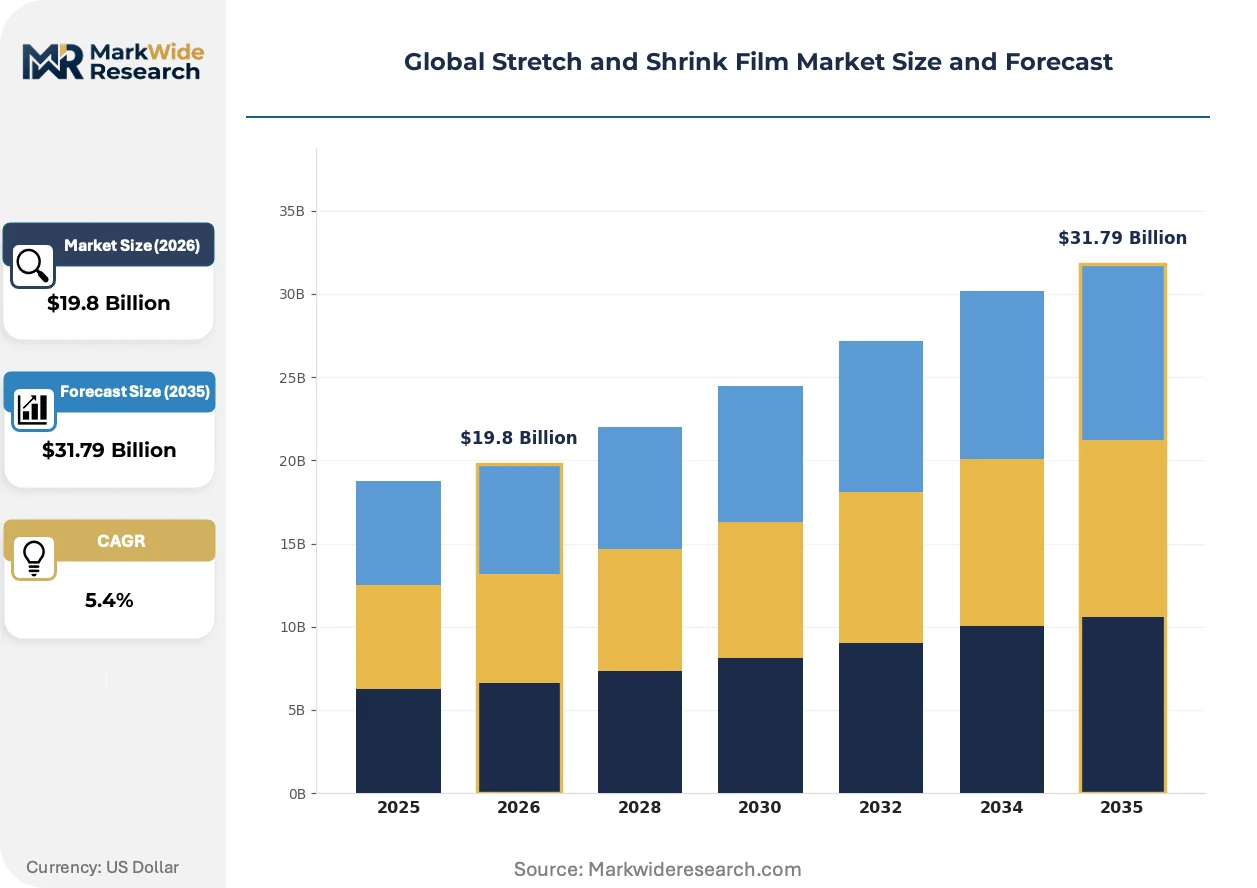
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $31.79 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Linear Low-Density Polyethylene, Low-Density Polyethylene, Polyvinyl Chloride, Polypropylene, Cast Film, Blown Film Application Sector: Food Packaging, Industrial Bundling, Pharmaceutical Wrapping, Printed Packaging, Consumer Goods, Office Supplies Packaging Format: Hand Wrap, Machine Wrap, Pre-Stretched, Center Folded, Gusseted, Perforated End Use Industry: Manufacturing Plants, Warehousing, Textile Processing, Electronics Assembly, Logistics, Agricultural Products |
| Companies Covered | Intertape Polymer Group, Berry Global Inc., Amcor plc, Millennium Packaging, Inc, Paragon Films, Sigma Plastics Group, SABIC, Bollore Inc, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stretch and Shrink Film Market Strategic Shifts & Innovations
Material science innovation is focused on resolving the conflict between performance and sustainability. The industry is pursuing films that deliver higher load containment with less material while simultaneously increasing the viability and percentage of recycled content within the polymer structure.
Advanced Polymer Formulations
Multi-layer coextrusion technology enables the creation of films with distinct layers optimized for specific properties like cling, strength, and puncture resistance. Processors are engineering thinner gauge films that provide equivalent or superior load containment compared to older, thicker films, supporting source reduction goals. This trend is integrating advanced metallocene catalysts to produce LLDPE with enhanced toughness and stretchability, allowing for significant downgauging.
Circular Economy Frameworks
The European Union's Green Deal and its associated Circular Economy Action Plan are forcing a systemic shift in film design and end-of-life management. These policies create strong incentives for designing films for recyclability and for building capacity to process post-consumer flexible packaging. Film producers targeting the European market are now prioritizing the development of mono-material PE films that are compatible with established recycling streams.
Service-Led Business Models
A shift away from purely transactional film sales is evident among large-volume customers. These buyers increasingly favor supply contracts that bundle film provision with on-site technical support, including equipment audits and wrap pattern optimization. This service-led approach displaces traditional distribution channels for major accounts by creating a direct, consultative relationship with the manufacturer, a trend most visible in the food processing and automated logistics sectors.
Global Stretch and Shrink Film Market Segmentation
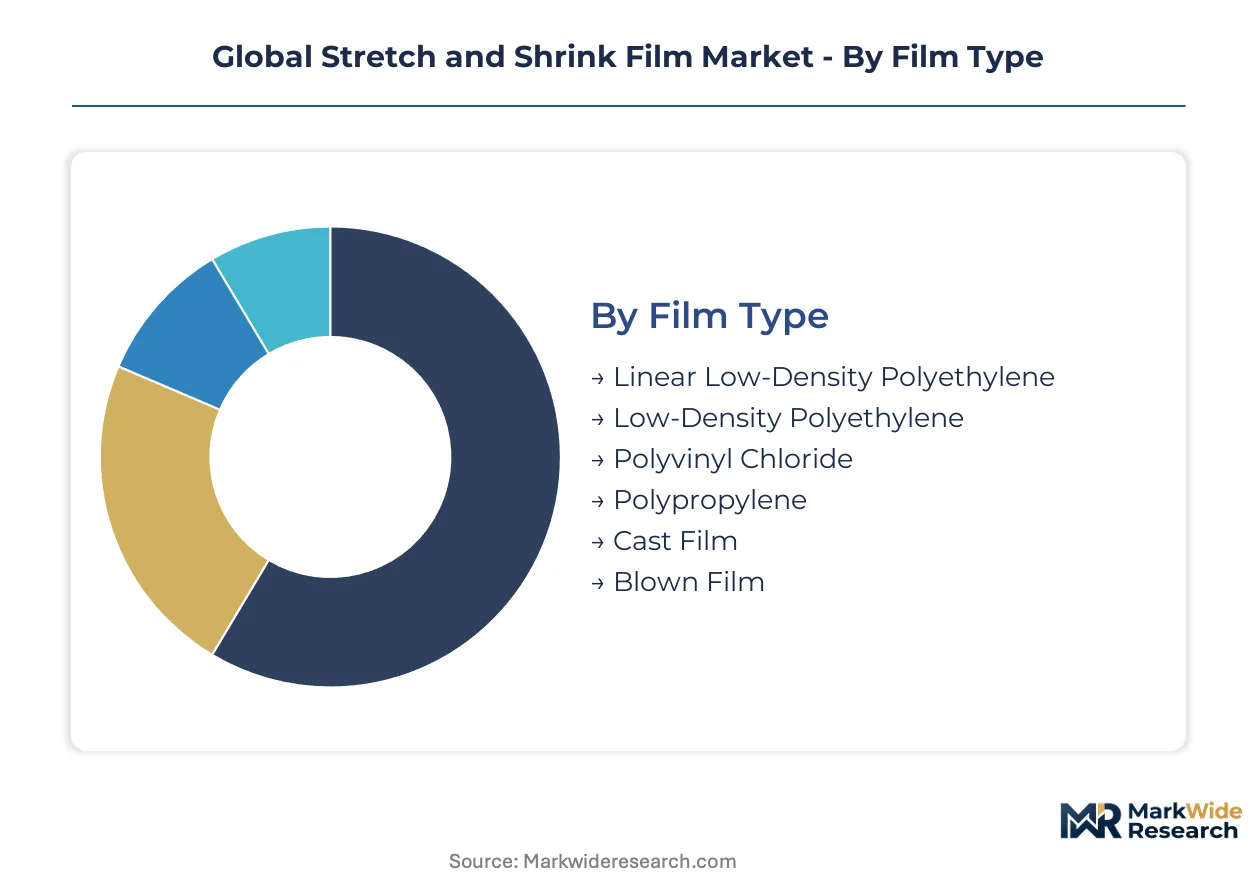
The global stretch and shrink film market differentiates across several key dimensions, reflecting the diverse material science, application requirements, and industrial contexts for these packaging solutions. Understanding these segments clarifies the varying performance demands and competitive dynamics influencing film manufacturers.
Film Type:
Film types are differentiated by their polymer composition and manufacturing process, influencing mechanical properties and end-use suitability.
- Linear Low-Density Polyethylene:This film type, primarily derived from LLDPE resin, offers high tensile strength and puncture resistance, making it suitable for heavy-duty load containment. Demand for LLDPE films is concentrated in industrial bundling applications across North America and Europe due to its robust performance.
- Cast Film:Produced by extruding molten polymer through a flat die onto a chilled roller, cast films provide superior clarity, quiet unwind, and consistent cling properties. Automated warehousing operations in Germany and Japan increasingly favor cast films for their efficiency and suitability for high-speed machinery.
- Low-Density Polyethylene:LDPE films are known for their flexibility and tear resistance, often used in lighter packaging applications.
- Polyvinyl Chloride:PVC films offer high clarity and excellent cling, commonly utilized for food wrapping and consumer product bundling.
- Polypropylene:PP films provide good stiffness and barrier properties, finding use in various consumer goods and textile packaging.
- Blown Film:Manufactured by extruding polymer through an annular die, blown films deliver high strength and tear resistance, often preferred for heavy-duty industrial wraps.
Mature deployment sits with Linear Low-Density Polyethylene. Newer deployment is concentrated in Cast Film.
Application Sector:
The market's application landscape is defined by the specific protective and unitizing needs across diverse industries.
- Food Packaging:This sector demands films that extend product shelf-life, offer barrier protection, and comply with strict food contact regulations like those from the US FDA and EU Regulation (EU) No 10/2011. Demand is high for fresh produce and meat packaging across Asian markets such as Vietnam.
- Industrial Bundling:Industrial bundling represents the largest volume application, focused on unitizing large, heavy, or irregularly shaped products for transit and storage. Manufacturing plants in China and India rely heavily on these films for securing pallets of raw materials and finished goods.
- Pharmaceutical Wrapping:Specialized films protect temperature-sensitive and sterile pharmaceutical products, crucial for cold chain integrity.
- Printed Packaging:Films with custom graphics enhance brand visibility and product appeal for consumer goods, particularly in retail environments.
- Consumer Goods:Films for consumer goods packaging prioritize visual appeal, tamper evidence, and ease of use for end-users.
- Office Supplies:Shrink films are used for bundling and protecting stationery, paper reams, and other office products.
Growth is most pronounced in Food Packaging while Industrial Bundling maintains stable adoption.
Packaging Format:
Packaging formats dictate the method of film application and material efficiency for various operational scales.
- Machine Wrap:Designed for automated stretch wrapping equipment, machine wrap films offer consistent tension and high throughput for pallet unitization. Large logistics hubs in Indonesia and the United States utilize machine wrap extensively for operational efficiency.
- Pre-Stretched:These films are stretched during manufacturing, requiring less force to apply and reducing material consumption per pallet, aligning with source reduction goals. European warehouses increasingly adopt pre-stretched films to meet sustainability targets.
- Hand Wrap:Manually applied films are suitable for low-volume packaging operations or irregular loads where automation is impractical.
- Center Folded:Films folded lengthwise are used for packaging items that require protection on multiple sides, such as consumer electronics.
- Gusseted:Films with side pleats accommodate bulky or irregularly shaped items, providing a custom fit for diverse products.
- Perforated:Films with small holes allow for product breathability, essential for fresh produce or items requiring ventilation.
The transition towards Pre-Stretched formats optimizes material use, contrasting with traditional Hand Wrap applications.
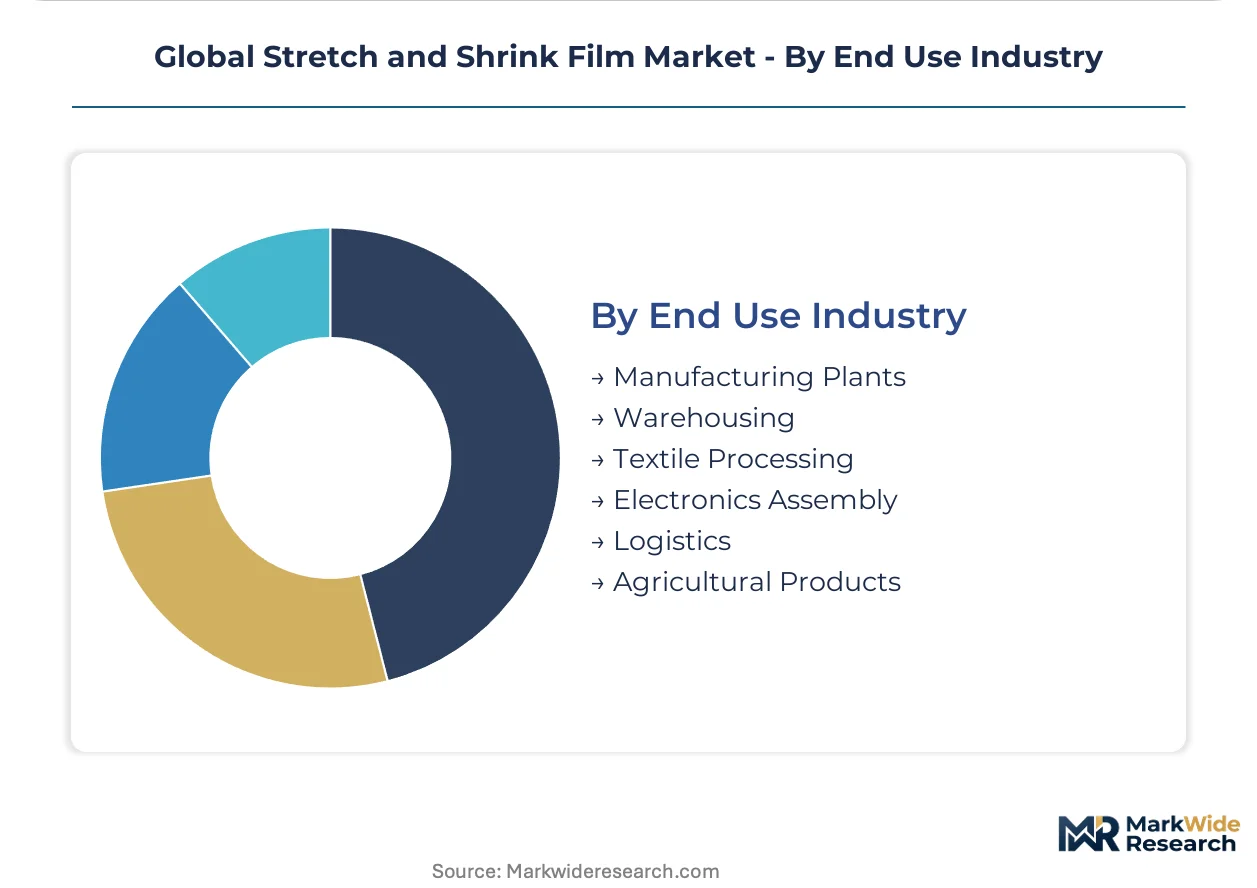
End Use Industry:
End-use industries determine the volume and performance requirements for stretch and shrink films.
- Warehousing:This sector requires films for pallet stabilization, product protection, and inventory management within storage facilities. Expanding e-commerce fulfillment centers in Southeast Asia, including Vietnam, drive significant demand for warehousing films.
- Logistics:Films in the logistics sector ensure product integrity and security during transportation across various modes, from road freight to maritime shipping. Global shipping operations, particularly from ports in Singapore and Rotterdam, depend on robust logistics films.
- Manufacturing Plants:Films secure components, raw materials, and finished goods on pallets within production environments.
- Textile Processing:Films protect textiles from dust, moisture, and damage during manufacturing, storage, and distribution.
- Electronics Assembly:High-performance films safeguard sensitive electronic components from static, dust, and physical impact.
- Agricultural Products:Films preserve freshness and protect produce from environmental factors during storage and transport from farms.
High-volume demand originates from Warehousing, with critical protection needs met by Electronics Assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's strategic position as a global logistics and transshipment hub drives significant demand for stretch and shrink films. The city-state's advanced warehousing infrastructure requires high-performance films for efficient load unitization and protection. This concentration of logistics activity influences film specifications across the broader Southeast Asian market.
Vietnam
E-commerce logistics expansion and the growing food processing sector are primary demand drivers in Vietnam. The country's national regulations increasingly emphasize packaging material sustainability. Industrial zones around Ho Chi Minh City require consistent supplies of machine wrap films for export goods.
Indonesia
Rapid growth in warehousing and consumer goods manufacturing underpins film demand across Indonesia. The government's focus on boosting domestic production influences material sourcing. Jakarta's expanding network of distribution centers relies heavily on efficient pallet stabilization films.
Germany
Automated warehousing systems and stringent food safety standards shape film consumption in Germany. EU Regulation (EU) No 10/2011 mandates strict compliance for food contact materials. The Rhine-Ruhr region's advanced manufacturing facilities utilize high-clarity cast films for automated processes.
China
Industrial bundling for export-oriented manufacturing and a large domestic consumer market drive substantial film volumes in China. The country's dual carbon goals are accelerating the adoption of recycled content in packaging. The Pearl River Delta's extensive factory networks depend on cost-effective, high-strength films.
United States
The vast network of logistics hubs and a mature food packaging industry generate consistent demand for stretch and shrink films in the United States. US FDA's food contact substance notifications govern material selection for perishable goods. The Chicago metropolitan area's central distribution infrastructure utilizes machine wrap films for efficient palletization.
Global Stretch and Shrink Film Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the stretch and shrink film market, creating a varied competitive structure. The industry blends large, integrated manufacturers with specialized converters and regional niche players. Strategic archetypes include scale-driven commodity producers, innovation-focused specialists, and regional service providers. Dominant competitive moves involve capacity expansion to achieve cost leadership and strategic partnerships to access new technologies.
Within the scale-driven manufacturing tier, Berry Global Inc. exemplifies extensive production capabilities. Amcor plc represents a focus on high-performance and sustainable films for specialized applications. Sigma Plastics Group sits within the large independent film producer segment, offering a broad product portfolio across various end-use industries.
| Leading Market Players |
|---|
| Intertape Polymer Group |
| Berry Global Inc. |
| Amcor plc |
| Millennium Packaging, Inc |
| Paragon Films |
| Sigma Plastics Group |
| SABIC |
| Bollore Inc |
| Sealed Air |
| Others |
Cost & Logistics Intelligence
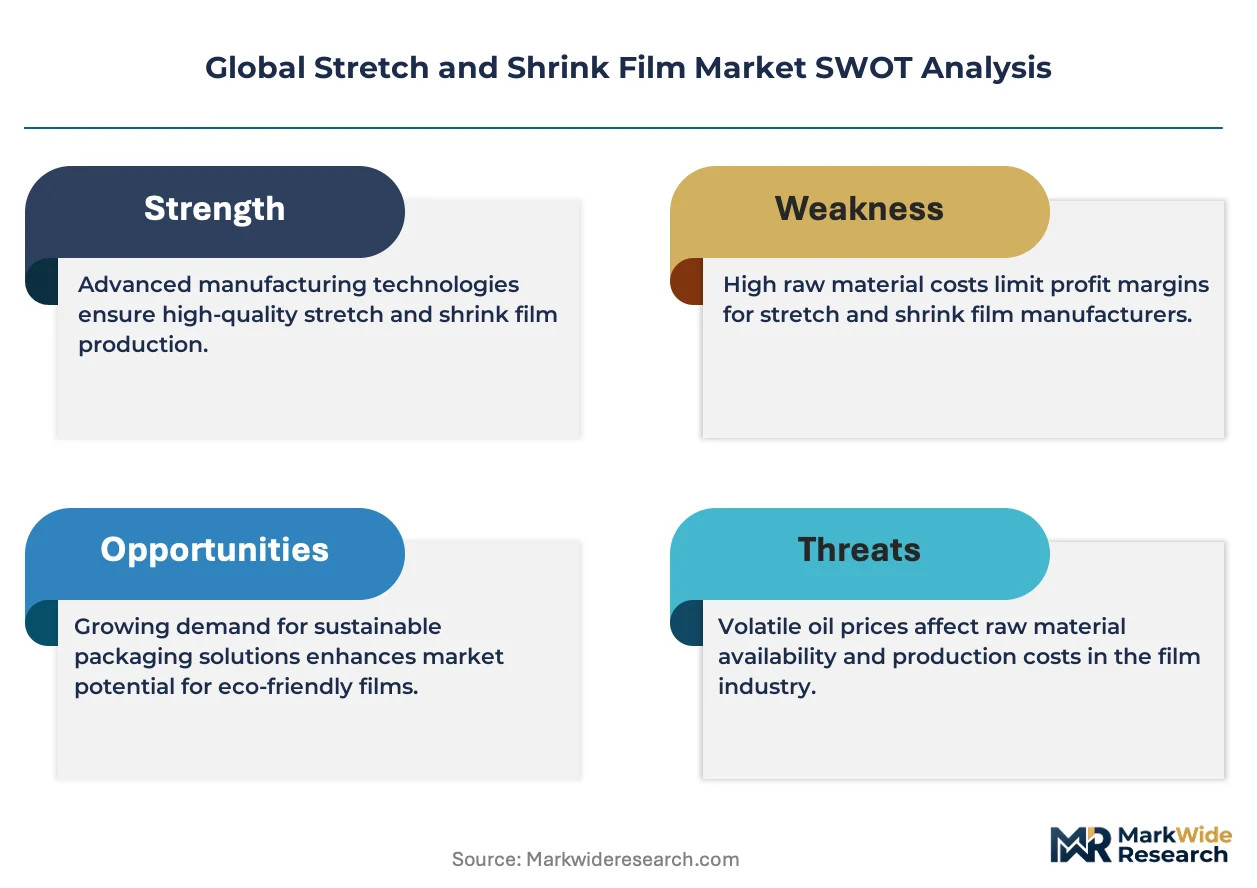
A clear performance-tier divergence between commodity films and specialized, high-performance films shapes both pricing strategies and supply chain configurations. This bifurcation influences material sourcing and value proposition across the market.
Pricing Analysis
Margin tightening in commodity film segments traces to persistent feedstock price volatility, particularly for Linear Low-Density Polyethylene. Pricing primarily operates on contract-based long-term offtake agreements for large buyers and commodity spot pricing for smaller volumes. Price differentiation stems from film quality grades, certified recycled content, and bundled on-site application services. Large-volume end-users exhibit lower price sensitivity due to service integration, while smaller buyers remain highly sensitive to spot market fluctuations.
Supply Chain Analysis
Reverse logistics for flexible polyethylene films currently faces significant infrastructure gaps, limiting the available supply of high-quality post-consumer resin. Geographic supply concentration for film production centers in China and the United States, drawing heavily from LLDPE resin produced in the Middle East and North America. Feedstock price volatility represents a primary structural risk across the supply chain. Distribution runs through direct sales channels for major accounts, often bundled with services, and through traditional distributors for smaller, fragmented buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, as advanced polymer formulations and multi-layer coextrusion replace older, less efficient film structures. This shift drives demand for materials offering superior performance with reduced environmental impact.
For Market Incumbents:Lock in long-term supply contracts with major end-users by bundling film provision with on-site application optimization services. Invest in advanced polymer R&D to develop mono-material PE films compatible with EU recycling streams, mitigating the threat of regulatory penalties and substitution from corrugated materials. Expand manufacturing capacity in high-growth logistics hubs like Vietnam and Indonesia, securing market share against regional competitors.
For New Entrants and Emerging Players:A price-point gap exists in specialized, high-performance films for niche applications like pharmaceutical cold chains and bio-based packaging alternatives. Target the e-commerce logistics sector in Southeast Asia with innovative, sustainable film solutions, emphasizing certified post-consumer recycled content. Focus on a service-led go-to-market angle that provides technical support and wrap optimization to penetrate automated warehousing operations.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized film manufacturers with proprietary sustainable material science or strong regional distribution networks in high-growth markets. The long-term viability of this market remains strong, driven by sustained demand from food packaging and e-commerce logistics over the next decade. Target acquisition profiles include companies with intellectual property in bio-based polymers or robust recycling infrastructure integration. Practitioners should monitor the adoption rate of digital watermarking technology for early signals of smart film market penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Achieves compliance with EU Green Deal mandates and attracts sustainability-focused brands. |
| Long-term Supply Agreements | Secures stable revenue streams and hardens relationships with large-volume end-users. |
| Capacity Expansion in Southeast Asia | Captures demand from rapidly expanding e-commerce and manufacturing sectors in Vietnam. |
| Strategic Partnerships for Recycling | Addresses recycling infrastructure gaps and ensures supply of high-quality PCR content. |
| Product Launch: Bio-based Films | Targets brands seeking to eliminate fossil-fuel-based plastics from their packaging portfolios. |
Research Approach
Customs and trade data, corporate sustainability reports, and regulatory body publications from the US FDA and EU Regulation (EU) No 10/2011 formed the secondary backbone of this study. Primary research involved in-depth interviews with film manufacturers' R&D heads, logistics managers, food packaging procurement specialists, and recycling infrastructure operators. This approach ensured a comprehensive bottom-up and top-down triangulation of market insights.
Historical trendline analysis established foundational growth patterns, informing the market sizing and competitive landscape evaluation across the analysis window. Segmentation dimensions modeled included film type, application sector, packaging format, end-use industry, and regional regulatory compliance. Compound Annual Growth Rates were derived from robust supply-demand models. Key forecast inputs included Linear Low-Density Polyethylene price projections and e-commerce growth rates in emerging markets.
Inputs from corporate filings and industry association reports were available through the study window; gaps in global recycling infrastructure data introduce uncertainty bands. Forecasts reflect assumptions regarding LLDPE price stability and sustained regulatory pressure. Practitioners should monitor geopolitical shifts impacting feedstock availability for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Special Effects Laminate Films Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Decorative Films and Foils Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Dual Ovenable Lidding Films Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Clear Barrier Films Market
Packaging Barrier Films
Nano Sealers Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market