
 Perforated Packaging Film Market | 2026-2036
Perforated Packaging Film Market Size, Share, and Industry Trends Forecast 2026-2036
Perforated Packaging Film Market Analysis
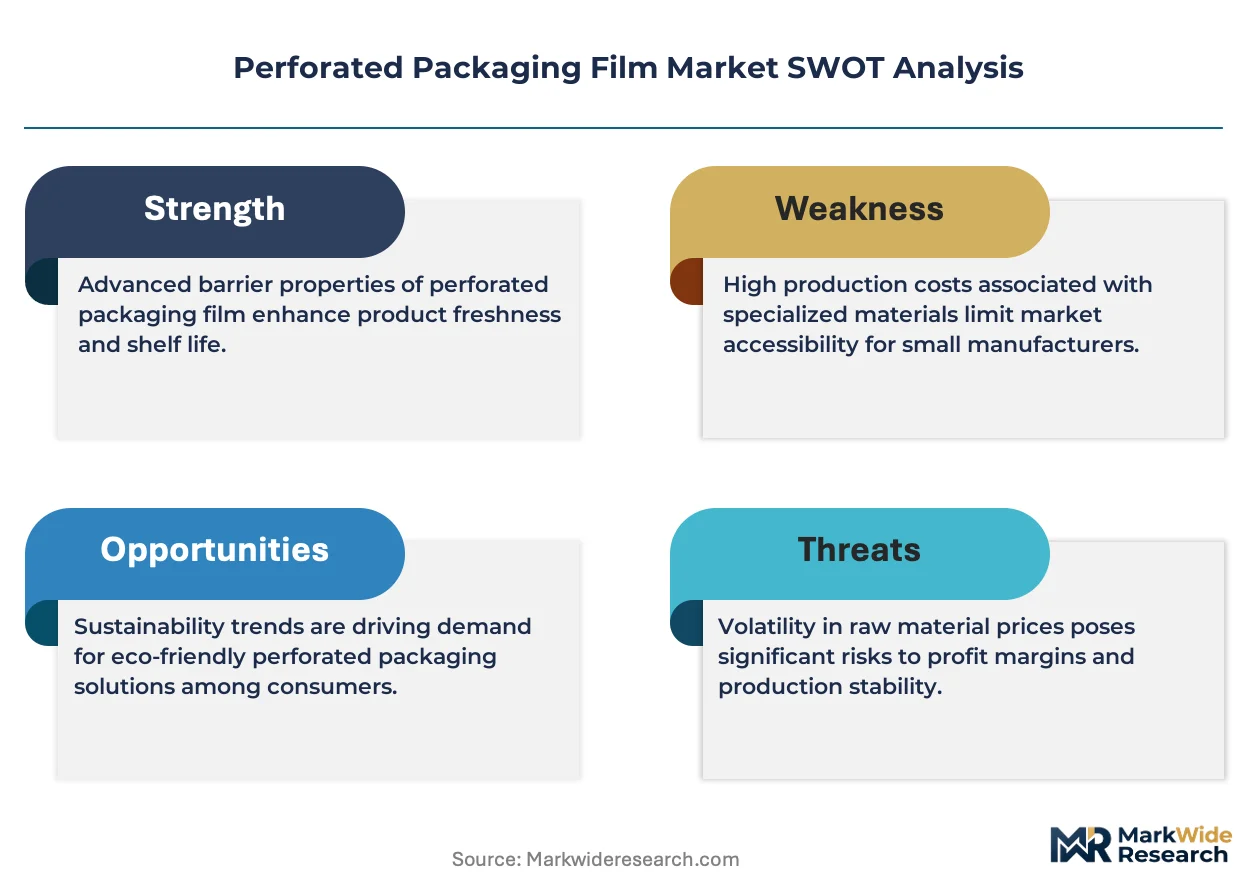
Fresh produce packers are rotating toward breathable film solutions as retailers impose stricter shelf-life guarantees. Mondi plc leverages its integrated paper and film operations to supply perforated structures with controlled permeability. Amcor plc anchors its position through R&D intensity in laser-perforation precision. Berry Global Group, Inc. competes via manufacturing scale across North American food corridors.
Perforated packaging film consists of polymeric substrates—typically polyethylene, polypropylene, or biodegradable resins—engineered with micro-perforations or macro-pores to regulate gas exchange, moisture vapor transmission, and pressure equalization. These films maintain product freshness while preventing condensation-induced decay in respiring commodities. Polyethylene occupies the largest volume share due to cost efficiency and heat-seal compatibility, though biodegradable grades are gaining fastest as European retailers mandate compostable alternatives. Snack packaging and fresh produce applications concentrate margin pools where oxygen transmission rates differentiate premium tiers from commodity supply.
FDA food-contact regulations govern migration limits for perforated films serving the US food industry, while REACH and the EU Green Deal restrict Substances of Very High Concern in imported substrates. EFSA safety assessments further condition market access for novel biodegradable chemistries. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between reformulating for compliance or exiting regulated European channels.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is compressing converter margins while forcing rapid substrate reformulation toward mono-material and certified compostable structures.
Growth Catalysts
- Extended Producer Responsibility frameworks:Germany's centralized retail distribution networks favor standardized breathable film formats, creating pull-through demand across fresh produce corridors.
- Biodegradable resin innovation:Polylactic acid and polyhydroxyalkanoate substrates achieve functional parity with polyethylene in moisture vapor transmission rates.
- Laser-perforation precision:Controlled atmosphere packaging for berries and leafy greens demands oxygen transmission rate tolerances below 5% variance.
Market Restraints
- Ethylene feedstock volatility:Crude oil price swings transmit directly to polyethylene film margins, compressing converter profitability during upstream spikes.
- Masterbatch supply concentration:European additive suppliers control 70% of breathable film additive formulations, creating single-source vulnerability.
- Compostable certification timelines:TÜV Austria and BPI certification cycles extend 14-18 months, delaying market entry for novel biodegradable chemistries.
Strategic Opportunities
- Ready-to-eat salad vertical:Modified atmosphere packaging for cut vegetables remains underpenetrated in Eastern European retail channels.
- Dual carbon goals in China:SAMR guidelines on plastic reduction create import demand for certified biodegradable perforated structures.
- E-commerce fresh delivery:Direct-to-consumer produce subscriptions require pressure-equalizing films that withstand last-mile handling stress.
Industry Challenges
- Migration testing capacity:EFSA safety assessments for novel biodegradable chemistries face 24-month backlogs at accredited laboratories.
- Legacy extrusion asset retrofit:Converting cast film lines to handle biodegradable resins requires $2-4 million per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perforated Packaging Film Market |
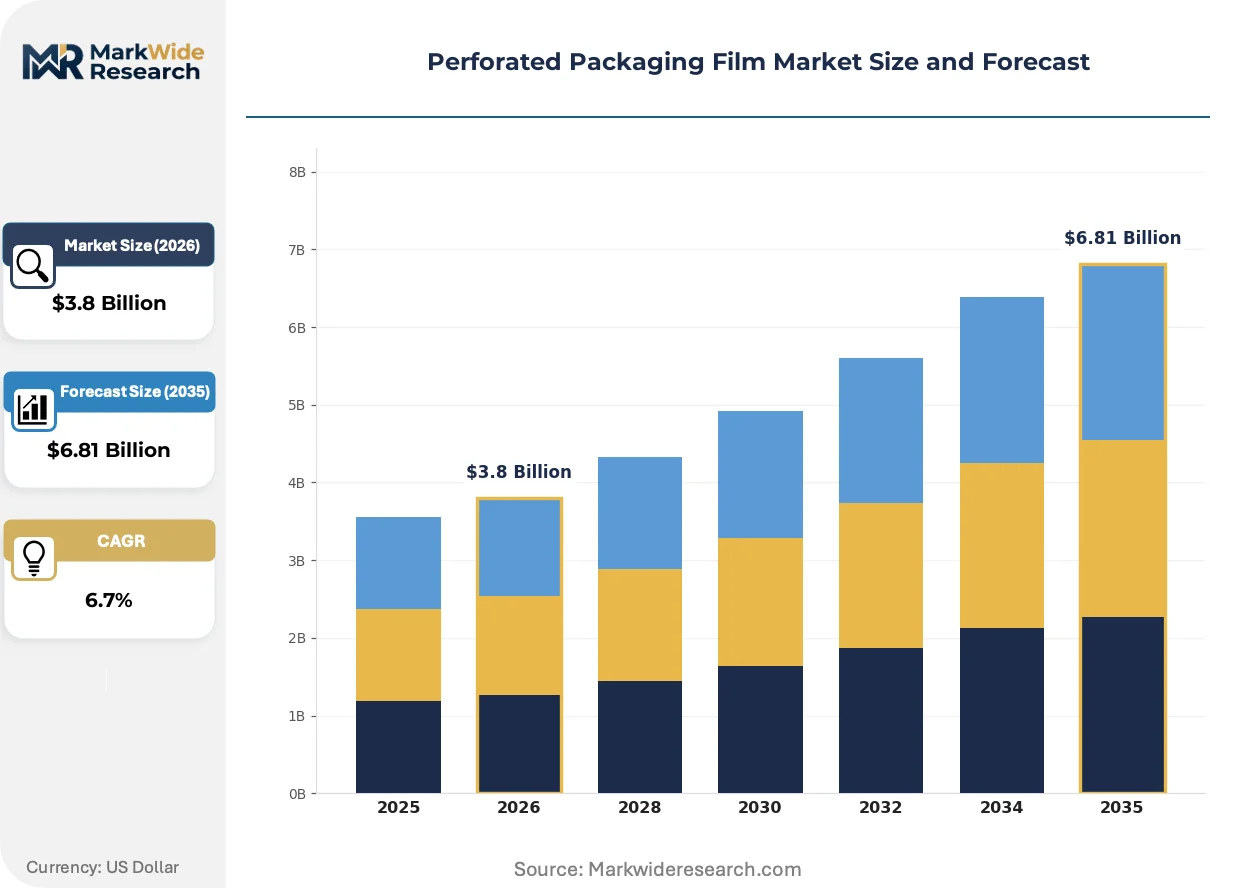
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Biodegradable End User: Food Industry, Healthcare, Consumer Goods, Electronics Application: Snack Packaging, Medical Packaging, Retail Packaging, Fresh Produce Thickness: Thin Film, Medium Film, Thick Film, Custom Thickness |
| Companies Covered | Mondi plc, ProAmpac, LLC, Amcor plc, Uflex Ltd., Huhtamaki Oyj, Berry Global Group, Inc., Sonoco Products Company, Winpak Ltd., Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perforated Packaging Film Market Emerging Trajectories
Active and intelligent packaging integration is redefining competitive differentiation, with sensor-enabled films moving from pilot to commercial scale across premium produce segments.
Electrochemical oxygen scavenger integration into perforated substrates is supplanting passive gas-flush methods in high-value berry exports. Chilean and Peruvian avocado packers are adopting these films for 35-day ocean freight cycles. The technology is supplanting conventional modified atmosphere packaging by eliminating the need for nitrogen injection infrastructure at packing houses.
REACH substance restrictions on phthalate plasticizers are forcing compounders toward bio-based alternatives in cling film applications. ECHA's 2023 update to the Candidate List added four polymer additives commonly used in food-contact films. German retailers are responding by mandating full material disclosure from converters serving their private-label programs.
Centralized procurement by European supermarket alliances is consolidating supplier panels and compressing tender cycles from annual to quarterly. Aldi and Lidl's joint purchasing entities now specify oxygen transmission rate bands rather than supplier brands. This concentration is most visible in the Benelux region, where three buying groups control 80% of breathable film volume.
Perforated Packaging Film Market Segmentation
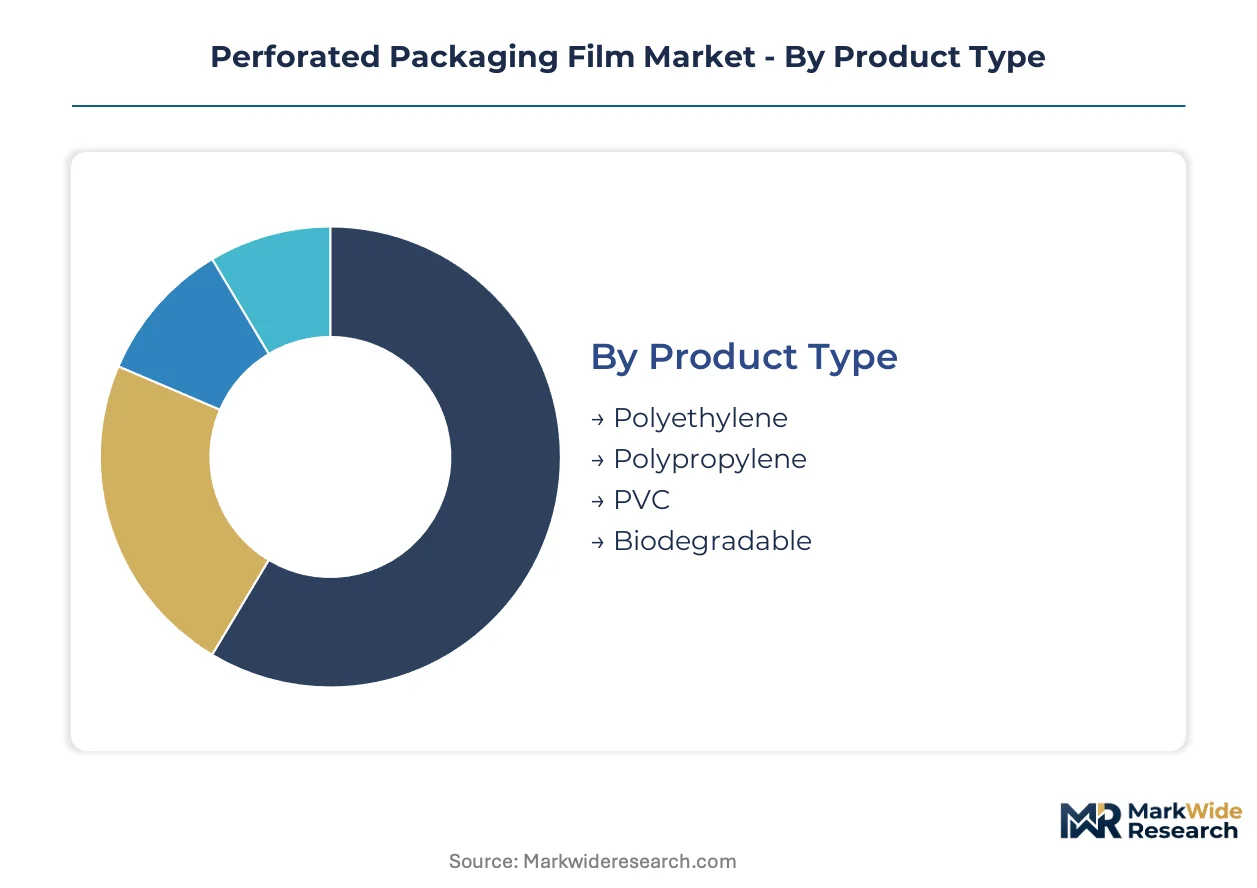
Segmentation in perforated packaging film reveals how substrate chemistry, end-use requirements, and application-specific gas transmission needs fragment manufacturing priorities across converter operations. Channel differentiation separates commodity polyethylene supply for mass retail from precision-engineered biodegradable grades serving regulated European markets.
Product Type:
Polyethylene dominates mass-market fresh produce corridors through established extrusion infrastructure, while biodegradable alternatives command premium positioning in compostable-mandated channels.
- Polyethylene:Linear low-density and metallocene grades provide heat-seal compatibility and cost efficiency for high-volume snack and produce applications. German retail distribution networks standardize on polyethylene breathable films for their centralized procurement systems, though REACH substance restrictions are forcing additive reformulation.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate substrates achieve functional parity in moisture vapor transmission for premium produce segments. TÜV Austria and BPI certification requirements in the Benelux region create 14-18 month entry barriers that concentrate supply among pre-qualified converters.
- Polypropylene:Cast and oriented grades serve medical packaging where clarity and sterilization compatibility matter. Biaxially oriented variants handle retort applications in ready-meal segments.
- PVC:Cling film applications persist in specific produce wrapping despite ECHA plasticizer restrictions driving substitution toward bio-based alternatives.
By volume, polyethylene leads. By growth pace, biodegradable grades are climbing the fastest.
End User:
Cost tier stratification separates food industry volume buyers from healthcare purchasers prioritizing migration testing documentation and lot traceability.
- Food Industry:Fresh produce packers and snack manufacturers drive the majority of perforated film tonnage. FDA food-contact regulations govern US migration limits while EFSA assessments condition European market access for novel biodegradable chemistries.
- Healthcare:Sterile barrier applications demand validated oxygen transmission rate tolerances and particulate-free perforation methods. Laser perforation precision meets surgical kit and medical device packaging requirements where variance below 5% is mandatory.
- Consumer Goods:Pressure-equalizing films for e-commerce subscription boxes and household products require last-mile durability specifications.
- Electronics:Anti-static perforated films protect sensitive components during controlled atmosphere shipping.
Food industry procurement concentrates volume; healthcare commands the highest margin tiers.
Application:
Application-specific oxygen transmission requirements create technology moats between passive perforation and active scavenger-integrated solutions.
- Fresh Produce:Respiring commodities demand precise gas exchange modulation to prevent condensation-induced decay. Chilean and Peruvian avocado exporters adopt electrochemical oxygen scavenger films for 35-day ocean freight cycles.
- Snack Packaging:Nitrogen-flush compatibility and aroma barrier properties differentiate premium nut and chip packaging from commodity supply.
- Medical Packaging:Sterile barrier integrity and ethylene oxide sterilization compatibility define specification compliance.
- Retail Packaging:Private-label programs across Aldi and Lidl purchasing entities now specify oxygen transmission rate bands rather than supplier brands.
Fresh produce captures the steepest expansion trajectory as retailers impose stricter shelf-life guarantees.
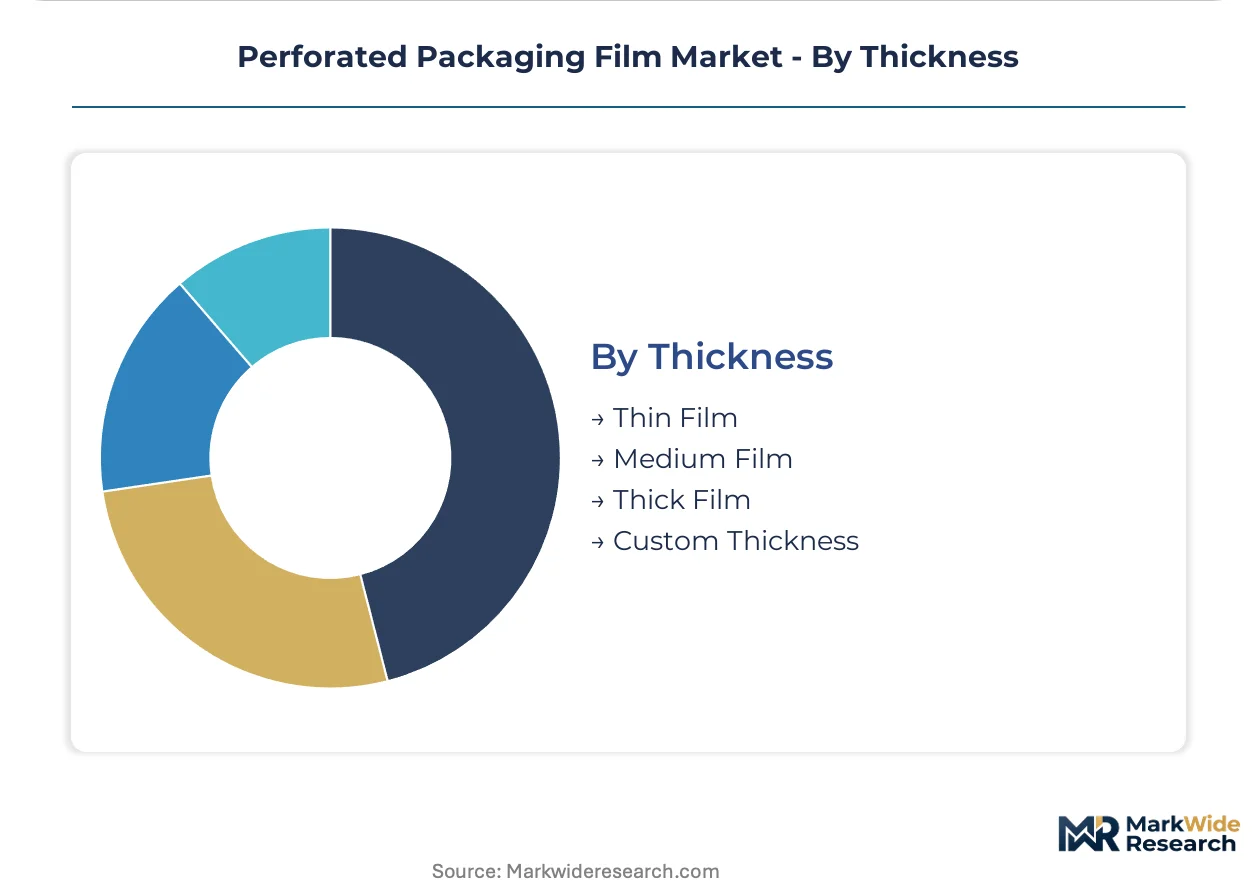
Thickness:
Thickness selection maps directly to mechanical stress requirements in handling and distribution channels.
- Thin Film:Sub-25 micron gauges serve lightweight snack portions and cost-optimized produce overwrap. E-commerce fresh delivery channels favor thin films for shipping weight reduction.
- Medium Film:25-50 micron range balances puncture resistance with material efficiency for standard retail produce applications.
- Thick Film:Above 50 micron structures withstand automated packing line stress and extended distribution cycles for centralized retail networks.
- Custom Thickness:Project-based specifications for modified atmosphere packaging of cut vegetables in underpenetrated Eastern European retail channels.
Medium film holds the volume center; custom thickness commands project premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Germany, the United States, China, and India, with specialized production lines serving distinct regulatory environments and retail procurement systems.
Germany
Centralized retail distribution networks at Aldi and Lidl drive standardization in breathable film specifications across fresh produce corridors. The EU's Packaging and Packaging Waste Regulation mandates mono-material structures and certified compostable alternatives by 2030. The Benelux-adjacent Rhine-Ruhr industrial zone hosts pre-qualified converters with TÜV Austria certification for biodegradable grades.
United States
Fresh produce distributors in California and Florida are expanding perforated film usage to meet retailer shelf-life guarantees for berries and leafy greens. FDA food-contact regulations govern migration limits for polyethylene and polypropylene substrates. The Midwest food processing corridor around Chicago concentrates extrusion capacity serving national snack packaging demand.
China
SAMR guidelines on plastic reduction and dual carbon goals are creating import demand for certified biodegradable perforated structures in coastal megacities. Domestic converters in the Yangtze River Delta are retrofitting cast film lines to handle polylactic acid resins. Shanghai-based fresh delivery platforms require pressure-equalizing films for last-mile e-commerce distribution.
India
Expanding organized retail in Maharashtra and Karnataka is adopting breathable packaging for cut vegetables and ready-to-eat salads. FSSAI food safety standards condition market access for imported film substrates. The Gujarat chemical belt is developing masterbatch formulations to reduce dependence on European additive suppliers.
Chile
Avocado and berry exporters are adopting electrochemical oxygen scavenger films for 35-day ocean freight cycles to European markets. SAG agricultural export regulations align phytosanitary packaging requirements with destination country standards. The Valparaíso port cluster concentrates value-added packing operations serving Peruvian and Chilean produce exports.
Perforated Packaging Film Market Vendor Landscape
Concentration sits with integrated packaging conglomerates and specialized film converters serving distinct tiered demand. The vendor base separates into scale-driven commodity suppliers, precision-engineered specialty producers, and vertically integrated paper-film hybrid operators. Strategic moves center on laser-perforation technology licensing and backward integration into resin compounding to secure additive supply.
Within the integrated multinational tier, Mondi plc, Amcor plc, and Berry Global Group, Inc. exemplify divergent positioning archetypes. Mondi leverages its paper and film integration to supply controlled-permeability structures. Amcor anchors its presence through precision engineering in gas-exchange modulation. Berry Global occupies the manufacturing scale vector across North American food corridors. These three represent the dominant competitive templates shaping procurement negotiations with centralized retail buying groups.
| Leading Market Players |
|---|
| Mondi plc |
| ProAmpac, LLC |
| Amcor plc |
| Uflex Ltd. |
| Huhtamaki Oyj |
| Berry Global Group, Inc. |
| Sonoco Products Company |
| Winpak Ltd. |
| Sealed Air Corporation |
| Others |
Supply Flow & Price Mechanics
Biodegradable resin substitution for polyethylene simultaneously redraws supply geography toward certified European converters and compresses pricing power for commodity-grade producers serving mass retail channels. This material transition forces buyers to accept extended certification timelines and premium positioning in exchange for regulatory compliance.
Pricing Analysis
EU's Packaging and Packaging Waste Regulation dictates the pricing tier structure across the perforated film market. Three-tier pricing separates TÜV Austria-certified biodegradable grades from REACH-compliant polyethylene and uncertified commodity supply. Price differentiation rests on certification level and volume scale, with centralized retail buying groups extracting concessions through quarterly tender cycles. Cost compression in standard polyethylene tiers is intensifying because crude oil feedstock volatility transmits directly to converter margins. Snack manufacturers exhibit highest price sensitivity, while healthcare sterile barrier purchasers prioritize migration documentation over unit economics.
Supply Chain Analysis
Germany and the United States anchor extrusion capacity for polyethylene and precision laser-perforation systems. China and India feed from polylactic acid resin imports and domestic masterbatch formulation development. Raw material dependencies center on ethylene feedstock, breathable film additives, and electrochemical scavenger components. Single-source vulnerability concentrates in European additive suppliers controlling the majority of formulation intellectual property. Distribution runs through centralized retail procurement entities in the Benelux region and Midwest food processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has consolidated around Aldi and Lidl purchasing alliances, compressing supplier margins and accelerating panel consolidation among converters.
For Market Incumbents: Compound defensive positioning through backward integration into resin compounding and captive additive supply. Secure TÜV Austria certification ahead of EU Green Deal mandates to preempt competitor entry. Laser-perforation precision R&D serves as the primary margin defense against commodity-grade substitution. For New Entrants and Emerging Players: E-commerce fresh delivery technical service gaps expose white-space opportunity for pressure-equalizing film specialists. Target Eastern European ready-to-eat salad channels where modified atmosphere packaging penetration remains limited. Deploy direct technical sales teams to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale converters with pre-qualified biodegradable certification and established retail panel relationships. The five-to-ten year viability window favors assets with demonstrated EFSA safety assessment navigation. Monitor SAMR enforcement patterns in China as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive additive supply secures margin protection against European supplier concentration. |
| Biodegradable Certification Investment | TÜV Austria pre-qualification unlocks Benelux retail procurement access ahead of regulatory deadlines. |
| Laser-Perforation Capacity Expansion | Precision gas-exchange modulation commands healthcare and premium produce margin tiers. |
| E-commerce Channel Technical Partnership | Last-mile durability specifications create sticky relationships with Shanghai-based delivery platforms. |
| Eastern European Distribution Buildout | Underpenetrated ready-to-eat salad channels offer first-mover positioning before retail consolidation. |
Methodological Framework
A spread of perspectives from extrusion plant managers, retail category buyers, regulatory affairs leads at converters, and masterbatch formulation specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC filings from integrated packaging conglomerates, EFSA safety assessment databases, and REACH substance restriction updates. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Segmentation dimensions modeled include substrate chemistry tier, end-use industry vertical, application-specific oxygen transmission requirements, and regional regulatory cluster. CAGRs were derived through trend extrapolation anchored in historical substitution patterns and forward policy implementation schedules. Forecast inputs incorporated EU PPWR compliance timelines, SAMR plastic reduction enforcement trajectories, and fresh produce export volume projections from Chile and Peru.
Material uncertainties — ethylene feedstock price spikes, EFSA laboratory backlog extensions, and sudden tariff adjustments on biodegradable resin imports — sit outside the modeled envelope. Forecasts reflect assumptions about certification cycle durations and retail procurement centralization pace. Recalibration cycles align with material shifts in regulatory enforcement and substitute material cost parity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Global Stretch and Shrink Film Market
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Clear Barrier Films Market
Packaging Barrier Films
USA Barrier Coated Paper Market
Packaging Barrier Films
Barrier Coated Carton Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Pipe Insulation Film Market