
 Europe Barrier Coated Paper Market | 2026-2036
Europe Barrier Coated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Barrier Coated Paper Market Foresight
Asset-light leasing models for coating lines is tilting competitive dynamics toward mid-sized converters that previously lacked capital for barrier technology investments. UPM-Kymmene leverages its integrated pulp-to-paper chain to secure raw material cost advantages across Nordic operations. Mondi Group differentiates through proprietary extrusion coating capabilities that span multiple barrier grades. BillerudKorsnäs specializes in high-strength fiber formulations for demanding food-contact applications.
Europe barrier coated paper comprises paper substrates treated with polymeric, wax, or bio-based layers to impart resistance against moisture, grease, oxygen, or heat, typically achieving barrier values below 10 g/m²/day water vapor transmission for food-grade specifications. The material serves primarily as a renewable substrate for packaging applications where product protection and shelf-life extension compete with plastic alternatives. Waterproof and greaseproof paper categories anchor current volume, reflecting entrenched demand from bakery and fast-food wrapping segments. Heat sealable paper represents the fastest-growing product type, driven by pouch-format adoption in ready-meal and pharmaceutical packaging. Food packaging dominates application-level margins, while medical packaging commands premium positioning due to sterilization compatibility requirements and stricter validation protocols.
EMA food-contact frameworks, EU Packaging and Packaging Waste Regulation targets, and national implementations of the EU Green Deal collectively mandate recyclability and recycled content thresholds that reshape formulation choices across the value chain. REACH compliance for coating chemistries and emerging restrictions on per- and polyfluoroalkyl substances constrain traditional fluorocarbon barrier solutions while accelerating bio-based polymer development. Stakeholders must monitor regulatory timelines for PFAS restrictions and recyclability performance standards to align R&D pipelines with compliance windows.
Market Dynamics
EU Packaging and Packaging Waste Regulation recyclability mandates are compressing formulation timelines across European converters, forcing simultaneous PFAS phase-out and bio-based barrier scale-up before 2030 compliance windows close.
Growth Catalysts
- REACH-compliant bio-polymer coatings:ECHA restrictions on fluorocarbon chemistries redirect R&D spending toward polylactic acid and chitosan formulations that maintain grease resistance without persistent organic pollutants.
- Quick-service restaurant fiber transitions:Chains across France and Germany are eliminating plastic-lined wraps through centralized procurement mandates that specify heat-sealable paper for hot-food applications.
- EMA sterilization validation protocols:Medical device packaging requirements for gamma-stable barriers create premium positioning for coated grades that withstand irradiation without delamination or yellowing.
Market Restraints
- Pulp cost volatility:Nordic softwood pulp contracts fluctuate with energy-intensive drying costs, squeezing converter margins when barrier coating add-ons cannot pass through to price-sensitive bakery segments.
- Extrusion coating equipment concentration:German and Italian machinery suppliers control 70% of installed high-speed coating lines, creating capex bottlenecks for mid-tier converters seeking barrier capability.
- Performance gap versus multilayer plastics:Current bio-based barriers achieve 8-12 g/m²/day water vapor transmission, insufficient for wet-ready-meal shelf-life requirements without secondary overwrap.
Strategic Opportunities
- Poland and Czech Republic converter expansion:Underpenetrated Central European markets lack indigenous barrier coating capacity, creating first-mover positioning for integrated producers establishing toll-coating hubs near Warsaw and Prague.
- Pharmaceutical cold-chain pouches:EMA temperature excursion guidelines for biologics drive demand for insulated paper-based shippers that combine fiber cushioning with moisture barriers.
- Digital print compatibility layers:Water-based inkjet receptive coatings that integrate with existing barrier stacks enable short-run customization for regional food brands without separate lamination steps.
Industry Challenges
- PFAS analytical detection expertise:Converters lack in-house mass spectrometry capability to verify sub-ppm fluorine content for EU Green Deal compliance, forcing reliance on third-party certification delays.
- Heat-seal jaw retrofit requirements:Legacy form-fill-seal lines designed for plastic films require temperature and pressure recalibration that extends validation timelines by 4-6 months for paper barrier adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Barrier Coated Paper Market |
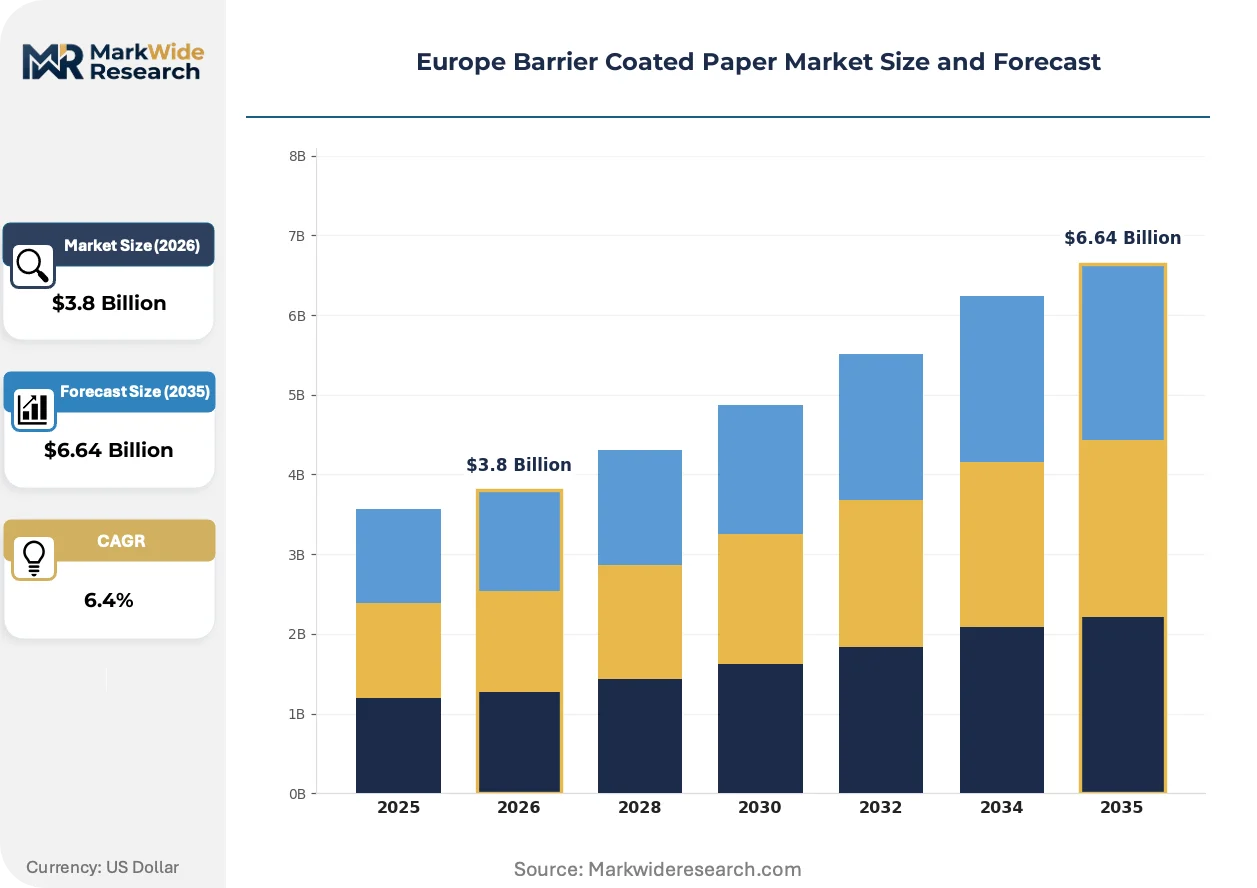
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterproof Paper, Heat Sealable Paper, Greaseproof Paper, Moisture Resistant Paper Application: Food Packaging, Medical Packaging, Industrial Applications, Graphic Arts End User: Food & Beverage Industry, Healthcare Sector, Retail Vendors, Printing Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | DS Smith, UPM-Kymmene, Mondi Group, Sappi, Ahlstrom-Munksjö, Stora Enso, BillerudKorsnäs, Cascades, Smurfit Kappa, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Barrier Coated Paper Market Shifts & Advancements
Virtualization of coating formulation development is compressing experimental cycles, while regulatory chemistry restrictions and buyer procurement centralization reshape how barrier specifications reach commercial scale.
Water-based polymer dispersions are virtualizing laboratory-scale barrier testing through cloud-connected pilot coaters that simulate full-production line conditions without material waste. Nordic pulp suppliers deploy these systems to validate customer-specific formulations remotely, cutting sample turnaround from weeks to days. The technology is virtualizing traditional technical service relationships, enabling smaller converters to access formulation expertise previously reserved for volume accounts.
EU Green Deal PFAS restriction proposals are forcing coating chemists to eliminate all perfluorinated substances from food-contact formulations by 2026. ECHA hazard classification updates classify side-chain fluorinated polymers as substances of very high concern, triggering automatic substitution obligations across member states. Bakery and confectionery packaging segments face the steepest compliance curves, with French regulators already requiring test method disclosure for total organic fluorine screening.
Centralized procurement by pan-European foodservice distributors is consolidating barrier specification authority away from individual restaurant operators. Buyers at Sodexo, Compass, and transnational co-ops now mandate single-supplier paper programs with harmonized recyclability claims across 12+ country operations. German quick-service chains demonstrate the most advanced consolidation, with headquarters-level sustainability committees pre-approving coated paper vendors before regional kitchens place orders.
Europe Barrier Coated Paper Market Segmentation
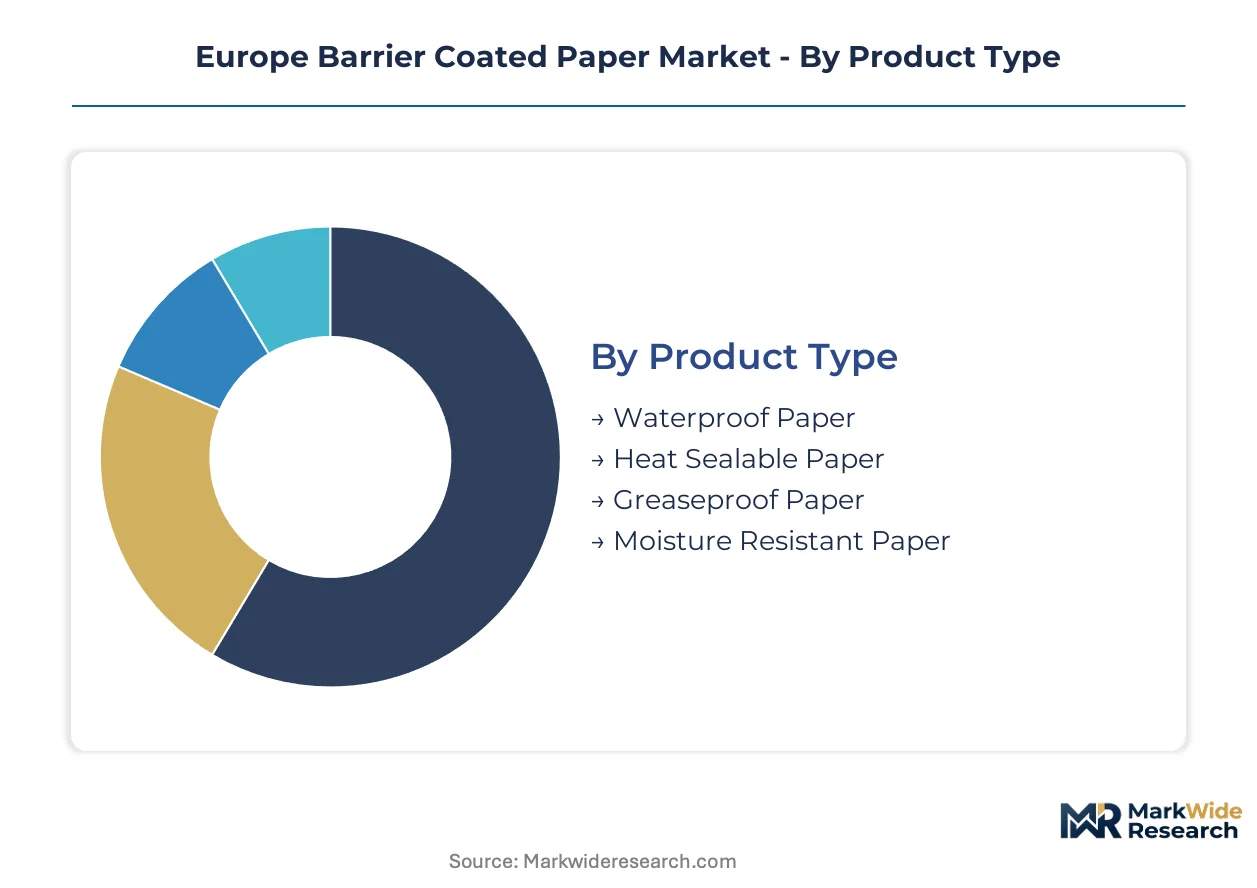
Segmentation in the Europe barrier coated paper market reveals how coating chemistry and distribution economics split margin capture across converter tiers. Technical specification depth varies sharply by end-use validation requirements, creating divergent service intensity needs.
Product Type:
After-sales service intensity escalates with coating complexity, as heat-sealable and multi-barrier grades require ongoing line calibration support that waterproof and greaseproof categories rarely demand.
- Waterproof Paper:Polyethylene or wax-laminated substrates achieve sub-10 g/m²/day water vapor transmission for frozen food outer wraps. German bakery chains specify this grade for refrigerated dough packaging where condensation resistance prevents soggy crusts. ECHA scrutiny of fluorocarbon additives is forcing reformulation toward bio-based waxes that demand closer technical service follow-up.
- Heat Sealable Paper:Coextruded polymer layers enable hermetic sealing on legacy form-fill-seal equipment modified for fiber substrates. French ready-meal producers in the Lyon corridor are standardizing this format for microwaveable pouch lines previously dedicated to multilayer plastics. Converter margins concentrate here due to sterilization validation protocols and heat-seal jaw retrofit consulting.
- Greaseproof Paper:Fluorochemical-free fluorine treatments or dense mechanical refining create oil resistance for fried food contact. Quick-service chains across Belgium and the Netherlands specify this for burger wraps and fry cartons.
- Moisture Resistant Paper:Medium-barrier polymer dispersions protect dry goods in humid supply chains. Italian pasta and confectionery exporters favor this grade for tropical destination shipments.
By volume, waterproof paper leads. By growth pace, heat sealable paper is gaining share fastest.
Application:
Application-level margin stratification follows validation burden, with medical and food-contact segments commanding premium positioning over industrial and graphic uses.
- Food Packaging:Direct-contact barriers for bakery, dairy, and ready-meal segments dominate tonnage. EFSA migration limits and EU Packaging and Packaging Waste Regulation recyclability mandates compress formulation windows for converters serving pan-European foodservice distributors.
- Medical Packaging:Gamma-stable, sterile barriers for device and pharmaceutical pouches carry the steepest qualification requirements. EMA sterilization validation protocols and biocompatibility testing extend sales cycles but lock in multi-year supply agreements at premium pricing.
- Industrial Applications:Rust-inhibiting VCI papers and moisture barriers for metal components serve automotive and machinery supply chains. Central European manufacturing clusters in Poland and Czech Republic drive regional demand concentration.
- Graphic Arts:Water-resistant poster and label stocks for outdoor advertising and durable goods labeling. Digital print compatibility requirements are fragmenting specifications across inkjet and toner platforms.
Food packaging captures the largest revenue pool. Medical packaging shows the steepest expansion trajectory.
End User:
End-user procurement centralization is reshaping how barrier specifications reach commercial scale, with sustainability committees at headquarters level preempting regional purchasing autonomy.
- Food & Beverage Industry:Quick-service chains and ready-meal manufacturers across France, Germany, and the UK are eliminating plastic-lined wraps through centralized mandates. Technical service teams must coordinate across 12+ country operations for pan-European distributors.
- Healthcare Sector:Hospital sterilization departments and pharmaceutical cold-chain operators demand gamma-stable, temperature-excursion-resistant barriers. EMA guidelines for biologics shipping are expanding insulated paper-based shipper specifications.
- Retail Vendors:Private-label food retailers in Scandinavia and the Benelux specify coated papers for bakery and deli counters. Shorter run lengths and seasonal variation require flexible coating line scheduling.
- Printing Companies:Commercial printers adding packaging capabilities need barrier grades compatible with existing sheet-fed and web press configurations. Ink adhesion and print registration tolerances vary by equipment vintage.
Food and beverage buyers generate the highest absolute volume. Healthcare procurement is climbing the fastest.
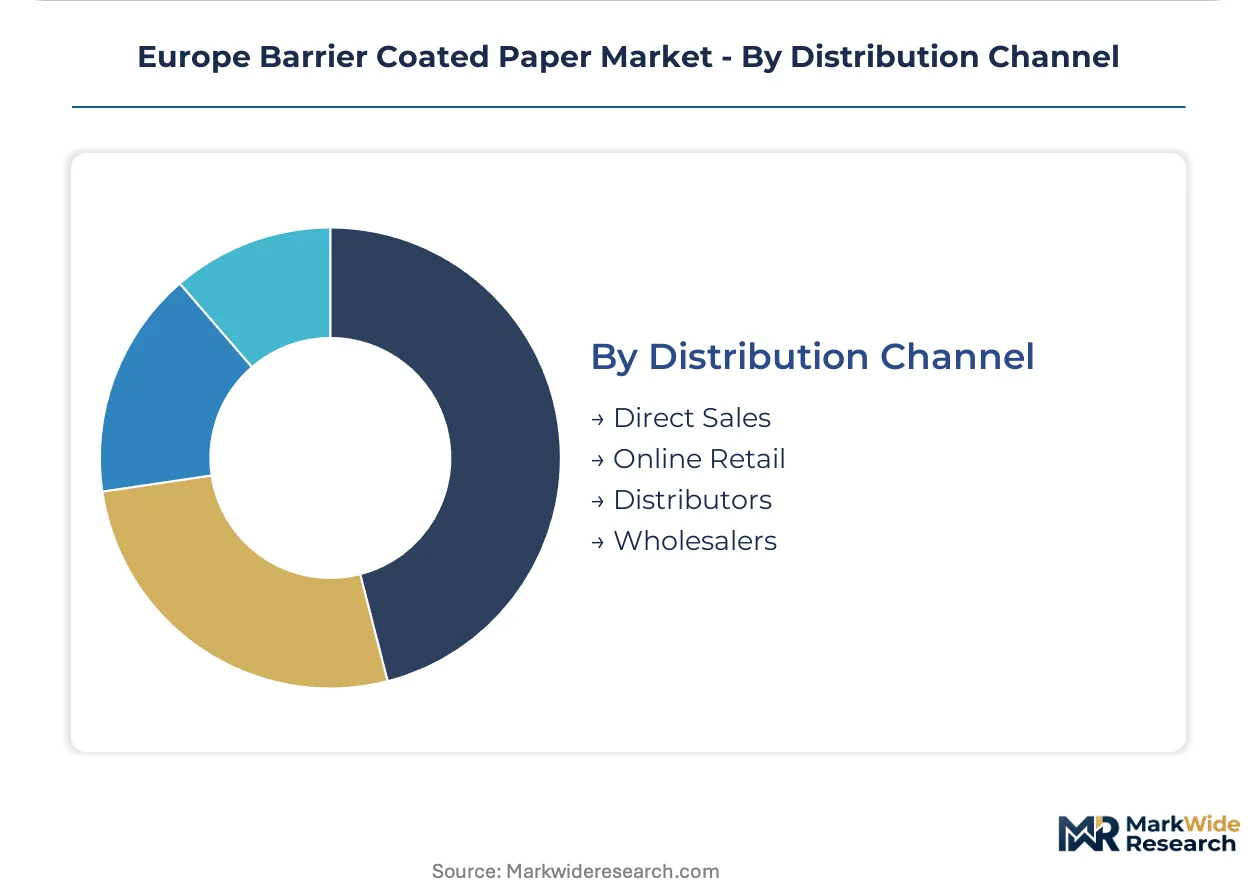
Distribution Channel:
Channel economics reflect order fragmentation patterns, with direct relationships consolidating at volume accounts while distributors capture mid-tier converters lacking technical specification expertise.
- Direct Sales:Integrated producers like UPM-Kymmene and Mondi Group deploy technical service engineers for high-volume food and medical accounts. Direct relationships enable collaborative formulation development and just-in-time delivery scheduling.
- Distributors:Regional paper merchants stock standard waterproof and greaseproof grades for smaller converters in Spain, Italy, and Eastern Europe. Inventory carrying costs and technical support limitations constrain barrier grade availability.
- Online Retail:E-procurement platforms serve job shops and prototype developers needing small-lot specialty grades. Sample validation and coating consistency verification remain friction points.
- Wholesalers:Bulk breakers supply commodity barrier papers to packaging converters without direct mill relationships. Price transparency pressures margin capture.
Direct sales dominate value capture. Online retail channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European barrier coated paper trade flows reflect a structural export surplus from Nordic pulp-integrated producers toward converting clusters in Germany, France, and Central Europe. Import dependency concentrates in specialty grades where regional coating capacity remains underdeveloped.
Germany
Quick-service restaurant chains headquartered in Munich and Cologne are mandating fiber-based packaging transitions across franchise networks. The national packaging ordinance implements EU Green Deal recyclability targets with stricter enforcement timelines than neighboring states. The Rhine-Main corridor hosts converting clusters serving pan-European foodservice distributors with heat-sealable paper specifications.
France
Ready-meal producers in the Lyon corridor are standardizing microwaveable pouch formats previously dedicated to multilayer plastics. ANSM pre-market consultation pathways for food-contact materials compress validation timelines for novel bio-based barriers. The Hauts-de-France region anchors bakery packaging demand from industrial bread and pastry manufacturers.
Sweden
Integrated pulp-to-paper producers leverage captive softwood supply to secure raw material cost positions for export markets. The Swedish Chemicals Agency (Kemi) enforces REACH compliance with accelerated PFAS screening protocols for food-contact coatings. The Värmland and Norrland regions concentrate bleached kraft pulp capacity serving specialty paper grades.
Poland
Underpenetrated barrier coating capacity creates first-mover positioning for toll-coating hubs near Warsaw serving Central European converters. The national waste management plan aligns with EU Packaging and Packaging Waste Regulation targets for 2030 recyclability thresholds. The Łódź industrial zone attracts packaging investment from food exporters targeting Eastern European markets.
Netherlands
Rotterdam port logistics enable import arbitrage for Nordic coated paper grades serving Benelux converting clusters. The National Institute for Public Health and the Environment (RIVM) coordinates ECHA implementation for food-contact substance evaluations. The Randstad region concentrates foodservice distribution headquarters with centralized procurement authority over barrier specifications.
Europe Barrier Coated Paper Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in coating chemistry and substrate formulation. The European barrier coated paper sector exhibits moderate consolidation, with Nordic pulp-integrated groups controlling substrate supply and mid-sized converters occupying differentiated coating niches. Three archetypes dominate: vertically integrated forest products groups with captive pulp supply, specialty converters with proprietary barrier formulations, and toll-coating operators serving regional packaging clusters. Capacity expansion and bio-based formulation partnerships constitute the dominant competitive vectors as PFAS phase-out deadlines approach.
Among Nordic-integrated producers, UPM-Kymmene and Stora Enso exemplify the substrate-control archetype, leveraging pulp cost positions across Finnish and Swedish operations. Mondi Group occupies a position spanning integrated production and proprietary extrusion coating capabilities. BillerudKorsnäs represents the specialty-grade vector with high-strength fiber formulations for demanding food-contact applications. These three anchors illustrate how geographic concentration of softwood pulp supply shapes competitive positioning in European barrier coated paper.
| Leading Market Players |
|---|
| DS Smith |
| UPM-Kymmene |
| Mondi Group |
| Sappi |
| Ahlstrom-Munksjö |
| Stora Enso |
| BillerudKorsnäs |
| Cascades |
| Smurfit Kappa |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors transmit Nordic pulp cost volatility directly into converter pricing power, with coating equipment scarcity in Germany and Italy amplifying margin stratification between integrated producers and toll-dependent mid-tiers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across medical-grade certification tiers, volume scale commitments, and heat-seal technical service bundling. Price differentiation separates gamma-validated medical barriers from commodity bakery wraps, with the former capturing premium positioning through EMA sterilization protocols. Cost compression in standard waterproof grades is intensifying because pulp drying energy expenses cannot pass through to price-sensitive frozen food segments. Quick-service restaurant chains exhibit lowest price sensitivity due to sustainability mandate urgency, while graphic arts converters face highest pressure from spot-market pulp fluctuations.
Supply Chain Analysis
Nordic softwood pulp supply from Sweden, Finland, and Norway feeds European barrier coated paper production, with polylactic acid and chitosan bio-polymer coatings increasingly sourced from specialty chemical producers in Germany and the Netherlands. Raw material dependencies center on bleached kraft pulp, extrusion-grade polyethylene, and emerging bio-based barrier formulations. Single-source vulnerability concentrates in German and Italian coating line machinery suppliers controlling high-speed extrusion equipment. Distribution runs through direct mill relationships for volume food and medical accounts, with regional paper merchants capturing fragmented smaller converters in Southern and Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around ECHA PFAS restrictions and EU Packaging and Packaging Waste Regulation recyclability mandates creates a defensive moat for converters with validated bio-based formulations and established EMA sterilization protocols.
For Market Incumbents: Build switching-cost moats through captive toll-coating networks in Poland and Czech Republic that lock in regional converters with heat-seal calibration support and just-in-time logistics. Deepen backward integration into bio-polymer formulation R&D to preempt ECHA substitution deadlines. Defend against emerging Asian coating technology entrants by accelerating EMA validation pipeline investments for gamma-stable medical grades. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical cold-chain pouches for biologics shipping, where EMA temperature excursion guidelines are expanding paper-based shipper specifications faster than incumbent capacity can respond. Target underpenetrated Central European converting clusters near Warsaw with toll-coating services that bypass German and Italian equipment bottlenecks. Lead with digital print compatibility layers that integrate barrier and inkjet receptive functions for short-run regional food brands. For Investors and Strategic Acquirers: Carve-out targets emerge from forest products groups spinning non-core specialty paper divisions ahead of consolidated pulp-to-packaging platform strategies. Long-term viability hinges on bio-based barrier patent estates and EMA sterilization validation track records rather than commodity substrate scale. Watch PFAS analytical detection certification delays as an inflection signal—converters lacking in-house mass spectrometry capability face forced reliance on third-party bottlenecks that compress margins and trigger distressed positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polymer Formulation | Captures REACH-compliant coating chemistry margins while eliminating fluorocarbon regulatory exposure. |
| Toll-Coating Hub Expansion | Central European capacity near Warsaw addresses underpenetrated Polish and Czech converter demand. |
| EMA Sterilization Validation Investment | Locks in multi-year medical packaging supply agreements at premium pricing tiers. |
| Digital Print Compatibility Layer Development | Enables short-run customization for regional food brands without separate lamination steps. |
| Heat-Seal Jaw Retrofit Consulting Services | Extends customer stickiness through legacy form-fill-seal line calibration support. |
Research Methodology
A spread of perspectives from coating line engineers at German and Italian machinery suppliers, procurement leads at pan-European foodservice distributors, technical R&D directors at Nordic pulp-integrated producers, and regulatory affairs specialists navigating ECHA restriction proposals converged on the working assumptions. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation timelines, EMA sterilization guidance documents, SEC filings of listed forest products groups, and Nordic pulp futures trade data. Bottom-up volume estimates from converter capacity utilization and top-down demand segmentation from end-use procurement patterns were triangulated to constrain forecast variance.
Demand-supply balance dynamics across the projection horizon were modeled through coating line capacity expansion schedules, pulp cost pass-through elasticity by buyer segment, and regulatory compliance deadline clustering. Segmentation dimensions included coating chemistry type, barrier performance tier, end-use validation burden, and regional converting cluster density. CAGRs were derived from segment-level volume trajectories weighted by pricing tier mix shifts. Industry-specific forecast inputs incorporated ECHA PFAS restriction phase-out timelines and centralized procurement mandate adoption curves at transnational foodservice distributors.
Macroeconomic conditions sit as an overlay; deviation in energy-intensive pulp drying costs, Baltic freight rates, or eurozone industrial production indices would shift the trajectory. Forecasts reflect assumptions about EMA validation pipeline throughput and bio-polymer coating scale-up yields that remain sensitive to technical execution risk. Cross-checking against Nordic pulp futures forward curves and European packaging machinery order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
Heat Transfer Films Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Global Adhesive Films Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Global Shrink Films Market