
 Europe Autonomous Navigation Market | 2026-2036
Europe Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Autonomous Navigation Market Analytics
Subscription-based fleet management software is restructuring how European logistics providers procure navigation capabilities. Thales leverages its sensor integration expertise to anchor defense and maritime contracts across France and the United Kingdom. Safran sustains R&D intensity in gyroscopic positioning systems for aerospace applications. ABB competes in industrial automation with localized manufacturing scale across Nordic markets.
Autonomous navigation encompasses self-directed positioning and path-planning systems that fuse Lidar point clouds, inertial measurement units, and real-time kinematic GPS corrections to achieve sub-decimeter accuracy in dynamic environments. Computer vision algorithms process optical feeds to classify obstacles and update trajectory models without human intervention. Sensor Fusion leads technology adoption because multi-modal redundancy satisfies maritime and automotive safety requirements. Self-Driving Cars capture the largest application value pool, while Mobile Robots in warehouse environments represent the fastest-expanding segment due to e-commerce fulfillment density.
The EU AI Act classifies autonomous navigation algorithms as high-risk systems, mandating conformity assessments before CE marking deployment. EASA coordinates with national maritime regulators to harmonize unmanned vessel certification standards across member states. REACH compliance restricts certain sensor coatings and battery chemistries, reshaping component sourcing decisions. Stakeholders must monitor how the CSRD disclosure regime will force navigation system vendors to document supply chain emissions and algorithmic audit trails.
Market Dynamics
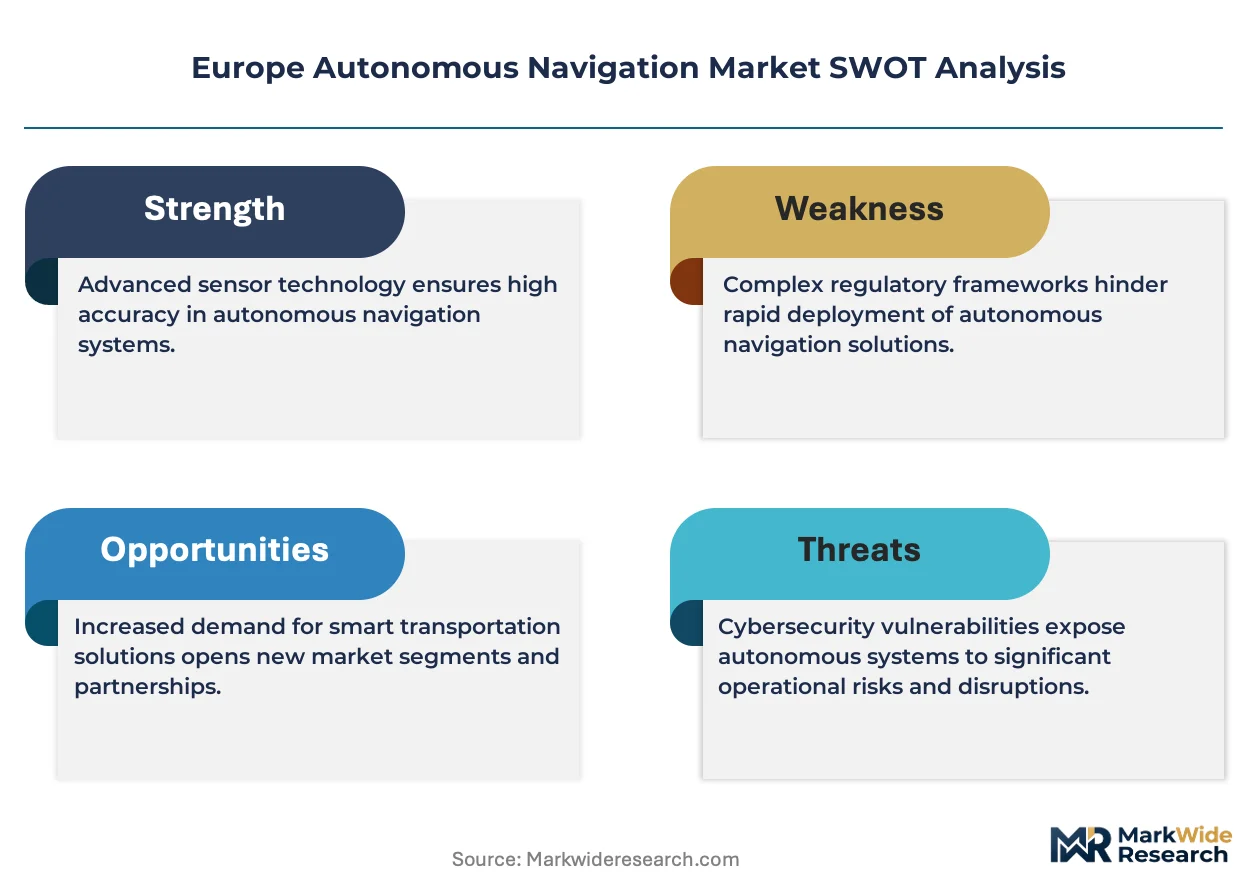
The EU AI Act's high-risk classification of navigation algorithms is compressing certification timelines while maritime freight operators accelerate unmanned vessel trials across North Sea corridors. This regulatory-pressure-plus-demand-pull combination is restructuring vendor priorities toward conformity assessment capabilities.
Growth Catalysts
- EU AI Act Conformity Mandates:The regulation's high-risk system designation forces navigation vendors to invest in documented algorithmic audit trails, creating captive demand for certified sensor fusion platforms.
- Harbor Automation Pilots:Hamburg and Bremen port authorities are deploying automated navigation systems for vessel maneuvering in constrained waterways, validating sub-decimeter accuracy requirements.
- Sensor Fusion Redundancy Standards:Maritime safety regulators now require multi-modal positioning systems that combine Lidar, inertial measurement units, and real-time kinematic GPS corrections.
Market Restraints
- REACH-Restricted Component Sourcing:Certain sensor coatings and battery chemistries face usage limitations, forcing redesigns of marine-grade Lidar housings and power systems.
- CE Marking Timeline Compression:Updated MDR frameworks extend certification cycles for safety-critical navigation hardware, delaying revenue recognition for new product introductions.
- Specialized Maritime Sensor Suppliers:Production of salt-spray-resistant optical components concentrates among Nordic component houses, creating single-source vulnerability for North Sea operators.
Strategic Opportunities
- Polish and Romanian Inland Waterways:Danube corridor freight operators lack autonomous navigation infrastructure, presenting first-mover positioning for retrofit vessel kits.
- CSRD Supply Chain Disclosure:The corporate sustainability reporting directive forces logistics providers to document navigation system emissions, favoring vendors with lifecycle transparency tools.
- Edge-AI and 5G Convergence:Real-time kinematic correction delivered via private cellular networks enables centimeter-accurate positioning without dedicated base station infrastructure.
Industry Challenges
- Functional Safety Engineer Scarcity:ISO 26262 and maritime equivalent certification expertise concentrates in Germany and France, constraining vendor expansion timelines.
- Legacy Vessel Integration Complexity:Retrofitting autonomous navigation onto existing commercial fleets requires mechanical adaptation of steering gear and propulsion interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Autonomous Navigation Market |
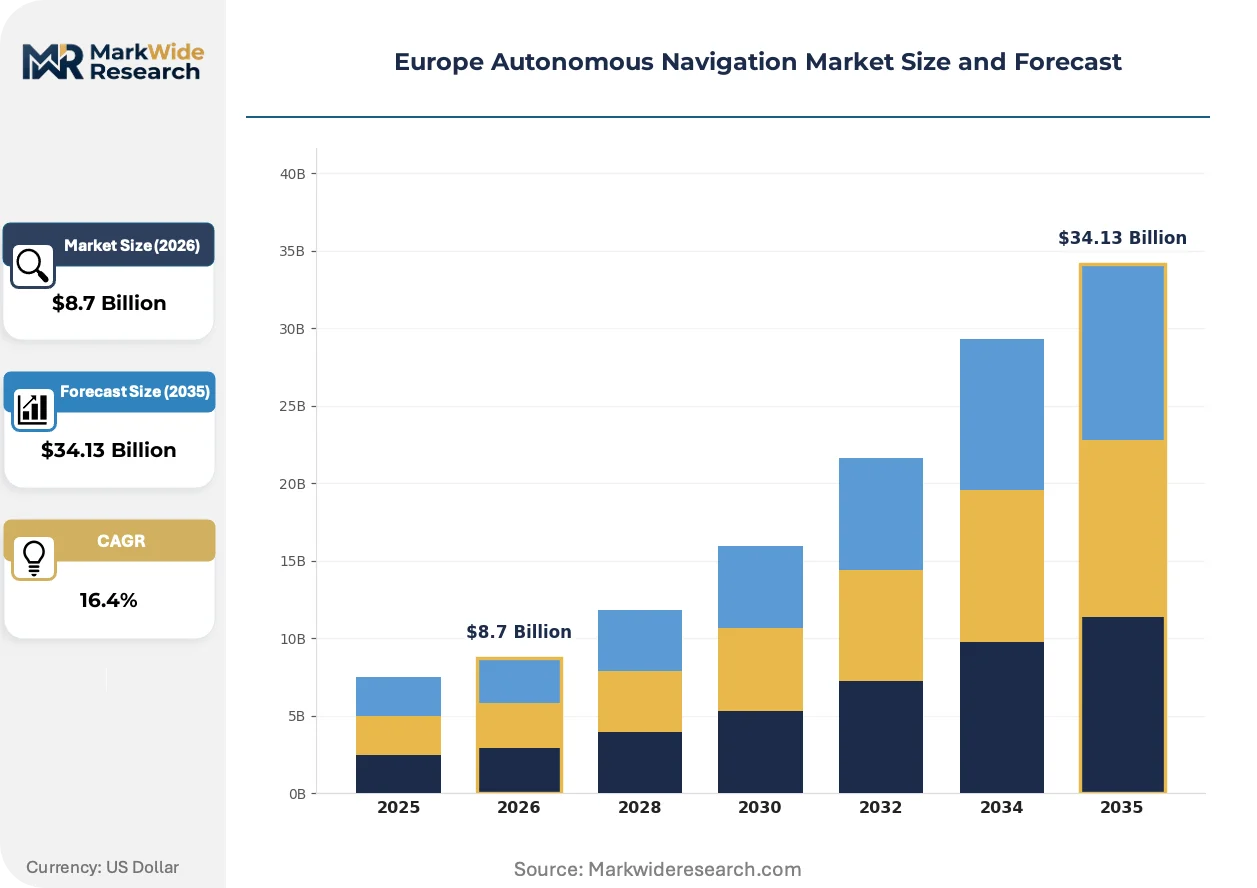
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Automotive OEMs, Logistics Providers, Public Transport Authorities, Drones Technology: Lidar, Computer Vision, GPS, Sensor Fusion Application: Self-Driving Cars, Maritime Navigation, Industrial Automation, Mobile Robots Installation: On-Vehicle Systems, Aftermarket Solutions, Integrated Platforms, Standalone Units |
| Companies Covered | Airbus, Thales, Safran, ABB, BAE Systems, Elbit Systems, L3Harris Technologies, Northrop Grumman, General Dynamics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Autonomous Navigation Market Evolving Landscape
Navigation technology is converging around unified perception stacks that serve multiple transport modes, while regulatory frameworks harden certification requirements and procurement patterns shift toward integrated service contracts.
Multi-modal sensor fusion is unifying previously separate positioning systems into single hardware-software stacks. Maritime operators in the North Sea corridor are adopting these platforms at pilot scale this year. This consolidation is unifying vendor competition around software-defined differentiation rather than discrete sensor hardware margins.
EASA coordination with national maritime regulators is harmonizing unmanned vessel certification standards across member states. The industrial consequence is a single conformity assessment pathway replacing fragmented national approvals. Mobile robot deployments in warehouse environments face the steepest compliance learning curves as vendors adapt aerospace-grade processes to ground-based logistics.
Subscription-based fleet management contracts are displacing perpetual license purchases among European logistics providers. Third-party navigation capability providers are capturing recurring revenue streams that hardware vendors previously monopolized. German port authorities and Scandinavian ferry operators exhibit the most advanced procurement model transitions.
Europe Autonomous Navigation Market Segmentation
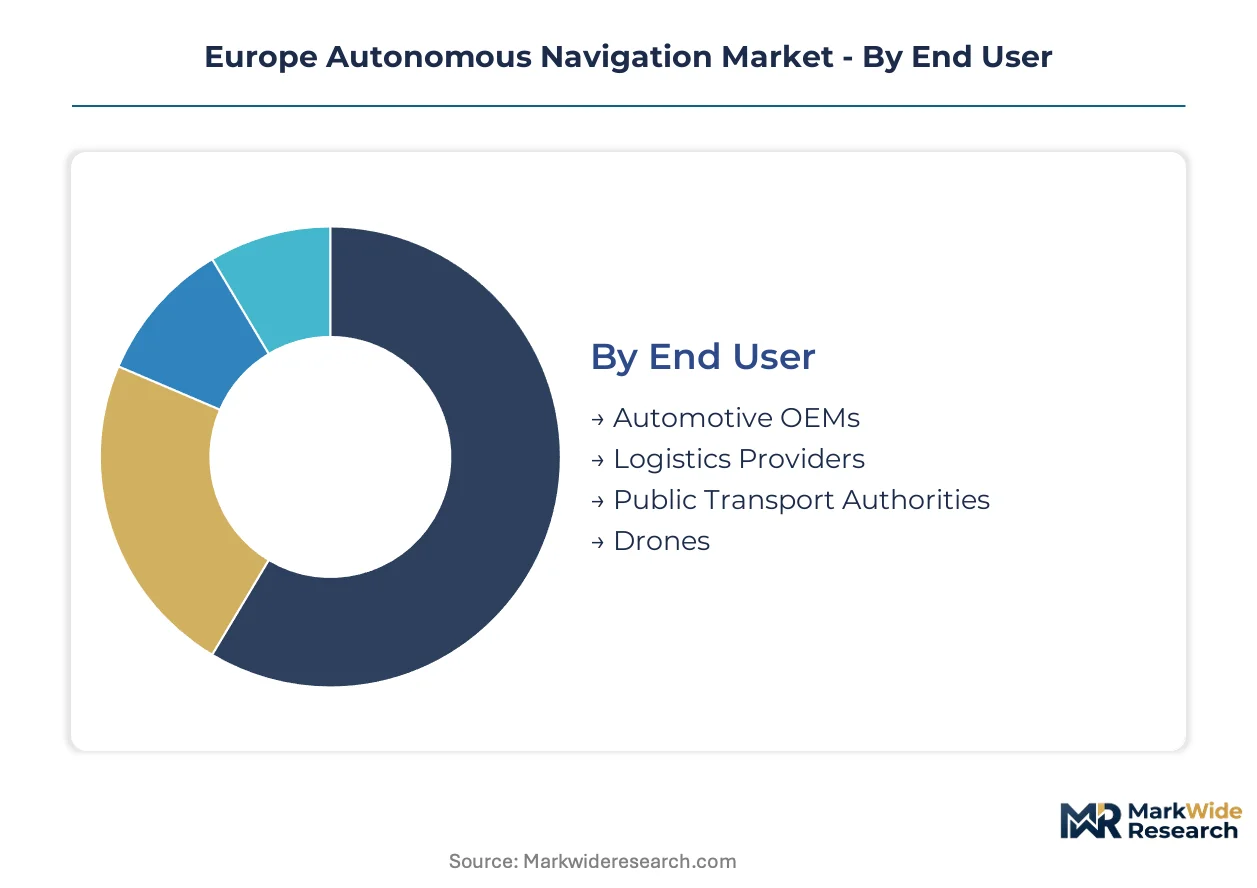
European autonomous navigation procurement patterns diverge sharply across end-user sophistication levels and installation complexity. Technology selection and application scope determine certification pathways under the EU AI Act, creating segment-specific compliance cost structures that reshape vendor targeting priorities.
End User:
Replacement cycles for navigation hardware compress as maritime and automotive operators pursue competitive positioning through sensor modernization programs.
- Automotive OEMs:Tier 1 suppliers integrate multi-modal perception stacks into vehicle platforms requiring ISO 26262 functional safety certification. German and French manufacturers anchor demand for Lidar-dominated sensor suites that satisfy EASA-EU AI Act harmonized standards.
- Logistics Providers:Fleet operators across Hamburg and Rotterdam corridors retrofit autonomous harbor maneuvering capabilities to reduce pilotage costs. Subscription procurement models dominate as third-party navigation service providers capture recurring revenue streams previously monopolized by hardware vendors.
- Public Transport Authorities:Municipal operators in Scandinavian cities pilot automated bus rapid transit corridors with centimeter-accurate positioning requirements.
- Drones:Commercial UAV operators in agriculture and infrastructure inspection face EASA remote identification mandates that reshape navigation payload specifications.
Volume placements concentrate in Automotive OEMs; the faster expansion belongs to Logistics Providers.
Technology:
Cost tiers separate premium multi-sensor fusion platforms from single-modality alternatives, with maritime safety regulations compressing the viable technology set toward redundancy-heavy configurations.
- Sensor Fusion:Unified perception stacks combine Lidar point clouds, inertial measurement units, and real-time kinematic GPS corrections into single hardware-software platforms. North Sea maritime operators adopt these systems at pilot scale to satisfy multi-modal redundancy requirements for unmanned vessel certification.
- Lidar:Salt-spray-resistant optical components for marine environments concentrate among Nordic suppliers, creating single-source vulnerability that elevates procurement risk for Baltic and North Sea operators.
- Computer Vision:Optical feed processing algorithms classify obstacles and update trajectory models without human intervention, with warehouse mobile robot deployments facing steepest compliance learning curves.
- GPS:Real-time kinematic correction services delivered via private 5G networks enable centimeter-accurate positioning without dedicated base station infrastructure.
Revenue concentration sits with Sensor Fusion; Computer Vision is climbing the fastest as warehouse automation accelerates.
Application:
Customer type stratification separates safety-critical maritime installations from productivity-focused industrial deployments, with certification intensity determining vendor margin structures.
- Self-Driving Cars:Passenger vehicle automation captures the largest value pool as German OEMs pursue SAE Level 3+ highway capabilities. EASA coordination with KBA and other national regulators harmonizes algorithmic audit trail requirements across member states.
- Maritime Navigation:Hamburg and Bremen port authorities deploy automated vessel maneuvering in constrained waterways, validating sub-decimeter accuracy requirements for harbor automation pilots.
- Mobile Robots:E-commerce fulfillment density drives warehouse navigation demand, with vendors adapting aerospace-grade certification processes to ground-based logistics applications.
- Industrial Automation:ABB and Nordic competitors supply localized manufacturing-scale platforms for manufacturing floor autonomous guided vehicles.
Commercial significance clusters in Self-Driving Cars; Mobile Robots gain share fastest on e-commerce fulfillment expansion.
Installation:
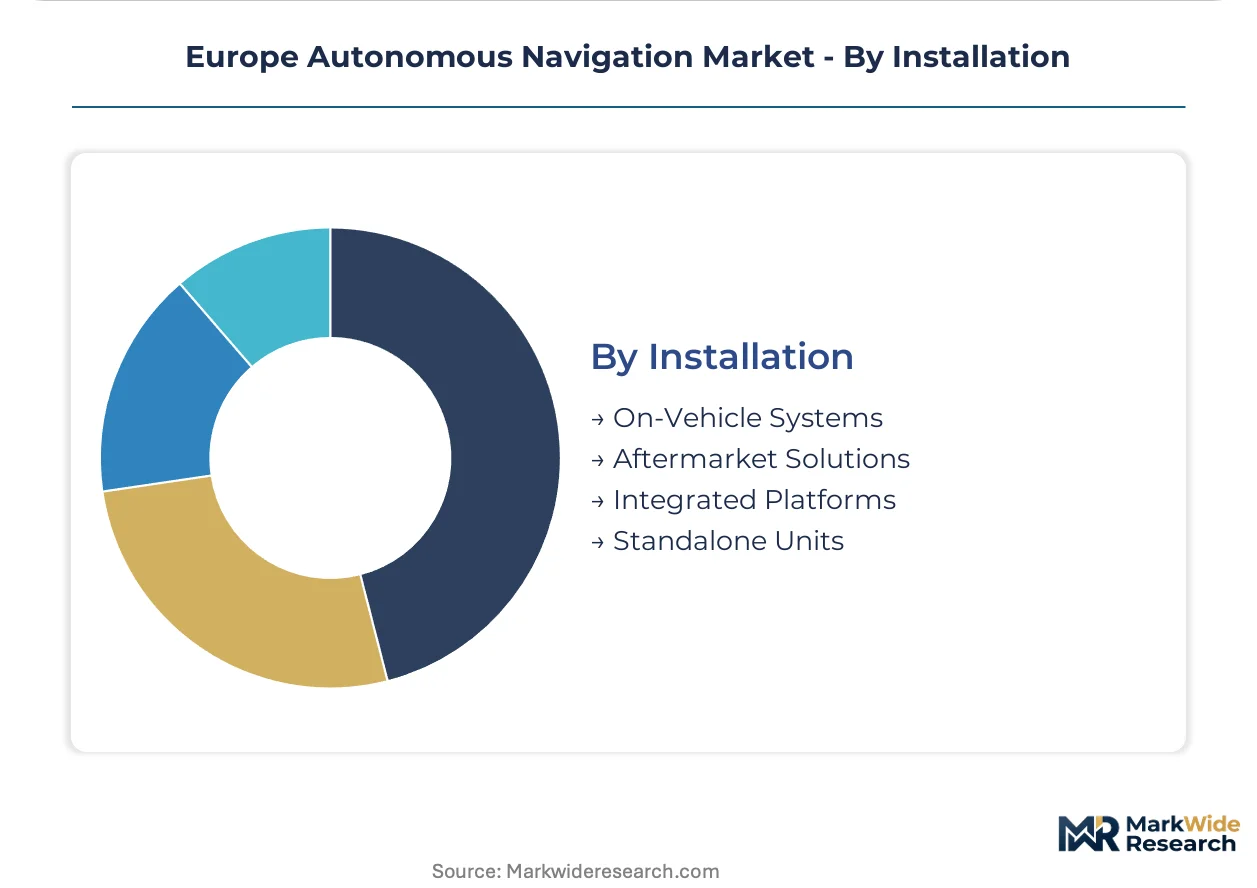
Supply concentration in integrated platform vendors shapes procurement options, with aftermarket solutions facing REACH-restricted component sourcing constraints that limit viable supplier pools.
- Integrated Platforms:Unified hardware-software stacks bundle perception, planning, and control functions into single vendor relationships. Thales anchors defense and maritime contracts across France and the United Kingdom through sensor integration expertise.
- On-Vehicle Systems:Factory-installed navigation capabilities dominate automotive OEM procurement, with CE marking timelines compressing under updated MDR frameworks for safety-critical hardware.
- Aftermarket Solutions:Retrofit vessel kits for Danube corridor freight operators present first-mover positioning in Polish and Romanian inland waterways lacking autonomous navigation infrastructure.
- Standalone Units:Modular positioning systems serve specialized industrial applications with discrete upgrade paths independent of platform vendor roadmaps.
Procurement gravity centers on Integrated Platforms; Aftermarket Solutions show the steepest expansion trajectory on legacy fleet retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates autonomous navigation production through Tier 1 automotive suppliers and maritime sensor houses, while demand distributes across North Sea port authorities and Scandinavian logistics operators seeking harbor automation capabilities.
Germany
Hamburg and Bremen port authorities deploy automated vessel maneuvering systems in constrained waterways, validating sub-decimeter accuracy requirements for harbor pilots. KBA coordinates with EASA on harmonized algorithmic audit trail standards for high-risk navigation systems under the EU AI Act. Bavaria-based automotive OEMs integrate multi-modal perception stacks requiring ISO 26262 functional safety certification.
United Kingdom
Maritime freight operators across the North Sea corridor expand autonomous vessel trials to reduce pilotage dependency and operational costs. BAE Systems anchors defense and maritime sensor integration contracts through established procurement relationships with national security agencies. London and Southeast England concentrate venture funding for warehouse mobile robot navigation startups serving e-commerce fulfillment density.
France
Thales leverages sensor integration expertise to secure defense and maritime navigation contracts across domestic and export markets. ANSM coordinates algorithmic conformity assessments for high-risk autonomous systems under EU AI Act implementation timelines. Paris and the Île-de-France region host aerospace-grade gyroscopic positioning R&D programs for next-generation navigation platforms.
Netherlands
Rotterdam port authorities retrofit autonomous harbor maneuvering capabilities to maintain competitive positioning against Hamburg and Antwerp corridor rivals. REACH compliance requirements reshape sensor coating and battery chemistry sourcing decisions for marine-grade Lidar housings. Randstad logistics providers pioneer subscription-based fleet management procurement models for third-party navigation services.
Sweden
Nordic component houses concentrate production of salt-spray-resistant optical components for North Sea maritime operators, creating single-source supply vulnerability. ABB competes in industrial automation with localized manufacturing scale for autonomous guided vehicle platforms serving manufacturing floors. Stockholm and Gothenburg anchor maritime sensor R&D clusters adapting aerospace certification processes to unmanned vessel applications.
Europe Autonomous Navigation Market Competitive Landscape
Top-tier vendors anchor integrated platform supply, while specialized component houses and regional system integrators populate lower tiers. The vendor base stratifies across defense-prime sensor integrators, industrial automation conglomerates, and aerospace-grade positioning specialists. Three archetypes dominate: platform bundlers unifying perception-planning-control stacks, component purists supplying salt-spray-resistant optical modules, and service-layer operators capturing recurring fleet management revenue. Competitive moves concentrate on conformity assessment capability acquisition and private 5G network partnerships for real-time kinematic correction services.
Within the defense-prime tier, Thales and BAE Systems exemplify sensor integration anchoring across maritime and aerospace applications. Safran occupies a position representing aerospace-grade gyroscopic positioning specialization. ABB sits within the industrial automation archetype competing on localized manufacturing scale across Nordic markets. These three named entities represent distinct competitive vectors without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Airbus |
| Thales |
| Safran |
| ABB |
| BAE Systems |
| Elbit Systems |
| L3Harris Technologies |
| Northrop Grumman |
| General Dynamics |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up maritime sensor specialists concentrate ownership of salt-spray-resistant optical component production across Nordic markets, anchoring both supply discipline and premium pricing power for marine-grade Lidar systems. This ownership pattern reinforces pricing rigidity as REACH compliance costs and EU AI Act certification investments compound margin protection strategies among consolidated component houses.
Pricing Analysis
Margin tightening in integrated sensor fusion platforms reflects REACH-restricted coating substitutions and extended CE marking timelines under updated MDR frameworks. Three-tier pricing structure across aerospace-certified, marine-grade, and industrial-standard levels separates procurement pools, with certification grade and volume scale as primary differentiation drivers. Cost compression accelerates in aftermarket retrofit segments as Danube corridor operators demand price-accessible vessel kits. Logistics providers exhibit highest price sensitivity due to subscription-model procurement, while defense primes demonstrate lowest sensitivity given mission-critical specifications.
Supply Chain Analysis
Refurbishment flows for inertial measurement units and Lidar modules create secondary supply channels that partially offset Nordic component house concentration. Geographic supply centers on Germany for Tier 1 automotive integration, Sweden for salt-spray-resistant optics, and France for aerospace-grade gyroscopic positioning. Raw material dependencies span rare-earth elements for gyroscopic sensors, specialized optical glass for marine Lidar, and REACH-compliant battery chemistries for power systems. Single-source vulnerability in Nordic optical component production elevates supply risk for North Sea maritime operators. Distribution runs through integrated platform vendors and third-party navigation service providers with recurring fleet management contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Autonomous Navigation Market functions as a cost-of-compliance story where EU AI Act high-risk system classification erects substantial barrier-to-entry moats favoring incumbent vendors with established conformity assessment capabilities and documented algorithmic audit trails.
For Market Incumbents: Extend certification infrastructure investments to capture CE marking timeline compression advantages as updated MDR frameworks delay competitor product introductions. Acquire specialized maritime sensor suppliers in Nordic markets to neutralize single-source vulnerability threats while deepening backward integration into salt-spray-resistant optical component production. Prioritize EASA coordination relationships to influence harmonized unmanned vessel standards before national regulators fragment compliance pathways. For New Entrants and Emerging Players: Begin with Polish and Romanian inland waterway retrofit opportunities where Danube corridor freight operators lack autonomous navigation infrastructure and incumbent presence remains minimal. Target aftermarket vessel kit segments with REACH-compliant component sourcing partnerships that circumvent integrated platform vendor lock-in. Pursue go-to-market angles through private 5G network partnerships offering real-time kinematic correction services without dedicated base station infrastructure investments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap sensor fusion specialists in Germany and France facing working capital constraints from extended CE marking timelines. Long-term viability concentrates in vendors with dual-use aerospace-maritime certification capabilities and recurring revenue exposure through subscription fleet management contracts. Monitor EASA-EU AI Act harmonization progress as inflection indicator for regulatory clarity enabling valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment Investment | CE marking acceleration captures revenue recognition timing advantages against certification-lagged competitors. |
| Private 5G Network Partnership | Real-time kinematic correction services via cellular infrastructure reduce base station capital requirements for harbor operators. |
| Backward Integration into Optical Components | In-house production of salt-spray-resistant modules neutralizes Nordic supplier concentration risk for maritime contracts. |
| Subscription Fleet Management Launch | Recurring revenue capture displaces perpetual license procurement patterns among Hamburg-Rotterdam logistics providers. |
| Danube Corridor Geographic Expansion | First-mover positioning in Polish and Romanian inland waterways lacking autonomous navigation infrastructure. |
Research Methodology
Independent corroboration across EASA regulatory filings, EU AI Act implementation guidance, and REACH compliance databases underwrites the qualitative findings on certification pathway evolution. Primary interviews with maritime sensor procurement officers, autonomous vessel program directors, port authority technology leads, and functional safety engineering consultants combined with secondary validation from customs trade records, SEC filings of listed navigation vendors, and EEA emissions disclosure repositories. Bottom-up vessel deployment counts and top-down logistics provider IT spending estimates were triangulated to anchor market sizing.
Rate-of-change decomposition across technology adoption curves, regulatory implementation timelines, and fleet replacement cycles structured the analytical framework. Segmentation dimensions modeled span end-user sophistication, technology redundancy configuration, application safety-criticality, and installation complexity. CAGRs were derived from installed base projections and average system value evolution. Industry-specific forecast inputs incorporated EU AI Act enforcement intensity assumptions and EASA-maritime regulator coordination progress indicators.
Underlying measurement precision varies by segment; integrated platform vendor revenue reporting carries tighter precision than fragmented aftermarket retrofit estimates. Forecasts reflect documented assumptions on regulatory timeline adherence and technology cost-down trajectories. Practitioners should monitor EASA-EU AI Act harmonization announcements, REACH restricted substance list updates, and Nordic component house M&A activity for early signals requiring forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Global Driverless Car Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Vehicle Intelligence System Market
Autonomous Vehicles
Italy Autonomous Navigation Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Robotaxi Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
Autonomous Navigation Sensing System Market