
 Commercial Telematics Market | 2026-2036
Commercial Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Telematics Market Analysis
Fleet software distribution is rewriting how telematics providers reach commercial vehicle operators. Verizon Connect leverages direct fleet relationships to sustain recurring revenue across North American logistics corridors. Samsara Inc. anchors its position through cloud-native architecture that dominates mid-market fleet deployments. Trimble Inc. specializes in construction and agriculture verticals where ruggedized hardware requirements create defensible margin pools.
Commercial telematics encompasses GPS-enabled hardware and software systems that capture vehicle location, engine diagnostics, driver behavior metrics, and asset status through cellular or satellite connectivity for fleet optimization and regulatory compliance. The technology layer shows GPS and cellular combinations leading installations while satellite backup gains traction in remote freight corridors where coverage gaps persist. Fleet management applications command the largest revenue share among product types, though compliance monitoring functions are expanding fastest as ELD and hours-of-service rules tighten across jurisdictions. Cloud services deployment now outpaces onboard-only configurations as fleet operators prioritize real-time analytics accessibility.
FCC equipment authorization requirements shape hardware certification timelines for US market entry, while EU REACH and CE marking directives govern embedded electronics sold across European member states. The EPA's SmartWay program and NHTSA safety standards further influence feature prioritization for domestic fleet procurement. Stakeholders must monitor how emerging AI Act transparency obligations in Europe and evolving state-level privacy statutes in the US reshape data governance architectures before committing to platform infrastructure investments.
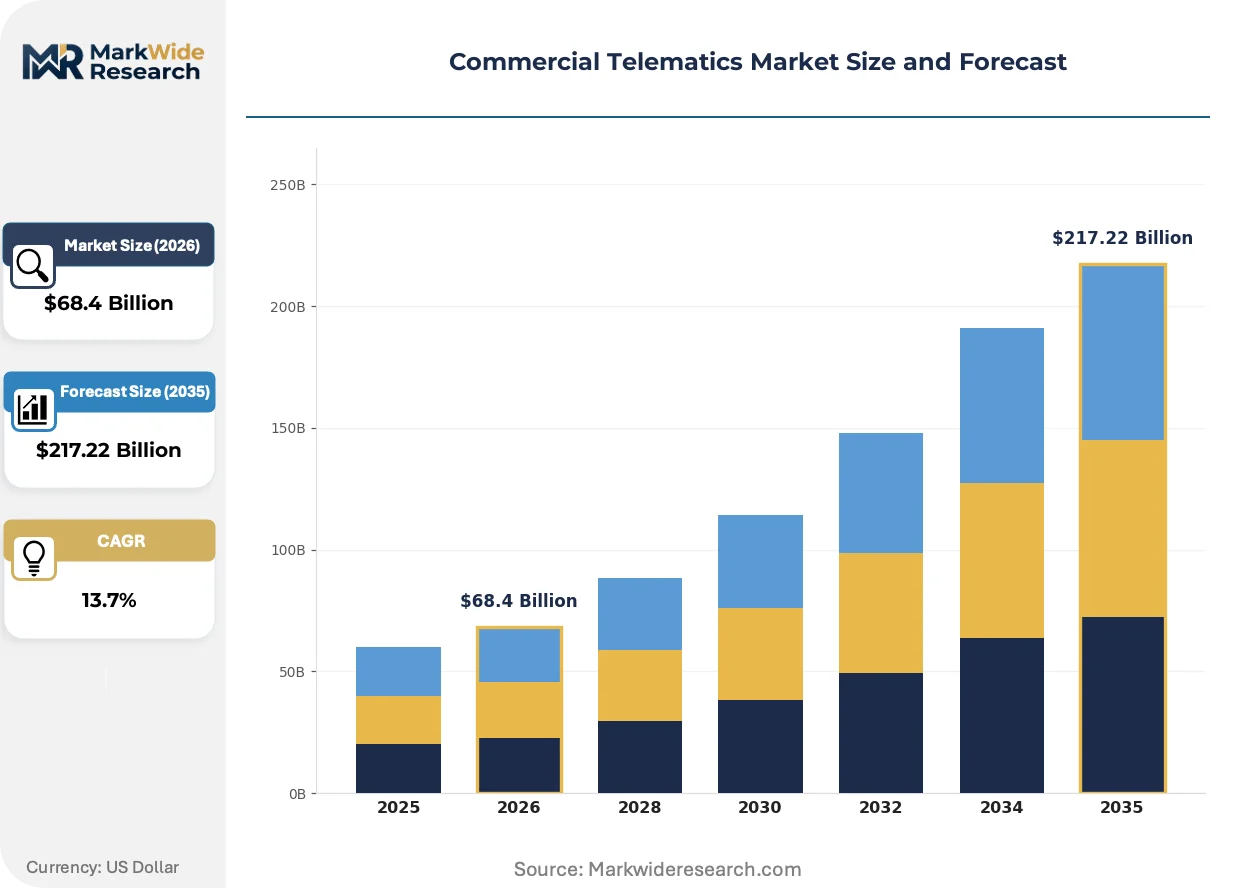
Market Dynamics
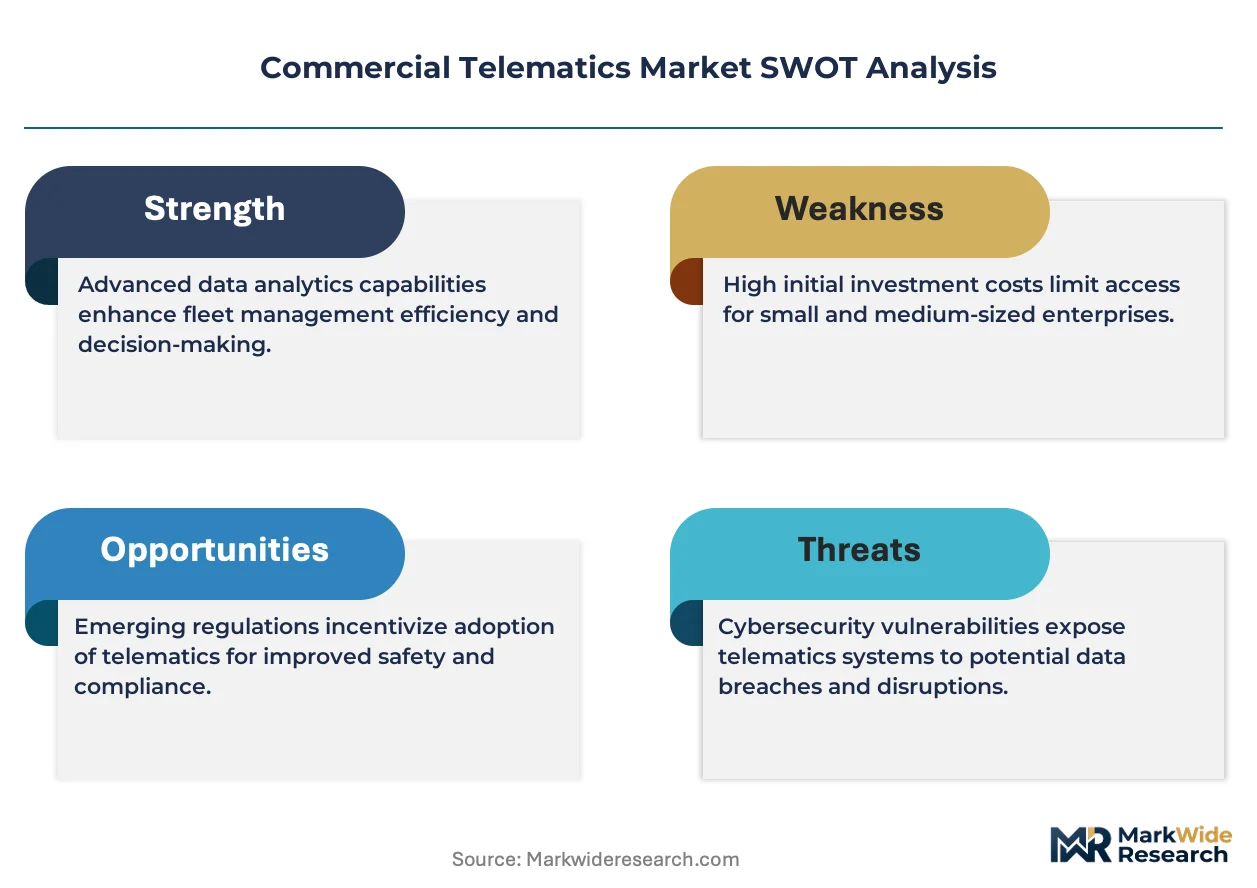
ELD mandates and AI transparency obligations are compressing deployment timelines across commercial fleet operations. The regulatory stack now dictates platform architecture decisions before procurement cycles begin.
Growth Catalysts
- Fleet electrification mandates:California's Advanced Clean Trucks regulation and EU CO2 standards for heavy-duty vehicles are forcing logistics operators to retrofit telematics for battery state-of-health monitoring and charging optimization.
- EU AI Act transparency requirements:Automated driver scoring algorithms now require explainability documentation, creating demand for telematics platforms with built-in audit trails and decision-logging capabilities.
- Insurance telematics integration:Commercial auto underwriters in Germany and the United Kingdom are embedding usage-based pricing models that require granular vehicle telemetry data streams.
Market Restraints
- Semiconductor supply concentration:GPS module and cellular modem fabrication concentrates in Taiwan and South Korea, exposing hardware vendors to single-source vulnerability during geopolitical disruptions.
- Cellular network fragmentation:2G/3G sunsetting schedules vary by carrier and country, stranding legacy hardware and forcing premature replacement cycles for fleet operators with mixed-age assets.
- Data sovereignty compliance costs:GDPR and emerging state-level privacy statutes in the US require region-specific data residency architectures that multiply infrastructure expenditure for platform providers.
Strategic Opportunities
- Construction equipment telematics:Earthmoving and crane fleets remain underpenetrated relative to over-the-road trucking, with ruggedized hardware requirements creating margin pools for specialized vendors.
- Refrigerated transport compliance:EU Good Distribution Practice for pharmaceuticals and FDA Food Safety Modernization Act cold chain rules are mandating continuous temperature logging that extends beyond basic GPS tracking.
- Video telematics convergence:Integration of dashcam footage with engine diagnostics and driver behavior scoring is opening new insurance partnership channels and claims dispute resolution revenue streams.
Industry Challenges
- Embedded software talent scarcity:Firmware engineering for automotive-grade hardware requires specialized safety-critical development practices that compete for talent with autonomous vehicle programs.
- FCC equipment authorization timelines:Hardware certification for new cellular bands or satellite backup modules faces 6-12 month review queues that delay product launches and compress revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Telematics Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $217.22 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fleet Management, Driver Behavior, Asset Tracking, Compliance Monitoring Technology: GPS, Cellular, Satellite, RFID End User: Logistics, Transportation, Construction, Retail Installation: Onboard Devices, Mobile Applications, Cloud Services, Embedded Systems |
| Companies Covered | Geotab Inc., Verizon Connect, Samsara Inc., Trimble Inc., Omnitracs LLC, PTC Inc., TomTom Telematics, Mix Telematics International, Solera Holdings LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Telematics Market Emerging Trajectories
Edge computing architectures are migrating analytics from cloud data centers to vehicle-mounted hardware. This shift reduces latency for safety-critical alerts while creating new firmware complexity for platform vendors.
AI-powered video analytics is rendering obsolete manual incident review processes for fleet safety departments. Machine vision algorithms now flag distracted driving, rolling stops, and following-distance violations in real time. Large trucking fleets and last-mile delivery operators are deploying these systems across entire vehicle populations within 18-month rollout cycles. The technology is compressing insurance claims resolution timelines from weeks to hours.
EU AI Act risk classification rules are reclassifying driver behavior scoring systems as high-risk AI applications. Telematics vendors must now maintain technical documentation, human oversight protocols, and accuracy testing records for algorithmic decision systems. German fleet operators and French logistics cooperatives are demanding platform vendors pre-certify compliance before contract signature. The regulatory burden favors established providers with dedicated compliance engineering teams.
Subscription-based hardware provisioning is replacing upfront capital expenditure models for mid-market fleet operators. Leasing arrangements bundle device installation, cellular connectivity, and software licenses into per-vehicle monthly fees. Equipment finance specialists and telematics vendors are building captive financing arms to capture this recurring revenue stream. The shift is most visible among 50-500 vehicle fleets in the United Kingdom and Netherlands where working capital constraints limit large hardware purchases.
Commercial Telematics Market Segmentation
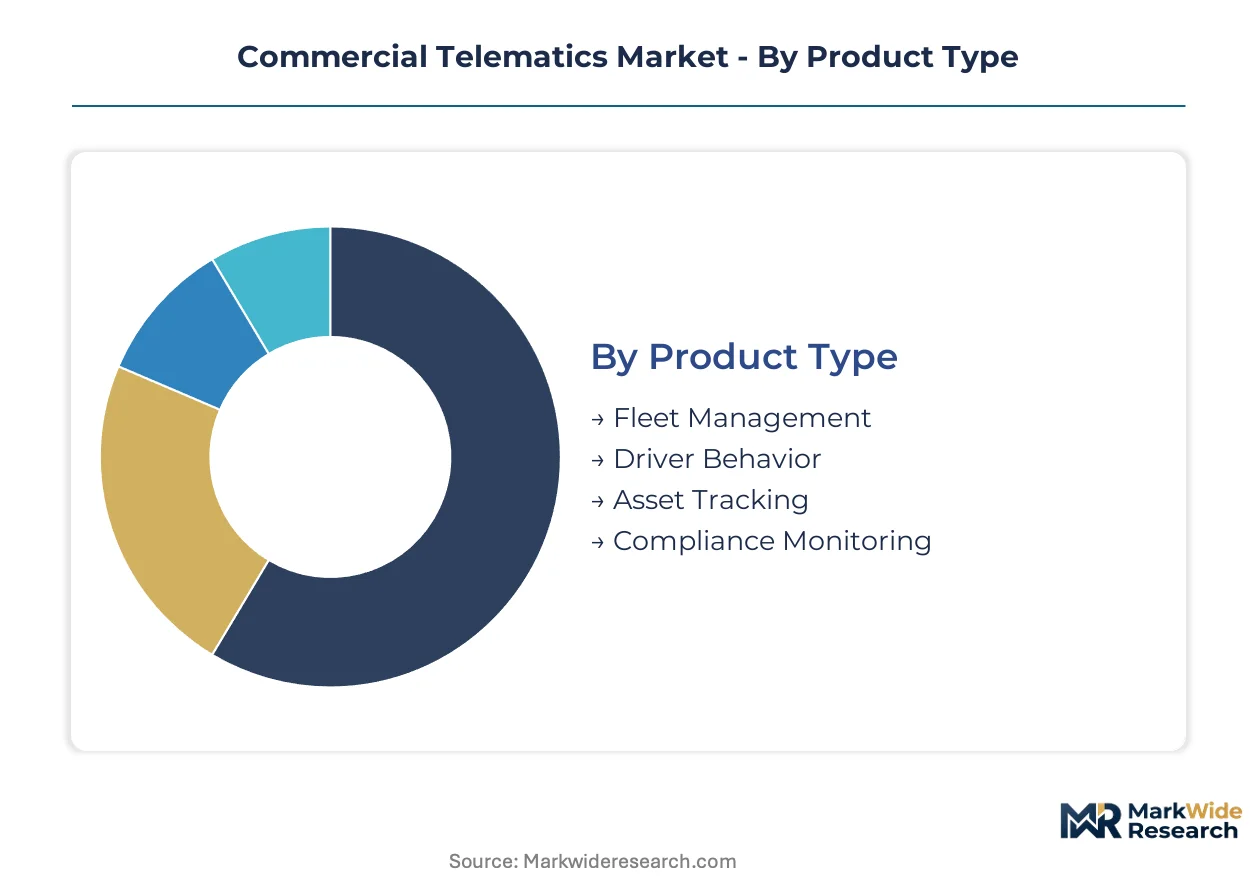
Commercial telematics segmentation reveals how fleet operators prioritize capabilities against compliance mandates and operational complexity. Product architecture choices cascade through installation decisions, technology stack, and end-use specialization.
Product Type:
Application focus determines how vendors bundle hardware, software, and data services into revenue-generating packages.
- Fleet Management:Integrated platforms combine GPS tracking, route optimization, fuel consumption analytics, and maintenance scheduling into unified dashboards. Demand concentrates among third-party logistics providers operating across German freight corridors and Dutch distribution hubs, where fuel efficiency regulations from the EU Green Deal tighten operating margins.
- Driver Behavior:Systems capture harsh braking, acceleration patterns, and idling duration to score operator performance. German commercial auto underwriters and UK fleet insurers are mandating these deployments for usage-based premium calculations, accelerating adoption among mid-size haulage operators.
- Asset Tracking:Non-powered equipment monitoring using battery-efficient beacons for trailers, containers, and construction machinery.
- Compliance Monitoring:ELD synchronization and hours-of-service logging for FMCSA and EU mobility package adherence.
Fleet Management holds installed capacity. Compliance Monitoring is rotating up the share rankings.
Technology:
Connectivity modality trade-offs shape hardware BOM costs and service reliability profiles for fleet operators.
- GPS:Satellite positioning provides foundational location data with 3-5 meter accuracy under open sky. Deployment concentrates in urban last-mile delivery fleets across the United Kingdom and France, where dense cellular coverage reduces need for backup connectivity and keeps hardware costs minimal.
- Cellular:LTE-M and NB-IoT modules enable real-time data transmission with lower power draw than legacy 4G. Scandinavian forestry operators and Australian mining haulers are adopting dual-mode GPS-cellular units as 2G/3G sunsets force hardware refresh cycles.
- Satellite:Iridium and Orbcomm backup for remote corridor coverage where terrestrial networks fail.
- RFID:Short-range identification for yard management and automated gate access control.
Cellular dominates active subscriptions. Satellite is climbing the fastest as remote freight corridors expand.
End User:
Customer type segmentation exposes how vertical specialization drives feature prioritization and sales channel selection.
- Logistics:Full-truckload and less-than-truckload operators demand route optimization, dwell time analytics, and cross-border compliance documentation. German freight forwarders and Dutch cold chain specialists are consolidating vendor relationships around platforms that pre-certify EU AI Act algorithmic transparency.
- Transportation:Passenger transit and school bus fleets prioritize student safety alerts, ADA compliance logging, and real-time arrival predictions. Municipal procurement in France and regional transit authorities in Spain are specifying these capabilities in tender documents.
- Construction:Earthmoving equipment and crane fleets require ruggedized hardware with IP67 ratings and extended temperature tolerance.
- Retail:Grocery and parcel delivery networks optimize last-mile sequencing and customer notification timing.
Logistics commands the largest deployment base. Construction is expanding most quickly as equipment OEMs embed telematics at factory.
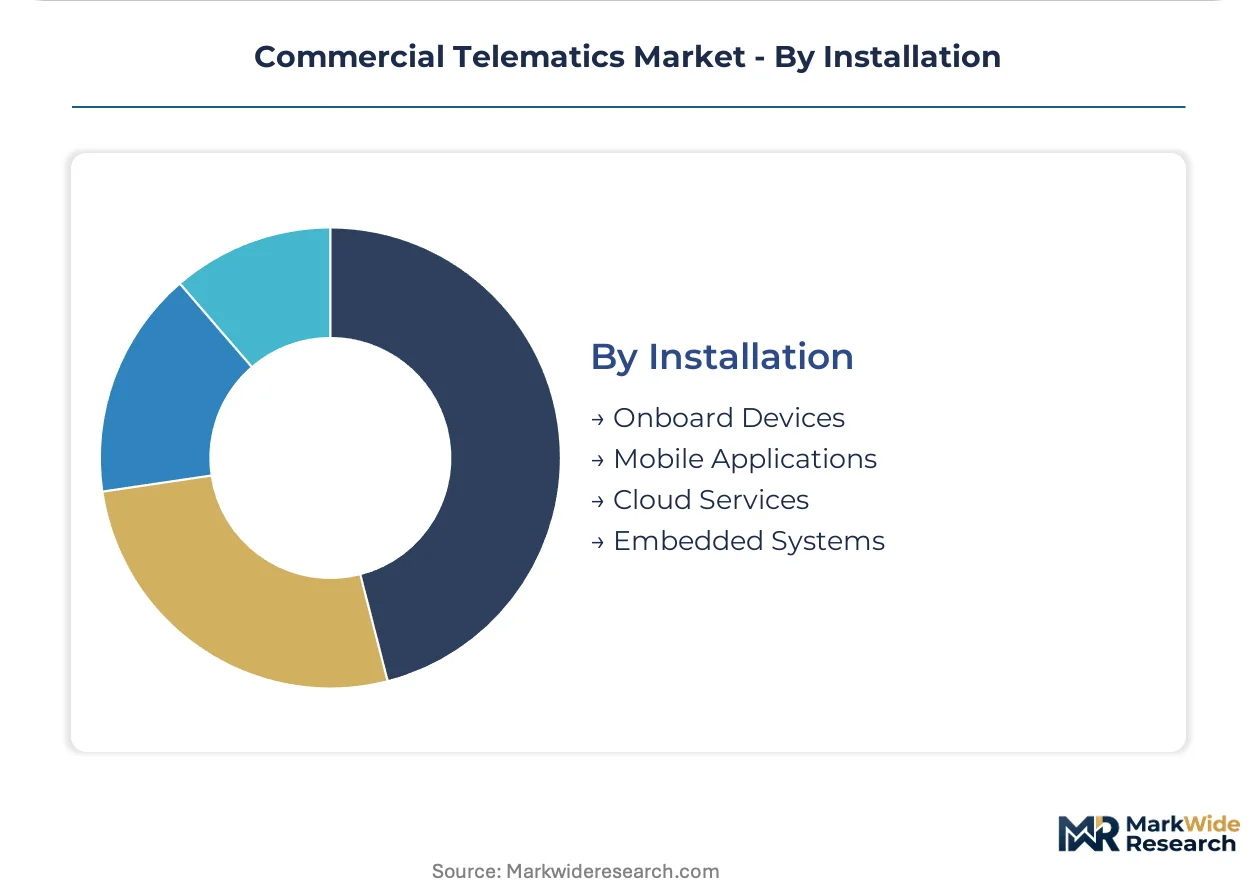
Installation:
Deployment architecture choices reflect fleet IT maturity, data sovereignty requirements, and real-time latency tolerances.
- Onboard Devices:Hardwired OBD-II or J1939-connected hardware captures engine diagnostics and vehicle bus data. Long-haul trucking fleets across Poland and Czech Republic corridors favor these installations for tamper resistance and continuous power supply during multi-day routes.
- Mobile Applications:Smartphone-based Bring Your Own Device solutions reduce hardware capital outlay. Small UK courier fleets and gig-economy delivery platforms in Spain are adopting these for rapid driver onboarding without installation logistics.
- Cloud Services:SaaS delivery models with browser-based analytics access and API integrations.
- Embedded Systems:Factory-integrated telematics from Volvo, Daimler, and Scania with proprietary data protocols.
Onboard Devices retain the largest installed base. Cloud Services are gaining share fastest as mid-market fleets prioritize OPEX flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European logistics density, underwriting the Netherlands' concentration of fleet management platforms serving cross-border freight corridors. This maritime infrastructure drives telematics deployment patterns across the continent.
Germany
Automotive OEM clusters in Stuttgart and Munich demand factory-embedded telematics with EU AI Act pre-certification. The KBA enforces type-approval standards for connected vehicle systems. Fleet integrators in Baden-Württemberg consolidate vendor relationships around platforms with algorithmic transparency documentation.
United States
Long-haul trucking corridors from Chicago to Los Angeles compress ELD compliance deployment timelines. The FMCSA mandates electronic logging device synchronization for hours-of-service enforcement. Dallas-Fort Worth logistics hubs concentrate third-party telematics providers serving refrigerated transport fleets.
United Kingdom
London's ultra-low emission zone forces last-mile delivery electrification with battery state-of-health monitoring requirements. The DVSA enforces driver hours regulations through remote tachograph data downloads. Midlands distribution centers adopt subscription-based hardware provisioning to preserve working capital.
China
MIIT mandates connected vehicle data localization for commercial fleets operating along Yangtze River Delta manufacturing belts. GB standards govern telematics device electromagnetic compatibility. Shenzhen-based logistics platforms integrate domestic GPS-BeiDou dual-mode positioning for port-to-factory container tracking.
India
National highway freight corridors from Delhi to Mumbai accelerate AIS-140 compliant telematics adoption for commercial vehicles. The Ministry of Road Transport mandates GPS-based vehicle tracking and emergency response buttons. Gujarat manufacturing zones cluster telematics hardware assemblers serving domestic fleet operators.
Commercial Telematics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying GPS modules, cellular modems, and ruggedized enclosures. The vendor base stratifies between full-stack fleet management providers and hardware-centric OEM embedment specialists. Three archetypes dominate: cloud-native software platforms, automotive-grade hardware fabricators, and vertical-specific solution bundlers. Competitive moves concentrate on API ecosystem expansion and captive financing arms for hardware leasing.
Among North American platform providers, Geotab Inc., Verizon Connect, and Samsara Inc. exemplify the cloud-native archetype with recurring revenue models. These entities occupy positions where direct fleet relationships and cellular connectivity bundling create defensive moats. Their market presence anchors the mid-market segment where subscription economics displace capital expenditure procurement patterns.
| Leading Market Players |
|---|
| Geotab Inc. |
| Verizon Connect |
| Samsara Inc. |
| Trimble Inc. |
| Omnitracs LLC |
| PTC Inc. |
| TomTom Telematics |
| Mix Telematics International |
| Solera Holdings LLC |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's cost dynamics expose how hardware supply concentration in East Asia feeds downstream price differentiation between fleet-scale deployments and small-operator subscriptions. Contract manufacturing leverage at cellular modem foundries compresses margins for mid-tier platform vendors while premium providers extract pricing power through EU AI Act pre-certification bundling.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise fleet management, mid-market subscription bundles, and small-fleet BYOD applications. Price differentiation hinges on certification grade for EU AI Act algorithmic transparency and after-sales service bundling including firmware lifecycle management. Pricing pressure stems from semiconductor cost volatility in GPS module sourcing. Small UK courier fleets exhibit highest price sensitivity; German automotive OEMs demonstrate lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan-based EMS providers and South Korean cellular modem foundries holding capacity for automotive-grade hardware. Geographic supply concentration centers on Taiwan, South Korea, and Shenzhen manufacturing zones. Raw material dependencies include GPS chipsets, LTE-M modems, and lithium-polymer batteries. Single-source vulnerability in cellular baseband fabrication poses structural risk. Distribution runs through direct fleet relationships and automotive OEM embedment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated German logistics cooperatives and Dutch freight forwarders capable of demanding EU AI Act pre-certification, fragmenting price-setting autonomy among platform vendors.
For Market Incumbents: Pre-empt margin erosion by embedding algorithmic transparency documentation into standard platform architecture before procurement cycles begin. Backward integration into captive cellular connectivity provisioning defends against commoditization. Vertical integration into firmware development teams addresses embedded software talent scarcity threatening product roadmaps. For New Entrants and Emerging Players: Scandinavian forestry equipment telematics represents underpenetrated white space where ruggedized hardware requirements deter generalist competitors. Australian mining haul corridors offer satellite-backup subscription traction absent entrenched incumbents. Construction equipment OEM embedment partnerships provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive OEM telematics divisions seeking to monetize non-core connected vehicle data infrastructure. Long-term viability favors platforms with dedicated compliance engineering teams capable of navigating evolving AI transparency obligations. Watch for inflection signals in captive financing arm formation among mid-market fleet operators.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Algorithmic transparency documentation accelerates German fleet procurement decisions. |
| Cellular Connectivity Captive Financing | Subscription bundling preserves working capital for UK mid-market operators. |
| Construction Equipment OEM Embedment | Factory-integrated ruggedized hardware opens margin pools in earthmoving verticals. |
| Edge Computing Firmware Development | Vehicle-mounted analytics reduces latency for safety-critical fleet alerts. |
| Video Telematics Insurance Partnership | Dashcam integration compresses claims resolution timelines for German underwriters. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, telematics platform engineers, commercial auto underwriters, and automotive OEM procurement leads; and secondary validation against FMCSA ELD certification databases, EU mobility package regulatory filings, SEC 10-K hardware vendor disclosures, and customs import records for GPS module trade flows. Bottom-up fleet deployment estimates triangulated against top-down market sizing from cellular connectivity subscription data.
Forecast inputs considered hardware shipment volumes, software subscription attach rates, and regulatory mandate implementation schedules across the projection horizon. Segmentation dimensions modeled include product architecture, connectivity modality, fleet size tier, vertical specialization, and regional regulatory cluster. CAGRs derived from S-curve adoption modeling for ELD compliance saturation and AI Act transparency requirement phase-ins.
Practitioners should monitor cellular network sunsetting schedules, EU AI Act implementing act releases, and semiconductor foundry capacity utilization for early signals requiring forecast revision. Quarterly review of FMCSA enforcement discretion patterns and German KBA type-approval queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Automotive OEM Telematics Market
Telematics and Infotainment
North America Automotive Infotainment System Market
Telematics and Infotainment
Smart Telematics Gateway Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
United States Commercial Telematics Market
Telematics and Infotainment
Video Telematics Market
Telematics and Infotainment
Fleet Telematics System Market
Telematics and Infotainment
Edge Computing in Automotive Market
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Global Taxi-Sharing Software Market
Telematics and Infotainment
Automotive Telematics System Market