
 In-Car Infotainment Market | 2026-2036
In-Car Infotainment Market Size, Share, and Industry Trends Forecast 2026-2036
In-Car Infotainment Market Intelligence
The EU Green Deal is shifting automotive electronics procurement criteria toward energy-efficient digital cockpit architectures. Robert Bosch leverages its semiconductor foundry partnerships to secure chip supply for integrated infotainment controllers. Harman International anchors premium audio and connected services across luxury vehicle programs. Continental AG dominates embedded software stacks through its cross-domain high-performance computer platforms.
In-car infotainment denotes the integrated hardware-software ecosystem delivering navigation, entertainment, telematics, and human-machine interface functionality within vehicles, typically operating on 12V automotive electrical architectures with real-time operating systems and ASIL-B safety compliance. Touchscreen displays lead product type revenue as OEMs standardize 10-15 inch curved panels across vehicle classes. Voice recognition technology grows fastest among interface modalities as natural language processing migrates from cloud-dependent to edge-computing architectures. OEM end users capture the dominant margin pool through bundled subscription services and over-the-air software update monetization.
The EU AI Act and GDPR constrain biometric driver monitoring and data localization in European vehicle programs, while the U.S. NHTSA and FCC govern distracted-driving interface design and spectrum allocation for vehicle-to-everything connectivity. China's MIIT mandates domestic encryption standards for connected car data streams, creating compliance fragmentation for multinational suppliers. Stakeholders must monitor evolving cybersecurity certification requirements across jurisdictions to preserve market access and avoid retrofit liability exposure.
Market Dynamics
Embedded high-performance computing architectures are compressing the traditional tiered supplier hierarchy as OEMs consolidate cockpit domain controllers under single-source contracts. This centralization is redistributing margin pools away from discrete component vendors toward integrated platform providers.
Growth Catalysts
- EU Green Deal efficiency mandates:Digital cockpit power consumption limits are accelerating procurement of energy-optimized semiconductor nodes and thermal management systems.
- Edge AI inference migration:Natural language processing is decentralizing from cloud dependencies to local neural accelerators, reducing latency for voice-controlled interfaces.
- Germany-South Korea-US electronics clusters:Concentrated R&D infrastructure in Stuttgart, Seoul, and Detroit is compressing development cycles for ASIL-B compliant software stacks.
Market Restraints
- Automotive-grade silicon foundry concentration:Advanced node capacity at TSMC and Samsung Foundry creates single-source vulnerability for 7nm and below infotainment SoCs.
- GDPR-EU AI Act compliance friction:Biometric driver monitoring systems face dual regulatory barriers requiring localized data processing and algorithmic transparency documentation.
- Legacy 12V electrical architecture lock-in:Electrification platform transitions to 48V systems demand complete cockpit electronics redesigns, extending validation timelines.
Strategic Opportunities
- Over-the-air monetization white space:Subscription-based feature activation for navigation, audio streaming, and performance tuning creates recurring revenue streams beyond hardware margins.
- India domestic market expansion:Localized infotainment platforms supporting 22 official languages represent underpenetrated demand as Maruti Suzuki and Tata Motors upgrade entry-segment offerings.
- Vehicle-to-everything spectrum allocation:FCC 5.9 GHz band rulings are enabling low-latency roadside infrastructure communication for predictive navigation and hazard alerting.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-B certification expertise concentrates at Continental, Bosch, and a handful of specialized consultancies, inflating program staffing costs.
- Multi-domain integration complexity:Consolidating instrument cluster, head-up display, and center stack software onto single high-performance computers demands real-time operating system harmonization across previously siloed supplier bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Car Infotainment Market |
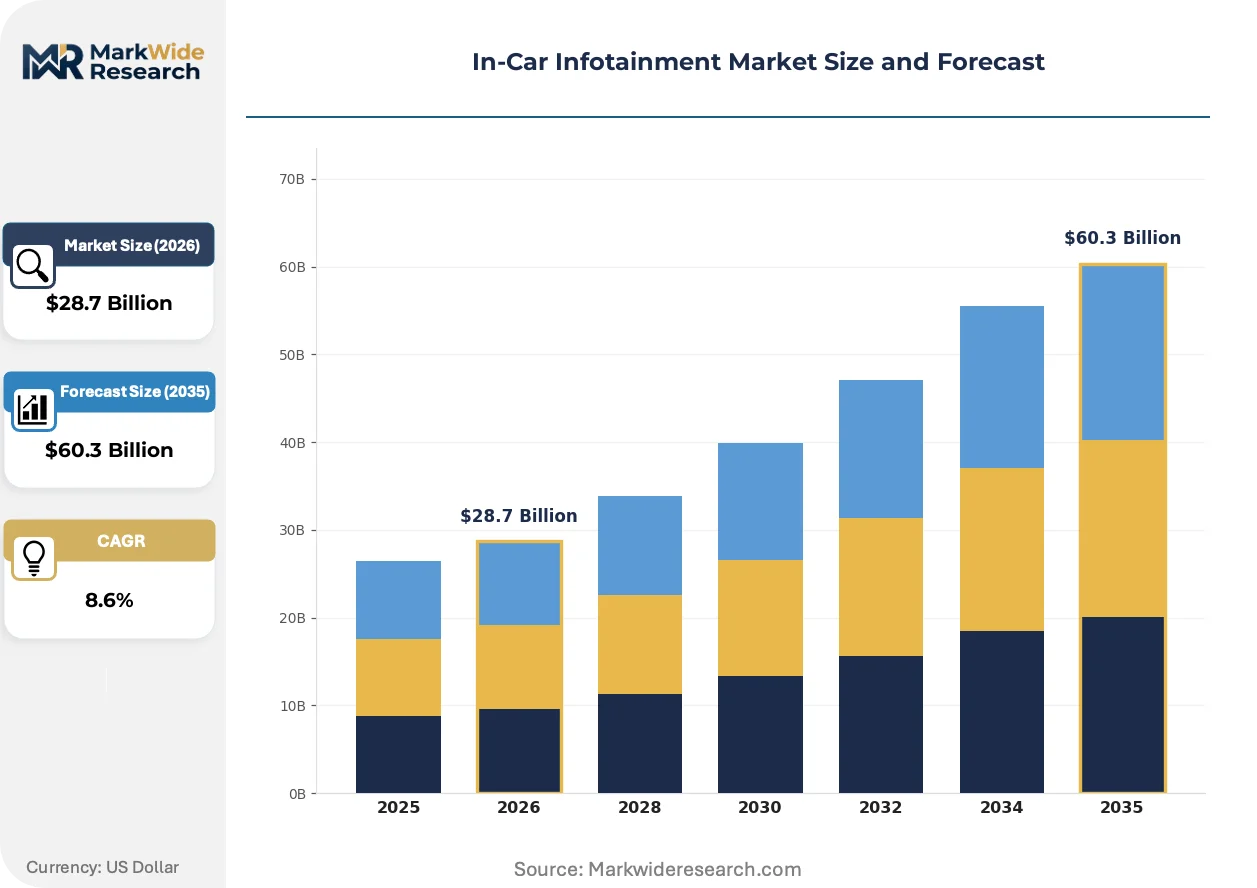
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $60.3 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head Units, Touchscreen Displays, Multimedia Interfaces, Sound Systems Technology: Android Auto, Apple CarPlay, Bluetooth, Voice Recognition End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships Service Type: Software Updates, Content Streaming, Navigation Services, Connectivity Services |
| Companies Covered | Denso Corporation, Robert Bosch, Harman International, Alps Alpine, Visteon Corporation, Continental AG, Pioneer Corporation, LG Electronics, Panasonic Automotive Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Car Infotainment Market Strategic Shifts & Innovations
Automotive cockpit electronics are undergoing architectural consolidation as discrete control units merge into cross-domain computing platforms. This compression is redistributing value capture toward software-defined vehicle stacks.
Automotive Ethernet switching is decentralizing in-vehicle network topologies from centralized gateway architectures to zonal compute configurations. Premium OEMs in Germany and the United States are deploying 10Gbps Ethernet backbone infrastructure across 2026-2027 vehicle programs. This topology shift is enabling deterministic data routing between sensors, actuators, and displays while reducing wiring harness mass and assembly complexity.
The EU AI Act's risk classification framework is imposing conformity assessment requirements on driver monitoring systems using computer vision. Tier-1 suppliers must now maintain technical documentation and human oversight protocols for emotion recognition and fatigue detection algorithms. European premium vehicle programs are responding by segregating biometric data processing to edge devices with localized inference, avoiding cloud transmission triggers for high-risk system classification.
Fleet operators and mobility service providers are unbundling after-sales service contracts from hardware procurement, purchasing predictive maintenance and software update subscriptions separately from initial system installation. This disaggregation is visible most acutely in North American commercial vehicle segments where rental car companies and last-mile delivery fleets negotiate multi-year service level agreements independent of capital equipment financing.
In-Car Infotainment Market Segmentation
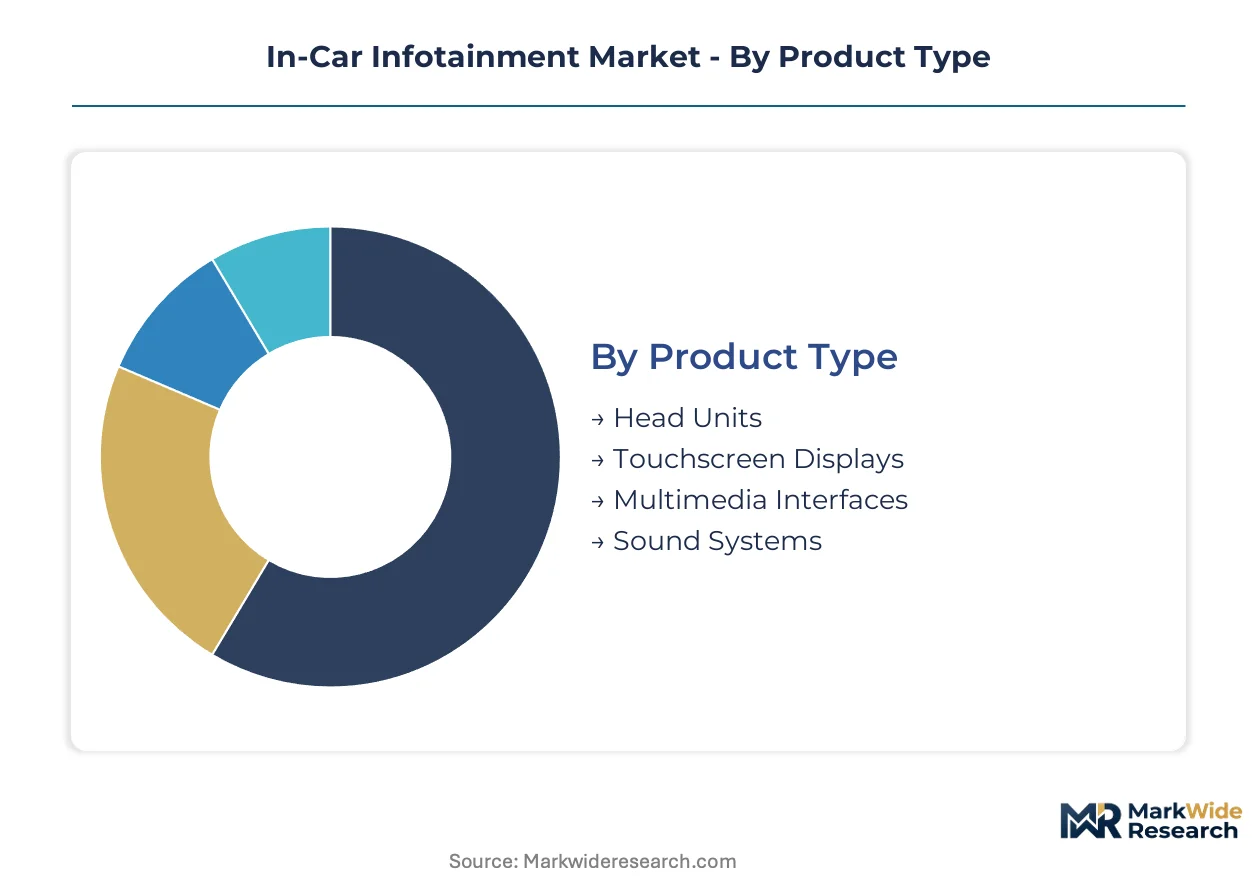
Infotainment procurement patterns diverge sharply between luxury OEMs pursuing integrated domain controllers and aftermarket channels serving legacy vehicle parc upgrades. Segmentation reveals how hardware-software bundling, connectivity standards, and service monetization reshape competitive positioning across supplier tiers.
Product Type:
Cost tier differentiation separates premium curved-panel deployments from entry-segment modular units, with thermal management and semiconductor node selection driving procurement decisions.
- Touchscreen Displays:Curved 10-15 inch panels with OLED or mini-LED backplanes dominate premium vehicle programs. German and South Korean OEMs standardize these across mid-luxury segments, pressured by EU Green Deal efficiency mandates for reduced power draw per pixel area.
- Head Units:Integrated computing platforms consolidating radio, navigation, and vehicle settings into single chassis-mounted assemblies. Aftermarket demand concentrates in North America for pickup truck and commercial vehicle retrofits where factory-installed options remain limited.
- Multimedia Interfaces:Physical control surfaces including rotary dials, touchpads, and steering wheel switches. Japanese OEMs retain these for tactile feedback compliance with NHTSA distracted-driving guidelines.
- Sound Systems:Amplifier-speaker arrays ranging from six-channel entry configurations to 20+ channel premium audio. High-fidelity deployments cluster in Stuttgart and Detroit luxury programs where branded audio partnerships command subscription bundling premiums.
Volume sits with Head Units; growth tilts toward Touchscreen Displays.
Technology:
Application maturity separates smartphone-mirroring protocols from emerging edge-AI interfaces, with latency requirements and data privacy architectures determining adoption velocity.
- Voice Recognition:Natural language processing migrating from cloud-dependent to edge-computing neural accelerators. GDPR and EU AI Act compliance pressures in European programs accelerate localized inference deployment for biometric driver monitoring exclusion.
- Apple CarPlay:Proprietary smartphone integration protocol with wireless certification expanding across vehicle classes. U.S. OEMs treat this as baseline expectation, while some German manufacturers resist full dashboard surrender to maintain native interface control.
- Android Auto:Google-developed mirroring standard with open-source customization for regional app ecosystems. Indian market expansion drives localization for 22 official languages through Maruti Suzuki and Tata Motors entry-segment programs.
- Bluetooth:Legacy audio streaming and hands-free telephony protocol. Fleet operators in North American commercial segments specify this for rental and last-mile delivery vehicle standardization where smartphone agnosticism reduces support overhead.
Bluetooth carries installed base volume; Voice Recognition claims the steepest expansion trajectory.
End User:
Customer type determines contract structure, with bundled subscription monetization separating OEM direct procurement from disaggregated fleet service agreements.
- OEMs:Direct vehicle manufacturer procurement with multi-year platform contracts and over-the-air update monetization rights. Single-source consolidation of cockpit domain controllers redistributes margin pools toward integrated platform providers.
- Fleet Operators:Mobility service providers unbundling hardware from predictive maintenance subscriptions. North American rental and delivery fleets negotiate multi-year service level agreements independent of capital equipment financing.
- Aftermarket Providers:Independent installers serving vehicle parc beyond warranty periods. Channels concentrate in Germany and the United States where aging vehicle fleets sustain retrofit demand.
- Dealerships:Franchised distribution networks offering factory-authorized upgrades. Service integration with warranty coverage limits their addressable market to brand-compliant system extensions.
Volume concentrates with OEMs; Fleet Operators expand most quickly.
Service Type:
Margin structure separates one-time navigation licensing from recurring connectivity revenues, with data localization requirements fragmenting regional deployment architectures.
- Software Updates:Over-the-air firmware and feature activation enabling subscription-based monetization. Premium OEMs capture dominant margin pools through performance tuning and audio streaming feature unlocks.
- Navigation Services:Real-time traffic routing and predictive hazard alerting leveraging 5.9 GHz vehicle-to-everything spectrum allocation. FCC rulings enable low-latency roadside infrastructure communication in U.S. programs.
- Connectivity Services:Embedded cellular data plans and Wi-Fi hotspot provisioning. China's MIIT mandates domestic encryption standards, creating compliance fragmentation for multinational suppliers.
- Content Streaming:Integrated audio and video platform partnerships. GDPR constraints on biometric data processing limit personalized content recommendation deployment in European vehicle programs.
Navigation Services anchor current revenue; Software Updates gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the industry's R&D gravity as German OEMs consolidate cockpit domain controller procurement under single-source contracts with embedded software specialists.
United States
Detroit's automotive electronics cluster drives embedded system development for luxury pickup and SUV programs. FCC 5.9 GHz spectrum rulings enable low-latency vehicle-to-everything connectivity for predictive navigation. Michigan-based engineering centers compress validation timelines for ASIL-B compliant software stacks.
Germany
EU Green Deal efficiency mandates accelerate procurement of energy-optimized semiconductor nodes for digital cockpits. KBA certification requirements govern human-machine interface safety compliance. Bavaria's semiconductor foundry partnerships secure chip supply for integrated infotainment controllers.
South Korea
Seoul's display panel manufacturers supply curved OLED and mini-LED backplanes for 10-15 inch touchscreen standardization. MFDS data localization guidance constrains biometric driver monitoring architectures. Gyeonggi-do electronics clusters concentrate neural accelerator development for edge AI voice recognition.
China
MIIT mandates domestic encryption standards for connected car data streams, fragmenting compliance for multinational suppliers. Shenzhen's hardware ecosystem produces cost-optimized head units for entry-segment vehicle programs. Yangtze River Delta automotive electronics corridors integrate thermal management systems for power-efficient cockpit architectures.
India
Maruti Suzuki and Tata Motors upgrade entry-segment offerings with localized infotainment platforms supporting 22 official languages. TRAI spectrum allocation frameworks govern embedded cellular connectivity provisioning. Tamil Nadu automotive clusters assemble modular head units for domestic and export vehicle programs.
In-Car Infotainment Market Key Industry Players
The competitive structure tilts toward integrated platform providers as OEMs consolidate cockpit domain controllers under single-source contracts. Discrete component vendors face margin compression while software-defined vehicle stacks capture expanding value pools. Two archetypes dominate: semiconductor-anchored systems integrators and audio-centric connected service providers. Consolidation through foundry partnerships and cross-domain computing platform development represents the primary competitive vector.
Among Germany-based diversified suppliers, Robert Bosch and Continental AG occupy positions as integrated platform architects. Harman International represents the audio and connected services specialization archetype. These three entities exemplify how embedded high-performance computing architectures redistribute margin pools away from discrete hardware vendors toward consolidated software stack providers.
| Leading Market Players |
|---|
| Denso Corporation |
| Robert Bosch |
| Harman International |
| Alps Alpine |
| Visteon Corporation |
| Continental AG |
| Pioneer Corporation |
| LG Electronics |
| Panasonic Automotive Systems |
| Others |
Cost & Logistics Intelligence
Semiconductor wafer costs cascade through three distinct pricing tiers as 7nm and below process nodes from TSMC and Samsung Foundry concentrate supply leverage among German and South Korean OEMs. Thermal management system procurement for curved OLED panels further stratifies cost structures between luxury integrated domain controllers and entry-segment modular head units.
Pricing Analysis
Subscription-based feature activation anchors value-based pricing as OEMs monetize over-the-air navigation unlocks and performance tuning software. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-B certified integrated platforms from aftermarket retrofit units and entry-segment Bluetooth-only configurations. Price differentiation hinges on semiconductor node sophistication and bundled connectivity service duration. Pricing pressure stems from foundry capacity constraints at advanced nodes, compressing margins for tier-2 suppliers lacking captive silicon access. Fleet operators exhibit highest price sensitivity through unbundled hardware procurement, while luxury OEMs absorb premiums for single-source domain controller consolidation.
Supply Chain Analysis
ISO 26262 ASIL-B functional safety certification gates supplier qualification, concentrating approved vendors among Continental, Bosch, and specialized consultancies. Taiwan, South Korea, and Germany anchor geographic supply for advanced node semiconductors, display backplanes, and embedded software stacks respectively. Raw material dependencies center on silicon wafers, rare-earth phosphors for mini-LED backplanes, and copper-lithium thermal interface materials. Single-source vulnerability at TSMC and Samsung Foundry for 7nm infotainment SoCs represents the dominant structural risk. Distribution runs through direct OEM platform contracts with multi-year offtake commitments, bypassing traditional tier-2 component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act and GDPR dual compliance framework erects substantial cost-of-entry barriers, advantaging incumbent platform providers with established localized data processing architectures and algorithmic transparency documentation protocols.
For Market Incumbents: Extend cross-domain computing platform consolidation to capture margin pools from discrete component vendors facing architectural obsolescence. Deepen foundry partnerships at 7nm and below to defend against single-source silicon vulnerability threatening production continuity. Lock in ASIL-B certification talent through captive consultancy acquisitions before functional safety engineer scarcity inflates program staffing costs further. For New Entrants and Emerging Players: Enter via India's entry-segment localization opportunity where Maruti Suzuki and Tata Motors demand 22-language voice recognition platforms with limited incumbent penetration. Target aftermarket head unit retrofit channels in Germany and the United States where aging vehicle parc sustains hardware replacement demand outside OEM warranty control. Pursue white-label edge AI neural accelerator supply to tier-2 suppliers lacking in-house inference chip development. For Investors and Strategic Acquirers: FCC 5.9 GHz spectrum allocation rulings enabling vehicle-to-everything connectivity is the leading indicator that predictive navigation and hazard alerting service monetization will accelerate recurring revenue capture. Long-term viability favors integrated platform architects over discrete hardware vendors as cockpit domain controller consolidation progresses. Acquisition targets should display embedded software stack dominance combined with foundry partnership security. The signal to monitor is OEM single-source contract announcements for next-generation high-performance computing platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Domain Controller Consolidation | Single-source contracts with Bosch and Continental redistribute margin pools toward software-defined vehicle stacks. |
| Edge AI Neural Accelerator Development | Gyeonggi-do electronics clusters enable GDPR-compliant localized inference for voice recognition migration. |
| Foundry Partnership Security | TSMC and Samsung Foundry capacity reservations at 7nm reduce single-source vulnerability for infotainment SoCs. |
| India Localization Platform | Maruti Suzuki and Tata Motors entry-segment programs create 22-language voice recognition white space. |
| 5.9 GHz V2X Spectrum Deployment | FCC rulings enable low-latency roadside infrastructure communication for predictive navigation monetization. |
Research Approach
SEC 10-K filings, EU regulatory guidance documents, and vehicle production databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distribution channel managers, and functional safety certification consultants validated demand assumptions and procurement timeline intelligence. Bottom-up unit economics triangulated against top-down market value estimates to anchor forecast credibility.
Bottom-up modeling segmented volume and value across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions throughout the forecast period. CAGRs derived from production ramp schedules, semiconductor node transition timelines, and regulatory compliance deadline clustering. Forecast inputs incorporated EU Green Deal efficiency mandate implementation velocity and edge AI inference migration patterns from cloud-dependent to localized architectures.
Revisions become necessary when foundry capacity allocation shifts, cybersecurity certification requirements fragment across jurisdictions, or 48V electrical architecture transitions accelerate beyond current validation timelines. Forecasts reflect documented assumptions regarding OEM single-source consolidation preferences and subscription monetization adoption curves. A model refresh is warranted upon material change in FCC spectrum allocation rulings or MIIT encryption standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Telematics-Linked Fleet Battery Health Management Systems Market
Telematics and Infotainment
Transport Data Logger Market
Telematics and Infotainment
Telematics Control Unit Market
Telematics and Infotainment
Roadside Assistance Software Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Boat and Ship Telematics Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Automotive Data Monetization Market
Telematics and Infotainment
United States Commercial Telematics Market
Telematics and Infotainment
Telematics Market