
 Smart Telematics Gateway Market | 2026-2036
Smart Telematics Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Telematics Gateway Market Analytics
Fleet management is consolidating its position as the dominant end-use vertical for smart telematics gateways. Harman International leverages its automotive audio heritage to extend into connected vehicle platforms. Sierra Wireless anchors its position through specialized cellular module integration for commercial transport. Texas Instruments competes on semiconductor cost structures that underpin gateway processing power.
A smart telematics gateway is an embedded or standalone computing device that aggregates vehicle sensor data, processes location and diagnostic information through GPS and cellular protocols, and transmits structured telemetry to cloud-based fleet platforms. Embedded gateway architectures dominate automotive OEM supply chains due to factory-integrated durability and warranty alignment. Cellular technology commands the highest value share among connectivity options, while standalone wireless configurations represent the fastest expansion path for aftermarket retrofit segments. Fleet management applications generate the largest revenue pool, though driver behavior monitoring is gaining traction among insurance-linked deployments.
The U.S. FMCSA and the EU's General Safety Regulation shape hardware mandates, with ELD compliance and intelligent speed assistance requirements forcing gateway specification upgrades. Germany's KBA enforces type-approval standards that filter non-compliant suppliers from European commercial vehicle channels. Stakeholders must monitor how cybersecurity certification requirements in connected vehicle regulations reshape component sourcing and firmware update architectures.
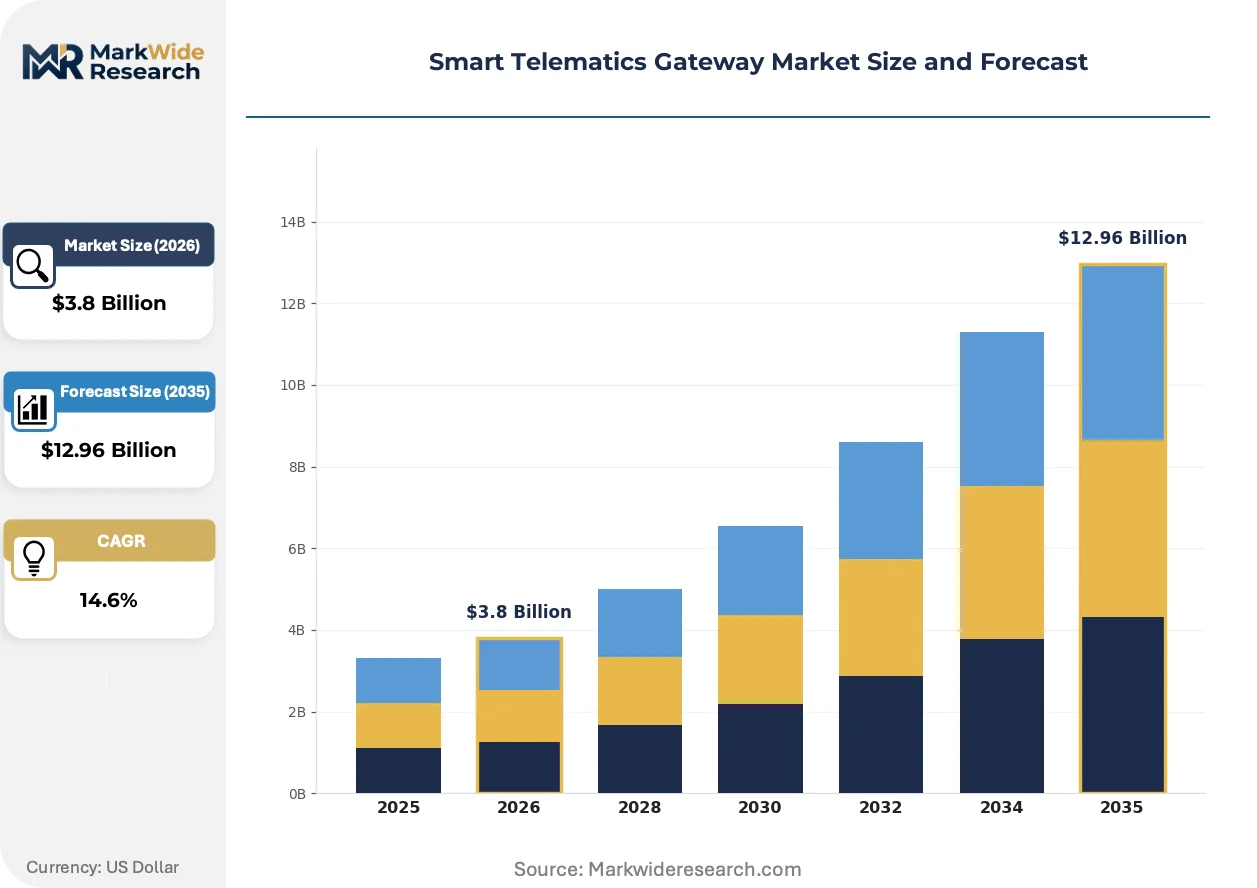
Market Dynamics
Fleet operators' mandate-driven hardware refresh cycles are compressing supplier lead times and forcing gateway architectures toward modular, firmware-upgradable designs that accommodate evolving ELD and cybersecurity specifications without physical replacement.
Growth Catalysts
- FMCSA ELD Mandate:U.S. commercial carriers must maintain compliant logging hardware, sustaining replacement demand and specification upgrades across heavy-duty vehicle fleets.
- Factory Integration:German commercial vehicle manufacturers embed gateways during assembly, locking in multi-year supply agreements and predictive maintenance service revenues.
- Cellular Module Evolution:5G LPWA protocols enable richer telemetry streams, allowing fleet platforms to process engine diagnostics and cargo sensor data in near-real-time.
Market Restraints
- Semiconductor Cost Volatility:Gateway processors and cellular modems face input price instability from concentrated foundry capacity in East Asian manufacturing hubs.
- Technical Obsolescence Risk:Rapid protocol evolution threatens hardware stranded by incompatible cellular bands or deprecated security standards.
- Regulatory Fragmentation:Divergent type-approval requirements between KBA, FMCSA, and Japan's MLIT force redundant certification investments for multi-region suppliers.
Strategic Opportunities
- Insurance-Linked Deployments:Usage-based insurance programs in North America and Europe are adopting driver behavior monitoring gateways for risk-adjusted premium models.
- EU General Safety Regulation:Intelligent speed assistance and automated emergency calling mandates create mandated installation volumes for compliant gateway hardware.
- Edge-AI Convergence:On-device inference engines combined with vehicle sensor fusion enable real-time cargo theft detection and predictive maintenance without cloud latency.
Industry Challenges
- Firmware Security Talent Scarcity:Over-the-air update architectures require embedded cybersecurity expertise that competes with automotive and consumer electronics sectors for limited engineering pools.
- Legacy Fleet Integration Complexity:Aftermarket gateway deployment in aging commercial vehicle parcs demands protocol adaptation for non-standardized OBD-II implementations and proprietary engine control modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Telematics Gateway Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded, Standalone, Integrated, Wireless Technology: GPS, Zigbee, Bluetooth, Cellular End User: Fleet Management, Automotive OEMs, Transport Operators, Insurance Application: Vehicle Tracking, Driver Behavior Monitoring, Fuel Management, Maintenance Alerts |
| Companies Covered | iWave Systems, Liebherr, Danfoss, Harman International, Spark Minda, Squarell Technology, Texas Instruments, Sierra Wireless, Lantronix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Telematics Gateway Market Evolving Landscape
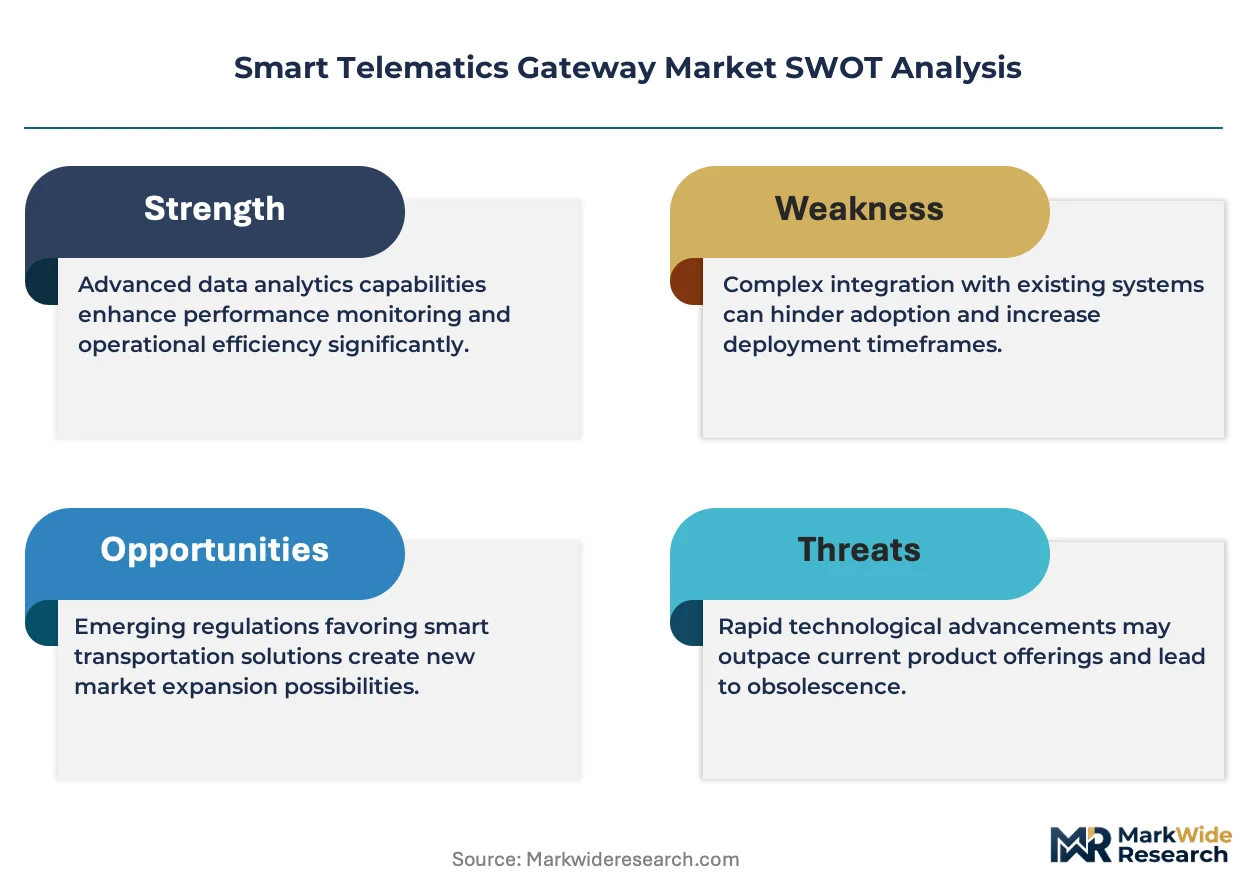
Gateway hardware is pivoting from passive data conduits toward intelligent edge nodes capable of local processing, while regulatory mandates accelerate specification convergence across major commercial vehicle markets.
Edge computing architectures are expanding into smart telematics gateways, enabling localized processing of video telematics and sensor fusion before selective cloud transmission. Heavy-duty fleet operators in North America and Europe are adopting these configurations to reduce cellular data costs and enable sub-second response for safety-critical alerts. This capability compression is displacing simpler telemetry-only hardware in premium fleet segments.
The EU's Cyber Resilience Act imposes mandatory security update obligations and vulnerability disclosure requirements on connected device manufacturers. Gateway suppliers must now maintain firmware support timelines spanning eight to ten years to satisfy type-approval continuity. Commercial vehicle OEMs in Germany and France are responding by consolidating supplier relationships with vendors demonstrating certified secure development lifecycle capabilities.
Leasing companies and large fleet aggregators are unbundling hardware procurement from connectivity service contracts, treating gateways as capital assets with separate financing structures. This procurement model evolution disrupts traditional bundled subscription offerings and pressures suppliers to disclose hardware bill-of-materials for residual value assessment. The shift is most visible in German and Dutch commercial vehicle leasing markets where operating lease penetration exceeds fifty percent of new heavy-duty registrations.
Smart Telematics Gateway Market Segmentation
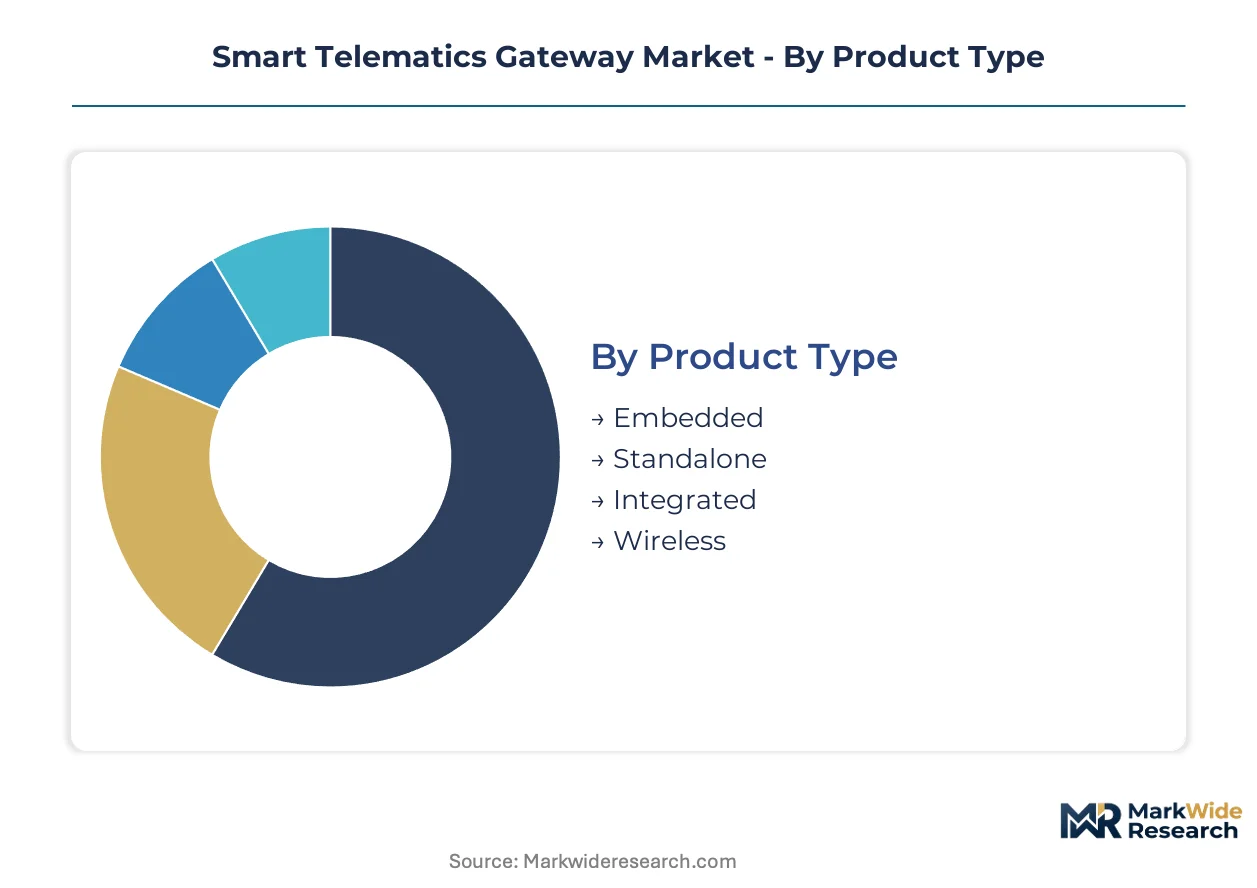
Smart telematics gateway segmentation reveals how hardware architectures, connectivity protocols, and customer procurement patterns fragment across distinct value pools. Understanding these divisions exposes where specification premiums concentrate and which configurations face commoditization pressure.
Product Type:
Customization intensity spans factory-integrated permanence to aftermarket flexibility, with durability warranties and upgrade pathways defining procurement preferences.
- Embedded:Factory-installed units sealed within vehicle electronics architectures carry OEM warranty alignment and vibration-resistant specifications. German commercial vehicle manufacturers embed these during assembly for predictive maintenance service integration. Demand concentrates in heavy-duty fleet channels where downtime costs justify premium hardware.
- Standalone:Aftermarket retrofit devices connect via OBD-II ports or hardwired installations, offering portability across vehicle assets. Fleet operators in North America deploy these for rapid ELD compliance without factory integration delays. This configuration gains traction among leasing companies treating gateways as transferable capital assets.
- Integrated:Multi-function units combining telematics with infotainment or diagnostic systems reduce installation complexity. Automotive OEMs favor these for cabin space optimization.
- Wireless:Battery-powered or solar-assisted units eliminate wiring harness requirements. Cargo monitoring applications in container logistics drive specialized demand.
Leading the category by volume: Embedded. Growing fastest: Standalone.
Technology:
Cost tiers separate legacy satellite positioning from cellular data transmission, with protocol maturity dictating hardware bill-of-materials and service subscription pricing.
- Cellular:LTE-M and 5G LPWA modules enable real-time telemetry streaming with bandwidth for video telematics and sensor fusion. Fleet management platforms in the United States process engine diagnostics and cargo alerts through these protocols. Cellular commands the highest value share due to recurring connectivity revenues.
- GPS:Satellite positioning remains foundational for location tracking, though increasingly bundled rather than standalone. Basic fleet tracking applications in price-sensitive segments rely on GPS-only configurations.
- Bluetooth:Short-range protocols support driver identification and peripheral sensor pairing. Last-mile delivery fleets use these for handheld device integration.
- Zigbee:Mesh networking capabilities suit warehouse yard management and trailer-to-tractor communication. Niche adoption concentrates in refrigerated transport with distributed temperature sensors.
Highest margin capture: Cellular. Steepest expansion trajectory: 5G LPWA variants.
End User:
Customer type determines procurement scale, with fleet aggregators negotiating enterprise pricing while insurers demand usage-based risk analytics.
- Fleet Management:Commercial vehicle operators deploy gateways across hundreds to thousands of assets for route optimization and regulatory compliance. FMCSA ELD mandates sustain replacement cycles in U.S. heavy-duty segments. This vertical generates the largest revenue pool through bundled hardware and connectivity contracts.
- Insurance:Usage-based insurance programs adopt driver behavior monitoring gateways for risk-adjusted premium models. North American and European carriers pilot these for commercial auto lines.
- Automotive OEMs:Factory-level integration locks in multi-year supply agreements with predictive maintenance service revenues.
- Transport Operators:Bus and rail systems prioritize passenger safety and schedule adherence over cargo telemetry.
Dominant procurement scale: Fleet Management. Emerging demand concentration: Insurance-linked deployments.
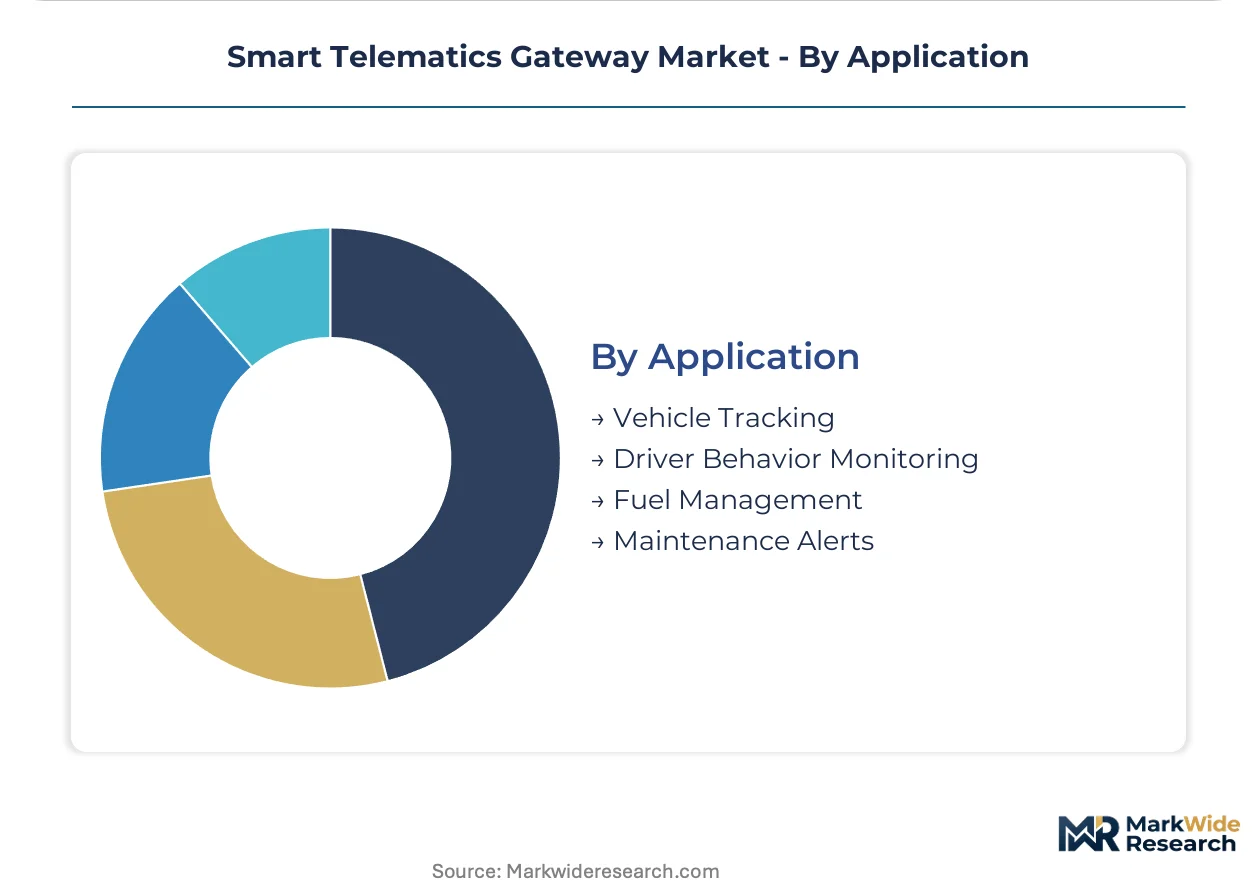
Application:
Maturity curves separate established tracking functions from emerging AI-enabled safety and efficiency use cases.
- Vehicle Tracking:Location monitoring with geofencing and route history forms the baseline functionality. Every fleet deployment includes this capability, though pricing pressure intensifies as hardware commoditizes.
- Driver Behavior Monitoring:Accelerometer and video analysis detect harsh braking, speeding, and distraction events. Insurance partnerships in Europe and North America accelerate adoption for premium discount eligibility.
- Fuel Management:Engine data integration tracks consumption patterns and idle time. Fuel represents the largest variable cost for commercial fleets.
- Maintenance Alerts:Predictive algorithms flag component degradation before failure. German OEMs bundle these with factory-embedded gateways.
Widest deployment: Vehicle Tracking. Gaining share fastest: Driver Behavior Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive manufacturing corridors and commercial vehicle production zones concentrate gateway demand across distinct regulatory environments. Factory integration mandates and fleet compliance requirements shape procurement patterns in each concentration area.
Germany
Commercial vehicle OEMs embed gateways during assembly for predictive maintenance service integration. The Kraftfahrt-Bundesamt enforces type-approval standards that filter non-compliant suppliers from European channels. Stuttgart and Munich anchor embedded gateway production for heavy-duty fleet channels.
United States
FMCSA ELD mandates sustain replacement cycles across heavy-duty vehicle fleets. The Federal Motor Carrier Safety Administration shapes hardware specifications through electronic logging device compliance architectures. Michigan and Ohio manufacturing clusters supply modular gateway designs for rapid specification upgrades.
China
Domestic commercial vehicle production scales drive embedded gateway volumes for factory integration. The Ministry of Industry and Information Technology governs connected vehicle cybersecurity certification requirements. Yangtze River Delta electronics manufacturing hubs process cellular module integration for regional OEM supply chains.
Japan
Commercial transport operators prioritize passenger safety and schedule adherence through gateway-enabled monitoring. The Ministry of Land, Infrastructure, Transport and Tourism administers type-approval requirements for connected vehicle hardware. Nagoya and Osaka industrial corridors concentrate on integrated multi-function gateway production.
India
Fleet operators deploy aftermarket gateways for rapid compliance without factory integration delays. The Bureau of Indian Standards develops certification frameworks for automotive electronics. Tamil Nadu and Gujarat automotive manufacturing zones attract gateway suppliers targeting commercial vehicle export channels.
Smart Telematics Gateway Market Competitive Landscape
Top-tier vendors anchor automotive OEM supply chains, while mid-tier specialists serve aftermarket retrofit segments. The competitive structure fragments across embedded integration specialists, cellular module integrators, and semiconductor cost leaders. Three archetypes dominate: automotive electronics heritage players, wireless communications specialists, and component-scale semiconductor suppliers. M&A activity concentrates on firmware capabilities and cybersecurity certification assets, while strategic partnerships lock in multi-year factory integration contracts.
Within the automotive electronics tier, Harman International and Texas Instruments exemplify divergent strategic positions. Harman leverages consumer audio heritage into connected vehicle platform integration, occupying a position among cabin-technology converged suppliers. Texas Instruments anchors the semiconductor cost-structure vector, supplying processing architectures that underpin gateway compute density. Sierra Wireless sits within the wireless communications specialist archetype, representing cellular module integration capabilities for commercial transport applications. These three companies collectively illustrate how component heritage shapes competitive positioning across factory-integrated and aftermarket channels.
| Leading Market Players |
|---|
| iWave Systems |
| Liebherr |
| Danfoss |
| Harman International |
| Spark Minda |
| Squarell Technology |
| Texas Instruments |
| Sierra Wireless |
| Lantronix |
| Others |
Value Network & Pricing Analysis
Captive semiconductor fabrication by Texas Instruments anchors both supply security and margin structure for gateway processors, insulating tier-one suppliers from foundry price volatility while forcing smaller competitors into spot-market cellular module procurement. This integration choice concentrates pricing power with vendors controlling in-house chip supply, particularly where FMCSA ELD mandates compress hardware refresh cycles.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as fleet operators face compressed ELD compliance windows. Three-tier pricing structure across premium, standard, and economy levels separates factory-embedded units with decade-long firmware support from aftermarket standalone devices. Price differentiation hinges on cybersecurity certification grade and cellular protocol generation. Pricing pressure stems from semiconductor input cost volatility in East Asian manufacturing hubs. Leasing companies exhibit highest price sensitivity, while German OEMs prioritize specification compliance over unit economics.
Supply Chain Analysis
Cellular module supply rests on Taiwanese and South Korean semiconductor packaging specialists, with GPS chip fabrication concentrated in US and Chinese foundries. Gateway assembly draws from Malaysian and Mexican electronics manufacturing hubs serving North American fleet demand. Raw material dependencies span lithium-ion battery cells for wireless units, automotive-grade aluminum enclosures, and 5G LPWA radio components. Single-source vulnerability concentrates in cellular baseband processor supply. Distribution runs through Tier 1 automotive suppliers and specialized fleet telematics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart telematics gateway market functions as a cost-of-compliance story where EU Cyber Resilience Act firmware mandates create a decade-long support obligation moat for certified suppliers. This regulatory barrier filters out undercapitalized entrants unable to sustain eight-to-ten-year security update architectures.
For Market Incumbents: Anchor factory integration relationships through predictive maintenance service bundling with German commercial vehicle OEMs. Deepen backward integration into cellular module sourcing to offset foundry concentration risk. Defend against standalone aftermarket specialists by accelerating edge-AI feature deployment in embedded architectures. For New Entrants and Emerging Players: Fleet leasing companies represent the most penetrable channel partner type for transferable capital asset positioning. Target insurance-linked driver behavior monitoring deployments in North America where usage-based premium models reduce price sensitivity. Pursue white-label manufacturing partnerships with established cellular module integrators to bypass certification timeline barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in automotive OEM captive acquisition and private equity consolidation of cybersecurity-certified firmware capabilities. Long-term viability favors vendors with demonstrated secure development lifecycle certification spanning the analysis window. Watch for FMCSA mandate expansion into medium-duty vehicle classes as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | EU Cyber Resilience Act compliance locks in multi-year OEM supply contracts with firmware support obligations. |
| Edge-AI Capability Integration | On-device inference enables real-time cargo theft detection without cloud latency for premium fleet segments. |
| Cellular Module Backward Integration | In-house 5G LPWA sourcing insulates margins from Taiwanese foundry price volatility and allocation constraints. |
| Insurance Channel Partnership | Usage-based premium programs in North America create recurring hardware refresh demand outside fleet cycles. |
| Leasing Company Direct Procurement | Unbundled hardware financing in German and Dutch markets treats gateways as transferable capital assets. |
Research Methodology
SEC 10-K filings, EU type-approval databases, and commercial vehicle production records formed the secondary backbone, cross-referenced with primary interviews across fleet operations directors, automotive OEM platform engineers, Tier 1 supplier procurement leads, and cellular module integration specialists. Bottom-up and top-down triangulation validated gateway shipment volumes against fleet telematics platform subscriber disclosures.
Bottom-up modeling aggregated unit economics across embedded, standalone, and wireless product configurations, while top-down analysis tracked regulatory mandate timelines and commercial vehicle production forecasts. Segmentation dimensions spanned hardware architecture, cellular protocol generation, end-user vertical, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and mandated installation volume floors. Forecast inputs incorporated FMCSA ELD compliance penetration curves and EU General Safety Regulation implementation schedules.
Caveats apply where semiconductor foundry allocation disruptions or accelerated cellular protocol obsolescence could materially shift the outlook. Forecasts reflect assumptions around regulatory enforcement continuity and fleet operator capital expenditure stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Next Generation in-Vehicle Networking (IVN) Market
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Automotive OEM Telematics Market
Telematics and Infotainment
Europe Telematics Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Global Taxi-Sharing Software Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Electronic Rotary Controller Systems for Infotainment Market
Telematics and Infotainment
Telematics Market