
 Automotive Wi-Fi Router Market | 2026-2036
Automotive Wi-Fi Router Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wi-Fi Router Market Analysis
Chinese electronics manufacturing clusters is expanding output capacity for automotive-grade networking chipsets, tightening supply availability for router assembly lines worldwide. TP-Link leverages its consumer networking scale to anchor aftermarket distribution across Latin America and Southeast Asia. Sierra Wireless sustains R&D intensity in embedded cellular modules, competing directly with Huawei Technologies' integrated vehicle-to-cloud platforms. NETGEAR differentiates through ruggedized hardware designs purpose-built for fleet telematics environments.
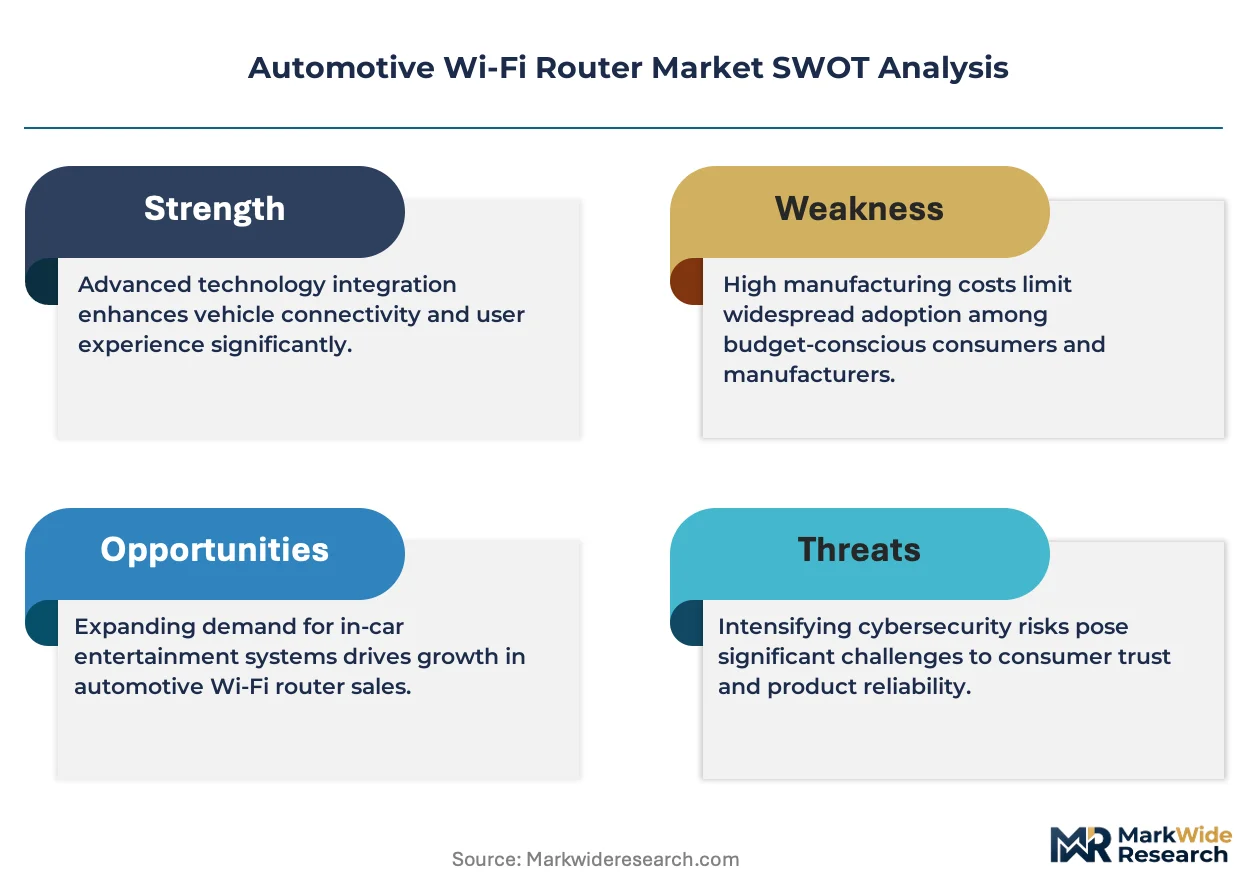
An automotive Wi-Fi router is a dedicated wireless access point engineered for vehicular deployment, typically operating across 2.4 GHz and 5 GHz bands with ingress protection ratings of IP54 or higher to withstand vibration, temperature cycling, and electromagnetic interference inherent to automotive environments. Its primary industrial purpose is to deliver persistent internet connectivity for passenger devices, telematics gateways, and over-the-air software update pipelines while the vehicle is in motion or parked. Embedded routers now capture the dominant share of OEM factory installations because automakers prioritize seamless dashboard integration and warranty-aligned support over aftermarket flexibility. 5G connectivity variants represent the fastest-expanding segment within the connectivity dimension, though Wi-Fi 6 maintains substantial volume in cost-sensitive fleet configurations where ultra-low latency is not operationally critical.
The FCC governs spectrum allocation for vehicular communications in the United States, while the EU AI Act and GDPR impose data governance obligations on connected vehicle platforms processing passenger information across European roads. China's MIIT enforces GB standards for in-vehicle wireless equipment, creating divergent certification pathways that fragment hardware design requirements. Stakeholders must monitor whether regional regulators harmonize cross-border data flow rules or harden localization mandates, as this determination will reshape supplier geographic footprints and compliance cost structures more decisively than any single technology cycle.
Market Dynamics
The DSRC-to-C-V2X migration mandated by the FCC is compressing OEM integration timelines while fragmenting hardware certification pathways across regulatory jurisdictions. This spectrum reallocation forces simultaneous redesigns of antenna subsystems and firmware stacks.
Growth Catalysts
- FCC broadband infrastructure mandates:Federal funding programs accelerate roadside unit deployment, creating pull-through demand for compatible in-vehicle router hardware across passenger and commercial fleets.
- Fleet telematics digitization:Commercial vehicle operators face tightening connectivity mandates for hours-of-service logging, remote diagnostics, and cargo monitoring.
- Over-the-air update pipelines:Automakers require persistent high-bandwidth links to distribute software patches to powertrain, infotainment, and ADAS modules.
Market Restraints
- Automotive-grade chipset supply concentration:Foundry capacity for AEC-Q100 qualified networking silicon clusters in Taiwan and South Korea, exposing router assemblers to allocation volatility.
- Regulatory fragmentation:China's MIIT GB standards, EU GDPR data localization, and US FCC Part 15 rules impose non-overlapping certification requirements that multiply SKU complexity.
- Power consumption constraints:Electric vehicle architectures prioritize range preservation, capping thermal budgets for always-on router subsystems.
Strategic Opportunities
- Aftermarket retrofit channels:Aging commercial fleets in Brazil and Mexico lack factory connectivity, creating demand for ruggedized plug-in router solutions.
- 5G-V2X convergence:Integration of cellular vehicle-to-everything stacks with Wi-Fi 6 backhaul enables unified hardware platforms serving both infrastructure communication and passenger hotspot functions.
- EU Green Deal procurement incentives:Public fleet operators gain preferential financing for connected vehicle upgrades that demonstrate emissions monitoring capabilities.
Industry Challenges
- Embedded systems firmware talent scarcity:Router manufacturers compete with consumer electronics firms for engineers skilled in real-time operating systems and automotive safety integrity levels.
- Multi-domain certification timelines:Simultaneous FCC, CE marking, and MIIT approvals for a single hardware variant extend time-to-revenue by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wi-Fi Router Market |
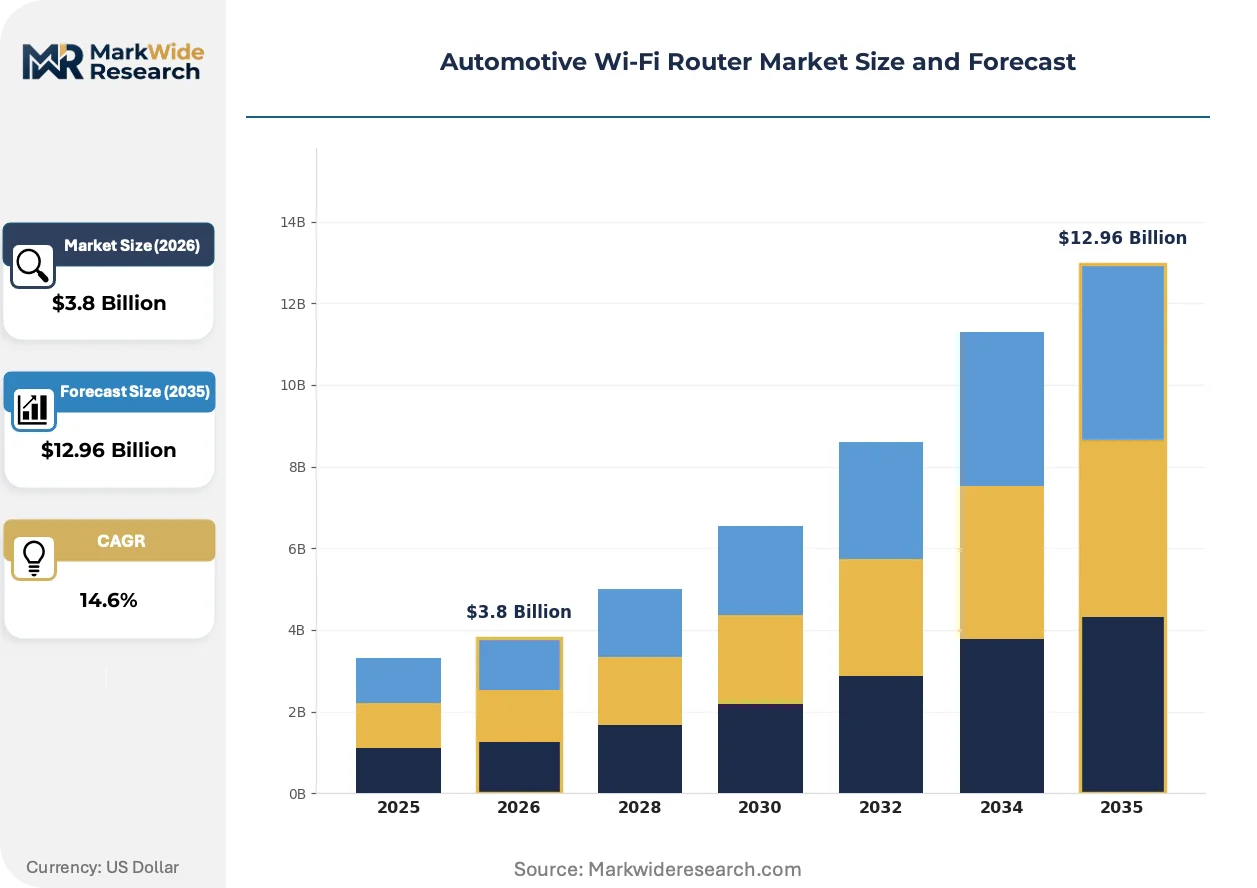
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Hotspot, Embedded Router, USB Dongle, OBD-II Router End User: OEMs, Fleet Operators, Individual Consumers, Aftermarket Providers Connectivity: 4G LTE, 5G, Wi-Fi 6, Wi-Fi 5 Application: In-Car Entertainment, Navigation, Vehicle Tracking, Remote Diagnostics |
| Companies Covered | TP-Link, NETGEAR, Sierra Wireless, Teldat Group, Linksys, Huawei Technologies, ZTE Corporation, Cisco Systems, KuWFi Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wi-Fi Router Market Emerging Trajectories
Automotive Wi-Fi router architectures are absorbing cellular and satellite connectivity modules into unified platforms, collapsing separate hardware stacks while raising thermal and electromagnetic compatibility design burdens.
Wi-Fi 6E is absorbing the 6 GHz spectrum allocation for low-latency in-vehicle entertainment and telematics backhaul. Luxury automakers in Germany and the United States are adopting tri-band routers to support concurrent passenger streaming and autonomous sensor data offload. This expansion is absorbing premium price tiers into mid-range vehicle configurations as chipset costs decline.
The EU AI Act imposes algorithmic transparency requirements on connected vehicle platforms processing biometric or behavioral data. European OEMs must now document data flows between router gateways and cloud inference engines. This regulatory layer is forcing hardware designers to embed edge-processing capabilities that pre-filter sensitive information before transmission.
Fleet procurement departments are consolidating vendor relationships around full-stack connectivity providers rather than discrete router hardware. Large logistics operators in the United States now specify bundled data plans, device management platforms, and hardware as single contracts. This bundling is compressing margins for pure-play router manufacturers while elevating systems integrators with captive carrier partnerships.
Automotive Wi-Fi Router Market Segmentation
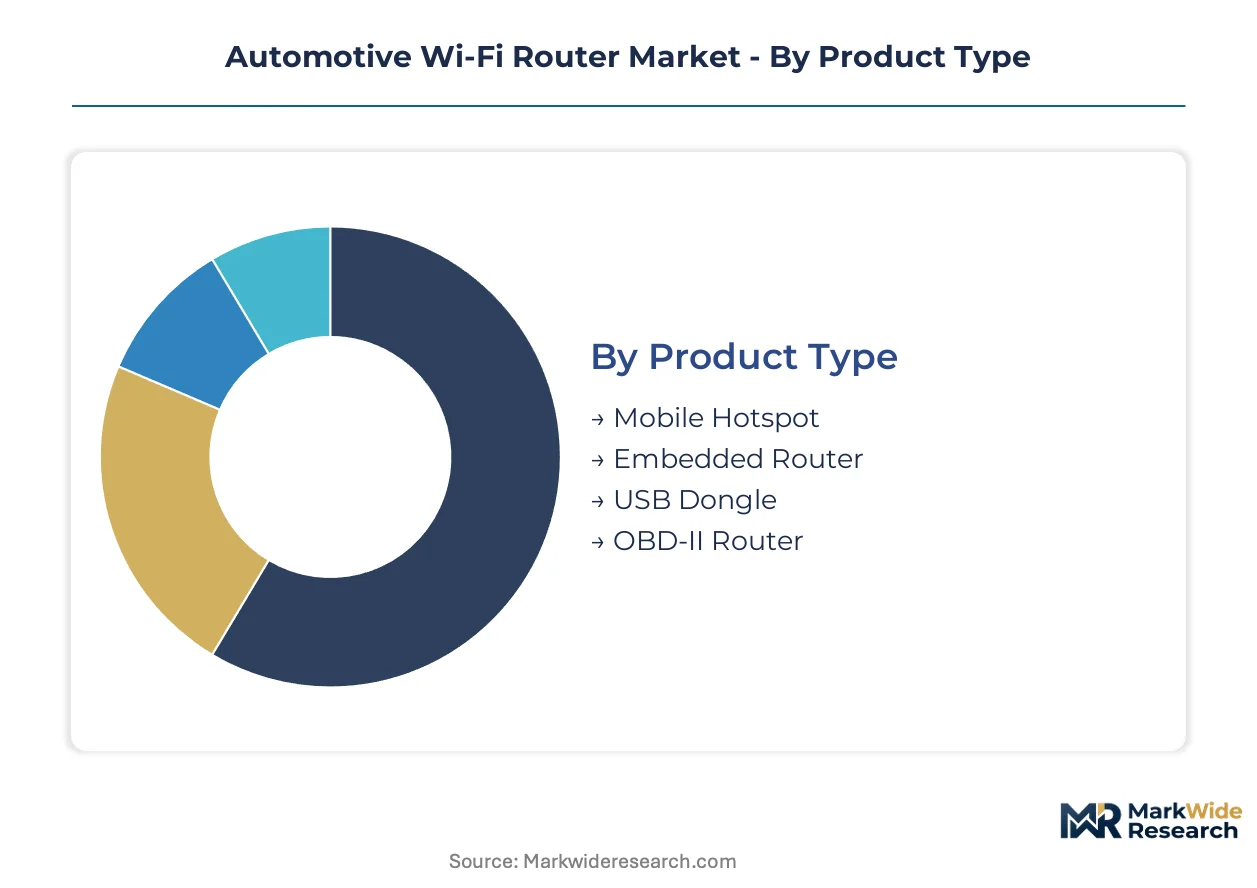
Automotive Wi-Fi router procurement decisions hinge on integration depth, connectivity performance, and regulatory compliance. Fleet operators prioritize ruggedized hardware with centralized management platforms, while OEMs demand seamless dashboard integration and warranty-aligned support cycles.
Product Type:
Fleet procurement departments evaluate total cost of ownership across hardware lifespan, installation complexity, and firmware update pathways.
- Embedded Router:Factory-integrated units mount directly into vehicle head units or telematics gateways with IP54+ ingress protection and AEC-Q100 qualified chipsets. OEMs in Germany and the United States specify these for seamless warranty coverage and over-the-air update pipelines. Volume sits with Embedded Router; growth tilts toward 5G-enabled variants expanding most quickly in luxury vehicle configurations.
- Mobile Hotspot:Portable battery-powered units deliver passenger connectivity without vehicle electrical integration, appealing to rental car operators and ride-hailing drivers seeking temporary deployment flexibility. Demand concentrates in Brazil and Mexico where aging fleet retrofits outpace factory-installed alternatives.
- USB Dongle:Compact plug-in devices draw power from vehicle USB ports, serving cost-sensitive individual consumers with minimal installation requirements.
- OBD-II Router:Devices interfacing through onboard diagnostic ports combine connectivity with vehicle telemetry extraction, targeting fleet telematics providers requiring engine data alongside internet access.
Embedded systems dominate OEM factory installations; aftermarket channels favor plug-and-play alternatives with lower upfront commitment.
End User:
Buyer sophistication varies sharply across volume commitments, technical specification depth, and post-sale support expectations.
- Fleet Operators:Commercial vehicle managers mandate connectivity for hours-of-service compliance, cargo monitoring, and predictive maintenance across distributed vehicle pools. United States logistics operators now specify bundled hardware-data-management contracts, compressing margins for pure-play router manufacturers. Procurement is shifting toward full-stack providers with captive carrier partnerships.
- OEMs:Automakers integrate routers during vehicle assembly, prioritizing electromagnetic compatibility certification and multi-year supply agreements with tier-1 electronics suppliers. European OEMs face EU AI Act documentation requirements for data flows between router gateways and cloud inference engines.
- Aftermarket Providers:Independent installers and automotive retailers serve vehicle owners seeking connectivity upgrades outside factory warranty periods.
- Individual Consumers:Private vehicle owners purchase through retail channels, driving price sensitivity and favoring established consumer networking brands.
Commercial buyers command specification authority; individual consumers follow brand recognition and retail availability.
Connectivity:
Network technology selection balances latency requirements against chipset cost curves and carrier coverage maps.
- 5G:Millimeter-wave and sub-6 GHz variants enable ultra-low latency for autonomous sensor data offload and high-definition passenger streaming. Luxury automakers in Germany and the United States adopt tri-band architectures absorbing 6 GHz spectrum allocations. This segment climbs the fastest as modem costs decline and carrier infrastructure expands.
- Wi-Fi 6:802.11ax standards deliver improved spectral efficiency for dense device environments within commercial cabins and motorcoach configurations. Fleet operators in cost-sensitive segments specify these where ultra-low latency is not operationally critical.
- 4G LTE:Mature modem ecosystems sustain volume in emerging markets and budget vehicle configurations with adequate bandwidth for standard telematics.
- Wi-Fi 5:Legacy 802.11ac hardware persists in entry-level aftermarket products and replacement cycles for installed base maintenance.
5G variants gain share fastest in premium tiers; Wi-Fi 6 sustains mid-range fleet volume through cost optimization.
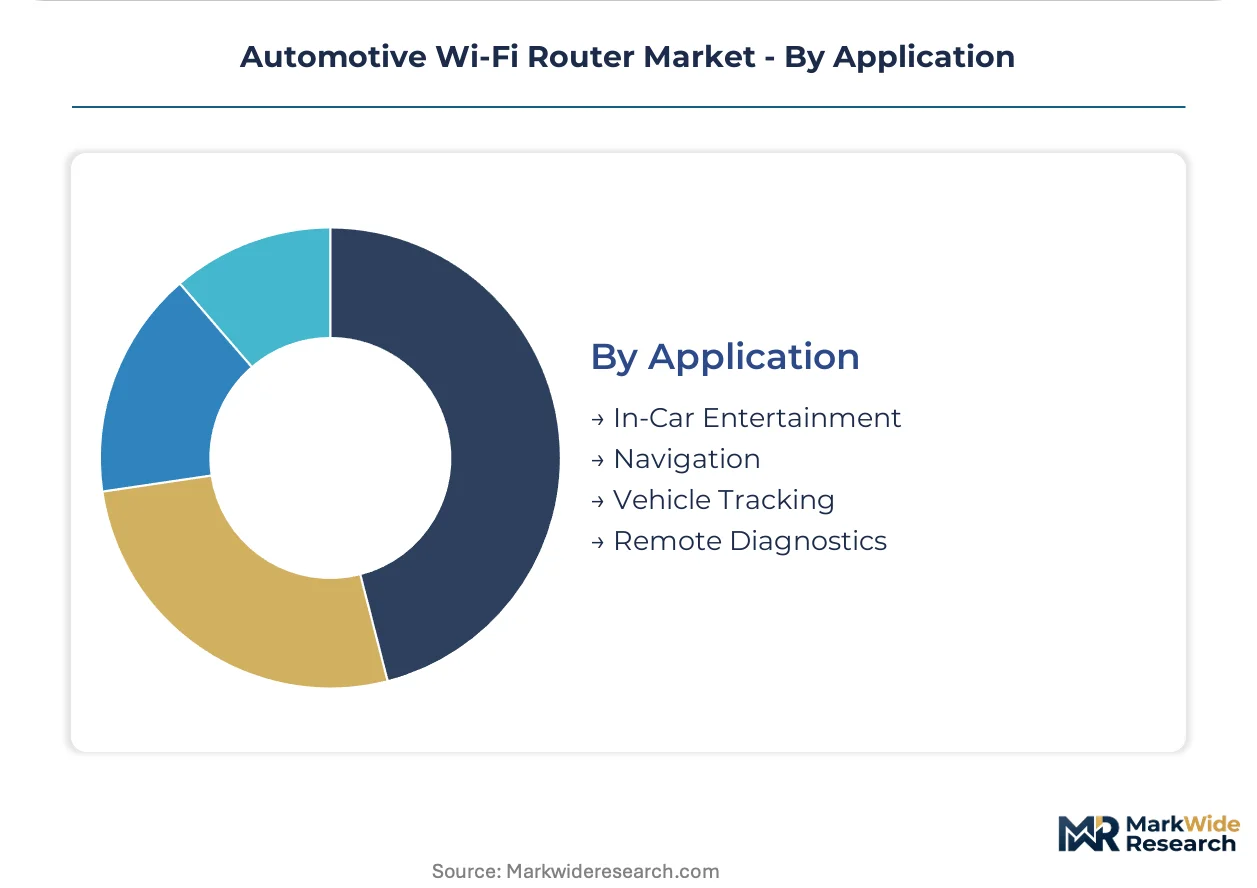
Application:
Functional use cases determine bandwidth, reliability, and security specification thresholds.
- Remote Diagnostics:Real-time powertrain and ADAS module monitoring demands persistent high-bandwidth links with automotive safety integrity level compliance. OEMs require these pipelines for warranty cost containment and predictive service scheduling.
- In-Car Entertainment:Passenger streaming and gaming drives consumer-facing bandwidth requirements, influencing router placement and antenna subsystem design.
- Vehicle Tracking:Location and route optimization services prioritize connectivity reliability over peak throughput for logistics operators.
- Navigation:Cloud-based mapping and traffic integration requires consistent low-latency data exchange with minimal packet loss.
Telematics applications anchor commercial procurement; entertainment features differentiate consumer retail positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive-grade networking silicon foundries cluster in Taiwan and South Korea, anchoring supply-side geography for router assembly ecosystems worldwide.
United States
Fleet telematics digitization and connected-car penetration drive procurement volume. The FCC's DSRC-to-C-V2X migration compresses OEM integration timelines. Detroit-Warren-Dearborn automotive electronics corridors host tier-1 supplier engineering centers developing embedded router platforms for domestic automakers.
Germany
Luxury automakers specify tri-band Wi-Fi 6E routers for concurrent passenger streaming and autonomous data offload. The EU AI Act imposes algorithmic transparency requirements on data flows between router gateways and cloud inference engines. Stuttgart and Munich engineering clusters concentrate embedded systems firmware talent for automotive safety integrity level compliance.
China
Electronics manufacturing clusters in Shenzhen and Dongguan expand output capacity for automotive-grade networking chipsets. MIIT enforces GB standards for in-vehicle wireless equipment, creating divergent certification pathways. Yangtze River Delta foundries supply AEC-Q100 qualified silicon to both domestic OEMs and export-oriented router assemblers.
Japan
Automakers integrate routers during vehicle assembly with multi-year supply agreements prioritizing electromagnetic compatibility certification. METI oversees spectrum allocation coordination with automotive safety regulators. Nagoya and Tokyo electronics corridors sustain precision manufacturing capabilities for ruggedized vehicular networking hardware.
Brazil
Aging commercial fleets lacking factory connectivity create aftermarket retrofit demand for ruggedized plug-in router solutions. ANVISA regulates electromagnetic emissions standards for in-vehicle electronic equipment. São Paulo industrial districts host distribution hubs serving Latin American fleet operators seeking cost-effective telematics upgrades.
Automotive Wi-Fi Router Market Vendor Landscape
Global majors compete with regional champions across certification expertise and carrier partnership depth. The vendor base stratifies between tier-1 electronics suppliers with captive automotive divisions and pure-play networking specialists pursuing fleet telematics niches. Three archetypes dominate: consumer networking brands leveraging retail scale, embedded cellular module specialists, and ruggedized hardware fabricators. Capacity expansion and strategic partnerships with mobile network operators constitute the dominant competitive moves.
Within the consumer-networking tier, TP-Link and NETGEAR exemplify scale-driven aftermarket positioning across Latin America and Southeast Asia distribution channels. Sierra Wireless occupies a position within embedded cellular specialists, while Huawei Technologies anchors integrated vehicle-to-cloud platform development. These three represent divergent strategic postures: retail brand extension, module-level R&D intensity, and full-stack vertical integration.
| Leading Market Players |
|---|
| TP-Link |
| NETGEAR |
| Sierra Wireless |
| Teldat Group |
| Linksys |
| Huawei Technologies |
| ZTE Corporation |
| Cisco Systems |
| KuWFi Technology |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal procurement incentives gate qualified supply for automotive-grade Wi-Fi routers, restricting premium-tier pricing access to vendors demonstrating emissions monitoring integration and GB-compliant certification stacks. Fleet operators purchasing bundled hardware-data-management contracts exert downward pressure on unbundled router margins, while OEMs absorb embedded system premiums through multi-year supply agreements with tier-1 electronics suppliers.
Pricing Analysis
Warranty and multi-year service bundling separate OEM embedded router pricing from aftermarket alternatives, with factory-integrated units commanding substantial premiums for seamless dashboard integration and AEC-Q100 qualified chipset guarantees. Price differentiation hinges on certification tier—FCC Part 15 plus CE marking versus single-jurisdiction approval—and volume scale commitments from fleet operators. Cost compression in aftermarket plug-in segments is intensifying because Chinese electronics manufacturing clusters expand output capacity for networking silicon. Individual consumers exhibit highest price sensitivity, while United States logistics operators prioritize total cost of ownership across hardware lifespan over unit acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea foundries producing AEC-Q100 qualified networking silicon, exposing router assemblers to allocation volatility when automotive-grade chipset demand spikes. The supply chain draws from Shenzhen and Dongguan for final assembly, with Yangtze River Delta facilities feeding both domestic OEMs and export markets. Raw material dependencies center on gallium nitride substrates, high-frequency laminates, and automotive-grade resin systems. Tariff exposure on Chinese-assembled finished goods threatens margin structures for brands without regional manufacturing footprints. Distribution runs through tier-1 automotive electronics suppliers for OEM channels, while aftermarket sales flow through consumer networking retail networks and fleet telematics integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over cellular module R&D and carrier partnership networks determines margin retention against full-stack connectivity providers.
For Market Incumbents: Cement multi-year supply agreements with Yangtze River Delta foundries to lock in AEC-Q100 qualified silicon allocation before capacity constraints intensify. Deepen backward integration into embedded cellular module design to defend margin position against Sierra Wireless and Huawei Technologies' integrated platforms. Priority investments should target DSRC-to-C-V2X firmware stacks, as FCC-mandated spectrum reallocation threatens obsolescence for hardware lacking unified cellular-V2X architectures. For New Entrants and Emerging Players: The FCC broadband infrastructure push in the United States opens a window for ruggedized plug-in router solutions targeting aging commercial fleets in Brazil and Mexico lacking factory connectivity. White-space concentration sits with aftermarket retrofit channels where ANVISA electromagnetic emissions compliance creates lower barriers than multi-jurisdiction OEM certification. Fleet telematics digitization mandates for hours-of-service logging represent the most penetrable application segment. Go-to-market execution should anchor on partnerships with Latin American mobile network operators offering bundled data plans alongside hardware deployment. For Investors and Strategic Acquirers: Accelerated 5G-V2X convergence adoption by luxury German automakers is the leading indicator that unified hardware platforms will displace discrete router and cellular module stacks within the projection horizon. Long-term viability favors systems integrators with captive carrier partnerships over pure-play router manufacturers facing margin compression from bundled procurement contracts. Target acquisition profile centers on embedded systems firmware specialists with automotive safety integrity level compliance capabilities and existing MIIT GB standard certification. The signal to monitor is tier-1 supplier consolidation around full-stack connectivity providers, which will strand hardware-only vendors without platform integration depth.| Strategic Initiative | Industry Significance |
|---|---|
| 5G-V2X Platform Integration | Unifies cellular vehicle-to-everything stacks with Wi-Fi 6 backhaul for OEM factory installations. |
| Backward Integration into Chipset Design | Captures AEC-Q100 qualified silicon sourcing through Yangtze River Delta foundry partnerships. |
| Carrier Partnership Consolidation | Locks in bundled hardware-data-management contracts with United States logistics operators. |
| Multi-Jurisdiction Certification Investment | Accelerates FCC, CE marking, and MIIT parallel approvals to compress 14-18 month time-to-revenue cycles. |
| Aftermarket Distribution Expansion | Penetrates Brazil and Mexico fleet retrofit demand through São Paulo industrial district hubs. |
Methodological Framework
Multi-period observation of vehicle production databases, connected-car penetration metrics, and fleet telematics adoption rates anchored the trend analysis, supplemented by interviews with tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers. Secondary validation drew from FCC spectrum allocation filings, MIIT GB standard publications, EU AI Act documentation requirements, and IHS Markit registration data. Bottom-up triangulation across router shipment volumes and top-down reconciliation against automotive electronics spending patterns ensured cross-verification of market sizing.
The input-output matrix framed projections across vehicle class, propulsion architecture, integration depth, connectivity technology, and regional production cluster dimensions. CAGRs were derived from segmented growth rate reconciliation against macroeconomic indicators and regulatory mandate timelines. Industry-specific forecast inputs included DSRC-to-C-V2X migration velocity, 5G infrastructure deployment curves, and fleet telematics digitization compliance deadlines.
The model assumes a particular technology adoption path; alternative pathways for C-V2X versus Wi-Fi-based vehicle-to-everything architectures would alter the outlook for unified hardware platform demand. Forecasts reflect assumptions regarding regulatory harmonization timelines, foundry capacity expansion schedules, and carrier infrastructure investment commitments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
India Fleet Management Software Market
Telematics and Infotainment
Edge Computing in Automotive Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Automotive Personal Navigation Systems Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
In-Vehicle Infotainment Systems Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
United States Commercial Telematics Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
North America Automotive Infotainment System Market
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
V2X Communication Module Market