
 Mobility on Demand (Mod) Market | 2026-2036
Mobility on Demand (Mod) Market Size, Share, and Industry Trends Forecast 2026-2036
Mobility on Demand (Mod) Market Insights
Asian fleet operators is expanding electric vehicle deployment across dense urban corridors to meet zero-emission targets. Uber Technologies leverages its global driver network to sustain market presence across multiple continents. Didi Chuxing anchors its competitive position through deep integration with China's smart city infrastructure. Grab differentiates by embedding financial services directly into its mobility super-app across Southeast Asia.
Mobility on Demand encompasses digitally intermediated transportation services where users access vehicles through real-time platforms rather than ownership, typically orchestrated via GPS-enabled mobile applications that match supply with demand algorithms. The primary commercial purpose centers on converting fixed asset costs into variable consumption while optimizing vehicle utilization rates across urban and suburban networks. Ride-hailing dominates current revenue pools due to established consumer habits and driver supply density, while bike-sharing segments exhibit the fastest trajectory as municipalities prioritize last-mile connectivity and micro-mobility lane expansion. Cloud computing infrastructure underpins margin scalability by enabling dynamic pricing engines and predictive demand clustering without proportional IT cost growth.
The US DOT and EPA jointly shape fleet composition through fuel economy standards and emissions benchmarks that directly determine vehicle procurement strategies for platform operators. India's Ministry of Road Transport and Highways enforces motor vehicle aggregator guidelines that mandate data localization and driver welfare provisions, altering platform cost structures. China's MIIT and SAMR coordinate on connected vehicle data security protocols that gate market access for foreign and domestic technology stacks. Stakeholders must monitor how fragmented regulatory frameworks across operating jurisdictions will force platform architecture modularization or geographic service fragmentation.
Market Dynamics
Electrification mandates from the EU Green Deal and California's Air Resources Board are compressing fleet procurement timelines while cloud-native dispatch platforms reduce marginal IT costs per ride.
Growth Catalysts
- Zero-Emission Fleet Mandates:California's Air Resources Board enforces progressively stricter emissions benchmarks that compel ride-hailing operators to accelerate EV deployment across vehicle pools.
- Smart City Infrastructure:Municipalities in Shenzhen, Singapore, and São Paulo are embedding mobility platforms into integrated traffic management systems that prioritize shared vehicle access.
- Last-Mile Connectivity Gaps:Urban commuters in dense Indian and Brazilian metropolitan corridors face unreliable public transit, creating sustained pull for app-based two-wheeler and micro-mobility services.
Market Restraints
- Driver Supply Volatility:Platform operators face recurring shortages of qualified drivers during peak demand windows, particularly in European markets with stringent employment classification rules.
- Battery Mineral Concentration:Lithium and cobalt processing capacity clusters in specific geographies, exposing fleet electrification timelines to raw material supply bottlenecks and price swings.
- Data Localization Requirements:India's motor vehicle aggregator guidelines mandate domestic server storage, forcing platform architecture duplication that raises fixed operational costs.
Strategic Opportunities
- Integrated Financial Services:Southeast Asian markets demonstrate strong uptake when ride-hailing platforms embed digital wallets, insurance products, and credit access directly into mobility applications.
- Suburban Network Expansion:Secondary cities across Brazil and India remain underserved by scheduled public transit, presenting white space for demand-responsive shuttle services.
- Vehicle-to-Grid Integration:Bidirectional charging infrastructure enables idle EV fleets to participate in electricity markets, converting parked assets into grid stabilization revenue streams.
Industry Challenges
- Algorithmic Bias in Dispatch Systems:Platform operators must continuously audit machine learning models to prevent discriminatory service patterns that attract regulatory penalties and driver litigation.
- Interoperability with Legacy Transit:Municipal payment systems and route data formats vary widely, forcing costly custom integrations for platforms seeking seamless multimodal trip planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobility on Demand (Mod) Market |
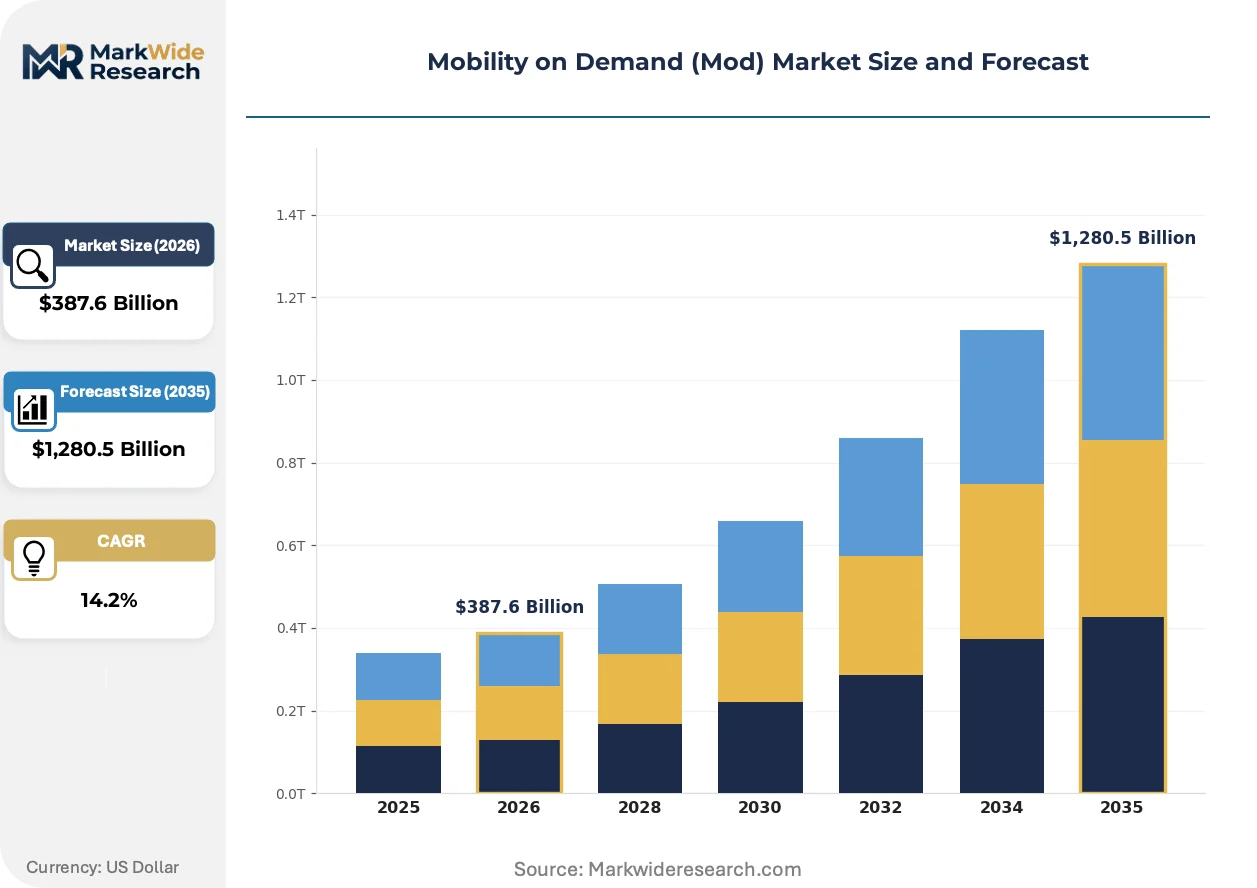
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,280.5 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Hailing, Car-Sharing, Bike-Sharing, Shuttle Services Technology: Mobile Apps, Cloud Computing, GPS Tracking, Telecommunication Customer Type: Individuals, Corporates, Government Agencies, Tourists Payment Model: Subscription, Pay-Per-Use, Flat Rate, Dynamic Pricing |
| Companies Covered | Uber Technologies, Lyft, Didi Chuxing, Grab, Turo, Zipcar, Via Transportation, Hertz, Ola, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobility on Demand (Mod) Market Trends and Innovations
Artificial intelligence and edge computing are compressing the latency between ride request and vehicle dispatch while regulatory pressure on emissions intensifies hardware refresh cycles across fleet portfolios.
Autonomous vehicle middleware is unifying sensor fusion, mapping, and decision engines into modular stacks that tier-one suppliers license to multiple OEMs. Fleet operators in Arizona and Texas are piloting these systems at constrained scale. This convergence is unifying previously fragmented R&D expenditures and accelerating validation timelines for urban robo-taxi deployment.
The EU Green Deal's Fit for 55 package mandates carbon intensity reductions across transport sectors that directly determine vehicle procurement specifications for platform operators. Fleet managers must now document lifecycle emissions across supply chains to maintain operating licenses in member states. Ride-hailing services in Germany and France face the most immediate compliance deadlines and are accelerating partnerships with European EV manufacturers.
Corporate travel managers are consolidating mobility spend under centralized SaaS platforms that aggregate receipts, enforce policy compliance, and negotiate volume discounts across multiple service providers. This procurement consolidation displaces individual employee reimbursement models and favors platforms with robust API connectivity and enterprise-grade reporting. The shift is most visible among technology and professional services firms with distributed workforces in North American and Western European urban centers.
Mobility on Demand (Mod) Market Segmentation
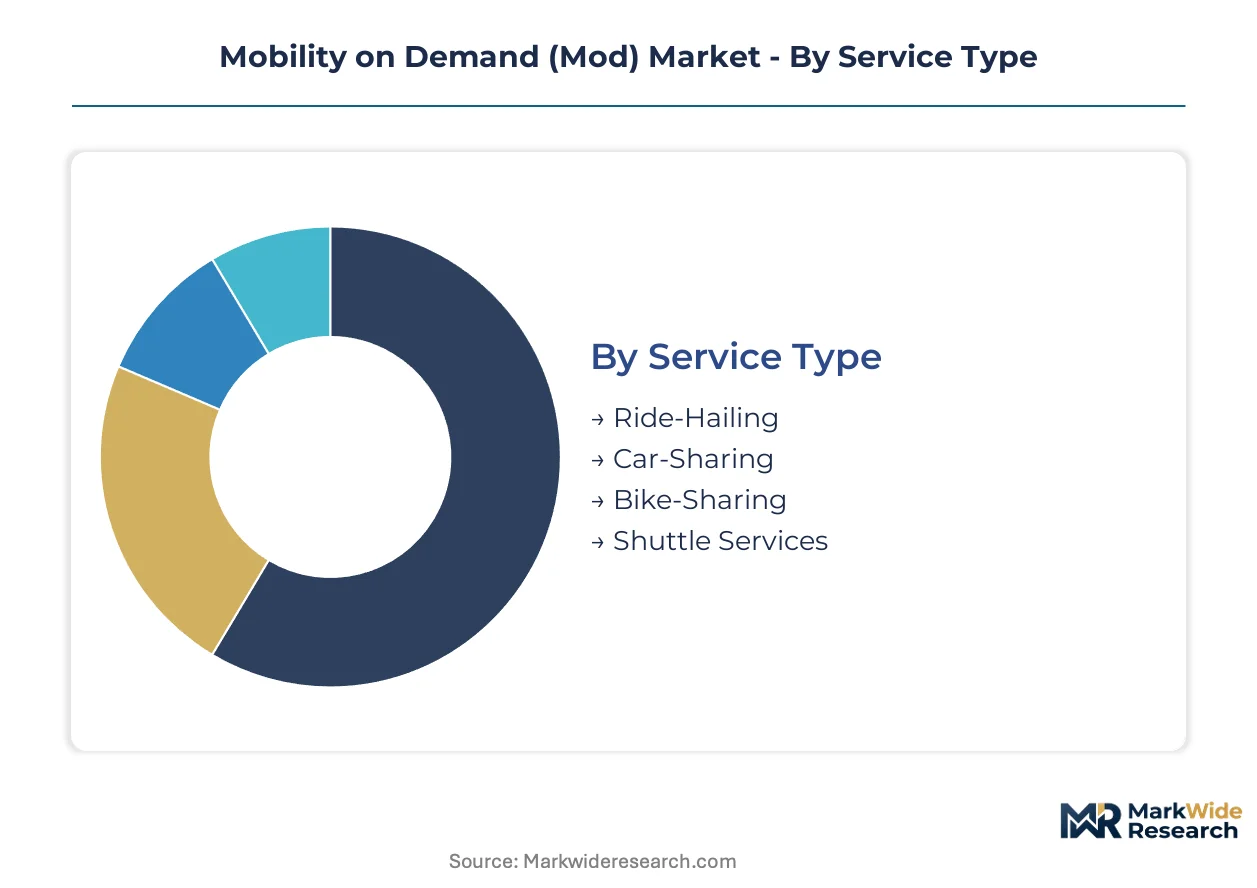
Service differentiation across Mobility on Demand platforms determines capital intensity, utilization economics, and regulatory exposure. Technology architecture choices directly shape marginal cost per transaction and geographic scalability. Customer and payment segmentation reveals diverging margin profiles and churn dynamics across urban mobility ecosystems.
Service Type:
Vehicle ownership models and trip duration specifications define the operational architecture and asset turnover characteristics for each service category.
- Ride-Hailing:On-demand vehicle dispatch through driver-operated fleets dominates current revenue concentration. Demand clusters in Indian and Brazilian metropolitan corridors where Ola and Uber compete for two-wheeler and four-wheeler market share, constrained by driver supply volatility during peak windows.
- Car-Sharing:Station-based or free-floating vehicle access models convert fixed ownership costs into variable hourly consumption. European fleet operators face accelerated procurement timelines under EU Green Deal emissions benchmarks, compressing ICE-to-EV transition schedules.
- Bike-Sharing:Docked and dockless micro-mobility services address last-mile connectivity gaps in dense urban networks. Municipal lane expansion in São Paulo and Shenzhen prioritizes shared bicycle and e-scooter access over private vehicle throughput.
- Shuttle Services:Fixed-route or demand-responsive collective transport serves suburban corridors with unreliable scheduled transit. Secondary cities across India and Brazil present white space for algorithmically routed shared van deployment.
Mature deployment sits with Ride-Hailing. Newer deployment is concentrated in Shuttle Services.
Technology:
Stack architecture decisions determine latency tolerance, data sovereignty compliance, and infrastructure cost scaling across operating jurisdictions.
- Mobile Apps:Consumer-facing interfaces orchestrate real-time matching between demand signals and distributed vehicle supply. India's motor vehicle aggregator guidelines mandate domestic server storage, forcing platform architecture duplication that raises fixed operational costs.
- Cloud Computing:Elastic compute resources enable dynamic pricing engines and predictive demand clustering without proportional IT expenditure growth. Edge computing deployments in Singapore and Shenzhen reduce dispatch latency for time-sensitive ride-matching.
- GPS Tracking:Satellite-based positioning systems enable route optimization, ETA prediction, and fleet telemetry collection. Chinese MIIT and SAMR coordinate on connected vehicle data security protocols that gate market access for foreign technology stacks.
- Telecommunication:Cellular and emerging V2X networks transmit operational data between vehicles, platforms, and traffic management systems. 5G infrastructure rollouts in Shenzhen and São Paulo support low-latency autonomous vehicle pilot programs.
Established infrastructure sits with Mobile Apps. Fastest capability expansion is occurring in Cloud Computing.
Customer Type:
Procurement behavior and price sensitivity vary substantially across consumer, enterprise, and institutional demand pools.
- Individuals:Price-sensitive urban commuters generate high-frequency, low-margin transactions concentrated in peak hours. App-based two-wheeler services in Indian metropolitan corridors capture this segment through aggressive driver incentive structures.
- Corporates:Centralized mobility spend under SaaS platforms aggregates receipts and enforces policy compliance across distributed workforces. Technology and professional services firms in North American urban centers drive procurement consolidation favoring API-connected providers.
- Government Agencies:Public sector contracts for employee transport and paratransit services require compliance with accessibility mandates and domestic content requirements. Fleet electrification specifications align with California Air Resources Board and EU Green Deal procurement guidelines.
- Tourists:Episodic demand with low switching costs and high willingness-to-pay for convenience and multilingual support. Airport and hospitality corridor concentration in Dubai, Singapore, and São Paulo shapes service design for this segment.
Volume concentration sits with Individuals. Margin expansion is concentrating in Corporates.
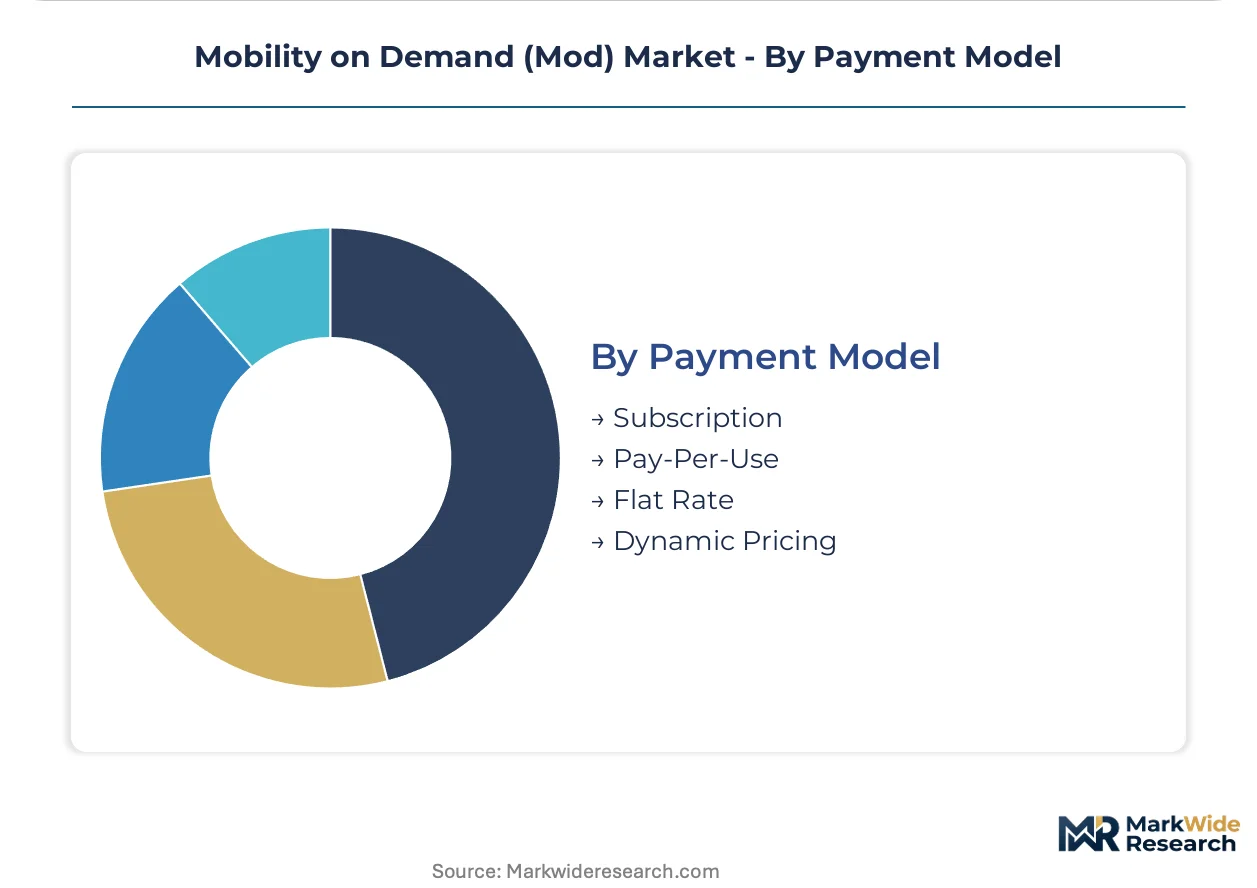
Payment Model:
Revenue recognition timing and customer lifetime value mechanics diverge sharply across pricing architectures.
- Subscription:Recurring monthly or annual commitments generate predictable cash flows and reduce per-transaction friction. Corporate travel managers in Western European markets favor subscription models for budget certainty and volume discount negotiation.
- Pay-Per-Use:Per-trip or per-minute metering aligns revenue with actual consumption and attracts price-sensitive occasional users. This model dominates individual consumer adoption in Indian and Brazilian markets with irregular mobility needs.
- Flat Rate:Unlimited access within defined zones or time windows simplifies value proposition communication. Municipal partnerships in São Paulo and Singapore experiment with flat-rate micro-mobility passes integrated into public transit fare systems.
- Dynamic Pricing:Algorithmic fare adjustment based on real-time supply-demand imbalances maximizes revenue per available seat-hour. Surge pricing triggers regulatory scrutiny in European markets with stringent consumer protection frameworks.
Revenue stability sits with Subscription. Transaction volume is climbing fastest in Pay-Per-Use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium processing clusters in Chile and Australia anchor battery supply chains for fleet electrification, while ride-hailing demand concentrates in dense metropolitan corridors across India, China, Brazil, and the United States.
United States
Corporate travel managers in North American urban centers consolidate mobility spend under centralized SaaS platforms that aggregate receipts and enforce policy compliance. California's Air Resources Board enforces progressively stricter emissions benchmarks compelling ride-hailing operators to accelerate EV deployment. Fleet operators in Arizona and Texas pilot autonomous vehicle middleware at constrained scale for urban robo-taxi deployment.
China
Urban commuters in Shenzhen and Shanghai access mobility platforms deeply integrated with smart city infrastructure that prioritizes shared vehicle access. MIIT and SAMR coordinate on connected vehicle data security protocols gating market access for foreign and domestic technology stacks. Yangtze River Delta municipalities embed mobility platforms into integrated traffic management systems with dedicated micro-mobility lane expansion.
India
Metropolitan commuters in Mumbai and Bangalore accelerate adoption of app-based two-wheeler and four-wheeler shared mobility services amid unreliable public transit. The Ministry of Road Transport and Highways enforces motor vehicle aggregator guidelines mandating data localization and driver welfare provisions. Ola and Uber compete for dominance across Indian metropolitan corridors through aggressive driver incentive structures.
Brazil
Urban commuters in São Paulo face sustained last-mile connectivity gaps creating pull for app-based two-wheeler and micro-mobility services. Municipal lane expansion in São Paulo prioritizes shared bicycle and e-scooter access over private vehicle throughput. Secondary cities across Minas Gerais and Rio Grande do Sul present white space for demand-responsive shuttle services with unreliable scheduled transit.
Germany
Corporate procurement consolidation among technology and professional services firms favors platforms with robust API connectivity and enterprise-grade reporting. The EU Green Deal's Fit for 55 package mandates carbon intensity reductions across transport sectors determining vehicle procurement specifications. Fleet managers in Bavaria and North Rhine-Westphalia document lifecycle emissions across supply chains to maintain operating licenses under member state deadlines.
Mobility on Demand (Mod) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in autonomous middleware and suburban shuttle networks. The vendor base organizes around three strategic archetypes: global platform operators with dense driver networks, regional specialists integrating financial services into mobility super-apps, and asset-light technology licensors supplying dispatch infrastructure. Competitive positioning hinges on M&A activity consolidating regional players and strategic partnerships with OEMs securing electrified vehicle supply.
Among US-based platform operators, Uber Technologies and Lyft anchor the ride-hailing archetype with established consumer habits and driver supply density across North American metropolitan corridors. Within the Asian specialist tier, Didi Chuxing and Grab exemplify regional positioning through deep smart city integration and embedded financial services respectively. These four entities represent contrasting geographic and service-model strategies within the broader mobility ecosystem.
| Leading Market Players |
|---|
| Uber Technologies |
| Lyft |
| Didi Chuxing |
| Grab |
| Turo |
| Zipcar |
| Via Transportation |
| Hertz |
| Ola |
| Others |
Pricing and Supply Chain Analysis
Captive integration into EV manufacturing and battery assembly anchors both procurement economics and fare-setting flexibility for fleet operators navigating California Air Resources Board mandates and EU Green Deal compliance deadlines. Platform operators with in-house electrification roadmaps capture margin insulation against volatile lithium carbonate pricing while externalizing driver supply costs through gig-economy labor models.
Pricing Analysis
Service bundling separates warranty-inclusive fleet maintenance packages from unbundled per-ride transactions, with subscription models commanding premium positioning among corporate travel managers in Western European markets. Three-tier pricing structure across premium black-car, standard ride-hail, and economy shared-pool levels tracks vehicle class and wait-time tolerance. Cost compression in economy tiers intensifies as driver incentive wars escalate across Indian metropolitan corridors. Individual commuters exhibit highest price sensitivity, while corporate SaaS procurement favors budget-certainty premiums.
Supply Chain Analysis
Workforce availability constraints in Chinese battery cell manufacturing and Indonesian nickel processing feed into fleet procurement bottlenecks for operators accelerating ICE-to-EV transitions. Lithium concentrate from Chilean salares and Australian hard-rock mines feeds Chinese cathode production, which supplies global EV assembly. Single-source vulnerability concentrates in cathode precursor chemicals from specific processing hubs. Distribution runs through OEM-direct fleet sales and third-party vehicle lessors with maintenance wrap.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
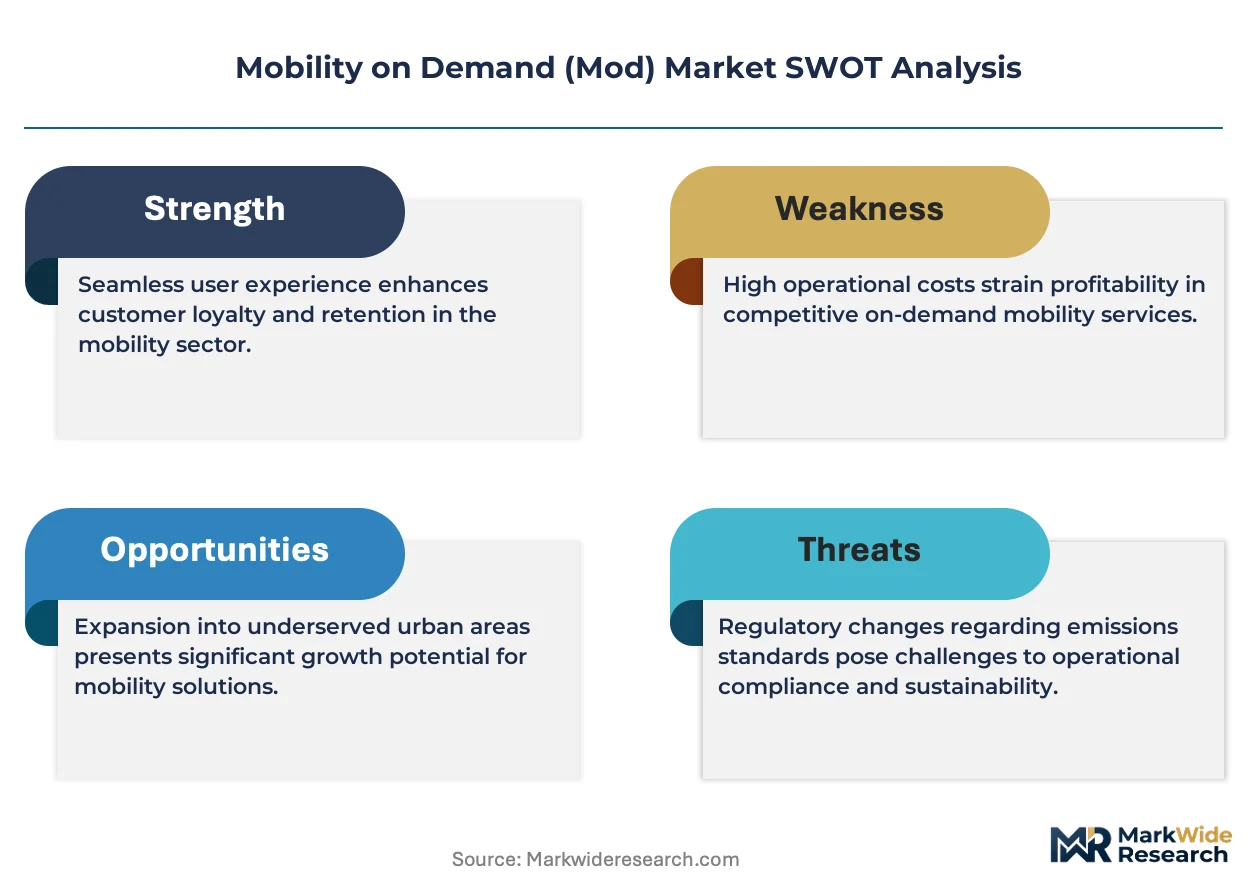
This market reads as a cost-of-compliance narrative where EU Green Deal fleet electrification mandates and India's data localization rules erect capital-intensive barriers that favor incumbent platforms with established regulatory affairs infrastructure and captive EV supply agreements.
For Market Incumbents: Anchor market position through exclusive battery supply partnerships with Korean and Chinese cell manufacturers securing preferential allocation during raw material crunches. Consolidate suburban shuttle networks in Brazilian secondary cities before regional specialists capture demand-responsive transit white space. Prioritize API connectivity investments to capture corporate travel manager procurement consolidation in North American and Western European SaaS platforms.
For New Entrants and Emerging Players: Launch via white-label dispatch infrastructure licensing to municipal transit authorities seeking algorithmic route optimization without proprietary platform development costs. Target demand-responsive shuttle services in Indian and Brazilian secondary cities where scheduled public transit reliability gaps persist. Embed financial services directly into mobility applications to replicate Southeast Asian super-app monetization models.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by automotive OEMs seeking fleet deployment channels and autonomous vehicle data generation partnerships. Long-term viability hinges on electrified fleet scale and regulatory compliance infrastructure rather than pure demand aggregation. Monitor California Air Resources Board zero-emission mandate phase-in deadlines as inflection signals for EV procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EV Fleet Procurement Acceleration | California Air Resources Board mandates compress ICE-to-EV transition timelines for compliance. |
| Suburban Shuttle Network Expansion | Secondary cities in Brazil and India present unserved demand-responsive transit white space. |
| Embedded Financial Services Integration | Southeast Asian super-app models demonstrate wallet and credit product monetization traction. |
| Autonomous Vehicle Middleware Licensing | Tier-one suppliers in Arizona and Texas pilot modular sensor fusion stacks for robo-taxi deployment. |
| Data Localization Architecture Duplication | India's motor vehicle aggregator guidelines force domestic server investments altering cost structures. |
Research Methodology
Independent corroboration across fleet operator procurement executives, municipal transit planning officers, and automotive OEM platform engineers underwrites the qualitative findings on electrification timelines and smart city integration patterns. Primary interviews with ride-hailing driver representatives and corporate travel managers in North American and Western European markets supplemented secondary validation from EPA emissions filings, EU Green Deal regulatory texts, and Indian Ministry of Road Transport aggregator guidelines. Bottom-up demand modeling across service type, technology stack, and customer segments triangulates against top-down market sizing from vehicle registration databases and platform disclosure aggregates.
Comparable-period anchoring to historical fleet deployment cycles and regulatory phase-in schedules shaped the projection horizon assumptions across the analysis window. Segmentation dimensions modeled include service type differentiation, cloud-native versus legacy dispatch architecture, and customer procurement behavior across individual, corporate, and institutional demand pools. CAGRs derive from vehicle utilization rate trajectories, driver supply elasticity estimates, and EV cost parity crossover analysis against internal combustion alternatives.
The model assumes a particular technology adoption path for autonomous vehicle middleware deployment; alternative pathways for sensor fusion standardization or regulatory permitting delays would alter the outlook. Forecasts reflect assumptions regarding lithium supply expansion, driver classification jurisprudence, and municipal lane allocation priorities. Material deviation in battery mineral pricing volatility or employment reclassification rulings warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Commercial Telematics Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
North America Commercial Vehicle Telematics Market
Telematics and Infotainment
North America Dashboard Camera Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
Roadside Assistance Software Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Automotive Data Monetization Market
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Motorcycle Infotainment System Market