
 Europe Adaptive Steering Market | 2026-2036
Europe Adaptive Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Adaptive Steering Market Foresight
OEM direct procurement channels is fragmenting as European automakers diversify supplier bases beyond legacy tier-one hierarchies. Robert Bosch GmbH leverages its integrated electronics manufacturing to sustain dominance in steer-by-wire control modules. ZF Friedrichshafen AG anchors its position through captive production of electric power steering racks for German premium brands. Nexteer Automotive competes by specializing in compact active steering systems for city-focused electric vehicle platforms.
Europe Adaptive Steering encompasses electromechanical systems that modulate steering ratio and assist torque based on vehicle speed, load, and lane position, typically integrating torque sensors with ECUs processing inputs at sub-50-millisecond intervals to optimize driver effort and vehicle stability. Electronic steering architectures now lead in new platform development, while hydraulic steering retains residual share in heavy commercial vehicles where power density requirements exceed electric actuator limits. Among applications, passenger vehicles occupy the broadest volume base, though performance cars command disproportionate margin pools due to calibration complexity and brand-specific tuning demands.
The EU AI Act and ECE R79 steering equipment regulations shape product certification pathways, with ECE R79 specifically governing automatic steering functions and lane-keeping performance thresholds for European type approval. REACH compliance on electronics materials and the EU Green Deal's embedded carbon reporting requirements add layer compliance costs that favor suppliers with in-house lifecycle assessment capabilities. Stakeholders must monitor how the EU's forthcoming software-defined vehicle standards reclassify steering control algorithms as safety-critical code subject to mandatory third-party audit.
Market Dynamics
Steer-by-wire architectures are displacing mechanical steering columns across European electric vehicle platforms, forcing suppliers to reengineer control software, sensor fusion, and fail-operational electronics for type approval under ECE R79.
Growth Catalysts
- EU Green Deal efficiency mandates:Embedded carbon reporting requirements for automotive supply chains accelerate procurement of lightweight electromechanical steering systems that reduce vehicle mass and improve energy efficiency ratings.
- Electric vehicle platform proliferation:Dedicated EV architectures from German, French, and Italian OEMs require active steering calibration for variable-ratio response at different speeds and load conditions.
- ECE R79 automatic steering provisions:Lane-keeping and hands-free driving thresholds in the updated regulation create certified demand for precision torque modulation and redundant actuator designs.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings in Chinese processing facilities compress margins on permanent-magnet electric power steering motors.
- Tier-one supplier concentration:Control module and rack-and-pinion production clusters in southern Germany create single-source vulnerability for French and Italian OEMs seeking dual sourcing.
- Hydraulic legacy in heavy commercial vehicles:Power density requirements for 40-tonne truck applications exceed current electric actuator thermal limits, preserving hydraulic share in vocational segments.
Strategic Opportunities
- Polish and Czech manufacturing corridors:Lower labor and facility costs in these EU member states attract steering component assembly for export to German OEM plants.
- Software-defined vehicle standards:Upcoming EU mandatory third-party audit requirements for safety-critical code create service revenue streams for cybersecurity-certified steering control suppliers.
- Active steering-city EV convergence:Compact urban electric platforms from French and Italian manufacturers demand specialized low-speed maneuverability systems with minimal packaging volume.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise for steering control systems concentrates in Stuttgart and Munich, creating recruitment bottlenecks for suppliers in peripheral regions.
- REACH electronics compliance timeline:Substance restriction updates from ECHA force reformulation of solder, coatings, and encapsulants with 18-month validation cycles for steering ECU production.
- Legacy hydraulic service integration:European commercial vehicle fleets require aftermarket support for existing hydraulic steering while OEMs transition to electromechanical architectures, straining distributor technical training capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Adaptive Steering Market |
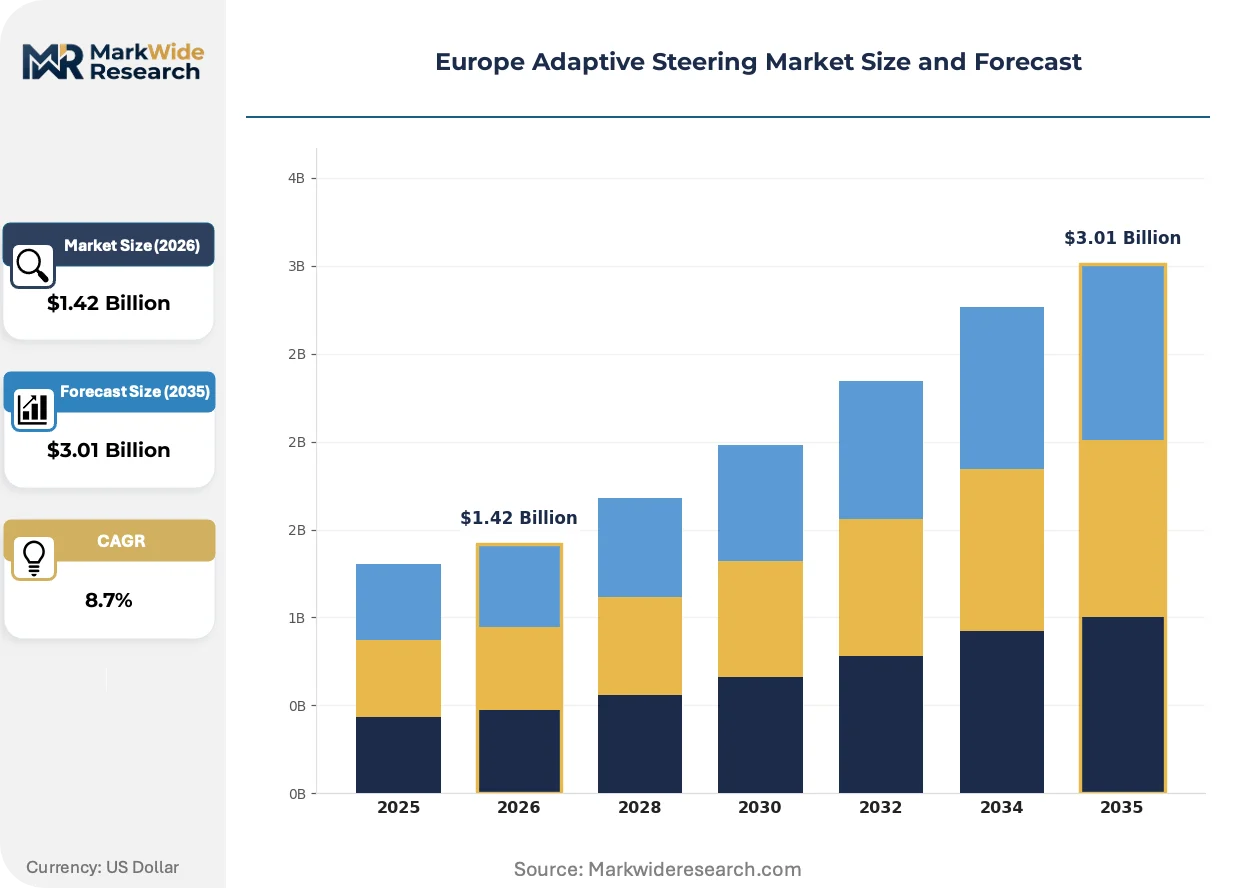
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Steering, Hydraulic Steering, Mechanical Steering, Power-Assisted Steering End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators Technology: Steer-by-Wire, Active Steering, Passive Steering, Semi-Automatic Steering Application: Passenger Vehicles, Commercial Vehicles, Luxury Vehicles, Performance Cars |
| Companies Covered | Robert Bosch GmbH, ZF Friedrichshafen AG, Thyssenkrupp AG, Ford Motor Company, Knorr-Bremse AG, Volvo Group, Nissan Motor Co., Ltd., BMW Group, Nexteer Automotive, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Adaptive Steering Market Shifts & Advancements
Control algorithm architectures are fragmenting as automakers internalize steering software development while outsourcing actuator hardware, creating new interface standards between OEM code bases and supplier mechatronics.
Steer-by-wire systems are hybridizing torque feedback generation with road surface estimation algorithms that synthesize haptic response from camera and radar inputs rather than mechanical column feedback. Premium German OEMs are deploying these configurations on flagship electric sedans ahead of mass-market rollout. This architecture is hybridizing the traditional boundary between chassis and ADAS engineering teams, forcing organizational restructuring at tier-one suppliers.
EU AI Act safety-critical system classifications are redefining steering control algorithms as high-risk AI requiring conformity assessment and post-market monitoring. The regulation mandates documentation of training data provenance and algorithmic decision logic for type approval. German KBA certification timelines have extended by four to six months for steer-by-wire platforms as auditors verify AI Act compliance alongside ECE R79 performance criteria.
Fleet procurement of steering systems is consolidating through direct OEM-supplier framework agreements that bypass traditional tier-two distributor networks. Large European rental and leasing groups now specify steering calibration parameters in vehicle configuration orders. This pattern is most visible in Germany's corporate fleet segment, where standardization across multi-brand vehicle pools reduces driver retraining costs and simplifies maintenance protocols.
Europe Adaptive Steering Market Segmentation
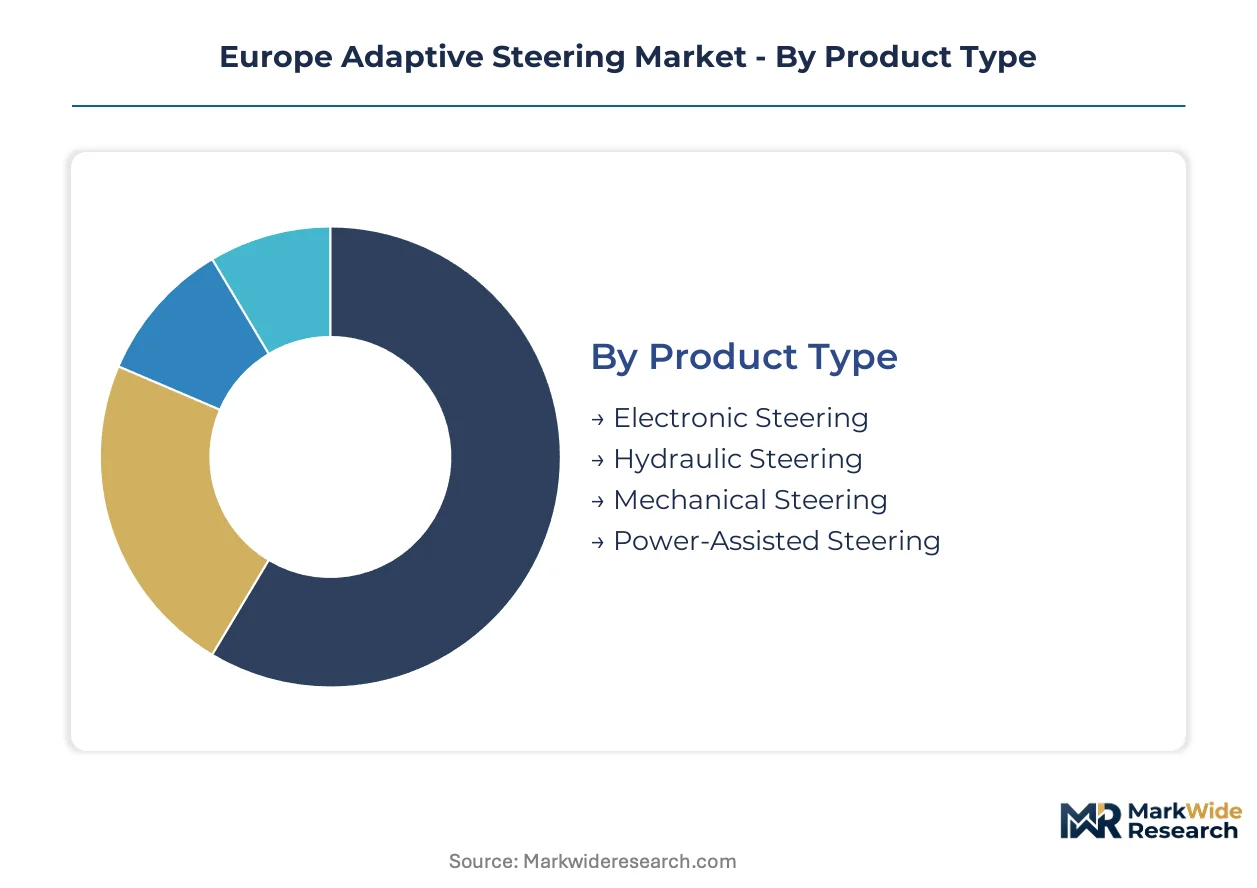
Adaptive steering procurement patterns diverge sharply across product architectures and customer channels. Segment-level analysis reveals where tier-one suppliers concentrate engineering resources versus where price competition dominates.
Product Type:
Electronic steering systems turn over fastest on new EV platform launches, while hydraulic architectures persist longest in heavy commercial vehicle refresh cycles.
- Electronic Steering:Torque-vectoring ECUs process lane-keeping inputs at sub-50-millisecond latency for German premium EV platforms. Demand concentrates in Stuttgart and Munich manufacturing corridors where OEMs specify integrated steer-by-wire modules for type approval under ECE R79.
- Hydraulic Steering:High-pressure servo systems deliver 200+ bar actuation force for 40-tonne truck applications where electric motor thermal limits constrain performance. French and Italian commercial vehicle builders retain hydraulic specifications for vocational segments with extreme load duty cycles.
- Mechanical Steering:Column-and-rack assemblies without power assistance persist in Eastern European budget vehicle production.
- Power-Assisted Steering:Conventional electric power steering racks serve mid-market vehicle platforms with fixed-ratio calibration.
Electronic steering anchors the volume base while hydraulic steering retains share in commercial applications with the slowest replacement trajectory.
End User:
Procurement authority concentrates differently across direct OEM channels versus fragmented aftermarket distribution.
- OEMs:German premium brands specify steer-by-wire control modules through direct framework agreements with Robert Bosch GmbH and ZF Friedrichshafen AG, bypassing tier-two distributors. ECE R79 type approval requirements force early-stage supplier integration into platform development cycles.
- Fleet Operators:Large European rental and leasing groups now embed steering calibration parameters in vehicle configuration orders to standardize driver experience across multi-brand pools. Corporate fleet procurement in Germany drives volume consolidation through direct OEM-supplier agreements.
- Aftermarket Providers:Independent distributors serve hydraulic steering rebuild demand from aging commercial vehicle fleets.
- Dealerships:Authorized service networks handle warranty repairs and software updates for electronic steering ECUs.
OEMs dominate absolute volume while fleet operators expand procurement influence fastest through direct supplier negotiations.
Technology:
Development cycle intensity varies from steer-by-wire's multi-year certification timelines to passive steering's minimal software validation burden.
- Steer-by-Wire:Redundant actuator architectures with fail-operational electronics require ISO 26262 ASIL-D certification and EU AI Act conformity assessment for high-risk AI classification. German KBA certification timelines have extended four to six months as auditors verify algorithmic decision logic documentation.
- Active Steering:Variable-ratio systems modulate steering response based on vehicle speed and load conditions for French and Italian urban EV platforms. Compact packaging requirements for city-focused electric vehicles drive specialized low-speed maneuverability development.
- Passive Steering:Fixed-ratio mechanical systems without electronic modulation serve cost-sensitive vehicle segments.
- Semi-Automatic Steering:Lane-keeping assist functions operate within ECE R79 hands-free driving thresholds with driver monitoring override requirements.
Steer-by-wire anchors technology investment while active steering climbs fastest on city EV platform proliferation.
Application:
Margin structure inverts across volume-driven passenger segments versus calibration-intensive performance specialization.
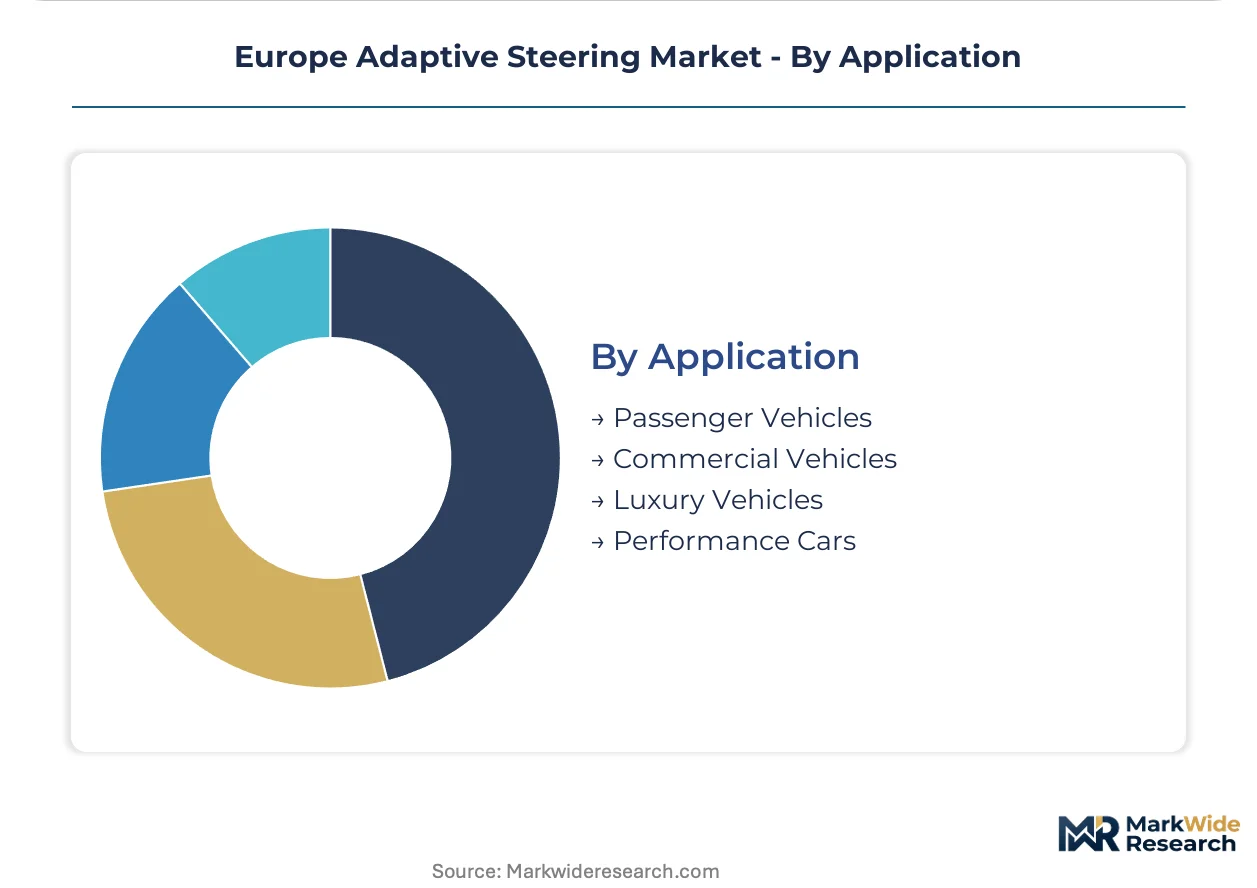
- Passenger Vehicles:Broadest volume base spans mass-market electric platforms from German, French, and Italian OEMs with standardized steering rack specifications. EU Green Deal efficiency mandates accelerate lightweight electromechanical system procurement across high-volume production lines.
- Performance Cars:Brand-specific tuning demands and track-calibrated torque modulation command disproportionate margin pools. Calibration complexity for Nürburgring-optimized response curves requires dedicated engineering teams at tier-one suppliers.
- Commercial Vehicles:40-tonne truck applications preserve hydraulic share where power density exceeds electric actuator limits.
- Luxury Vehicles:Flagship German electric sedans deploy hybridized torque feedback with road surface estimation algorithms synthesizing haptic response from camera and radar inputs.
Passenger vehicles anchor the volume base while performance cars expand at the steepest margin premium trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central European automotive logistics, enabling just-in-time component delivery from Bavarian steering module plants to assembly lines across the continent.
Germany
Premium OEM steer-by-wire procurement from Robert Bosch GmbH and ZF Friedrichshafen AG concentrates in Stuttgart and Munich manufacturing corridors. KBA certification timelines under ECE R79 and EU AI Act conformity assessment extend type approval cycles by four to six months. The Baden-Württemberg supplier cluster co-locates control module production with Mercedes-Benz and Porsche assembly plants.
France
Urban EV platform demand from Renault and Stellantis drives active steering development for compact city maneuverability systems. ANSM technical standards alignment with EU vehicle safety frameworks shapes product validation pathways. The Île-de-France automotive engineering base around Paris hosts calibration teams for variable-ratio response tuning.
Italy
Fiat and Lamborghini procurement specifications split between mass-market electric platforms and performance car torque modulation. ECE R79 lane-keeping thresholds apply to semi-automatic steering functions in luxury vehicle segments. The Emilia-Romagna motor valley around Modena anchors high-performance steering rack development for track-calibrated applications.
Poland
Lower labor and facility costs attract steering component assembly operations serving German OEM export demand. EU Green Deal embedded carbon reporting requirements favor Polish manufacturing for lightweight electromechanical system production. The Silesian automotive corridor near Katowice hosts tier-two suppliers producing rack-and-pinion subassemblies.
United Kingdom
Jaguar Land Rover and Bentley procurement maintains specialized calibration requirements for luxury vehicle haptic feedback systems. DVSA type approval processes run parallel to ECE R79 certification for vehicles exported to EU markets. The West Midlands manufacturing cluster around Birmingham retains steering system integration capacity despite post-Brexit supply chain adjustments.
Europe Adaptive Steering Market Competitive Landscape
On the supply side, the industry is consolidating around integrated electronics manufacturers with captive mechatronics capabilities. Tier-one suppliers with in-house ECU production dominate steer-by-wire procurement channels, while specialized actuator fabricators occupy niche urban EV segments. Two strategic archetypes prevail: diversified industrial conglomerates with chassis system portfolios, and steering-focused specialists with compact platform expertise. Competitive moves center on fail-operational electronics certification and software-defined vehicle code audit preparation.
Within the diversified industrial tier, Robert Bosch GmbH and ZF Friedrichshafen AG occupy positions as integrated control module suppliers, while Nexteer Automotive represents the specialist archetype focused on compact active steering systems. Bosch leverages its Stuttgart-based electronics manufacturing footprint to anchor steer-by-wire development for German premium OEMs. ZF Friedrichshafen AG exemplifies the captive production model through its Friedrichshafen headquarters and proximity to Lake Constance automotive clusters. Nexteer Automotive, despite its North American origins, competes in European city EV procurement through specialized low-speed maneuverability architectures.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Thyssenkrupp AG |
| Ford Motor Company |
| Knorr-Bremse AG |
| Volvo Group |
| Nissan Motor Co., Ltd. |
| BMW Group |
| Nexteer Automotive |
| Others |
Supply & Pricing Matrix
The Baden-Württemberg supplier cluster around Stuttgart concentrates steer-by-wire module production capacity, giving tier-one suppliers pricing leverage over French and Italian OEMs seeking dual-source alternatives. Control module fabrication co-located with Mercedes-Benz and Porsche assembly plants enables just-in-time delivery premiums that downstream buyers absorb through long-term framework agreements.
Pricing Analysis
Volume-discount tiering structures separate German premium OEM direct procurement from mid-market fleet aggregation channels. Pricing stratifies across ASIL-D certified steer-by-wire systems, standard electric power steering racks, and residual hydraulic architectures for commercial vehicles. Cost compression in permanent-magnet electric motors is intensifying because Chinese rare earth processing volatility feeds through to actuator bill-of-materials. Fleet operators exhibit highest price sensitivity through consolidated multi-brand standardization mandates, while performance car divisions tolerate premium calibration charges for Nürburgring-optimized response curves.
Supply Chain Analysis
Neodymium and dysprosium feedstock from Chinese separation facilities anchors permanent-magnet motor production, while ECU semiconductor wafer supply concentrates in Taiwan and South Korea. Aluminum die-cast housings and torque sensor subassemblies draw from Czech and Polish manufacturing corridors serving German OEM export demand. Single-source vulnerability in southern Germany control module production creates structural risk for French and Italian automakers. Distribution runs through direct OEM-supplier framework agreements that bypass traditional tier-two distributor networks for electronic steering platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as steer-by-wire architectures displace mechanical steering columns across European electric vehicle platforms, threatening legacy hydraulic component revenues.
For Market Incumbents: Pre-empt margin erosion in hydraulic steering by accelerating ASIL-D certification investment for fail-operational steer-by-wire electronics. Captive production of torque-vectoring ECUs in Baden-Württemberg defends pricing power against Polish and Czech assembly competitors. Backward integration into rare earth magnet recycling hedges Chinese feedstock volatility.
For New Entrants and Emerging Players: Compact urban electric platforms from French and Italian manufacturers represent the most penetrable entry point for specialized low-speed maneuverability systems. Polish and Czech manufacturing corridors offer facility cost advantages for rack-and-pinion subassembly production serving German OEM export demand. Direct fleet procurement channels bypass entrenched tier-one hierarchies for volume consolidation.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EU AI Act conformity assessment and ECE R79 certification timelines create moats around approved steering control suppliers. Acquisition targets should exhibit in-house ISO 26262 functional safety engineering and software-defined vehicle code audit readiness. Watch KBA certification timeline extensions as the inflection signal for supply-constrained premium platform allocations.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Fail-operational electronics approval under ISO 26262 unlocks German premium OEM steer-by-wire procurement. |
| Software-Defined Vehicle Code Audit Preparation | EU AI Act third-party audit readiness creates service revenue streams for cybersecurity-certified control suppliers. |
| Polish Manufacturing Footprint Expansion | Lower labor costs in Silesian corridors attract steering component assembly for German OEM export demand. |
| Rare Earth Magnet Recycling Integration | In-house material recovery hedges Chinese neodymium and dysprosium price volatility for electric power steering motors. |
| Fleet Direct Procurement Channel Development | Corporate fleet standardization mandates bypass tier-two distributors for volume aggregation across multi-brand vehicle pools. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and dealership service operations anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through ECE R79 type approval documentation, EU AI Act regulatory filings, vehicle production databases, and IHS Markit registration data. Bottom-up segment modeling triangulated against top-down market sizing across electronic, hydraulic, and mechanical steering architectures.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling spanning vehicle class, propulsion architecture, steering technology tier, and regional production cluster. CAGRs derived from production volume trajectories weighted by content-per-vehicle assumptions for steer-by-wire versus conventional electric power steering. Forecast inputs incorporated EU Green Deal efficiency mandate compliance timelines and ECHA REACH substance restriction update cycles.
Macroeconomic conditions sit as an overlay; deviation in rare earth commodity prices, semiconductor foundry capacity allocation, or KBA certification staffing levels would shift the trajectory. Forecasts reflect documented assumptions on EV platform launch schedules and regulatory implementation timelines. Cross-checking against vehicle registration data and tier-one supplier order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
China Airbag Systems Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market
Automotive Safety and Security Systems
Vehicle Anti-Theft System Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
Automotive Friction Brake System Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market