
 Commercial Vehicle Switches and Relays Market | 2026-2036
Commercial Vehicle Switches and Relays Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicle Switches and Relays Market Outlook
A widening capability gap between vertically integrated suppliers and component assemblers is reorganizing competitive tiers in this market. TE Connectivity leverages its sensor-to-switch integration to command premium positioning in engine management applications. Robert Bosch GmbH anchors its presence through captive semiconductor sourcing for solid-state relay production. Denso Corporation differentiates via thermal management expertise that extends relay life cycles under severe-duty cycles.
Commercial vehicle switches and relays are electromechanical or solid-state devices engineered to interrupt or route electrical current between 12V and 48V architectures, with contact ratings typically spanning 10A to 200A depending on load type. These components manage power distribution, signal routing, and safety interlocks across heavy-duty electrical systems operating in vibration-intensive environments. Relays dominate volume shipments due to their ubiquity in power distribution and engine management circuits, though solid-state variants are capturing margin pools as thermal performance improves. Smart switches represent the fastest-expanding technology segment, embedding diagnostics and CAN bus communication that reduce wiring harness complexity. Aftermarket channels sustain steady demand as fleet operators prioritize uptime through preventive replacement programs.
NHTSA, EPA, and ISO 26262 collectively shape product validation requirements, with functional safety standards mandating redundant switching architectures in autonomous-ready commercial platforms. The EPA's Phase 3 greenhouse gas rules are accelerating 48V mild-hybrid adoption, forcing relay suppliers to redesign contact materials for higher arc suppression tolerance. Stakeholders must monitor how solid-state displacement timelines intersect with fleet replacement cycles to calibrate capacity investments and technology roadmaps.
Market Dynamics
The transition from 12V to 48V electrical architectures in heavy-duty commercial platforms is forcing wholesale redesigns of switching and relay specifications, compressing supplier development cycles while expanding thermal management requirements.
Growth Catalysts
- EPA Phase 3 Greenhouse Gas Rules:US federal mandates for 48V mild-hybrid powertrains are expanding contact material specifications and arc suppression tolerances across relay portfolios.
- Telematics Integration:Smart switches embedding CAN bus diagnostics are reducing wiring harness complexity for fleet operators managing electrified vehicle platforms.
- Aftermarket Preventive Replacement:US-based fleet maintenance programs are standardizing relay replacement intervals to minimize unplanned downtime in long-haul operations.
Market Restraints
- Copper and Silver Contact Volatility:Precious metal price swings in commodity markets are compressing margin structures for electromechanical relay manufacturers.
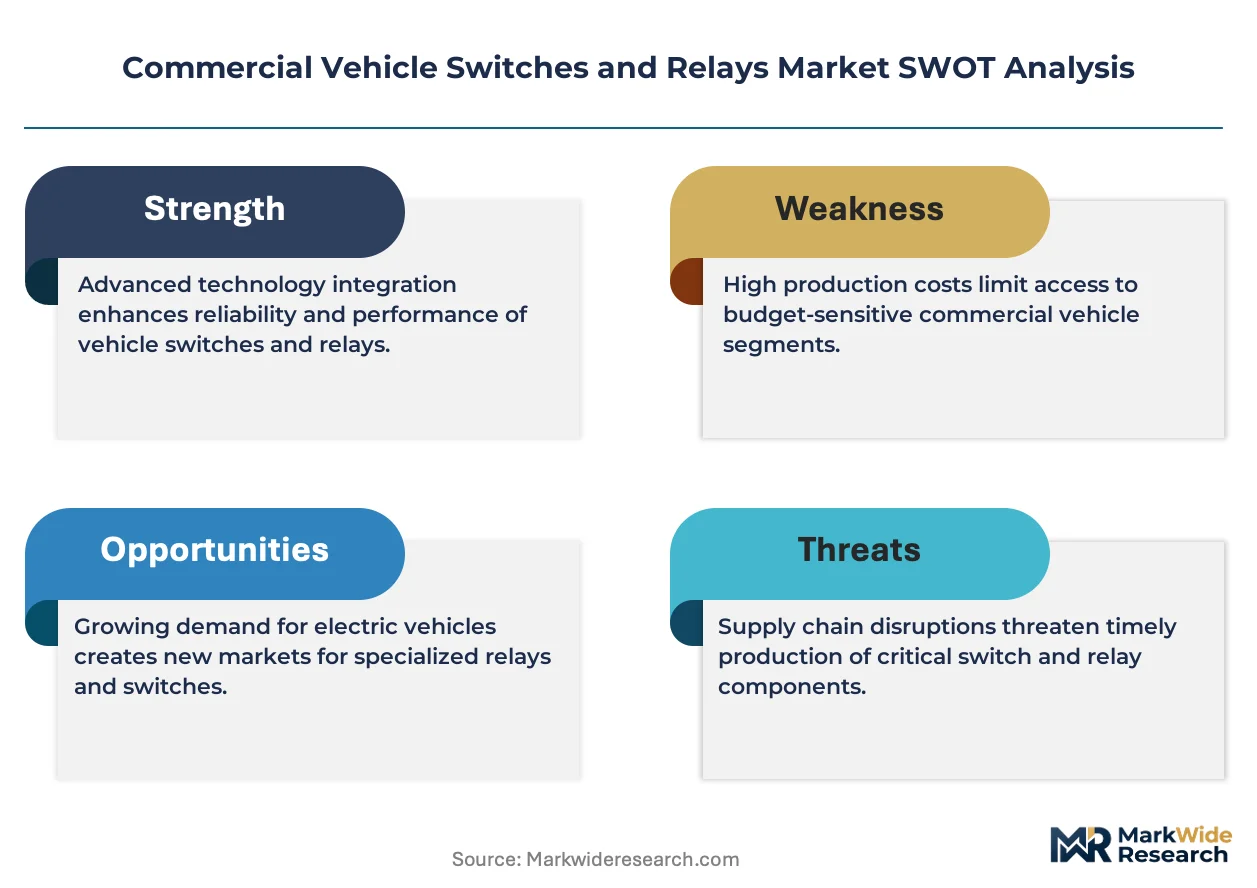
- Semiconductor Supply Concentration:Captive silicon sourcing by integrated tier-one suppliers limits independent relay producers' access to solid-state switching components.
- Functional Safety Certification Burden:ISO 26262 ASIL-D compliance timelines for autonomous-ready platforms are extending product validation cycles beyond 24 months.
Strategic Opportunities
- India Commercial Vehicle Electrification:BIS standards adoption for 48V architectures creates entry points for suppliers with thermal management expertise in severe-duty applications.
- Predictive Maintenance Platforms:Smart switch diagnostic data streams are enabling subscription-based fleet uptime services that unbundle hardware from software revenue.
- EU Green Deal Commercial Fleet Mandates:CSRD-aligned procurement requirements are favoring suppliers with verified lifecycle carbon data for switching components.
Industry Challenges
- Embedded Systems Engineering Talent:Shortages of firmware developers with automotive functional safety experience are delaying smart switch program launches.
- Legacy 12V Integration Complexity:Dual-architecture platforms require relay suppliers to maintain parallel production lines while managing 48V transition tooling investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicle Switches and Relays Market |
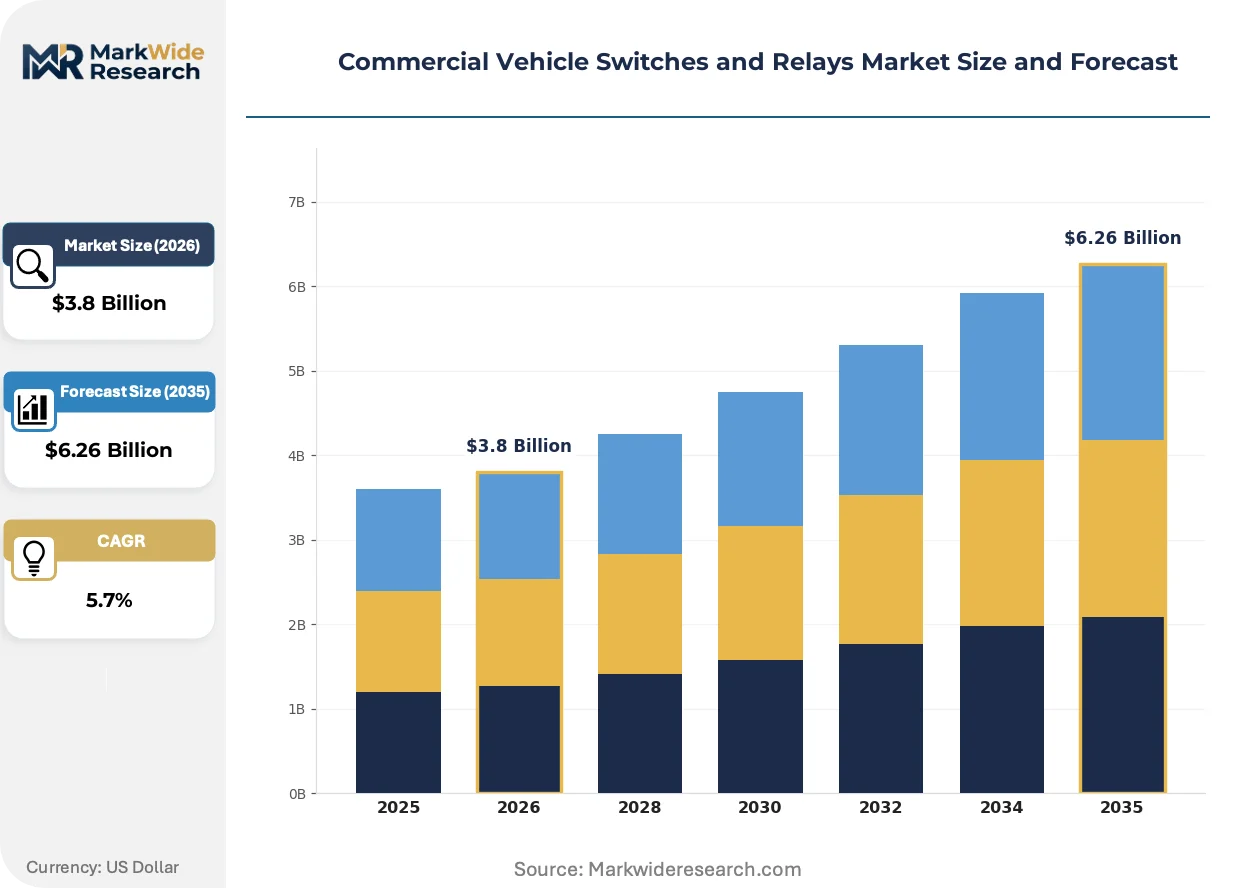
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toggle Switches, Rocker Switches, Push Button Switches, Relays Technology: Electromechanical, Solid State, Embedded Systems, Smart Switches End User: Fleet Operators, OEMs, Aftermarket, Service Centers Application: Lighting Control, Engine Management, Power Distribution, Accessory Control |
| Companies Covered | Omron Corporation, Fujitsu Ltd., TE Connectivity, Eaton Corporation, Denso Corporation, Robert Bosch GmbH, Littelfuse Inc., Mitsubishi Electric, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicle Switches and Relays Market Strategic Shifts
Solid-state switching technologies are compressing traditional electromechanical relay applications while regulatory pressure on vehicle electrification accelerates specification changes across supplier portfolios.
Silicon carbide MOSFET-based solid-state relays are displacing electromechanical contactors in high-current battery management systems for electric commercial vehicles. Tier-one powertrain integrators in the United States are specifying these components for 200A+ traction battery disconnect circuits. This displacement is eliminating mechanical wear points while forcing incumbent relay suppliers to restructure R&D spending toward semiconductor packaging expertise.
REACH substance restrictions on hexavalent chromium coatings are compelling European relay manufacturers to redesign contact plating chemistries for corrosion resistance. The ECHA authorization timeline is compressing supplier qualification windows for alternative surface treatments. German commercial vehicle producers are accelerating validation of tin-silver-copper contact alloys to maintain supply continuity.
Fleet operators are consolidating switch and relay procurement through integrated vehicle lifecycle contracts rather than discrete component purchasing. This consolidation is disintermediating traditional aftermarket distributors in favor of direct supplier-fleet data partnerships. The pattern is most pronounced among US-based Class 8 truck operators with centralized maintenance management systems.
Commercial Vehicle Switches and Relays Market Segmentation
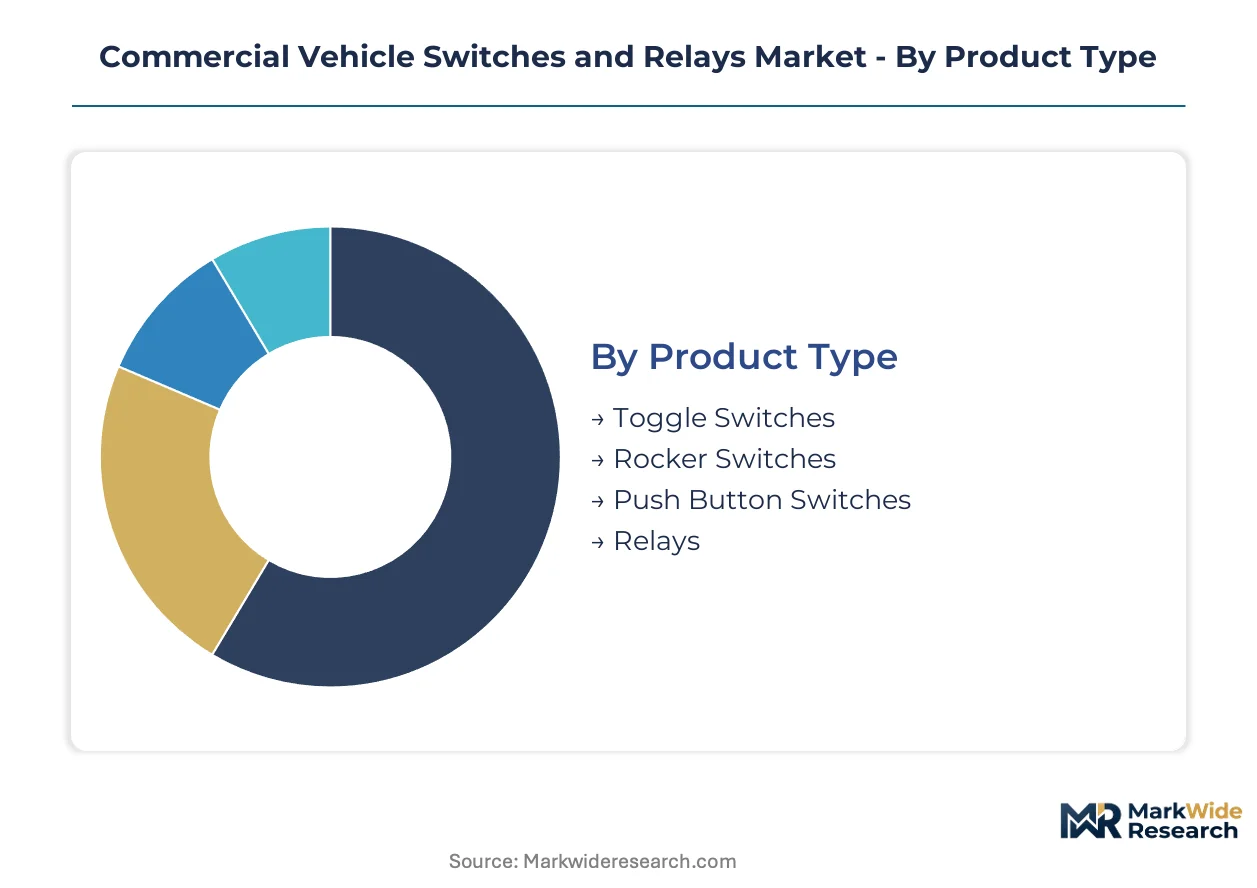
Segmentation in the commercial vehicle switches and relays market reveals how electrification pressures are fragmenting demand across incompatible voltage architectures. Fleet procurement patterns and regulatory mandates are concentrating volume in specific product categories while accelerating obsolescence in legacy segments.
Product Type:
Relays face the most acute substitution pressure as solid-state alternatives capture high-current battery management applications, while mechanical switches retain defensible positions in cost-sensitive auxiliary circuits.
- Relays:Electromechanical contactors rated 10A to 200A dominate power distribution and engine management circuits across heavy-duty platforms. Fleet operators in the United States are standardizing preventive replacement intervals for these components to minimize unplanned downtime in long-haul operations.
- Push Button Switches:Momentary and latching configurations with sealed IP ratings serve cab interface and emergency shutdown functions. Demand concentrates in OEM specifications for autonomous-ready platforms where ISO 26262 compliance mandates redundant switching architectures.
- Toggle Switches:Lever-actuated mechanisms with mechanical detents persist in accessory control and auxiliary power circuits where cost minimization overrides diagnostic requirements.
- Rocker Switches:Snap-in panel mount designs with illuminated legends address lighting control and HVAC interface applications in commercial vehicle cabs.
Relays anchor the volume base while push button switches gain share at the steepest rate.
Technology:
Cost tier stratification separates premium semiconductor-based solutions from commodity electromechanical alternatives, with mid-range embedded systems capturing fleet telematics integration demand.
- Solid State:Silicon carbide MOSFET-based relays eliminate mechanical wear in 200A+ traction battery disconnect circuits for electric commercial vehicles. EPA Phase 3 greenhouse gas rules are accelerating 48V mild-hybrid adoption, forcing contact material redesigns for higher arc suppression tolerance.
- Smart Switches:CAN bus-embedded diagnostics reduce wiring harness complexity and enable predictive maintenance data streams. Fleet operators managing electrified platforms in the United States are consolidating procurement through integrated lifecycle contracts favoring these components.
- Electromechanical:Traditional relay architectures with silver-alloy contacts persist in 12V legacy systems and price-sensitive aftermarket replacement.
- Embedded Systems:Microcontroller-integrated switching modules bridge electromechanical reliability with digital communication protocols for mid-tier commercial platforms.
Electromechanical technology retains the largest installed base while smart switches climb the fastest.
End User:
Customer type determines specification authority, with OEMs driving technology roadmaps and fleet operators controlling aftermarket replacement velocity through centralized maintenance programs.
- Fleet Operators:Centralized procurement departments at US-based Class 8 truck operators are disintermediating traditional distributors through direct supplier data partnerships. These stakeholders prioritize uptime metrics over component cost in switching system selection.
- OEMs:Powertrain integrators specify solid-state components for autonomous-ready platforms requiring ASIL-D functional safety compliance. NHTSA mandates are extending their validation cycles beyond 24 months.
- Aftermarket:Independent distributors serve preventive replacement demand from regional operators without centralized maintenance management systems.
- Service Centers:Authorized repair facilities handle warranty-related switching component replacements for electrified platforms requiring specialized diagnostic equipment.
Fleet operators command the highest value per socket while OEMs set the technology trajectory.
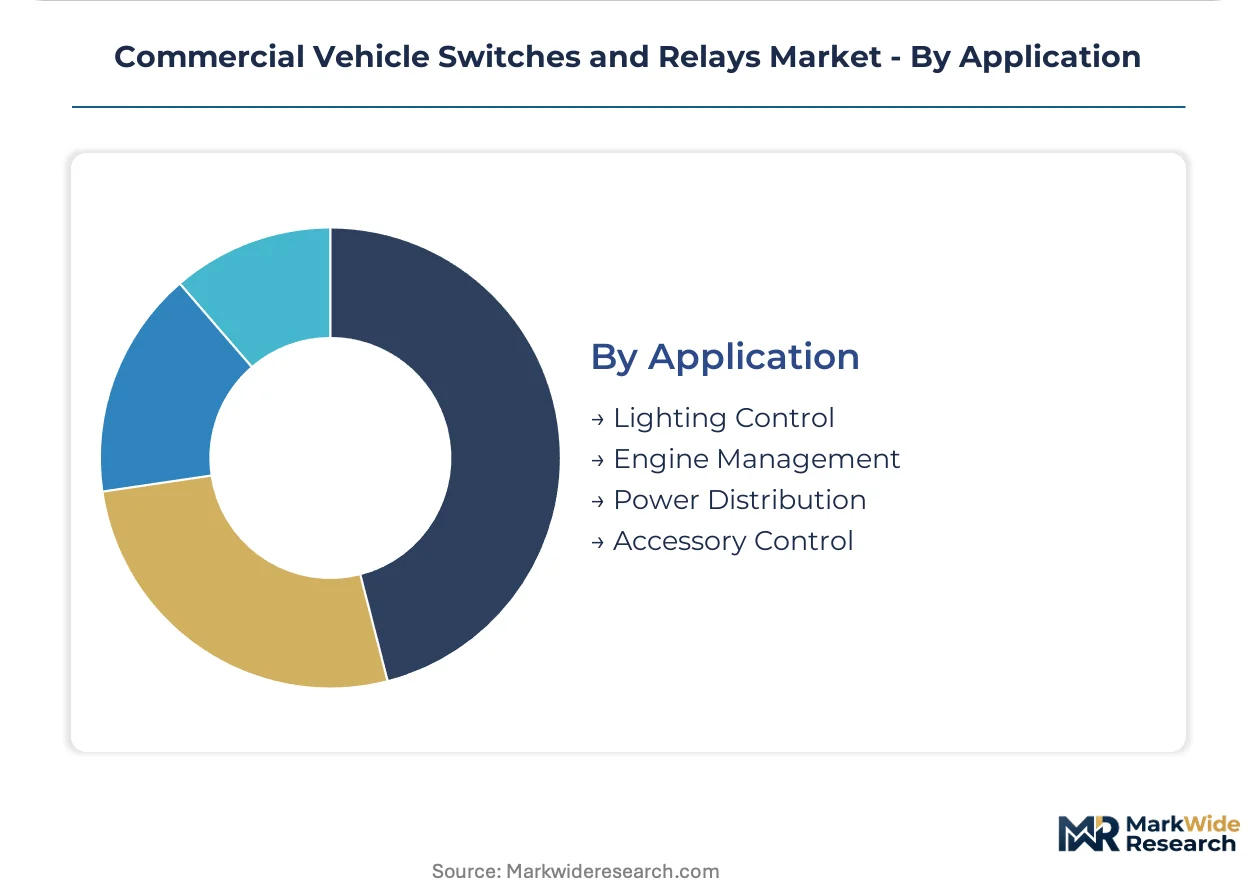
Application:
Maturity gradients separate established lighting and accessory control functions from emerging power distribution architectures reshaping relay specifications.
- Power Distribution:High-current bus management in 48V mild-hybrid and full-electric platforms demands solid-state switching with integrated thermal protection. The transition from 12V architectures is compressing supplier development cycles while expanding semiconductor packaging requirements.
- Engine Management:Sensor-to-switch integration in powertrain control modules commands premium positioning as electrified powertrains require more sophisticated control architectures.
- Lighting Control:Sealed rocker and push button switches address exterior and interior illumination circuits with established reliability requirements.
- Accessory Control:Low-current switching for HVAC, infotainment, and comfort systems in commercial vehicle cabs.
Lighting control provides the most stable demand while power distribution shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German relay manufacturers commanding premium positioning for ASIL-D certified components, while Chinese suppliers compete on volume for 12V aftermarket replacement. Electrification mandates are fragmenting regional demand across incompatible voltage architectures.
United States
EPA Phase 3 greenhouse gas rules are accelerating 48V mild-hybrid adoption across Class 8 truck platforms. NHTSA safety mandates require redundant switching architectures for autonomous-ready commercial vehicles. Detroit-Warren-Dearborn anchors production concentration where powertrain integrators specify solid-state components for battery management systems.
Germany
REACH substance restrictions on hexavalent chromium coatings are compressing supplier qualification windows for alternative contact plating chemistries. KBA type-approval processes extend validation timelines for functional safety compliance. Stuttgart and Munich industrial clusters host relay manufacturers redesigning tin-silver-copper alloys for corrosion resistance.
China
GB standards adoption for commercial vehicle electrification is expanding domestic demand for high-current solid-state switching. MIIT new energy vehicle mandates prioritize local sourcing of power distribution components. Yangtze River Delta manufacturing hubs concentrate capacity for silicon carbide MOSFET packaging.
India
BIS standards for 48V architectures create entry points for suppliers with thermal management expertise in severe-duty applications. PLI scheme incentives favor domestic assembly of automotive electrical components. Tamil Nadu and Maharashtra industrial corridors attract relay producers targeting electrified bus and truck platforms.
Japan
METI carbon neutrality roadmaps drive fleet electrification timelines for commercial vehicle operators. JIS standards govern reliability testing for switching components in vibration-intensive environments. Nagoya and Osaka manufacturing belts specialize in sensor-to-switch integration for powertrain control modules.
Commercial Vehicle Switches and Relays Market Competitive Environment
Concentration sits with diversified electrical component conglomerates that command semiconductor sourcing advantages for solid-state relay production. The vendor base spans three tiers: integrated tier-one suppliers with captive silicon access, specialized relay manufacturers with thermal management expertise, and regional assemblers serving price-sensitive aftermarket channels. Dominant competitive moves include backward integration into semiconductor packaging and strategic partnerships with powertrain integrators for 48V platform qualification.
Within the integrated tier-one archetype, TE Connectivity, Robert Bosch GmbH, and Denso Corporation exemplify the sensor-to-switch integration and captive semiconductor sourcing that commands premium positioning in engine management and battery disconnect applications. These entities anchor the competitive structure through functional safety certification depth and direct fleet operator data partnerships.
| Leading Market Players |
|---|
| Omron Corporation |
| Fujitsu Ltd. |
| TE Connectivity |
| Eaton Corporation |
| Denso Corporation |
| Robert Bosch GmbH |
| Littelfuse Inc. |
| Mitsubishi Electric |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between US-based Class 8 fleet operators and tier-one relay suppliers lock in semiconductor allocation priority while fixing contact material costs against copper and silver volatility. These agreements bundle preventive replacement schedules with telemetry-enabled diagnostics, converting transactional component sales into subscription-based uptime guarantees that stabilize revenue visibility across electrification transitions.
Pricing Analysis
Configured-to-order pricing for ASIL-D certified smart switches commands substantial premiums over standard electromechanical relay catalogs. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262 functional safety tiers from commodity aftermarket replacements. Price differentiation hinges on embedded firmware complexity and thermal management certification grade. Cost compression in the electromechanical tier is intensifying because REACH substance restrictions force contact plating chemistry redesigns. Regional operators without centralized maintenance systems exhibit highest price sensitivity, while national fleet accounts prioritize uptime metrics over unit economics.
Supply Chain Analysis
Strategic stockpiling of silver-alloy contact materials and silicon carbide substrates dominates inventory strategy over just-in-time approaches given EPA Phase 3 regulatory uncertainty. Manufacturing concentration centers on Germany, China, and the United States for final relay assembly, with semiconductor packaging capacity concentrated in Taiwan and South Korea. Raw material flows draw from Chilean copper mines, Mexican silver refineries, and Japanese silicon carbide wafer production. Single-source vulnerability in silicon carbide MOSFET sourcing poses structural risk as captive production by integrated tier-one suppliers limits independent access. Distribution runs through direct supplier-fleet partnerships that disintermediate traditional aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against silicon carbide solid-state relays displacing electromechanical contactors in high-current battery management applications. Incumbents must navigate semiconductor packaging expertise gaps while preserving electromechanical revenue in auxiliary circuits.
For Market Incumbents: Shield core electromechanical revenue in 12V legacy systems and auxiliary power circuits where cost minimization overrides diagnostic requirements. Accelerate backward integration into silicon carbide packaging capabilities to capture solid-state displacement in 200A+ traction battery disconnect circuits. Prioritize captive semiconductor sourcing agreements with Taiwanese foundries to secure MOSFET allocation priority against integrated tier-one competitors.
For New Entrants and Emerging Players: Differentiate on thermal management expertise for severe-duty applications in India's electrified bus and truck platforms where BIS standards adoption creates qualification windows. Target fleet operator data partnerships in the United States as the most penetrable channel, bypassing traditional aftermarket distributors through direct lifecycle contracts. Pursue go-to-market angles anchored to predictive maintenance platform integration rather than discrete hardware sales.
For Investors and Strategic Acquirers: Specialized relay manufacturers with functional safety certification depth and existing direct fleet relationships represent the most attractive acquisition archetype for solid-state transition strategies. Long-term viability hinges on 48V platform qualification timelines intersecting with fleet replacement cycles. Watch silicon carbide cost curves as the inflection indicator triggering accelerated electromechanical displacement in power distribution applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Packaging Integration | Captive silicon carbide MOSFET sourcing secures solid-state relay capacity against tier-one supplier lockout. |
| Functional Safety Certification Investment | ISO 26262 ASIL-D compliance enables specification into autonomous-ready commercial vehicle platforms. |
| Direct Fleet Data Partnership | Bypassing aftermarket distributors captures lifetime value through subscription-based uptime services. |
| Thermal Management R&D Expansion | Contact material redesign for 48V arc suppression tolerance addresses EPA Phase 3 mandate requirements. |
| India Manufacturing Footprint | PLI scheme incentives and BIS standards alignment position for electrified commercial vehicle demand. |
Study Parameters
The analysis maps electromechanical relay, solid-state switching, and smart switch sub-sectors, each validated through procurement directors at US-based Class 8 fleet operators, tier-one powertrain integration engineers, and aftermarket distribution channel managers. Primary interview insights triangulate against vehicle production databases, EPA regulatory filings, NHTSA safety mandate documentation, and customs trade records for copper and silver contact materials. Bottom-up component shipment estimates reconcile with top-down commercial vehicle production forecasts across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including IHS Markit vehicle registration data and semiconductor packaging capacity disclosures. The analytical framework models product type, technology tier, end-user archetype, and application segment dimensions throughout the forecast period. CAGRs derive from regression analysis of historical shipment patterns and electrification adoption curves, with specific inputs including 48V mild-hybrid penetration rates and fleet preventive replacement interval standardization.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Phase 3 enforcement and stable copper-silver commodity price bands; material deviation would warrant model refresh. Forecasts reflect base-case electrification timelines and functional safety certification throughput capacity. Revision becomes warranted when silicon carbide cost reduction curves accelerate solid-state displacement beyond modeled electromechanical obsolescence schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Switchrack Assemblies Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
Europe Electric Power Steering Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
Germany X by Wire Systems Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Global Automotive on Board Power Inverter Market