
 Steering Wheel Switches Market | 2026-2036
Steering Wheel Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Steering Wheel Switches Market Analysis
The divergence between premium capacitive interfaces and commodity mechanical switches is realigning procurement strategies across automotive tiers. Tokai Rika Co., Ltd. leverages its heritage in precision haptic feedback systems to anchor the Japanese OEM supply base. Valeo SA competes through integrated cockpit electronics that extend beyond discrete switch components into full human-machine interface modules.
Steering wheel switches are electromechanical or capacitive control interfaces mounted on steering wheel spokes, typically rated for actuation cycles exceeding one million operations and operating temperatures from minus forty to plus eighty-five degrees Celsius, enabling driver command inputs without hand displacement from the steering rim. Multifunction switches dominate value pools as they consolidate audio, telephony, and driver-assistance controls into single modules, while capacitive technology leads growth trajectories due to its seamless surface integration and programmable gesture recognition. Mechanical switches retain cost-sensitive volume in emerging-market vehicle platforms where tooling amortization favors proven contact architectures.
NHTSA guidelines on driver distraction, ECE R79 regulations on steering equipment, and ISO 26262 functional-safety standards collectively mandate shorter driver eye-off-road times and validated fail-operational behavior for steering-mounted controls. These frameworks elevate engineering barriers for new entrants while rewarding incumbents with certified development processes and established OEM validation relationships. Stakeholders must monitor how software-defined vehicle architectures migrate switch logic into domain controllers, potentially decoupling physical interfaces from electronic control units and redistributing value toward firmware suppliers.
Market Dynamics
The migration of switch logic into software-defined vehicle architectures is fragmenting traditional tier-1 supplier roles while elevating firmware developers and domain controller specialists into critical procurement decisions.
Growth Catalysts
- Capacitive Touch Interfaces:Luxury vehicle platforms in Germany's Stuttgart-Ingolstadt corridor are standardizing seamless surface integration with programmable gesture recognition, creating premium value pools beyond mechanical actuation.
- NHTSA Distraction-Reduction Guidelines:Mandated shorter eye-off-road times are forcing ergonomic redesigns that consolidate multifunction controls into validated fail-operational modules certified to ISO 26262 ASIL-B.
- Emerging-Market Vehicle Platforms:Cost-sensitive production in Brazil and India sustains mechanical switch volumes where tooling amortization favors proven contact architectures over capacitive retooling.
Market Restraints
- Input Cost Volatility:Copper and silver-based contact materials face price swings that compress margins on commodity mechanical switches serving entry-level vehicle segments.
- Supply Concentration Risk:Precision haptic feedback component manufacturing clusters heavily in Japan's Aichi and Shizuoka prefectures, creating single-source vulnerability for premium capacitive systems.
- Technical Limitation:Capacitive interfaces suffer reduced reliability in extreme temperature cycling below minus thirty degrees Celsius, restricting deployment in Nordic and Canadian fleet applications.
Strategic Opportunities
- Software-Defined Migration:Decoupling physical interfaces from electronic control units enables aftermarket upgrade pathways and subscription-based feature activation through over-the-air firmware deployment.
- EU Green Deal Compliance:REACH substance restrictions and end-of-life vehicle directives are accelerating demand for mercury-free contact materials and recyclable thermoplastic housings.
- India's PLI Scheme:Production-linked incentives for automotive electronics manufacturing are drawing component localization investments to Tamil Nadu and Maharashtra supplier parks.
Industry Challenges
- Functional-Safety Certification Timeline:ISO 26262 ASIL-D validation for steering-mounted driver-assistance controls extends development cycles by fourteen to eighteen months, freezing design specifications early in vehicle programs.
- Legacy System Integration Complexity:Hybrid architectures mixing domain controllers with distributed switch electronics create signal-routing conflicts and diagnostic ambiguity during warranty claims resolution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steering Wheel Switches Market |
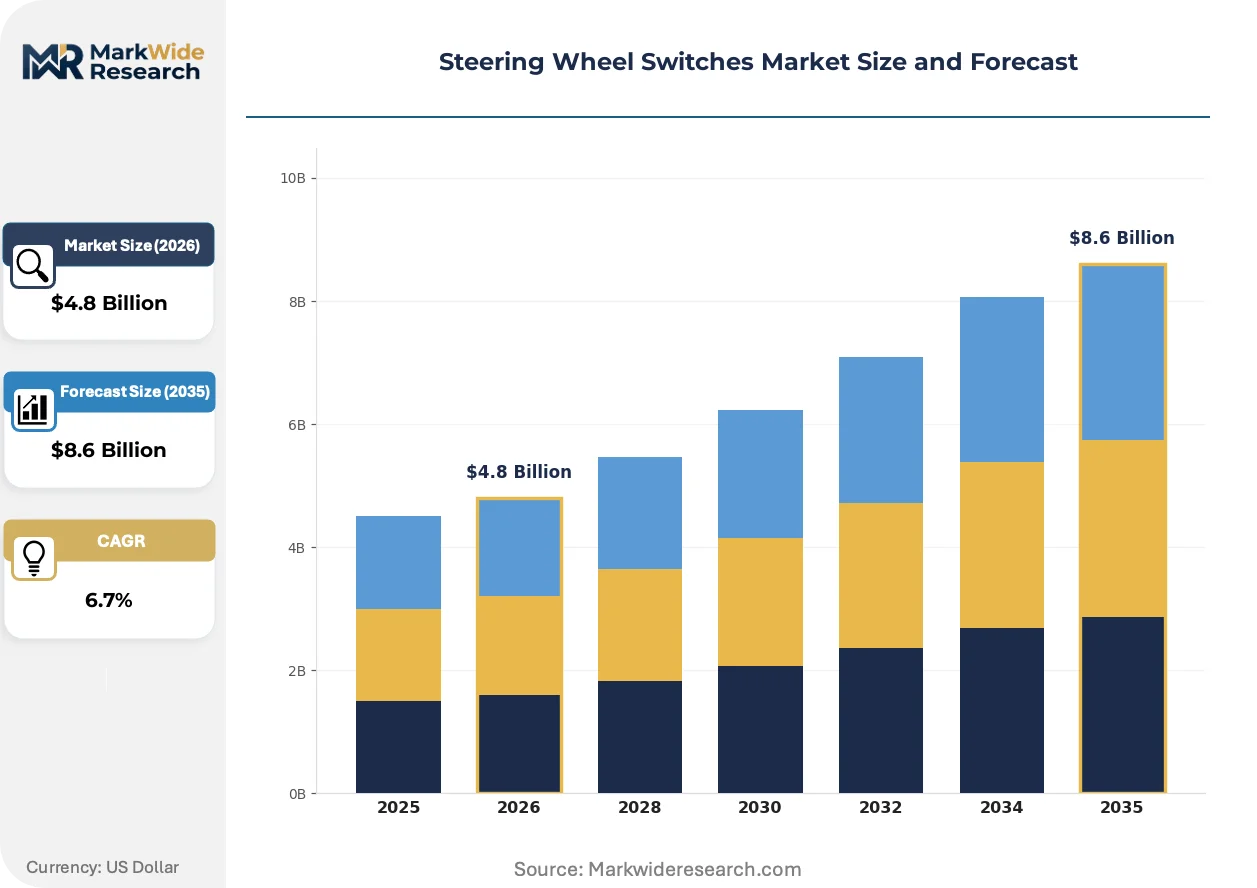
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multifunction Switches, Volume Control Switches, Cruise Control Switches, Lighting Control Switches End User: Automotive Manufacturers, Aftermarket Installers, Fleet Operators, Vehicle Assemblers Technology: Wired, Wireless, Capacitive, Mechanical Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | C&K Components, Inc., Tokai Rika Co., Ltd., Valeo SA, Preh GmbH, Panasonic Corporation, ALPS Alpine Co., Ltd., Delphi Technologies, KOSTAL Automobil Elektrik GmbH & Co. KG, ZF Friedrichshafen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steering Wheel Switches Market Emerging Trajectories
Human-machine interface consolidation is collapsing discrete switch boundaries into unified cockpit electronics, while regulatory pressure on driver attention is accelerating validation requirements for haptic feedback precision.
Force-sensitive resistor technology is absorbing mechanical detent functions previously handled by separate micro-switches, enabling variable actuation thresholds programmable per vehicle mode. Tier-1 suppliers in Germany and Japan are embedding these sensors beneath leather-wrapped rim surfaces for luxury OEM programs. This convergence is compressing the supplier base as haptic module specialists acquire printed-electronics capabilities in-house.
ECE R79 regulations on steering equipment are mandating redundant signal paths and fail-operational behavior for all steering-mounted controls in European type-approved vehicles. The industrial consequence is a shift from single-string switch matrices to dual-channel capacitive arrays with cross-checking logic. Light commercial vehicles and heavy trucks sold across EU member states are experiencing the steepest compliance cost increases as they retrofit validated architectures.
Fleet procurement departments are consolidating switch specifications across multiple vehicle nameplates to capture volume pricing and simplify service-part logistics. Tier-1 suppliers respond with modular platform designs configurable through software rather than hardware variants. This pattern is most visible in North American full-size pickup and SUV segments where single fleet operators specify identical control layouts across half-ton and heavy-duty platforms.
Steering Wheel Switches Market Segmentation
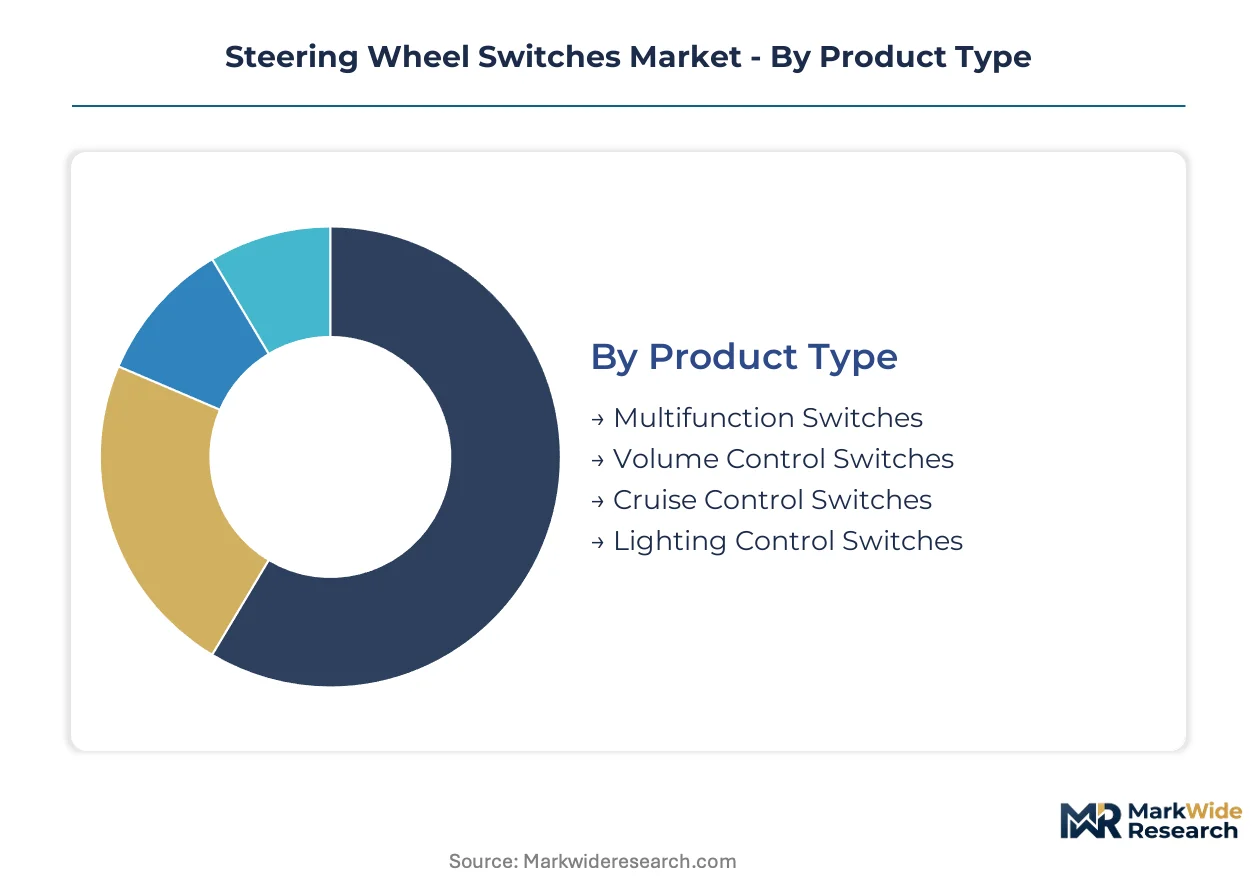
Switch integration depth varies dramatically across vehicle architectures, from standalone electromechanical modules to fully embedded domain-controller interfaces. Procurement strategies diverge based on whether switch logic remains distributed or migrates into centralized software-defined stacks.
Product Type:
Standalone multifunction modules dominate premium platforms, while discrete single-function switches persist in cost-optimized embedded configurations.
- Multifunction Switches:These consolidate audio, telephony, and driver-assistance controls into single modules with haptic feedback rated for one million-plus actuation cycles. Demand concentrates in Germany's Stuttgart-Ingolstadt corridor where luxury OEMs mandate seamless surface integration. NHTSA distraction-reduction guidelines are accelerating ergonomic consolidation into these validated fail-operational units.
- Cruise Control Switches:Discrete actuators with mechanical detents or force-sensitive resistors govern speed-setting functions. Brazil and India sustain volumes where tooling amortization favors proven contact architectures over capacitive retooling.
- Volume Control Switches:Rotary encoders and rocker interfaces for audio level adjustment.
- Lighting Control Switches:Dedicated actuators for headlamp and signal activation, common in commercial vehicle platforms.
Volume placements concentrate in multifunction switches; the faster expansion belongs to cruise control switches as adaptive systems proliferate.
End User:
Customer type determines specification authority, with direct OEM relationships commanding design-influence versus aftermarket channels serving retrofit demand.
- Automotive Manufacturers:Full vehicle producers specify switch architectures during platform development, locking designs fourteen to eighteen months ahead of production. ISO 26262 ASIL-B certification requirements freeze specifications early in vehicle programs, rewarding incumbents with validated development processes.
- Fleet Operators:Corporate procurement departments consolidate specifications across multiple nameplates to capture volume pricing and simplify service-part logistics. North American full-size pickup and SUV segments exhibit this pattern most visibly.
- Aftermarket Installers:Independent service providers retrofit replacement modules and upgrade kits.
- Vehicle Assemblers:Contract manufacturers building for regional brands.
Revenue gravity sits with automotive manufacturers; aftermarket installers are climbing the fastest as software-defined architectures enable subscription-based feature activation.
Technology:
Interface physics separates premium capacitive surfaces from commodity mechanical contacts, with connectivity architecture adding a secondary dimension.
- Capacitive:Seamless surface integration with programmable gesture recognition enables haptic feedback beneath leather-wrapped rim surfaces. Japan's Aichi and Shizuoka prefectures concentrate precision component manufacturing, creating single-source vulnerability for premium systems.
- Mechanical:Proven contact architectures with copper and silver-based materials face input cost volatility that compresses margins on entry-level vehicle segments.
- Wired:Traditional signal routing through dedicated harnesses to distributed electronic control units.
- Wireless:Emerging Bluetooth and proprietary protocols decoupling physical interfaces from domain controllers.
Shipment volumes favor mechanical switches; capacitive technology is gaining share fastest as luxury platforms standardize gesture-enabled interfaces.
Application:
Vehicle category dictates thermal envelope, functional-safety grade, and surface-material requirements for steering-mounted controls.
- Luxury Vehicles:Premium cabins demand force-sensitive resistors embedded beneath leather-wrapped surfaces with variable actuation thresholds programmable per vehicle mode. ECE R79 regulations mandate redundant signal paths and fail-operational behavior, shifting architectures to dual-channel capacitive arrays.
- Electric Vehicles:Software-defined architectures native to EV platforms accelerate migration of switch logic into domain controllers, redistributing value toward firmware suppliers and enabling over-the-air upgrade pathways.
- Passenger Vehicles:Mass-market platforms balancing cost and feature content across mechanical and capacitive options.
- Commercial Vehicles:Light commercial and heavy truck applications experience steepest ECE R79 compliance cost increases as EU type-approval requirements retrofit validated architectures.
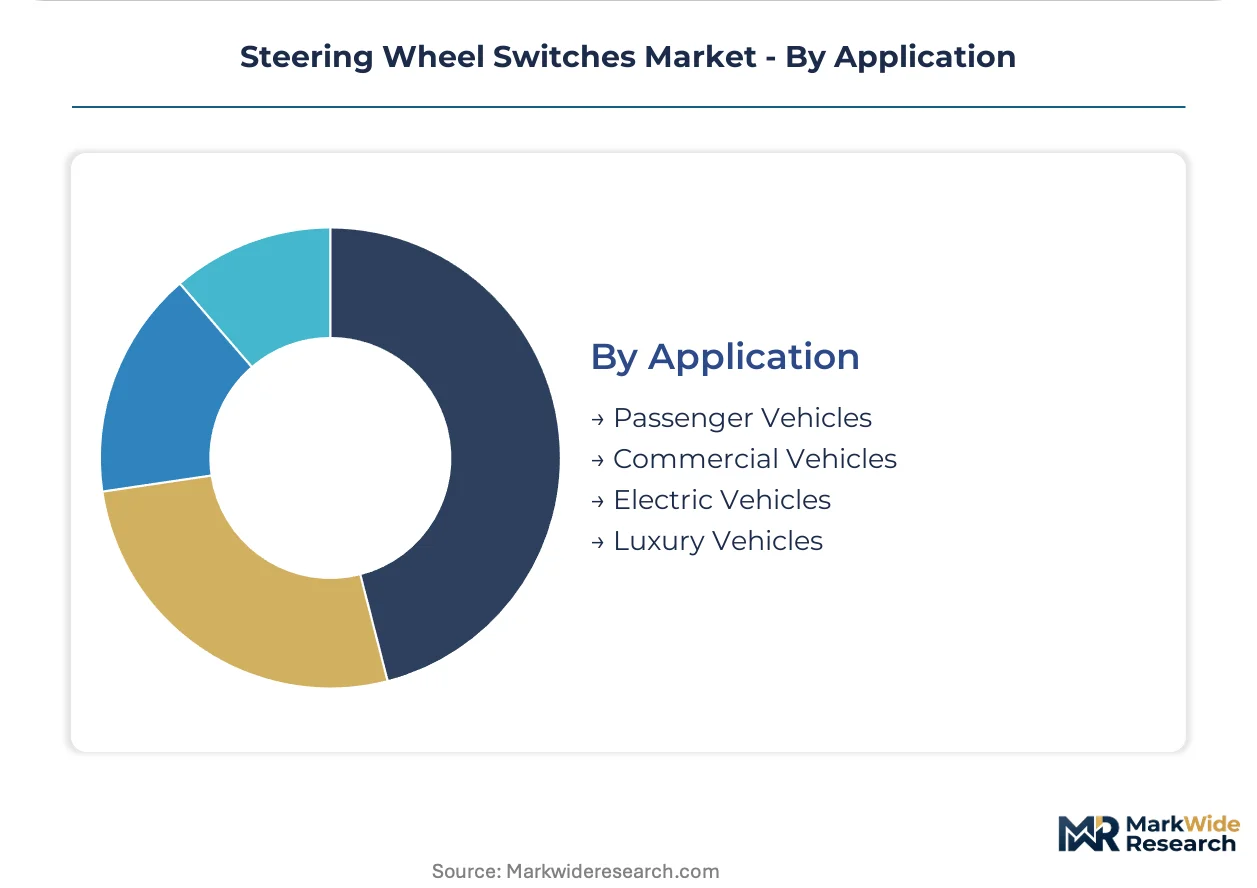
Unit economics concentrate in passenger vehicles; electric vehicles are expanding most quickly as native software-defined stacks displace legacy distributed electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors steering wheel switch engineering for premium automotive platforms, with Ingolstadt's manufacturing corridor processing validated fail-operational modules for luxury OEM programs. Demand clusters trace regulatory stringency and OEM headquarters concentration across three continents.
United States
NHTSA distraction-reduction guidelines mandate shorter driver eye-off-road times, consolidating multifunction controls into ISO 26262 ASIL-B certified modules. The Detroit-Warren corridor hosts validation laboratories serving domestic full-size pickup and SUV fleet operators. Tier-1 suppliers respond with modular platform designs configurable through software rather than hardware variants.
Germany
ECE R79 regulations on steering equipment mandate redundant signal paths and fail-operational behavior for type-approved vehicles. The Stuttgart-Ingolstadt corridor concentrates capacitive touch interface development for luxury platforms. KBA enforcement elevates engineering barriers for new entrants while rewarding incumbents with certified development processes.
Japan
Aichi and Shizuoka prefectures concentrate precision haptic feedback component manufacturing for premium capacitive systems. METI industrial policy supports domestic supplier consolidation amid software-defined vehicle migration. Tokai Rika leverages heritage in precision actuation to anchor the Japanese OEM supply base against domain controller disruption.
China
MIIT standards on vehicle electronics accelerate localization of switch module production for domestic EV platforms. The Yangtze River Delta clusters printed-electronics capabilities serving both local brands and joint-venture programs. Dual carbon goals pressure mercury-free contact material transitions across supplier parks.
India
PLI scheme production-linked incentives for automotive electronics draw component localization investments to Tamil Nadu and Maharashtra supplier parks. CDSCO-equivalent automotive regulators enforce functional-safety alignment with ISO 26262 as domestic OEMs upgrade platforms. Cost-sensitive mechanical switch volumes persist where tooling amortization favors proven contact architectures.
Steering Wheel Switches Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification grade and haptic precision dimensions, with ISO 26262 ASIL-D validation separating validated incumbents from unqualified entrants. The supplier base compresses as haptic module specialists acquire printed-electronics capabilities in-house, collapsing discrete switch boundaries into unified cockpit electronics. Three archetypes dominate: precision haptic specialists with certified development processes, integrated cockpit electronics providers extending beyond discrete components, and scale-driven mechanical switch fabricators serving emerging-market platforms. Dominant competitive moves include strategic partnerships with domain controller specialists and backward integration into force-sensitive resistor manufacturing.
Among Japan-based precision component fabricators, Tokai Rika Co., Ltd. and ALPS Alpine Co., Ltd. exemplify the heritage-driven archetype occupying positions anchored in haptic feedback system validation. Valeo SA represents the integrated cockpit electronics vector, extending supplier roles beyond discrete switch components into full human-machine interface modules. These three companies illustrate how geographic origin and corporate structure map onto divergent strategic postures amid software-defined vehicle migration.
| Leading Market Players |
|---|
| C&K Components, Inc. |
| Tokai Rika Co., Ltd. |
| Valeo SA |
| Preh GmbH |
| Panasonic Corporation |
| ALPS Alpine Co., Ltd. |
| Delphi Technologies |
| KOSTAL Automobil Elektrik GmbH & Co. KG |
| ZF Friedrichshafen |
| Others |
Supply Flow & Price Mechanics
ISO 26262 certification grade divergence between ASIL-D validated haptic modules and commodity mechanical switches manifests in divergent pricing power and sourcing strategies across automotive tiers. Premium capacitive interfaces command value-based premiums tied to fail-operational guarantees while mechanical switch procurement gravitates toward spot-market copper and silver pricing in emerging-market supply parks.
Pricing Analysis
Value-based pricing anchored to ISO 26262 ASIL certification tiers dominates procurement negotiations, with ASIL-D validated modules capturing premiums against ASIL-B alternatives. Price differentiation stems from functional-safety grade and haptic precision tolerances, with copper contact material volatility compressing margins on entry-level mechanical switches serving Brazil and India platforms. Pricing pressure intensifies in the commodity mechanical tier due to silver-based contact cost swings, while fleet operators in North America exhibit lowest price sensitivity for validated fail-operational modules.
Supply Chain Analysis
Precision haptic feedback component supply rests on Japan's Aichi and Shizuoka prefectures, with secondary concentrations in Germany's Stuttgart-Ingolstadt corridor and China's Yangtze River Delta. Copper and silver-based contact materials, force-sensitive resistors, and printed-electronics substrates constitute critical input dependencies. Single-source vulnerability in Japanese precision component manufacturing creates structural risk for premium capacitive systems. Distribution runs through Tier-1 supplier direct contracts to OEM platform engineering teams, with aftermarket channels serving retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into force-sensitive resistor manufacturing and firmware development capabilities is accelerating as suppliers defend margin positions against domain controller disruption. Players are racing upstream to capture haptic module value and downstream to control subscription-based feature activation pathways.
For Market Incumbents: Extend certified development process advantages into domain controller partnerships before firmware suppliers consolidate switch logic. Lock in fourteen-to-eighteen-month validation timelines with Stuttgart and Ingolstadt luxury OEMs to freeze out unqualified entrants. Acquire printed-electronics capabilities in-house to collapse discrete switch boundaries into unified cockpit electronics modules. For New Entrants and Emerging Players: Launch via aftermarket subscription-based feature activation channels where software-defined architectures decouple physical interfaces from electronic control units. Target India's Tamil Nadu and Maharashtra supplier parks under PLI scheme incentives where cost-sensitive mechanical switch volumes persist. Pursue white-space in Nordic and Canadian fleet applications where capacitive reliability gaps below minus thirty degrees Celsius create mechanical switch demand. For Investors and Strategic Acquirers: Re-rating potential sits with haptic module specialists possessing ISO 26262 ASIL-D validation and backward integration into force-sensitive resistor manufacturing given software-defined vehicle migration. Five-to-ten-year viability favors suppliers with certified OEM relationships and in-house printed-electronics capabilities over pure-play mechanical fabricators. Monitor domain controller specialist acquisitions of switch logic suppliers as inflection signal for value redistribution timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Fleet operators in North America consolidate specifications across full-size pickup and SUV nameplates. |
| Software-Defined Vehicle Investment | Domain controller migration decouples physical interfaces from ECUs, enabling over-the-air upgrade pathways. |
| Backward Integration | Haptic module specialists acquire force-sensitive resistor manufacturing to compress supplier base. |
| Geographic Manufacturing Footprint | PLI scheme incentives draw localization investments to Tamil Nadu and Maharashtra supplier parks. |
| Charging Infrastructure Partnership | Electric vehicle native architectures accelerate switch logic migration into centralized software stacks. |
Methodological Framework
Multi-period observation of vehicle production databases, IHS Markit registration data, and OEM platform engineering timelines anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads. Secondary validation drew from NHTSA guideline filings, ECE R79 regulatory texts, ISO 26262 certification registries, and customs trade data. Bottom-up segment sizing triangulated against top-down automotive electronics spend estimates.
Input-output matrix framing connected vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions across the projection horizon. CAGRs were derived from segmented volume and value build-ups validated against macroeconomic automotive demand indicators. Industry-specific forecast inputs included ECE R79 compliance cost trajectories for light commercial vehicles and software-defined vehicle adoption curves in electric platforms.
Regulatory enforcement delays, copper and silver price volatility, and domain controller supplier consolidation are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on certification timeline stability and OEM validation relationship continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
India Automotive LED Lighting Market
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
Automotive E-Axle Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
Stair Lift Motors Market
Automotive Electrical & Electronics
Automotive Rain Sensor Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Automotive E-Axle Disconnect Actuator Market