
 Europe Automotive Pressure Sensor Market | 2026-2036
Europe Automotive Pressure Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Pressure Sensor Market Intelligence
The European Union's General Safety Regulation is repositioning the cost-of-entry calculus for component suppliers. This mandate requires advanced safety features, including precise tire pressure monitoring, in all new vehicle models. Robert Bosch leverages its deep integration with leading German automakers to supply complete powertrain and safety systems. Infineon Technologies specializes in semiconductor-based sensor solutions optimized for the thermal management needs of electric vehicle batteries. Sensata Technologies competes with a broad portfolio of sensors for engine, transmission, and emission control applications.
An automotive pressure sensor is a device that converts physical pressure into a calibrated electrical signal used by a vehicle's electronic control unit. These components, often based on piezoelectric or capacitive sensing elements, provide critical data for optimizing engine performance, safety, and emissions. Within applications, tire pressure monitoring systems represent the fastest-growing segment due to regulatory enforcement. Engine management and transmission control applications constitute a mature but high-volume segment, essential for both internal combustion and hybrid vehicle architectures.
CE marking is a fundamental requirement for market access, confirming a product's adherence to European safety and environmental standards. The EU's REACH regulation directly impacts sensor manufacturing by restricting certain hazardous substances, which influences material procurement and design choices. Compliance with these frameworks is essential for all OEMs and aftermarket providers operating in the region. Sensor manufacturers must now navigate the strategic choice between developing specialized, high-margin sensors for EV platforms or focusing on mass-market components for the established combustion engine sector.
Market Dynamics
The Europe automotive pressure sensor market is fundamentally shaped by regulatory mandates for vehicle safety and emissions. The EU's General Safety Regulation acts as a non-discretionary demand driver, compelling component adoption across all vehicle classes, not just premium segments.
Growth Catalysts
- Regulatory Mandates:The European Union's updated General Safety Regulation, which makes tire pressure monitoring systems a standard requirement for all new vehicles, provides a powerful and consistent demand signal across the region.
- Vehicle Electrification:The expansion of electric vehicle production creates new demand for specialized pressure sensors within battery thermal management and hydrogen fuel cell systems to ensure operational safety and efficiency.
- Manufacturing Concentration:Germany's dense ecosystem of automotive OEMs and Tier 1 suppliers concentrates demand, creating a high-volume hub for advanced sensor technologies, particularly for powertrain and chassis applications.
Market Restraints
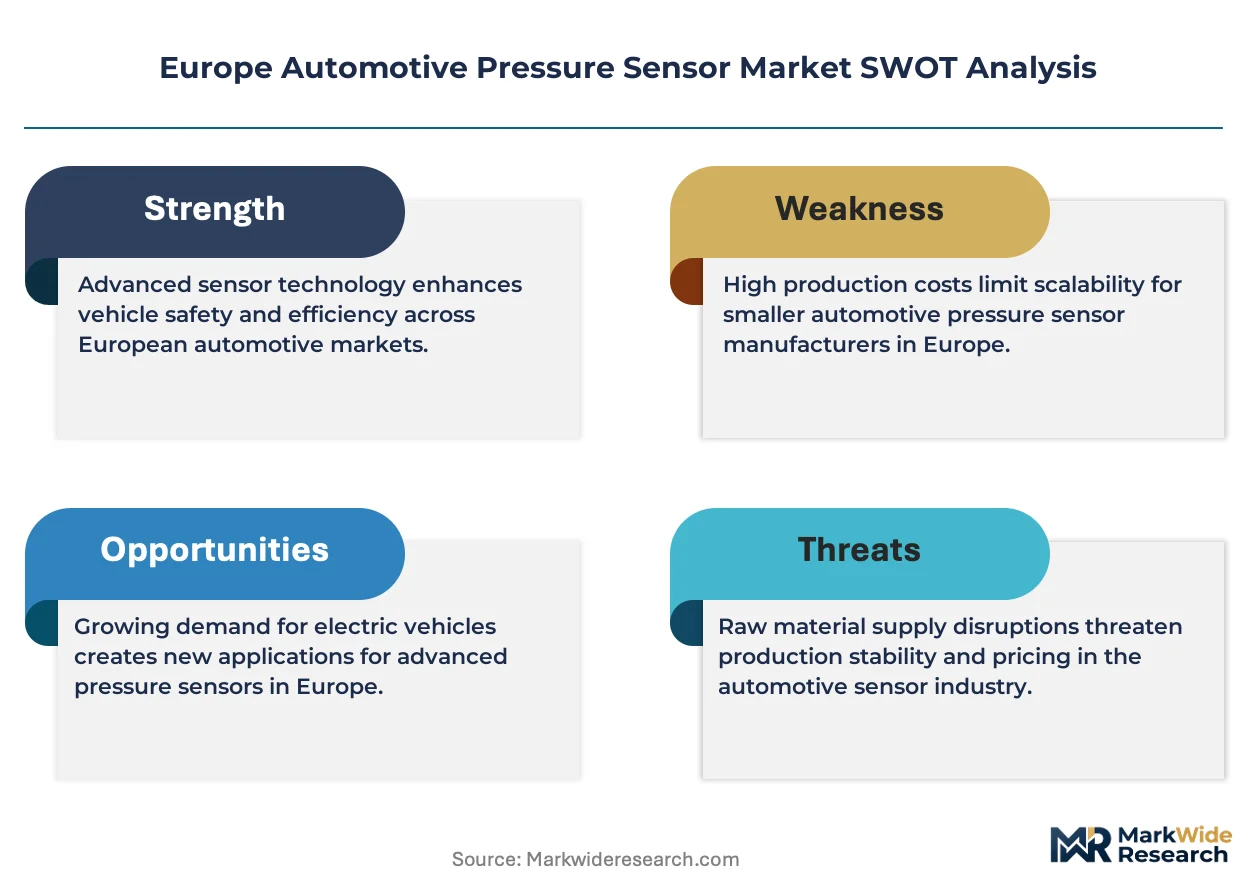
- Input Material Volatility:A high dependency on semiconductor materials sourced from outside Europe exposes manufacturers to supply chain disruptions and significant price fluctuations, impacting production costs and margins.
- Material Restrictions:The EU's REACH regulation restricts the use of certain hazardous substances, such as lead in some piezoelectric materials, forcing costly research and requalification of alternative sensor designs.
- Technical Miniaturization Limits:Developing smaller sensors that can reliably withstand the extreme temperature, pressure, and vibration of modern engine and transmission environments presents a persistent engineering and material science barrier.
Strategic Opportunities
- Hydrogen Mobility Applications:The emerging hydrogen fuel cell vehicle sector, especially for commercial trucks and buses, presents an opportunity to develop high-pressure sensors for storage tank and fuel line monitoring.
- Sensor Fusion Modules:Integrating pressure sensing with temperature, humidity, or gas detection into a single smart module for applications like EV battery packs or cabin air quality systems offers a path to higher-value products. *Aftermarket ADAS Expansion: The growing aftermarket for retrofitting Advanced Driver-Assistance Systems in older vehicles creates a new channel for sensors that support functions like adaptive cruise control and emergency braking.
Industry Challenges
- Certification Timelines:Navigating the lengthy and capital-intensive processes for achieving both CE marking for market access and the stringent AEC-Q100 qualification for automotive-grade reliability delays the introduction of new products.
- Legacy System Integration:Ensuring new, advanced sensors are fully interoperable and can communicate effectively with the existing electronic control units and diverse CAN bus architectures of older vehicle platforms is a major technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Pressure Sensor Market |
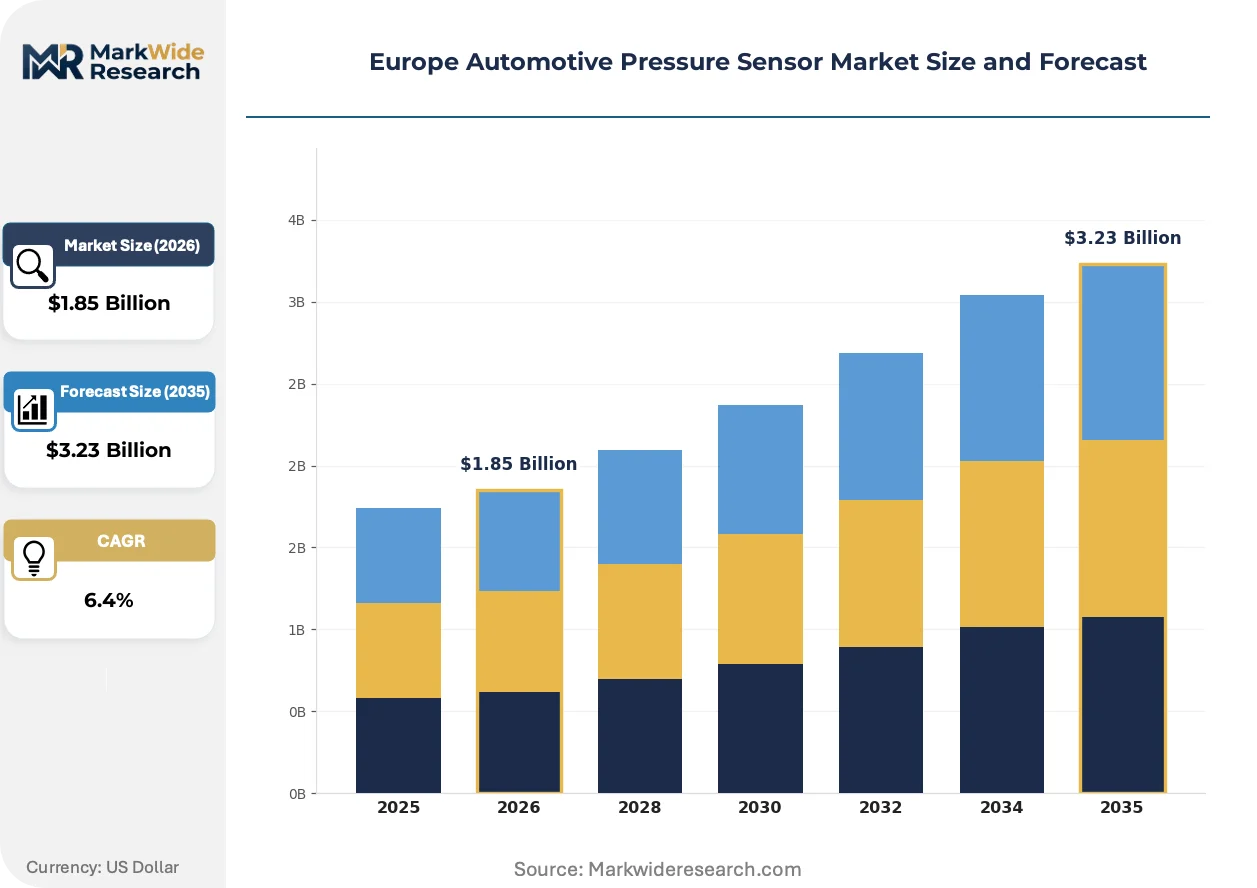
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piezoelectric Sensors, Capacitive Sensors, Resistive Sensors, Optical Sensors, Ultrasonic Sensors Application: Engine Management, Tire Pressure Monitoring, Fuel System, Transmission Control, Emission Control End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers Distribution Channel: Direct Sales, Distributors, E-commerce, Automotive Workshops, Specialty Retailers |
| Companies Covered | NXP Semiconductors, Kistler, Infineon Technologies, Delphi, Sensata Technologies, Robert Bosch, TE Connectivity, STMicroelectronics, Continental, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Pressure Sensor Market Strategic Shifts & Innovations
The market's evolution is defined by a transition from discrete components toward integrated, intelligent sensing modules. This shift is driven by the parallel demands of vehicle electrification, which requires new sensing capabilities, and automation, which requires more precise and redundant data streams.
MEMS (Micro-Electro-Mechanical Systems) technology facilitates the fabrication of highly accurate and miniaturized pressure sensors on silicon wafers. Automakers, especially within Germany's premium vehicle segment, are accelerating their adoption of these components for complex control systems. This advanced semiconductor-based technology is absorbing the functions of older, bulkier sensor types, enabling more compact and power-efficient designs in powertrain and safety applications.
Europe's REACH regulation directly influences material science and product design within the sensor industry. The policy's restriction of specific chemicals forces manufacturers to reformulate materials used in sensor housings, seals, and electronic elements. The high-volume combustion engine sensor segment is most affected, as suppliers must invest in re-validating their products to maintain compliance and access to the EU market.
Automotive OEMs are altering their purchasing behavior, moving from sourcing individual components to procuring pre-calibrated and integrated sensing modules from Tier 1 suppliers. This change disrupts the business model for smaller, specialized sensor makers who sell directly to car manufacturers. This pattern is most pronounced in the German automotive sector, where major car brands are consolidating supply chains to simplify assembly and improve system-level performance.
Europe Automotive Pressure Sensor Market Segmentation
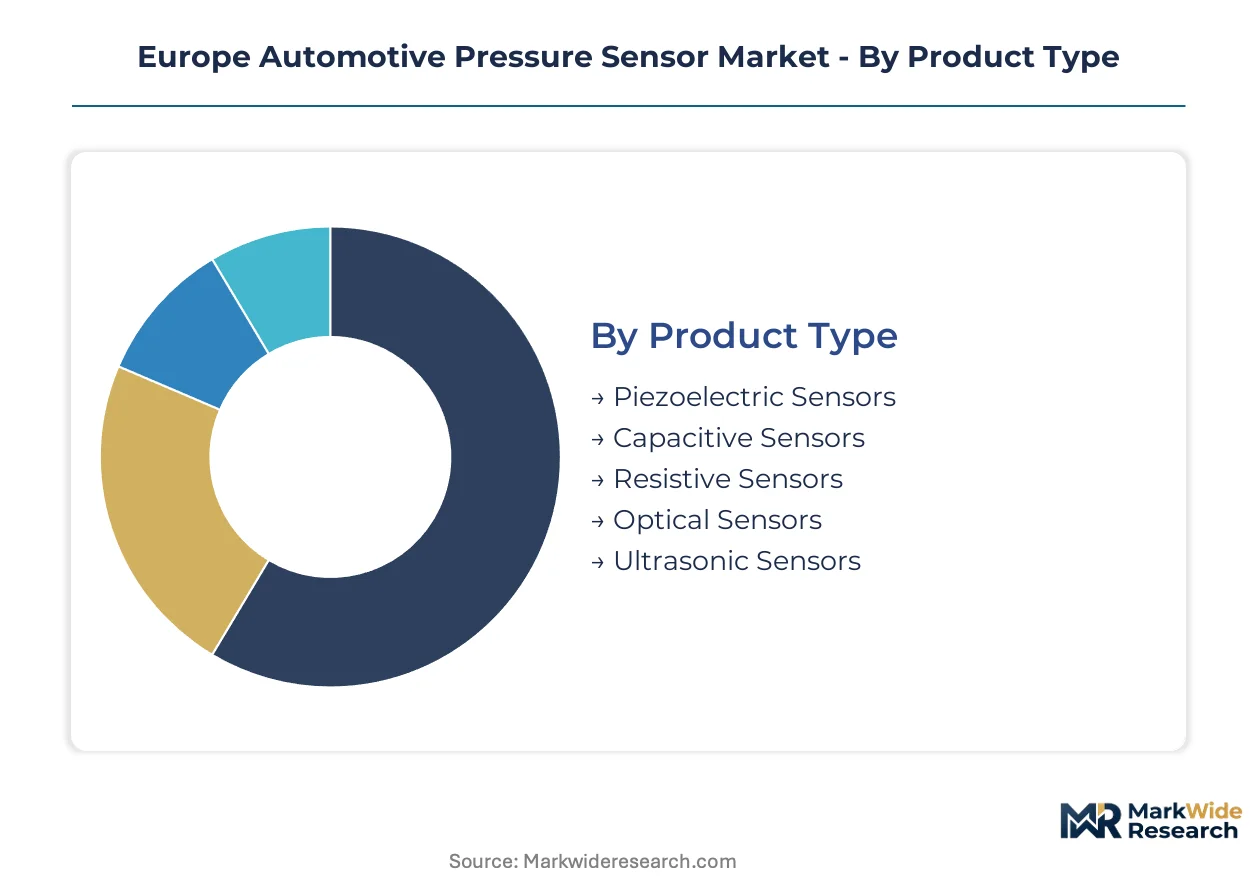
The Europe automotive pressure sensor market segmentation clarifies how different product technologies, applications, and end-user demands shape the competitive landscape. Understanding these distinctions is crucial for suppliers to align their product development and market strategies with regional regulatory mandates and evolving vehicle architectures.
Product Type:
Buyer decisions for pressure sensor product types hinge on the specific performance requirements, durability, and cost-effectiveness needed for integration into diverse automotive systems.
- Piezoelectric Sensors:These sensors generate an electrical charge proportional to applied mechanical stress, offering high sensitivity and rapid response times. Demand concentrates in advanced safety systems and engine control within Germany's premium vehicle segment, driven by precision requirements.
- Capacitive Sensors:Utilizing changes in capacitance due to pressure-induced deformation of a dielectric material, these sensors provide stable measurements across varying temperatures. European EV battery thermal management systems increasingly rely on these for their accuracy and power efficiency.
- Resistive Sensors:These devices measure pressure by detecting changes in electrical resistance, commonly used for less demanding applications due to their cost-effectiveness.
- Optical Sensors:Employing light-based principles to detect pressure variations, these sensors offer immunity to electromagnetic interference in critical vehicle environments.
- Ultrasonic Sensors:These sensors use sound waves to measure pressure, particularly in non-contact applications such as liquid level sensing within fuel tanks.
Piezoelectric Sensors leads on scale; Capacitive Sensors leads on momentum.
Application:
The functional requirements of specific vehicle applications dictate the choice of pressure sensor technology, influencing design complexity and required qualification standards.
- Tire Pressure Monitoring:These systems continuously measure tire inflation levels, transmitting data to the vehicle's ECU to enhance safety and fuel efficiency. The EU's General Safety Regulation drives demand for TPMS sensors across all new vehicle models.
- Engine Management:Sensors in engine management systems monitor manifold absolute pressure, oil pressure, and fuel pressure to optimize combustion, emissions, and overall performance. German automotive OEMs integrate these for precise powertrain control in both ICE and hybrid vehicles.
- Fuel System:Sensors within the fuel system monitor fuel rail pressure and tank pressure, ensuring efficient fuel delivery and compliance with emission standards.
- Transmission Control:These sensors measure hydraulic pressure within automatic transmissions, facilitating smooth gear shifts and optimizing power delivery.
- Emission Control:Pressure sensors support exhaust gas recirculation and diesel particulate filter systems, helping vehicles meet stringent European environmental regulations.
Tire Pressure Monitoring is gaining share fastest; Engine Management holds the largest volume contribution.
End User:
Customer type significantly influences procurement strategies and the required level of integration support, from raw components to pre-calibrated modules.
- OEMs:Original Equipment Manufacturers directly integrate pressure sensors into vehicle designs during the production phase, demanding high reliability and custom specifications. Major European automakers source these components for their assembly lines, especially in Germany.
- Tier-1 Suppliers:These companies develop and supply complete sub-systems to OEMs, often requiring pressure sensors as integrated components within larger modules. Robert Bosch and Infineon Technologies are prominent suppliers to this segment.
- Vehicle Assemblers:These entities primarily focus on vehicle assembly and often source larger pre-assembled components rather than individual sensors.
- Aftermarket Providers:This segment includes companies supplying replacement parts and upgrade kits for vehicles already in operation, including TPMS sensors and engine diagnostics.
OEMs represent the primary value segment; Aftermarket Providers exhibit significant expansion potential for standardized components.
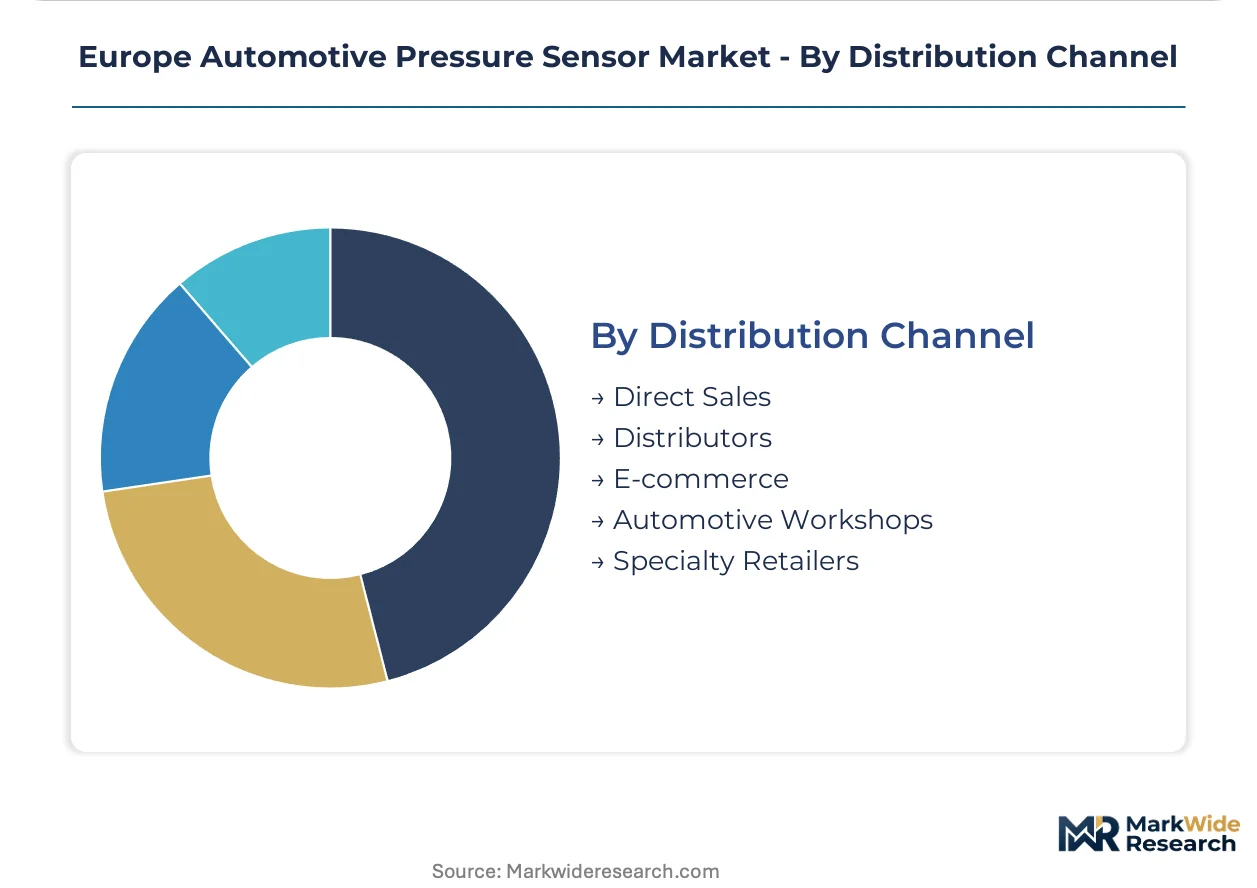
Distribution Channel:
The efficiency and reach of distribution channels are paramount for ensuring timely delivery of pressure sensors, influencing market penetration and inventory management across Europe.
- Direct Sales:Manufacturers sell directly to large automotive OEMs and Tier-1 suppliers, facilitating deep technical collaboration and custom supply agreements. This channel dominates for high-volume, specialized sensor components.
- Distributors:These intermediaries manage logistics and sales to smaller OEMs, Tier-2 suppliers, and aftermarket providers, offering broader market access and localized support. European distributors handle a diverse portfolio of sensor technologies.
- E-commerce:Online platforms facilitate the sale of standardized pressure sensors and aftermarket components, offering convenience and competitive pricing for a wide customer base.
- Automotive Workshops:Independent and franchised workshops procure replacement pressure sensors for repair and maintenance services, especially for TPMS and engine diagnostic systems.
- Specialty Retailers:These outlets cater to niche markets, offering performance-oriented or specialized pressure sensors for specific vehicle modifications or industrial applications.
Direct Sales ensure strategic supply chain control; Distributors provide extensive market reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's deep-rooted automotive engineering talent and extensive R&D infrastructure anchor the region's demand for advanced pressure sensors. This concentration of expertise drives innovation in vehicle safety and performance systems. The European market integrates sophisticated sensor technologies across its diverse automotive manufacturing base.
Germany
Germany's robust automotive manufacturing ecosystem, home to major OEMs and Tier 1 suppliers, drives significant demand for pressure sensors. The KBA's stringent vehicle certification processes ensure high-quality component integration. Bavaria and Baden-Württemberg host dense clusters of automotive research and production, accelerating sensor adoption in premium vehicles.
France
French automakers prioritize advanced safety and emissions control systems, boosting the adoption of pressure sensors. The country's environmental regulations, aligned with EU directives, compel sensor integration for compliance. The Île-de-France region, with its strong industrial base, supports sensor technology development for electric and hybrid platforms.
Italy
Italian automotive design and engineering emphasize performance and efficiency, creating demand for precise pressure sensors in engine and transmission systems. The Ministry of Infrastructure and Transport enforces EU safety standards, including TPMS requirements. Lombardy and Piedmont are key manufacturing hubs, fostering innovation in sensor applications for luxury and sports vehicles.
United Kingdom
United Kingdom's automotive sector, with its focus on niche and high-performance vehicles, requires specialized pressure sensors for critical applications. The Vehicle Certification Agency ensures compliance with EU-derived safety and emissions standards. The Midlands region remains a significant automotive production center, integrating advanced sensor technologies into vehicle platforms.
Europe Automotive Pressure Sensor Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists to capture market share in the automotive pressure sensor sector. The market structure exhibits consolidation among established Tier 1 suppliers. Strategic archetypes include broad automotive system integrators, specialized sensor technology providers, and semiconductor giants. Dominant competitive moves involve strategic partnerships with OEMs and continuous portfolio diversification into new vehicle architectures.
Among the leading players, Robert Bosch GmbH, a German multinational engineering and technology company, exemplifies the broad automotive system integrator archetype, offering comprehensive sensor solutions across various vehicle systems. Infineon Technologies AG, a German semiconductor manufacturer, and STMicroelectronics N.V., a French-Italian multinational electronics and semiconductor manufacturer, represent specialized sensor technology providers. These companies occupy a position at the forefront of innovation, particularly in semiconductor-based and MEMS sensor solutions, catering to the evolving demands of the European automotive industry. Their presence underscores the market's reliance on both established system providers and advanced component specialists.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Kistler |
| Infineon Technologies |
| Delphi |
| Sensata Technologies |
| Robert Bosch |
| TE Connectivity |
| STMicroelectronics |
| Continental |
| Others |
Cost & Logistics Intelligence
Semiconductor material volatility directly influences the cost structure of automotive pressure sensors, impacting pricing tiers from Tier 1 suppliers to vehicle OEMs. This upstream cost pressure cascades downstream, affecting final product pricing across Europe.
Pricing Analysis
Contract-based long-term offtake agreements define the primary pricing model for automotive pressure sensors, often incorporating hybrid elements for customization. Price differentiation stems from AEC-Q100 certification levels and the volume scale of orders. Pricing pressure from major OEMs drives continuous cost optimization, though specialized EV sensors command a premium. Aftermarket providers typically exhibit the highest price sensitivity for replacement components.
Supply Chain Analysis
Skilled workforce availability in key manufacturing hubs like Germany and Eastern European nations shapes the automotive pressure sensor supply chain. The industry relies heavily on semiconductor materials from Asian producers and specialized piezoelectric elements. Single-source vulnerability for advanced sensor components presents a significant supply chain risk. Distribution runs through direct sales channels to large OEMs and Tier 1s, complemented by regional distributors for smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe automotive pressure sensor market offers a geographic-arbitrage play, with significant cost differentials in manufacturing and labor between Western and Eastern European production centers.
For Market Incumbents: To counter input material volatility, market incumbents must deepen vertical integration into specialized semiconductor and piezoelectric material production. Investing in advanced AEC-Q100 certification for new EV platforms reinforces their position against emerging specialized sensor competition. Strategic partnerships with key German automakers secure long-term demand and foster collaborative R&D.
For New Entrants and Emerging Players: MEMS technology integration represents a primary technology-first wedge for new entrants, enabling highly miniaturized and accurate pressure sensors for EV battery thermal management. Targeting the emerging hydrogen mobility sector with high-pressure storage tank sensors offers a white-space opportunity. A direct-to-Tier 2 or aftermarket sales strategy can bypass entrenched OEM relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized sensor technology and material science expertise are scarce, particularly for EV and hydrogen applications. The market offers long-term viability driven by sustained regulatory mandates and vehicle electrification. Acquiring mid-sized firms with proprietary MEMS technology or advanced material science capabilities is a strong archetype. The pace of new EU safety regulation implementation is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Streamlining sensor designs across vehicle models reduces manufacturing complexity for OEMs. |
| Technology Licensing | Accessing proprietary MEMS or material science innovations accelerates product development for advanced sensors. |
| Strategic Partnership | Collaborating with EV battery manufacturers ensures early integration of specialized thermal management sensors. |
| Green Manufacturing Transition | Adopting REACH-compliant materials and processes mitigates regulatory risks for sensor production. |
| Acquisition of Specialist Firm | Gaining expertise in hydrogen pressure sensing addresses an emerging high-growth segment. |
Research Approach
Coverage spans Europe, with primary inputs from key automotive manufacturing countries informing the analysis. Interviews with automotive OEM platform engineers, Tier 1 supplier procurement leads, sensor R&D directors, and aftermarket distributors provided critical insights. Secondary data from EU regulatory documents, KBA statistics, and industry reports validated primary findings. Both bottom-up and top-down triangulation methods were applied.
The rate-of-change decomposition framework projects market dynamics across the projection horizon. Segmentation dimensions modeled include product type, application, end user, distribution channel, and regional production clusters. Compound Annual Growth Rates were derived from historical data analysis and projected market drivers. Key forecast inputs include vehicle production forecasts and regulatory compliance timelines.
The model holds under prevailing EU regulatory frameworks and stable semiconductor supply; deviation in geopolitical disruptions or EV adoption rates would shift market trajectories. Forecasts reflect assumptions regarding technological advancements. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Electrical Park Brake (EPB) Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
Switchrack Assemblies Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Automotive Electronic Expansion Valve Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Asia Pacific Automotive Camera Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market